
 CAS9 Technology Market | 2026-2036
CAS9 Technology Market Size, Share, and Industry Trends Forecast 2026-2036
CAS9 Technology Market Outlook
Pharmaceutical companies is repositioning toward in vivo gene editing programs, pulling demand away from pure research-tool procurement. Thermo Fisher Scientific leverages its reagent manufacturing scale to dominate plasmid DNA supply chains. Merck KGaA anchors European distribution through its life science division. GenScript competes on custom sgRNA synthesis turnaround times.
CAS9 technology comprises a programmable RNA-guided endonuclease system derived from Streptococcus pyogenes, operating at 37°C with a protospacer adjacent motif requirement for DNA cleavage precision. The system enables targeted double-strand breaks for knockout, insertion, or base-editing applications across mammalian, plant, and microbial genomes. Ribonucleoprotein complex formats are gaining fastest due to reduced off-target effects and transient expression profiles that simplify regulatory pathways. Viral vector delivery technology leads revenue share in therapeutic contexts despite manufacturing complexity, while electroporation occupies the academic lab segment on cost efficiency.
FDA gene therapy guidance and EMA's ATMP framework shape clinical-grade product standards, forcing manufacturers to adopt GMP-compliant production earlier in development cycles. ISO 13485 and WHO TRS 978 standards govern raw material qualification for cell and gene therapy applications. Stakeholders must monitor evolving patent landscapes around CRISPR-Cas9 licensing to avoid downstream product development constraints.
Market Dynamics
Pharmaceutical pipelines are pivoting from ex vivo cell therapies toward in vivo gene editing, compressing demand timelines and forcing reagent suppliers to reconfigure manufacturing footprints for clinical-grade material flows.
Growth Catalysts
- FDA Gene Therapy Guidance:Streamlined Investigational New Drug pathways reduce clinical trial initiation timelines for CRISPR-based therapeutics, accelerating sponsor commitments to CAS9 programs.
- Ribonucleoprotein complex adoption:Transient expression formats with reduced off-target liability are displacing plasmid-based delivery in IND-enabling studies, pulling demand toward GMP-compatible RNP manufacturing.
- Germany's bio-cluster density:Concentrated academic-industry partnerships in Heidelberg and Berlin generate sustained procurement of high-fidelity CAS9 variants for preclinical validation.
Market Restraints
- GMP plasmid supply concentration:Contract manufacturing organizations in the United States and Germany control majority capacity for clinical-grade starting material, creating queue bottlenecks for Phase I sponsors.
- Patent licensing fragmentation:Broad Institute versus University of California CRISPR ownership disputes generate legal uncertainty that delays platform licensing decisions by mid-cap biotech firms.
- Electroporation device limitations:In vivo delivery efficiency for solid organ targets remains below therapeutic thresholds, constraining addressable disease indications.
Strategic Opportunities
- Base editing convergence:Fusion of cytosine and adenine base editors with engineered CAS9 variants opens precision medicine applications requiring single-nucleotide correction without double-strand breaks.
- Japan's regenerative medicine framework:PMDA's conditional approval pathway for gene therapies creates accelerated market access for sponsors demonstrating early efficacy signals.
- Direct-to-biotech distribution platforms:Digital procurement channels bypass traditional distributor markups for custom sgRNA synthesis, capturing margin from fragmented academic and startup segments.
Industry Challenges
- Gene editing workforce scarcity:Qualified cell and gene therapy manufacturing operators command premium compensation, constraining facility expansion timelines for CDMOs.
- ISO 13485 certification complexity:Medical device quality system requirements for automated electroporation instruments extend development cycles by 12-18 months versus research-use equipment.
- Legacy plasmid inventory obsolescence:Transition to synthetic mRNA and RNP formats strands existing GMP DNA stocks, forcing write-downs at contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CAS9 Technology Market |
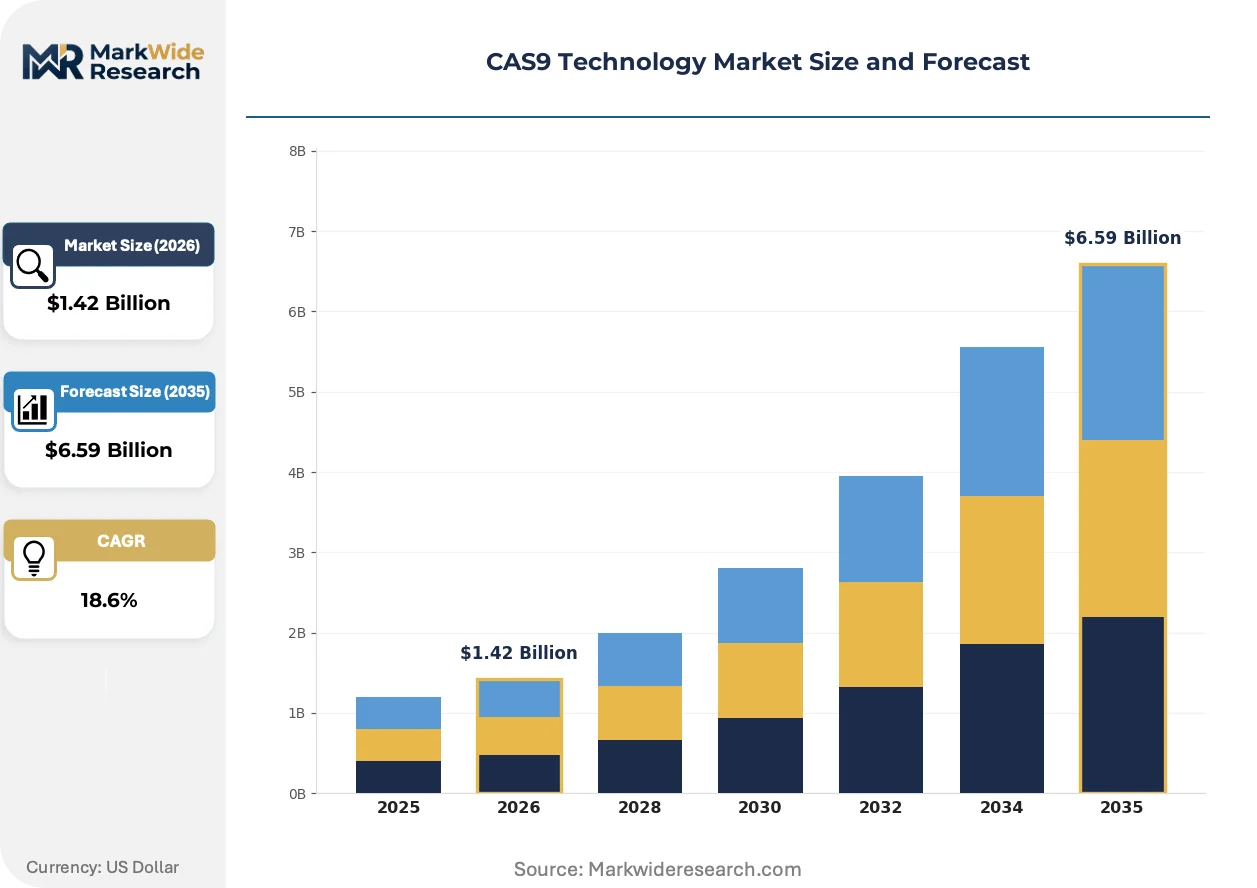
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $6.59 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasmid DNA, Ribonucleoprotein Complex, Cas9 Protein, Single-guide RNA Application: Gene Editing, Genetic Engineering, Cellular Therapeutics, Functional Genomics End User: Research Institutions, Pharmaceutical Companies, Biotech Firms, Academic Labs Technology: Microinjection, Electroporation, Viral Vectors, Lipofection |
| Companies Covered | Thermo Fisher Scientific, Agilent Technologies, Merck KGaA, New England Biolabs, GenScript, GeneCopoeia, Cellecta, Origene Technologies, Takara Bio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CAS9 Technology Market Strategic Shifts
Engineered nuclease architectures and delivery modalities are compressing development timelines while regulatory frameworks mature to accommodate complex therapeutic modalities. Three developments merit close attention.
Prime editing is consolidating precision genome engineering by combining reverse transcriptase activity with nicked CAS9 variants to install targeted insertions, deletions, and all 12 base-to-base conversions without donor DNA requirements. Large pharma sponsors are adopting the platform for inherited disease programs where single-nucleotide precision outweighs editing efficiency trade-offs. This capability is compressing the addressable market for earlier base editing approaches in indications requiring small corrective edits.
EMA's ATMP framework revision tightens comparability requirements for viral vector manufacturing changes, forcing sponsors to lock process parameters earlier in development than prior guidance permitted. The industrial consequence is elevated capital allocation to analytical method development and reference standard qualification. Viral vector-dependent CAS9 delivery programs face the steepest compliance burden, particularly those targeting European commercialization.
Biotech procurement teams are unbundling after-sales technical support from reagent contracts, negotiating standalone service agreements with specialized gene editing consultancies. Traditional distributors lose attach revenue as buyers source sgRNA design and off-target analysis through discrete vendor relationships. This pattern is most pronounced in the United States, where startup density supports specialized service provider ecosystems.
CAS9 Technology Market Segmentation
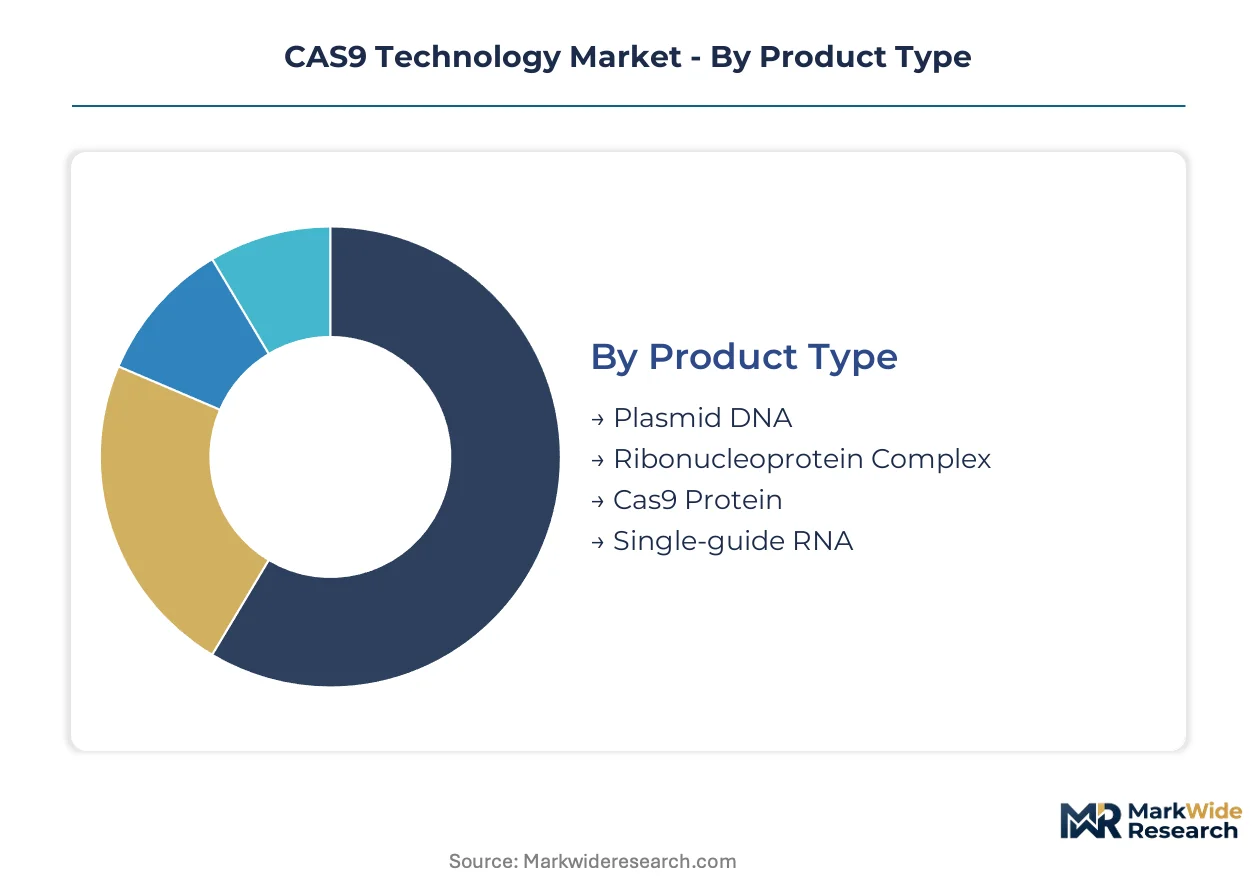
CAS9 technology segmentation reveals how supply chain configuration shapes procurement patterns across research and therapeutic applications. Product formats, delivery mechanisms, and end-user requirements fragment the competitive landscape into distinct value pools with diverging margin profiles.
Product Type:
Supply concentration in GMP manufacturing capacity favors formats compatible with existing plasmid DNA infrastructure while pushing adoption toward transient expression systems.
- Plasmid DNA:Circular DNA vectors encoding Cas9 and guide RNA sequences remain the workhorse for stable cell line engineering. Demand concentrates in early-phase pharmaceutical sponsors in the United States and Germany, constrained by queue bottlenecks at contract manufacturers with GMP certification.
- Ribonucleoprotein Complex:Pre-assembled Cas9 protein-guide RNA complexes enable transient editing with reduced off-target liability. Academic labs in Heidelberg and Berlin drive fastest adoption for preclinical validation studies, displacing plasmid formats in IND-enabling work.
- Cas9 Protein:Recombinant endonuclease supplied as purified enzyme for in-house RNP assembly.
- Single-guide RNA:Synthetic RNA oligonucleotides designed to target specific genomic loci.
Today's leader: Plasmid DNA. Tomorrow's challenger: Ribonucleoprotein Complex.
Application:
Cost tier differentiation separates high-value therapeutic programs from commoditized research tools, with clinical-grade applications commanding 3-5x pricing premiums over discovery-grade equivalents.
- Gene Editing:Therapeutic correction of disease-causing mutations through targeted DNA modification. Pharmaceutical pipelines in the United States pivot toward in vivo indications, compressing development timelines and elevating regulatory scrutiny for delivery technology.
- Cellular Therapeutics:Ex vivo modification of patient cells for adoptive transfer. EMA's ATMP framework tightens comparability requirements, forcing sponsors to lock process parameters earlier than prior guidance permitted.
- Genetic Engineering:Industrial strain optimization and agricultural trait development.
- Functional Genomics:Large-scale knockout screens for target identification and validation.
Cellular therapeutics capture premium pricing. In vivo gene editing expands most quickly.
End User:
Customer type determines procurement sophistication, with pharmaceutical sponsors demanding integrated regulatory support while academic buyers prioritize cost efficiency and technical flexibility.
- Pharmaceutical Companies:Integrated drug developers advancing CRISPR-based therapeutics through clinical stages. FDA gene therapy guidance streamlines IND pathways, accelerating commitment to CAS9 programs and pulling demand toward GMP-compatible formats.
- Biotech Firms:Venture-backed developers specializing in gene editing platforms. Patent licensing fragmentation between Broad Institute and University of California generates legal uncertainty that delays platform decisions.
- Research Institutions:Academic medical centers and national laboratories conducting discovery research.
- Academic Labs:University-based groups with limited procurement budgets and high technical autonomy.
Pharmaceutical companies dominate value capture. Biotech firms show steepest expansion trajectory.
Technology:
Maturity gradients separate established delivery methods from emerging modalities, with viral vector manufacturing complexity creating barriers to entry that electroporation avoids.
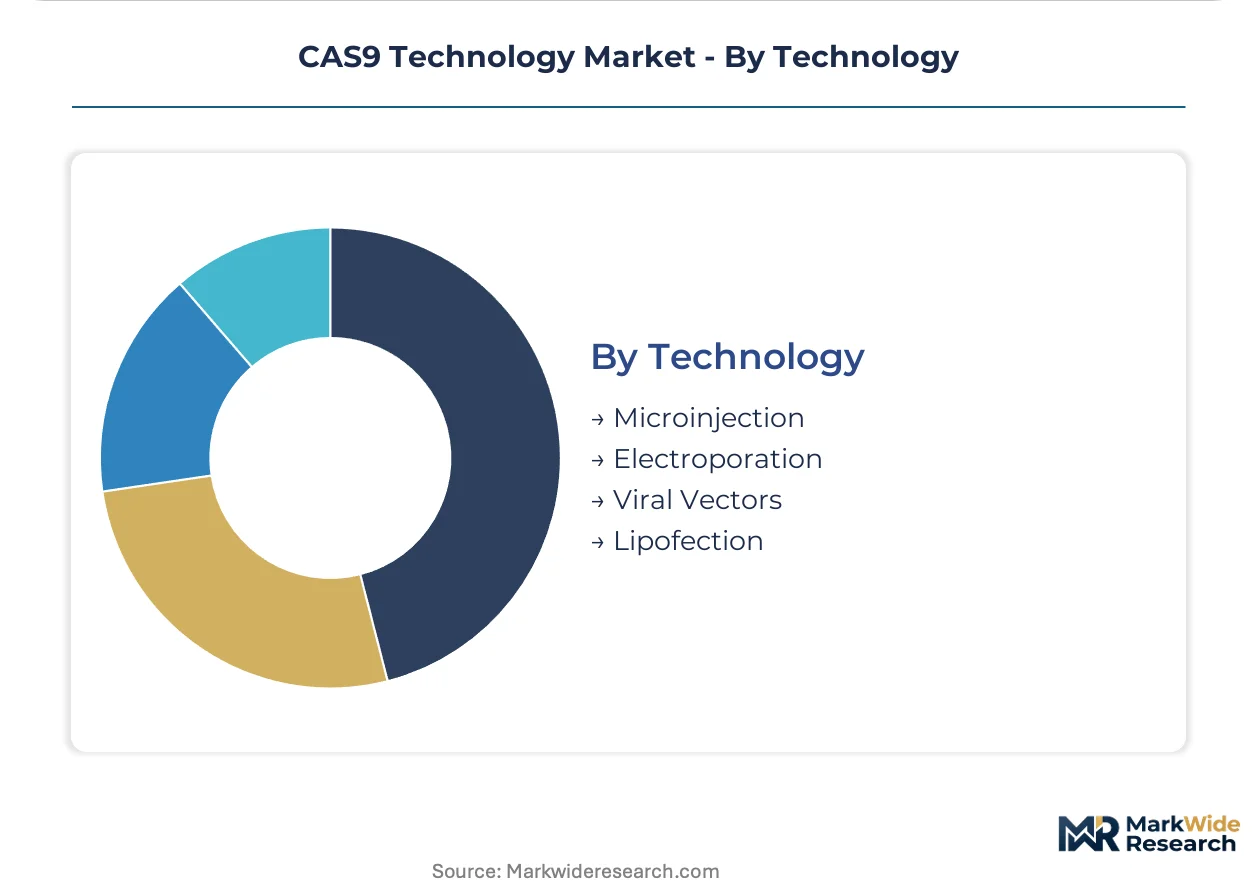
- Viral Vectors:Adeno-associated and lentiviral particles enabling efficient in vivo and ex vivo delivery. Manufacturing scale-up constraints in the United States and Germany limit capacity for Phase I sponsors, elevating capital requirements for analytical method development.
- Electroporation:Electrical pulse-mediated membrane permeabilization for RNP or plasmid entry. Academic labs favor this format for cost efficiency, though in vivo solid organ delivery efficiency remains below therapeutic thresholds.
- Microinjection:Direct physical delivery into cells or embryos for precision applications.
- Lipofection:Lipid nanoparticle-mediated transfection for research-scale editing.
Viral vectors command revenue share. Electroporation gains share fastest in discovery applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping CAS9 manufacturing footprints as sponsors relocate GMP production to jurisdictions with streamlined gene therapy pathways and lower compliance costs. The United States and Germany maintain premium positioning through FDA and EMA guidance maturity, while Japan and South Korea capture share via accelerated approval frameworks. Production gravity is shifting toward clusters where CDMO capacity, academic partnership density, and reimbursement clarity converge.
United States
FDA gene therapy guidance streamlines Investigational New Drug pathways for CRISPR-based therapeutics, compressing trial initiation timelines and pulling sponsor investment toward domestic manufacturing. The agency's regenerative medicine advanced therapy designation creates priority review incentives for CAS9 programs addressing rare diseases. Boston-Cambridge and San Diego biotech clusters concentrate preclinical validation demand, with local CDMOs queueing Phase I plasmid supply contracts.
Germany
EMA's ATMP framework governs clinical-grade product standards, forcing earlier GMP adoption than competing jurisdictions and elevating compliance costs for foreign sponsors seeking European commercialization. Heidelberg and Berlin bio-clusters sustain procurement of high-fidelity CAS9 variants through dense academic-industry partnerships. Local contract manufacturers control majority capacity for viral vector production, creating bottlenecks for international sponsors.
Japan
PMDA's conditional approval pathway for gene therapies permits accelerated market access upon demonstration of early efficacy signals, attracting sponsors with compressed development timelines. The regulator's alignment with ICH gene therapy guidelines reduces duplicate testing burdens for multinational trials. Tokyo-Osaka biotech corridors host specialized consultancies supporting sgRNA design and off-target analysis for domestic startups.
Switzerland
Swissmedic's streamlined clinical trial authorization process and proximity to EMA standards enable sponsors to pilot European development strategies with lower regulatory friction than direct German filing. Basel and Zurich clusters concentrate precision genome engineering expertise, with local service providers supporting RNP complex optimization for therapeutic applications. The country's bilateral recognition agreements facilitate cross-border manufacturing qualification.
United Kingdom
Medicines and Healthcare products Regulatory Agency post-Brexit gene therapy guidance maintains alignment with EMA standards while offering independent innovation incentives through the Innovative Licensing and Access Pathway. London-Oxford-Cambridge golden triangle sustains CRISPR research procurement despite reduced Horizon Europe participation. Local biotech firms navigate patent licensing uncertainty by securing Broad Institute and University of California platform rights through UK-specific agreements.
CAS9 Technology Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with research-tool suppliers capturing volume through distributor networks while therapeutic-grade vendors compete on GMP certification depth. The vendor base concentrates around three strategic archetypes: diversified life science conglomerates with plasmid manufacturing scale, specialized sgRNA synthesis boutiques with rapid turnaround capabilities, and viral vector CDMOs with locked analytical methods. Dominant competitive moves include backward integration into GMP raw material production and geographic expansion into Japan's regenerative medicine corridor.
Among diversified life science conglomerates, Thermo Fisher Scientific and Merck KGaA exemplify the scale-driven archetype, with the former representing US-based reagent manufacturing breadth and the latter anchoring European distribution infrastructure. GenScript occupies a position within the specialized synthesis tier, with its corporate structure suggesting custom nucleic acid production focus. These three entities collectively illustrate how procurement unbundling is eroding traditional distributor attach revenue as buyers source technical support through discrete vendor relationships.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Agilent Technologies |
| Merck KGaA |
| New England Biolabs |
| GenScript |
| GeneCopoeia |
| Cellecta |
| Origene Technologies |
| Takara Bio |
| Others |
Value Chain & Pricing Dynamics
GMP-grade plasmid DNA synthesis costs cascade through three pricing tiers as material progresses from research-grade feedstock through clinical-grade purification to commercial-scale viral vector incorporation. Thermo Fisher Scientific and Merck KGaA capture margin at each conversion point, while academic buyers face 40-60 percent cost premiums for ISO 13485-certified material over research-use equivalents.
Pricing Analysis
Distributor markups on custom sgRNA synthesis contracts compress as GenScript and specialized boutiques launch direct-to-biotech procurement portals. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified RNP complexes from plasmid-based research tools and basic recombinant protein formats. Pricing pressure stems from queue bottlenecks at contract manufacturers with GMP certification, forcing sponsors toward longer-term offtake commitments. Academic labs exhibit highest price sensitivity, while pharmaceutical companies absorb premium tiers for regulatory de-risking.
Supply Chain Analysis
Freight costs for temperature-controlled viral vector shipments from United States and Germany CDMOs add 15-25 percent to delivered material costs for Asia-Pacific sponsors. Supply concentration in the United States, Germany, and Switzerland controls majority capacity for clinical-grade plasmid DNA and viral vector production. Raw material dependencies span synthetic mRNA precursors, high-fidelity polymerases, and GMP-certified cell culture media. Single-source vulnerability at specialized electroporation device manufacturers creates procurement risk for in vivo delivery programs. Distribution runs through life science distributors with regional warehousing, though direct manufacturer relationships are gaining share in high-volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CAS9 Technology Market functions as a regulatory compounder where FDA gene therapy guidance and EMA's ATMP framework revisions continuously elevate compliance thresholds, pulling sponsor investment toward certified suppliers and compressing development timelines for platform licensing decisions.
For Market Incumbents: Anticipate displacement of plasmid DNA formats by synthetic mRNA and RNP complexes, and accelerate backward integration into GMP raw material production to defend margin position against CDMO queue bottlenecks. Lock analytical method development partnerships with viral vector sponsors before EMA comparability requirements harden. Prioritize certification investment in ISO 13485 quality systems for automated electroporation instruments. For New Entrants and Emerging Players: Launch via direct-to-biotech distribution platforms targeting fragmented academic and startup segments with rapid-turnaround custom sgRNA synthesis. Japan's regenerative medicine corridor offers the most penetrable geography given PMDA's conditional approval pathway and reduced incumbent density. Base editing convergence with engineered CAS9 variants represents the highest-value white-space application for precision medicine positioning. For Investors and Strategic Acquirers: Consolidation pressure builds where patent licensing fragmentation between Broad Institute and University of California generates legal uncertainty that delays platform decisions by mid-cap biotech firms. Long-term viability favors vertically integrated specialists with captive GMP manufacturing capacity and locked viral vector analytical methods. Watch for FDA regenerative medicine advanced therapy designation signals as inflection indicators for sponsor commitment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Manufacturing Scale-Up | Queue de-risking at Thermo Fisher and Merck KGaA facilities accelerates Phase I sponsor timelines. |
| Patent Licensing Agreement | Platform rights from Broad Institute or University of California unlock downstream therapeutic development. |
| Ribonucleoprotein Format Transition | Reduced off-target liability simplifies FDA IND pathways for in vivo gene editing programs. |
| Base Editing Pipeline Diversification | Single-nucleotide precision opens inherited disease indications without double-strand break risks. |
| Japan Regulatory Expansion | PMDA conditional approval pathway captures accelerated market access for early efficacy signals. |
Study Parameters
Direct dialogue with gene therapy development executives, regulatory affairs leads at pharmaceutical sponsors, CDMO manufacturing operators, and academic lab principal investigators grounded qualitative findings in operational reality. Secondary validation drew from FDA gene therapy guidance documents, EMA ATMP framework revisions, ClinicalTrials.gov CRISPR program listings, and ISO 13485 certification databases. Bottom-up demand modeling across product formats, delivery technologies, and end-user segments triangulated against top-down market sizing from plasmid DNA and viral vector production capacity estimates.
Bottom-up segmentation analysis modeled demand across plasmid DNA, ribonucleoprotein complex, and protein formats by application type, delivery technology, and geographic regulatory cluster. Top-down validation referenced pharmaceutical pipeline disclosures and venture financing flows into gene editing platforms. CAGRs were derived from sponsor commitment velocity to CAS9 programs, GMP manufacturing capacity expansion timelines, and regulatory pathway maturation across the analysis window. Forecast inputs incorporated patent licensing resolution probability and electroporation device technical progression for solid organ delivery.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged patent litigation, regulatory rejection of RNP formats, or electroporation efficiency breakthroughs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gene Editing & CRISPR
Cas9 Nuclease Market
Gene Editing & CRISPR
India Gene Editing Market
Gene Editing & CRISPR
South Korea Gene Editing Market
Gene Editing & CRISPR
Spain Gene Editing Market
Gene Editing & CRISPR
Immunodeficient Mouse Models Market
Gene Editing & CRISPR
Zinc Finger Nuclease Technology Market
Gene Editing & CRISPR
DNA and Gene Cloning Services Market
Gene Editing & CRISPR
CRISPR Technology Market
Gene Editing & CRISPR
Japan Gene Editing Market
Gene Editing & CRISPR
Italy Gene Editing Market
Gene Editing & CRISPR
CRISPR Gene Detection and Diagnostic Market
Gene Editing & CRISPR
Base Editing Market
Gene Editing & CRISPR
Gene Editing Technology Market
Gene Editing & CRISPR
Genome Engineering Market
Gene Editing & CRISPR
Global CRISPR and Cas Genes Market
Gene Editing & CRISPR
Genetic Engineering Market