
 France Gene Editing Market | 2026-2036
France Gene Editing Market Size, Share, and Industry Trends Forecast 2026-2036
France Gene Editing Market Insights
A shift from single-source CRISPR licensing to multi-source reagent procurement is rebalancing supplier power across French research institutions. Thermo Fisher Scientific leverages its end-to-end platform portfolio to anchor large-scale genomic workflows. Cellectis differentiates through proprietary TALEN expertise in immuno-oncology applications. Lonza Group sustains its position via contract manufacturing scale for cell and gene therapy clients.
Gene editing comprises targeted nuclease systems—CRISPR-Cas9, TALEN, and ZFN—that introduce precise double-strand breaks at designated genomic loci, followed by cellular repair mechanisms enabling knockout, insertion, or correction of DNA sequences. These technologies serve therapeutic development, crop trait engineering, and industrial strain optimization. CRISPR dominates the product type landscape due to lower cost and simpler guide-RNA design, while TALEN retains niche utility in contexts requiring reduced off-target activity. The therapeutics application segment captures the deepest margin pools as pharmaceutical sponsors fund late-stage clinical programs. Research institutions represent the most fragmented end-user category, with procurement distributed across INSERM units, CNRS laboratories, and university hospitals.
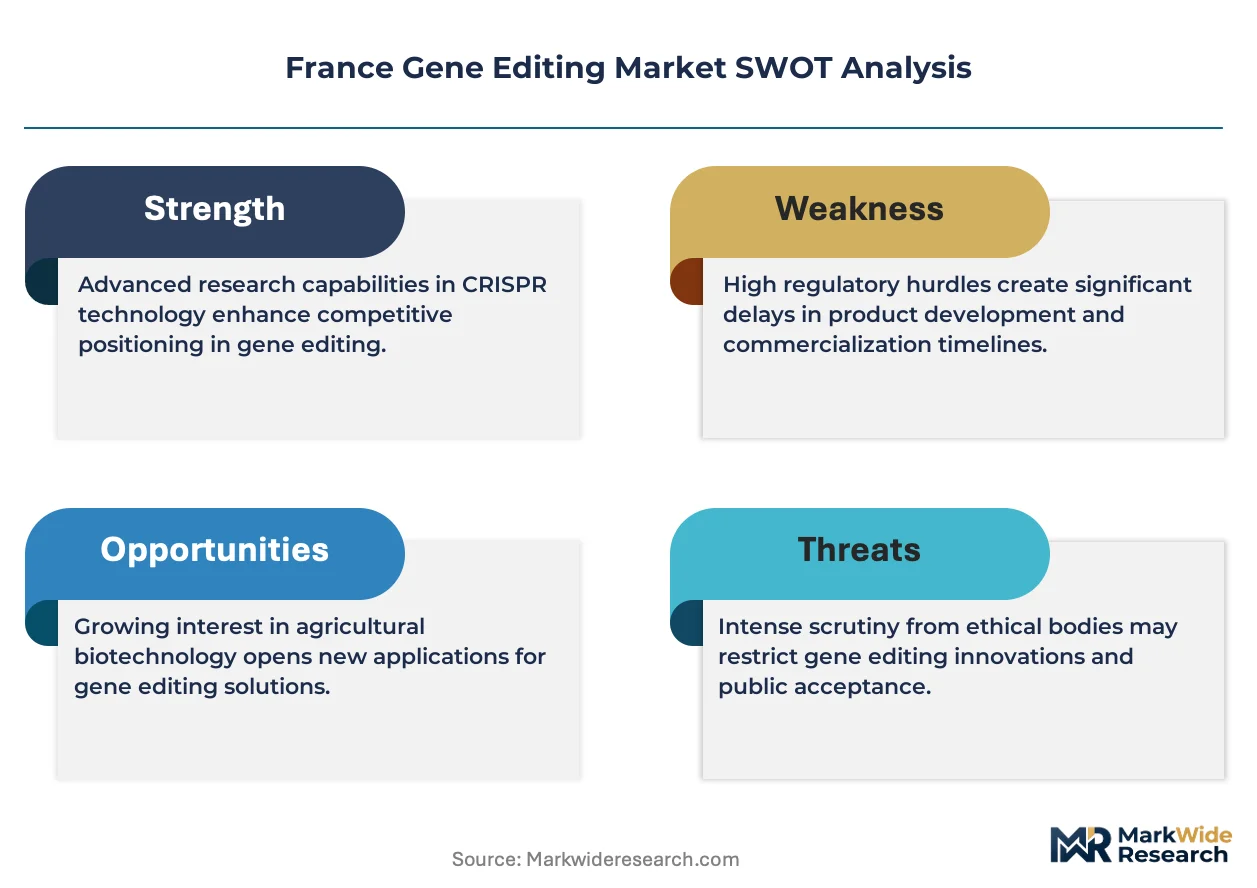
ANSM enforces clinical trial authorization protocols for gene-edited therapeutics, while EU MDR and REACH frameworks govern device classifications and reagent chemical safety respectively. CSRD disclosure requirements now compel listed biotechnology firms to report environmental and social impacts of gene-editing operations. Stakeholders must track evolving EU AI Act implications for automated CRISPR guide design software and prepare for potential dual-use export controls on gene-editing reagents.
Market Dynamics
Pharmaceutical sponsors are consolidating CRISPR therapeutic pipelines around Paris-Saclay and Lyon, compressing procurement cycles and forcing reagent suppliers to bundle platform services rather than sell discrete enzymes.
Growth Catalysts
- EU MDR Alignment:ANSM's streamlined clinical trial authorization for gene-edited therapeutics reduces regulatory lag, accelerating sponsor investment in French trial sites.
- Paris-Saclay Research Cluster:Concentrated INSERM and CNRS laboratories generate sustained demand for high-throughput CRISPR screening infrastructure.
- Base Editing Maturation:Cytosine and adenine base editors enable precise point mutations without double-strand breaks, expanding addressable therapeutic targets beyond knockout applications.
Market Restraints
- Guide RNA Synthesis Cost Volatility:Solid-phase oligonucleotide production depends on phosphoramidite feedstock pricing, squeezing margin for high-complexity multiplexed experiments.
- Off-Target Liability:CRISPR's guide-dependent cleavage generates unintended genomic alterations, forcing sponsors into expensive validation protocols that extend preclinical timelines.
- EU AI Act Uncertainty:Automated guide design algorithms face pending classification as high-risk AI systems, creating compliance ambiguity for software-integrated platforms.
Strategic Opportunities
- Auvergne-Rhône-Alpes Biotech Corridor:Lyon-based cell therapy manufacturing infrastructure remains underutilized for gene-edited autologous products, offering contract expansion potential.
- CSRD Disclosure Mandate:Listed biotechnology firms must report environmental impacts of gene-editing operations, creating service revenue for sustainability auditing specialists.
- Prime Editing Convergence:Reverse transcriptase-mediated insertion capabilities combine with CRISPR precision to address dominant genetic disorders previously inaccessible to nuclease editing.
Industry Challenges
- Bioinformatics Talent Scarcity:CRISPR data analysis pipelines require computational biologists trained in both genomic informatics and machine learning, a skill intersection scarce in French labor markets.
- GMP Facility Certification Lag:Viral vector and cell processing suites for gene-edited therapeutics face 18-24 month ANSM inspection queues, delaying commercial manufacturing readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Gene Editing Market |
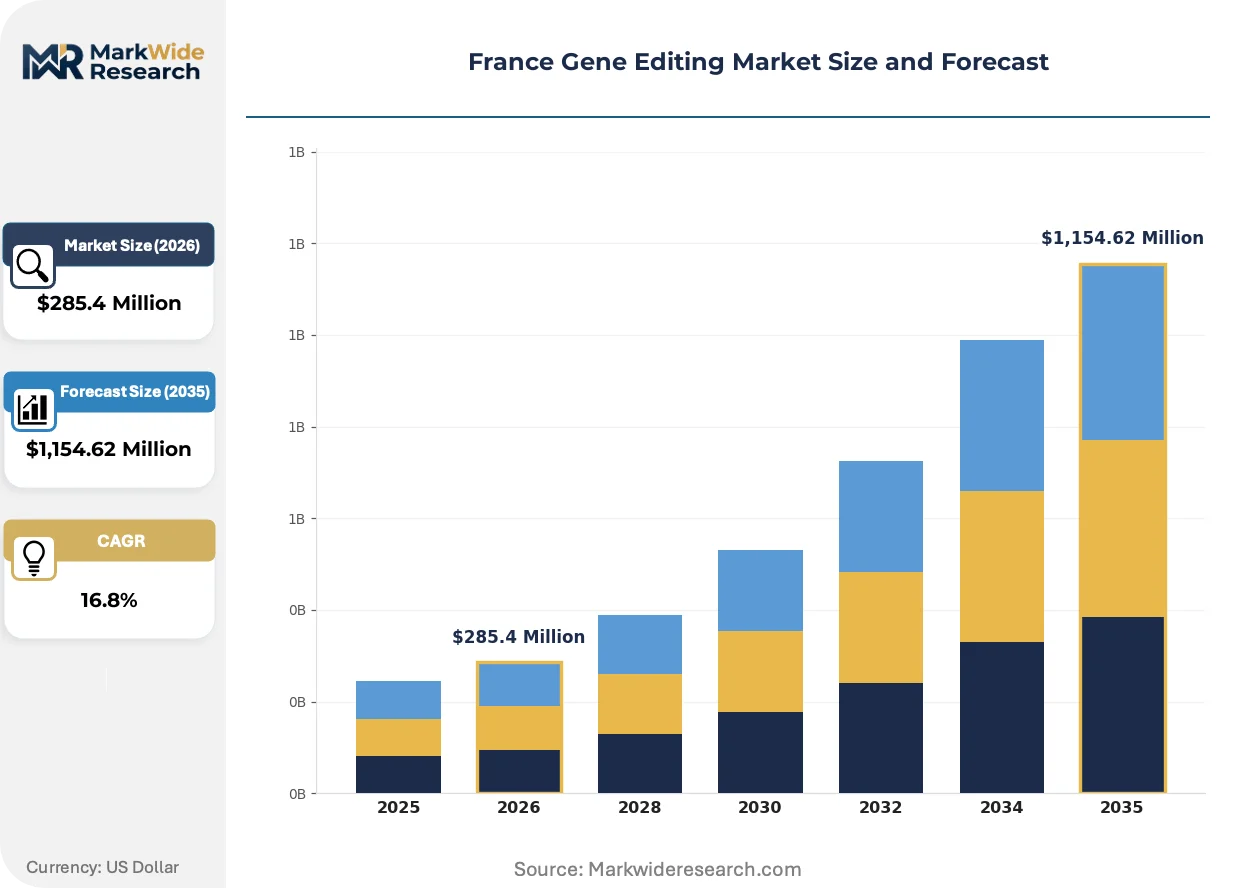
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $1,154.62 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CRISPR, TALEN, ZFN, Other Technologies Application: Therapeutics, Agriculture, Industrial Biotechnology, Genetic Diagnosis End User: Pharmaceutical Companies, Research Institutions, Agricultural Firms, Biotechnology Companies Technology: Gene Therapy, Cell Therapy, Genomic Sequencing, Synthetic Biology |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, Cellectis, Bio-Rad Laboratories, Genscript Biotech, Lonza Group, New England Biolabs, Revvity, Eligo Bioscience, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Gene Editing Market Trends and Innovations
Base editing and prime editing architectures are displacing conventional CRISPR-Cas9 in therapeutic programs, while regulatory frameworks scramble to keep pace with molecular precision advances.
Prime editing is rewriting the addressable disease landscape by enabling all 12 types of point mutation, small insertion, and small deletion without donor DNA templates or double-strand break repair errors. Sickle cell disease and Tay-Sachs programs at French university hospitals are adopting the platform for previously intractable genotypes. This precision is compressing preclinical validation timelines and reducing the regulatory burden for genotoxicity assessment.
CSRD disclosure requirements now compel listed biotechnology firms to report environmental and social impacts of gene-editing operations, including energy consumption of sequencing validation and ethical sourcing of human biological materials. The framework forces sponsors to audit supplier chains for reagent manufacturing waste. Early responders are integrating lifecycle assessment into procurement criteria, disadvantaging smaller reagent vendors lacking sustainability documentation.
Research consortia are consolidating purchasing through shared service centers rather than individual laboratory procurement, concentrating volume with platform-integrated suppliers capable of delivering CRISPR reagents, synthetic RNA, and analytical validation as bundled workflows. INSERM units in the Paris region have pioneered this model, with university hospitals in Bordeaux and Strasbourg now replicating the structure. The shift disadvantages standalone enzyme suppliers lacking adjacent service capabilities.
France Gene Editing Market Segmentation
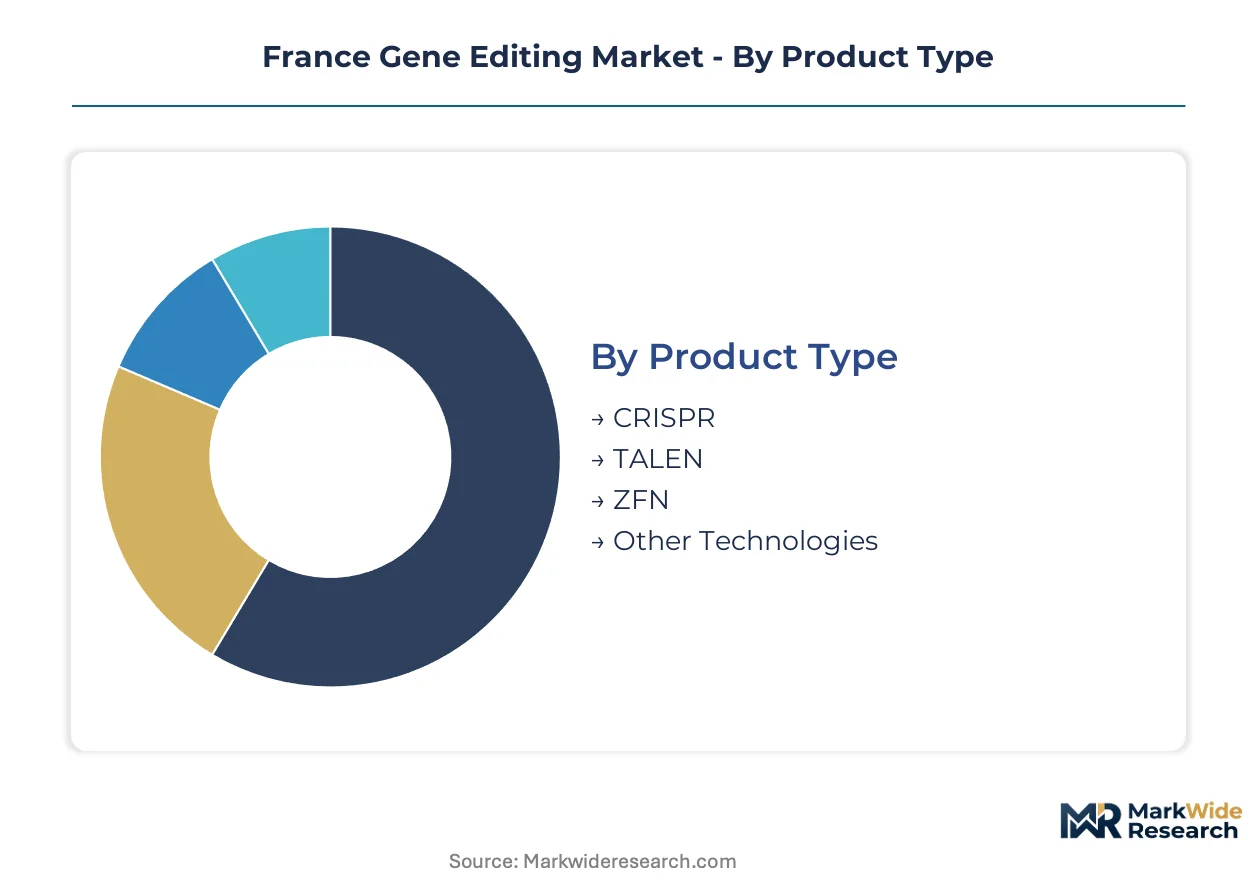
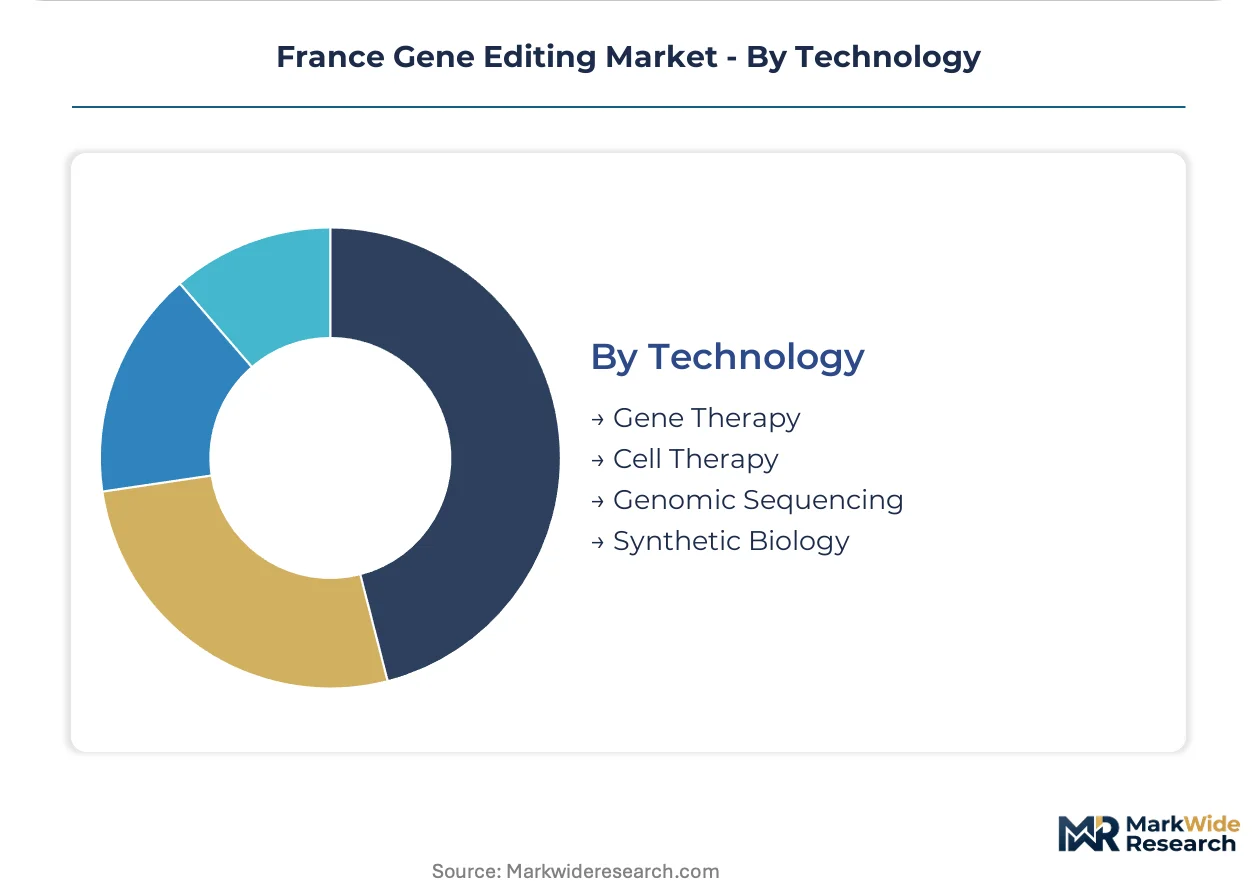
Gene editing markets fragment across multiple technical and commercial dimensions, each with distinct capital requirements, regulatory pathways, and customer procurement behaviors. Understanding these segment boundaries clarifies where value concentrates and which technology trajectories warrant strategic attention.
Product Type:
Capital intensity varies sharply across nuclease platforms, with therapeutic-grade enzyme production requiring GMP-certified facilities that smaller reagent vendors cannot sustain.
- CRISPR:RNA-guided endonuclease systems dominate procurement volumes due to simpler guide-RNA design and lower per-experiment cost. Paris-Saclay INSERM units and Lyon-based pharmaceutical sponsors drive demand for high-throughput screening formats, though off-target liability forces expensive validation protocols.
- TALEN:Transcription activator-like effector nucleases retain niche positioning where reduced off-target cleavage justifies higher reagent cost. Cellectis maintains proprietary expertise in this architecture for immuno-oncology applications, anchoring demand within French cell therapy pipelines.
- ZFN:Zinc finger nucleases represent legacy technology with declining research investment but persistent utility in specific industrial strain optimization contexts.
- Other Technologies:Base editors and prime editing systems fall outside traditional nuclease categories, attracting venture funding for precision therapeutic programs at French university hospitals.
CRISPR absorbs the bulk of installed capacity; base editing and prime editing architectures are expanding most quickly.
Application:
Margin profiles diverge based on regulatory complexity, with clinical-stage programs commanding premium pricing over research-tool applications.
- Therapeutics:Pharmaceutical sponsors fund late-stage clinical programs targeting hematologic and oncologic indications, generating the deepest margin pools. ANSM oversight under EU MDR alignment compresses trial authorization timelines, accelerating sponsor commitment to French sites.
- Agriculture:Crop trait engineering faces distinct regulatory pathways through EFSA and national varietal registration, with French seed companies exploring CRISPR-mediated disease resistance in wheat and grapevine.
- Industrial Biotechnology:Microbial strain optimization for enzyme and biofuel production relies on multiplexed editing workflows, prioritizing throughput over precision.
- Genetic Diagnosis:Research-grade sequencing validation supports carrier screening and prenatal applications, with demand concentrated in Paris university hospital networks.
Therapeutics commands the dominant revenue share; agricultural applications are gaining share fastest as regulatory clarity emerges.
End User:
Procurement consolidation patterns separate institutional buyers with platform integration needs from standalone reagent purchasers.
- Pharmaceutical Companies:Sanofi and emerging biotech sponsors centralize CRISPR procurement through therapeutic development partnerships, bundling reagent supply with analytical validation services.
- Research Institutions:CNRS laboratories and INSERM units represent the most fragmented category, with individual PIs maintaining discrete supplier relationships despite emerging shared-service consolidation.
- Agricultural Firms:Seed and agrochemical companies pursue trait engineering with lower regulatory burden than human therapeutics, though EFSA guidance remains in flux.
- Biotechnology Companies:Cell therapy specialists in the Auvergne-Rhône-Alpes corridor contract manufacturing scale from Lonza and comparable CDMOs, integrating gene editing into autologous product workflows.
Pharmaceutical companies anchor procurement volume; biotechnology companies are expanding fastest as cell therapy pipelines mature.
Technology:
Platform integration requirements determine supplier stickiness, with end-to-end workflow vendors capturing disproportionate share from fragmented point-solution providers.
- Gene Therapy:Viral vector delivery of editing machinery requires GMP manufacturing suites facing 18-24 month ANSM inspection queues, delaying commercial readiness for French sponsors.
- Cell Therapy:Ex vivo editing of autologous and allogeneic cell products drives demand for closed-system manufacturing platforms, with Lyon infrastructure underutilized relative to pipeline potential.
- Genomic Sequencing:Validation of editing outcomes depends on high-throughput sequencing capacity, with energy consumption now subject to CSRD disclosure requirements for listed firms.
- Synthetic Biology:Multiplexed pathway engineering combines gene editing with automated strain construction, attracting computational biology investment in the Paris-Saclay cluster.
Gene therapy absorbs the dominant capital commitment; cell therapy is climbing the fastest as manufacturing infrastructure scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phosphoramidite feedstock supply from German chemical producers anchors reagent manufacturing for French gene editing laboratories. This raw material corridor shapes procurement economics across Île-de-France research clusters.
Île-de-France
Paris-Saclay research cluster concentrates INSERM and CNRS laboratories driving high-throughput CRISPR screening demand. ANSM enforces clinical trial authorization protocols under EU MDR alignment for gene-edited therapeutics. Pharmaceutical sponsors in the Paris region compress procurement cycles by bundling reagent supply with analytical validation services.
Auvergne-Rhône-Alpes
Lyon biotech corridor hosts underutilized cell therapy manufacturing infrastructure for gene-edited autologous products. The national pharmaceutical regulator ANSM maintains inspection queues for GMP-certified viral vector suites. Biotechnology companies contract manufacturing scale from CDMOs while integrating gene editing into closed-system production workflows.
Provence-Alpes-Côte d'Azur
Marseille university hospital networks generate demand for genetic diagnosis applications and sequencing validation capacity. CNRS laboratories in the region participate in national research consortia consolidating purchasing through shared service centers. Local biotechnology startups attract venture funding for precision therapeutic programs targeting previously intractable genotypes.
Hauts-de-France
Lille metropolitan area anchors agricultural biotechnology research with seed companies exploring CRISPR-mediated disease resistance in wheat varieties. EFSA guidance frameworks govern crop trait engineering pathways distinct from human therapeutic regulations. Regional research institutes coordinate with Paris-based pharmaceutical sponsors on multiplexed editing workflows for industrial strain optimization.
France Gene Editing Market Competitive Landscape
Global majors compete with regional champions across platform integration and therapeutic specialization dimensions. The supplier base separates into consolidated end-to-end workflow vendors and fragmented point-solution enzyme producers. Three archetypes dominate: platform-integrated multinationals anchoring large-scale genomic workflows, TALEN specialists differentiating through proprietary nuclease expertise, and contract manufacturers scaling GMP production for cell therapy clients. Competitive moves concentrate on strategic partnerships bundling reagent supply with analytical services, and backward integration into phosphoramidite feedstock security.
Among platform-integrated multinationals, Thermo Fisher Scientific and Merck KGaA occupy positions anchoring high-throughput screening infrastructure across French research institutions. Cellectis represents the therapeutic-specialist archetype with proprietary TALEN positioning. Lonza Group exemplifies the manufacturing-scale tier serving cell therapy sponsors in the Auvergne-Rhône-Alpes corridor.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| Cellectis |
| Bio-Rad Laboratories |
| Genscript Biotech |
| Lonza Group |
| New England Biolabs |
| Revvity |
| Eligo Bioscience |
| Others |
Pricing and Supply Chain Analysis
Captive phosphoramidite sourcing from German chemical producers anchors reagent manufacturing economics for French gene editing laboratories, concentrating upstream control with integrated suppliers while compressing margins for standalone enzyme vendors lacking backward integration into feedstock security.
Pricing Analysis
Service-bundling differentiation separates platform-integrated vendors from discrete reagent suppliers, with Thermo Fisher Scientific and Merck KGaA commanding premium positioning through combined CRISPR reagent, synthetic RNA, and analytical validation workflows. Price differentiation rests on GMP certification tier and after-sales technical support depth, with clinical-grade enzymes carrying substantial premiums over research-use-only grades. Cost compression in research-grade CRISPR kits is intensifying because INSERM shared-service centers consolidate procurement volume and demand standardized pricing. Academic research institutions exhibit highest price sensitivity due to fixed grant funding, while pharmaceutical sponsors prioritize reliability and regulatory documentation over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from ANSM-qualified pharmaceutical sponsors require French biotech firms to qualify multiple reagent suppliers for clinical-grade gene editing programs, preventing single-source dependency despite consolidation economics favoring platform vendors. Geographic supply concentration centers on Germany for phosphoramidite feedstocks, Switzerland for precision fermentation capacity, and the United States for CRISPR patent-licensed enzyme production. Raw material dependencies include synthetic oligonucleotides, recombinant Cas proteins, and high-purity cell culture media. Single-source vulnerability persists for TALEN engineering expertise concentrated at Cellectis. Distribution runs through authorized distributors for research-grade products and direct contractual relationships for GMP-certified therapeutic supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GMP facility certification queues stretching 18-24 months under ANSM oversight constrain commercial manufacturing readiness, propping pricing power for CDMOs with cleared viral vector and cell processing suites.
For Market Incumbents: Deepen TALEN engineering capabilities to defend against CRISPR base editing substitution in precision therapeutic programs, while expanding captive phosphoramidite production to secure margin against German chemical supplier pricing volatility. Anchor platform stickiness through integration of automated guide design software ahead of EU AI Act high-risk system classification deadlines. For New Entrants and Emerging Players: Direct-to-researcher digital channels offer lower customer acquisition cost than field sales forces for penetrating fragmented CNRS laboratory procurement, where individual PIs retain discrete supplier relationships. Target agricultural biotechnology applications in Hauts-de-France seed company networks, where EFSA regulatory clarity remains pending and incumbent platform vendors have limited presence. Emphasize sustainability documentation and lifecycle assessment capabilities to capture CSRD-driven procurement criteria from listed biotechnology firms. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by platform-integrated multinationals seeking TALEN or prime editing specialization, with valuation premia attaching to GMP-certified manufacturing assets. Long-term viability over the coming decade hinges on regulatory navigation capabilities under evolving EU MDR and AI Act frameworks. Monitor ANSM inspection queue clearance rates as the critical inflection signal for commercial manufacturing capacity availability.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Facility Certification | ANSM clearance unlocks commercial manufacturing for gene-edited therapeutics in Lyon corridor. |
| Prime Editing Pipeline Advancement | French university hospital programs address previously intractable dominant genetic disorders. |
| Phosphoramidite Backward Integration | Captive feedstock production insulates margin from German chemical supplier pricing swings. |
| Shared-Service Center Partnership | INSERM procurement consolidation concentrates volume with platform-integrated vendors. |
| EU AI Act Compliance Investment | Automated guide design software classification determines regulatory burden for integrated platforms. |
Research Methodology
Independent corroboration across primary interviews with gene therapy development executives, regulatory affairs leads at ANSM, CDMO procurement managers, and CRISPR platform engineers, combined with secondary validation through EMA submissions, ClinicalTrials.gov records, and SEC filings from listed biotechnology firms, underwrites the qualitative findings. Bottom-up segmentation modeling triangulates against top-down market sizing from trade flow analysis.
Comparable historical reference periods spanning pre-pandemic, pandemic disruption, and recovery phases anchor the forecast window across the projection horizon. The analytical framework models segmentation dimensions including nuclease platform type, therapeutic versus research application, end-user institutional category, and GMP certification tier. CAGRs derive from installed base growth, pricing trajectory assumptions, and penetration rate analysis for base editing and prime editing architectures. Forecast inputs incorporate ANSM inspection queue duration, EU MDR implementation timelines, and phosphoramidite feedstock pricing indices.
The model holds under stable regulatory alignment between ANSM and EU MDR frameworks; deviation in EU AI Act enforcement stringency or phosphoramidite supply disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gene Editing & CRISPR
Knockout Mice Model Market
Gene Editing & CRISPR
DNA Modifying Agents Market
Gene Editing & CRISPR
Gene Editing Off-Target Effect Detection Test Systems Market
Gene Editing & CRISPR
UK Gene Editing Market
Gene Editing & CRISPR
Zinc Finger Nuclease Technology Market
Gene Editing & CRISPR
Global Recombinant DNA (Rdna) Technology Market
Gene Editing & CRISPR
Rare NGR1 Fusion Market
Gene Editing & CRISPR
China Gene Editing Market
Gene Editing & CRISPR
Brazil Gene Editing Market
Gene Editing & CRISPR
CRISPR Genomic Cure Market
Gene Editing & CRISPR
Global Plant Breeding and CRISPR Plant Market
Gene Editing & CRISPR
Genome Editing Market
Gene Editing & CRISPR
Gene Editing Market
Gene Editing & CRISPR
Gene Editing Tools Market
Gene Editing & CRISPR
CRISPR Gene Detection and Diagnostic Market
Gene Editing & CRISPR
US Gene Editing Market