
 Spain Food Flavor and Enhancer Market | 2026-2036
Spain Food Flavor and Enhancer Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Food Flavor and Enhancer Market Analytics
Buyer concentration across Spain's mid-sized food manufacturers is broadening as regional cooperatives and private-label specialists multiply their flavor procurement budgets. Givaudan leverages its Barcelona technical center to sustain close formulation partnerships with Iberian beverage producers. Symrise AG anchors its position through specialized savory and sweet taste solutions tailored to Mediterranean palates. International Flavors & Fragrances Inc. competes by controlling distribution networks that reach smaller processors in Valencia and Galicia.
Food flavor and enhancer systems comprise volatile aromatic compounds, taste-active molecules, and carrier substrates engineered to deliver consistent sensory profiles in processed foods. These formulations typically specify minimum purity thresholds for key actives and must withstand thermal degradation during pasteurization, baking, or extrusion processes. Natural flavor types command premium positioning as Spanish retailers enforce stricter clean-label standards, while liquid forms dominate beverage applications where solubility and dosing precision matter. Powder formats lead in bakery and snacks, where shelf stability and dry-blend compatibility reduce manufacturing complexity.
Spain's national food safety agency enforces EU Regulation 1333/2008 on food additives alongside EFSA guidance for novel flavor substances, while REACH compliance governs synthetic precursor chemicals. The EU Green Deal's pesticide reduction targets are reshaping agricultural input availability for natural extract sourcing. Firms must monitor regulatory divergence between Madrid's interpretation of EFSA thresholds and emerging autonomous community labeling requirements that exceed baseline EU mandates.
Market Dynamics
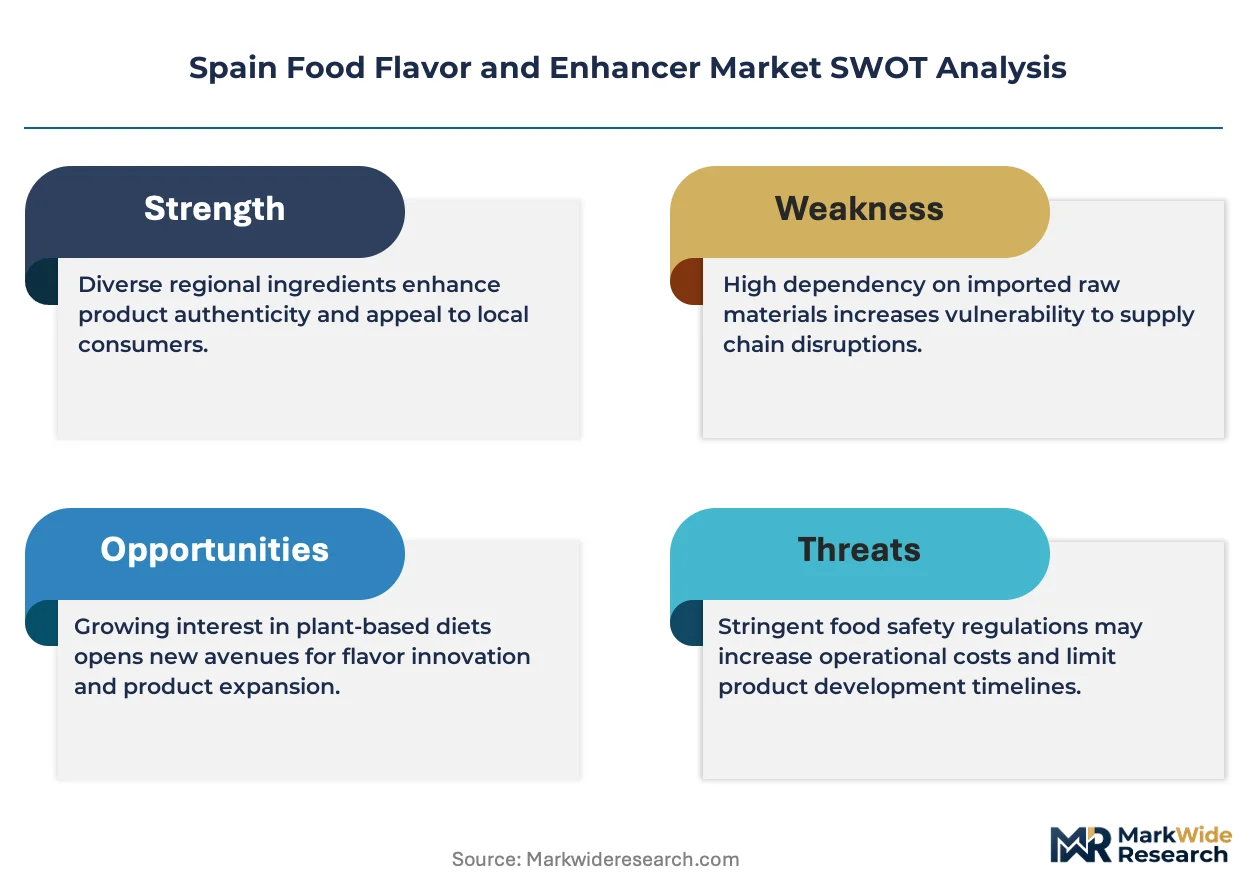
Spain's food flavor and enhancer sector faces structural compression from the EU Green Deal's Farm to Fork Strategy, which mandates pesticide reduction targets and accelerates reformulation timelines for natural extract sourcing across Iberian processing facilities.
Growth Catalysts
- Clean-label mandates:Spanish retailers enforce stricter additive disclosure requirements under autonomous community labeling rules exceeding baseline EU standards, compelling processors to upgrade to natural flavor systems.
- Beverage sector expansion:Catalonia's dense cluster of beverage producers drives procurement volumes for liquid flavor formats with solubility-optimized profiles.
- EFSA novel substance pathways:Streamlined safety assessments for natural extracts accelerate product registration timelines compared to synthetic additive approvals.
Market Restraints
- Agricultural input volatility:EU pesticide reduction targets under the Green Deal constrain raw material availability for citrus and herb-based extracts sourced from Valencia growing regions.
- Supply concentration risk:Natural vanilla and saffron extracts depend on concentrated Moroccan and Iranian supplier bases vulnerable to climate disruption.
- Thermal stability limitations:Natural flavor actives degrade faster than synthetic equivalents during high-temperature extrusion processes used in snack manufacturing.
Strategic Opportunities
- Basque Country savory innovation:Underpenetrated demand for umami-enhancing yeast extracts exists among pintxo and prepared seafood processors in San Sebastián and Bilbao corridors.
- Plant-based meat analogues:Emerging application for masking off-notes in pea and soy protein formulations creates white space for bitter-blocking flavor technologies.
- Digital flavor matching platforms:AI-driven formulation tools reduce development cycles from months to weeks for mid-sized private-label specialists.
Industry Challenges
- Flavor chemist scarcity:Spanish universities produce insufficient graduates trained in gas chromatography-mass spectrometry analysis for volatile compound identification.
- Clean-label certification timelines:Organic and non-GMO verification processes extend supplier onboarding by 8-14 months, delaying product launches.
- Legacy ERP integration:Small cooperatives in Galicia lack compatible systems for real-time inventory tracking with multinational flavor houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Food Flavor and Enhancer Market |
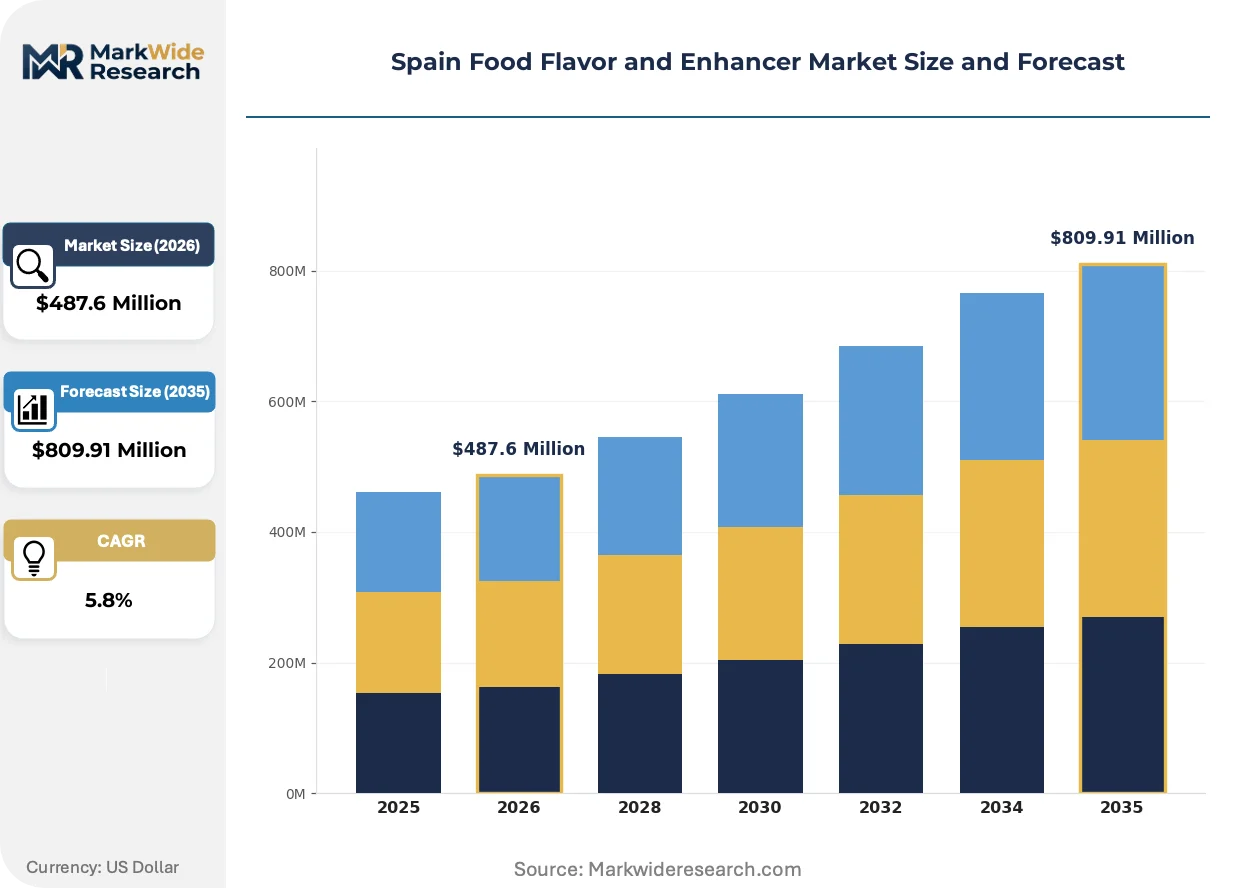
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Flavor Type: Natural, Synthetic, Organic, Artificial Form: Liquid, Powder, Granular, Paste Application: Bakery, Beverages, Sauces, Snacks End User: Food Manufacturers, Restaurants, Home Cooks, Catering Services |
| Companies Covered | Archer Daniels Midland Company, Lucta Group, Givaudan, Symrise AG, Flavorchem Corporation, International Flavors & Fragrances Inc., Koninklijke DSM N.V, Takasago International Corporation, Firmenich SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Food Flavor and Enhancer Market Evolving Landscape
Biotechnology-derived flavor precursors and precision fermentation platforms are displacing conventional extraction methods, while digital formulation tools compress development timelines for Spanish processors adapting to accelerated clean-label deadlines.
Precision fermentation for natural vanillin and citrus terpenes is integrating into Spanish flavor house R&D pipelines. Mid-sized beverage processors in Catalonia adopt these biosynthesized actives at pilot scale. The technology is integrating supply chain resilience by reducing dependency on weather-sensitive agricultural harvests.
REACH compliance for synthetic precursor chemicals tightens registration requirements for hydrolyzed vegetable protein manufacturers. Industrial consequence includes accelerated migration toward enzymatic processing methods. Basque Country savory specialists face the steepest reformulation costs as they retrofit facilities to meet 2025 dossier deadlines.
Buyer consolidation among Spanish retail cooperatives compresses supplier negotiation cycles from annual to quarterly reviews. Regional private-label specialists in Valencia and Galicia now demand fixed-price multi-year contracts with volume guarantees. This pattern concentrates procurement leverage with distributors serving the Mercadona and Carrefour España supply bases.
Spain Food Flavor and Enhancer Market Segmentation
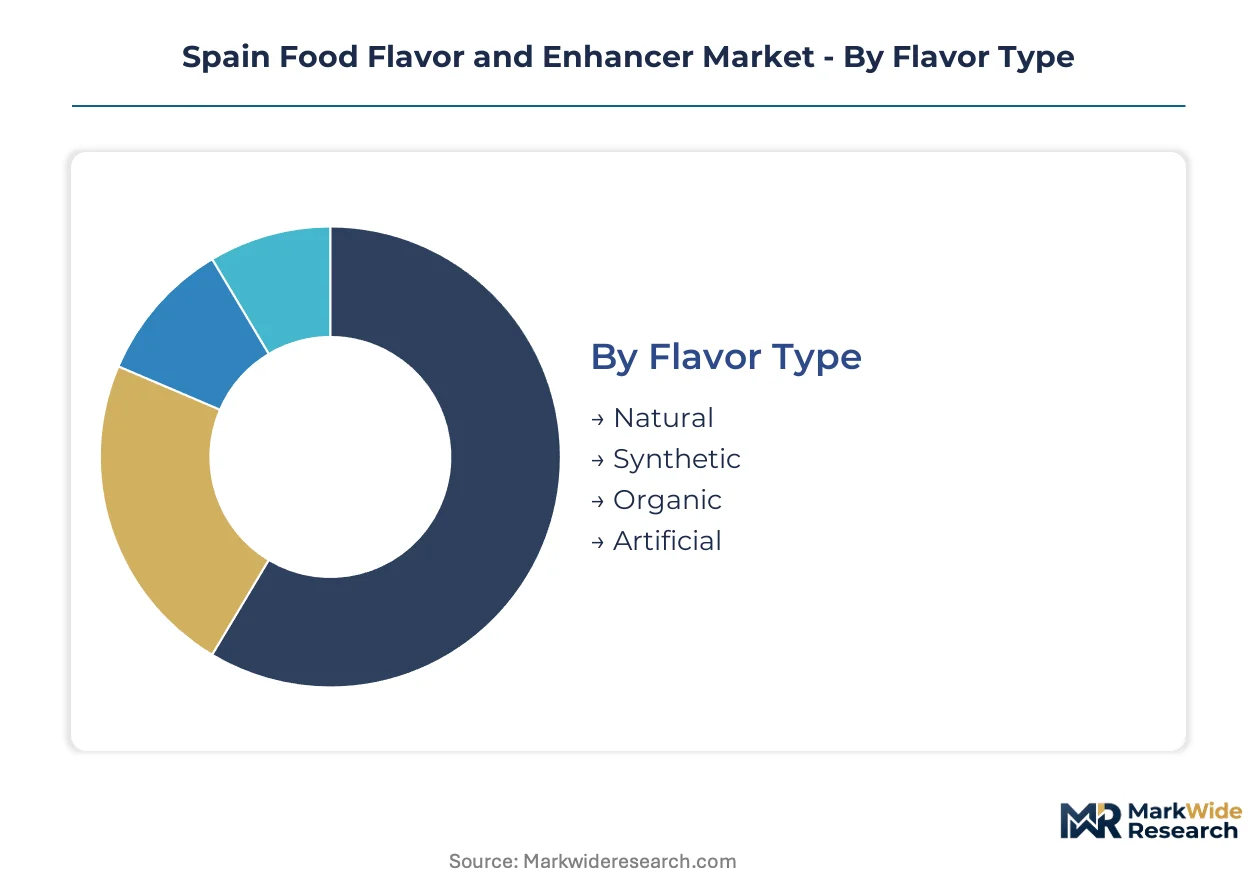
Flavor and enhancer procurement patterns across Spain diverge sharply by technical specification and end-use requirements. Catalonia's beverage clusters, Basque savory processors, and Valencia's citrus extractors each impose distinct formulation constraints that reshape supplier priorities.
Flavor Type:
Standardization dominates commodity synthetic production while natural extracts demand bespoke sourcing relationships with Mediterranean agricultural cooperatives.
- Natural:Derived from citrus peels, herbs, and fermentation processes, these extracts carry volatile aromatic compounds requiring cold-chain integrity from Valencia growing regions through Barcelona processing facilities. Clean-label mandates from autonomous community labeling rules exceeding baseline EU standards compel reformulation across Iberian premium lines.
- Synthetic:Engineered aromatic molecules deliver batch-to-batch consistency at lower unit cost. Thermal stability during high-temperature extrusion processes makes these formulations indispensable for snack manufacturers in Galicia where equipment retrofit costs delay natural migration.
- Organic:Certified extracts command premium positioning through restricted pesticide regimens aligned with EU Green Deal Farm to Fork targets.
- Artificial:Laboratory-synthesized taste actives face tightening EFSA scrutiny under novel substance pathways, compressing approval timelines relative to natural alternatives.
Most installed capacity flows through Synthetic. Expansion is steepest in Natural.
Form:
Volume throughput and dosing precision requirements determine format selection across Iberian processing infrastructure.
- Liquid:Solubility-optimized profiles dominate Catalonia's beverage corridor where homogeneous dispersion in aqueous matrices prevents phase separation. Pasteurization compatibility testing consumes 12-16 weeks of technical validation with Barcelona-area technical centers.
- Powder:Shelf-stable formats reduce moisture sensitivity for bakery and snack applications across Castile-León manufacturing zones. Dry-blend compatibility with flour matrices eliminates hydration-stage complexity.
- Granular:Free-flowing particles suit automated dosing equipment prevalent in mid-sized Andalusian cooperatives.
- Paste:High-viscosity concentrates serve prepared sauce manufacturers in Murcia seeking intense flavor delivery at reduced water content.
Production gravity centers on Liquid. Climbing the fastest is Powder.
Application:
End-use thermal regimes and shelf-life specifications fragment procurement specifications across Spanish food manufacturing.
- Beverages:Solubility and clarity requirements drive liquid format dominance. Catalonia's dense producer cluster sustains dedicated technical service relationships with flavor houses maintaining Barcelona innovation centers.
- Bakery:Maillard reaction compatibility and oven stability tests filter supplier qualification. Powder formats integrate with dry premix operations across Castile-La Mancha industrial bakeries.
- Sauces:Acid stability under vinegar and tomato matrices constrains extract selection for Murcia processors.
- Snacks:Extrusion temperatures exceeding 180°C degrade natural actives, preserving synthetic share in Galicia's fried product lines.
Demand concentrates in Beverages. Gaining share fastest is Bakery.
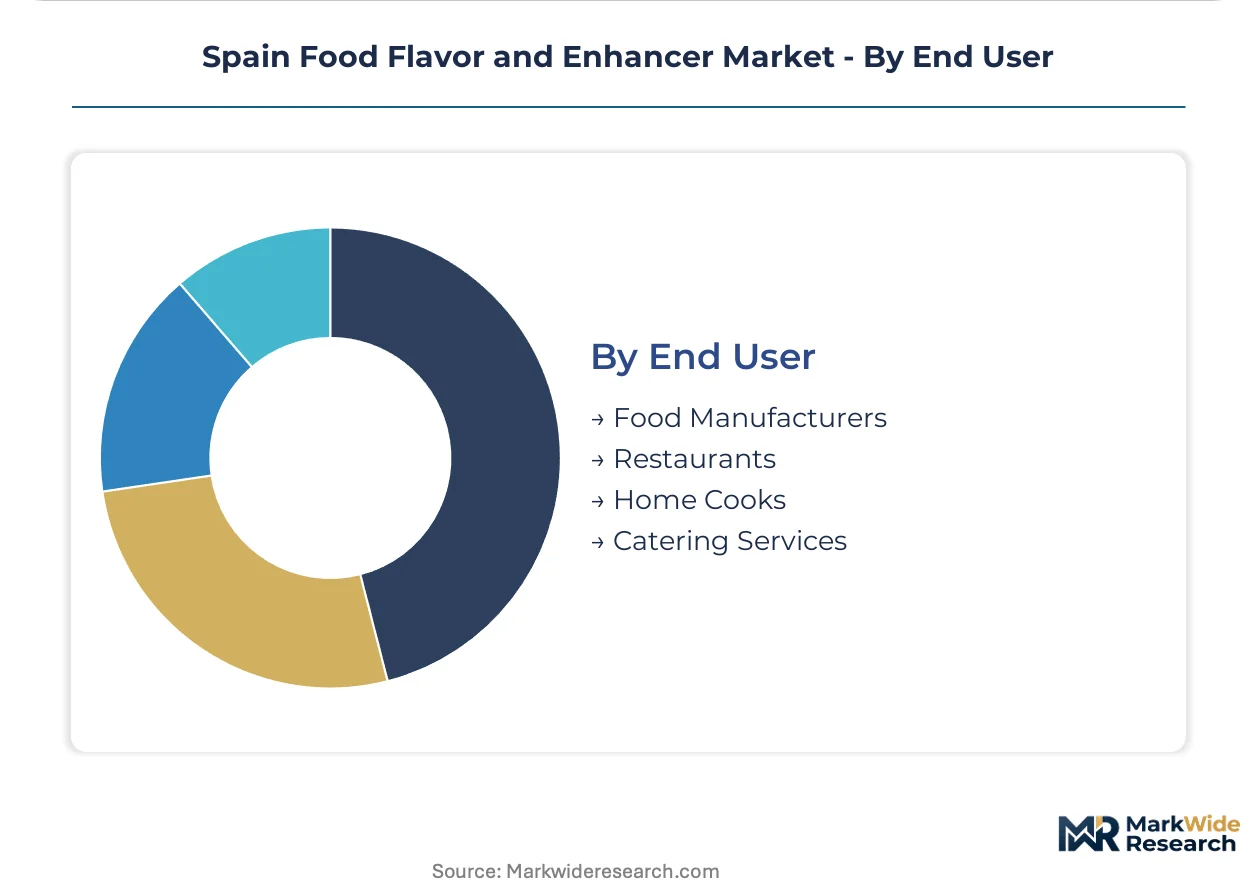
End User:
Scale economies and formulation sophistication separate industrial procurement from foodservice spot purchasing.
- Food Manufacturers:Integrated R&D functions demand collaborative development partnerships with technical service teams. Annual procurement volumes exceeding 50 tonnes unlock dedicated production runs and custom masking solutions.
- Restaurants:Basque Country pintxo bars and Madrid fine-dining groups source concentrated bases through specialized distributors.
- Home Cooks:Retail-format extracts reach consumers through Mercadona and Carrefour España private-label programs.
- Catering Services:Volume foodservice operators in conference and event sectors prioritize cost-stable synthetic options.
Procurement leverage concentrates with Food Manufacturers. Steepest expansion trajectory sits with Restaurants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's beverage manufacturers source cleaner-label flavor systems faster than Spanish processors, yet both face identical EFSA novel substance approval timelines that compress product development windows.
Catalonia
Beverage producers in Barcelona and Girona drive liquid flavor procurement for solubility-optimized profiles in premium water and functional drinks. EFSA guidance on natural extract safety assessments accelerates registration compared to synthetic pathways. The Penedès wine corridor increasingly demands flavor masking solutions for low-alcohol product lines.
Basque Country
Pintxo manufacturers and prepared seafood processors in San Sebastián and Bilbao sustain demand for umami-enhancing yeast extracts and savory taste solutions. Spain's national food safety agency enforces EU Regulation 1333/2008 alongside autonomous community labeling requirements exceeding baseline EU standards. The region's culinary innovation hubs anchor collaborative development partnerships with technical service teams from multinational flavor houses.
Valencia
Citrus extractors and agricultural cooperatives supply cold-chain dependent volatile aromatic compounds from orange and lemon growing regions. The EU Green Deal's Farm to Fork Strategy pesticide reduction targets constrain raw material availability for herb-based extracts. Mid-sized processors in the metropolitan area pilot precision fermentation platforms for biosynthesized terpenes to reduce weather-sensitive harvest dependency.
Madrid
Centralized procurement functions for national retail cooperatives concentrate supplier negotiation leverage and compress review cycles from annual to quarterly. REACH compliance governs synthetic precursor chemicals used in hydrolyzed vegetable protein manufacturing. The region's logistics infrastructure connects formulation partnerships between Barcelona technical centers and Castile-León bakery operations.
Galicia
Snack manufacturers maintain synthetic flavor share due to thermal stability requirements during high-temperature extrusion processes exceeding 180°C. Legacy ERP integration gaps delay real-time inventory tracking compatibility with multinational flavor house systems. Fried product lines in the region preserve equipment configurations that defer natural migration timelines.
Spain Food Flavor and Enhancer Market Competitive Landscape
Swiss and German producers anchor the premium formulation tier; Spanish regional specialists hold procurement relationships with autonomous community processors. The market structure concentrates around multinational flavor houses with Barcelona technical centers and mid-sized private-label distributors serving Mercadona and Carrefour España supply bases. Three archetypes dominate: integrated taste solution providers, precision fermentation technology developers, and regional distribution specialists. Competitive moves center on collaborative formulation partnerships and multi-year fixed-price contracts with volume guarantees.
Among Switzerland-anchored integrated providers, Givaudan and Firmenich SA occupy positions exemplifying technical service depth, while Symrise AG represents the German savory specialization archetype. These entities anchor the premium tier through sustained formulation partnerships with Iberian beverage and prepared food manufacturers. Regional procurement leverage concentrates with distributors serving retail cooperative supply bases.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Lucta Group |
| Givaudan |
| Symrise AG |
| Flavorchem Corporation |
| International Flavors & Fragrances Inc. |
| Koninklijke DSM N.V |
| Takasago International Corporation |
| Firmenich SA |
| Others |
Value Network & Pricing Analysis
Flavor chemist concentration in Catalonia and the Basque Country widens pricing-tier spreads between premium natural extracts and commodity synthetic formulations, as labor-cost differentials between Barcelona technical centers and Galicia processing facilities compound raw material premiums.
Pricing Analysis
Capacity additions in Valencia citrus extraction facilities are reshaping price floors for natural terpene-based actives. Three-tier pricing structure across premium certified-organic, standard natural, and economy synthetic levels stratifies procurement budgets. Price differentiation hinges on EU organic certification status and volume-scale commitments exceeding fifty tonnes annually. Pricing pressure stems from Moroccan vanilla and Iranian saffron supply volatility, with retail cooperatives in Madrid demanding fixed-price multi-year contracts that squeeze mid-tier suppliers.
Supply Chain Analysis
Citrus terpene supply rests on Valencia agricultural cooperatives and Moroccan vanilla orchards, with secondary dependencies on Iranian saffron harvesting regions. Raw material inputs include cold-chain dependent volatile aromatic compounds, fermentation-derived yeast extracts, and enzymatically processed hydrolyzed vegetable proteins. Single-source vulnerability concentrates in weather-sensitive agricultural harvests for natural extracts. Distribution runs through multinational flavor houses with Barcelona technical centers serving Iberian beverage clusters, supplemented by regional distributors supplying Mercadona and Carrefour España private-label programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's Farm to Fork Strategy operates as a regulatory compounder, with pesticide reduction targets and accelerated natural extract approval pathways reshaping procurement priorities across Iberian food manufacturers.
For Market Incumbents: Deepen collaborative formulation partnerships with Basque Country pintxo processors and Catalonia beverage clusters to lock in multi-year technical service contracts. Expand precision fermentation capabilities for biosynthesized vanillin and citrus terpenes to reduce weather-sensitive harvest dependency. Invest in Barcelona technical center capacity additions to defend against emerging biotechnology-derived flavor developers.
For New Entrants and Emerging Players: Specialized distributors serving regional private-label specialists in Valencia and Galicia represent the most accessible channel entry point. Target underpenetrated umami-enhancing yeast extract demand among San Sebastián prepared seafood processors. Pursue plant-based meat analogue masking technology partnerships with pea and soy protein formulation startups.
For Investors and Strategic Acquirers: Mid-sized biotechnology flavor houses are the most active acquirer in this space, consolidating precision fermentation platforms and AI-driven formulation tools. Five-to-ten year viability hinges on clean-label certification infrastructure and REACH-compliant synthetic precursor alternatives. Watch for EFSA novel substance approval timeline compression as inflection indicator for natural extract valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Biosynthesized vanillin reduces dependency on Moroccan climate-vulnerable harvests. |
| Clean-Label Certification Investment | Organic and non-GMO verification accelerates supplier onboarding with Madrid retail cooperatives. |
| AI-Driven Formulation Platform Deployment | Digital flavor matching compresses development cycles for mid-sized private-label specialists. |
| Backward Integration into Valencia Citrus Extraction | Captive supply of cold-chain terpenes secures volatile aromatic compound integrity. |
| Basque Country Technical Partnership Expansion | Collaborative development with San Sebastián pintxo processors anchors savory specialization. |
Research Methodology
Coverage spans Catalonia, Basque Country, Valencia, Madrid, and Galicia, with primary inputs from each autonomous community's food processing clusters. The approach combines primary interviews with flavor chemists, procurement leads at mid-sized cooperatives, technical R&D directors at multinational flavor houses, and category buyers at retail cooperatives, validated against secondary sources including EFSA guidance documents, EU Regulation 1333/2008 filings, REACH registration databases, and Spanish autonomous community labeling requirement disclosures. Bottom-up procurement volume estimates triangulate with top-down market sizing from trade flow analysis.
Segmentation granularity extends to flavor type, form, application, and end-user dimensions, with additional modeling for thermal stability requirements across extrusion and pasteurization processes. Value projections incorporate price-tier stratification between synthetic and natural extracts across the analysis window. CAGR derivation reflects volume-weighted segment growth rates applied to baseline procurement patterns. Industry-specific inputs include EFSA novel substance approval pipeline status and EU Green Deal Farm to Fork implementation timelines.
Revisions become necessary when EFSA regulatory threshold interpretations diverge from Madrid's national implementation, or when autonomous community labeling requirements exceed baseline EU mandates beyond modeled scenarios. Forecasts reflect documented assumptions regarding precision fermentation technology adoption curves and natural extract raw material availability. A small set of named triggers—climate disruption in Moroccan vanilla regions, REACH compliance deadline acceleration, and retail cooperative consolidation pace—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Dysphagia Diet Thickening Agents Market
Food Enhancers and Additives
Food Raising Agents Market
Food Enhancers and Additives
Liquid Smoke Market
Food Enhancers and Additives
United Kingdom Water Enhancer Market
Food Enhancers and Additives
Asia-Pacific Food Flavor and Enhancer Market
Food Enhancers and Additives
South Africa Water Enhancer Market
Food Enhancers and Additives
Fortified Salts Market
Food Enhancers and Additives
Africa Water Enhancer Market
Food Enhancers and Additives
North America Food Thickeners Market
Food Enhancers and Additives
Fortified Eggs Market
Food Enhancers and Additives
Used Cooking Oil Market
Food Enhancers and Additives
South Korea Fat Replacers Market
Food Enhancers and Additives
Vegetable Shortening Market
Food Enhancers and Additives
Isoprenol Market
Food Enhancers and Additives
Asia-Pacific Flavor Enhancer Market
Food Enhancers and Additives
Isomalt Market