
 Food Raising Agents Market | 2026-2036
Food Raising Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Food Raising Agents Market Analytics
Specialized fermentation technologists is reorganizing capacity planning across European and North American facilities. Lesaffre leverages its century-old strain libraries to dominate fresh yeast supply chains. DSM sustains competitive pressure through biotechnology-driven nutrient yeast platforms. AB Mauri anchors Asia-Pacific distribution networks with regionally adapted product portfolios.
Food raising agents comprise chemical and biological compounds that generate carbon dioxide, acid, or steam to induce leavening in dough and batter systems; baking powder typically contains sodium bicarbonate paired with monocalcium phosphate and cornstarch, requiring controlled moisture activation to prevent premature reaction. Yeast segments command the largest revenue pool due to irreplaceable roles in artisanal and industrial bread production, while baking soda occupies thin-margin commodity channels where price sensitivity limits differentiation. Powder form leads volume shipments for shelf stability and dosing precision, though liquid yeast concentrates gain traction in high-throughput commercial bakeries seeking reduced handling steps.
EFSA purity standards, EU Green Deal sustainability benchmarks, and FDA GRAS determinations collectively constrain formulation flexibility while creating compliance-driven switching costs for reformulated products. REACH chemical registration requirements in Europe add testing burdens for imported synthetic raising agents. Stakeholders must weigh biotechnology investments against regulatory lag times as jurisdictions diverge on novel strain approvals and carbon-footprint labeling mandates.
Market Dynamics
EFSA additive disclosure mandates and EU Green Deal carbon-footprint labeling are forcing simultaneous reformulation of established product lines and acceleration of biotechnology-derived alternatives across European commercial bakeries.
Growth Catalysts
- Clean-label bakery expansion:Artisanal bread producers in Germany and France are eliminating synthetic preservatives, creating pull for biological raising agents with shorter ingredient lists.
- REACH chemical registration:European testing requirements for imported synthetic compounds are creating compliance-driven switching costs that favor regional yeast suppliers with established dossiers.
- Liquid yeast concentrate adoption:High-throughput commercial bakeries are reducing handling steps through pumpable delivery systems that integrate directly into continuous mixing lines.
Market Restraints
- Fresh yeast supply concentration:Strain library control by century-old European fermentation specialists limits new entrant access to proven commercial cultures.
- Monocalcium phosphate input volatility:Phosphate rock sourcing disruptions and energy-intensive processing create margin pressure for baking powder manufacturers.
- Novel strain approval lag:EFSA's multi-year safety assessment timelines for genetically modified yeast variants delay product pipeline commercialization.
Strategic Opportunities
- Carbon-footprint labeling mandate:EU Green Deal protocols create first-mover advantage for suppliers with verified lifecycle data and low-carbon fermentation processes.
- Biotechnology-nutrition convergence:Fortified yeast platforms combining leavening function with B-vitamin and protein enrichment address dual-demand from health-conscious consumers.
- Direct-to-bakery digital channels:Specialized fermentation technologists are bypassing traditional distribution through predictive replenishment platforms for industrial-scale buyers.
Industry Challenges
- Fermentation technologist scarcity:Specialized strain development and scale-up expertise concentrates within legacy European facilities, constraining capacity expansion timelines.
- Dual certification burden:Products requiring both EFSA purity standards and FDA GRAS determinations face parallel testing costs and divergent documentation requirements.
- Legacy equipment incompatibility:Liquid yeast concentrate adoption requires capital retrofit of temperature-controlled storage and metering systems at mid-scale bakeries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Raising Agents Market |
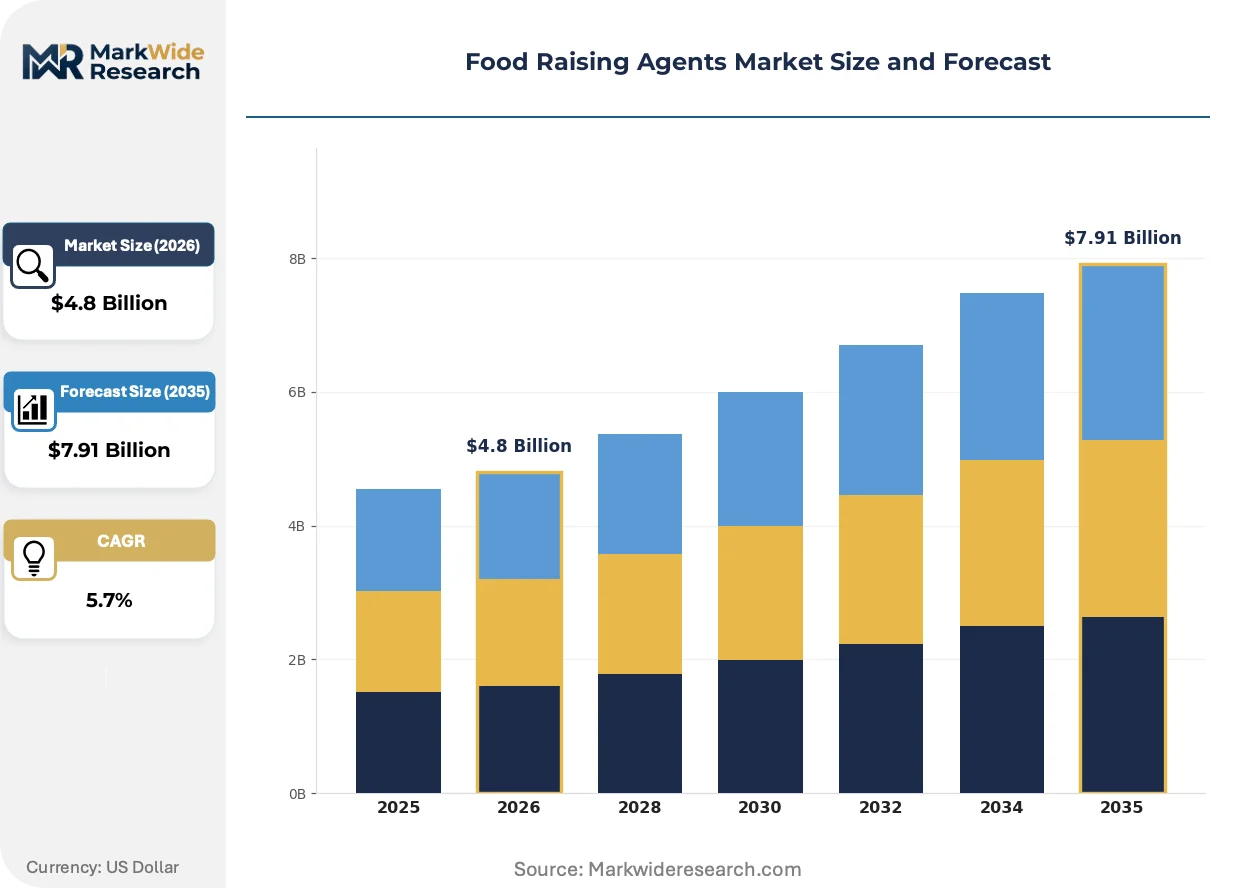
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baking Powder, Yeast, Baking Soda, Cream of Tartar Form: Powder, Liquid, Granular, Paste Application: Baked Goods, Confectionery, Sauces, Cooking End User: Households, Commercial Bakeries, Food Processing, Restaurants |
| Companies Covered | Lallemand, Lesaffre, AB Mauri, DSM, Solvay SA, Kraft Foods Group Inc., Eagle International, Forise Yeast, Kudos Blends Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Raising Agents Market Evolving Landscape
Biotechnology platforms, regulatory disclosure mandates, and procurement model evolution are simultaneously reshaping formulation priorities, supply relationships, and competitive positioning across the raising agent value chain.
Precision fermentation for customized yeast strains is fragmenting the historical dominance of commodity fresh yeast in industrial bread production. Large-scale bakeries in the Netherlands and Belgium are piloting strain-specific cultures optimized for specific flour protein contents and desired crumb structures. This capability is fragmenting volume commitments previously captured by standardized product portfolios, enabling smaller biotechnology specialists to secure niche supply contracts.
EFSA's tightened additive disclosure protocols now require quantitative labeling of all enzymatic processing aids and carrier compounds in compound raising agents. Industrial bakeries serving retail private-label contracts are demanding full supply chain transparency documentation from ingredient suppliers. Powder-form baking powder segments face the steepest compliance burden, as reformulation to eliminate undisclosed carriers requires simultaneous stability and activation profile verification.
Consolidated bakery groups are unbundling after-sales technical service from ingredient supply contracts, previously bundled by dominant yeast suppliers. Mid-scale commercial operations in Italy and Spain are procuring raising agents through centralized purchasing cooperatives that negotiate volume terms separately from formulation support. This disintermediation of technical advisory services is compressing supplier margins while creating openings for independent fermentation consultants and equipment-integrated solution providers.
Food Raising Agents Market Segmentation
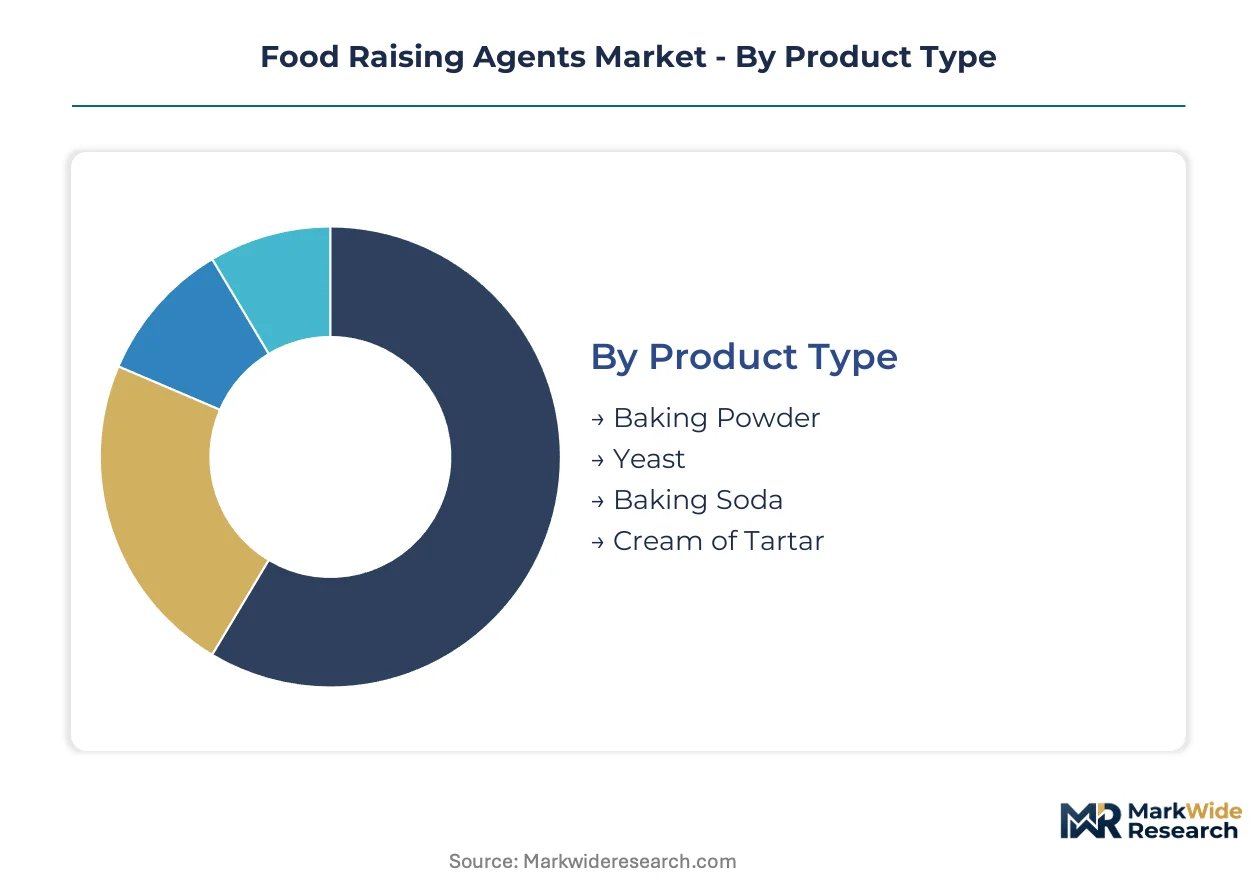
Raising agent selection determines compliance pathways, equipment compatibility, and margin structures across bakery operations. EFSA disclosure mandates and EU Green Deal carbon-footprint protocols create divergent technical requirements by product chemistry and physical state.
Product Type:
EFSA purity standards and REACH registration obligations create asymmetric compliance burdens across synthetic versus biological raising agents, reshaping supplier qualification criteria.
- Yeast:Living Saccharomyces cerevisiae cultures generate carbon dioxide through fermentation, requiring temperature-controlled supply chains. Artisanal bread producers in Germany and France source fresh and dried variants to meet clean-label commitments while EFSA's multi-year strain approval timelines constrain novel biotechnology entrants.
- Baking Powder:Compound formulations of sodium bicarbonate, acid salts, and moisture buffers demand precise activation control. Commercial bakeries across Italy and Spain face reformulation pressure as quantitative labeling mandates expose previously undisclosed enzymatic carriers and processing aids.
- Baking Soda:Single-component sodium bicarbonate serves commodity channels where price sensitivity limits differentiation.
- Cream of Tartar:Potassium bitartrate byproduct from winemaking supplies niche acidulation for stabilizing egg whites and specialty confections.
Yeast handles the majority of throughput; baking powder is expanding most quickly as clean-label reformulation accelerates.
Form:
Physical state dictates shelf stability, dosing precision, and capital equipment requirements across bakery scale tiers.
- Powder:Dehydrated formulations with extended ambient stability dominate retail and industrial procurement. REACH-registered synthetic powders face disclosure burdens under tightened EFSA protocols, while yeast powders compete on strain-specific performance claims.
- Liquid:Pumpable yeast concentrates integrate into continuous mixing lines at high-throughput commercial bakeries in the Netherlands and Belgium. Temperature-controlled storage and metering systems require capital retrofit at mid-scale operations, slowing adoption outside consolidated bakery groups.
- Granular:Free-flowing particles suit volumetric dosing in artisanal settings with variable batch sizes.
- Paste:Compressed fresh yeast blocks serve traditional bakeries with established cold-chain relationships.
Powder maintains volume leadership; liquid concentrates are gaining share fastest through industrial automation upgrades.
Application:
End-use specifications vary by required crumb structure, volume yield, and processing speed, fragmenting formulation requirements.
- Baked Goods:Bread, pastry, and cake production consumes raising agents across all chemistry types. German commercial bakeries are eliminating synthetic preservatives, pulling biological agents into industrial-scale applications previously dominated by chemical leavening.
- Confectionery:Meringues, mousses, and aerated candies demand precise acid-base control. Cream of tartar stabilizes egg proteins in premium chocolate and patisserie segments where EFSA additive transparency requirements expose formulation complexity.
- Sauces:Controlled aeration thickens emulsified preparations in prepared food manufacturing.
- Cooking:Direct-application raising agents serve household and foodservice channels with minimal processing infrastructure.
Baked goods anchor demand volume; confectionery shows the steepest expansion trajectory as premium dessert segments professionalize.
End User:
Procurement scale and technical sophistication create distinct service requirements across customer tiers.
- Commercial Bakeries:Industrial and artisanal operations drive bulk purchasing with strain-specific performance demands. French and German facilities are unbundling technical advisory services from supply contracts, compressing margins for legacy yeast suppliers while opening channels for independent fermentation consultants.
- Food Processing:Prepared meal and mix manufacturers require standardized activation profiles for continuous production. EU Green Deal carbon-footprint labeling mandates force lifecycle data verification across ingredient portfolios.
- Households:Retail-packaged volumes serve home baking with convenience-oriented formats.
- Restaurants:Foodservice operators prioritize inventory flexibility over technical optimization.
Commercial bakeries command the largest share; food processing is climbing the fastest as private-label contract manufacturing concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and France consume biological raising agents at industrial scales unmatched elsewhere, while the United States and China rely more heavily on chemical leavening for mass-market baked goods production.
Germany
Commercial bakeries in Bavaria and North Rhine-Westphalia are eliminating synthetic preservatives from industrial bread lines. EFSA purity standards and REACH chemical registration requirements favor regional yeast suppliers with established compliance dossiers. The Munich-Stuttgart corridor hosts concentrated clean-label reformulation activity among artisanal and industrial producers alike.
France
Artisanal bread producers in Île-de-France and Auvergne-Rhône-Alpes drive premium fresh yeast consumption for traditional baguette and viennoiserie output. EU Green Deal carbon-footprint labeling mandates force lifecycle data verification across ingredient portfolios. Lyon and Paris basin facilities are unbundling technical advisory services from supply contracts, compressing margins for legacy fermentation specialists.
United States
Mass-market baking operations prioritize standardized activation profiles and extended shelf stability for national distribution networks. FDA GRAS determinations and state-level food safety codes create parallel compliance pathways for imported and domestic raising agents. The Midwest bread belt spanning Illinois, Ohio, and Michigan concentrates industrial chemical leavening demand for packaged goods manufacturing.
China
Rapid urbanization and Western-style bakery proliferation are expanding commercial yeast consumption in tier-one and tier-two cities. The country's national food safety regulator maintains strict strain registration requirements for imported biological raising agents. Yangtze River Delta and Pearl River Delta manufacturing clusters are scaling automated production lines that favor pumpable liquid concentrate formats.
Netherlands
High-throughput commercial bakeries in the Randstad region are piloting precision-fermented yeast strains optimized for specific flour protein contents. EFSA additive disclosure mandates require quantitative labeling of enzymatic processing aids in compound formulations. Rotterdam and Amsterdam industrial zones lead European adoption of continuous mixing lines with integrated liquid yeast delivery systems.
Food Raising Agents Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with century-old fermentation houses commanding strain library advantages over chemical compound manufacturers. The market structure reflects asymmetric compliance burdens, where biological suppliers with established EFSA dossiers capture switching costs from reformulating bakeries. Two dominant archetypes emerge: legacy yeast specialists with captive culture collections, and diversified biotechnology platforms converging nutrition and leavening functions. Competitive moves concentrate on backward integration into phosphate rock sourcing and geographic expansion through regionally adapted distribution networks.
Within the heritage fermentation tier, Lesaffre and Lallemand occupy positions anchored by proprietary strain development capabilities and temperature-controlled supply infrastructure. AB Mauri represents the Asia-Pacific distribution archetype with regionally localized product portfolios. DSM exemplifies biotechnology convergence, sitting within the nutrition-leavening intersection where fortified yeast platforms address dual-function demand from health-conscious consumers and industrial formulators seeking simplified ingredient declarations.
| Leading Market Players |
|---|
| Lallemand |
| Lesaffre |
| AB Mauri |
| DSM |
| Solvay SA |
| Kraft Foods Group Inc. |
| Eagle International |
| Forise Yeast |
| Kudos Blends Limited |
| Others |
Value Network & Pricing Analysis
Century-old strain libraries in European fermentation houses generate scale economies that compress price floors for fresh yeast while elevating switching costs for industrial bakeries seeking alternative suppliers. This concentration of biological production capacity in France and Germany creates asymmetric pricing power where regional yeast specialists capture margin premiums from REACH-registered synthetic compound manufacturers facing disclosure burdens under tightened EFSA protocols.
Pricing Analysis
Long-term offtake agreements dominate procurement between consolidated bakery groups and established yeast suppliers, insulating volume buyers from phosphate rock volatility that pressures spot-market baking powder margins. Price differentiation rests on strain-specific performance certification and bundled technical advisory services, with artisanal producers in France showing lowest sensitivity due to clean-label premiums while commodity baking soda channels face acute cost compression from energy-intensive processing inputs.
Supply Chain Analysis
Strategic stockpiling of dried yeast powders prevails among mid-scale bakeries mitigating temperature-controlled supply risks, whereas high-throughput operations in the Netherlands and Belgium run just-in-time liquid concentrate replenishment through integrated pumping systems. Biological production concentrates in France, Germany, and China, drawing from phosphate rock deposits in Morocco and Tunisia for chemical leavening inputs. Single-source vulnerability in century-old strain libraries threatens supply continuity. Distribution runs through temperature-controlled logistics networks anchored by regional fermentation facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through centralized purchasing cooperatives in Italy and Spain that unbundle technical services from ingredient supply, fragmenting legacy supplier margins and creating negotiation leverage for mid-scale commercial operations.
For Market Incumbents: Compound defensive advantages by deepening backward integration into phosphate rock sourcing for baking powder portfolios while accelerating biotechnology-derived strain development to preempt EFSA approval lag for novel variants. Lock in consolidated bakery groups through predictive replenishment platforms that embed switching costs via equipment-integrated liquid concentrate delivery systems. For New Entrants and Emerging Players: Differentiate on carbon-footprint verified fermentation processes to capture EU Green Deal labeling premiums in German and French artisanal segments. Target the precision-fermentation niche for strain-specific cultures optimized to regional flour protein profiles, leveraging independent technical consulting channels to bypass legacy distribution control. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biotechnology platforms converging nutrition and leavening functions over commodity chemical compound manufacturers facing input volatility. Long-term viability hinges on regulatory dossier depth and strain library breadth. Watch EFSA novel strain approval velocity as inflection indicator for pipeline commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Sourcing | Secures supply continuity for baking powder manufacturers facing Moroccan export volatility. |
| Precision Fermentation Scale-Up | Enables strain-specific cultures tailored to Dutch and Belgian flour protein specifications. |
| Carbon-Footprint Certification Program | Aligns supplier portfolios with EU Green Deal quantitative labeling mandates. |
| Direct-to-Bakery Digital Platform Launch | Bypasses traditional distribution layers to capture margin from unbundled procurement cooperatives. |
| Joint Venture for Regional Strain Libraries | Overcomes century-old European fermentation house control through collaborative biotechnology development. |
Research Methodology
Operator-level perspectives from commercial bakery procurement directors, fermentation technologists, EFSA regulatory affairs specialists, and temperature-controlled logistics coordinators anchored the qualitative base. Primary interview insights triangulated against secondary sources including EFSA additive disclosure filings, REACH chemical registration databases, EU Green Deal carbon-footprint protocol documentation, and customs trade records for phosphate rock and yeast concentrate movements. Bottom-up volume modeling across bakery scale tiers converged with top-down value estimates derived from supplier revenue disclosures.
Sensitivity analysis tested forecast robustness across alternative regulatory lag scenarios and input cost trajectories throughout the projection horizon. Segmentation dimensions modeled include product chemistry type, physical form factor, end-use application, and bakery operational scale tier. CAGRs derived from fitted growth curves applied to historical consumption patterns, with explicit incorporation of strain approval timelines and clean-label reformulation adoption curves as industry-specific inputs.
Forecasts assume regulatory continuity in EFSA purity standards and EU Green Deal implementation regimes; material policy shifts would require re-modeling. Revision becomes warranted when EFSA novel strain approval velocity or phosphate rock sourcing disruption severity crosses thresholds that alter supplier switching cost dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Charcoal-Infused Food Market
Food Enhancers and Additives
South Africa Water Enhancer Market
Food Enhancers and Additives
Frying Shortening Market
Food Enhancers and Additives
Australia Food Flavor and Enhancer Market
Food Enhancers and Additives
France Water Enhancer Market
Food Enhancers and Additives
Brazzein Market
Food Enhancers and Additives
South Korea Fat Replacers Market
Food Enhancers and Additives
Europe Water Enhancer Market
Food Enhancers and Additives
Kaempferol Market
Food Enhancers and Additives
Australia Water Enhancer Market
Food Enhancers and Additives
Veratrole Market
Food Enhancers and Additives
Dysphagia Diet Thickening Agents Market
Food Enhancers and Additives
Asia-Pacific Food Flavor and Enhancer Market
Food Enhancers and Additives
Mexico Food Flavor and Enhancer Market
Food Enhancers and Additives
Africa Food Flavor and Enhancer Market
Food Enhancers and Additives
Water Enhancer Market