
 Used Cooking Oil Market | 2026-2036
Used Cooking Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Used Cooking Oil Market Intelligence
Advanced hydrotreating technology for renewable diesel production is tilting the value chain away from traditional biodiesel processing. Darling Ingredients Inc. leverages its integrated collection and processing infrastructure to supply its own renewable diesel facilities. Baker Commodities Inc. competes through its extensive logistics network across North American markets. Mahoney Environmental Solutions, a subsidiary of Neste, operates with a focus on securing high-quality feedstock for sustainable aviation fuel (SAF) production.
Used cooking oil consists of lipids and oils degraded by heating during food preparation, with quality determined by free fatty acid (FFA) content and moisture levels. Its primary commercial purpose is serving as a sustainable, low-carbon feedstock for second-generation biofuel manufacturing. The biofuel production application, specifically for renewable diesel and SAF, constitutes the largest and fastest-growing end-use segment. Collection from restaurants and food processing units, which primarily generate vegetable oil waste, commands the majority of supply volumes.
Regulatory frameworks such as the EU's Renewable Energy Directive and the EPA's Renewable Fuel Standard in the United States create mandated demand for UCO as a biofuel feedstock. These policies, alongside similar initiatives in countries like China under its dual carbon goals, define market access and value through carbon intensity scoring. The critical decision for energy producers is whether to pursue long-term supply contracts or invest in upstream collection infrastructure to ensure feedstock security.
Market Dynamics
The market's central dynamic is the conversion of a waste product into a regulated commodity, driven by biofuel mandates like the EU's RED II. This regulatory pull structures supply chains and investment, defining value based on carbon intensity scores and feedstock traceability.
Growth Catalysts
- EU Biofuel Mandates:The Renewable Energy Directive (RED II) creates mandated demand for advanced biofuels, specifically targeting UCO for sustainable aviation fuel and renewable diesel production.
- Hydrotreating Technology:Advanced hydrotreating processes enable the efficient conversion of UCO into high-quality renewable diesel, a drop-in fuel compatible with existing infrastructure.
- National Decarbonization Goals:Policies in nations like China promote waste-to-energy pathways, increasing domestic collection and processing of UCO to meet carbon reduction targets.
Market Restraints
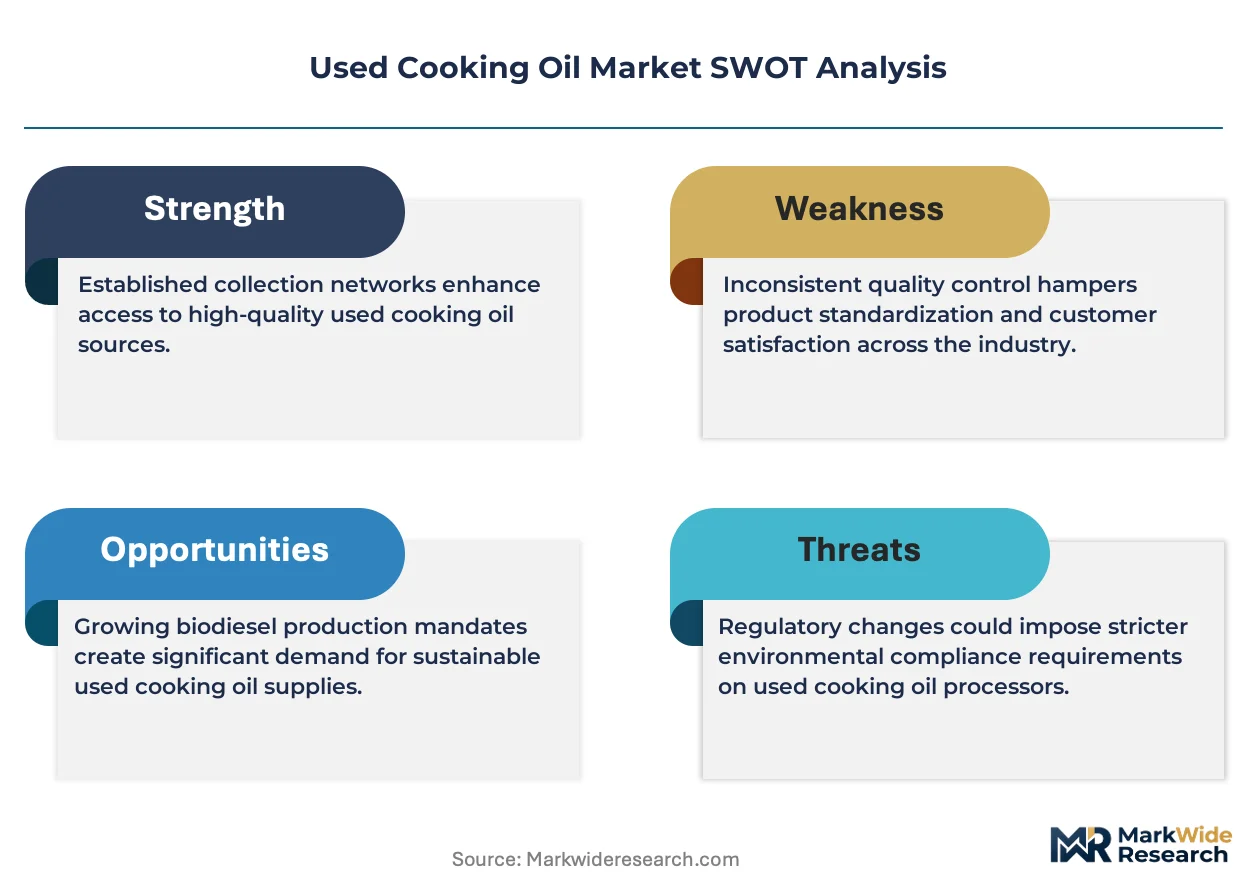
- Feedstock Inconsistency:Supply is characterized by highly fragmented collection points and variable quality, complicating logistics and increasing processing costs due to contaminants.
- Substitution from Other Wastes:UCO competes directly with other low-carbon feedstocks such as animal fats (tallow) and agricultural residues for access to biorefinery capacity.
- Certification Burdens:Proving provenance and sustainability under schemes like the International Sustainability and Carbon Certification (ISCC) is complex and costly, creating a barrier for smaller collectors.
Strategic Opportunities
- Marine Biofuels:The maritime shipping industry's decarbonization efforts open a significant new end-market for UCO-derived biofuels to meet emissions reduction mandates from regulators.
- Collection Infrastructure in Asia:Developing formal UCO collection networks in Southeast Asian countries presents an opportunity to tap into a large, unorganized supply source for export.
- Digital Traceability:Implementing blockchain or IoT-based tracking systems can enhance supply chain transparency, verify sustainability claims, and command premium value for certified feedstock.
Industry Challenges
- Logistical Optimization:Managing the complex logistics of collecting small, variable quantities of UCO from thousands of geographically dispersed sources remains a significant operational hurdle for aggregators.
- Quality Control at Scale:Consistently and cost-effectively testing for high free fatty acid (FFA) and moisture levels at the point of collection is difficult but essential for efficient refining.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Used Cooking Oil Market |
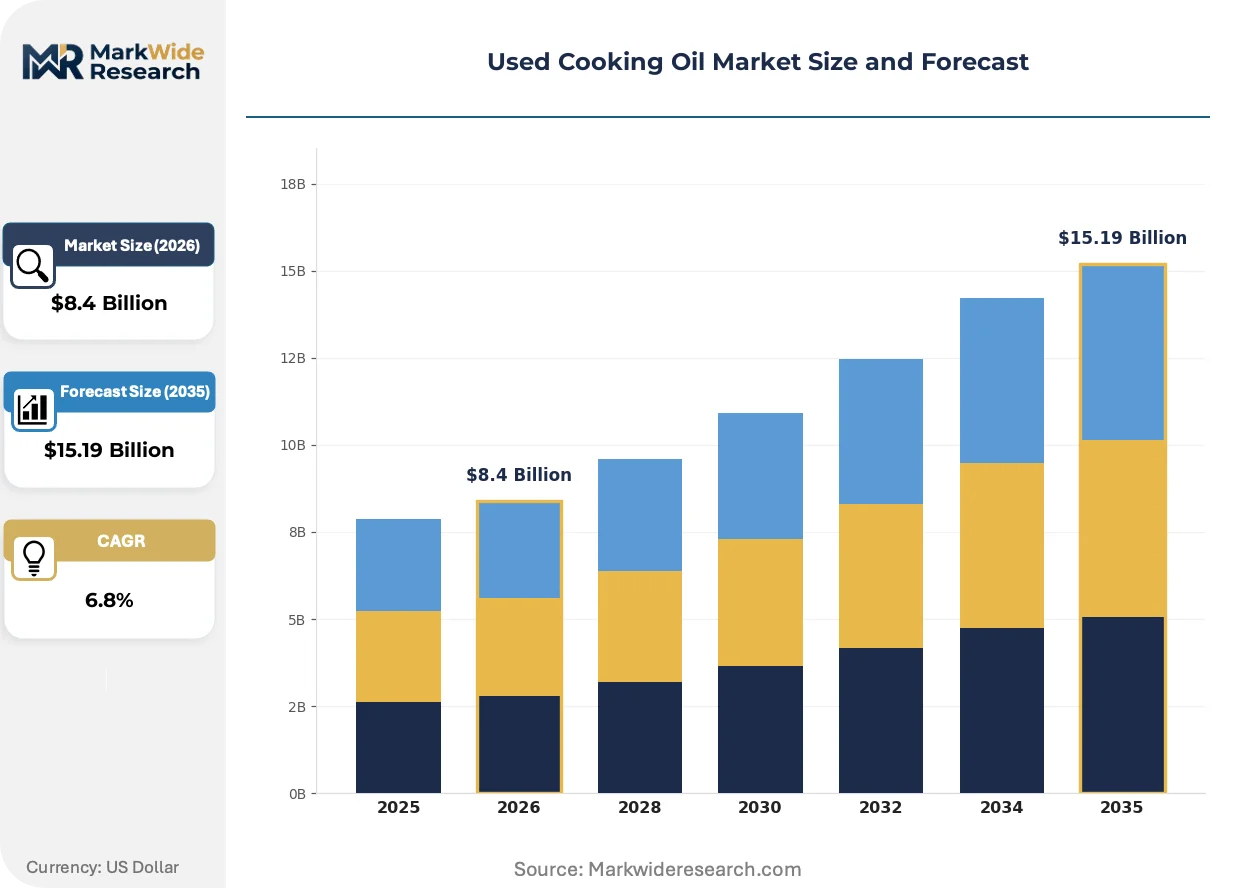
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Source Type: Vegetable Oil, Animal Fat, Recycled Frying Oil, Industrial Cooking Oil Application: Biofuel Production, Soap Manufacturing, Animal Feed, Chemical Industry, Biodiesel Production Collection Channel: Restaurants, Food Processing Units, Households, Catering Services, Food Courts End User: Energy Producers, Chemical Manufacturers, Farm Operators, Cosmetic Companies, Waste Management Firms |
| Companies Covered | Darling Ingredients Inc., Baker Commodities Inc., ABP Food Group (Olleco), Arrow Oils Ltd., Valley Proteins Inc., Brocklesby Limited, Mahoney Environmental Solutions, Grand Natural Inc., Oz Oils Pty. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Used Cooking Oil Market Strategic Shifts & Innovations
Technological advancements and policy mandates are transforming used cooking oil from a waste product into a strategic feedstock for the energy transition. This evolution is formalizing collection networks and creating value chains centered on carbon intensity.
Co-processing allows petroleum refineries to introduce UCO-derived biocrudes into existing fluid catalytic crackers. Major energy companies adopt this method to leverage their infrastructure for meeting renewable fuel targets. This strategy is hybridizing conventional fossil fuel assets with biorefining functions, enabling faster scale-up of drop-in fuels.
The U.S. Environmental Protection Agency's Renewable Fuel Standard assigns value to biofuels based on feedstock. Its mechanism creates financial incentives for fuels from waste like UCO, which generate valuable D4 RIN credits. The policy influences investment in North America, prioritizing UCO supply chain development for transportation fuels.
Major biofuel producers are shifting from spot market transactions toward securing long-term offtake agreements for UCO. This model bypasses intermediate aggregators, as energy firms contract directly with large-scale generators. The practice is most pronounced in the United States and Europe, where feedstock security is critical.
Used Cooking Oil Market Segmentation
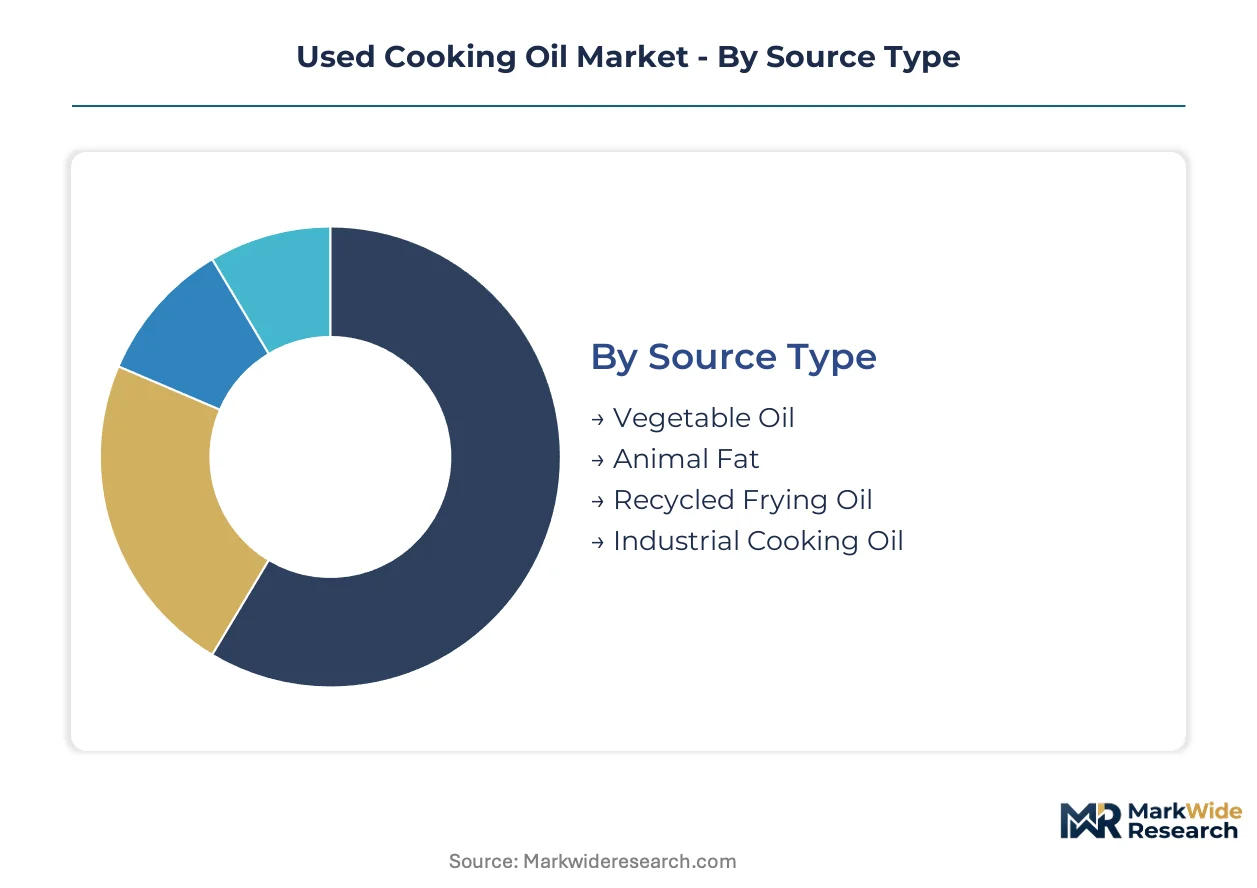
The Used Cooking Oil (UCO) market exhibits distinct segmentation, driven by varied source materials, diverse applications, and complex collection logistics. Understanding these segments is crucial for stakeholders to optimize procurement strategies and capitalize on specific end-use demands within the evolving bioeconomy.
Source Type:
The market for used cooking oil is structured across a diverse use-case spectrum, reflecting varied origins and initial processing.
- Vegetable Oil:This segment comprises lipids derived from plant sources like soybean, canola, and palm, degraded through heating during food preparation. Its high availability from restaurants and food processing units drives its primary use as a feedstock for renewable diesel production in the European Union.
- Recycled Frying Oil:Recycled Frying Oil specifically refers to oils collected after multiple frying cycles, often exhibiting higher free fatty acid content. This segment commands value in regions like the United States due to established collection networks and its direct suitability for biofuel conversion.
- Animal Fat:Animal Fat includes rendered fats from livestock, competing with UCO as a low-carbon feedstock for biofuel production.
- Industrial Cooking Oil:Industrial Cooking Oil encompasses oils used in large-scale food manufacturing, offering substantial volumes for collection and processing.
Established volume favors Vegetable Oil; emerging adoption favors Industrial Cooking Oil.
Application:
Volume concentration dictates the commercial viability of various end-use applications for used cooking oil.
- Biofuel Production:Biofuel Production encompasses the conversion of UCO into various renewable fuels, including renewable diesel and sustainable aviation fuel. This application represents the largest and fastest-growing end-use segment, driven by global decarbonization mandates and carbon intensity scoring mechanisms.
- Biodiesel Production:Biodiesel Production specifically involves transesterification of UCO to produce fatty acid methyl esters (FAME), a traditional biofuel. This process remains significant in markets with established infrastructure, such as parts of Europe, offering a readily available alternative to fossil diesel.
- Soap Manufacturing:Soap Manufacturing utilizes UCO as a cost-effective raw material for producing fatty acid-based soaps and detergents.
- Animal Feed:Animal Feed incorporates processed UCO as an energy-dense ingredient, enhancing nutritional value for livestock.
- Chemical Industry:The Chemical Industry employs UCO derivatives in producing lubricants, paints, and other oleochemicals.
Demand for Biofuel Production drives market volume; Chemical Industry represents a niche but growing opportunity.
Collection Channel:
Supply concentration across collection channels significantly impacts the logistics and cost efficiency of used cooking oil procurement.
- Restaurants:Restaurants represent a primary collection channel, generating fragmented but consistent volumes of used vegetable oil. Aggregators deploy dedicated routes to service these numerous small-volume sources in urban centers across the United States.
- Food Processing Units:Food Processing Units offer larger, more centralized volumes of industrial cooking oil waste, simplifying collection logistics. These facilities provide higher quality feedstock often suitable for direct long-term supply contracts with major energy producers in China.
- Households:Households contribute smaller, highly dispersed volumes, often collected through municipal programs or community drop-off points.
- Catering Services:Catering Services generate intermittent volumes from events, requiring flexible collection schedules and specialized logistics.
- Food Courts:Food Courts, often within malls or airports, provide concentrated collection points for multiple restaurant tenants.
Large-scale collection centers on Food Processing Units; fragmented collection characterizes Households.
End User:
Margin potential influences the strategic focus of various end-user segments engaging with used cooking oil supply.
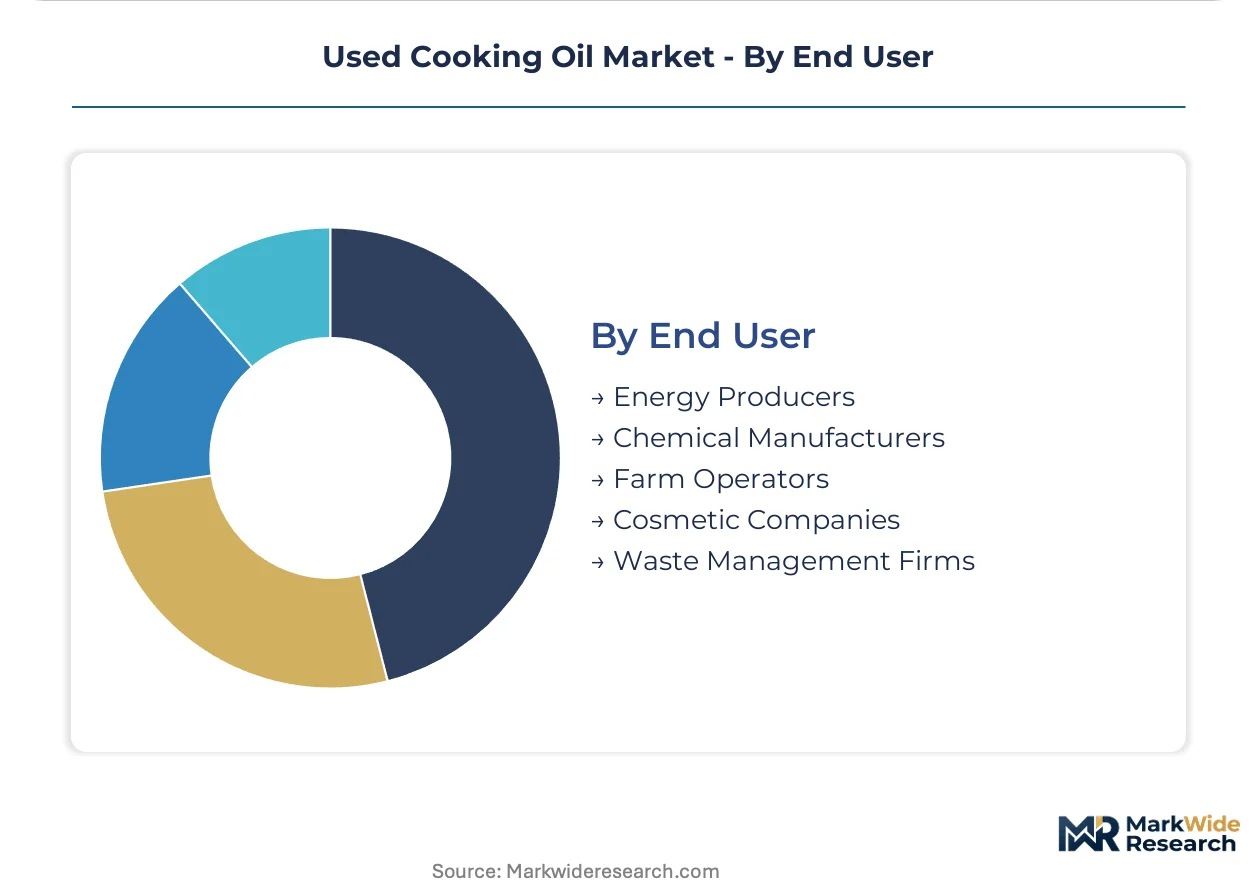
- Energy Producers:Energy Producers, including renewable diesel and sustainable aviation fuel refiners, represent the largest and most value-driven end-users. Their demand is mandated by regulatory frameworks like the EU's RED II and the US EPA's Renewable Fuel Standard, driving significant investment in UCO sourcing.
- Waste Management Firms:Waste Management Firms play a critical role in the initial collection, aggregation, and pre-processing of UCO from diverse sources. These firms optimize logistics and ensure compliance with environmental regulations before selling to higher-value end-users.
- Chemical Manufacturers:Chemical Manufacturers utilize UCO as a sustainable feedstock for producing oleochemicals, lubricants, and other industrial products.
- Farm Operators:Farm Operators use UCO, often after minimal processing, as an energy supplement in animal feed formulations.
- Cosmetic Companies:Cosmetic Companies incorporate UCO derivatives into sustainable personal care products, valuing its natural lipid content.
Core demand originates from Energy Producers; specialized applications emerge from Cosmetic Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Energy producers drive regional demand for used cooking oil, propelled by stringent decarbonization targets and biofuel mandates. Biofuel production, particularly for renewable diesel and sustainable aviation fuel, concentrates demand in developed economies. Regulatory frameworks in these regions provide significant financial incentives for UCO utilization as a low-carbon feedstock.
United States
Demand for renewable diesel production significantly drives UCO consumption across the United States. The EPA's Renewable Fuel Standard creates financial incentives through D4 RIN credits, prioritizing UCO supply chain development. Investment in biorefinery capacity is concentrating in the Gulf Coast region, particularly in states like Louisiana and Texas.
Germany
Germany's UCO market responds strongly to the EU's Renewable Energy Directive (RED II) for advanced biofuel mandates. Hydrotreating technology enables efficient conversion of UCO into high-quality renewable diesel for the transportation sector. Biorefinery clusters in areas like the Rhine-Ruhr region are expanding to process increasing UCO volumes.
China
China's dual carbon goals promote waste-to-energy pathways, increasing domestic collection and processing of UCO. Major energy producers in China are pursuing long-term supply contracts to ensure feedstock security for biofuel production. Industrial food processing units in provinces like Shandong and Guangdong offer substantial volumes for collection.
India
India presents an emerging opportunity for formal UCO collection networks, driven by waste management initiatives and biofuel blending targets. The country's national biofuel policy encourages the use of advanced biofuels from waste feedstocks. Efforts to establish organized collection from urban centers like Mumbai and Delhi are gaining momentum.
Used Cooking Oil Market Key Industry Players
Channel-controlling players compete with product-specialist players in the used cooking oil market. The market structure exhibits fragmentation at the collection point, with numerous small-scale operators, but consolidates significantly among larger processors and biofuel producers. Strategic archetypes include vertically integrated aggregators managing the entire value chain, specialized logistics providers focusing on efficient collection networks, and dedicated biorefinery feedstock suppliers. Competitive moves center on securing long-term supply contracts to ensure feedstock security and expanding processing capacity to meet rising biofuel demand.
Integrated players like Darling Ingredients Inc. exemplify the vertical integration strategy, controlling collection infrastructure through to biofuel production facilities. These entities often manage vast networks to secure diverse UCO streams, ensuring a consistent supply for their own refining operations. Baker Commodities Inc. represents a logistics-focused archetype, leveraging its extensive network across North American markets for efficient UCO collection and aggregation from fragmented sources. Such companies specialize in optimizing collection routes and initial processing. Mahoney Environmental Solutions, a subsidiary of Neste, anchors the high-quality feedstock segment, focusing on securing specific UCO grades essential for sustainable aviation fuel production. This specialized approach addresses the stringent quality requirements for advanced biofuels, commanding premium value for certified feedstock.
| Leading Market Players |
|---|
| Darling Ingredients Inc. |
| Baker Commodities Inc. |
| ABP Food Group (Olleco) |
| Arrow Oils Ltd. |
| Valley Proteins Inc. |
| Brocklesby Limited |
| Mahoney Environmental Solutions |
| Grand Natural Inc. |
| Oz Oils Pty. Ltd. |
Cost & Logistics Intelligence
European shipping lanes, a critical freight corridor for UCO, see cost dynamics heavily influenced by supply concentration in Southeast Asia, directly impacting downstream price differentiation for certified feedstock in the EU.
Pricing Analysis
Cost-plus contract patterns, often indexed to biofuel credit values like D4 RINs or carbon intensity scores, define the pricing structure for used cooking oil. Price differentiation stems from free fatty acid content, moisture levels, and International Sustainability and Carbon Certification (ISCC) status. Pricing stability for high-quality UCO remains robust due to mandated demand from energy producers and regulatory incentives. Energy producers exhibit the least price sensitivity, prioritizing feedstock security and compliance, while the chemical industry shows higher sensitivity to UCO costs.
Supply Chain Analysis
Logistical optimization challenges for fragmented collection points remain a primary supply chain risk for used cooking oil. Geographic supply concentrates in the United States, European Union, and China, driven by established collection networks and processing infrastructure. Raw material dependencies center on consistent volumes of vegetable oil waste from restaurants and food processing units. Aggregators primarily collect UCO, with distribution running through specialized processors before reaching biofuel producers via long-term contracts or spot market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a service-attach opportunity, with digital traceability solutions expanding faster than raw UCO collection volumes, offering premium value for certified feedstock.
For Market Incumbents:Harden existing collection infrastructure by integrating advanced IoT sensors for real-time quality assessment at fragmented collection points. Invest in upstream processing capabilities, particularly hydrotreating technology, to efficiently convert diverse UCO streams into high-quality renewable diesel. Mitigate the threat of feedstock inconsistency by securing long-term supply contracts directly with large industrial food processing units. Leverage existing logistics networks to expand into nascent collection markets in Southeast Asia, preempting new entrant competition.
For New Entrants and Emerging Players:Establish a beachhead in the marine biofuels segment, which offers a significant new end-market for UCO-derived fuels. Target underserved urban centers in India and other developing economies to build formal UCO collection networks, capitalizing on waste management initiatives. A go-to-market angle focusing on digital traceability platforms, utilizing blockchain technology, can offer certified, premium-value feedstock to advanced biofuel producers. This approach bypasses traditional aggregator models by ensuring provenance and sustainability.
For Investors and Strategic Acquirers:Vertically integrated aggregators with strong collection networks and processing capabilities represent compelling acquisition targets for long-term viability in the UCO market. These entities offer feedstock security to energy producers facing decarbonization mandates. The signal to watch is the increasing adoption of digital traceability solutions and the expansion of biorefinery clusters in regions with aggressive biofuel targets. Investment in specialized logistics providers focusing on efficient, high-volume UCO aggregation should also be considered.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand upstream collection infrastructure | Secures consistent feedstock supply for biofuel production, mitigating supply chain volatility. |
| Invest in advanced hydrotreating technology | Enables efficient conversion of UCO into high-quality renewable diesel and sustainable aviation fuel. |
| Develop digital traceability platforms | Enhances supply chain transparency, verifies sustainability claims, and commands premium for certified UCO. |
| Target marine biofuel applications | Opens a significant new end-market driven by the maritime shipping industry's decarbonization efforts. |
| Form long-term supply contracts | Ensures feedstock security for major energy producers, stabilizing procurement costs and volumes. |
Research Approach
Desk research of regulatory frameworks, industry association reports, and company financial filings preceded structured interviews with energy producers, waste management firms, and biofuel technology developers. This approach combined primary insights with secondary data validation, employing both bottom-up and top-down triangulation for accuracy.
Assumptions regarding regulatory stability, technological advancements in biofuel refining, and global decarbonization efforts were held constant across the modeling period. The analytical framework segmented the market by source type, application, collection channel, end user, and geographic region. Compound annual growth rates were derived from historical data, expert consensus, and projected policy impacts, with feedstock availability and carbon intensity credit values serving as key forecast inputs.
Sensitivities concentrate around shifts in biofuel mandates, changes in carbon credit values, and the competitive landscape with alternative waste feedstocks. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Canada Food Flavor and Enhancer Market
Food Enhancers and Additives
Liquid Smoke Market
Food Enhancers and Additives
Feed Palatability Enhancers and Modifiers Market
Food Enhancers and Additives
North America Food Flavor and Enhancer Market
Food Enhancers and Additives
Fortified Eggs Market
Food Enhancers and Additives
North America Vinegar Market
Food Enhancers and Additives
North America Food Thickeners Market
Food Enhancers and Additives
Australia Food Flavor and Enhancer Market
Food Enhancers and Additives
Food Thickeners Market
Food Enhancers and Additives
Vegetable Shortening Market
Food Enhancers and Additives
Spain Food Flavor and Enhancer Market
Food Enhancers and Additives
Germany Water Enhancer Market
Food Enhancers and Additives
Food Raising Agents Market
Food Enhancers and Additives
Instant Whipping Agents Market
Food Enhancers and Additives
Emulsifier Alternatives Market
Food Enhancers and Additives
Raising Agents Market