
 United Kingdom Water Enhancer Market | 2026-2036
United Kingdom Water Enhancer Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Water Enhancer Market Analytics
Food science graduate shortages in British universities is redrawing the competitive map for flavour innovation in the water enhancer category. Britvic plc leverages its established bottling infrastructure to sustain shelf presence across major UK grocers. The Kraft Heinz Company anchors its position through deep distribution relationships with supermarket chains. PepsiCo Inc competes by extending its beverage portfolio into low-calorie enhancement formats.
Water enhancers comprise concentrated liquid or powder formulations containing flavour compounds, acidulants, sweeteners, and functional additives designed for dilution into plain water, typically achieving palatability at dilution ratios between 1:20 and 1:80. These products serve commercial and household purposes by transforming unflavoured water into flavoured beverages without the caloric load of ready-to-drink alternatives. Natural flavours and sugar-free variants capture the strongest margin pools as health-conscious consumers trade away artificial ingredients. Single-serve packs dominate impulse purchase occasions while bulk containers anchor household replenishment cycles through supermarkets and online retail channels.
The Food Standards Agency enforces compositional standards for flavourings and additives under retained EU food law, while Advertising Standards Authority rules constrain health claims on packaging. Sugar tax levy mechanisms administered by HM Revenue and Customs directly pressure formulation decisions toward zero-sugar profiles. Stakeholders must monitor evolving front-of-pack labelling consultations and potential extension of advertising restrictions to online channels.
Market Dynamics
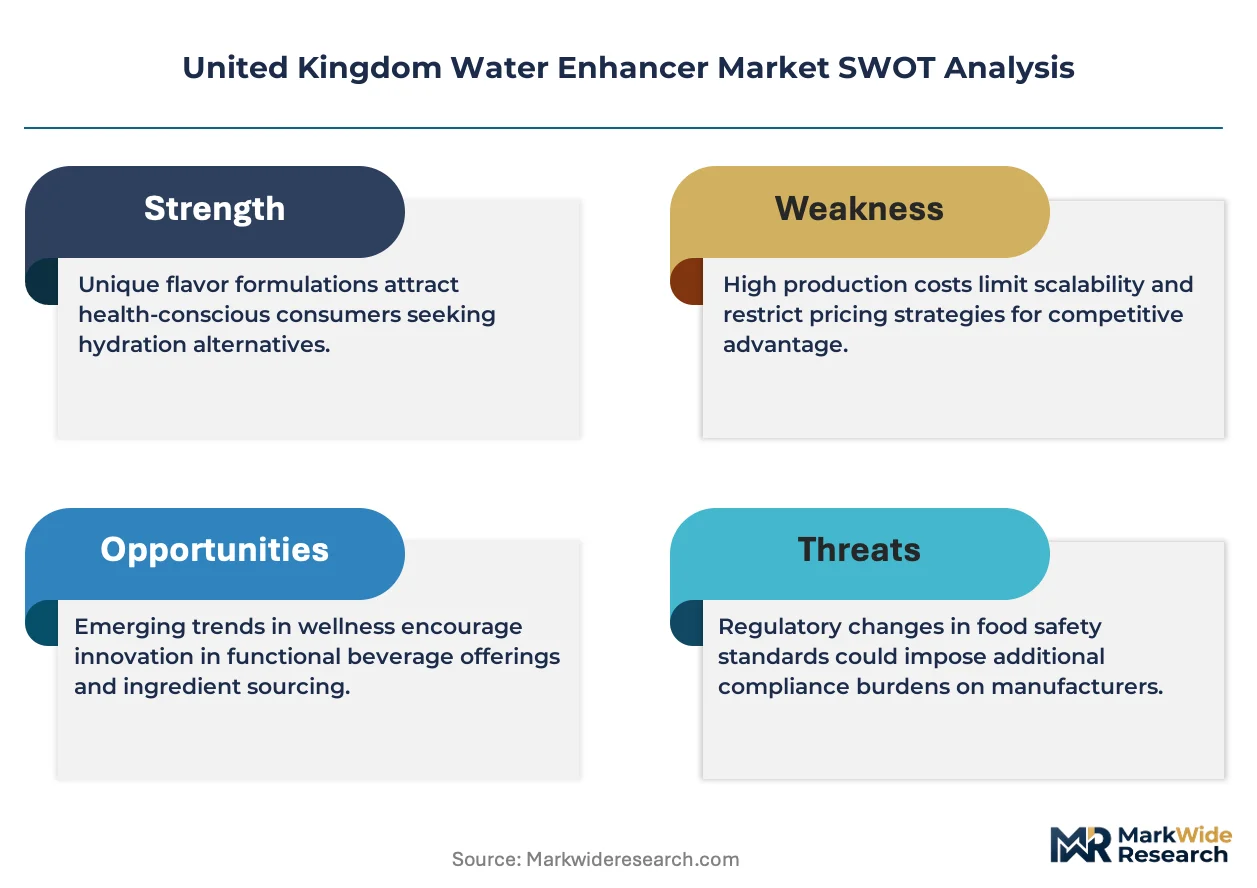
HM Revenue and Customs' sugar tax levy is compressing formulation margins and forcing rapid zero-sugar pivots across British water enhancer portfolios. This fiscal pressure intersects with food science graduate shortages to create a talent-constrained innovation environment where technical capability determines competitive survival.
Growth Catalysts
- Soft Drinks Industry Levy:The tiered tax structure on sugar-laden beverages redirects consumer preference toward dilutable low-calorie alternatives, expanding the addressable base for water enhancers in household replenishment cycles.
- Urban health clusters:Metropolitan England's fitness-oriented populations in London, Manchester and Birmingham generate concentrated demand for functional formulations with electrolytes and vitamins.
- Retained EU food law:The Food Standards Agency's compositional standards for flavourings create regulatory clarity that reduces market entry friction for compliant domestic and international suppliers.
Market Restraints
- Natural flavour input volatility:Citrus and botanical extract prices fluctuate with Mediterranean harvest conditions, compressing margin stability for premium-positioned variants.
- Single-source sweetener concentration:Sucralose and stevia supply chains concentrate among three global chemical processors, creating vulnerability to production disruptions.
- Advertising Standards Authority constraints:Health claim restrictions on packaging limit differentiation messaging and extend new product launch timelines through compliance review.
Strategic Opportunities
- Scottish and Welsh retail corridors:Underpenetrated independent convenience networks in Edinburgh, Glasgow and Cardiff offer first-mover shelf space ahead of national grocer saturation.
- Functional ingredient convergence:Probiotic and nootropic additive integration creates premium positioning at dilution points where sports nutrition and cognitive wellness categories overlap.
- Online subscription channels:Direct-to-consumer replenishment models bypass slotting fee barriers and capture household lifetime value through automated reorder algorithms.
Industry Challenges
- Food technologist scarcity:British university pipeline shortfalls in flavour chemistry and formulation science constrain R&D throughput and extend product development cycles.
- Front-of-pack labelling uncertainty:Pending government consultations on nutritional scoring systems create formulation hesitation as manufacturers await final display requirements.
- Legacy retail integration complexity:Major supermarket chains demand extensive EDI compliance and promotional fund commitments that strain emerging brand cash flows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Water Enhancer Market |
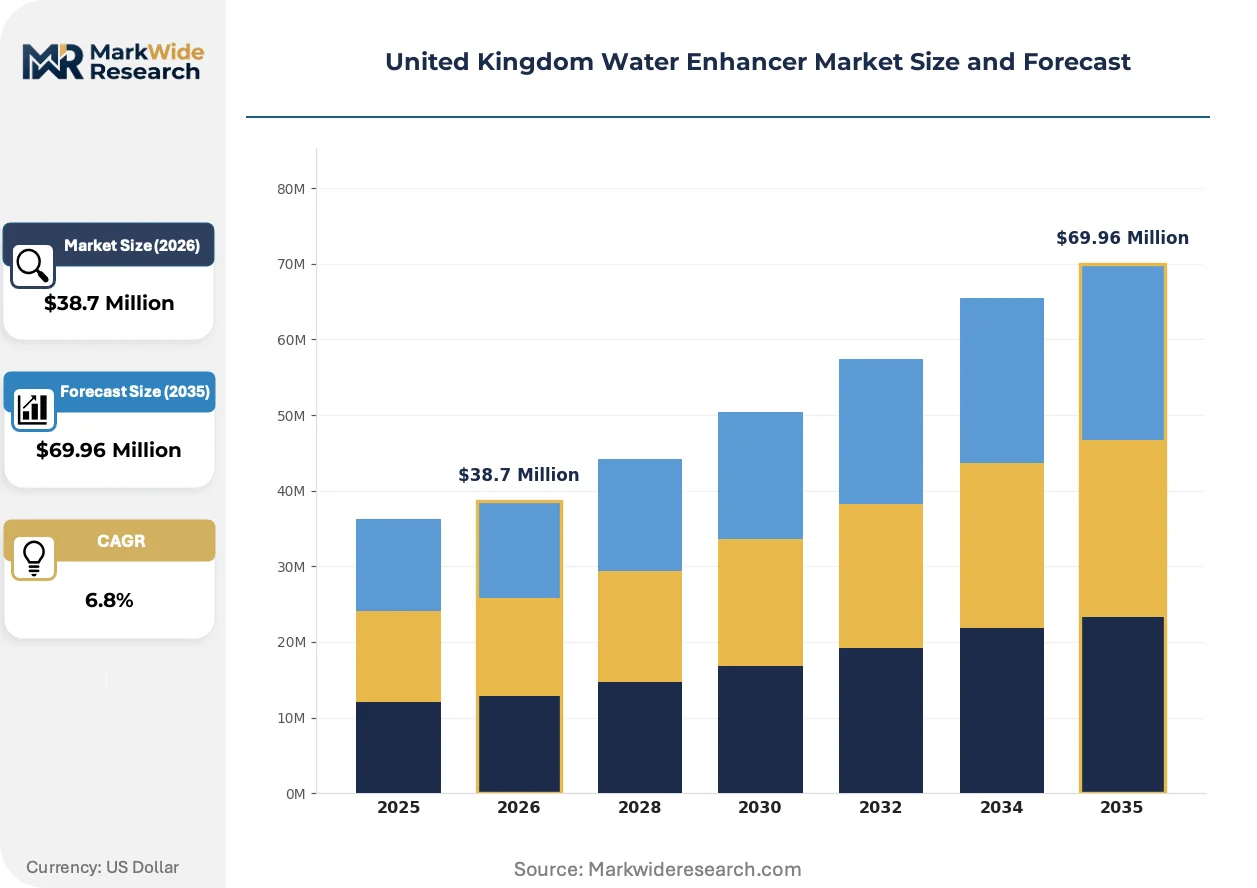
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $69.96 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Flavors, Artificial Flavors, Sugar-Free, Nutritional Enhancers Container Type: Single-Serve Packs, Bottles, Sachets, Bulk Containers Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Convenience Stores Target Consumer: Fitness Enthusiasts, Health-Conscious Individuals, Families, Older Adults |
| Companies Covered | The Coca-Cola Company, The Kraft Heinz Company, Nestle S.A., Britvic plc, Dyla LLC, PepsiCo Inc, Lucozade Ribena Suntory, Refresco, Jel Sert Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Water Enhancer Market Evolving Landscape
Clean-label formulation priorities are redrawing competitive boundaries as artificial ingredient rejection spreads from premium tiers into mass-market positioning. This shift is compressing legacy portfolios and forcing accelerated natural certification investments.
Plant-derived sweetener blends combining monk fruit with stevia extracts are displacing artificial alternatives in mid-market formulations. Health-conscious millennials in England's metropolitan corridors adopt these variants at pace, with dilution ratios tightening toward 1:40 for intensity-matched palatability. The structural consequence is margin compression on legacy sucralose-dependent lines as reformulation costs concentrate in 12-18 month windows.
HM Revenue and Customs' enforcement of soft drinks levy tiers is accelerating zero-sugar profile standardization across supermarket own-label ranges. The industrial consequence is formulation homogenization at the sugar-free threshold, with differentiation shifting toward functional additive claims. Premium private label segments in Waitrose and Marks & Spencer are most affected, responding through limited-edition botanical collaborations with British herb suppliers.
Subscription-based replenishment is fragmenting traditional supermarket dependency among urban households with predictable consumption patterns. Direct-to-consumer platforms are capturing 30-day cycle loyalty through personalized flavour rotation algorithms, displacing impulse purchases at convenience retail points. This pattern concentrates in London's Zone 1-2 residential clusters where delivery density minimizes logistics cost per unit.
United Kingdom Water Enhancer Market Segmentation
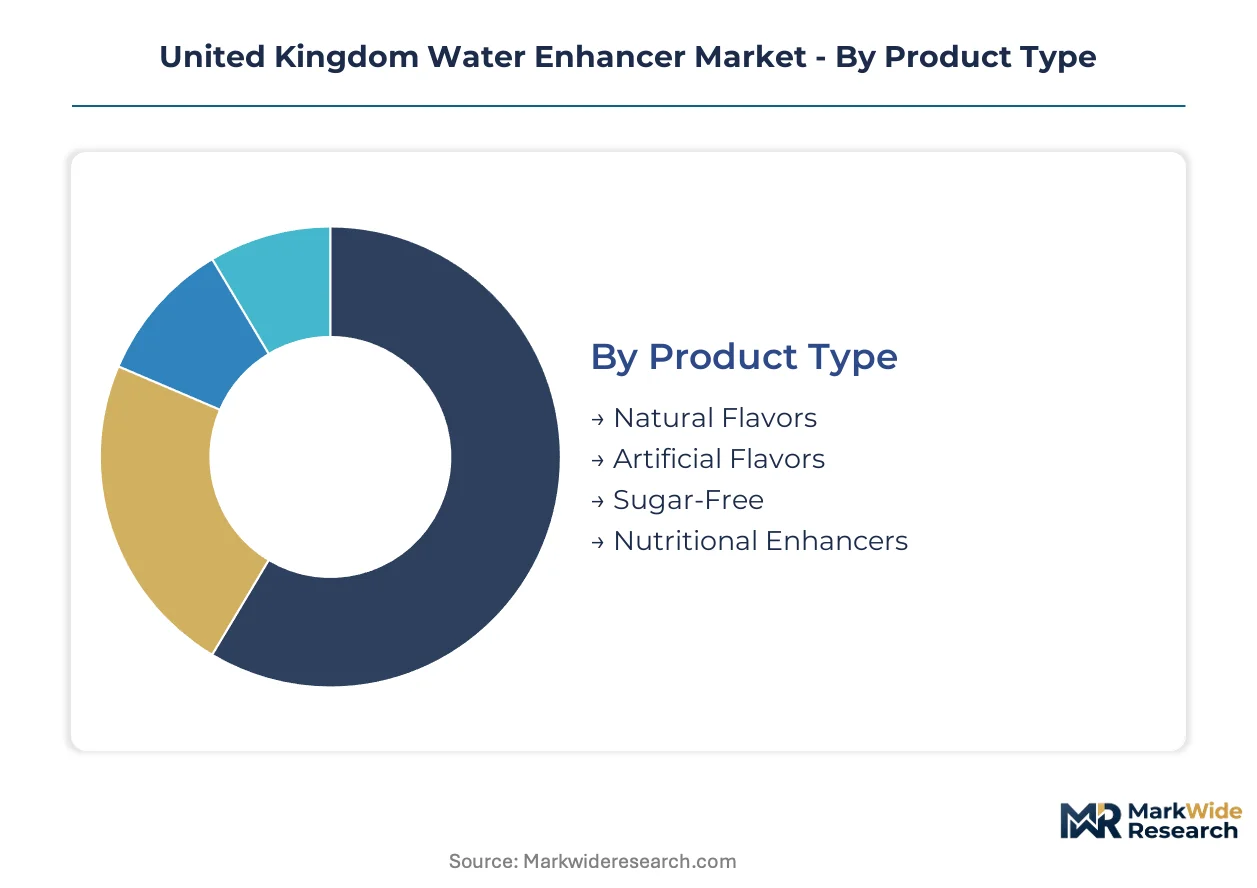
Water enhancer purchasing patterns fragment sharply across formulation philosophy, packaging convenience, and channel accessibility. Manufacturers must calibrate portfolio depth to where substitution pressure from ready-to-drink alternatives concentrates most intensely.
Product Type:
Natural flavour variants face acute substitution pressure from premium bottled waters and cold-pressed juices, while artificial formulations confront collapse under sugar levy scrutiny and clean-label migration.
- Natural Flavors:Botanical and fruit-derived extracts certified free from synthetic additives command shelf space in Waitrose and Marks & Spencer premium tiers. London's Zone 1-2 health clusters drive replenishment velocity as consumers reject artificial ingredient panels.
- Sugar-Free:Sucralose, stevia, and monk fruit formulations dominate supermarket own-label ranges after HM Revenue and Customs' levy tier enforcement. Manchester and Birmingham metropolitan households anchor volume through bulk container purchases.
- Artificial Flavors:Synthetic colour and flavour compounds retreat to price-sensitive convenience channels. Regulatory pressure from Food Standards Agency retained EU law accelerates portfolio rationalisation.
- Nutritional Enhancers:Electrolyte, vitamin, and mineral fortifications target fitness-oriented consumers. Edinburgh and Glasgow gym partnerships create trial pathways for functional variants.
Sugar-Free anchors the volume base while Natural Flavors gains share at the steepest rate.
Container Type:
Packaging economics stratify sharply between impulse convenience and household replenishment economies, with cost-per-dose calculations driving channel placement decisions.
- Single-Serve Packs:Portable sachets and droppers capture transport hub and workplace vending occasions. London commuter corridors generate highest turnover for on-the-go dilution formats.
- Bulk Containers:Multi-dose bottles dominate suburban household pantry stocking. Online subscription algorithms favour these units for automated replenishment cycles.
- Sachets:Individual powder portions target trial and travel segments. Cardiff independent convenience networks show strongest adoption for impulse sachet placement.
- Bottles:Mid-size liquid concentrates balance portability with value. Supermarket promotional calendars rotate these SKUs most heavily.
Bulk Containers capture the highest household lifetime value while Single-Serve Packs expand most quickly through transport retail.
Distribution Channel:
Channel concentration determines margin structure, with slotting fee barriers and promotional fund commitments reshaping competitive access.
- Supermarkets:Tesco, Sainsbury's, and Asda control mass-market penetration through extensive EDI compliance requirements. Own-label ranges here face direct sugar levy pressure.
- Online Retail:Direct-to-consumer platforms bypass slotting fees through subscription algorithms. Automated 30-day cycles concentrate in England's metropolitan residential clusters.
- Convenience Stores:Independent networks in underpenetrated Scottish and Welsh corridors offer first-mover shelf space. Single-serve packs dominate this channel's impulse architecture.
- Health Food Stores:Holland & Barrett and independent specialists curate premium natural and functional variants. Clean-label certification serves as entry ticket.
Supermarkets retain volume dominance while Online Retail climbs the fastest through subscription model adoption.
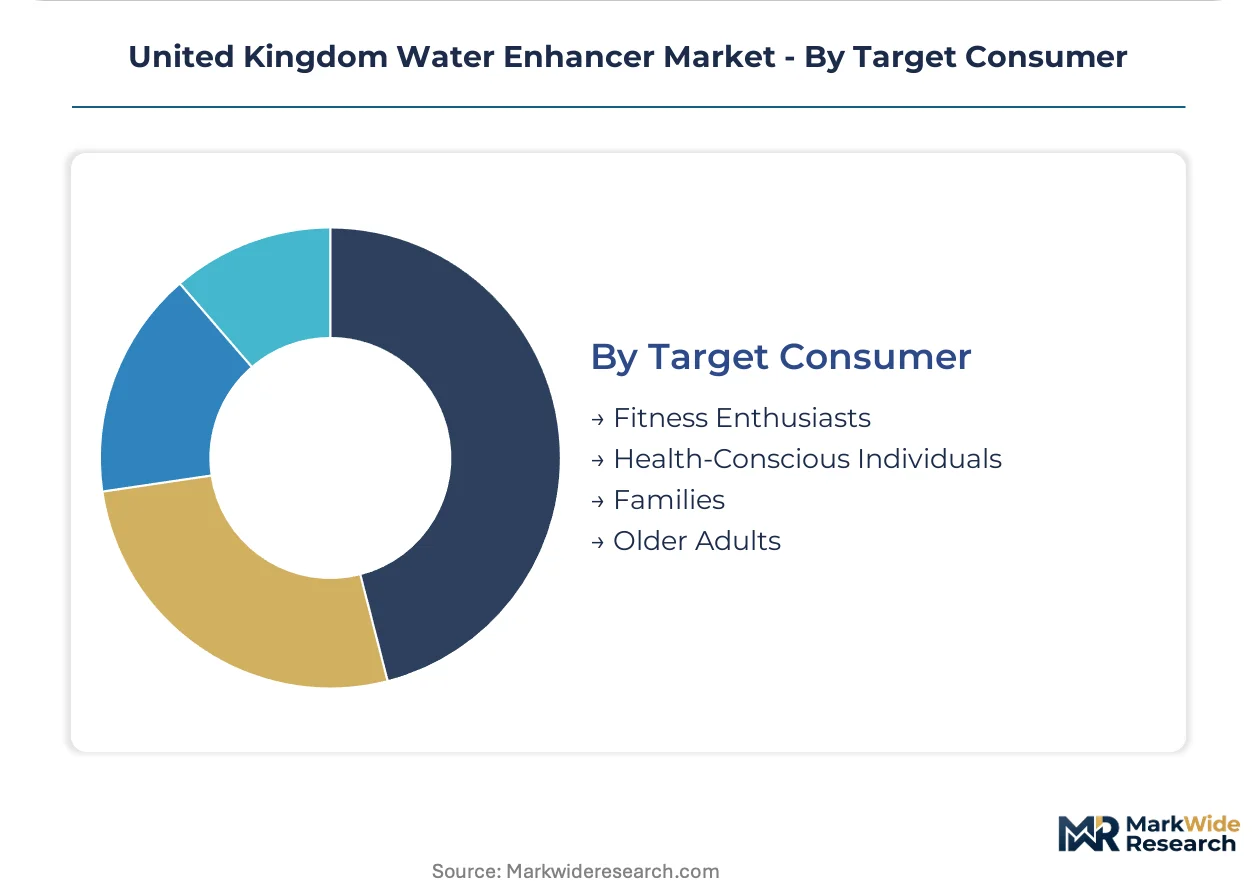
Target Consumer:
Demographic targeting must reconcile divergent price sensitivities and functional claim receptivity across life stage and lifestyle segmentation.
- Health-Conscious Individuals:Millennial and Gen Z consumers in England's urban centres reject artificial ingredients outright. Clean-label purchasing drives premium tier migration.
- Fitness Enthusiasts:Gym members and amateur athletes demand electrolyte and protein-enhanced formulations. Sports nutrition category overlap creates premium positioning opportunities.
- Families:Multi-person households prioritise bulk container value and child-friendly flavour profiles. Supermarket promotional calendars heavily influence brand switching.
- Older Adults:Medication interaction awareness and sugar restriction needs concentrate demand for transparent labelling. Pharmacy channel presence supports trust transfer.
Families anchor the volume base while Health-Conscious Individuals gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
HM Revenue and Customs' sugar tax enforcement is compressing formulation margins across the United Kingdom's water enhancer landscape. England's metropolitan corridors dominate volume consumption while Scottish and Welsh markets present underpenetrated expansion vectors.
London and the Southeast
Zone 1-2 residential clusters generate the highest direct-to-consumer subscription density for automated replenishment cycles. The Advertising Standards Authority's health claim restrictions constrain packaging differentiation for brands targeting fitness-oriented millennials. Waitrose and Marks & Spencer premium tiers anchor natural flavour variant distribution in this corridor.
Midlands
Birmingham's metropolitan households drive bulk container purchases through supermarket promotional calendars. The Food Standards Agency's retained EU compositional standards reduce regulatory friction for compliant domestic suppliers. Independent convenience networks in Coventry and Leicester show emerging adoption for single-serve impulse formats.
North England
Manchester's health clusters concentrate demand for functional formulations with electrolyte fortifications. HM Revenue and Customs' tiered levy structure redirects consumer preference toward dilutable low-calorie alternatives. Tesco and Sainsbury's distribution networks control mass-market penetration across Liverpool and Leeds corridors.
Scotland
Edinburgh and Glasgow gym partnerships create trial pathways for nutritional enhancer variants targeting fitness enthusiasts. The Scottish Government's public health positioning on sugar reduction aligns with zero-sugar portfolio standardization. Independent convenience networks in Aberdeen and Dundee remain underpenetrated relative to English saturation levels.
Wales
Cardiff's independent convenience networks show strongest adoption for impulse sachet placement among transport retail occasions. The Welsh Government's ongoing consultations on front-of-pack nutritional labelling create formulation hesitation pending final display requirements. Swansea and Newport retail corridors offer first-mover shelf space ahead of national grocer consolidation.
United Kingdom Water Enhancer Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the United Kingdom water enhancer market. The upper tier commands supermarket shelf presence through established bottling infrastructure and deep distribution relationships with major grocery chains. Specialist players occupy direct-to-consumer and health food channels with clean-label certifications and functional additive positioning. Competitive survival depends on rapid zero-sugar pivot execution and subscription algorithm deployment for automated household replenishment.
Within the integrated beverage conglomerate tier, The Coca-Cola Company, PepsiCo Inc, and Britvic plc occupy positions defined by bottling infrastructure scale and grocer relationship depth. These entities exemplify the structural advantage of backward integration into existing soft drinks distribution networks. The Kraft Heinz Company and Nestle S.A. represent packaged goods specialists whose supermarket chain partnerships translate into water enhancer slotting access. Lucozade Ribena Suntory and Refresco illustrate regional beverage manufacturing scale as a competitive anchor.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| The Kraft Heinz Company |
| Nestle S.A. |
| Britvic plc |
| Dyla LLC |
| PepsiCo Inc |
| Lucozade Ribena Suntory |
| Refresco |
| Jel Sert Company |
| Others |
Value Network & Pricing Analysis
HM Revenue and Customs' sugar tax levy gates both supplier qualification and price differentiation simultaneously, compressing margins on legacy formulations while rewarding zero-sugar certification with supermarket shelf access. Manufacturers face dual pressure: reformulation costs concentrate in 12-18 month windows, and clean-label compliance determines which tiers command premium positioning.
Pricing Analysis
London's Zone 1-2 residential clusters show the widest price spread, with natural flavour variants commanding multiples over artificial formulations in Waitrose and Marks & Spencer premium tiers. Three-tier pricing structure across premium, standard, and economy levels separates certified clean-label SKUs from supermarket own-label ranges and price-sensitive convenience channels. Cost compression in mid-market stevia-sucralose blends is intensifying because of single-source sweetener concentration among three global chemical processors. Families anchor volume through bulk container promotional sensitivity, while health-conscious millennials in metropolitan England show least price elasticity for botanical-certified variants.
Supply Chain Analysis
Just-in-time inventory strategies dominate liquid concentrate bottling through Britvic plc and Refresco facilities, while strategic stockpiling of Mediterranean citrus and botanical extracts buffers harvest volatility for natural flavour lines. Raw material sourcing draws from Spain and Italy for citrus extracts, India and China for stevia and monk fruit processing, and domestic British herb suppliers for limited-edition botanical collaborations. Single-source sweetener concentration among three global chemical processors creates vulnerability to production disruptions. Distribution runs through Tesco, Sainsbury's, and Asda EDI-compliant networks for mass-market penetration, with direct-to-consumer platforms bypassing slotting fee barriers for automated replenishment cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription algorithm deployment transforms this market's platform economics, as automated 30-day replenishment cycles displace impulse purchases and consolidate household lifetime value capture.
For Market Incumbents: Compound shelf presence advantage through backward integration into captive stevia and monk fruit extraction partnerships, securing supply continuity against single-source processor vulnerability. Deepen formulation science capabilities through university pipeline partnerships, addressing food technologist scarcity that constrains R&D throughput. Accelerate zero-sugar pivot execution ahead of potential advertising restriction extensions to online channels.
For New Entrants and Emerging Players: Direct-to-consumer flavour rotation algorithms represent the service-layer gap where incumbents under-serve, offering personalized replenishment that supermarket promotional calendars cannot match. Scottish and Welsh independent convenience networks present the most penetrable geography, with Edinburgh, Glasgow and Cardiff corridors offering first-mover shelf space ahead of national grocer saturation. Lead with clean-label certification as the go-to-market entry ticket for Holland & Barrett and independent health food channel placement.
For Investors and Strategic Acquirers: HM Revenue and Customs' tiered levy enforcement reshapes the acquisition landscape toward zero-sugar formulation capabilities and subscription platform infrastructure. Five-to-ten year viability hinges on automated replenishment algorithm ownership and natural certification asset bases. Acquisition targets should display direct-to-consumer platform traction or Scottish/Welsh retail corridor penetration ahead of saturation. Watch for front-of-pack labelling consultation finalization as the signal indicating formulation commitment windows and compliance investment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Sugar Formulation Pivot | HM Revenue and Customs' levy tiers redirect consumer preference toward dilutable alternatives, expanding addressable base. |
| Subscription Platform Deployment | Automated 30-day cycles capture household lifetime value through personalized flavour rotation algorithms in metropolitan England. |
| Natural Certification Investment | Clean-label purchasing drives premium tier migration as artificial ingredient rejection spreads into mass-market positioning. |
| Scottish and Welsh Corridor Expansion | Underpenetrated independent convenience networks in Edinburgh, Glasgow and Cardiff offer first-mover shelf space advantages. |
| Functional Additive Integration | Probiotic and nootropic convergence creates premium positioning at sports nutrition and cognitive wellness category overlap points. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Food Standards Agency compositional standards, HM Revenue and Customs levy administration documents, and Advertising Standards Authority regulatory guidance. Primary interviews engaged category buyers at Tesco, Sainsbury's and Asda, formulation scientists at British universities, brand managers at integrated beverage conglomerates, and procurement leads at stevia and monk fruit processors. Secondary validation drew from retained EU food law documentation, supermarket promotional calendar data, and direct-to-consumer platform traffic analytics. Bottom-up demand modeling triangulates against top-down category sizing from retail audit databases.
Segmentation dimensions modeled include formulation philosophy (natural, sugar-free, artificial, nutritional enhanced), packaging convenience (single-serve, bulk container, sachet, bottle), channel accessibility (supermarket, online retail, convenience store, health food store), and target consumer archetype (health-conscious individual, fitness enthusiast, family, older adult). CAGRs derive from trend extrapolation calibrated against historical levy impact elasticity and substitution pattern analysis from bottled water and cold-pressed juice categories. Forecast inputs incorporate sugar tax tier enforcement trajectory and front-of-pack labelling consultation outcomes.
Forecasts assume regulatory continuity in HM Revenue and Customs levy administration and Food Standards Agency compositional standards; material policy shifts would require re-modeling of formulation cost structures and competitive positioning. Revision becomes warranted when Advertising Standards Authority health claim restriction scope crosses thresholds into online channel prohibition or when front-of-pack nutritional scoring systems mandate display format changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
India Food Flavor and Enhancer Market
Food Enhancers and Additives
Feed Palatability Enhancers and Modifiers Market
Food Enhancers and Additives
Water Enhancer Market
Food Enhancers and Additives
Used Cooking Oil Market
Food Enhancers and Additives
Vegetable Shortening Market
Food Enhancers and Additives
Cake Softener Market
Food Enhancers and Additives
Dysphagia Diet Thickening Agents Market
Food Enhancers and Additives
Italy Anti-Caking Market
Food Enhancers and Additives
Japan Water Enhancer Market
Food Enhancers and Additives
South Africa Food Flavor and Enhancer Market
Food Enhancers and Additives
North America Food Thickeners Market
Food Enhancers and Additives
UK Food Flavor and Enhancer Market
Food Enhancers and Additives
Dysphagia Diet Thickening Market
Food Enhancers and Additives
Emulsifier Enhancers Market
Food Enhancers and Additives
Asia-Pacific Food Stabilizers Market
Food Enhancers and Additives
High Ratio Shortening Market