
 Isomalt Market | 2026-2036
Isomalt Market Size, Share, and Industry Trends Forecast 2026-2036
Isomalt Market Outlook
Specialty ingredient distribution is tilting toward direct technical partnerships between sweetener suppliers and large food manufacturers. BENEO GmbH leverages its Palatinit production base in Offstein to sustain supply security for European confectionery clients. Cargill Incorporated anchors North American availability through its broad food ingredient logistics network. Evonik Industries AG competes on pharmaceutical-grade isomalt standards for nutraceutical coating applications.
Isomalt is a disaccharide sugar alcohol manufactured through enzymatic rearrangement of sucrose followed by catalytic hydrogenation, yielding a product with approximately half the caloric value of sucrose and a negligible glycemic response. Its primary commercial purpose centers on bulk sweetening in sugar-free confectionery, pharmaceutical excipients, and specialty bakery where crystallization behavior and thermal stability matter. Powder and granule formats dominate volume throughput due to their handling efficiency in automated manufacturing lines, while crystal grades command premium positioning in artisanal and decorative confectionery where visual clarity and slow dissolution are prized. The confectionery application segment leads absolute consumption, though nutraceuticals is expanding fastest as tablet and gummy manufacturers seek non-cariotic, low-glycemic excipients.
EU REACH and the EFSA novel food evaluation framework govern isomalt placement in new product categories across Europe, while FDA GRAS status shapes US market access and formulation claims. Germany's Federal Institute for Risk Assessment (BfR) and France's ANSES provide national-level scientific opinions that influence member-state enforcement of sugar substitute labeling. Stakeholders must monitor evolving EFSA guidance on polyol labeling thresholds and anticipated EU front-of-pack nutrition labeling rules that could recalibrate consumer perception of sugar-free positioning.
Market Dynamics
EU Regulation 1169/2011 on food information to consumers is tightening labeling requirements for sugar substitutes, forcing manufacturers to reformulate around certified low-glycemic ingredients and reshaping procurement criteria across European confectionery supply chains.
Growth Catalysts
- Tooth-friendly candy positioning:Dental health claims are accelerating isomalt adoption in sugar-free chewing gum and hard candy formulations across German and French retail channels.
- EFSA novel food evaluation framework:Clearer pathways for polyol approval in new product categories are reducing regulatory uncertainty for bakery and nutraceutical applications.
- Enzymatic hydrogenation advances:Improved catalytic processes are lowering production energy intensity and expanding crystal-grade output for artisanal confectionery.
Market Restraints
- Sucrose price volatility:Isomalt's enzymatic feedstock dependency creates margin pressure when raw sugar markets fluctuate.
- Single-source production risk:European supply concentrates heavily on the Palatinit facility in Offstein, creating geographic concentration exposure.
- Polyol digestive tolerance thresholds:Mandatory laxative warning labels under EU law limit dosage flexibility in fortified foods.
Strategic Opportunities
- Pharmaceutical excipient expansion:Tablet coating and pediatric formulation applications remain underdeveloped relative to food uses.
- EU front-of-pack nutrition labeling rules:Anticipated Nutri-Score modifications could recalibrate consumer perception of sugar-free positioning.
- Direct technical partnerships:Sweetener suppliers are bypassing distributors to embed formulation scientists within large food manufacturer R&D teams.
Industry Challenges
- Food technologist scarcity:Specialized expertise in polyol crystallization behavior and thermal stability remains concentrated among veteran confectionery scientists.
- REACH registration timelines:Extended substance evaluation periods delay new isomalt derivative commercialization.
- Legacy equipment retrofit costs:Automated manufacturing lines designed for sucrose require modification to handle hygroscopic sugar alcohol powders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isomalt Market |
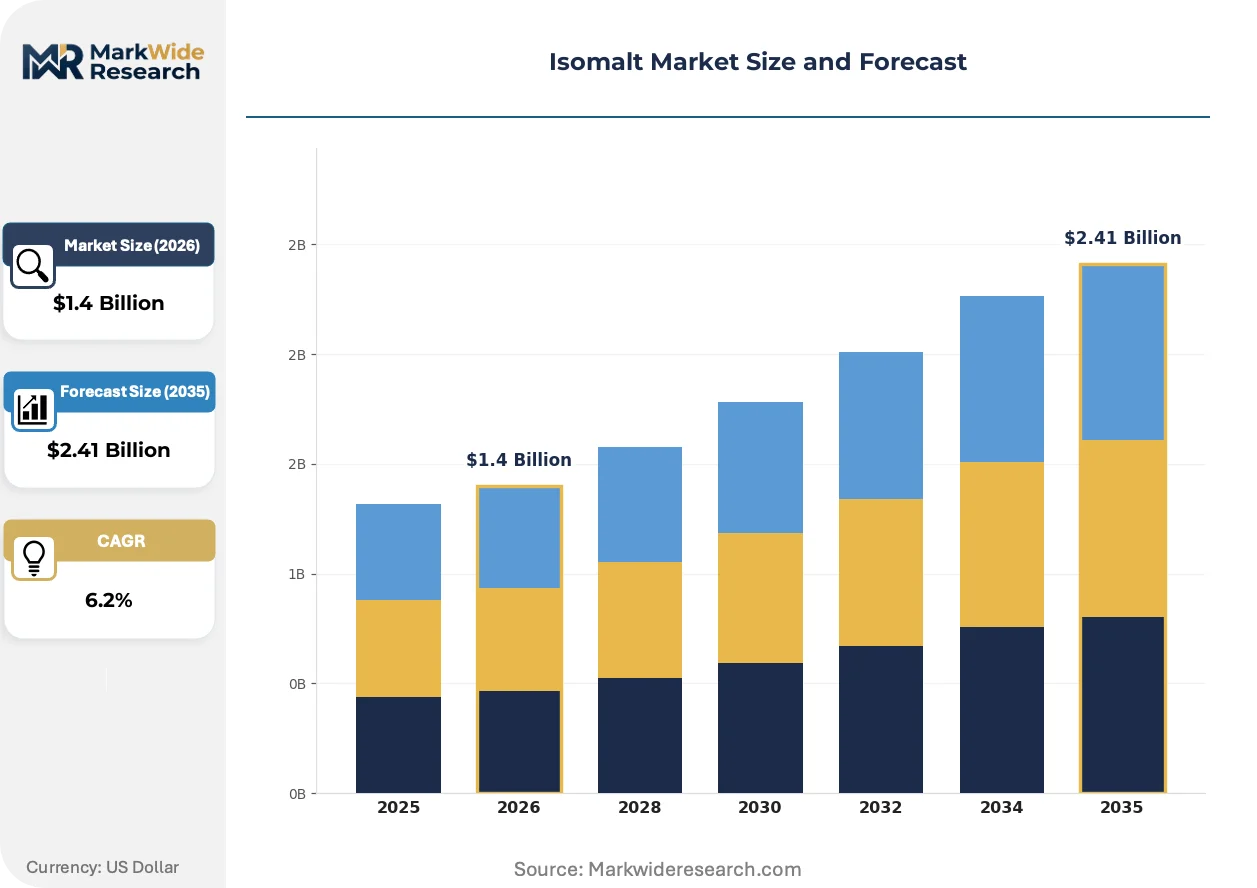
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.41 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Syrup, Crystals Application: Confectionery, Bakery, Dairy, Nutraceuticals Distribution Channel: Online, Supermarkets, Specialty Stores, Direct Sales End User: Food Manufacturers, Retailers, Food Service, Home Bakers |
| Companies Covered | Foodchem International Corporation, Evonik Industries AG, Cargill Incorporated, Wilmar Sugar, Akhil Healthcare, BENEO GmbH, Baolingbao Biology, Tereos Starch & Sweeteners, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isomalt Market Strategic Shifts
Specialty ingredient markets are experiencing a convergence of regulatory precision, manufacturing automation, and health-positioning sophistication that is compressing traditional supplier-buyer relationships.
Continuous enzymatic rearrangement systems are replacing batch sucrose conversion processes in isomalt production. Large-scale confectionery manufacturers in Germany and France are adopting these systems to secure supply consistency. This capital-intensive transition is rendering obsolete smaller batch producers unable to achieve comparable unit economics.
EFSA guidance on polyol labeling thresholds is tightening quantitative disclosure requirements for sugar alcohol content. Food manufacturers must now reformulate or redesign packaging to accommodate expanded nutritional panels. The bakery segment faces the steepest compliance burden as multi-ingredient products trigger cumulative threshold calculations.
Buyer concentration among multinational food manufacturers is compressing supplier negotiation cycles. Direct procurement agreements with technical service attachments are displacing traditional ingredient distributor relationships. This pattern is most visible in German nutraceutical manufacturing clusters where formulation collaboration precedes volume commitments.
Isomalt Market Segmentation
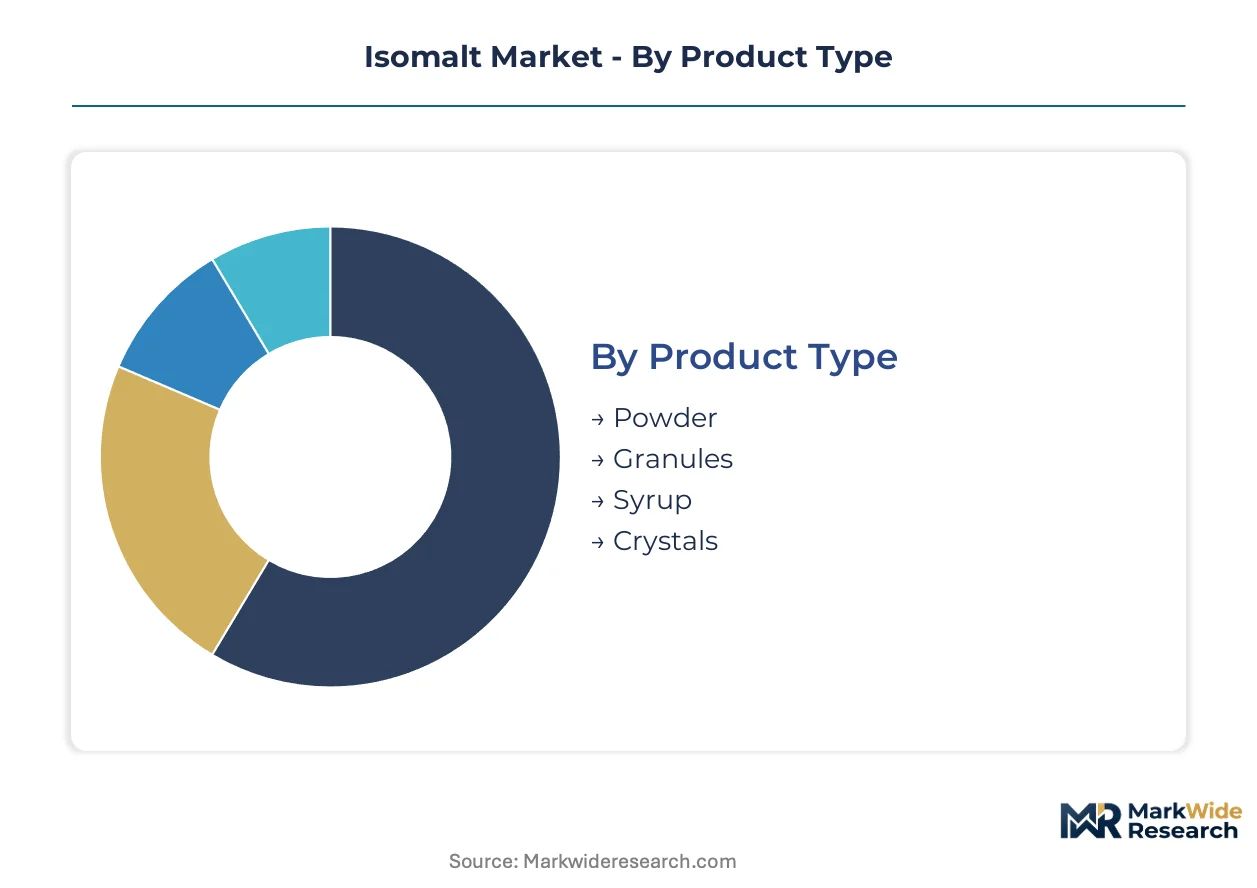
Isomalt's crystallization behavior and thermal stability create divergent value profiles across physical formats. Application requirements for bulk sweetening versus pharmaceutical-grade excipients drive distinct procurement patterns. Distribution channel selection reflects whether buyers prioritize formulation technical support or commodity logistics efficiency.
Product Type:
Physical form dictates handling efficiency in automated manufacturing lines and determines premium positioning in artisanal applications.
- Powder:Fine particle distribution enables rapid dissolution in beverage and compressed tablet applications. German nutraceutical manufacturers favor powder grades for high-speed tableting operations where flowability directly impacts throughput. EFSA polyol labeling thresholds create reformulation pressure as cumulative sugar alcohol content triggers mandatory disclosure.
- Granules:Intermediate particle size balances dissolution speed with dust control in industrial bakery environments. French confectionery producers specify granule grades for pan-coating operations where uniform crystal deposition matters. REACH registration timelines for modified granule specifications delay new product introductions.
- Syrup:Pre-dissolved format eliminates hydration steps in liquid food systems.
- Crystals:Large, visually clear structures command premium positioning in decorative and artisanal confectionery.
Powder commands the established base. The steepest expansion runs through crystals.
Application:
End-use differentiation separates commodity bulk sweetening from specialized excipient functionality.
- Confectionery:Hard candy and chewing gum formulations exploit isomalt's non-cariogenic properties and thermal stability during high-temperature processing. German retail channels feature tooth-friendly positioning prominently. EU Regulation 1169/2011 mandates precise sugar substitute labeling that constrains marketing claims.
- Nutraceuticals:Tablet coating and gummy matrices demand pharmaceutical-grade isomalt with tight microbiological specifications. Evonik Industries AG supplies this segment with certified excipient grades. BfR scientific opinions on polyol safety influence formulation maximums in pediatric applications.
- Bakery:Maillard reaction limitations restrict isomalt usage in browning-dependent products.
- Dairy:Frozen dessert applications leverage depressed freezing point depression relative to sucrose.
Confectionery retains volume leadership. Nutraceuticals climbs the fastest.
Distribution Channel:
Channel selection reflects buyer scale and technical service requirements.
- Direct Sales:Large food manufacturers negotiate technical partnership agreements embedding supplier formulation scientists within R&D teams. BENEO GmbH leverages its Palatinit production base for direct supply security. Procurement cycles compress as buyer concentration increases among multinational confectionery groups.
- Specialty Stores:Artisanal and small-batch producers source crystal grades through regional ingredient distributors.
- Supermarkets:Commodity powder and granule formats move through retail channels for home baker segments.
- Online:E-commerce platforms serve fragmented small-volume buyers with standardized specifications.
Direct sales anchors commercial relationships. Online channels gain share fastest among fragmented buyers.
End User:
Customer type determines whether procurement prioritizes unit economics or formulation collaboration.
- Food Manufacturers:Automated production lines demand consistent powder and granule flow characteristics. Legacy equipment retrofit costs create switching friction when transitioning from sucrose-based systems. Continuous enzymatic rearrangement systems at supplier level secure batch-to-batch consistency for high-volume contracts.
- Food Service:Institutional kitchens and bakery chains source through broadline distributors.
- Retailers:Private-label sugar-free product lines drive specification requirements.
- Home Bakers:Small-package retail sales concentrate in specialty and online channels.
Food manufacturers dominate volume. Food service expands most quickly as sugar-free menu positioning accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's specialized bulk liquid handling infrastructure underwrites Benelux distribution reach for European isomalt supply chains. Rail corridors connecting German chemical clusters to French confectionery centers enable just-in-time delivery windows. Mediterranean port expansions in Barcelona and Marseille are shortening lead times to North African processing facilities.
Germany
Tooth-friendly candy positioning and pharmaceutical excipient demand drive German consumption volumes. BfR scientific opinions on polyol safety influence maximum dosage formulations in pediatric applications. The Palatinit production base in Offstein anchors supply security for pan-European confectionery clients.
France
Artisanal confectionery producers in Lyon and Paris specify crystal-grade isomalt for decorative applications. ANSES evaluations of sugar substitute safety shape national enforcement of EU labeling thresholds. The Auvergne-Rhône-Alpes cluster houses specialized distributors serving Mediterranean bakery chains.
United States
FDA GRAS status enables sugar-free positioning claims across chewing gum and hard candy segments. Cargill's broad logistics network secures Midwest and Southeast manufacturing coverage. Chicago-area food technologist clusters support formulation adaptation from sucrose-based legacy equipment.
China
Domestic pharmaceutical tablet coating applications expand as SAMR tightens excipient quality standards. NMPA novel food pathways are clarifying polyol approval timelines for bakery applications. Shandong Province hosts enzymatic hydrogenation facilities supplying Asian nutraceutical manufacturers.
India
FSSAI sugar substitute labeling rules are accelerating reformulation in Mumbai and Delhi confectionery markets. CDSCO pharmaceutical-grade certifications enable export-oriented excipient production. Gujarat chemical corridors host toll manufacturers serving Middle East and African buyers.
Isomalt Market Competitive Environment
On the supply side, the industry is consolidating around integrated sweetener specialists with captive enzymatic hydrogenation capabilities. Three strategic archetypes dominate: European pharmaceutical-grade specialists, Asian toll manufacturers with cost-optimized batch processes, and global ingredient distributors with technical service attachments. Dominant competitive moves include backward integration into sucrose feedstock sourcing and direct embedding of formulation scientists within large food manufacturer R&D teams.
Among Germany-based integrated producers, BENEO GmbH and Evonik Industries AG exemplify the pharmaceutical-grade specialization archetype. Cargill Incorporated anchors North American availability through scale-driven distribution infrastructure. Foodchem International Corporation represents the China-based toll manufacturing tier serving cost-sensitive export markets.
| Leading Market Players |
|---|
| Foodchem International Corporation |
| Evonik Industries AG |
| Cargill Incorporated |
| Wilmar Sugar |
| Akhil Healthcare |
| BENEO GmbH |
| Baolingbao Biology |
| Tereos Starch & Sweeteners |
| Merck KGaA |
| Others |
Value Chain & Pricing Dynamics
Single-source production risk at the Palatinit facility in Offstein determines both the spread between pharmaceutical-grade crystal premiums and commodity powder baselines and the geographic shape of European distribution networks. Sucrose feedstock volatility feeds directly into margin compression for batch producers unable to secure long-term beet sugar contracts.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade crystal premiums from standard powder and granule baselines. Price differentiation hinges on EFSA certification status and microbiological specification stringency for nutraceutical applications. Cost compression in commodity grades is intensifying as Asian toll manufacturers expand enzymatic hydrogenation capacity. Food manufacturers with automated high-volume lines exhibit lowest price sensitivity; artisanal confectioners and home baker segments drive hardest bargain hunting.
Supply Chain Analysis
Upstream sucrose beet sourcing draws from German, French, and Polish agricultural cooperatives through seasonal harvest contracts. Catalytic hydrogenation equipment and specialized crystallization vessels rest on German and Chinese manufacturing bases. Single-source vulnerability concentrates at the Offstein production complex, where any operational disruption would cascade through pan-European confectionery supply chains. Distribution runs through direct technical partnerships for multinational food manufacturers, with specialty distributors serving fragmented artisanal buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation technical services represent a recurring-revenue layer expanding faster than commodity isomalt tonnage, as embedded R&D collaboration locks in multi-year supply agreements ahead of volume commitments.
For Market Incumbents: Harden supply security through backward integration into sucrose feedstock sourcing and captive enzymatic hydrogenation capacity additions. Invest in pharmaceutical-grade certification infrastructure to defend margin position against Asian toll manufacturers entering European nutraceutical channels.
For New Entrants and Emerging Players: Pursue underdeveloped pharmaceutical excipient segments, particularly pediatric tablet coatings and sustained-release matrices where BfR dosage guidance creates formulation complexity barriers. Target Indian and Middle Eastern export markets through Gujarat-based toll manufacturing partnerships.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated specialists with captive production and direct technical service capabilities. Acquisition screening should prioritize European producers with Palatinit-equivalent enzymatic rearrangement assets. Watch EFSA front-of-pack nutrition labeling rulemaking as the signal for consumer perception shifts that would recalibrate sugar-free premium positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sucrose Feedstock | Captive beet sugar supply from German and French agricultural cooperatives insulates margin volatility. |
| Pharmaceutical-Grade Certification Investment | EFSA and BfR excipient standards unlock pediatric and sustained-release formulation premiums. |
| Direct Technical Partnership Expansion | Embedded formulation scientists within Cargill and BENEO client R&D teams displace distributor relationships. |
| Continuous Enzymatic Rearrangement Scale-Up | Capital-intensive process conversion at Offstein secures batch-to-batch consistency for high-volume contracts. |
| Asian Toll Manufacturing Joint Venture | Shandong and Gujarat production bases serve cost-sensitive Middle East and African export demand. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with confectionery formulation scientists, pharmaceutical excipient procurement managers, bakery R&D directors, and specialty ingredient distributors. Secondary validation drew from EFSA guidance documents, BfR scientific opinions, EU REACH registration databases, and trade flow data through the Port of Rotterdam. Bottom-up volume modeling from application segments was triangulated against top-down capacity assessments at major production facilities.
Calibration against historical price spreads between crystal and powder grades informed elasticity assumptions across the analysis window. Segmentation dimensions modeled include physical form, application category, distribution channel, and end-user scale tier. CAGRs were derived from trend extrapolation of enzymatic hydrogenation capacity expansion and regulatory approval timelines for novel food categories. Forecast inputs incorporated sucrose price volatility scenarios and EFSA polyol labeling threshold revisions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese enzymatic hydrogenation specialists or sudden EFSA regulatory reversals would shift outcomes materially. Cross-checking against customs trade data and BENEO quarterly production disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Charcoal-Infused Food Market
Food Enhancers and Additives
Liquid Water Enhancers Market
Food Enhancers and Additives
Natural Taste Enhancers and Modifiers Market
Food Enhancers and Additives
Raising Agents Market
Food Enhancers and Additives
Dough Conditioners Market
Food Enhancers and Additives
Cake Softener Market
Food Enhancers and Additives
Liquid Smoke Market
Food Enhancers and Additives
Food Raising Agents Market
Food Enhancers and Additives
Veratrole Market
Food Enhancers and Additives
Feed Palatability Enhancers and Modifiers Market
Food Enhancers and Additives
Dysphagia Diet Thickening Agents Market
Food Enhancers and Additives
Gut Modifiers Market
Food Enhancers and Additives
South Africa Food Flavor and Enhancer Market
Food Enhancers and Additives
Canada Food Flavor and Enhancer Market
Food Enhancers and Additives
United Kingdom Water Enhancer Market
Food Enhancers and Additives
Enriched Yeast Extract Market