
 Fortified Eggs Market | 2026-2036
Fortified Eggs Market Size, Share, and Industry Trends Forecast 2026-2036
Fortified Eggs Market Foresight
Subscription-based replenishment programs for omega-3 enriched eggs is broadening how producers monetize recurring household demand. Eggland's Best leverages its retail shelf presence to sustain brand recognition across conventional and natural grocery channels. Vital Farms anchors its competitive stance through pasture-raised sourcing claims that resonate with ethically motivated shoppers. Cal-Maine Foods dominates production scale, operating the largest shell egg network in the United States with integrated feed-to-retail capabilities.
Fortified eggs denote shell eggs enhanced through modified hen diets with specific micronutrients—typically omega-3 fatty acids, vitamin D, or lutein—achieving measurable compositional shifts in yolk lipid profiles and albumen vitamin content. These products serve clinical nutrition, preventive health, and performance-oriented dietary protocols where whole-food delivery of bioavailable nutrients outperforms synthetic supplementation. Omega-3 enriched eggs command the largest volume position due to cardiovascular health positioning, while vitamin D fortified variants represent the fastest-growing category as deficiency screening expands in temperate climates. Margin pools concentrate in multinutrient enriched products targeting geriatric diets, where reimbursement-adjacent positioning supports price premiums over standard specialty eggs.
The FDA oversees nutrient content claims and hen feed additive approvals in the United States, while EFSA in Europe establishes maximum enrichment thresholds and labeling requirements that constrain formulation latitude. USDA organic certification and state-level cage-free mandates in California and Massachusetts further segment competitive access by production method. Stakeholders must monitor evolving EPA-DHA source regulations for feed, as algae-derived versus fish-oil enrichment pathways face divergent sustainability and contaminant scrutiny that will reshape supplier qualification standards.
Market Dynamics
Feed additive regulatory divergence between EFSA thresholds and FDA approval pathways is fragmenting formulation strategies, forcing producers to maintain parallel enrichment protocols or sacrifice cross-border market access.
Growth Catalysts
- Sports nutrition protocols:Athletes and fitness practitioners prioritize whole-food protein sources with verified omega-3 content, creating pull-through demand from performance-oriented retail channels.
- EFSA guidance updates:The European Food Safety Authority's revised maximum enrichment thresholds provide clearer compliance boundaries, reducing regulatory uncertainty for EU-focused producers.
- Algae-derived DHA:Marine microalgae cultivation for feed-grade omega-3 bypasses fish-oil supply volatility and contaminant concerns, securing sustainable input streams for premium positioning.
Market Restraints
- Fish-meal price volatility:Traditional marine-derived feed inputs fluctuate with capture fishery yields, compressing margin predictability for omega-3 enriched production lines.
- California cage-free mandates:State-level production method requirements fragment national supply chains, forcing dual-sourcing infrastructure or geographic market exclusion.
- Synthetic supplement substitution:Pharmaceutical-grade omega-3 capsules and vitamin D tablets offer standardized dosing at lower per-unit nutrient cost, constraining price ceiling for food-format alternatives.
Strategic Opportunities
- Geriatric nutrition reimbursement:Clinical positioning of multinutrient enriched eggs adjacent to Medicare Advantage supplemental benefit programs unlocks institutional procurement channels.
- Direct-to-consumer subscription:Recurring delivery models bypass conventional retail slotting fees, capturing household lifetime value through automated replenishment.
- Pasture-raised certification convergence:Integration of welfare credentials with nutrient enrichment commands dual premium pricing in natural grocery and foodservice segments.
Industry Challenges
- Hen nutritionist talent scarcity:Specialized expertise in micronutrient bioavailability and yolk deposition kinetics remains concentrated among academic and large integrated operations.
- USDA organic compliance timelines:Three-year feed conversion requirements for organic certification delay enriched product launches and tie up working capital in transition flocks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fortified Eggs Market |
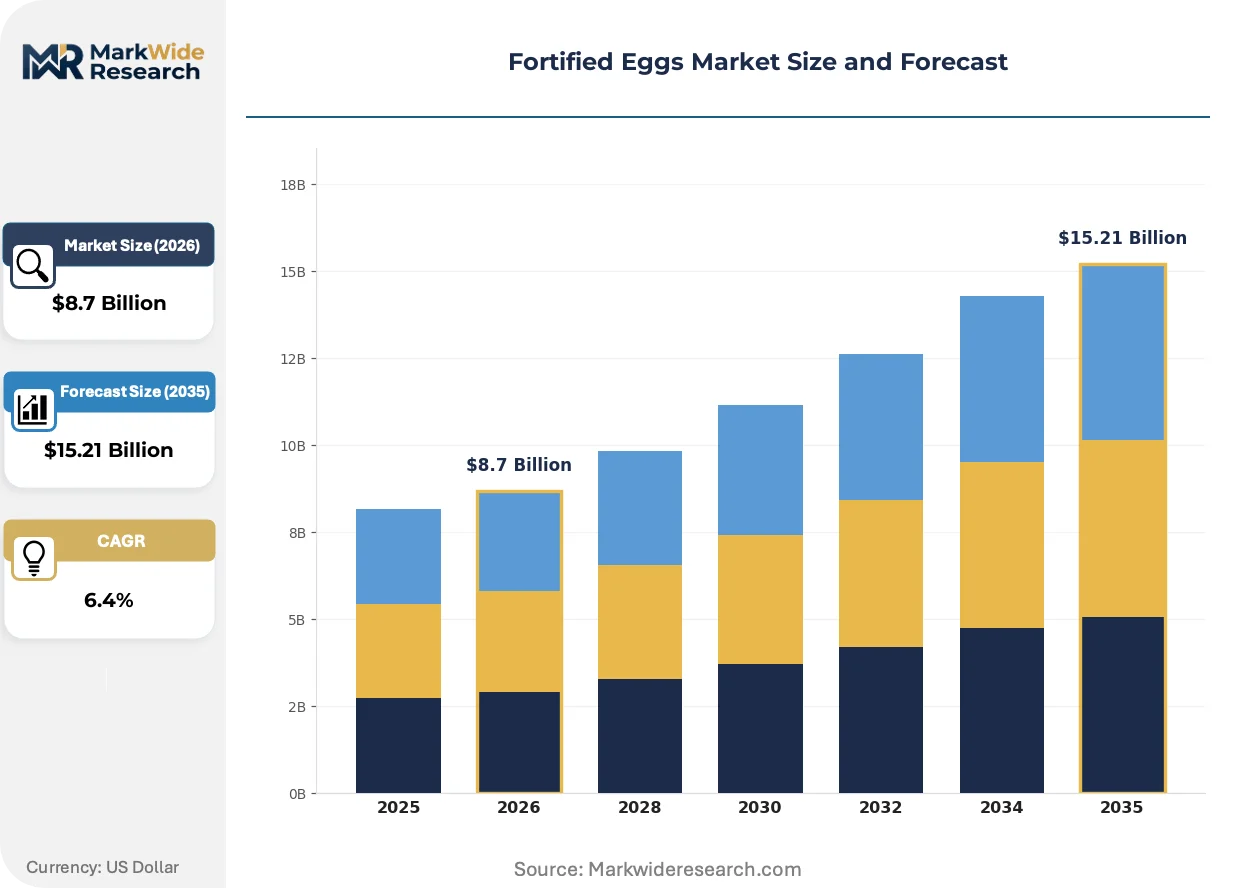
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Omega-3 Enriched, Vitamin D Fortified, Iron Fortified, Calcium Enhanced, Multinutrient Enriched Application: Infant Nutrition, Geriatric Diets, Sports Nutrition, Weight Management, Culinary Use Customer Type: Health-Conscious Individuals, Nutritional Supplement Users, Foodservice Providers, Specialty Retailers, Fitness Enthusiasts Distribution Channel: Supermarkets, Online Grocery Platforms, Convenience Stores, Specialty Health Stores, Wholesale Suppliers |
| Companies Covered | Oakdell, NutriPlus, Eggland’s Best, Farm Pride Foods Ltd., Boulder Brands USA, Vital Farms, Cal-Maine Foods, Wilcox, Clover Stornetta Farms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fortified Eggs Market Shifts & Advancements
Precision feed formulation and alternative DHA sourcing are compressing the cost premium between fortified and conventional eggs, while digital traceability infrastructure reshapes how producers communicate enrichment provenance to skeptical buyers.
Algae-based omega-3 enrichment is expanding into mainstream retail tiers as cultivation scale drives input cost parity with marine fish oil. Mid-tier producers in the United States and Netherlands are adopting algae-derived DHA to meet sustainability commitments without sacrificing cardiovascular health claims. This shift is expanding into private-label supply agreements previously reserved for premium branded portfolios, compressing differentiation windows for early movers.
EFSA's 2023 updated guidance on maximum vitamin D levels in hen eggs mandates tighter analytical verification and batch documentation across European production facilities. The regulation forces reformulation of legacy products exceeding new thresholds and accelerates investment in in-house HPLC testing capabilities. German and Dutch producers face the steepest compliance curves given their historical positioning at upper enrichment limits.
Subscription-based replenishment is displacing conventional retail purchasing among health-conscious households with predictable consumption patterns. Digital-native entrants and established brands alike deploy direct-to-consumer platforms with flexible delivery cadences, capturing customer data that informs product development. This channel rotation concentrates in United States metropolitan corridors with established cold-chain logistics density and high functional food literacy.
Fortified Eggs Market Segmentation
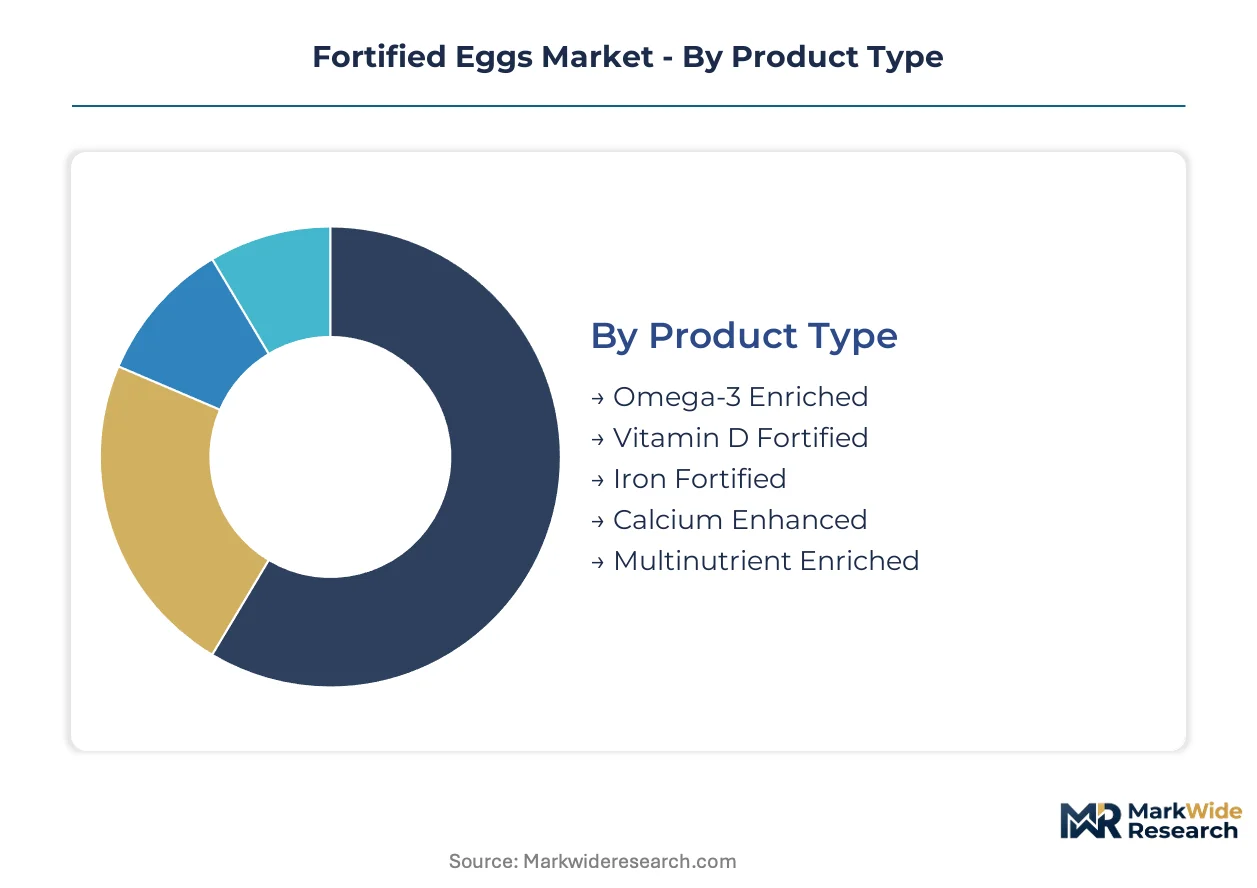
Fortified eggs fragment across nutrient composition, end-use application, and procurement channel, with each axis commanding distinct margin profiles and regulatory exposure. Producers must align enrichment protocols with specific buyer willingness-to-pay thresholds rather than pursuing uniform premium positioning.
Product Type:
Buyers differentiate by targeted health outcome and bioavailability verification, not by shell appearance or conventional quality grades.
- Omega-3 Enriched:Yolk DHA and EPA elevation through marine or algae-derived feed additives delivers cardiovascular and cognitive health claims. Demand concentrates in sports nutrition protocols across United States metropolitan markets where athletes prioritize verified fatty acid content over synthetic supplements.
- Multinutrient Enriched:Simultaneous omega-3, vitamin D, and lutein deposition targets geriatric nutrition reimbursement pathways. German and Dutch producers face EFSA threshold compliance pressure that constrains legacy formulation latitude.
- Vitamin D Fortified:Seasonal deficiency correction in temperate climates drives household replenishment cycles through direct-to-consumer channels.
- Iron Fortified:Bioavailable heme-iron analogs in yolk target pediatric and maternal nutrition programs in India and Brazil.
- Calcium Enhanced:Shell and albumen mineral density modifications serve institutional foodservice contracts with mandated nutritional specifications.
Volume sits with omega-3 variants; growth tilts toward multinutrient formulations as reimbursement-adjacent positioning expands.
Application:
End-use determines packaging format, shelf-life requirements, and the depth of clinical validation demanded by procurement decision-makers.
- Sports Nutrition:Whole-food protein positioning with verified omega-3 content captures performance-oriented retail channels and collegiate athletic programs. United States fitness practitioners drive pull-through demand from specialty grocers and direct-to-consumer platforms.
- Geriatric Diets:Nutrient density per serving and ease of mastication command institutional procurement through Medicare Advantage supplemental benefit structures. Massachusetts and California cage-free mandates complicate national supply chain configuration for this price-insensitive segment.
- Infant Nutrition:Choline and DHA bioavailability claims target parental anxiety about early cognitive development.
- Weight Management:Satiety-index positioning and portion-controlled packaging serve bariatric protocol adherence.
- Culinary Use:Functional properties including emulsification stability and flavor neutrality matter more than micronutrient claims for foodservice procurement.
Procurement scale favors geriatric institutional channels; steepest expansion trajectory runs through sports nutrition as clean-label protein alternatives displace processed supplements.
Customer Type:
Purchasing sophistication varies from data-driven clinical specification to impulse-driven welfare credential preference.
- Health-Conscious Individuals:Subscription-based replenishment with flexible delivery cadences captures household lifetime value in United States metropolitan corridors with established cold-chain logistics density.
- Foodservice Providers:Volume contracts with specified nutrient thresholds and audit documentation requirements dominate procurement for hospital and long-term care facilities.
- Nutritional Supplement Users:Cross-shopping behavior between pharmaceutical-grade capsules and whole-food alternatives constrains price ceiling tolerance.
- Specialty Retailers:Pasture-raised certification convergence with enrichment claims commands dual premium positioning in natural grocery segments.
- Fitness Enthusiasts:Macro-tracking app integration and verified protein-to-fat ratios drive brand switching behavior.
Transaction frequency peaks with health-conscious households; margin concentration sits with foodservice providers under institutional contract terms.
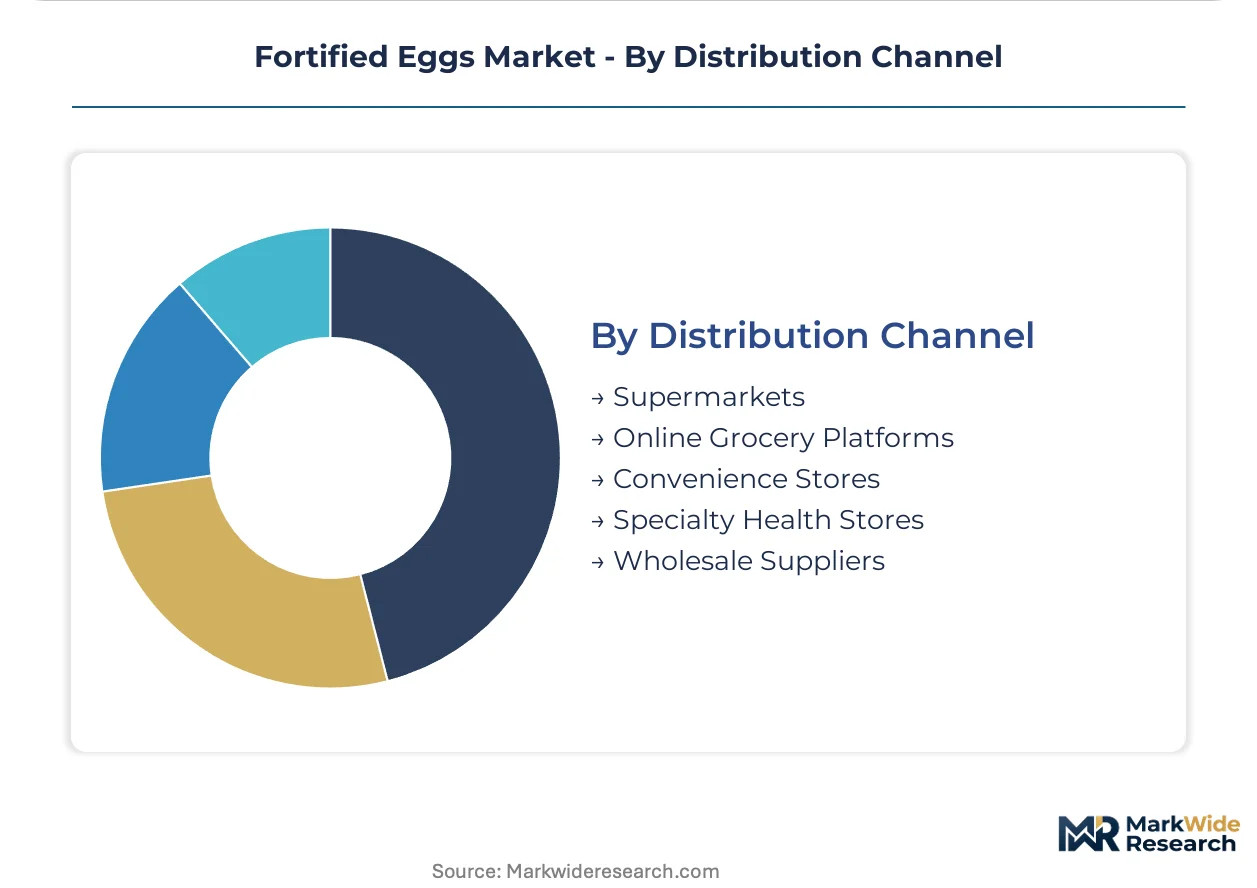
Distribution Channel:
Channel selection determines working capital intensity, traceability infrastructure requirements, and exposure to slotting fee structures.
- Online Grocery Platforms:Direct-to-consumer models bypass conventional retail slotting fees while capturing consumption data that informs precision feed formulation. Cold-chain logistics density in Netherlands and United States urban corridors enables viable fulfillment economics.
- Supermarkets:Retail shelf presence sustains brand recognition across conventional and natural grocery channels, though slotting fees compress net revenue per dozen.
- Specialty Health Stores:Educated staff and supplement-adjacent merchandising justify premium pricing for clinically positioned variants.
- Convenience Stores:Grab-and-go packaging and abbreviated shelf-life specifications serve immediate consumption occasions with limited nutrient claim visibility.
- Wholesale Suppliers:Institutional procurement aggregation for foodservice and healthcare facilities demands batch documentation and HPLC verification capabilities.
Revenue concentration remains with supermarkets; channel rotation toward online grocery platforms is accelerating among subscription-adopted households.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Des Moines anchors North American fortified egg production through integrated feed-to-retail networks serving metropolitan demand corridors. Regulatory divergence between EFSA thresholds and FDA approval pathways fragments cross-border formulation strategies.
United States
Sports nutrition protocols and direct-to-consumer subscription models drive adoption across metropolitan corridors with established cold-chain logistics density. FDA oversight of nutrient content claims and hen feed additive approvals shapes enrichment protocol design. California cage-free mandates and Massachusetts production requirements fragment national supply chains, forcing dual-sourcing infrastructure or geographic market exclusion.
Germany
Geriatric nutrition reimbursement pathways and multinutrient enriched product demand concentrate procurement scale in institutional channels. EFSA maximum enrichment thresholds constrain legacy formulation latitude and mandate tighter analytical verification. The Lower Saxony poultry corridor faces steep compliance curves given historical positioning at upper enrichment limits.
Netherlands
Algae-derived DHA adoption and precision feed formulation capabilities position Dutch producers at the sustainability frontier of omega-3 enrichment. EFSA 2023 vitamin D guidance updates force reformulation and accelerate HPLC testing investment. The Gelderland feed innovation cluster compresses cost premiums between fortified and conventional eggs through cultivation scale economics.
India
Iron-fortified variants targeting pediatric and maternal nutrition programs expand addressable household base beyond cardiovascular positioning. FSSAI feed additive regulations and state-level nutritional intervention schemes shape enrichment protocol standardization. The Punjab-Haryana poultry belt concentrates production scale for institutional procurement contracts with mandated nutritional specifications.
Brazil
Calcium-enhanced egg demand from institutional foodservice contracts with mandated nutritional specifications drives mineral density modifications. ANVISA oversight of feed-grade additives and yolk deposition claims constrains clinical positioning latitude. The São Paulo state corridor integrates welfare credentials with nutrient enrichment for dual premium positioning in natural grocery segments.
Fortified Eggs Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across feed formulation, enrichment verification, and channel access dimensions. The vendor base clusters around three strategic archetypes: integrated feed-to-retail operators with captive supply networks, pasture-raised specialists with welfare credential convergence, and digital-native subscription platforms with direct household relationships. Dominant competitive moves include backward integration into algae-derived DHA cultivation and geographic capacity expansion to serve state-level cage-free mandates.
Within the integrated operator tier, Cal-Maine Foods and Vital Farms exemplify divergent scale-positioning strategies. Eggland's Best occupies a position bridging conventional and natural grocery channel access. Among pasture-raised specialists, Vital Farms anchors welfare credential convergence with nutrient enrichment claims. The subscription-platform vector remains contested by digital-native entrants and established brands deploying automated replenishment models.
| Leading Market Players |
|---|
| Oakdell |
| NutriPlus |
| Eggland's Best |
| Farm Pride Foods Ltd. |
| Boulder Brands USA |
| Vital Farms |
| Cal-Maine Foods |
| Wilcox |
| Clover Stornetta Farms |
| Others |
Supply & Pricing Matrix
Subscription-based household replenishment in United States metropolitan corridors forces producers to reconfigure fulfillment infrastructure toward direct-to-consumer cold-chain networks, compressing slotting-fee avoidance into margin recovery that sustains premium positioning against conventional retail alternatives.
Pricing Analysis
Margin tightening in multinutrient enriched tiers reflects EFSA threshold compliance costs and HPLC testing investment. Three-tier pricing structure across pasture-raised premium, cage-free standard, and conventional economy levels separates welfare-credentialed products from basic enrichment variants. Price differentiation hinges on certification grade and volume scale, with institutional foodservice buyers exhibiting lowest sensitivity due to reimbursement-adjacent procurement, while convenience channel shoppers face highest price elasticity.
Supply Chain Analysis
Algae-derived DHA supply rests on Netherlands and United States cultivation facilities scaling marine microalgae fermentation. Feed-grade omega-3 inputs, vitamin D premixes, and cage-free layer housing equipment constitute critical component dependencies. Single-source vulnerability concentrates in algae cultivation bioreactors, where equipment lead times constrain capacity expansion. Distribution runs through integrated feed-to-retail networks anchored in Des Moines and Gelderland, with cold-chain density determining last-mile economics for subscription fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence between EFSA enrichment thresholds and FDA approval pathways is forcing smaller producers toward exit or acquisition, consolidating formulation expertise among capital-heavy integrated operators with parallel compliance capabilities.
For Market Incumbents: Anchor market position through backward integration into algae-derived DHA cultivation, securing sustainable input streams against fish-oil price volatility. Invest in in-house HPLC testing capabilities to accelerate EFSA compliance verification and capture geriatric nutrition reimbursement channels before smaller competitors exhaust transition capital. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable route, bypassing supermarket slotting fees while capturing household lifetime value through automated replenishment. Target sports nutrition segments in United States metropolitan corridors with cold-chain logistics density, positioning whole-food protein alternatives against synthetic supplement displacement. For Investors and Strategic Acquirers: Re-rating potential sits with pasture-raised specialists possessing welfare credential convergence and nutrient enrichment capabilities, given Medicare Advantage supplemental benefit expansion as a demand catalyst. Watch EFSA guidance harmonization pressure as an inflection signal that would accelerate consolidation among European producers facing compliance cost cliffs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Algae Cultivation | Secures sustainable DHA supply bypassing fish-oil volatility and contaminant scrutiny. |
| Direct-to-Consumer Subscription Launch | Captures household lifetime value while avoiding retail slotting fees in United States corridors. |
| Pasture-Raised Certification Investment | Commands dual premium pricing through welfare credential convergence with enrichment claims. |
| HPLC Testing Capability Buildout | Enables EFSA compliance verification and accelerates multinutrient product reformulation. |
| Geriatric Nutrition Reimbursement Strategy | Unlocks institutional procurement through Medicare Advantage supplemental benefit positioning. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with layer nutritionists, feed formulation specialists, retail category buyers, and institutional foodservice procurement managers. FDA guidance documents, EFSA scientific opinions, USDA organic certification databases, and state-level cage-free mandate filings provided regulatory boundary conditions. Bottom-up volume estimates from production facility counts reconciled against top-down expenditure flows from household panel data.
Data-stream reconciliation across the projection horizon modeled nutrient composition, end-use application, procurement channel, and regional regulatory cluster as segmentation dimensions. CAGRs derived from trend extrapolation of enrichment adoption rates and premium pricing persistence, with inputs including hen feed additive approval timelines and cold-chain logistics density indices.
The model holds under stable regulatory enforcement and sustained reimbursement pathway expansion; deviation in EFSA threshold tightening or algae supply disruption would shift volume trajectories. Forecasts reflect assumptions about consumer willingness-to-pay for welfare credentials and bioavailability verification. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
India Food Flavor and Enhancer Market
Food Enhancers and Additives
Natural Taste Enhancers and Modifiers Market
Food Enhancers and Additives
North America Vinegar Market
Food Enhancers and Additives
Mexico Food Flavor and Enhancer Market
Food Enhancers and Additives
Emulsifier Enhancers Market
Food Enhancers and Additives
Cake Softener Market
Food Enhancers and Additives
Food Thickening Agents Market
Food Enhancers and Additives
Europe Water Enhancer Market
Food Enhancers and Additives
Emulsifier Alternatives Market
Food Enhancers and Additives
Dough Conditioners Market
Food Enhancers and Additives
Spain Food Flavor and Enhancer Market
Food Enhancers and Additives
Liquid Water Enhancers Market
Food Enhancers and Additives
Charcoal-Infused Food Market
Food Enhancers and Additives
Isoprenol Market
Food Enhancers and Additives
Frying Shortening Market
Food Enhancers and Additives
Vegetable Shortening Market