
 United States Energy Bar Market | 2026-2036
United States Energy Bar Market Size, Share, and Industry Trends Forecast 2026-2036
United States Energy Bar Market Outlook
Market Context
The outdoor recreation and endurance sports vertical is realigning purchasing patterns toward higher-protein, cleaner-label formats. Clif Bar and Co. leverages its organic supply chain and brand heritage in cycling and climbing communities to sustain loyalty among performance-oriented users. General Mills Inc. competes through mainstream retail penetration and portfolio breadth that spans nutritional bars to snack-oriented offerings. Post Holdings Inc. anchors its position through protein-forward formulations targeting serious athletes and gym-based consumers.
Technical Definition and Segment Structure
A United States Energy Bar is a shelf-stable, individually wrapped food product typically delivering 150–300 calories with macronutrient profiles emphasizing carbohydrates, protein, or balanced energy release, manufactured through cold-press extrusion or baked slab-and-cut processes for portable consumption during physical exertion or meal gap situations. Protein Bars dominate value contribution due to premium pricing and repeat purchase frequency among fitness enthusiasts, while Snack Bars extend volume through impulse-driven convenience store channels. Online Retail represents the fastest-growing distribution pathway as direct-to-consumer subscriptions and performance-oriented curation reduce friction for ingredient-discerning buyers.
Regulatory Framework and Outlook
The FDA governs nutrition labeling, health claim substantiation, and allergen disclosure under the Food Allergen Labeling and Consumer Protection Act, while USDA Organic certification and Non-GMO Project verification create tiered market access thresholds that shape formulation investment and price positioning. State-level regulations in California under Proposition 65 add chemical exposure warning requirements that influence ingredient sourcing decisions for national brands. Stakeholders must monitor evolving FDA guidance on added sugars disclosure and protein quality scoring methods that could force label renovations and reformulation cycles.
Market Dynamics
Protein quality scoring methodology under FDA review is forcing reformulation cycles across the United States Energy Bar Market as brands recalibrate amino acid profiles and labeling claims ahead of anticipated regulatory finalization.
Growth Catalysts
- Plant Protein Isolates:Pea and rice protein concentrates are displacing whey in formulations targeting lactose-intolerant athletes and vegan lifestyle adopters across Pacific Northwest retail clusters.
- California Proposition 65 Enforcement:Chemical exposure warning requirements are accelerating clean-label ingredient sourcing decisions among national brands seeking unified formulation strategies.
- Outdoor Recreation Culture:Climbing, cycling, and trail running communities in Colorado and Utah are sustaining repeat purchase velocity for portable, high-density nutrition formats.
Market Restraints
- Organic Supply Concentration:Certified organic ingredient sourcing clusters in California's Central Valley and Pacific Northwest, creating geographic vulnerability to drought and climate disruption.
- Protein Input Volatility:Isolated soy and pea protein prices fluctuate with commodity crop yields and processing capacity constraints at North American extraction facilities.
- Substitute Proliferation:Ready-to-drink protein shakes and functional beverages are capturing meal-replacement occasions previously held by solid bar formats.
Strategic Opportunities
- USDA BioPreferred Program:Biobased packaging mandates for federal procurement channels create preferential access pathways for domestically manufactured bars with certified sustainable wrapping.
- Direct-to-Consumer Subscriptions:Performance-oriented curation platforms are reducing customer acquisition costs while building predictable revenue streams outside conventional retail slotting fee structures.
- Senior Nutrition Segment:Sarcopenia-conscious consumers over 55 represent underdeveloped demand for high-leucine, texture-modified protein bars in assisted living and pharmacy channels.
Industry Challenges
- Dual-Label Inventory Complexity:Simultaneous compliance with legacy and updated FDA Nutrition Facts panels is fragmenting production runs and elevating working capital requirements.
- Co-Manufacturer Capacity Constraints:Cold-press extrusion and baked slab-and-cut processing lines face 12-18 month qualification timelines for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Energy Bar Market |
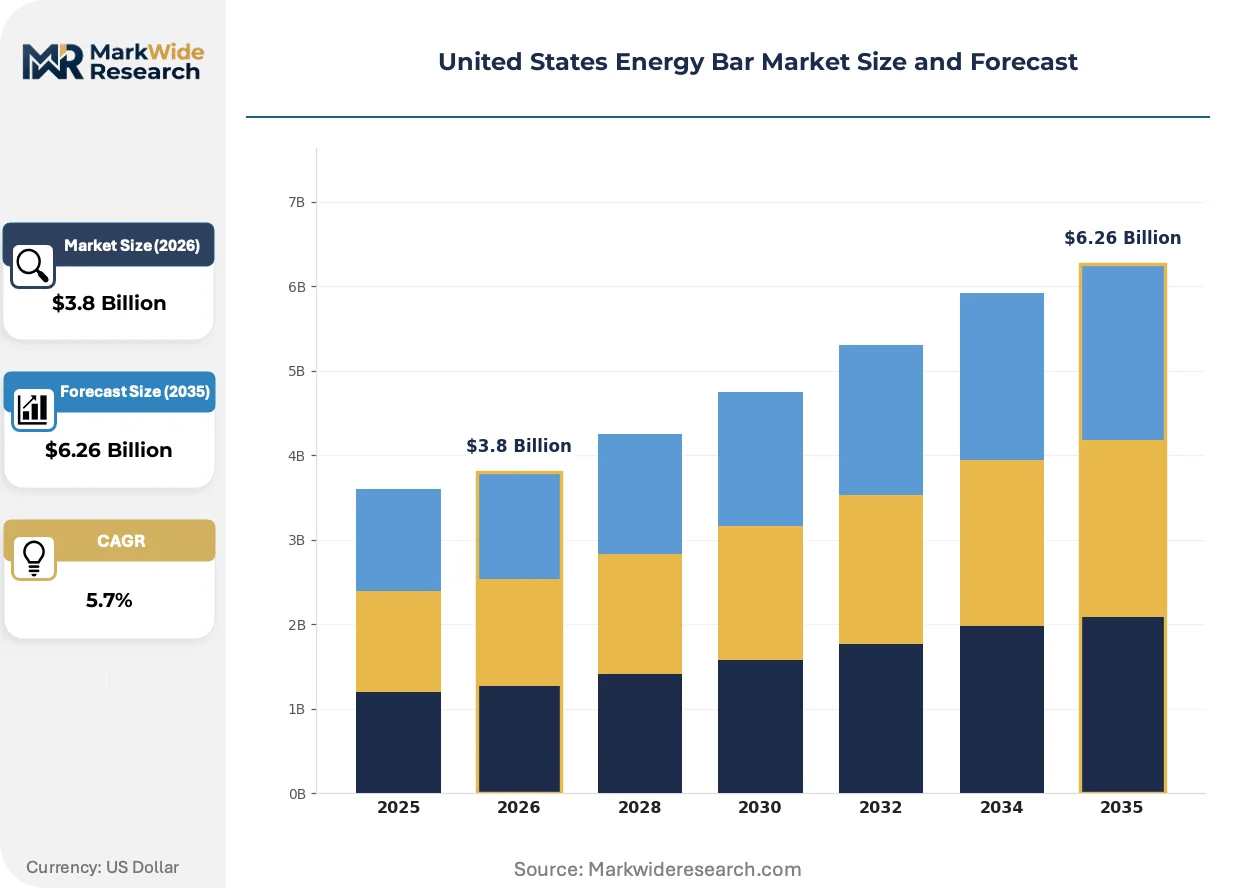
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Bars, Meal Replacement Bars, Nutritional Bars, Snack Bars Ingredient Type: Nuts, Seeds, Grains, Sweeteners Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Shops End User: Athletes, Fitness Enthusiasts, Busy Professionals, Students |
| Companies Covered | Post Holdings Inc., Clif Bar and Co., General Mills Inc., PepsiCo Inc., Nestle SA, Mondelez International Inc., Kellanova, The Hershey Co., Mars Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Energy Bar Market Strategic Shifts
Reformulation priorities are converging on texture optimization and protein bioavailability as brands differentiate within increasingly crowded shelf space. Three developments are restructuring competitive positioning.
Fermentation-derived protein isolates are integrating into premium tier formulations, enabling complete amino acid profiles without allergen-bearing crop inputs. Early adopters in endurance sports nutrition are piloting these ingredients at limited scale. This technology is integrating supply chain resilience by decoupling protein sourcing from agricultural yield volatility.
FDA guidance on added sugars disclosure is compressing formulation flexibility for honey and date-sweetened positioning claims. Manufacturers are responding with monk fruit and allulose blends that maintain sweetness perception while reducing glycemic load callouts. Snack-oriented segments in conventional grocery are most affected, accelerating renovation cycles for existing SKUs.
Subscription-based replenishment models are displacing impulse-driven convenience store purchases among ingredient-discerning buyers. Performance-oriented consumers in metropolitan California and Texas markets are locking into 30-60 day delivery cycles with flavor customization options. This behavioral pivot is concentrating customer lifetime value with direct-to-consumer operators while eroding traditional wholesale velocity.
United States Energy Bar Market Segmentation
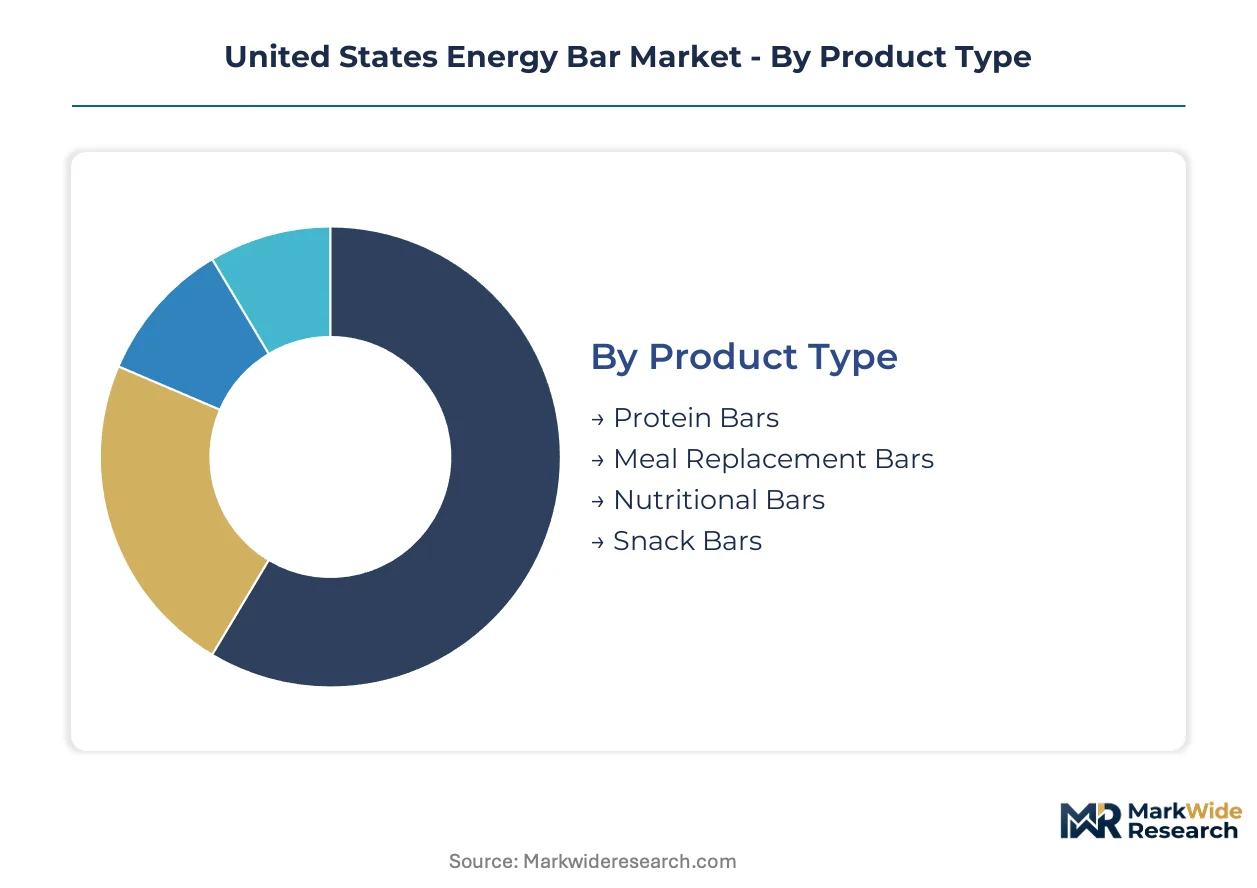
Energy bar purchasing decisions hinge on distinct use-case scenarios that reshape formulation priorities and channel strategies. Manufacturers must calibrate macronutrient profiles, packaging formats, and retail placement against four intersecting dimensions that determine repeat purchase velocity and price realization.
Product Type:
Buyers prioritize functional outcome over brand heritage when selecting bar formats for specific consumption occasions.
- Protein Bars:Formulations delivering 15-25g protein per serving through whey, casein, or plant isolates dominate gym-adjacent retail and direct-to-consumer subscriptions. Demand concentrates among serious athletes and physique-conscious consumers in metropolitan Texas and Florida markets where fitness club density exceeds national averages.
- Meal Replacement Bars:Balanced 300-400 calorie profiles with vitamin fortification and sustained-release carbohydrates target traveling professionals and shift workers seeking portable nutrition completeness. Hospital and airport vending channels in Chicago and Atlanta sustain placement premiums for these formats.
- Nutritional Bars:General wellness positioning with moderate protein and fiber content serves aging consumers managing weight and digestive health. Pharmacy and assisted living procurement in Arizona and Nevada retirement clusters favors these SKUs.
- Snack Bars:Lower-calorie, taste-forward formulations with indulgent flavor profiles drive impulse purchases in convenience stores and conventional grocery checkout lanes. California and New York urban convenience retail generates highest velocity for single-serve formats.
Protein Bars lead on scale; Snack Bars lead on momentum.
Ingredient Type:
Supply geography and allergen sensitivity reshape sourcing economics across formulation tiers.
- Nuts:Almond and cashew bases deliver premium texture and satiety signals in organic and clean-label positioning. California Central Valley orchards supply 80% of domestic almond inputs, creating price linkage to drought cycles and water allocation politics.
- Seeds:Chia, pumpkin, and sunflower inclusions target omega-3 and mineral-conscious buyers seeking alternatives to tree nut allergens. Pacific Northwest contract farming agreements with Montana and North Dakota growers secure organic seed supply chains.
- Grains:Oat and quinoa foundations provide gluten-free carbohydrate bases and soluble fiber claims. Midwest grain processing infrastructure in Minnesota and Iowa concentrates sourcing for national brands.
- Sweeteners:Honey, date paste, and alternative sweetener systems navigate FDA added sugars disclosure requirements. Monk fruit extraction facilities in California's Central Coast region supply clean-label sweetness solutions.
Nuts anchor premium tier pricing; Seeds expand most quickly on allergen-free demand.
Distribution Channel:
Channel selection determines margin structure and customer data access for repeat purchase engineering.
- Supermarkets:Mass-market penetration through conventional grocery chains demands slotting fee investments and promotional velocity commitments. Kroger and Albertsons banner networks in Ohio and Colorado sustain volume concentration for mainstream brands.
- Convenience Stores:Impulse-driven single-serve purchases at 7-Eleven and Circle K locations prioritize grab-and-go packaging and competitive price points. Texas and Florida interstate corridor stores generate highest throughput for snack-oriented formats.
- Online Retail:Direct-to-consumer subscriptions and Amazon marketplace presence enable flavor customization and auto-replenishment models. California and Washington metropolitan consumers lock into 30-60 day delivery cycles with highest retention rates.
- Specialty Shops:REI, Whole Foods, and independent running stores curate performance-oriented assortments with ingredient transparency emphasis. Colorado and Utah outdoor recreation retail clusters sustain premium pricing for technical formulations.
Supermarkets retain volume dominance; Online Retail claims steepest expansion trajectory.
End User:
Demographic-specific consumption rituals drive formulation texture, flavor, and packaging requirements.
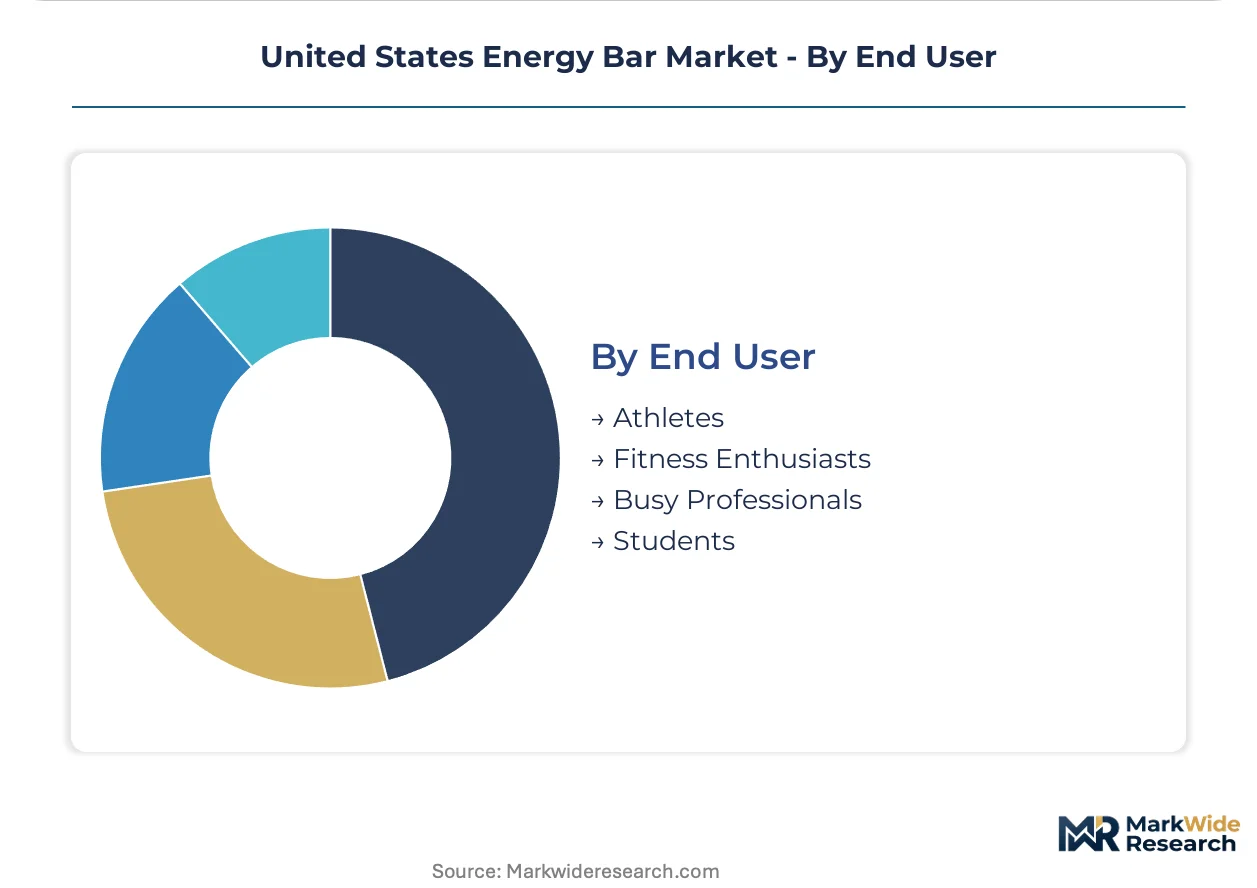
- Athletes:Competitive and recreational endurance athletes prioritize rapid glycogen replenishment and leucine-rich protein for muscle protein synthesis. Triathlon and marathon training communities in Arizona and Colorado sustain repeat purchase for technical sports nutrition formats.
- Fitness Enthusiasts:Gym-regular consumers seeking physique optimization and post-workout recovery drive protein-forward SKU concentration. Boutique fitness studio partnerships in New York and Los Angeles generate trial and subscription conversion.
- Busy Professionals:Time-constrained knowledge workers value meal-gap coverage and cognitive performance claims. Financial and technology sector employment clusters in Boston and Seattle favor premium convenience positioning.
- Students:Price-sensitive younger consumers prioritize value packs and campus retail accessibility. University bookstore and vending contracts in Texas and California public university systems sustain volume for economy-tier formats.
Fitness Enthusiasts concentrate spending power; Busy Professionals gain share fastest on workplace wellness program integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production economics favor states with lower compliance burdens for Proposition 65 chemical warnings and streamlined organic certification pathways, concentrating manufacturing investment away from high-regulation coastal corridors toward interior processing hubs.
California
Outdoor recreation culture and health-conscious urban consumers drive premium-tier demand in San Francisco and Los Angeles metropolitan clusters. FDA Nutrition Facts labeling renovations and Proposition 65 enforcement accelerate clean-label sourcing decisions among brands seeking unified national formulations. The Central Valley anchors almond and monk fruit supply chains that feed organic bar production lines.
Texas
Fitness club density exceeding national averages sustains protein-forward SKU velocity in Houston and Dallas-Fort Worth retail networks. State-level business climate incentives attract co-manufacturing capacity from brands seeking to escape California regulatory costs. Interstate corridor convenience stores generate highest throughput for single-serve snack-oriented formats.
Colorado
Endurance sports communities in Boulder and Denver sustain repeat purchase velocity for technical sports nutrition formats. USDA Organic certification requirements shape ingredient sourcing for brands targeting mountain west outdoor retail channels. Climbing and trail running culture concentrates demand for portable high-density nutrition in specialty outdoor shops.
Pacific Northwest
Plant-based protein adoption rates exceed national benchmarks in Seattle and Portland metropolitan areas. Contract farming agreements with Montana and North Dakota growers secure organic seed supply chains for allergen-free formulations. Cold-press extrusion processing infrastructure concentrates near Portland for brands serving vegan lifestyle adopters.
Florida
Retirement cluster demographics in Tampa and Miami sustain pharmacy-channel demand for nutritional bars targeting sarcopenia-conscious seniors. Fitness enthusiast density drives gym-adjacent retail placement for protein-forward formats. Interstate convenience retail generates impulse-driven volume for lower-calorie snack-oriented SKUs.
United States Energy Bar Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with portfolio conglomerates dominating mainstream retail velocity while heritage outdoor brands anchor premium-tier positioning. Market structure tilts toward consolidated control at the mass-market tier and fragmented specialization in performance-oriented niches. Three archetypes define competitive posture: diversified food conglomerates with bar portfolios, heritage outdoor nutrition specialists, and private-label contract manufacturers serving retail banners. Capacity expansion and portfolio diversification represent the dominant competitive moves as players seek to capture subscription-channel growth and senior nutrition whitespace.
Within the heritage outdoor nutrition tier, Clif Bar and Co. exemplifies brand authenticity built through cycling and climbing community engagement. Post Holdings Inc. occupies a position among protein-forward specialists targeting serious athletes and gym-based consumers. General Mills Inc. anchors the diversified conglomerate archetype with mainstream retail penetration spanning nutritional to snack-oriented bar formats.
| Leading Market Players |
|---|
| Post Holdings Inc. |
| Clif Bar and Co. |
| General Mills Inc. |
| PepsiCo Inc. |
| Nestle SA |
| Mondelez International Inc. |
| Kellanova |
| The Hershey Co. |
| Mars Incorporated |
| Others |
Value Chain & Pricing Dynamics
Fitness enthusiast procurement preferences for subscription-based replenishment are forcing manufacturers to restructure channel economics and absorb fulfillment costs that compress headline pricing power across conventional retail tiers.
Pricing Analysis
Retailer markup layers in conventional grocery and convenience channels absorb 35-45 points of manufacturer landed cost, while direct-to-consumer subscriptions bypass slotting fees and trade promotion accruals entirely. Three-tier pricing structure across premium, standard, and economy levels separates USDA Organic-certified formulations with Non-GMO Project verification from conventional ingredient bars and private-label economy SKUs. Pricing pressure stems from co-manufacturer capacity constraints that extend new product introduction timelines and elevate minimum order quantities. Students and campus retail buyers exhibit highest price sensitivity, while endurance athletes in specialty outdoor channels accept premium positioning for technical sports nutrition formats.
Supply Chain Analysis
Regional distribution centers in Texas and Ohio execute hub-and-spoke patterns that reach convenience store networks and supermarket banners with 3-5 day replenishment cycles. Protein isolate supply concentrates in Minnesota and Iowa processing infrastructure for whey and casein fractions, while organic almond and monk fruit inputs draw from California Central Valley orchards and Central Coast extraction facilities. Single-source vulnerability runs through Pacific Northwest cold-press extrusion co-manufacturers serving vegan and allergen-free formulation demand. Distribution runs through direct-to-consumer fulfillment centers in Nevada and Tennessee that bypass wholesale intermediaries for subscription-channel velocity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Energy Bar Market represents a late-cycle quality story as ingredient-discerning buyers migrate toward fermentation-derived protein isolates and biobased packaging certifications that command sustainable price premiums.
For Market Incumbents: To counter ready-to-drink protein shake substitution threats, anchor market position through backward integration into organic almond supply chains in California Central Valley and captive pea protein processing capacity in Midwest grain corridors. Prioritize USDA BioPreferred program certification to secure federal procurement channel access and defend shelf space against private-label encroachment. For New Entrants and Emerging Players: The gap between premium organic positioning and economy-tier private-label pricing creates entry space for mid-tier brands emphasizing clean-label transparency without full certification cost burdens. Target senior nutrition segments in Florida and Arizona retirement clusters with texture-modified, high-leucine formulations distributed through pharmacy and assisted living procurement channels. Pursue boutique fitness studio partnerships in New York and Los Angeles for trial conversion and subscription platform buildout. For Investors and Strategic Acquirers: Asymmetric upside sits with direct-to-consumer operators possessing proprietary subscription technology and flavor customization infrastructure. Five-to-ten year viability hinges on decoupling from agricultural yield volatility through fermentation-derived protein investments. Monitor FDA protein quality scoring finalization as inflection indicator for reformulation cycle intensity and working capital demands across portfolio holdings.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Platform | Bypasses slotting fees and builds predictable revenue streams outside conventional retail economics. |
| Fermentation-Derived Protein Integration | Decouples supply from agricultural volatility while enabling complete amino acid profiles without allergen inputs. |
| USDA BioPreferred Packaging Certification | Unlocks federal procurement preferential access and differentiates sustainability positioning for premium tiers. |
| Senior Nutrition Segment Development | Captures sarcopenia-conscious demand in pharmacy and assisted living channels with texture-modified formats. |
| Co-Manufacturer Capacity Expansion | Reduces 12-18 month qualification timelines and secures production allocation for new product velocity. |
Study Parameters
Multiple input streams — executive interviews with brand managers and category buyers, supply chain consultations with co-manufacturing operations heads, and regulatory discussions with FDA compliance officers — were reconciled against secondary validation from Nielsen retail audit data, USDA organic certification databases, and SEC 10-K filings from diversified food conglomerates. Bottom-up SKU-level demand modeling and top-down category expenditure analysis were cross-referenced to establish volume and value baselines.
Historical shipment data was cross-referenced against expert panel inputs covering protein isolate sourcing economics and channel migration patterns. Segmentation dimensions modeled include product type, ingredient certification tier, distribution channel, and end-user demographic across the projection horizon. CAGRs were derived from trend extrapolation adjusted for regulatory intervention probability and substitution elasticity estimates from functional beverage competitive dynamics.
Caveats apply where FDA protein quality scoring finalization, California Proposition 65 enforcement expansion, or climate disruption in Central Valley almond production could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Low-Fat Tortillas Market
Snacks
Qatar Potato Chips Market
Snacks
Poland Snack Bar Market
Snacks
Extruded Snacks Market
Snacks
Meat Protein Chips Market
Snacks
South America Cereal Bar Market
Snacks
Grass-Fed Jerkies Market
Snacks
North America Potato Chips Market
Snacks
Roasted Snacks Market
Snacks
Fiber Bars Market
Snacks
France Energy Bar Market
Snacks
Low Fat Crackers Market
Snacks
Global Vegetable Chips Market
Snacks
Nuts and Seeds (Savory Snacks) Market
Snacks
Low-Calorie Savoury Snacks Market
Snacks
Granola Bars Market