
 Spain Courier, Express, and Parcel (CEP) Market | 2026-2036
Spain Courier, Express, and Parcel (CEP) Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Courier, Express, and Parcel (CEP) Market Insights
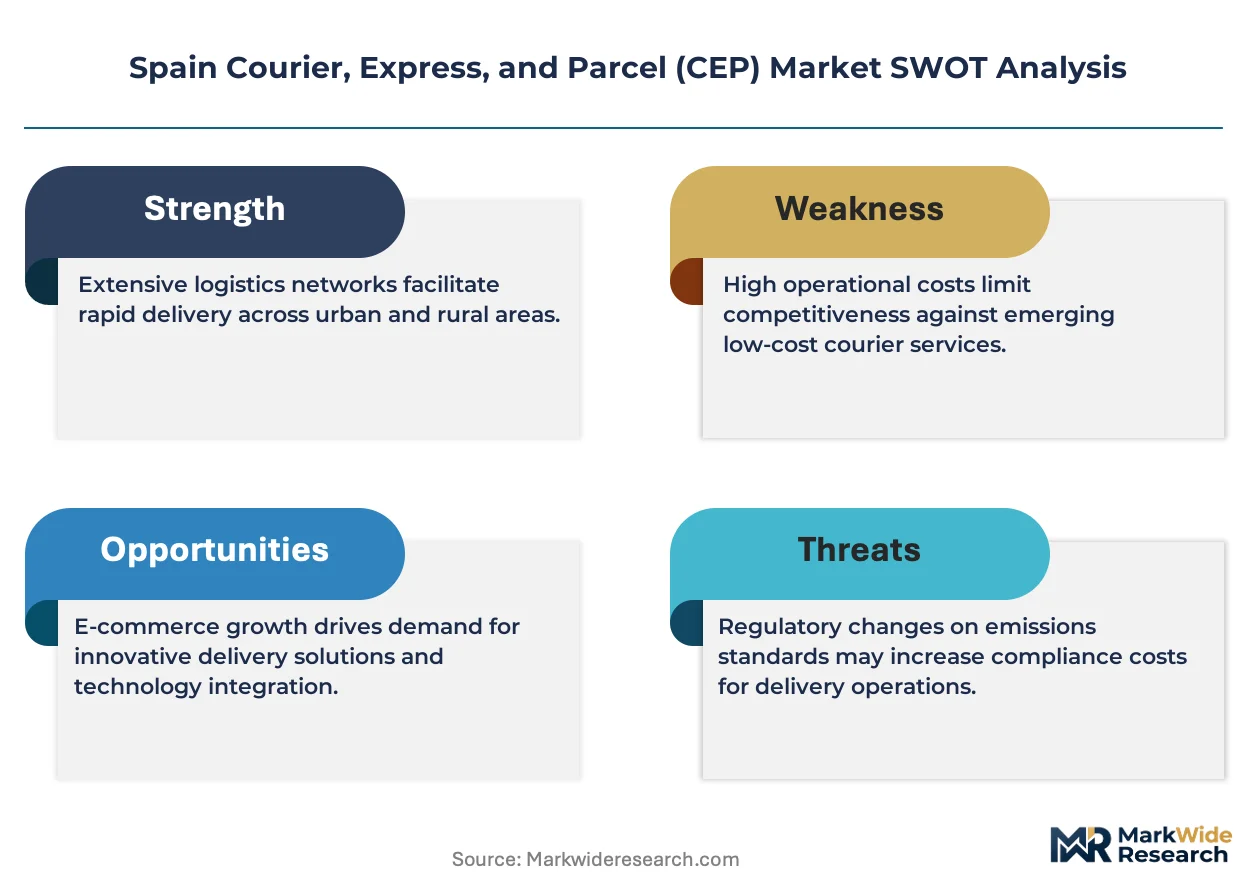
Delivery driver shortages across the Iberian Peninsula is reorganizing how operators allocate last-mile capacity and retain warehouse staff. Correos Express leverages its postal heritage to sustain dense rural coverage networks that competitors struggle to replicate. SEUR anchors its position through temperature-controlled infrastructure for pharmaceutical and perishable segments. MRW competes aggressively on time-definite business-to-business lanes between industrial clusters.
Courier, Express, and Parcel services encompass time-sensitive collection, sorting, transportation, and delivery of documents and packages weighing from envelopes to palletized freight, utilizing hub-and-spoke networks with automated sortation and GPS-tracked vehicles. The primary commercial purpose is enabling just-inventory replenishment and direct-to-consumer fulfillment across manufacturing, retail, and healthcare supply chains. Same-day and next-day delivery types are capturing premium margin pools as e-commerce fulfillment expectations tighten, while economy services face volume pressure from cross-border postal alternatives. Domestic service types dominate revenue tonnage, though international freight segments are expanding fastest through Barcelona and Valencia gateway operations.
Spain's Directorate General of Traffic enforces driving hour limits and vehicle emission standards that directly constrain fleet utilization and capital deployment timelines for delivery operators. The Spanish Data Protection Agency imposes parcel tracking and customer data handling protocols that shape technology investment priorities across the sector. The National Commission on Markets and Competition monitors access terms for postal infrastructure, influencing interconnection pricing between incumbent and challenger networks. Stakeholders must monitor how Madrid's low-emission zone expansions and autonomous vehicle pilot programs will reshape depot location strategies and labor deployment models.
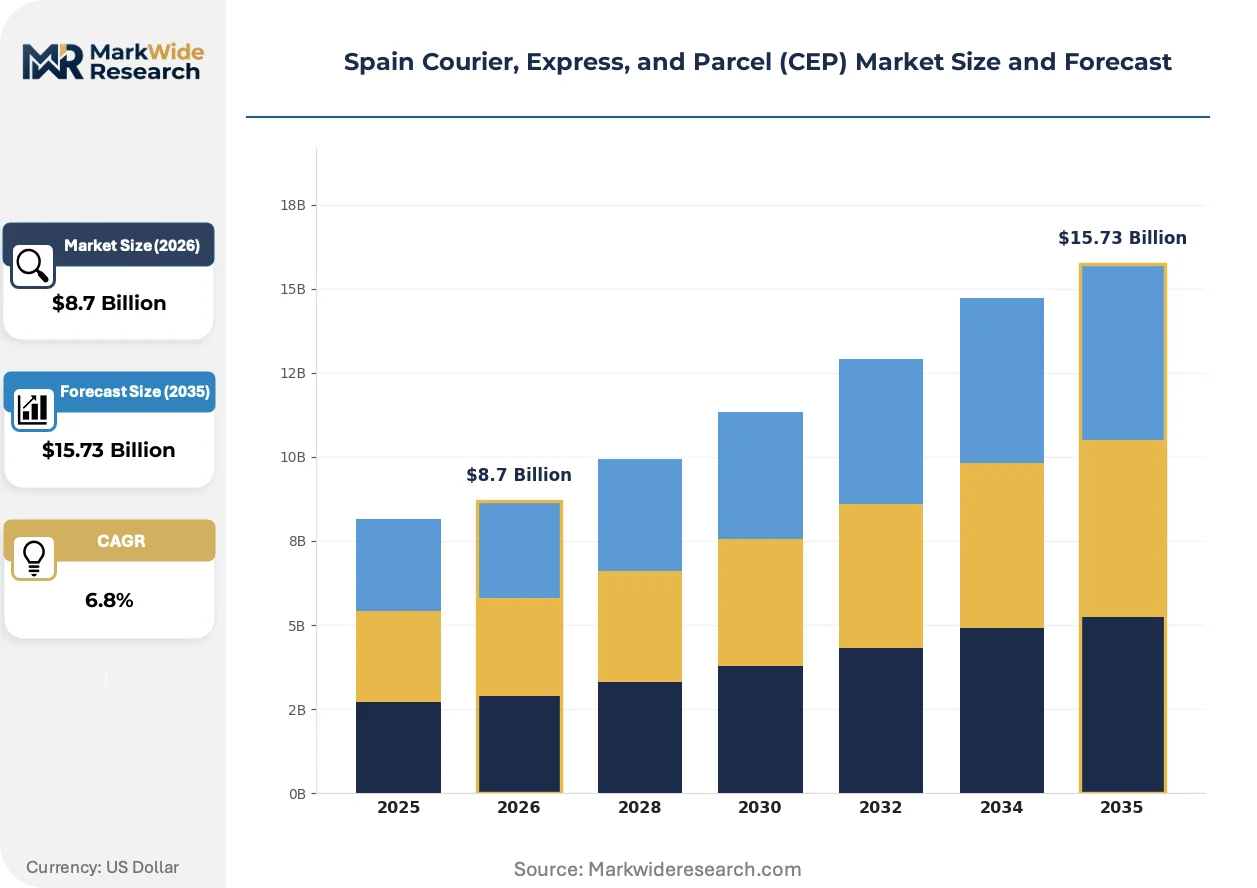
Market Dynamics
Fleet electrification mandates under Spain's Sustainable Mobility Law are forcing depot operators to reconfigure capital deployment timelines and last-mile capacity planning across Iberian logistics corridors.
Growth Catalysts
- E-commerce fulfillment tightening:Same-day delivery expectations from fashion and electronics retailers are pulling volume into express networks and away from economy postal alternatives.
- Port-linked distribution zones:Valencia's container terminal expansion is creating dedicated customs clearance infrastructure that accelerates cross-border parcel throughput into Mediterranean markets.
- Temperature-controlled infrastructure:Pharmaceutical cold chain requirements are expanding dedicated fleet investment and specialized handling capacity across the Madrid-Barcelona corridor.
Market Restraints
- Driver hour limits:Spain's Directorate General of Traffic enforces strict driving time regulations that cap fleet utilization rates and compress route optimization margins.
- Emission zone friction:Madrid's low-emission zone expansions require premature vehicle retirement and accelerate depreciation schedules for diesel-powered last-mile fleets.
- Data handling protocols:The Spanish Data Protection Agency imposes parcel tracking compliance costs that constrain technology vendor selection and integration timelines.
Strategic Opportunities
- Rural coverage gaps:Dense postal heritage networks in Castile-La Mancha and Extremadura remain undercontested by challenger operators focused on urban corridors.
- Autonomous vehicle pilots:Madrid's regulatory sandbox for driverless depot-to-depot freight movement is creating first-mover positioning for hub-and-spoke automation.
- Cross-border postal alternatives:Economy service pressure from Iberian postal networks is opening white space for premium time-definite positioning on Portugal-Spain lanes.
Industry Challenges
- Sortation automation capex:Hub modernization requires eight-figure capital commitments that strain mid-tier operators competing against incumbent scale advantages.
- Interconnection pricing disputes:The National Commission on Markets and Competition's postal infrastructure access rulings create uncertainty in network cost allocation between carriers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Courier, Express, and Parcel (CEP) Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Type: Same-Day, Next-Day, Scheduled, Economy Service Type: Domestic, International, Freight, Returns End User: Retailers, E-commerce, Corporates, Individuals Package Size: Small, Medium, Large, Oversized |
| Companies Covered | Correos Express, SEUR, MRW, DHL Group, NACEX, CTT Express, UPS, FedEx, GLS Spain, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Courier, Express, and Parcel (CEP) Market Trends and Innovations
Electrification, automation, and delivery expectation compression are restructuring how Spanish CEP operators deploy fleet assets and price service tiers across domestic and cross-border lanes.
Electric van fleets are displacing diesel last-mile vehicles in Madrid and Barcelona urban zones. Retailers with sustainability mandates are specifying zero-emission delivery windows for their fulfillment contracts. This transition is compressing total cost of ownership calculations and accelerating residual value risk for conventional fleet operators.
Spain's Sustainable Mobility Law mandates progressive fleet electrification percentages that tighten through 2030. Logistics operators must front-load capital expenditure into charging infrastructure and vehicle procurement ahead of revenue-neutral payback periods. The Madrid metropolitan delivery zone faces the steepest compliance trajectory and is driving early consolidation of depot electrification planning.
Buyer consolidation among large e-commerce marketplaces is compressing switching costs and intensifying rate negotiation leverage. Long-term fulfillment contracts with volume guarantees are displacing spot-market parcel movements for high-frequency shippers. This pattern concentrates revenue risk with a handful of retail platforms and is most visible in Catalonia's dense e-commerce fulfillment cluster.
Spain Courier, Express, and Parcel (CEP) Market Segmentation
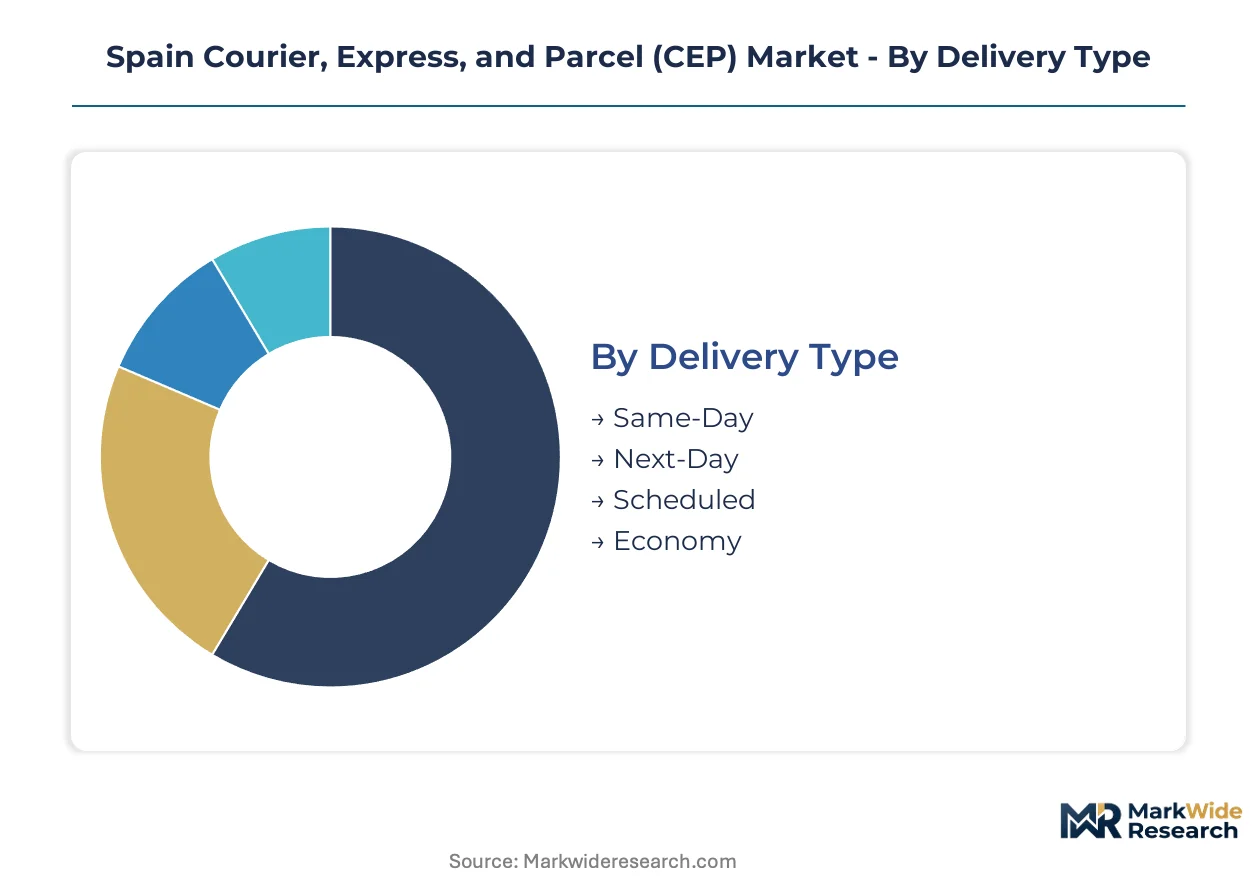
Spanish CEP operators route volume through distinct channel configurations that determine fleet deployment, depot placement, and margin capture. Each segmentation dimension reveals where infrastructure investments concentrate and which customer contracts command pricing power.
Delivery Type:
Channel-mix dynamics separate premium fulfillment windows from postal alternatives, with express networks capturing fashion and electronics contracts while economy flows through consolidated postal infrastructure.
- Same-Day:Ultra-time-critical service utilizing dedicated urban van pools and micro-fulfillment depots positioned within Madrid and Barcelona metropolitan radii. Fashion retailers and pharmacy chains in Catalonia's dense e-commerce cluster are pulling volume into this tier as consumer tolerance for waiting collapses.
- Next-Day:Hub-and-spoke overnight sortation with guaranteed morning delivery windows. Industrial suppliers along the Madrid-Barcelona corridor rely on this tier for just-inventory replenishment, though driver hour limits from Spain's Directorate General of Traffic constrain route density.
- Scheduled:Pre-arranged delivery slots with recipient-specified timing. Corporate document flows and healthcare specimen transport in Valencia's port-linked distribution zones favor this predictability.
- Economy:Consolidated deferred delivery utilizing postal infrastructure and interconnection pricing. Cross-border postal alternatives pressure margins here, particularly on Portugal-Spain lanes.
By volume, Economy leads. By growth pace, Same-Day is climbing the fastest.
Service Type:
Cost tier stratification separates asset-heavy domestic networks from gateway-dependent international operations requiring customs clearance specialization.
- Domestic:National hub-and-spoke coverage with dense last-mile penetration into Castile-La Mancha and Extremadura rural zones. Correos Express leverages postal heritage infrastructure that challengers struggle to replicate profitably.
- International:Cross-border freight utilizing Barcelona and Valencia gateway operations with dedicated customs infrastructure. Container terminal expansion at Valencia is accelerating Mediterranean market throughput.
- Freight:Palletized and non-conveyable shipments requiring specialized handling equipment. MRW competes aggressively on time-definite B2B lanes between Spanish industrial clusters.
- Returns:Reverse logistics processing including inspection, refurbishment, and restocking. E-commerce marketplace consolidation is tightening returns volume concentration with a handful of retail platforms.
Domestic commands the revenue base. International freight is gaining share fastest.
End User:
Application-specific requirements dictate temperature control, proof-of-delivery protocols, and contract structure across customer categories.
- Retailers:Omnichannel fulfillment integrating store inventory with home delivery promises. Sustainability mandates are specifying zero-emission delivery windows for contract awards.
- E-commerce:Direct-to-consumer parcel flows with extreme delivery expectation compression. Buyer consolidation among large marketplaces is intensifying rate negotiation leverage and displacing spot-market movements.
- Corporates:B2B document and specimen transport with compliance documentation requirements. Pharmaceutical cold chain needs are expanding dedicated fleet investment.
- Individuals:Intermittent shipper demand with high acquisition cost and low loyalty. This segment flows predominantly through postal retail access points and locker networks.
E-commerce dominates volume contribution. Corporate pharmaceutical logistics shows the steepest expansion trajectory.
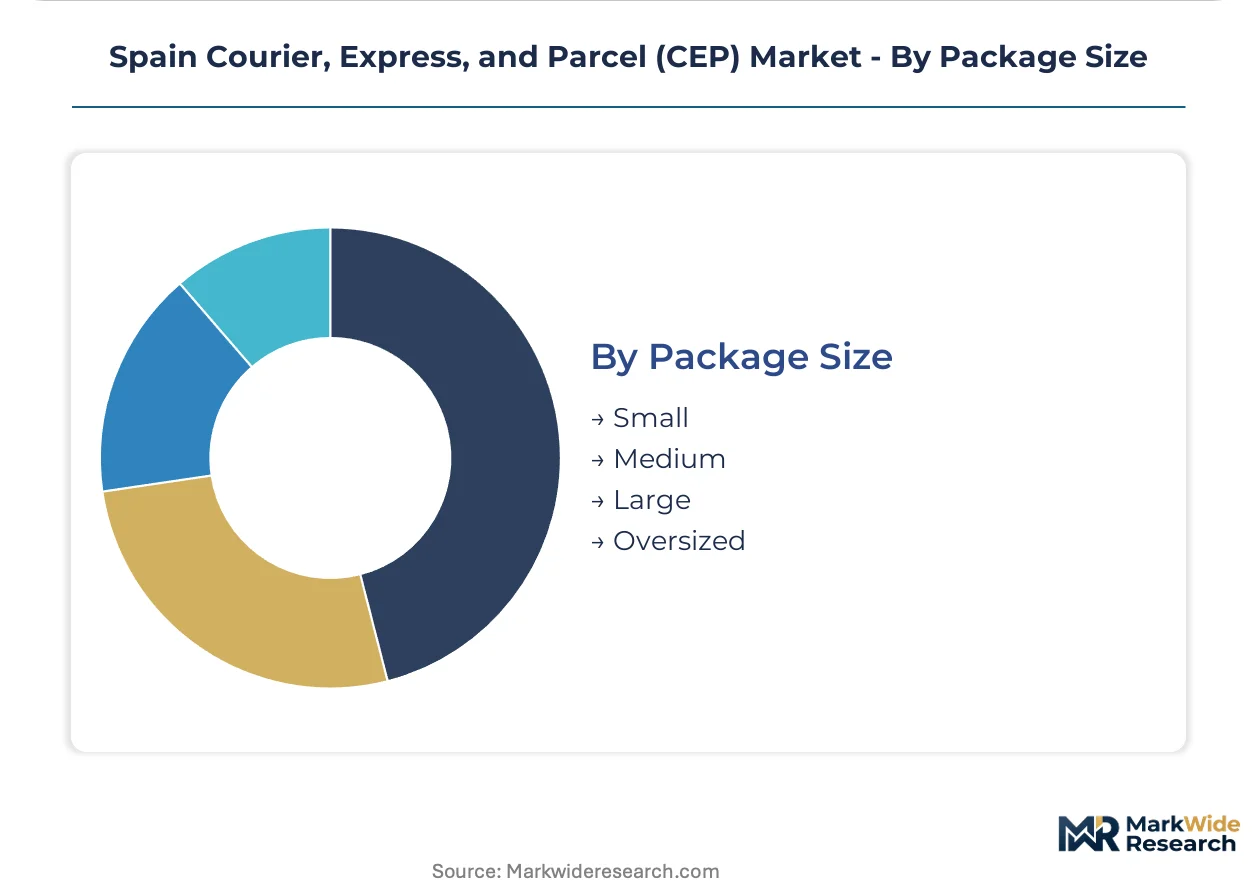
Package Size:
Volume-to-value ratios determine sortation automation requirements and vehicle fleet composition across handling categories.
- Small:Envelope and small parcel formats compatible with automated sortation and standard van loading. Electronics and fashion items in Catalonia's fulfillment cluster drive density here.
- Medium:Standard parcel dimensions representing the conveyor-compatible sweet spot for hub automation. This tier captures the bulk of residential e-commerce volume.
- Large:Non-conveyable items requiring manual handling and specialized vehicle configurations. Furniture and appliance retailers are expanding this category through home delivery promises.
- Oversized:Palletized freight and bulky items demanding flatbed or box truck deployment. Industrial equipment and construction materials move through this tier with dedicated fleet allocation.
Medium parcels anchor volume throughput. Large format is expanding most quickly as furniture e-commerce penetrates Spanish households.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's Directorate General of Traffic anchors regulatory enforcement across Iberian logistics corridors, with regional delivery markets differentiating by industrial density, port access, and rural penetration challenges.
Madrid
E-commerce fulfillment centers and pharmaceutical distribution hubs concentrate demand in the capital region. The city's low-emission zone expansions enforce premature diesel fleet retirement and accelerate depot electrification timelines. Madrid-Barcelona corridor traffic anchors national express volume, with automated sortation investments clustering in Alcalá de Henares logistics parks.
Catalonia
Fashion and electronics retailers in Barcelona's dense e-commerce cluster pull same-day delivery volume into premium service tiers. The Catalan regional government aligns with Spain's Sustainable Mobility Law on urban freight restrictions. Temperature-controlled infrastructure for pharmaceutical cold chains concentrates along the Mediterranean corridor toward Tarragona.
Valencia
Container terminal expansion at Valencia's port creates dedicated customs clearance infrastructure for Mediterranean cross-border throughput. The national port authority's investment program accelerates parcel processing capacity for international freight segments. Port-linked distribution zones in Sagunto and Paterna anchor gateway operations for North African and Italian markets.
Andalusia
Seville and Málaga logistics corridors face rural coverage gaps in interior provinces where postal heritage networks retain advantage. Regional climate conditions stress fleet air conditioning loads during peak summer delivery windows. The Junta de Andalucía's sustainable transport initiatives parallel national electrification mandates for urban last-mile operations.
Basque Country
Industrial B2B lanes between Bilbao, San Sebastián, and Vitoria-Gasteiz demand time-definite freight services for manufacturing supply chains. The Basque government's advanced manufacturing support programs indirectly shape logistics requirements for precision components. Port of Bilbao activity links to French border crossings for cross-border postal alternatives.
Spain Courier, Express, and Parcel (CEP) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Spanish CEP sector. The market structure tiers between incumbent postal heritage operators with rural density and international integrators with automated hub networks. Three strategic archetypes dominate: national postal express hybrids, global integrators with gateway specialization, and regional B2B specialists. Competitive moves concentrate on fleet electrification partnerships and last-mile automation pilots.
Within the postal heritage tier, Correos Express anchors national coverage density that challengers struggle to replicate profitably. SEUR and MRW occupy positions on opposite ends of service specialization—temperature-controlled pharmaceutical infrastructure versus aggressive time-definite B2B lane competition. These three Spanish-origin operators exemplify how domestic market knowledge and regulatory navigation create defensive positioning against global integrator expansion.
| Leading Market Players |
|---|
| Correos Express |
| SEUR |
| MRW |
| DHL Group |
| NACEX |
| CTT Express |
| UPS |
| FedEx |
| GLS Spain |
| Others |
Pricing and Supply Chain Analysis
Long-term fulfillment contracts with volume guarantees lock in both depot capacity access and price visibility for e-commerce retailers operating across the Madrid-Barcelona corridor. Spain's Sustainable Mobility Law tightens fleet electrification mandates that compress total cost of ownership calculations and accelerate residual value risk for diesel-dependent operators.
Pricing Analysis
Madrid-Barcelona corridor rates command premiums over peripheral routes due to density advantages and driver hour constraints from Spain's Directorate General of Traffic. Three-tier pricing structure across premium, standard, and economy levels separates same-day pharmaceutical deliveries from deferred postal alternatives. Price differentiation rests on delivery speed windows and temperature-control certification tiers. Pricing pressure stems from buyer consolidation among large e-commerce marketplaces that intensify rate negotiation leverage. Small retailers show highest price sensitivity, while pharmaceutical distributors accept premium tiers for cold-chain compliance.
Supply Chain Analysis
Just-in-time inventory replenishment dominates industrial B2B lanes, though pharmaceutical distributors maintain strategic stockpiles for temperature-sensitive products. Vehicle manufacturing concentrates in Germany, China, and Japan, with electric van fleets sourcing battery cells from South Korean and Chinese suppliers. Hub automation equipment draws from German and Japanese industrial technology providers. Supply chain risk centers on semiconductor availability for sortation systems and GPS tracking hardware. Distribution runs through hub-and-spoke networks anchored at Alcalá de Henares logistics parks and Valencia port-linked zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's CEP sector sits in early-cycle expansion as e-commerce fulfillment expectations compress delivery windows and pull volume from postal alternatives into express networks.
For Market Incumbents: Fortify rural coverage density in Castile-La Mancha and Extremadura where postal heritage infrastructure creates defensible moats against urban-focused challengers. Accelerate fleet electrification partnerships ahead of Madrid's low-emission zone expansions to preempt competitor positioning. Invest in temperature-controlled depot infrastructure along the Mediterranean corridor to capture pharmaceutical cold chain growth.
For New Entrants and Emerging Players: Rural last-mile service gaps in Andalusia's interior provinces present white-space opportunities where Correos Express retains near-monopoly positioning. Target scheduled delivery slots for corporate document and healthcare specimen transport in Valencia's port-linked distribution zones. Pursue autonomous vehicle pilot partnerships under Madrid's regulatory sandbox to establish hub-and-spoke automation credentials before infrastructure access terms harden.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among operators with long-term e-commerce fulfillment contracts and pharmaceutical logistics certifications. Long-term viability favors mid-tier specialists with temperature-controlled infrastructure or dense rural networks over undifferentiated regional players. Monitor autonomous vehicle pilot program outcomes as inflection indicator for labor cost structure transformation.
| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Partnership | Spain's Sustainable Mobility Law mandates progressive zero-emission percentages through 2030. |
| Temperature-Controlled Depot Expansion | Pharmaceutical cold chain requirements concentrate investment along the Madrid-Barcelona corridor. |
| Autonomous Vehicle Pilot Program | Madrid's regulatory sandbox enables first-mover positioning in depot-to-depot freight automation. |
| Rural Network Densification | Castile-La Mancha and Extremadura coverage gaps remain undercontested by urban-focused operators. |
| Cross-Border Gateway Capacity | Valencia container terminal expansion accelerates Mediterranean parcel throughput into North African markets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs records, Directorate General of Traffic enforcement data, and National Commission on Markets and Competition rulings. Interviews with logistics depot managers, e-commerce fulfillment directors, pharmaceutical supply chain leads, and fleet procurement officers inform operational cost structures and contract terms. Secondary validation draws from Spain's Sustainable Mobility Law implementation schedules, port authority investment disclosures, and EU postal directive compliance reports. Bottom-up volume modeling triangulates against top-down market sizing from carrier capacity announcements.
Segmentation dimensions modeled include delivery type, service type, end-user category, and package size across the projection horizon. CAGRs derive from trend extrapolation of e-commerce penetration rates, fleet electrification cost curves, and pharmaceutical logistics growth patterns. Forecast inputs incorporate Madrid low-emission zone expansion timelines, Valencia port capacity additions, and autonomous vehicle pilot program scaling assumptions.
Underlying assumptions cover regulatory compliance trajectories and e-commerce volume retention, with deviation risk concentrated in driver shortage severity and battery supply chain constraints. Revision becomes warranted when electrification cost parity thresholds cross ahead of or behind modeled timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
India Contract Logistics Market
Logistics and Shipping
Nordics Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
US Express Delivery Market
Logistics and Shipping
South Korea Third-Party Logistics (3PL) Market
Logistics and Shipping
Bangladesh Contract Logistics Market
Logistics and Shipping
Netherlands Last Mile Delivery Market
Logistics and Shipping
Inbound Logistics Market
Logistics and Shipping
GCC Finished Vehicle Logistics Market
Logistics and Shipping
Mexico Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Romania Freight and Logistics Market
Logistics and Shipping
Latin America Freight Forwarding Market
Logistics and Shipping
Sweden Cold Chain Logistics Market
Logistics and Shipping
Shipping Container Modification Market
Logistics and Shipping
Remanufacturing and Core Returns Logistics Management Market
Logistics and Shipping
Military Logistics Market
Logistics and Shipping
Logistics Automation Market