
 GCC Finished Vehicle Logistics Market | 2026-2036
GCC Finished Vehicle Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Finished Vehicle Logistics Market Foresight
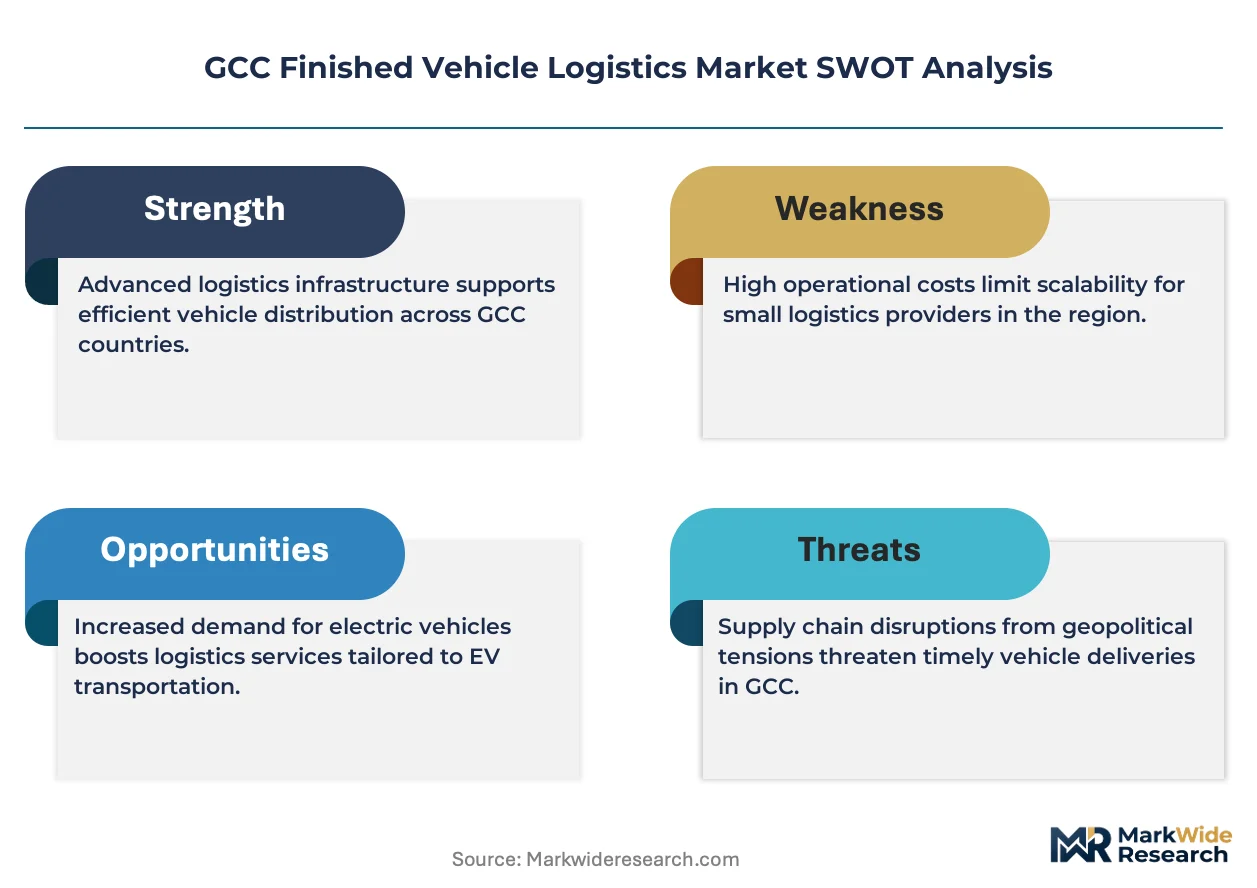
Buyer concentration among fleet operators and rental companies is shifting as Saudi Arabia's Public Investment Fund-backed mobility ventures consolidate procurement volumes. Almajdouie Logistics leverages its dedicated vehicle processing facilities in Dammam to anchor East Coast distribution. GEFCO competes through European-origin quality systems adapted to GCC temperature extremes. DB Schenker extends its rail-integrated multimodal footprint across the UAE-Saudi corridor.
Finished vehicle logistics encompasses the specialized handling, storage, and movement of automobiles from manufacturing endpoints or import ports to final delivery locations, requiring climate-controlled warehousing with ambient temperatures maintained below 45°C and humidity monitoring to preserve paint integrity and electronic systems. The primary purpose centers on minimizing transit damage while synchronizing inventory flows with dealership sales cycles. Transportation services dominate value capture given the region's port-to-inland distances exceeding 800 kilometers on major corridors. Electric vehicle handling represents the fastest-growing vehicle type segment, necessitating battery state-of-charge monitoring and hazardous-material protocols during vessel stowage. Warehousing for SUVs sustains premium pricing due to specialized racking height requirements and longer average dwell times.
Saudi Standards, Metrology and Quality Organization (SASO) technical regulations govern vehicle import conformity, while UAE's Ministry of Economy enforces consumer protection standards affecting warranty logistics obligations. The Saudi Customs Authority and Dubai Customs both mandate pre-arrival documentation that shapes clearance velocity and port storage economics. Stakeholders must monitor how Saudi Vision 2030 localization targets will reshape import-source patterns and corresponding logistics infrastructure investments.
Market Dynamics
Saudi Vision 2030 industrial localization mandates are forcing finished vehicle logistics providers to reconfigure port-to-inland distribution networks around domestic assembly capacity rather than pure import throughput.
Growth Catalysts
- Battery Electric Vehicle Handling Protocols:Specialized hazardous-material stowage and state-of-charge monitoring requirements are creating dedicated service tiers for EV imports through Jeddah's King Abdullah Port.
- SASO Technical Conformity Mandates:Saudi Standards, Metrology and Quality Organization pre-arrival documentation rules are accelerating digital customs integration investments by port operators.
- East Coast Industrial Clustering:Dammam's dedicated vehicle processing terminals are capturing rising transshipment volumes as Saudi Arabia expands domestic automotive assembly.
Market Restraints
- Extreme Temperature Infrastructure Costs:Climate-controlled warehousing requiring sub-45°C ambient maintenance consumes 23-31% of facility operating budgets across UAE and Saudi Arabia.
- Port Concentration Risk:Over 70% of GCC finished vehicle import volume funnels through Jebel Ali and King Abdullah Port, creating single-point-of-failure exposure during peak seasonal surges.
- Limited Rail Gauge Standardization:Disconnected Saudi and UAE rail networks force multimodal transfers at border zones, adding 18-24 hours to UAE-Saudi corridor transit times.
Strategic Opportunities
- Kuwait and Bahrain Market Penetration:Underdeveloped dedicated vehicle processing infrastructure in these markets offers first-mover terminal construction opportunities for regional operators.
- Rail-Seaport Integration:Etihad Rail's expanding freight network is enabling direct port-to-inland depot services bypassing congested highway corridors.
- Digital Twin Deployment:Real-time yard management systems combining IoT vehicle tracking with predictive dwell-time analytics are compressing inventory carrying costs for SUV-heavy stockpiles.
Industry Challenges
- EV-Specific Technician Certification:Battery handling and high-voltage safety credentials remain scarce across GCC logistics workforces, delaying service line expansion.
- Legacy Yard Management System Integration:Proprietary port community systems at King Abdulaziz Port Dammam resist API connectivity with third-party logistics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Finished Vehicle Logistics Market |
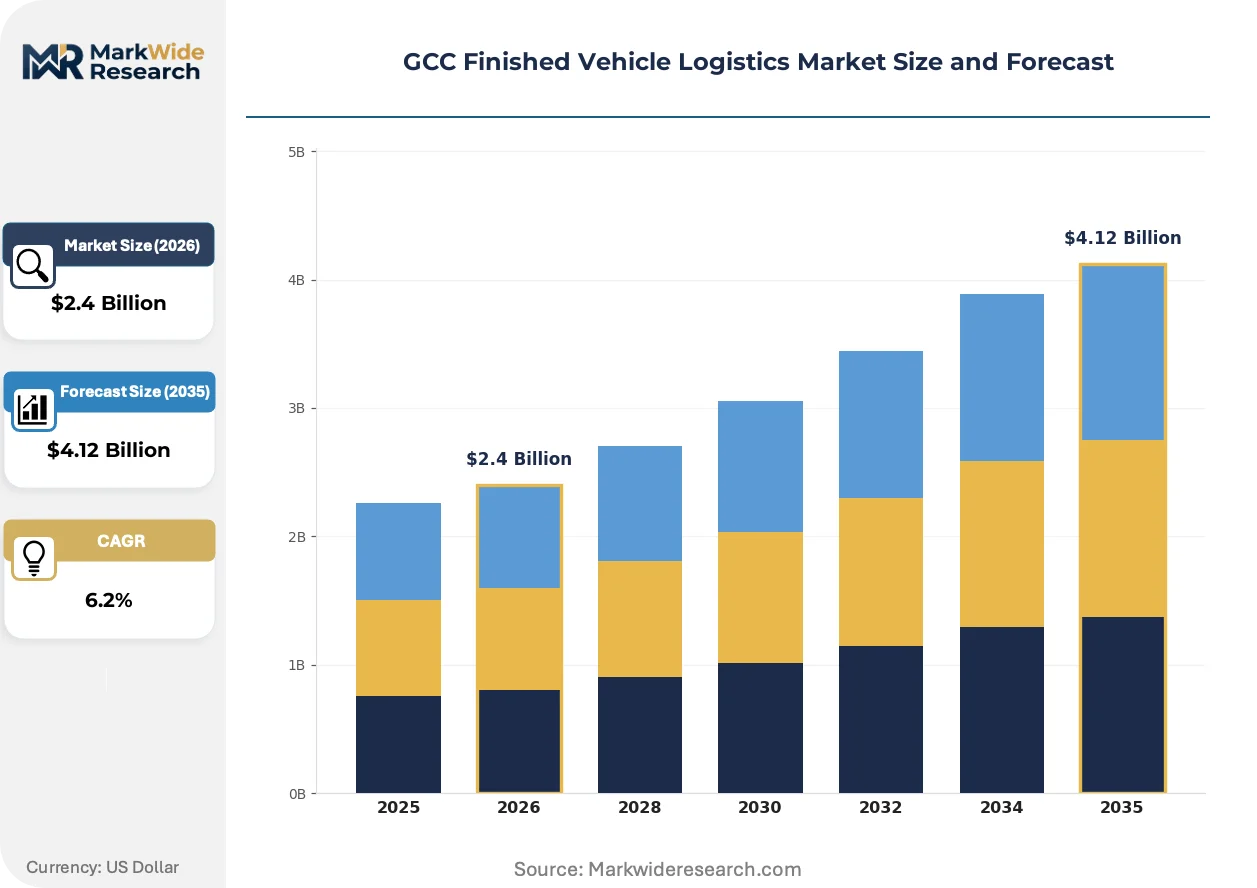
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.12 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Distribution, Packaging, Customs Clearance Vehicle Type: Passenger Cars, Commercial Trucks, Motorcycles, Electric Vehicles, SUVs End User: Dealerships, Fleet Operators, Aftermarket Providers, Rental Companies, Automotive OEMs Distribution Channel: Direct Sales, Online Platforms, Auctions, Export/Import, Logistics Providers |
| Companies Covered | Gallega Global Logistics, RSA Global, Almajdouie Logistics, Al-Futtaim Logistics, Gulf Agency Company Ltd., GEFCO, CEVA Logistics, DB Schenker, DHL, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Finished Vehicle Logistics Market Shifts & Advancements
Digital yard management and electrification protocols are compressing vehicle dwell times while forcing infrastructure investments that separate specialized from commodity logistics providers.
Autonomous yard tractors are rewriting vehicle marshalling economics at high-volume processing terminals. Almajdouie Logistics and GEFCO are piloting self-driving tractor units at Dammam and Jebel Ali facilities to reduce labor dependency during peak import seasons. The technology is compressing vessel-to-warehouse transfer windows from 72 hours to sub-48-hour benchmarks.
Dubai Customs' pre-arrival clearance digitization mandate is eliminating paper-based documentation bottlenecks at UAE entry points. The regulation requires electronic bill-of-lading submission 48 hours before vessel arrival, forcing freight forwarders to upgrade legacy documentation workflows. European-origin logistics providers with existing digital platforms are capturing disproportionate clearance velocity advantages.
Fleet operators are consolidating procurement under long-term throughput agreements rather than spot-rate tendering. Public Investment Fund-backed mobility ventures in Saudi Arabia are anchoring multi-year contracts with guaranteed annual volume minimums. This concentration is visible in Riyadh and Jeddah metropolitan zones where rental fleet turnover cycles have compressed from 24 to 18 months.
GCC Finished Vehicle Logistics Market Segmentation
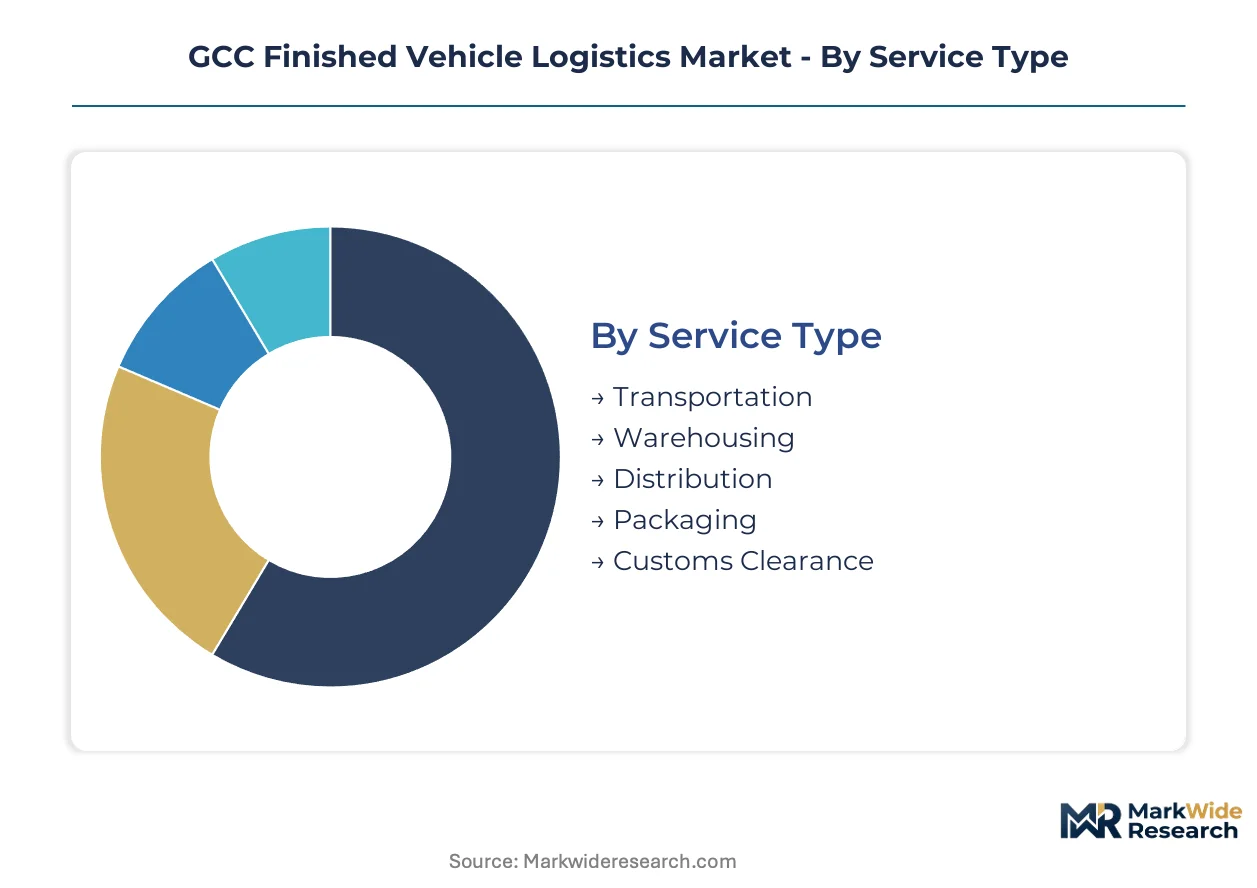
Service differentiation across the GCC finished vehicle logistics market determines margin capture and infrastructure investment priorities. Temperature-controlled handling requirements and port proximity create divergent cost structures across segment tiers.
Service Type:
Standardized port-to-depot movements compete with specialized value-added services requiring certification and equipment customization.
- Transportation:Port-to-inland haulage exceeding 800 kilometers on Saudi Arabia's major corridors dominates value capture. Fleet operators in Riyadh and Jeddah metropolitan zones anchor contract volumes through multi-year throughput agreements with guaranteed annual minimums.
- Warehousing:Climate-controlled facilities maintaining sub-45°C ambient temperatures consume 23-31% of operating budgets across UAE and Saudi Arabia. King Abdullah Port's dedicated vehicle processing terminals and Almajdouie Logistics' Dammam facilities concentrate premium-capacity investment.
- Distribution:Last-mile synchronization with dealership sales cycles requires real-time inventory visibility. Dubai Customs' pre-arrival clearance digitization mandate is compressing documentation bottlenecks for rapid yard-to-showroom transfer.
- Packaging:Protective wrapping and transit damage prevention protocols vary by vehicle class. SUV-heavy stockpiles demand specialized racking height accommodations.
- Customs Clearance:SASO technical conformity pre-arrival documentation rules and Dubai Customs' 48-hour electronic bill-of-lading requirements are accelerating digital platform investments by freight forwarders.
Leading the category by volume: Transportation. Growing fastest: Customs Clearance.
Vehicle Type:
Volume concentration in conventional internal combustion segments contrasts with emerging electrification protocols demanding hazardous-material handling credentials.
- Passenger Cars:Standard sedan and hatchback movements constitute the baseline service tier. Jeddah's King Abdullah Port automotive hub processes rising import volumes through dedicated terminals.
- Commercial Trucks:Heavy-duty vehicle logistics requires specialized lifting equipment and extended dwell-time accommodation. Dammam's East Coast industrial clustering captures transshipment volumes as Saudi Arabia expands domestic assembly.
- Motorcycles:Two-wheeler handling employs consolidated container stowage for cost efficiency. Smaller unit economics limit dedicated infrastructure investment.
- Electric Vehicles:Battery state-of-charge monitoring and hazardous-material protocols during vessel stowage necessitate technician certification scarce across GCC logistics workforces. Jeddah's King Abdullah Port is developing dedicated service tiers for EV imports.
- SUVs:Premium segment sustaining above-market pricing through specialized racking requirements and longer average dwell times. Public Investment Fund-backed mobility ventures in Saudi Arabia are compressing rental fleet turnover cycles from 24 to 18 months.
Highest margin capture: SUVs. Steepest expansion trajectory: Electric Vehicles.
End User:
Procurement consolidation under long-term contracts is displacing spot-rate tendering among institutional buyers.
- Dealerships:Franchise networks require synchronized inventory flows matching promotional sales cycles. Real-time yard management systems are compressing carrying costs.
- Fleet Operators:Rental and corporate fleet managers are consolidating procurement volumes. Saudi Arabia's Public Investment Fund-backed mobility ventures anchor multi-year agreements with logistics providers.
- Aftermarket Providers:Spare parts and accessory logistics demands fragmented, high-frequency delivery scheduling. Smaller shipment sizes limit economies of scale.
- Rental Companies:Accelerated vehicle turnover cycles in Riyadh and Jeddah are intensifying processing velocity requirements at receiving terminals.
- Automotive OEMs:Domestic assembly localization under Saudi Vision 2030 mandates is reconfiguring port-to-inland distribution networks around manufacturing endpoints rather than pure import throughput.
Contract concentration highest: Fleet Operators. Fastest procurement cycle compression: Rental Companies.
Distribution Channel:
Direct control versus third-party intermediation shapes margin retention and customer data access.
- Direct Sales:OEM-controlled logistics preserves margin and brand experience standardization. Requires captive infrastructure investment.
- Online Platforms:Digital retail channels are forcing real-time inventory visibility integration with consumer-facing availability systems.
- Auctions:Remarketing logistics for off-lease and fleet disposal vehicles demands rapid condition assessment and reprocessing capabilities.
- Export/Import:Cross-border movements face disconnected Saudi and UAE rail networks forcing multimodal transfers at border zones, adding 18-24 hours to corridor transit times.
- Logistics Providers:Third-party specialists including GEFCO and DB Schenker compete through European-origin quality systems adapted to GCC temperature extremes and rail-integrated multimodal footprints.
Volume dominance: Logistics Providers. Channel integration priority: Online Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet procurement consolidation among Saudi Arabia's Public Investment Fund-backed mobility ventures and UAE-based rental operators is reshaping logistics demand patterns across the Gulf. Saudi Vision 2030 localization mandates and UAE's pre-arrival customs digitization are forcing infrastructure investments at major port hubs.
Saudi Arabia
Saudi Arabia's domestic automotive assembly expansion under Vision 2030 is redirecting port-to-inland distribution networks toward manufacturing endpoints. SASO technical conformity pre-arrival documentation rules are accelerating digital customs platform investments. King Abdullah Port in Jeddah anchors the automotive hub with dedicated vehicle processing terminals handling rising import volumes.
United Arab Emirates
UAE fleet operators and rental companies are consolidating procurement under multi-year throughput agreements with guaranteed annual minimums. Dubai Customs' 48-hour electronic bill-of-lading submission mandate is eliminating paper-based documentation bottlenecks. Jebel Ali concentrates over 70% of GCC finished vehicle import volume alongside multimodal rail-integrated corridors.
Kuwait
Kuwait's underdeveloped dedicated vehicle processing infrastructure offers first-mover terminal construction opportunities for regional operators expanding beyond saturated Saudi and UAE markets. The country's national customs authority maintains import documentation requirements that lag behind UAE digitization standards. Shuwaikh Port handles vehicle volumes without specialized automotive-dedicated terminals.
Bahrain
Bahrain's compact geography enables rapid port-to-showroom distribution cycles that attract regional logistics providers seeking operational efficiency benchmarks. The country's Ministry of Transportation and Telecommunications oversees port modernization programs. Khalifa Bin Salman Port automotive handling capacity remains constrained relative to regional throughput growth.
Qatar
Qatar's FIFA 2022 legacy infrastructure investments created surplus commercial vehicle capacity now redirecting toward regional transshipment roles. The Qatar Free Zones Authority promotes automotive logistics clustering near Hamad Port. Doha's metropolitan fleet renewal cycles are compressing from 24 to 18 months for rental operators.
GCC Finished Vehicle Logistics Market Competitive Landscape
European-origin logistics providers anchor one tier through quality systems adapted to GCC temperature extremes; regional specialists from Saudi Arabia and the UAE hold port-proximate infrastructure advantages. The vendor base splits between asset-heavy terminal operators and technology-integrated freight managers. Three archetypes dominate: captive automotive logistics arms of diversified industrial groups, European multinational forwarders with rail-multimodal footprints, and regional pure-plays with dedicated vehicle processing facilities. Competitive moves concentrate on terminal capacity expansion at East Coast Saudi hubs and digital yard management system deployment.
Among regional infrastructure owners, Almajdouie Logistics, Al-Futtaim Logistics, and Gulf Agency Company Ltd. exemplify the asset-heavy archetype with dedicated vehicle processing terminals and climate-controlled warehousing networks. These operators occupy positions where port proximity and Saudi Vision 2030 localization alignment create defensive moats against European multinational entrants. European-origin providers including GEFCO and DB Schenker represent the technology-integrated tier, leveraging existing digital platforms to capture clearance velocity advantages under UAE and Saudi customs digitization mandates.
| Leading Market Players |
|---|
| Gallega Global Logistics |
| RSA Global |
| Almajdouie Logistics |
| Al-Futtaim Logistics |
| Gulf Agency Company Ltd. |
| GEFCO |
| CEVA Logistics |
| DB Schenker |
| DHL |
| Others |
Supply & Pricing Matrix
Captive integration into dedicated vehicle processing terminals anchors both supply position and pricing power for regional operators across Saudi Arabia and the UAE. SASO technical conformity mandates and Dubai Customs digitization requirements erect compliance barriers that favor incumbent asset owners with existing certification infrastructure, compressing margin pressure onto non-compliant spot-rate providers.
Pricing Analysis
High-volume port-to-depot movements capture baseline revenue while specialized EV handling and climate-controlled warehousing command premium margins. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and volume scale, with fleet operators anchoring long-term contracts at favorable rates. Cost compression in standard transportation tiers is intensifying because European multinational entrants leverage existing digital platforms for clearance velocity advantages. Fleet operators and rental companies show least price sensitivity due to procurement consolidation, while fragmented aftermarket providers face acute margin pressure.
Supply Chain Analysis
Freight economics across the UAE-Saudi corridor hinge on disconnected rail networks that force multimodal transfers at border zones, adding dwell time and handling costs. Supply concentration centers on Jebel Ali and King Abdullah Port, with Dammam's East Coast terminals capturing rising transshipment volumes as domestic assembly expands. Battery electric vehicle imports draw from hazardous-material handling protocols and scarce technician certification pools. Single-point-of-failure exposure at concentrated port hubs represents the dominant structural risk. Distribution runs through third-party logistics providers with rail-integrated multimodal footprints and captive terminal operators with port-proximate infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where SASO technical conformity pre-arrival documentation rules and Dubai Customs digitization mandates create barrier-to-entry moats for certified terminal operators and digital platform investors.
For Market Incumbents: Deepen captive integration into climate-controlled warehousing networks at King Abdullah Port and Dammam's East Coast automotive cluster to defend against European multinational entrants with clearance velocity advantages. Prioritize battery handling technician certification investments to capture EV service line expansion before workforce scarcity delays market entry. Lock in multi-year throughput agreements with Public Investment Fund-backed mobility ventures to anchor volume visibility. For New Entrants and Emerging Players: The gap between premium climate-controlled warehousing rates and economy-grade open-yard storage creates white-space opportunity in Kuwait and Bahrain's underdeveloped dedicated vehicle processing infrastructure. Target first-mover terminal construction at Shuwaikh Port and Khalifa Bin Salman Port before regional incumbents extend capacity. Lead with digital yard management system deployment to bypass legacy proprietary port community systems that resist API connectivity. For Investors and Strategic Acquirers: Exit pathways concentrate in regional pure-play acquisition by European multinational forwarders seeking port-proximate infrastructure and Saudi Vision 2030 localization alignment. Long-term viability favors asset-heavy operators with dedicated vehicle processing terminals over technology-integrated freight managers lacking captive capacity. Monitor Etihad Rail freight network expansion as inflection indicator for rail-seaport integration plays that bypass congested highway corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Terminal Capacity Expansion | East Coast Saudi hubs near Dammam capture rising transshipment volumes from domestic assembly growth. |
| Digital Yard Management Deployment | Real-time IoT vehicle tracking with predictive dwell-time analytics compresses SUV-heavy inventory carrying costs. |
| EV Handling Certification Investment | Battery state-of-charge monitoring and high-voltage safety credentials unlock fastest-growing vehicle type segment. |
| Rail-Seaport Integration | Etihad Rail freight network enables direct port-to-inland depot services bypassing congested UAE-Saudi highway corridors. |
| Long-term Throughput Agreements | Multi-year contracts with guaranteed annual minimums anchor volume visibility against spot-rate tendering volatility. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with fleet procurement directors, terminal operations managers, customs brokerage leads, and automotive OEM logistics planners. Saudi Customs Authority import documentation, Dubai Customs clearance velocity statistics, and vehicle production databases provided quantitative grounding. Bottom-up service type and vehicle type segmentation combined with top-down regional demand aggregation to triangulate market sizing.
Granularity-level modeling distinguished transportation, warehousing, distribution, packaging, and customs clearance service tiers across passenger cars, commercial trucks, electric vehicles, and SUVs. End-user segmentation captured dealerships, fleet operators, rental companies, aftermarket providers, and automotive OEMs. CAGRs derived from regression analysis against macroeconomic indicators and sector-specific demand drivers including Saudi Vision 2030 localization targets and EV import penetration trajectories.
Underlying measurement precision varies by segment; electric vehicle handling protocols and customs clearance digitization carry tighter precision than fragmented aftermarket logistics. Forecasts reflect assumptions about regulatory enforcement continuity, rail network completion timelines, and technician certification pipeline development. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Vietnam Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
India 3PL Market
Logistics and Shipping
Sweden Cold Chain Logistics Market
Logistics and Shipping
Russia 3PL Market
Logistics and Shipping
Global Courier Market
Logistics and Shipping
United States Contract Logistics Market
Logistics and Shipping
Singapore Shipping Agency Services Market
Logistics and Shipping
Egypt 3PL Market
Logistics and Shipping
United States Freight and Logistics Market
Logistics and Shipping
Multi-Enterprise Logistics Contract and SLA Performance Management Platforms Market
Logistics and Shipping
United States Digital Freight Forwarding Market
Logistics and Shipping
Air Cargo Capacity and Allotment Marketplace Platforms Market
Logistics and Shipping
Cloud Logistics Market
Logistics and Shipping
Middle Mile Delivery Market
Logistics and Shipping
Air Cargo Market
Logistics and Shipping
United States Air Freight Market