
 Mexico Courier, Express, and Parcel (CEP) Market | 2026-2036
Mexico Courier, Express, and Parcel (CEP) Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Courier, Express, and Parcel (CEP) Market Insights
Market Context
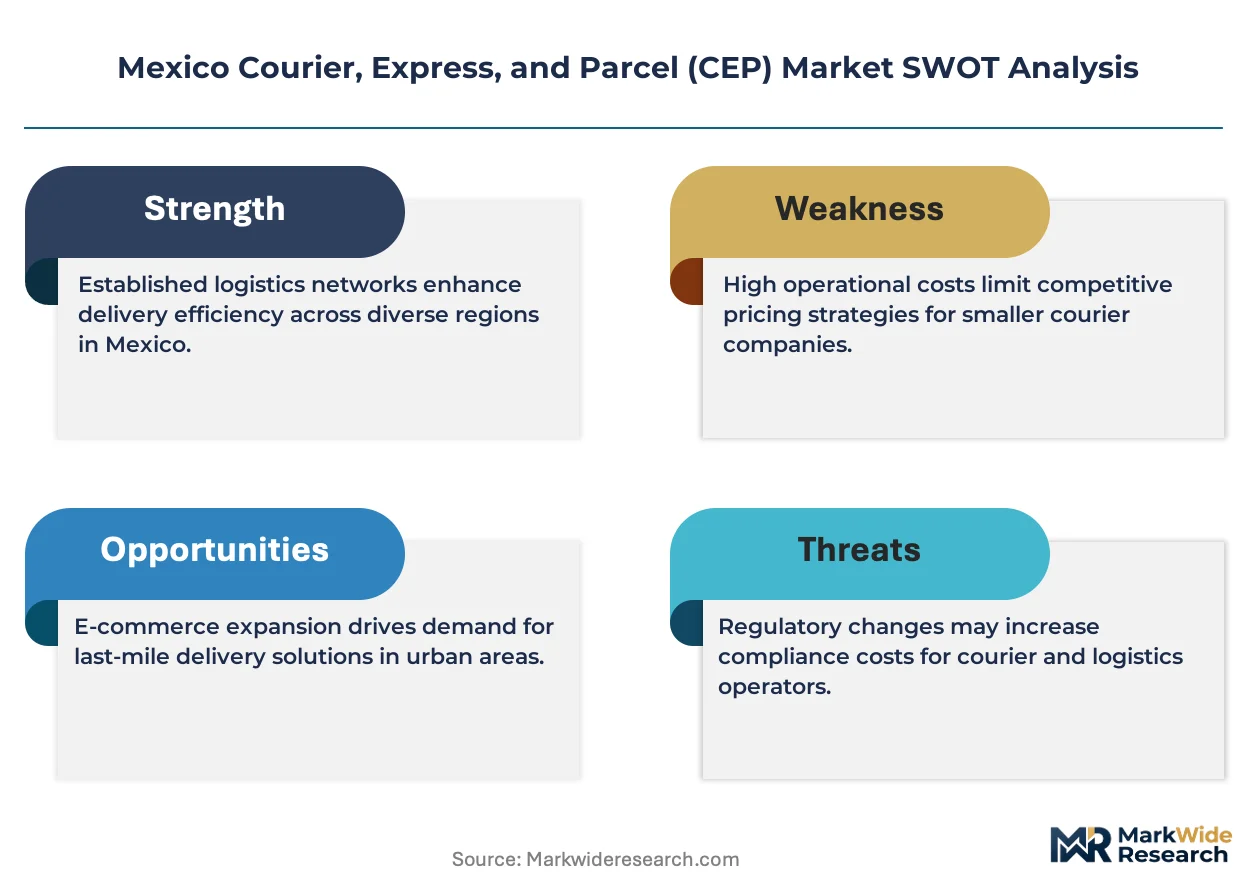
The capital-intensity divergence between integrated global networks and regional last-mile specialists is rotating competitive investment toward automated sorting hubs and proprietary fleet expansion. DHL Group leverages its bonded warehouse infrastructure and customs-brokerage integration to dominate cross-border express corridors between Mexico and the United States. Estafeta anchors domestic coverage through its dense branch network in secondary cities and state capitals outside the central plateau. 99minutos competes on velocity, sustaining same-day delivery promises through micro-fulfillment nodes positioned in Guadalajara, Monterrey, and Mexico City.
Technical Definition and Segment Structure
Courier, Express, and Parcel services constitute time-definite logistics solutions encompassing document envelopes, small packages, and palletized freight moved through integrated collection, line-haul, and distribution networks with guaranteed delivery windows. These services employ barcode tracking, electronic proof-of-delivery, and customs pre-clearance systems to manage shipment visibility and regulatory compliance across domestic and international lanes. Same-day and next-day delivery categories command premium rate structures due to their dependence on localized inventory positioning and dynamic route optimization, while scheduled delivery and freight services absorb higher weight-class shipments with lower per-unit velocity requirements. E-commerce platforms and retailers concentrate volume growth, though individual consumer direct-to-door expectations are compressing delivery windows across all customer type segments.
Regulatory Framework and Outlook
SECOFI (now part of SE through regulatory consolidation) and SAT customs authorities govern cross-border express clearance procedures, while SCT transport regulations mandate commercial vehicle safety standards and operator certification for freight fleets operating federal highways. USMCA origin rules and de minimis thresholds shape parcel flow economics, determining which shipments qualify for expedited customs treatment versus full formal entry processing. Stakeholders must monitor whether Mexican authorities harmonize drone delivery airspace permissions with existing SCT aviation rules, as aerial last-mile trials advance from pilot phases toward operational scale in constrained urban corridors.
Market Dynamics
Nearshoring manufacturing mandates under USMCA are compressing cross-border transit windows and forcing carriers to reconfigure northern border corridor capacity around bonded express lanes and pre-cleared freight flows.
Growth Catalysts
- USMCA de minimis thresholds:Expedited customs treatment for qualifying parcels accelerates cross-border velocity and reduces brokerage friction for e-commerce fulfillment.
- E-commerce platform penetration:Digital retail expansion across Mexican metropolitan areas concentrates parcel volume in dense last-mile zones, creating network economies for automated sorting investments.
- Micro-fulfillment positioning:Urban inventory nodes in Guadalajara, Monterrey, and Mexico City enable same-day delivery promises that capture premium rate structures.
Market Restraints
- Diesel price volatility:Fleet operators face margin compression from fuel cost swings that resist full pass-through in competitive tendering environments.
- Federal highway safety certification:SCT commercial vehicle mandates impose recurring compliance burdens and driver qualification bottlenecks that constrain fleet expansion velocity.
- Customs formal entry requirements:SAT procedures for non-qualifying shipments create clearance delays that degrade express service guarantees.
Strategic Opportunities
- Secondary city branch density:Underpenetrated state capitals outside the central plateau offer whitespace for proprietary pickup and delivery network extension.
- Drone delivery airspace harmonization:SCT aviation rule convergence with urban aerial trials could unlock constrained corridor capacity in Mexico City's densest zones.
- Cross-border bonded warehousing:Integrated customs-brokerage infrastructure near northern border states captures USMCA-qualifying manufacturing flows.
Industry Challenges
- Dynamic route optimization talent:Scarcity of data science and operations research specialists limits algorithmic fleet deployment and real-time capacity rebalancing.
- Automated sorting hub capex:Capital intensity of integrated hub investments strains regional specialists competing against global network scale.
- Legacy TMS integration:Proprietary fleet management systems resist interoperability with customer ERP platforms, creating onboarding friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Courier, Express, and Parcel (CEP) Market |
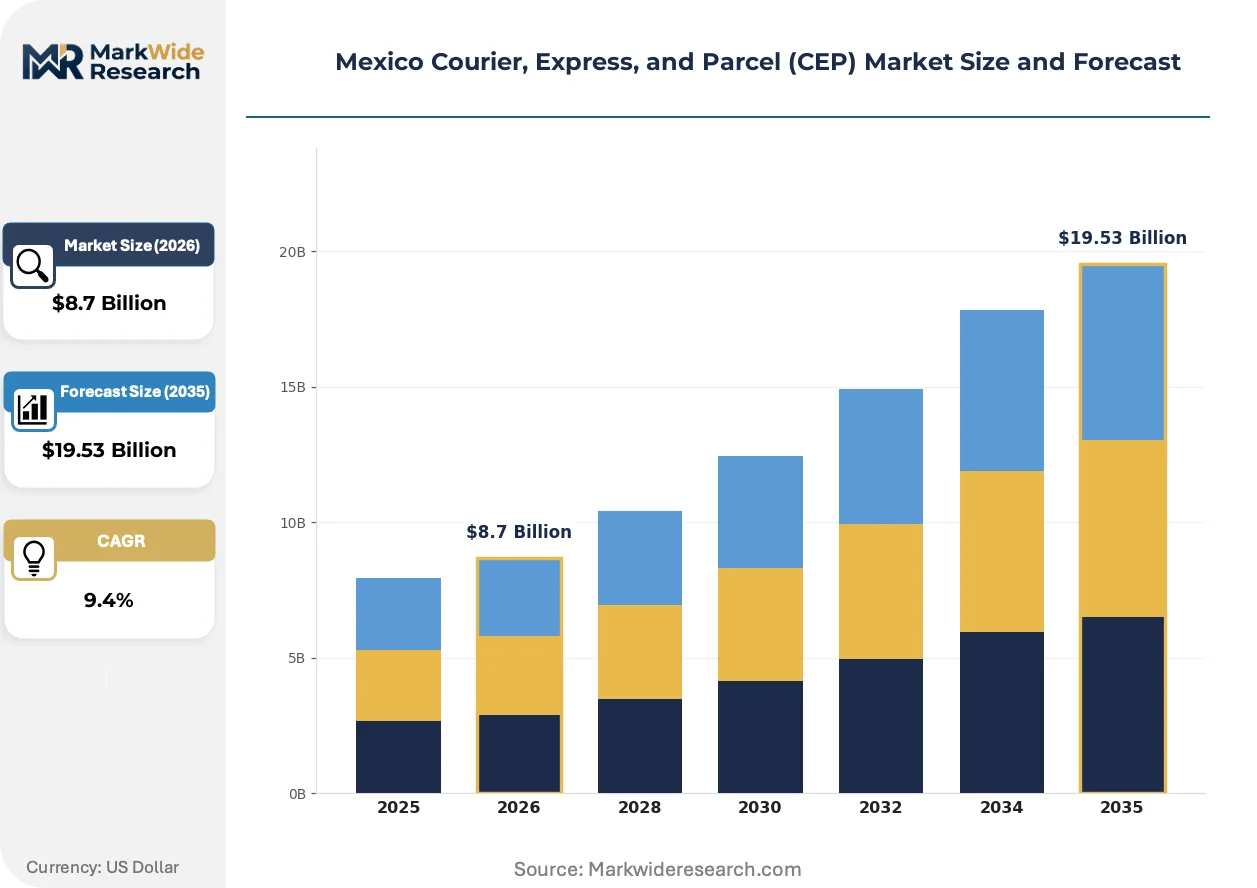
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Same-Day Delivery, Next-Day Delivery, Scheduled Delivery, Freight Services Packaging Type: Standard Box, Climate-Controlled Packaging, Secure Packaging, Palletized Shipping Customer Type: Retailers, E-commerce Platforms, Corporates, Individual Consumers Delivery Mode: Ground, Air, Sea, Drone |
| Companies Covered | DHL Group, Estafeta, FedEx Corporation, United Parcel Service of America, Inc. (UPS), Traxion (including Redpack), 99minutos, iVoy Mensajería Express, Paquetexpress Services Operator, SA de CV, SkyPostal Networks, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Courier, Express, and Parcel (CEP) Market Trends and Innovations
Digital freight matching and predictive capacity algorithms are compressing planning cycles and redrawing competitive boundaries between asset-heavy integrators and technology-enabled brokers.
Dynamic route optimization software is supplanting static hub-and-spoke scheduling in last-mile operations. E-commerce fulfillment centers in Mexico City and Monterrey deploy real-time algorithmic dispatch to compress delivery windows. This capability is supplanting traditional zone-based routing and enabling same-day service promises that capture premium pricing tiers.
SAT customs pre-clearance protocols are tightening documentary requirements for cross-border express shipments. Electronics and automotive parts manufacturers face expanded origin verification demands that extend processing timelines. Northern border logistics clusters are responding by embedding bonded warehouse capacity closer to manufacturing plants to maintain velocity.
Buyer procurement patterns are consolidating volume under fewer carrier relationships with integrated visibility platforms. Mid-market retailers are abandoning fragmented multi-vendor arrangements for single-source contracts with API-tracked performance guarantees. This concentration is most visible in Mexico City metropolitan zone tenders where delivery density justifies dedicated fleet commitments.
Mexico Courier, Express, and Parcel (CEP) Market Segmentation
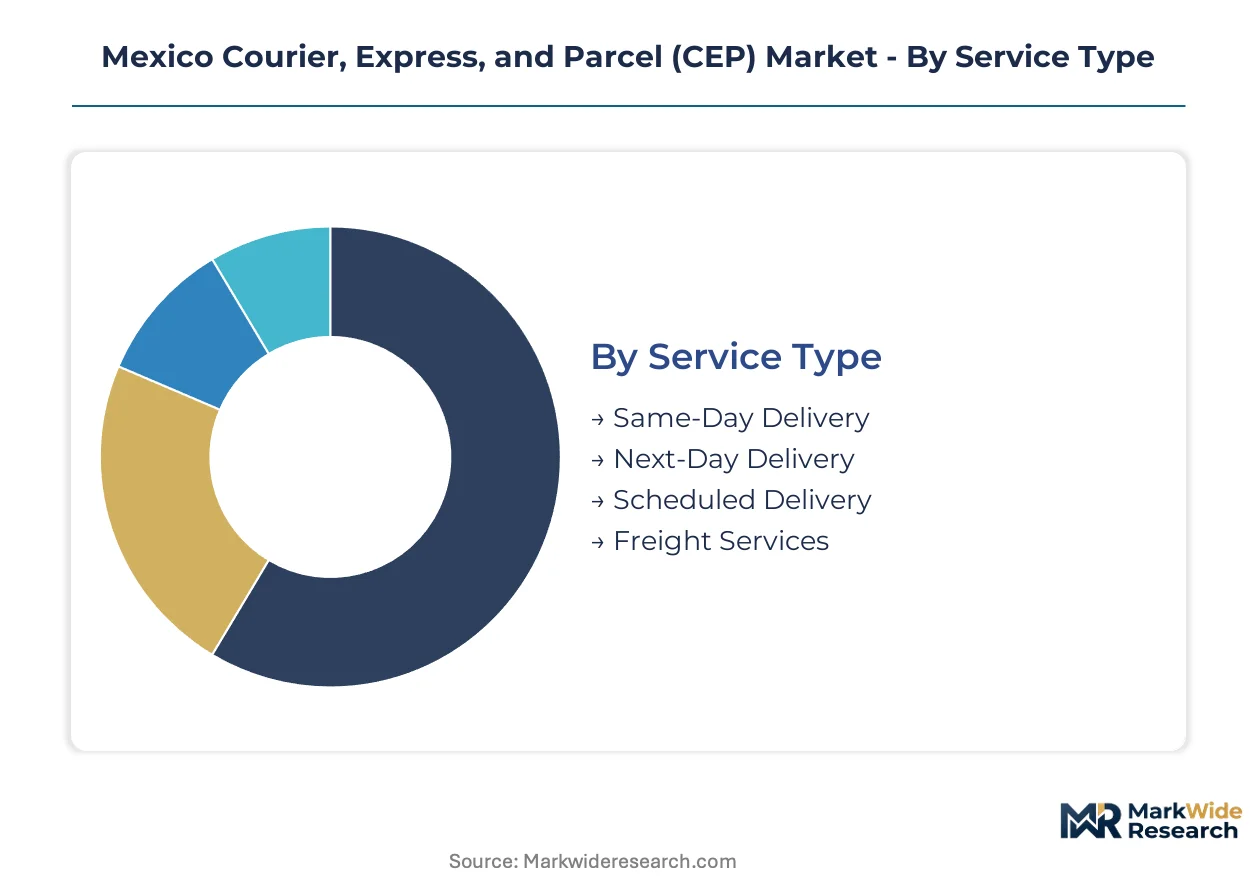
Segmentation in Mexico's CEP market reveals divergent margin structures and capital requirements across service tiers. Each dimension exposes distinct competitive moats, from velocity premiums in same-day delivery to customs integration in cross-border freight.
Service Type:
Domestic metropolitan corridors concentrate velocity-driven segments, while cross-border lanes favor scheduled and freight categories tied to manufacturing nearshoring flows.
- Same-Day Delivery:Ultra-time-definite service requiring micro-fulfillment nodes within 15-kilometer radii of demand clusters. Mexico City, Guadalajara, and Monterrey absorb capacity as e-commerce platforms compress delivery windows to capture premium rate tiers.
- Next-Day Delivery:Hub-and-spoke network service balancing speed against line-haul density. Northern border states generate volume from USMCA-qualifying manufacturing shipments requiring expedited customs pre-clearance.
- Scheduled Delivery:Day-definite service for non-urgent palletized freight with lower per-unit handling costs.
- Freight Services:Heavy-weight LTL and FTL movements through bonded corridors serving automotive and electronics manufacturers.
Scheduled delivery holds the largest share; momentum sits with same-day delivery.
Packaging Type:
Cost-to-serve varies dramatically by thermal and security requirements, with climate-controlled and secure formats commanding 3-4x standard handling premiums.
- Standard Box:Corrugated fiberboard containers for non-fragile general merchandise. E-commerce fulfillment centers in Mexico City metropolitan zone drive volume through automated sortation compatibility.
- Climate-Controlled Packaging:Insulated containers with gel packs or active cooling for temperature-sensitive pharmaceuticals and fresh produce. SCT transport regulations mandate cold-chain documentation that extends processing timelines.
- Secure Packaging:Tamper-evident containers with GPS tracking and chain-of-custody protocols for high-value electronics and jewelry.
- Palletized Shipping:Unitized freight on standardized platforms for manufacturing inputs and retail distribution center replenishment.
Standard box dominates volume; climate-controlled packaging is climbing the fastest.
Customer Type:
Procurement consolidation patterns favor integrated carriers capable of serving enterprise accounts with API-tracked visibility across all touchpoints.
- E-commerce Platforms:Digital retailers requiring API-integrated fulfillment with real-time inventory synchronization. Mexico City density enables dedicated fleet commitments that compress per-unit delivery costs below multi-vendor alternatives.
- Corporates:B2B accounts with contracted service level agreements spanning document exchange, parts logistics, and event-driven surge capacity. Automotive OEMs near Monterrey anchor cross-border express volume.
- Retailers:Brick-and-mortar chains replenishing store inventory or fulfilling omnichannel orders from distribution centers.
- Individual Consumers:Fragmented C2C and direct-to-door demand with low per-shipment value and high last-mile cost sensitivity.
E-commerce platforms hold the largest share; corporates show steepest expansion trajectory.
Delivery Mode:
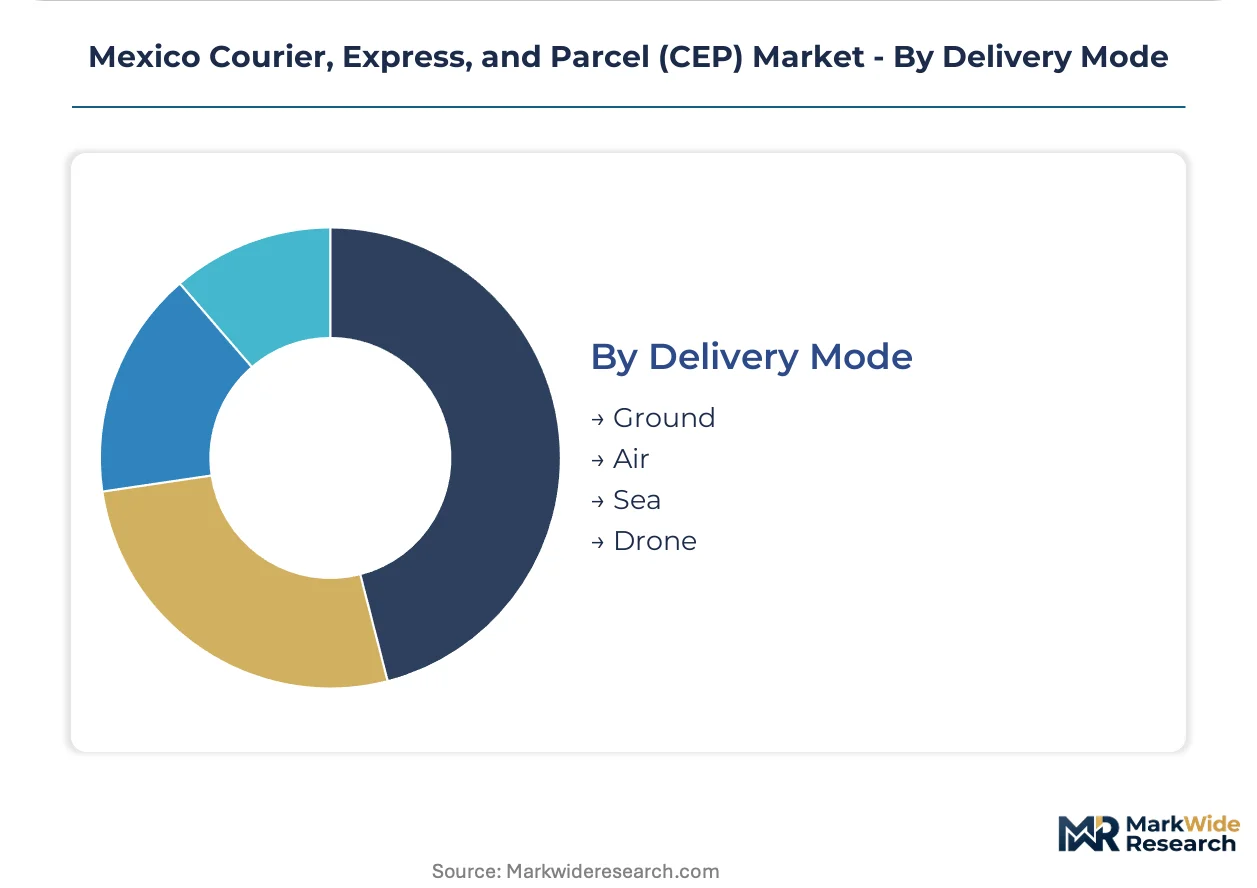
Modal choice reflects the trade-off between capital intensity and velocity, with ground networks absorbing 80%+ of domestic volume while air and drone capture premium niches.
- Ground:Fleet-based surface transportation through federal highway networks. SCT commercial vehicle safety certification creates driver qualification bottlenecks that constrain fleet expansion velocity.
- Air:Line-haul cargo capacity through Mexico City International Airport and Monterrey Intermodal Hub for cross-border express and time-critical domestic lanes.
- Sea:Maritime containerized freight for non-urgent international shipments with lowest per-kilogram economics.
- Drone:Aerial last-mile trials in constrained urban corridors pending SCT aviation rule harmonization with existing airspace permissions.
Ground holds the largest share; drone delivery is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import intensity across Mexico's sub-regions determines CEP corridor profitability, with manufacturing nearshoring tilting volume northward while consumption gravity anchors last-mile investment in the central plateau.
Northern Border States
Cross-border express lanes through Tijuana, Ciudad Juárez, and Nuevo Laredo absorb USMCA-qualifying automotive and electronics shipments. SAT customs pre-clearance protocols govern bonded warehouse operations that compress transit windows. Monterrey anchors manufacturing logistics clusters where carriers embed dedicated fleet capacity to capture just-in-time delivery contracts.
Mexico City Metro
E-commerce fulfillment density in the metropolitan zone concentrates same-day delivery demand and automated sorting hub investment. SCT commercial vehicle safety certification mandates constrain fleet expansion velocity for last-mile operators. Toluca and Cuautitlán Izcalli host fulfillment center clusters where micro-fulfillment nodes enable sub-two-hour delivery promises.
Jalisco
Guadalajara's technology sector generates high-value document and parts logistics demand with strict time-definite requirements. The state's central location positions it as a distribution hub connecting Pacific port corridors to interior consumption markets. Zapopan and El Salto industrial parks attract pharmaceutical and medical device manufacturers requiring cold-chain CEP services.
Bajío Region
Automotive OEM concentration in Guanajuato and Querétaro drives scheduled freight and cross-border express volume toward US assembly plants. SCT federal highway regulations impose driver qualification standards that limit carrier capacity scaling. Silao and Apaseo el Grande logistics parks concentrate bonded warehousing for USMCA-origin parts consolidation.
Nuevo León
Monterrey's industrial base generates the highest B2B express density outside Mexico City, with manufacturing procurement patterns favoring integrated carriers. State-level infrastructure investment in intermodal connectivity supports hub-and-spoke network efficiency. Apodaca and Santa Catarina host the densest logistics park concentration in northern Mexico.
Mexico Courier, Express, and Parcel (CEP) Market Competitive Landscape
Concentration sits with integrated global networks that command cross-border express corridors, while regional specialists defend domestic last-mile density through proprietary branch infrastructure. The competitive structure stratifies into three archetypes: bonded customs integrators, metropolitan velocity specialists, and secondary city coverage players. Dominant competitive moves include automated sorting hub capex deployment and micro-fulfillment node positioning in high-density zones.
Within the integrated global tier, DHL Group and FedEx Corporation occupy positions defined by customs-brokerage integration and bonded warehouse infrastructure. Estafeta and 99minutos exemplify domestic specialists competing on branch density and velocity promises respectively. These named entities anchor archetype discussions without constraining strategic optionality for other market participants.
| Leading Market Players |
|---|
| DHL Group |
| Estafeta |
| FedEx Corporation |
| United Parcel Service of America, Inc. (UPS) |
| Traxion (including Redpack) |
| 99minutos |
| iVoy Mensajería Express |
| Paquetexpress Services Operator, SA de CV |
| SkyPostal Networks, Inc. |
| Others |
Pricing and Supply Chain Analysis
SCT commercial vehicle safety certification governs fleet operator qualification standards, simultaneously filtering supply-side participation and enabling rate premiums for certified carriers serving time-definite lanes. This regulatory gate compresses margin structures for non-compliant operators while rewarding integrated networks with bonded customs infrastructure.
Pricing Analysis
The customization-premium spread separates configured-to-order express services from standard parcel tiers, with same-day delivery commanding 3-4x standard handling rates due to micro-fulfillment positioning. Three-tier pricing structure across premium, standard, and economy levels stratifies by velocity guarantee and customs integration depth. Pricing pressure stems from diesel cost volatility that resists full pass-through in competitive e-commerce tenders. Individual consumers exhibit highest price sensitivity, while automotive OEMs near Monterrey absorb premium rates for just-in-time reliability.
Supply Chain Analysis
The Laredo-Colombia Solidarity International Bridge chokepoint underwrites cross-border express economics, with SAT customs pre-clearance protocols determining which shipments bypass formal entry delays. Fleet assets concentrate in Mexico, the United States, and Canada under USMCA manufacturing corridors. Diesel fuel, bonded warehouse capacity, and line-haul driver certification constitute critical input dependencies. Single-source vulnerability sits with northern border customs brokerage concentration. Distribution runs through hub-and-spoke networks anchored by Mexico City and Monterrey sorting facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's CEP market represents an early-cycle expansion story, with e-commerce platform penetration deepening across metropolitan zones and compressing delivery windows toward same-day velocity tiers.
For Market Incumbents: Fortify proprietary fleet scale through automated sorting hub deployment in Toluca and Cuautitlán Izcalli fulfillment clusters. DHL Group and FedEx Corporation should deepen bonded warehouse integration near Tijuana and Ciudad Juárez to capture USMCA-qualifying manufacturing flows. Capacity addition in secondary cities outside the central plateau defends against Estafeta's branch density advantages. For New Entrants and Emerging Players: SCT commercial vehicle certification fast-tracks enable immediate participation in scheduled freight segments with lower velocity requirements than express tiers. Underpenetrated state capitals in the Bajío region offer whitespace for proprietary pickup and delivery network extension. A go-to-market angle targeting pharmaceutical cold-chain services in Zapopan and El Salto industrial parks captures climate-controlled packaging premiums. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across same-day delivery infrastructure, favoring asset-light technology platforms over fleet-heavy integrators. Acquisition targets should display API-tracked visibility integration and micro-fulfillment node positioning in Guadalajara or Monterrey. The signal to monitor is SCT aviation rule harmonization permitting drone delivery scale in Mexico City's densest corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Sorting Hub Deployment | Mexico City and Monterrey facilities capture e-commerce volume density through algorithmic parcel processing. |
| Bonded Warehouse Expansion | Northern border states embed customs-brokerage integration for USMCA-qualifying manufacturing shipments. |
| Micro-Fulfillment Node Positioning | Urban inventory clusters within 15-kilometer radii enable sub-two-hour delivery promises. |
| Secondary City Branch Extension | State capitals outside the central plateau offer proprietary network whitespace against regional specialists. |
| Drone Delivery Airspace Harmonization | SCT aviation rule convergence unlocks constrained corridor capacity in dense metropolitan zones. |
Research Methodology
Desk research of customs trade databases, SCT regulatory filings, and carrier fleet disclosure documents preceded structured interviews with logistics operations directors, e-commerce fulfillment managers, SAT customs brokers, and automotive supply chain planners. Primary fieldwork with DHL Group, Estafeta, and 99minutos executives validated service tier definitions and pricing structures. Secondary sources included SAT administrative rulings, USMCA origin verification protocols, and SCT commercial vehicle safety standards. Bottom-up volume triangulation across service type, packaging format, and customer segment converged with top-down macroeconomic elasticity checks.
Variance-decomposition framing separated volume growth drivers from price-mix effects across the projection horizon. Segmentation dimensions modeled encompass service velocity tier, packaging thermal requirements, customer procurement scale, and delivery mode capital intensity. CAGRs derived from logistic adoption curves fitted to e-commerce penetration rates and nearshoring manufacturing flow projections. Forecast inputs incorporated diesel price elasticity assumptions and SCT driver certification bottleneck severity indices.
Underlying assumptions cover USMCA trade framework stability, SCT regulatory enforcement continuity, and e-commerce platform consolidation patterns, with deviation risk concentrated in SAT customs clearance protocol changes and federal highway infrastructure investment delays. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Digital Freight Forwarder Market
Logistics and Shipping
Illinois Freight and Logistics Market
Logistics and Shipping
Europe less-Than Container Load Market
Logistics and Shipping
South Africa Third-Party Logistics (3PL) Market
Logistics and Shipping
Nordics Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
China less than Truckload Road Freight Transport Market
Logistics and Shipping
United Kingdom Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Global Connected Logistics Market
Logistics and Shipping
Georgia Freight and Logistics Market
Logistics and Shipping
Smart Shipping Containers Market
Logistics and Shipping
Myanmar Freight and Logistics Market
Logistics and Shipping
GCC Air Freight and Logistics Market
Logistics and Shipping
Internet of Things (IoT) in Logistics Market
Logistics and Shipping
Qatar Freight and Logistics Market
Logistics and Shipping
Jordan Freight and Logistics Market
Logistics and Shipping
Argentina Freight and Logistics Market