
 Nordics Courier, Express, and Parcel (CEP) Market | 2026-2036
Nordics Courier, Express, and Parcel (CEP) Market Size, Share, and Industry Trends Forecast 2026-2036
Nordics Courier, Express, and Parcel (CEP) Market Insights
Recycled corrugated fiber is decoupling Nordic parcel packaging from virgin paper dependence, compressing material costs while satisfying retailer sustainability mandates. PostNord leverages its state-owned postal infrastructure to dominate rural last-mile coverage across Sweden and Denmark. DSV A/S anchors its competitive position through specialized pharmaceutical and temperature-controlled logistics networks. Instabee differentiates via gig-economy courier pools that flex capacity during e-commerce peak seasons without fixed-asset commitments.
Courier, Express, and Parcel services constitute time-definite logistics solutions encompassing document envelopes through palletized freight, typically operating on guaranteed delivery windows ranging from two hours to five business days depending on service tier and distance. These networks function through integrated hub-and-spoke sortation facilities, line-haul transportation, and localized delivery circuits designed to minimize cost per stop while maximizing delivery density. Same-day delivery commands premium pricing but remains structurally constrained by population dispersion outside Copenhagen, Stockholm, and Oslo metropolitan zones, whereas standard delivery occupies the volume base through automated sortation economies. Ground transport dominates Nordic CEP movements due to short intra-regional distances and well-maintained highway infrastructure, though air freight retains critical importance for Norwegian west coast and northern Finnish destinations beyond practical road transit times.
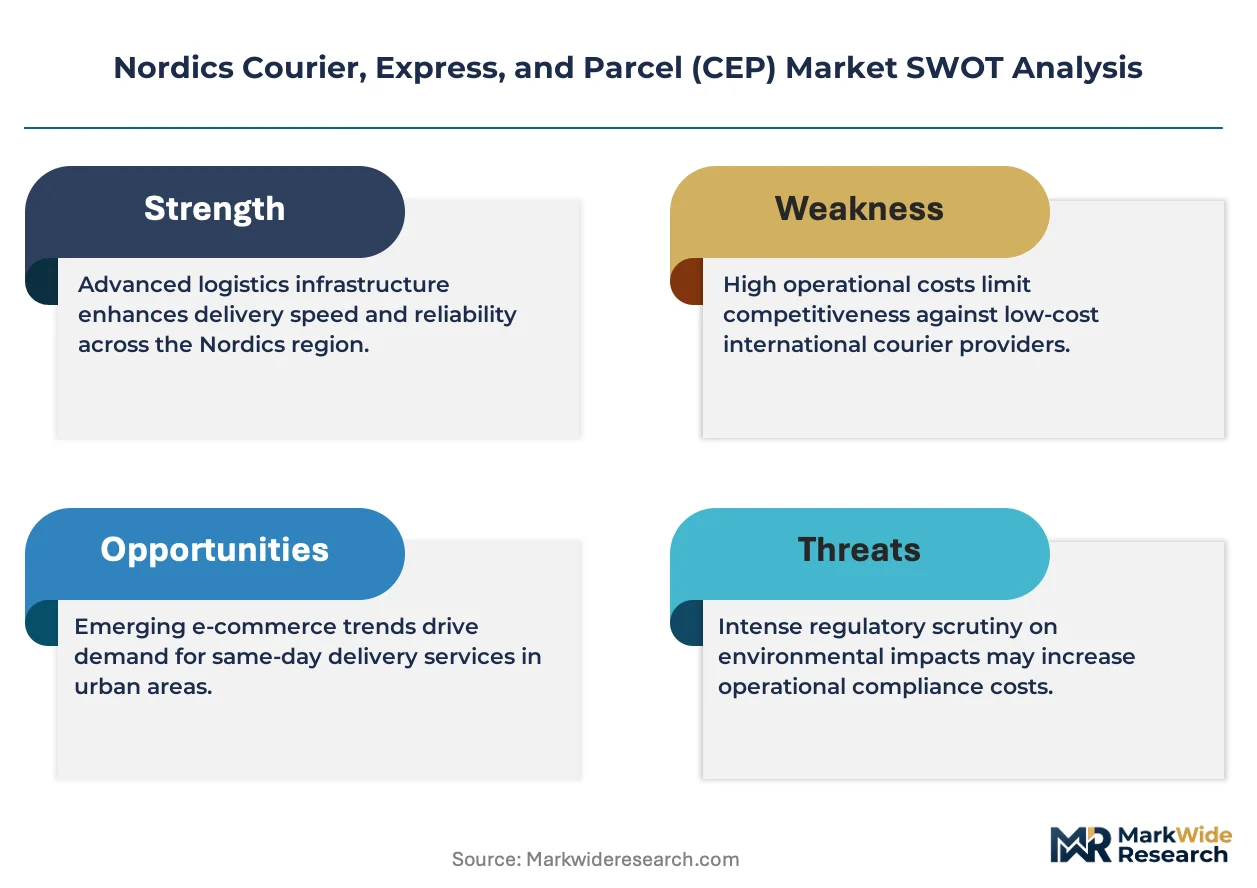
EU Green Deal emission targets enforced by national environmental agencies in Denmark, Sweden, Norway, and Finland are mandating progressive fleet electrification, directly influencing capital allocation toward electric vans and cargo bikes in urban delivery zones. REACH chemical regulations and national packaging ordinances govern adhesive, ink, and cushioning materials permitted in parcel construction, creating compliance barriers for non-EU suppliers. Stakeholders must monitor how Norway's upcoming carbon border adjustments and Sweden's proposed urban congestion charging zones reshape route economics and hub location decisions across the integrated Nordic delivery network.
Market Dynamics
EU Green Deal emission mandates are forcing fleet electrification across Nordic logistics networks, redirecting capital toward electric vans and cargo bikes while compressing delivery economics in urban zones. This regulatory pressure intersects with e-commerce volume surges to reshape route density requirements and hub placement strategies across Denmark, Sweden, Norway, and Finland.
Growth Catalysts
- E-commerce fulfillment intensity:Same-day and next-day delivery expectations from digital retailers are compressing delivery windows and expanding addressable service tiers across Stockholm, Copenhagen, and Oslo metropolitan corridors.
- EU Green Deal fleet mandates:Binding emission reduction targets enforced by national environmental agencies are accelerating electric vehicle procurement and alternative fuel infrastructure deployment among Nordic operators.
- Recycled corrugated fiber adoption:Sustainable packaging materials are decoupling parcel construction from virgin paper dependence while satisfying retailer sustainability procurement criteria.
Market Restraints
- Population dispersion outside urban corridors:Low delivery density across Norwegian west coast and northern Finnish territories structurally constrains same-day service economics and inflates per-stop costs.
- REACH chemical compliance barriers:Adhesive, ink, and cushioning material restrictions create non-tariff barriers for non-EU packaging suppliers entering Nordic supply chains.
- Air freight dependency for remote zones:Geographic constraints beyond practical road transit times lock in higher-cost transport modes for Norwegian and Finnish northern destinations.
Strategic Opportunities
- Swedish urban corridor densification:The Stockholm-to-Malmö population belt offers optimal last-mile economics for automated sortation investment and micro-fulfillment node placement.
- Norwegian carbon border adjustment preparation:Upcoming border mechanisms create first-mover advantage for operators with verified low-emission fleet credentials and documented supply chain transparency.
- Gig-economy courier pool integration:Flexible capacity models enable peak season volume absorption without fixed-asset commitments across Denmark and Sweden e-commerce surges.
Industry Challenges
- Electric fleet charging infrastructure gaps:Rural and semi-urban coverage limitations complicate route planning and vehicle range optimization across Norwegian and Finnish territories.
- Congestion charging zone navigation:Sweden's proposed urban toll schemes require dynamic route restructuring and hub relocation decisions that disrupt established network configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nordics Courier, Express, and Parcel (CEP) Market |
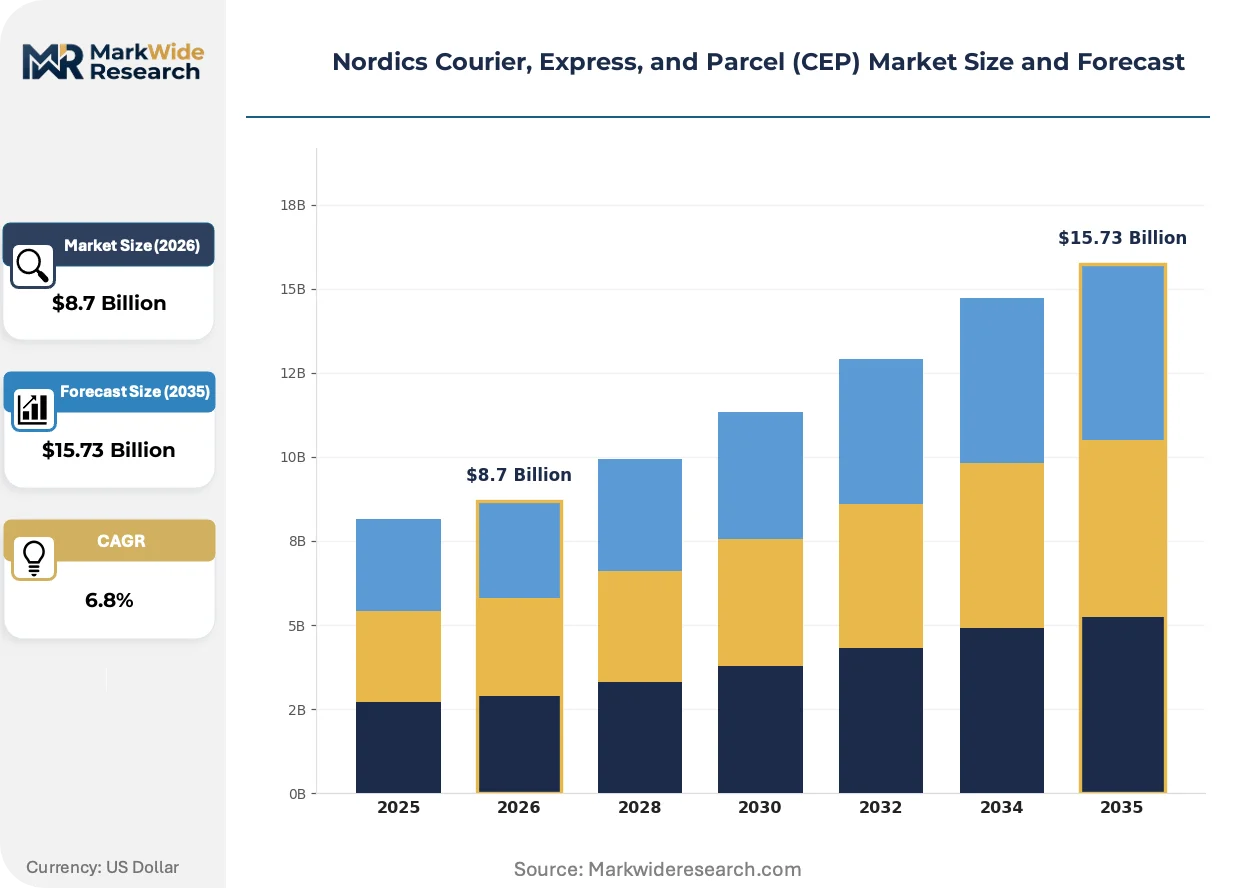
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standard Delivery, Same-Day Delivery, Next-Day Delivery, International Shipping Delivery Mode: Air Freight, Ground Transport, Rail Transport, Ocean Freight Customer Type: Business-to-Business, Business-to-Consumer, E-commerce, Retailers Package Size: Small Packages, Medium Packages, Large Packages, Palletized Shipments |
| Companies Covered | DHL Group, FedEx Corporation, PostNord, Jetpak Top Holding AB, GEODIS, DSV A/S, United Parcel Service (UPS), Instabee, Posten Bring AS, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nordics Courier, Express, and Parcel (CEP) Market Trends and Innovations
Digital commerce penetration is compressing delivery expectation windows across Nordic urban centers, forcing logistics operators to reconfigure sortation technology and fleet composition simultaneously. Three converging developments are restructuring competitive requirements in the region.
Cargo bikes and light electric vehicles are overtaking traditional van-based delivery in Copenhagen, Stockholm, and Oslo city centers. Municipal authorities are accelerating this transition through zero-emission zone designations and parking privilege allocations. The shift is compressing capital requirements for urban last-mile entry while displacing diesel van economics in dense delivery zones.
EU Green Deal emission targets enforced by Denmark, Sweden, Norway, and Finland are mandating progressive fleet electrification with binding compliance deadlines. National environmental agencies are monitoring operator progress through mandatory reporting frameworks. Pharmaceutical and temperature-controlled logistics networks face disproportionate compliance complexity due to refrigeration energy requirements and payload constraints.
Retailer procurement criteria now prioritize packaging material provenance and end-of-life recyclability over unit cost minimization. Corrugated fiber with post-consumer recycled content is displacing virgin paperboard in parcel construction across Nordic e-commerce fulfillment. This preference shift is most visible among Swedish and Danish fashion and electronics retailers with published sustainability commitments.
Nordics Courier, Express, and Parcel (CEP) Market Segmentation
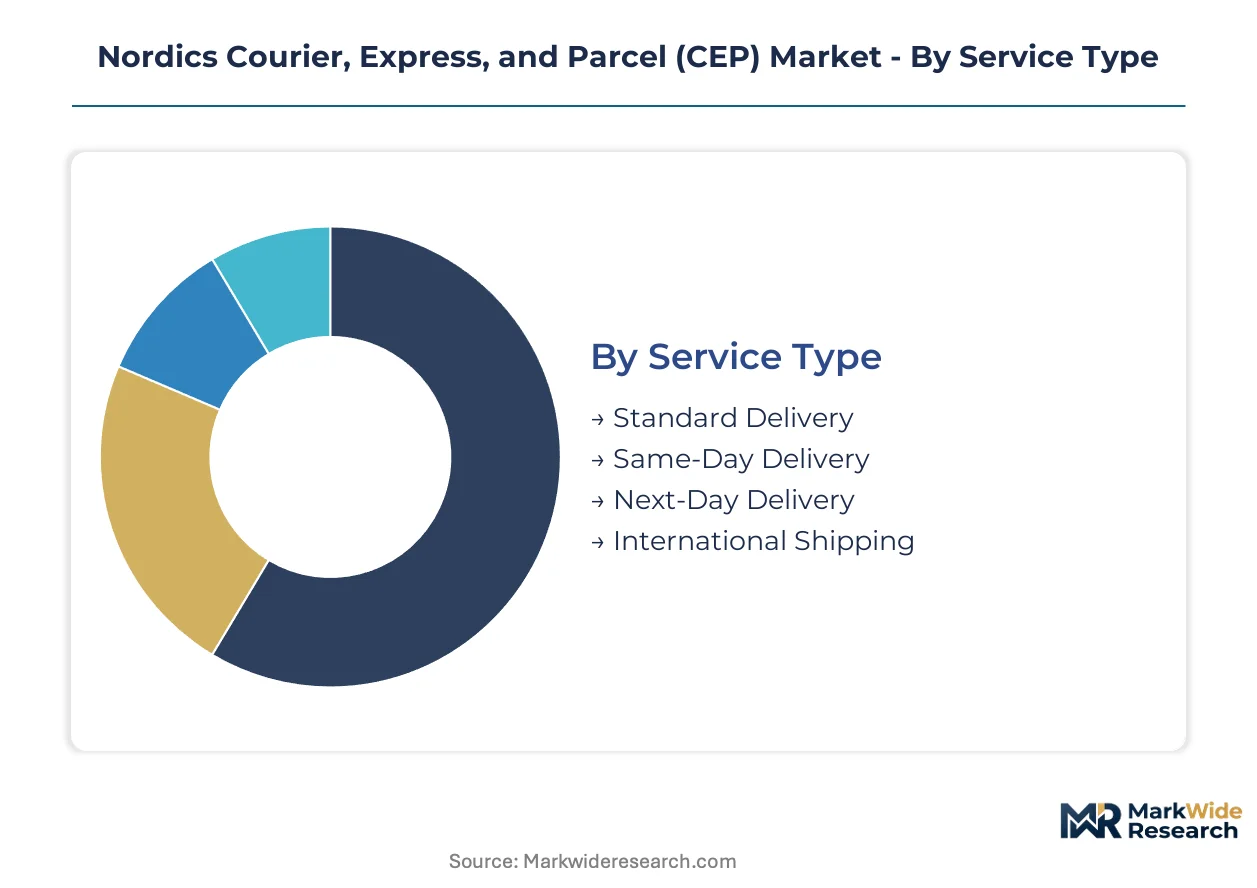
CEP operators configure network assets around service velocity tiers and payload characteristics. Customer procurement patterns and EU Green Deal compliance requirements further stratify competitive positioning across Nordic markets.
Service Type:
Delivery urgency dictates capital allocation between automated sortation hubs and flexible gig-economy pools.
- Standard Delivery:Two-to-five-day guaranteed windows leverage consolidated line-haul economies and automated hub sortation. Volume concentrates in Sweden's Stockholm-to-Malmö corridor where delivery density justifies fixed infrastructure investment.
- Same-Day Delivery:Two-hour fulfillment windows require distributed micro-fulfillment nodes and real-time courier dispatch platforms. Demand clusters in Copenhagen, Stockholm, and Oslo metropolitan zones where population concentration enables per-stop cost absorption.
- Next-Day Delivery:Overnight hub sorts with early-morning delivery circuits balance speed against capital intensity. E-commerce retailers in Denmark and Sweden drive procurement through published sustainability commitments.
- International Shipping:Cross-border customs clearance and multi-modal handoffs extend service reach beyond Nordic boundaries. REACH chemical compliance for packaging materials creates non-tariff barriers for non-EU origin shipments.
Volume sits with Standard Delivery; growth tilts toward Same-Day Delivery.
Delivery Mode:
Modal selection reflects geographic constraints and EU emission mandates.
- Ground Transport:Diesel and electric van fleets dominate intra-Nordic movements through well-maintained highway networks. Norway's upcoming carbon border adjustments favor operators with documented low-emission credentials.
- Air Freight:Turboprop and narrow-body cargo services serve Norwegian west coast and northern Finnish destinations beyond practical road transit. Payload constraints and fuel costs compress margins on remote zone coverage.
- Rail Transport:Intermodal container movements link major Nordic population centers with continental European gateways. Swedish and Danish rail electrification aligns with EU Green Deal fleet mandates.
- Ocean Freight:Short-sea feeder services connect Danish ports with Swedish and Norwegian coastal distribution points. Transit times exclude ocean freight from time-definite service tiers.
Ground Transport anchors volume; Rail Transport gains share fastest as electrification proceeds.
Customer Type:
Procurement sophistication and sustainability mandates differentiate buyer segments.
- Business-to-Business:Scheduled collection and delivery contracts with manufacturing and wholesale accounts emphasize reliability metrics over velocity. Pharmaceutical and temperature-controlled logistics networks require specialized fleet equipment.
- Business-to-Consumer:Residential delivery windows with recipient presence requirements drive investment in predictive delivery notifications and secure drop points. Population dispersion outside urban corridors inflates per-stop costs.
- E-commerce:Digital retailers with published sustainability commitments prioritize packaging provenance and end-of-life recyclability over unit cost minimization. Recycled corrugated fiber adoption concentrates among Swedish and Danish fashion and electronics merchants.
- Retailers:Brick-and-mortar chains utilize CEP networks for store replenishment and customer order fulfillment from physical inventory. Peak season volume surges strain fixed-asset capacity.
E-commerce commands the steepest expansion trajectory; Business-to-Business provides margin stability.
Package Size:
Payload characteristics determine vehicle fleet composition and sortation technology requirements.
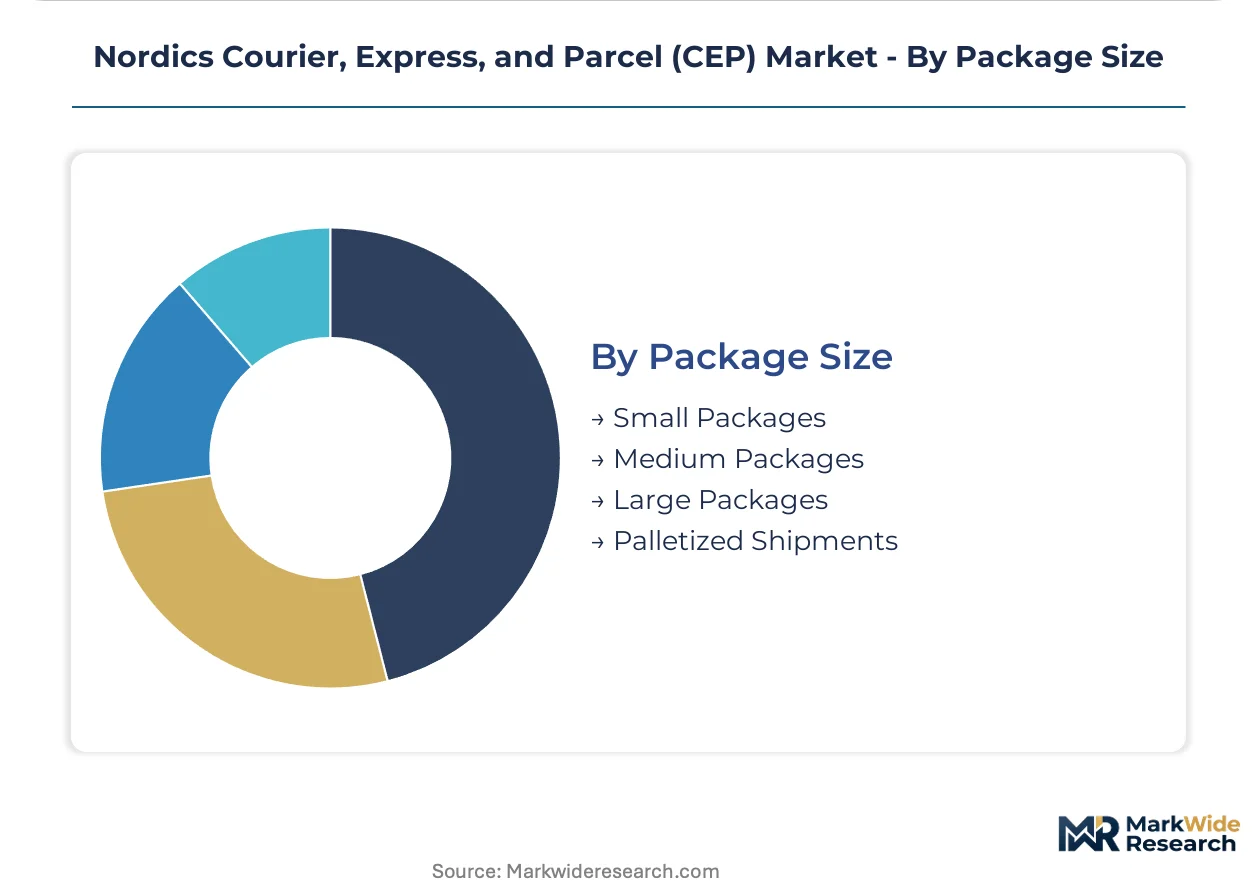
- Small Packages:Document envelopes and single-item e-commerce parcels under two kilograms enable cargo bike and light electric vehicle deployment in Copenhagen, Stockholm, and Oslo zero-emission zones. Municipal parking privileges accelerate modal shift.
- Medium Packages:Standard parcel dimensions dominate automated sortation throughput and occupy the revenue base across Nordic CEP networks. PostNord's state-owned infrastructure optimizes rural coverage for this payload tier.
- Large Packages:Bulky items exceeding standard parcel dimensions require manual handling and specialized vehicle configurations. Furniture and appliance e-commerce drives demand concentration in Swedish urban corridors.
- Palletized Shipments:Unitized freight at parcel network margins competes with dedicated LTL carriers on cost and transit time. Temperature-controlled pharmaceutical pallets face disproportionate EU Green Deal compliance complexity.
Medium Packages generate volume concentration; Small Packages climb the fastest on urban electrification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stockholm's urban logistics incentive zones concentrate CEP investment along Sweden's high-density corridor, with municipal subsidies accelerating micro-fulfillment node placement in designated last-mile districts.
Sweden
Same-day delivery demand from Stockholm-to-Malmö fashion retailers drives automated sortation investment. The Swedish Environmental Protection Agency enforces EU Green Deal fleet electrification deadlines through mandatory operator reporting. Gothenburg's port logistics cluster integrates short-sea feeder services with electric last-mile distribution networks.
Denmark
Copenhagen's zero-emission zone designations displace diesel van economics for cargo bike deployment. The Danish Maritime Authority coordinates short-sea shipping electrification with port infrastructure grants. Aarhus logistics parks attract pharmaceutical cold-chain operators seeking EU-compliant temperature-controlled capacity.
Norway
West coast population dispersion locks air freight dependency for Tromsø and Bergen destinations beyond road transit practicality. Norway's forthcoming carbon border adjustment mechanisms favor operators with documented low-emission fleet credentials. Oslo's congestion charging pilot reshapes hub placement decisions for last-mile operators.
Finland
Northern Finnish e-commerce penetration creates air freight demand for Rovaniemi and Oulu zones outside practical ground coverage. Finnish Transport and Communications Agency Traficom monitors EU Green Deal compliance through vehicle fleet registration databases. Helsinki-Turku corridor density supports electric van route economics for medium-package volumes.
Nordics Courier, Express, and Parcel (CEP) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated postal incumbents dominating rural coverage while gig-economy platforms capture urban peak-season flexibility. The vendor base stratifies across three tiers: state-affiliated universal service providers, global express networks with pharmaceutical specializations, and technology-enabled flexible capacity platforms. Dominant competitive moves include fleet electrification capital commitments and micro-fulfillment node densification in metropolitan zones.
Within the state-affiliated tier, PostNord anchors universal service obligations across Sweden and Denmark through inherited postal infrastructure. Global express specialists DHL Group and FedEx Corporation occupy premium service positions for temperature-controlled and time-definite international movements. Technology-native platforms exemplified by Instabee represent the flexible-capacity archetype, deploying gig-economy courier pools without fixed-asset exposure during e-commerce volume surges.
| Leading Market Players |
|---|
| DHL Group |
| FedEx Corporation |
| PostNord |
| Jetpak Top Holding AB |
| GEODIS |
| DSV A/S |
| United Parcel Service (UPS) |
| Instabee |
| Posten Bring AS |
| Others |
Pricing and Supply Chain Analysis
Horizontal consolidation among Nordic postal operators anchors supply position and pricing power, with PostNord's inherited state infrastructure creating captive last-mile coverage that insulates standard delivery tiers from cost-based competition. This integration pattern compresses rival margins in rural Sweden and Denmark while enabling premium capture in urban corridors where gig-economy platforms lack density.
Pricing Analysis
Volume concentrates in standard delivery while margins cluster in same-day and temperature-controlled tiers. Three-tier pricing structure across premium, standard, and economy levels differentiates by delivery velocity and payload specialization, with pharmaceutical cold-chain commands capturing widest spreads. Cost compression in urban last-mile stems from cargo bike deployment and zero-emission zone mandates. E-commerce retailers exhibit highest price sensitivity; pharmaceutical manufacturers show lowest.
Supply Chain Analysis
EU Green Deal local-content rules for fleet procurement are reshaping sourcing toward European electric vehicle manufacturers and domestic charging infrastructure providers. Vehicle and battery supply concentrates in Germany, Sweden, and the Netherlands. Sortation equipment and telematics software draw from German and US technology clusters. Single-source vulnerability sits with battery cell supply for electric van fleets. Distribution runs through hub-and-spoke networks anchored in Stockholm, Copenhagen, and Oslo metropolitan zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with fleet electrification and micro-fulfillment node ownership as the critical downstream levers players are pursuing to defend margin position.
For Market Incumbents: Extend electrified fleet coverage into Norwegian and Finnish rural territories before regulatory deadlines harden competitive moats. Consolidate pharmaceutical cold-chain certification investments to offset gig-economy platform erosion in urban same-day segments. Lock in charging infrastructure partnerships that preempt rival hub placement.
For New Entrants and Emerging Players: Enter via Swedish urban corridor micro-fulfillment, where Stockholm-to-Malmö density supports asset-light courier pool economics without PostNord's fixed infrastructure burden. Target medium-package B2C residential delivery as the most penetrable white space. Pursue direct retailer API integration as the go-to-market angle.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by global express networks seeking Nordic pharmaceutical specialization. Long-term viability favors operators with documented EU Green Deal compliance and captive last-mile infrastructure in Norway and Finland. Watch Norway's carbon border adjustment implementation timing as the inflection signal for fleet credential valuation.
| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Program | EU Green Deal mandates from the Swedish Environmental Protection Agency force capital reallocation toward battery-electric vans. |
| Micro-Fulfillment Node Densification | Stockholm urban incentive zones subsidize last-mile hub placement for same-day delivery economics. |
| Pharmaceutical Cold-Chain Certification | Temperature-controlled logistics networks face disproportionate compliance complexity under REACH chemical regulations. |
| Gig-Economy Courier Pool Integration | Flexible capacity models absorb Danish and Swedish e-commerce peaks without fixed-asset exposure. |
| Recycled Packaging Material Sourcing | Retailer procurement criteria prioritize post-consumer corrugated fiber over virgin paperboard for sustainability compliance. |
Research Methodology
Trade association filings, EU regulatory databases, and national transport agency statistics formed the secondary backbone, cross-referenced with primary interviews involving fleet operations directors, e-commerce logistics procurement managers, pharmaceutical supply chain leads, and municipal urban planning officers. Bottom-up and top-down triangulation validated volume estimates across service tiers and geographic segments.
Bottom-up modeling aggregated operator fleet disclosures and hub capacity investments, while top-down approaches calibrated against macro trade flows and e-commerce penetration indices. Segmentation dimensions covered service velocity, delivery mode, customer type, and package size, with urban density gradients as the industry-specific overlay. CAGRs were derived from trend extrapolation moderated by regulatory compliance timelines and infrastructure deployment schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU emission mandate enforcement or Norwegian carbon border adjustment implementation delays. Forecasts reflect assumptions on e-commerce volume trajectories and fleet electrification cost curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Russia Third-Party Logistics (3PL) Market
Logistics and Shipping
South Korea Third-Party Logistics (3PL) Market
Logistics and Shipping
Spain 3PL Market
Logistics and Shipping
Chile Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Poland Third Party Logistics (3PL) Market
Logistics and Shipping
GCC Contract Logistics Market
Logistics and Shipping
Russia Courier Service Market
Logistics and Shipping
Armenia Freight and Logistics Market
Logistics and Shipping
Germany Contract Logistics Market
Logistics and Shipping
Global Retail 3PL Market
Logistics and Shipping
Global Dry Bulk Shipping Market
Logistics and Shipping
Spain Pharmaceutical Logistics Market
Logistics and Shipping
UAE Logistics Market
Logistics and Shipping
Global Logistics Market
Logistics and Shipping
Contract Logistics Market
Logistics and Shipping
Australia Freight and Logistics Market