
 Sweden Courier, Express, and Parcel Market | 2026-2036
Sweden Courier, Express, and Parcel Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Courier, Express, and Parcel Market Insights
Sweden is tilting its logistics capacity toward electrified last-mile hubs in Stockholm and Malmö. PostNord AB anchors domestic parcel distribution through its extensive Nordic network. DHL competes on cross-border e-commerce fulfillment, leveraging its European air hub structure. DB Schenker differentiates through integrated supply chain solutions serving manufacturing clients across southern Sweden.
Courier, express, and parcel services encompass time-definite shipment of documents and goods through integrated collection, sorting, and delivery networks operating under contracted service levels. These services rely on hub-and-spoke infrastructure with automated sortation achieving throughput rates exceeding 15,000 parcels per hour at major facilities. Same-day delivery commands premium positioning among urban consumers, while standard delivery retains volume leadership in cost-sensitive segments. International shipping captures the fastest expansion as Swedish exporters prioritize bonded warehouse solutions and streamlined customs brokerage.
Post- och telestyrelsen enforces universal service obligations that mandate nationwide coverage at regulated price points, while the Swedish Transport Agency governs commercial vehicle emissions standards accelerating fleet electrification. EU Green Deal targets for transport decarbonization filter into national procurement rules, pressuring operators to replace diesel vans with electric alternatives. Stakeholders must monitor how carbon border adjustments and evolving battery-electric range capabilities reshape total cost of ownership calculations for rural route economics.
Market Dynamics
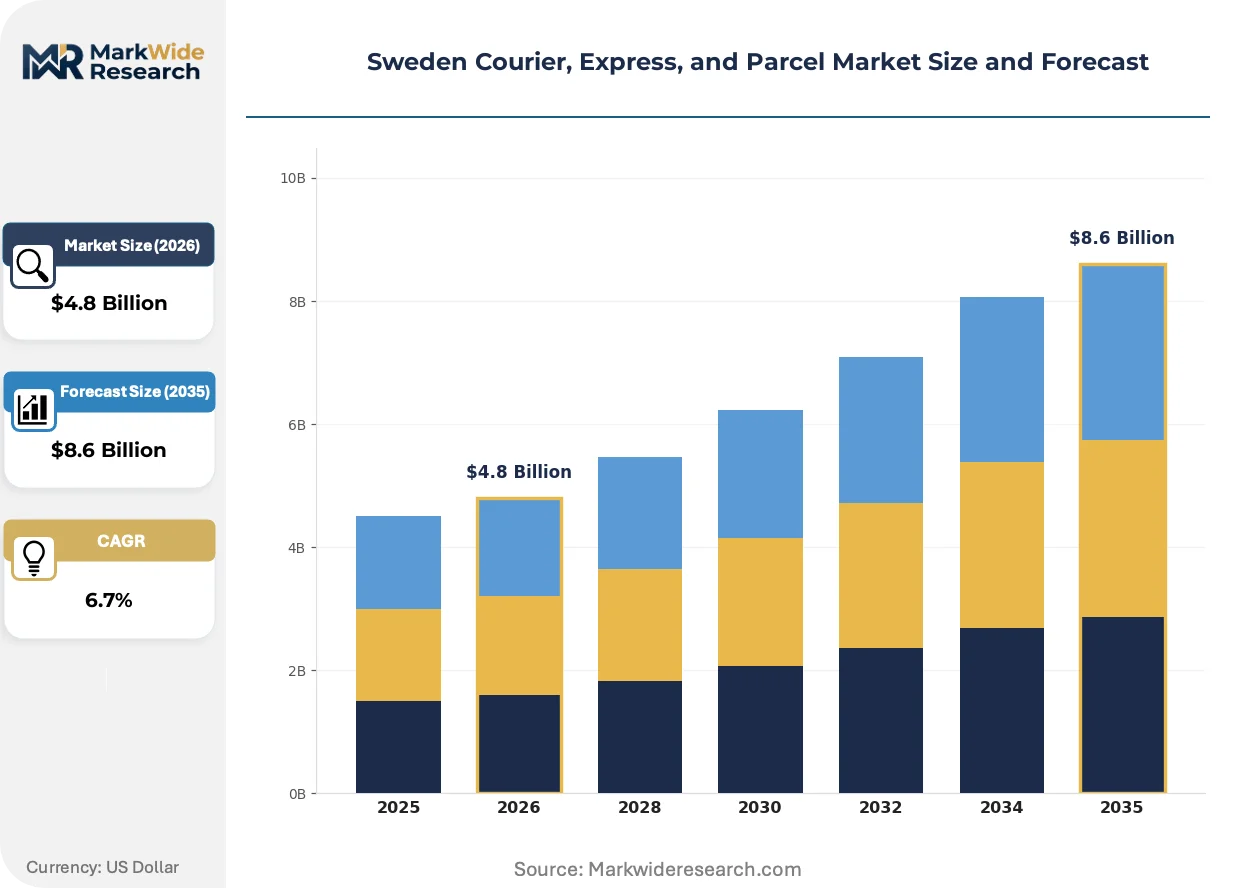
Electrification mandates under the EU Green Deal are compressing diesel fleet economics while Stockholm's urban congestion pricing reshapes last-mile hub placement. Post- och telestyrelsen's universal service obligations lock in baseline coverage costs that commercial operators must cross-subsidize through premium express segments.
Growth Catalysts
- Cross-border e-commerce volumes:Swedish consumers purchasing from German and Polish online retailers are pulling bonded warehouse capacity into Malmö and Gothenburg port zones.
- EU Green Deal transport decarbonization targets:Fleet electrification procurement rules are accelerating battery-electric van deployment on urban routes.
- Automated sortation throughput:Hub facilities achieving parcel processing rates above 15,000 units per hour are compressing per-unit handling costs.
Market Restraints
- Battery-electric range constraints:Rural route economics in Norrland remain tethered to diesel infrastructure due to charging network gaps.
- Regulated universal service pricing:Post- och telestyrelsen's price caps on standard mail create margin compression that operators must absorb.
- Last-mile labor cost structures:Driver wages in the Stockholm metropolitan area outpace automation savings on small-parcel delivery.
Strategic Opportunities
- Carbon border adjustment mechanisms:EU import taxation on embedded emissions creates demand for low-carbon logistics certification.
- Reverse logistics integration:E-commerce return flows into Stockholm consolidation centers enable backhaul revenue capture.
- Micro-fulfillment urban nodes:Dark store conversion in Gothenburg dense districts supports sub-two-hour delivery windows.
Industry Challenges
- Electric vehicle technician scarcity:Fleet maintenance networks lack certified specialists for high-voltage battery systems.
- Legacy warehouse management system integration:Automated sortation hardware requires middleware adaptation with existing inventory platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Courier, Express, and Parcel Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Same-Day Delivery, Next-Day Delivery, Standard Delivery, International Shipping Delivery Mode: Ground, Air, Ocean, Drone Package Type: Envelope, Box, Pallet, Crate End User: Retail, E-Commerce, Healthcare, Manufacturing |
| Companies Covered | UPS, Bring, PostNord AB, Jetpak, DSV, DB Schenker, FedEx, GLS Group, DHL, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Courier, Express, and Parcel Market Trends and Innovations
Parcel networks are reconfiguring around electrified hub-and-spoke infrastructure while regulatory pressure on emissions compresses diesel fleet residual values. Three developments are altering competitive positioning.
Automated parcel sortation is migrating from fixed tilt-tray systems toward modular robotic cell architectures. Mid-sized operators in the Malmö logistics corridor are piloting these configurations to match peak-season throughput without permanent capacity expansion. This migration from rigid automation is compressing the capital threshold for competitive hub operations.
The EU Green Deal's transport decarbonization targets are mandating phased diesel van phase-out across member states. Swedish fleet operators face binding procurement rules that favor battery-electric alternatives in urban access zones. Last-mile providers serving Stockholm's congestion-pricing districts are responding with accelerated depot electrification and on-route fast-charging partnerships.
Consolidation behavior among e-commerce buyers is shifting toward platform-integrated delivery preference settings. Merchants in the Stockholm-Gothenburg-Malmö corridor are embedding carbon-neutral shipping options at checkout, displacing pure cost-based carrier selection. This preference shift is most visible in fashion and consumer electronics verticals where brand sustainability positioning drives logistics procurement.
Sweden Courier, Express, and Parcel Market Segmentation
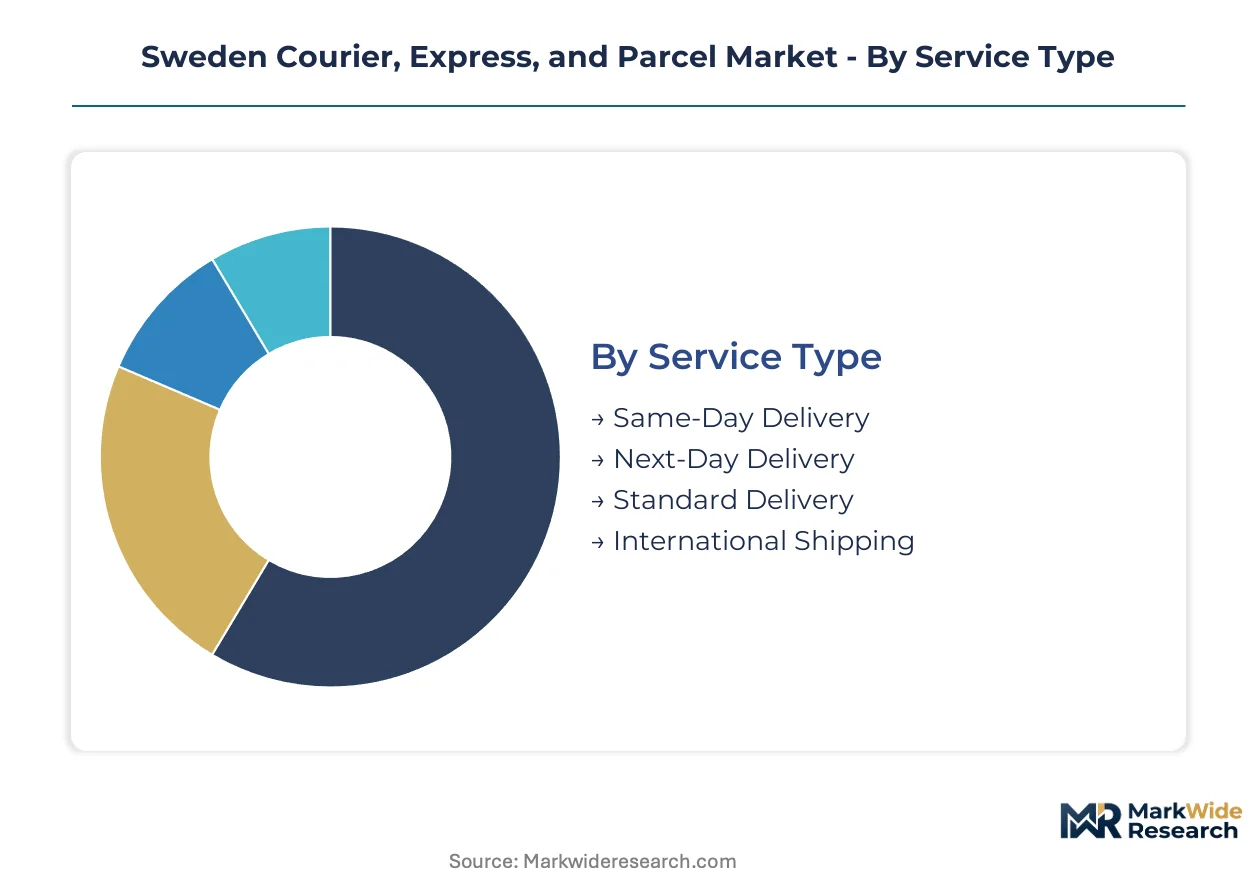
Parcel operators in Sweden optimize network design around service speed tiers and modal economics. Segment-specific infrastructure investments determine margin capture across Stockholm's urban density corridors and Norrland's sparse route structures.
Service Type:
Mature express segments coexist with emerging instant delivery formats as e-commerce platforms recalibrate consumer expectations.
- Same-Day Delivery:Ultra-time-definite service requiring micro-fulfillment nodes within 15 kilometers of recipient concentration. Stockholm's congestion pricing zones and Malmö's cross-border e-commerce hubs concentrate demand from fashion and consumer electronics merchants seeking checkout differentiation.
- Next-Day Delivery:Premium tier leveraging automated sortation facilities achieving throughput rates above 15,000 parcels per hour. Gothenburg's port-adjacent logistics parks anchor this segment for German and Polish retail imports.
- Standard Delivery:Cost-optimized ground transport with 2-5 day transit windows. Post- och telestyrelsen's universal service obligations intersect here, mandating nationwide coverage at regulated price points that compress operator margins.
- International Shipping:Bonded warehouse solutions and streamlined customs brokerage for Swedish exporters. Malmö's proximity to continental Europe and Gothenburg's deep-water port infrastructure concentrate cross-border volume.
Standard Delivery retains volume leadership; Same-Day Delivery holds the steepest expansion curve.
Delivery Mode:
Modal selection hinges on route distance, payload density, and EU Green Deal emissions compliance timelines.
- Ground:Dominant mode for domestic parcel flows with electrified van fleets penetrating Stockholm and Malmö urban cores. Battery-electric range constraints preserve diesel economics in Norrland rural territories.
- Air:Time-critical international express linking Swedish shippers to DHL's European air hub structure. Premium positioning reflects fuel cost pass-through and slot scarcity at Stockholm Arlanda cargo terminals.
- Ocean:Consolidated containerized freight for non-urgent bulk movements. Gothenburg port automation investments are compressing dwell times for palletized e-commerce inbound.
- Drone:Experimental last-mile modality piloted in Stockholm archipelago zones with limited road access. Regulatory frameworks under the Swedish Transport Agency govern beyond-visual-line-of-sight operations.
Ground transport retains volume leadership; Drone delivery holds the steepest expansion curve.
Package Type:
Physical form factor dictates handling equipment, vehicle cube utilization, and damage liability structures.
- Envelope:Document and small-item format dominated by express carriers. Automated sortation compatibility and low damage rates sustain margin premiums in business-to-business corridors.
- Box:Standard e-commerce parcel format driving hub infrastructure design. Stockholm-Gothenburg-Malmö throughput concentration justifies tilt-tray and robotic cell capital deployment.
- Pallet:Business-to-business freight requiring forklift-capable vehicles and dock-height infrastructure. Manufacturing clients in southern Sweden generate recurring volume through integrated supply chain contracts.
- Crate:Specialized handling for high-value or fragile goods. Healthcare and precision manufacturing end-users in Gothenburg's industrial zones specify this format for temperature-sensitive or shock-prohibited cargo.
Box format retains volume leadership; Crate handling holds the steepest expansion curve.
End User:
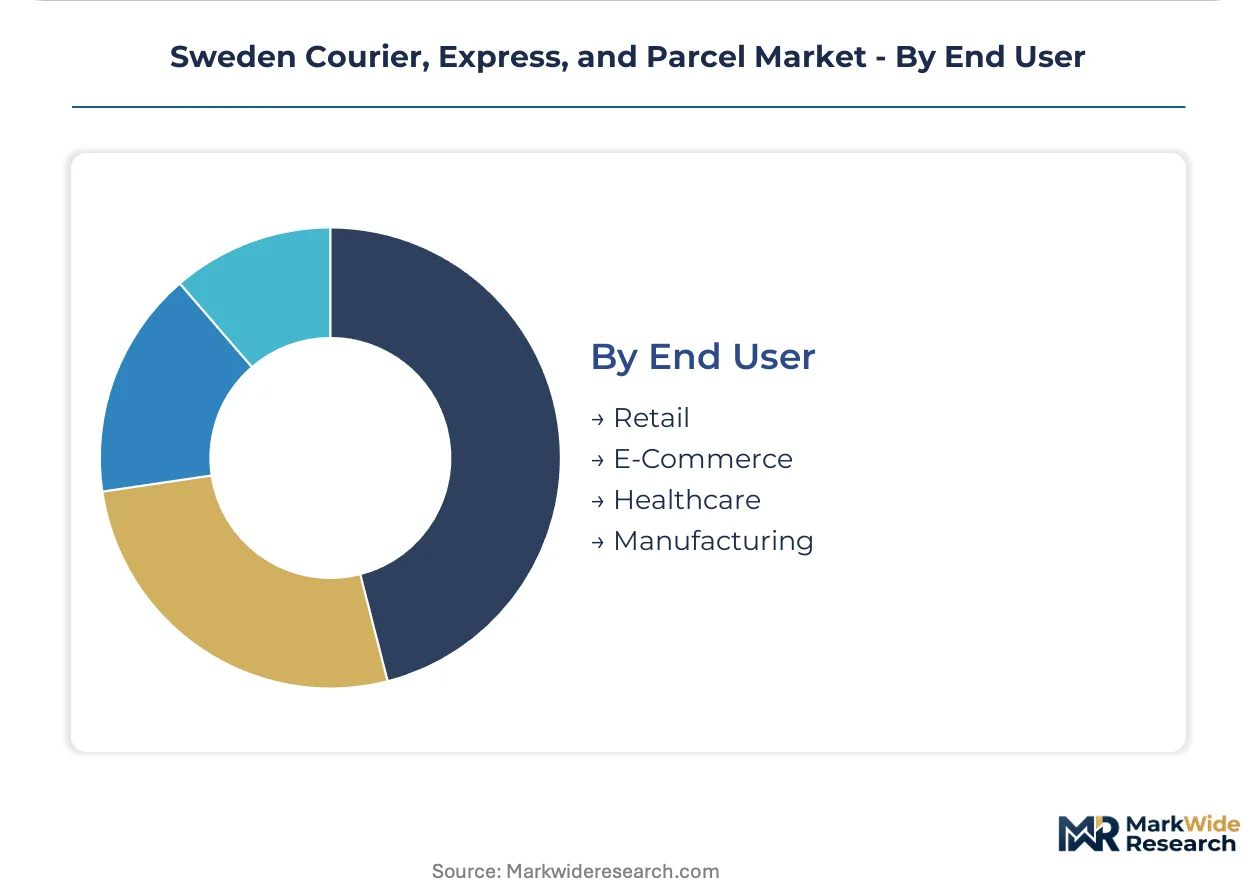
Vertical-specific service requirements fragment procurement patterns across the three-city corridor.
- Retail:Brick-and-mortar replenishment with predictable scheduling and backhaul optimization potential. Fashion retailers in Stockholm prioritize carbon-neutral shipping options at checkout.
- E-Commerce:Surge-volume dynamics with extreme seasonality and return-flow complexity. Platform-integrated delivery preference settings are displacing pure cost-based carrier selection.
- Healthcare:Temperature-controlled and time-critical shipments governed by patient safety protocols. Stockholm's hospital networks and pharmaceutical distributors specify validated cold chain capabilities.
- Manufacturing:Just-in-time component flows with penalty structures for production line stoppage. Automotive and electronics assemblers in western Sweden demand bonded warehouse solutions and customs brokerage integration.
E-Commerce retains volume leadership; Healthcare logistics holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hub capacity clusters along the Stockholm-Gothenburg-Malmö corridor where automated sortation facilities process the highest parcel throughput. Post- och telestyrelsen's universal service obligations extend coverage mandates into Norrland's sparse route structures. Sub-regional specialization reflects urban density gradients and cross-border proximity advantages.
Stockholm Metropolitan Area
Congestion pricing zones and electrified last-mile hubs concentrate same-day delivery demand from fashion and consumer electronics merchants. The Swedish Transport Agency governs commercial vehicle emissions standards that accelerate battery-electric van deployment. E-commerce platforms in Stockholm's dense districts embed carbon-neutral shipping options at checkout, displacing cost-based carrier selection.
Gothenburg
Port-adjacent logistics parks anchor next-day delivery infrastructure for German and Polish retail imports. EU Green Deal procurement rules filter into national fleet replacement timelines for urban access zones. Automated sortation facilities in Gothenburg's industrial zones achieve throughput rates above 15,000 parcels per hour, compressing per-unit handling costs for bonded warehouse solutions.
Malmö
Cross-border e-commerce volumes pull bonded warehouse capacity into port zones serving continental European retail flows. Post- och telestyrelsen enforces price caps on standard mail that create margin compression operators must absorb through premium express segments. Malmö's proximity to Denmark enables integrated Nordic network routing for PostNord AB's domestic parcel distribution.
Norrland
Rural route economics remain tethered to diesel infrastructure due to battery-electric range constraints and charging network gaps. The Swedish Transport Agency's emissions standards face implementation challenges in territories below Arctic Circle population thresholds. Sparse manufacturing and retail density limit parcel throughput to levels below automated sortation capital deployment thresholds.
Southern Sweden Manufacturing Belt
Just-in-time component flows from automotive and electronics assemblers generate recurring volume through integrated supply chain contracts. DB Schenker differentiates through bonded warehouse solutions and customs brokerage integration serving western Sweden's industrial zones. Manufacturing clients specify pallet and crate formats requiring forklift-capable vehicles and dock-height infrastructure.
Sweden Courier, Express, and Parcel Market Competitive Landscape
National postal incumbents and global integrators split the market between universal service obligations and premium express positioning. PostNord AB anchors domestic distribution through Nordic network density while DHL and FedEx compete on cross-border e-commerce fulfillment. Two strategic archetypes dominate: integrated supply chain specialists serving manufacturing clients, and platform-integrated last-mile providers capturing urban consumer demand. Competitive moves center on depot electrification partnerships and micro-fulfillment node placement in congestion-pricing districts.
Among Nordic-origin operators, PostNord AB represents the universal service archetype with extensive last-mile coverage obligations. DHL and FedEx occupy positions as global integrators leveraging European air hub structures for time-critical international express. DB Schenker exemplifies the integrated supply chain specialist archetype through manufacturing-focused solutions in southern Sweden's industrial corridors.
| Leading Market Players |
|---|
| UPS |
| Bring |
| PostNord AB |
| Jetpak |
| DSV |
| DB Schenker |
| FedEx |
| GLS Group |
| DHL |
| Others |
Pricing and Supply Chain Analysis
Stockholm's electrified last-mile hub concentration compresses per-unit handling costs while amplifying pricing power for premium same-day tiers. Post- och telestyrelsen's universal service obligations lock in baseline coverage costs that operators cross-subsidize through express segment premiums.
Pricing Analysis
Post- och telestyrelsen's universal service obligations dictate the pricing tier structure across standard, express, and same-day delivery segments. Three-tier pricing structure across premium, standard, and economy levels differentiates by transit speed and carbon certification grade. Cost compression in standard delivery is intensifying because regulated price caps limit pass-through of fleet electrification investments. E-commerce merchants represent the most price-sensitive buyer segment, while healthcare and manufacturing clients exhibit lowest sensitivity due to penalty structures for delivery failure.
Supply Chain Analysis
Tariff exposure between Germany and Sweden dominates cross-border e-commerce fulfillment economics in the Malmö corridor. Vehicle fleet supply concentrates in Germany, the Netherlands, and Belgium for electric van procurement. Battery cell and charging infrastructure components draw from Chinese and South Korean manufacturing. Single-source vulnerability in high-voltage technician certification programs threatens maintenance network expansion. Distribution runs through hub-and-spoke configurations anchored by automated sortation facilities in Stockholm, Gothenburg, and Malmö.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
E-commerce platform consolidation in the Stockholm-Gothenburg-Malmö corridor shifts procurement power toward fewer buyers with volume-based negotiating leverage. Merchant embedding of carbon-neutral checkout options accelerates carrier switching costs.
For Market Incumbents: Build electrified depot networks as a geographic moat against diesel-dependent challengers. Accelerate fast-charging partnerships in Stockholm congestion-pricing zones to capture same-day delivery premiums. Secure bonded warehouse capacity in Gothenburg port zones before cross-border volume peaks. Vertical integration into reverse logistics consolidation centers captures backhaul revenue from e-commerce return flows. For New Entrants and Emerging Players: Pursue micro-fulfillment node placement in Malmö's dense districts underserved by incumbent depot coverage. Target healthcare logistics as the most penetrable vertical due to cold chain capability scarcity and validated service requirements. Position around carbon-neutral certification as the go-to-market angle for fashion and consumer electronics merchants. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-anchored consolidation play because electrified hub capacity scarcity will concentrate volume among operators with deployed capital. Acquisition targets should display automated sortation throughput above 15,000 parcels per hour and established fast-charging partnerships. Monitor EU Green Deal procurement rule acceleration as the signal to watch for fleet replacement inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Depot Electrification Partnership | Stockholm congestion pricing zones mandate battery-electric fleet access for premium same-day delivery positioning. |
| Automated Sortation Deployment | Hub facilities achieving 15,000 parcels per hour compress per-unit handling costs in Gothenburg logistics parks. |
| Bonded Warehouse Expansion | Malmö port-adjacent capacity captures German and Polish retail import flows for next-day delivery tiers. |
| Reverse Logistics Integration | Stockholm consolidation centers enable backhaul revenue capture from e-commerce return flows. |
| Carbon Certification Program | EU Green Deal procurement rules favor certified operators in public sector and large merchant contracts. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with logistics operations directors, fleet procurement managers, e-commerce platform supply chain leads, and Post- och telestyrelsen regulatory affairs officers; and secondary validation through Swedish Transport Agency emissions filings, EU customs trade databases, and operator sustainability disclosures. Bottom-up volume modeling triangulated against top-down market sizing from postal regulatory statistics.
Forecast inputs considered service type segmentation by speed tier, delivery mode by vehicle propulsion architecture, package type by handling equipment requirements, and end-user vertical by cold chain and customs integration needs. CAGRs derived from trend extrapolation of e-commerce penetration rates and fleet electrification procurement timelines across the projection horizon. Battery-electric range capability curves and charging network density assumptions shaped rural route economics modeling.
Sensitivities concentrate around EU Green Deal enforcement acceleration, carbon border adjustment mechanism implementation, and battery technology cost curves. Forecasts reflect documented assumptions on merchant checkout integration speed and congestion pricing zone expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Air Cargo Container Market
Logistics and Shipping
Thailand E-Commerce Logistics Market
Logistics and Shipping
Global Retail 3PL Market
Logistics and Shipping
US Courier, Express, and Parcel Market
Logistics and Shipping
Saudi Arabia Contract Logistics Market
Logistics and Shipping
GCC Automotive Logistics Market
Logistics and Shipping
Terminal Tractors Market
Logistics and Shipping
ISO Shipping Container Market
Logistics and Shipping
Egypt 3PL Market
Logistics and Shipping
Asia-Pacific Shipping Agency Services Market
Logistics and Shipping
China Shipping Agency Services Market
Logistics and Shipping
Poland Cold Chain Logistics Market
Logistics and Shipping
Food Delivery Logistic Market
Logistics and Shipping
China Digital Freight Forwarding Market
Logistics and Shipping
Saudi Arabia Secure Logistics Market
Logistics and Shipping
Europe Domestic Courier Market