
 India less than Truckload Road Freight Transport Market | 2026-2036
India less than Truckload Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
India less than Truckload Road Freight Transport Market Foresight
Compressed natural gas is pivoting from niche alternative to mainstream fuel across the India less than Truckload Road Freight Transport Market, cutting per-kilometer operating costs by nearly half versus diesel for urban pickup routes. Delhivery Limited leverages its technology-first hub-and-spoke infrastructure to dominate e-commerce last-mile connectivity. VRL Logistics Limited anchors its position through extensive terminal ownership across South and West India. Safexpress Private Limited differentiates through specialized handling capabilities for high-value electronics and pharmaceutical cargo.
India less than Truckload Road Freight Transport involves consolidation of multiple shippers' partial loads into shared truck capacity, typically covering shipments between kilograms and several tons with hub-based sorting and multi-stop routing. Cold chain service type commands premium pricing due to specialized reefer infrastructure and temperature compliance requirements, while express delivery segments capture fastest volume expansion from e-commerce fulfillment pressures. GPS tracking and route optimization technologies within the technology segment are shifting from competitive differentiators to baseline operational requirements as fuel efficiency and delivery predictability become margin-critical.
The Ministry of Road Transport and Highways enforces axle load norms and vehicle fitness standards that directly constrain fleet composition and replacement cycles for LTL operators. BIS certification requirements for automotive components and CDSCO cold chain guidelines for pharmaceuticals shape specialized equipment investments and service capabilities. Fleet operators, e-commerce platforms, and third-party logistics providers must weigh capital deployment toward dedicated fleet capacity against asset-light brokerage models as regulatory compliance costs escalate and fuel transition timelines compress.
Market Dynamics
Fleet operators across India are compressing turnaround times at sorting hubs as e-commerce fulfillment windows tighten from 48 hours to same-day delivery in metropolitan corridors.
Growth Catalysts
- Bharatmala Pariyojana:This highway expansion program is reducing interstate transit times by 25-30% on key freight corridors connecting Mumbai, Delhi, and Chennai.
- Compressed natural gas infrastructure:Urban pickup routes in Delhi NCR and Mumbai are converting to CNG as fuel station density reaches viability thresholds for daily operations.
- Pharmaceutical cold chain:CDSCO temperature compliance mandates for biologics distribution are forcing investment in reefer capacity that serves adjacent high-value cargo segments.
Market Restraints
- Diesel price volatility:Fuel constitutes 55-60% of operating costs for LTL operators, with no effective hedging mechanisms available in Indian commodity markets.
- Driver shortage concentration:Long-haul route availability is collapsing in Maharashtra and Karnataka as commercial driving licenses fail to keep pace with fleet expansion.
- Axle load enforcement:Ministry of Road Transport norms are forcing premature replacement of 9-12 year old vehicles that previously operated at overload margins.
Strategic Opportunities
- Northeast corridor penetration:Assam and Tripura remain underserved by organized LTL networks despite improving road connectivity through the Siliguri corridor.
- PLI scheme alignment:Electronics manufacturing clusters in Tamil Nadu and Uttar Pradesh are generating predictable component flows that reward dedicated lane contracts.
- GPS-optimization convergence:Real-time tracking integration with dynamic routing engines is enabling guaranteed delivery windows that command 15-20% rate premiums.
Industry Challenges
- Hub automation talent gap:Conveyor systems and scan-sort infrastructure require maintenance technicians that existing workforce development pipelines cannot supply.
- Multi-state permit fragmentation:National Permit System digitization remains incomplete, forcing operational teams to manage 28 distinct state-level compliance interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India less than Truckload Road Freight Transport Market |
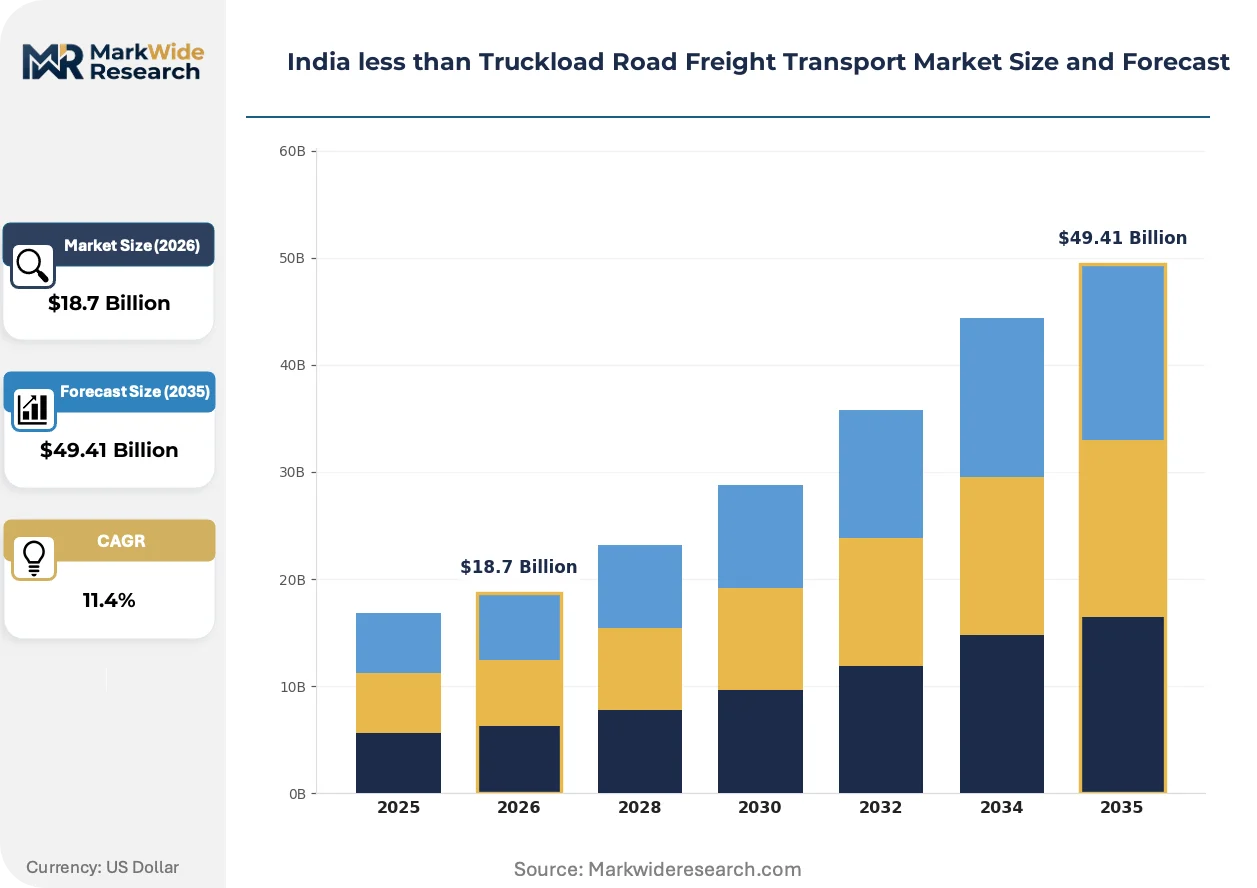
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cold Chain, Express Delivery, Dedicated Fleet, Flatbed Transport End User: Manufacturing, E-commerce, Retail, Pharmaceuticals Technology: Telematics, GPS Tracking, Route Optimization, Freight Management Delivery Mode: Door-to-Door, Terminal-to-Terminal, Scheduled Services, On-Demand |
| Companies Covered | Delhivery Limited, Transport Corporation of India Limited, VRL Logistics Limited, Mahindra Logistics Limited, Gati Limited, Safexpress Private Limited, Blue Dart Express Limited, BLR Logistiks (India) Private Limited, ABC India Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India less than Truckload Road Freight Transport Market Shifts & Advancements
Digital freight matching platforms are consolidating previously fragmented owner-operator capacity into bookable networks, compressing the traditional broker-mediated spot market.
Telematics integration with engine control modules is unifying fuel consumption monitoring, driver behavior scoring, and predictive maintenance alerts into single-dashboard fleet management. Third-party logistics providers operating 500+ vehicle fleets are mandating these systems as procurement preconditions for contract awards. This unification is compressing the competitive advantage window for early technology adopters as baseline connectivity becomes table stakes.
BIS certification requirements for automotive components are mandating traceability systems that capture origin documentation through every hub touchpoint. Tier-1 suppliers to OEMs are extending these requirements downstream to LTL partners handling inbound production parts. Component manufacturers in Pune and Manesar clusters are responding by dedicating specific terminal capacity to certified-lane operations.
Shippers are unbundling transportation from warehousing contracts that previously locked them into single-provider arrangements. E-commerce platforms in Bengaluru and Hyderabad are maintaining active relationships with three to four LTL operators per lane to ensure capacity redundancy during peak cycles. This fragmentation is most visible in apparel and electronics verticals where inventory velocity tolerates no single-point failure.
India less than Truckload Road Freight Transport Market Segmentation
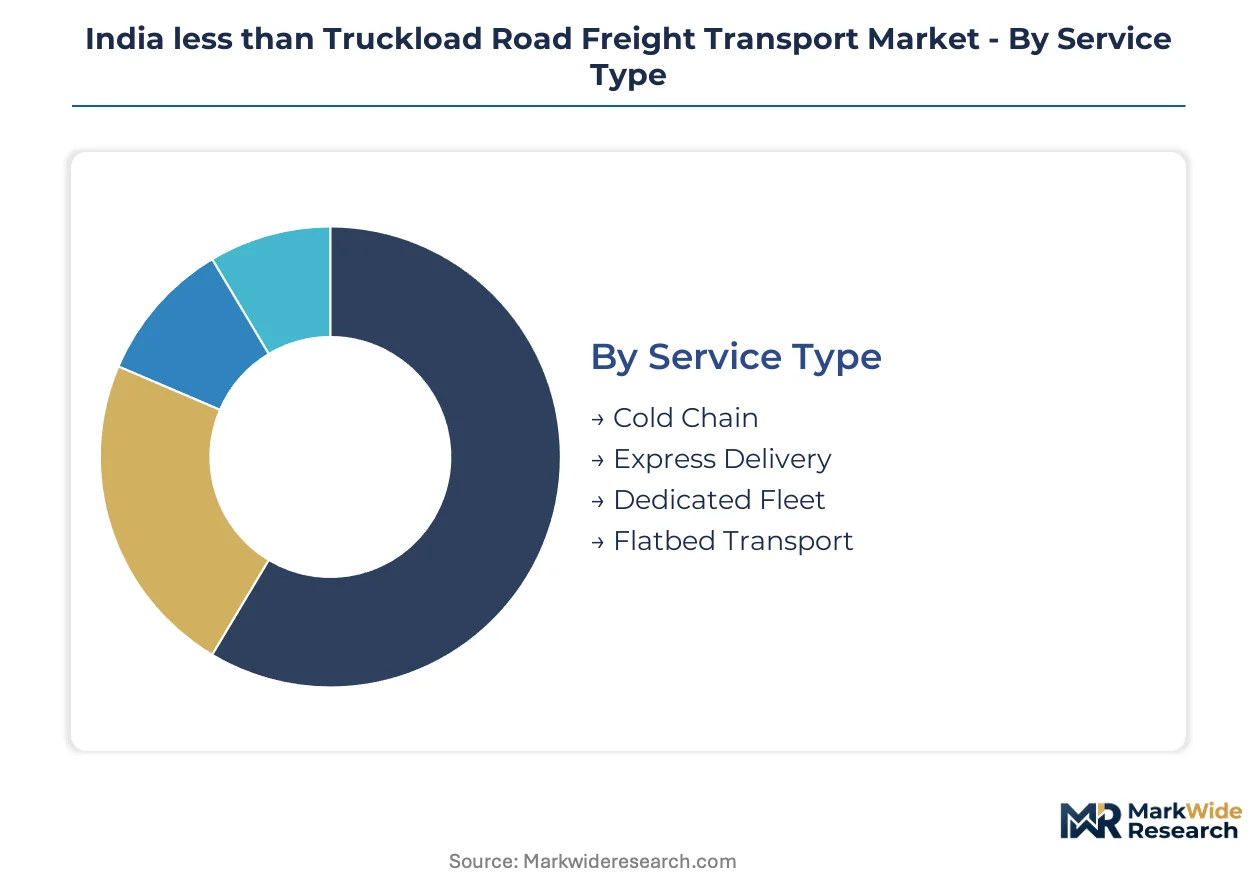
Segmentation in the India less than Truckload Road Freight Transport Market reveals how specialized infrastructure investments and regulatory compliance requirements create distinct competitive arenas. Each axis reflects different capital intensity thresholds and margin structures that shape operator positioning.
Service Type:
Temperature control capabilities and delivery velocity specifications define the technology hierarchy across service tiers.
- Express Delivery:Time-definite shipments with hub-based sorting and multi-stop routing achieve 24-48 hour delivery windows through dedicated lane networks. E-commerce fulfillment pressures in Mumbai, Delhi, and Bengaluru corridors are compressing these windows toward same-day service. Express Delivery leads on momentum.
- Cold Chain:Reefer-equipped vehicles maintain pharmaceutical and perishable cargo within CDSCO-mandated temperature bands through continuous monitoring and backup power systems. Biologics distribution requirements in Gujarat and Maharashtra clusters drive premium pricing multiples. Cold Chain leads on scale.
- Dedicated Fleet:Captive vehicle allocation for single-shipper accounts provides schedule certainty and brand-controlled delivery experience. Electronics manufacturing clusters in Tamil Nadu under PLI scheme incentives generate predictable volume commitments.
- Flatbed Transport:Open-deck capacity serves industrial machinery and construction materials with oversized load accommodations. Steel and cement dispatch from Jharkhand and Chhattisgarh mines relies on this segment for irregular dimensional cargo.
Cold Chain commands the steepest expansion trajectory among premium service tiers; Express Delivery captures volume scale through platform economics.
End User:
Customer procurement sophistication and inventory velocity requirements determine service bundling and contract structures.
- E-commerce:Platform-driven fulfillment networks demand API-integrated booking, real-time visibility, and flexible capacity scaling across peak cycles. Bengaluru and Hyderabad marketplaces maintain redundant operator relationships to mitigate single-point failure risk. E-commerce leads on momentum.
- Pharmaceuticals:CDSCO compliance mandates for temperature documentation and chain-of-custody traceability require specialized handling protocols. Biologics manufacturers in Hyderabad and Pune clusters enforce BIS-certified lane operations for inbound production materials. Pharmaceuticals leads on margin.
- Manufacturing:Just-in-time component flows from automotive and electronics clusters in Manesar, Pune, and Sri City reward dedicated lane contracts with volume guarantees.
- Retail:Seasonal inventory replenishment and store distribution networks prioritize cost efficiency over velocity for non-perishable merchandise.
E-commerce is reshaping procurement patterns through platform intermediation; Pharmaceuticals maintains the highest contract renewal rates.
Technology:
Data capture density and algorithmic decision scope separate baseline connectivity from competitive differentiation.
- GPS Tracking:Real-time location transmission enables customer-facing delivery windows and exception management. Third-party logistics procurement preconditions now mandate this capability as table stakes across 500+ vehicle fleet operators. GPS Tracking leads on scale.
- Route Optimization:Dynamic routing engines integrate traffic, fuel station locations, and delivery time constraints to minimize per-kilometer costs. Delhi NCR and Mumbai urban pickup routes achieve 12-15% efficiency gains through CNG station proximity algorithms. Route Optimization leads on momentum.
- Telematics:Engine control module integration unifies fuel consumption, driver behavior scoring, and predictive maintenance alerts into unified fleet management dashboards.
- Freight Management:Digital freight matching platforms consolidate fragmented owner-operator capacity into bookable networks, compressing traditional broker-mediated spot markets.
GPS Tracking has achieved universal deployment among organized operators; Route Optimization is gaining share fastest through fuel cost pressures.
Delivery Mode:
Network topology and customer interface intensity define operational cost structures and pricing flexibility.
- Door-to-Door:Direct pickup and delivery without intermediate handling minimizes damage risk and transit time for high-value electronics and pharmaceutical cargo. Last-mile labor costs in dense urban corridors consume disproportionate cost share. Door-to-Door leads on scale.
- Scheduled Services:Fixed-departure lane operations with published timetables enable shipper planning certainty and vehicle utilization optimization on trunk routes. Bharatmala corridor improvements support 25-30% transit time compression on Mumbai-Delhi-Chennai axes. Scheduled Services leads on efficiency.
- Terminal-to-Terminal:Shipper-managed first and last mile with operator-handled line-haul reduces cost for price-sensitive bulk commodities.
- On-Demand:Ad-hoc capacity activation through digital platforms serves spot market requirements with premium pricing for urgency.
Door-to-Door captures the highest revenue per shipment; Scheduled Services is expanding most quickly through manufacturing cluster integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's manufacturing and port infrastructure generates the densest LTL cargo flows across India, with Mumbai-Pune industrial corridor serving as the primary freight gravity center for western India distribution networks.
Maharashtra
Automotive component manufacturing in Chakan and Talegaon clusters, combined with JNPT port container traffic, sustains continuous LTL demand for inbound parts and outbound finished goods. The state's Motor Vehicles Department enforces axle load compliance through automated weighbridge networks on Mumbai-Pune Expressway. Pune-based electronics manufacturers under PLI scheme incentives are contracting dedicated lane capacity for component replenishment.
Gujarat
Pharmaceutical manufacturing in Ahmedabad-Vadodara belt and Mundra port cargo movements create specialized cold chain and express delivery requirements. CDSCO's temperature compliance mandates for biologics distribution force reefer infrastructure investments across the region. Sanand automotive cluster suppliers are mandating BIS-certified lane operations for production material flows.
Karnataka
Bengaluru's e-commerce platform concentration and electronics manufacturing in Sri City corridor generate high-velocity express delivery demand with compressed fulfillment windows. The state's commercial tax department maintains distinct permit requirements that complicate interstate fleet routing. Hosur-Tumkur manufacturing belt is experiencing driver shortage concentration as fleet expansion outpaces license issuance.
Tamil Nadu
PLI scheme electronics manufacturing clusters in Sriperumbudur and Oragadam generate predictable component flows rewarding dedicated lane contracts. State highway development under Chennai Peripheral Ring Road project is improving last-mile connectivity to manufacturing zones. Coimbatore's automotive component suppliers are unbundling transportation from warehousing contracts to maintain multi-operator redundancy.
Telangana
Hyderabad's pharmaceutical manufacturing base and emerging data center equipment logistics create dual demand streams for temperature-controlled and high-value cargo handling. The state's single-window clearance system for commercial vehicles reduces permit processing friction relative to neighboring regions. Genome Valley biologics producers are enforcing CDSCO chain-of-custody documentation requirements downstream to LTL partners.
India less than Truckload Road Freight Transport Market Competitive Landscape
Capacity expansion dominates the current landscape as operators deploy hub-and-spoke infrastructure to capture e-commerce fulfillment volumes. The market structure shows moderate consolidation around technology-enabled platforms and asset-heavy regional specialists, with long-tail fragmentation among owner-operators. Three strategic archetypes have emerged: technology-first integrators, terminal-owning regional anchors, and specialized handlers of high-value cargo. M&A activity concentrates on digital freight platforms and cold chain capability acquisitions, while strategic partnerships between fleet operators and e-commerce platforms lock in dedicated capacity commitments.
Among the technology-first integrators, Delhivery Limited exemplifies platform-driven network economics with API-integrated booking systems. VRL Logistics Limited anchors the terminal-owning archetype through extensive infrastructure ownership across South and West India. Safexpress Private Limited occupies the specialized handler position, representing high-value cargo expertise through pharmaceutical and electronics handling protocols. These three patterns illustrate how capital deployment choices—technology infrastructure, physical terminals, or specialized equipment—create distinct competitive positioning within the same market.
| Leading Market Players |
|---|
| Delhivery Limited |
| Transport Corporation of India Limited |
| VRL Logistics Limited |
| Mahindra Logistics Limited |
| Gati Limited |
| Safexpress Private Limited |
| Blue Dart Express Limited |
| BLR Logistiks (India) Private Limited |
| ABC India Limited |
| Others |
Supply & Pricing Matrix
CDSCO-certified cold chain lanes command 40-60% rate premiums over standard LTL services, bifurcating the market into compliance-gated premium tiers and price-competitive commodity flows with divergent fleet investment requirements and hub infrastructure configurations. This certification ladder shapes both customer procurement patterns and operator capital deployment, as pharmaceutical shippers in Gujarat and Maharashtra enforce temperature documentation protocols that smaller operators cannot satisfy.
Pricing Analysis
Fuel cost pass-through mechanisms dominate LTL pricing structures, with diesel and CNG price movements translating directly to per-kilometer tariffs within 30-45 day adjustment windows. Price differentiation rests on certification grade—BIS-certified lanes for automotive components and CDSCO-compliant cold chain services—and volume scale, with dedicated fleet contracts securing 12-18% discounts against spot market rates. Cost compression in express delivery segments is intensifying because e-commerce platforms are consolidating procurement volumes through API-integrated booking systems. Third-party logistics providers operating 500+ vehicle fleets exhibit the lowest price sensitivity, while owner-operators in the spot market face the highest margin pressure.
Supply Chain Analysis
BIS certification requirements for automotive components are gating supplier qualification, forcing Tier-1 manufacturers in Pune and Manesar to extend traceability mandates downstream to LTL partners handling inbound production materials. Manufacturing inputs draw from steel and cement dispatch from Jharkhand and Chhattisgarh mines, electronics components from Tamil Nadu PLI scheme clusters, and pharmaceutical biologics from Hyderabad Genome Valley. Single-source vulnerability concentrates in reefer equipment supply, where specialized vehicle chassis and temperature monitoring systems rest on limited domestic production capacity. Distribution runs through hub-and-spoke networks with Mumbai-Pune, Delhi NCR, and Bengaluru-Chennai corridors serving as primary sorting gravity centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India less than Truckload Road Freight Transport Market has entered a late-cycle quality phase where CDSCO compliance capabilities and GPS-integrated route optimization separate viable operators from margin-compressed commodity players. Pharmaceutical cold chain specifications are pulling demand toward certified handlers with documented temperature custody protocols.
For Market Incumbents: Acquire reefer fleet capacity and temperature monitoring infrastructure to capture pharmaceutical biologics distribution mandates from Genome Valley and Ahmedabad-Vadodara clusters. Digital freight matching platforms threaten traditional broker-mediated spot market revenues, making API integration and real-time visibility dashboards essential defensive investments. Secure dedicated lane contracts with PLI scheme electronics manufacturers in Tamil Nadu and Uttar Pradesh to lock in predictable volume commitments against cyclical downturns. For New Entrants and Emerging Players: The 25-30% rate gap between premium certified lanes and economy spot markets creates entry opportunity for mid-tier operators investing in selective certification capabilities. Northeast corridor penetration into Assam and Tripura offers the most penetrable geography, as organized LTL networks remain underdeveloped despite Siliguri corridor road improvements. A go-to-market angle anchored on CNG-powered urban pickup fleets in Delhi NCR and Mumbai can capture e-commerce last-mile contracts with lower operating costs than diesel-dependent incumbents. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented owner-operator capacity faces technology-enabled platform competition and escalating compliance costs. Long-term viability favors asset-light digital freight platforms with network effects or specialized handlers with irreplaceable certification credentials. Acquisition target archetypes include regional terminal owners in South and West India with established lane density, and cold chain operators with CDSCO-audited infrastructure. Watch for inflection when national permit system digitization completes, eliminating multi-state compliance friction and accelerating organized sector capture.| Strategic Initiative | Industry Significance |
|---|---|
| CNG Fleet Conversion | Delhi NCR and Mumbai operators halve per-kilometer fuel costs against diesel benchmarks. |
| Hub Automation Investment | Conveyor and scan-sort infrastructure compresses turnaround times for same-day delivery windows. |
| Cold Chain Certification | CDSCO compliance opens biologics distribution from Genome Valley and Ahmedabad clusters. |
| API Integration Development | Real-time booking and visibility systems secure e-commerce platform procurement preconditions. |
| Northeast Corridor Expansion | Assam and Tripura road improvements enable first-mover advantage in underserved markets. |
Research Methodology
Bottom-up e-commerce and pharmaceutical shipper modeling reconciled against top-down fleet capacity and fuel consumption tracking forms the analytical core of this study. Primary interviews with logistics procurement officers at third-party logistics providers, fleet operations directors, e-commerce platform supply chain managers, and CDSCO compliance auditors were validated against secondary sources including Ministry of Road Transport axle load enforcement records, Bharatmala Pariyojana project disclosures, BIS certification databases, and PLI scheme beneficiary announcements.
Historical trendline analysis of LTL tonnage flows, fleet utilization rates, and fuel price elasticity established baseline growth trajectories across the projection horizon. Segmentation dimensions modeled include service type, end-user vertical, technology adoption tier, and delivery mode topology, with CAGRs derived from regression analysis against highway infrastructure investment schedules and manufacturing cluster output forecasts. Industry-specific inputs incorporated e-commerce fulfillment window compression rates and pharmaceutical cold chain compliance cost curves.
Caveats apply where diesel price volatility, driver shortage concentration in Maharashtra and Karnataka, or accelerated CNG infrastructure rollout could materially shift the outlook. Forecasts reflect assumptions regarding Bharatmala corridor completion timelines and PLI scheme manufacturing volume commitments. A model refresh is warranted upon material change in national permit system digitization progress or CDSCO biologics distribution mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Egypt Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Latin America Contract Logistics Market
Logistics and Shipping
Singapore 3PL Market
Logistics and Shipping
Retail Logistics Market
Logistics and Shipping
Global 5PL Solutions Market
Logistics and Shipping
Intralogistics Containers Market
Logistics and Shipping
South America Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
US Retail Logistics Market
Logistics and Shipping
Refurbishment and Repair Logistics Orchestration Platforms Market
Logistics and Shipping
GCC Secure Logistics Market
Logistics and Shipping
India Freight and Logistics Market
Logistics and Shipping
GCC Air Freight Transport Market
Logistics and Shipping
Georgia Freight and Logistics Market
Logistics and Shipping
Saudi Arabia Secure Logistics Market
Logistics and Shipping
Asia-Pacific Cold Chain Logistics Market
Logistics and Shipping
Halal Logistics Market