
 Less-Than-Truckload Market | 2026-2036
Less-Than-Truckload Market Size, Share, and Industry Trends Forecast 2026-2036
Less-Than-Truckload Market Outlook
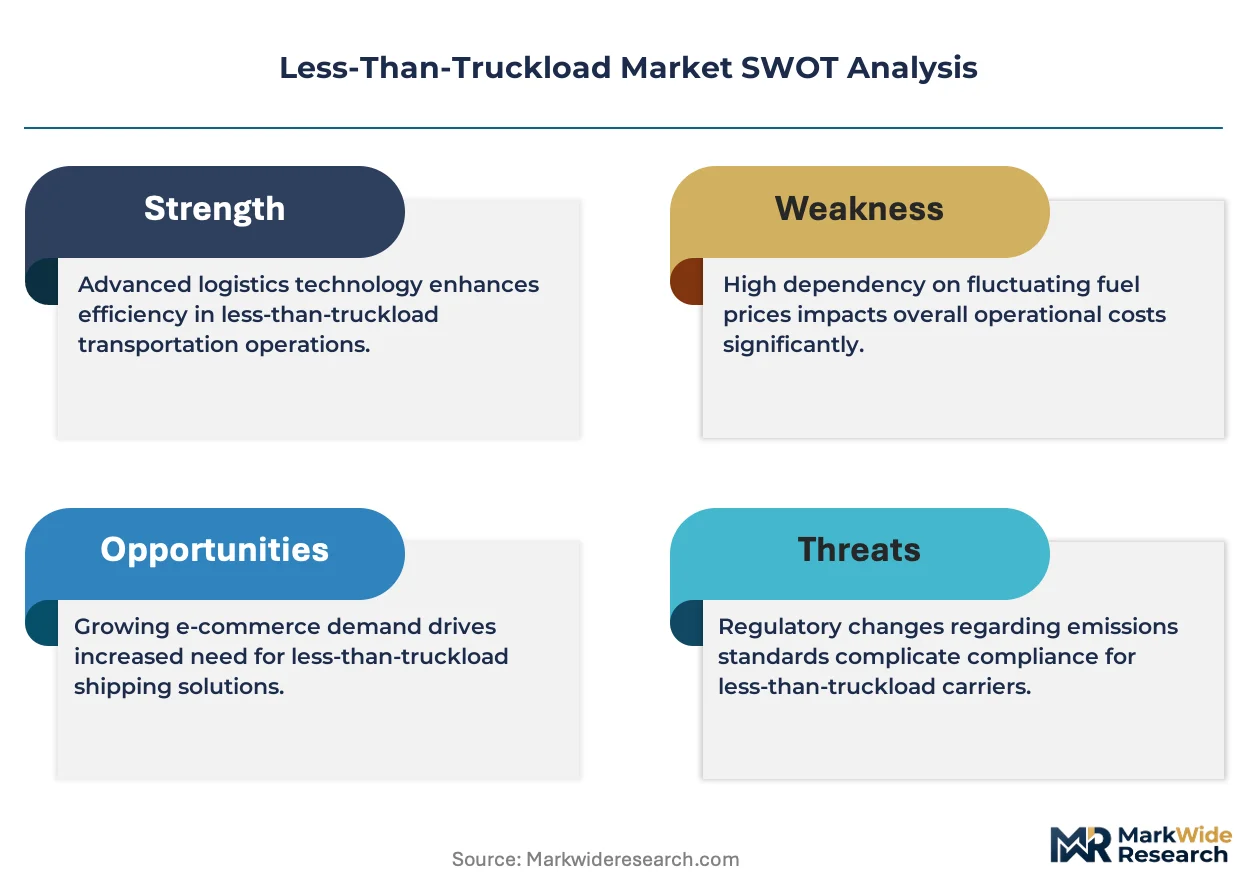
The national LTL carrier network is fragmenting as regional specialists erode the density economics that once protected incumbents. FedEx Freight leverages its integrated parcel-LTL platform to capture cross-selling opportunities across mid-market shippers. Old Dominion Freight Line sustains industry-leading operating ratios through disciplined lane-level profitability management. Estes Express Lines anchors its competitive position with one of the largest private less-than-truckload fleets in North America.
Less-than-truckload freight denotes shipments typically weighing between 150 and 15,000 pounds that do not require a full trailer, consolidated through hub-and-spoke terminal networks using freight class ratings based on density, stowability, handling, and liability. The primary commercial purpose centers on cost-efficient transportation for shippers with palletized or crated goods insufficient for full truckload commitment. Standard LTL service generates the bulk of revenue volume but commands thinner margins, while expedited LTL captures premium pricing from time-defensive manufacturing and healthcare supply chains. Temperature-controlled LTL remains structurally constrained by equipment scarcity and higher claims exposure, creating defensive margin pools for qualified operators.
The Federal Motor Carrier Safety Administration governs hours-of-service limits and electronic logging device mandates that directly constrain network velocity and driver utilization across US LTL operations. The EPA's Phase 3 greenhouse gas standards and California Air Resources Board's Advanced Clean Trucks rule are forcing accelerated capital deployment into electric and alternative-fuel tractors, reshaping fleet replacement cycles and terminal power infrastructure requirements. ISO 9001 quality management certifications and SmartWay transport partnership standards increasingly filter procurement eligibility for enterprise shipper contracts. Stakeholders must monitor how terminal automation investments and dynamic pricing algorithms reshape the trade-off between density efficiency and service customization.
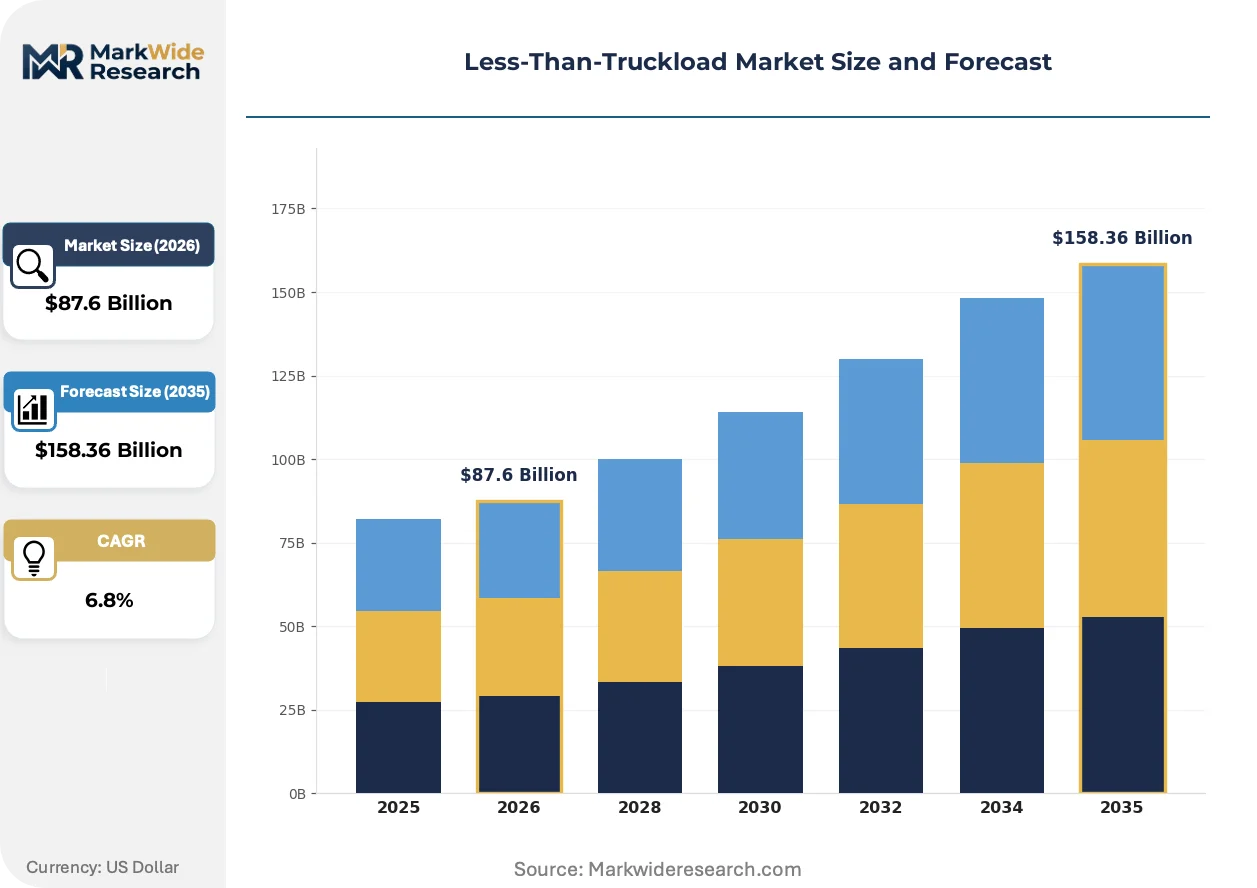
Market Dynamics
Terminal density economics are fragmenting as e-commerce fulfillment networks demand sub-24-hour regional coverage, forcing carriers to rebuild hub-and-spoke configurations around parcel-style velocity rather than traditional freight consolidation efficiency.
Growth Catalysts
- EPA Phase 3 Standards:The EPA's greenhouse gas regulations for heavy-duty vehicles are accelerating fleet electrification investments, creating procurement advantages for carriers with early zero-emission deployments.
- Healthcare supply chains:Temperature-controlled pharmaceutical distribution demands are expanding qualified cold-chain LTL networks, particularly for biologics requiring 2-8°C transit integrity.
- Final-mile convergence:Parcel carriers are backward integrating into LTL to capture mid-market shippers seeking unified billing and visibility platforms.
Market Restraints
- Driver availability constraints:FMCSA hours-of-service limits and electronic logging device mandates compress network velocity, constraining asset utilization across US operations.
- Terminal real estate scarcity:Urban infill land costs in Dallas, Chicago, and Atlanta are blocking greenfield hub development for regional specialists.
- Diesel-electric cost parity gaps:Battery-electric tractor capital costs remain structurally elevated versus diesel replacements, delaying fleet turnover timelines.
Strategic Opportunities
- Mexico cross-border lanes:Nearshoring manufacturing relocation is generating southbound finished goods and northbound component flows requiring bonded LTL services.
- Dynamic pricing algorithms:Machine learning-enabled yield management systems are enabling real-time lane-level profitability optimization previously unavailable to mid-tier carriers.
- ISO 9001 certification gaps:Enterprise shipper procurement filters are creating defensive moats for quality-certified operators serving automotive and aerospace supply chains.
Industry Challenges
- Terminal automation integration:Automated sortation and dimensioning equipment requires retrofitting legacy facilities without disrupting daily freight flows.
- Freight class litigation exposure:Density-based NMFC reclassification disputes generate claims liability and customer friction for high-cube commodities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Less-Than-Truckload Market |
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standard LTL, Expedited LTL, Final Mile, Temperature-Controlled Delivery Mode: Van, Flatbed, Drop Deck, Intermodal End User: E-Commerce, Retail, Manufacturing, Healthcare Pricing Model: Freight Class, Weight-Based, Zone-Based, Contractual |
| Companies Covered | FedEx Freight, Old Dominion Freight Line, Estes Express Lines, XPO Logistics, ABF Freight, R+L Carriers, Saia Inc., Schneider National, C.H. Robinson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Less-Than-Truckload Market Strategic Shifts
Digital freight matching and predictive analytics are compressing the traditional quote-to-book cycle from hours to minutes, while electrification and automation reshape physical network economics.
Dimensioning and weighing technology is hybridizing terminal operations. Automated freight classification systems using machine vision and laser scanning capture precise density data at intake, eliminating manual inspection delays. Mid-market carriers are deploying these systems fastest, narrowing the service gap with integrated parcel-LTL platforms. This convergence is hybridizing the operational boundary between parcel sortation and LTL consolidation, compressing handling costs per hundredweight.
The EPA's Phase 3 greenhouse gas standards are forcing accelerated capital deployment into electric and alternative-fuel tractors. Fleet operators must reconfigure terminal electrical infrastructure for megawatt-scale charging while managing diesel asset stranded value. California's Advanced Clean Trucks rule is compressing compliance timelines most severely for intrastate carriers serving Los Angeles and Long Beach port corridors.
Shippers are consolidating vendor relationships around integrated parcel-LTL platforms that offer unified visibility and single-invoice billing. Mid-market manufacturers are displacing standalone LTL contracts with bundled services from integrated carriers. This concentration is most visible in the Midwest manufacturing belt, where procurement teams prioritize network density over rate minimization.
Less-Than-Truckload Market Segmentation
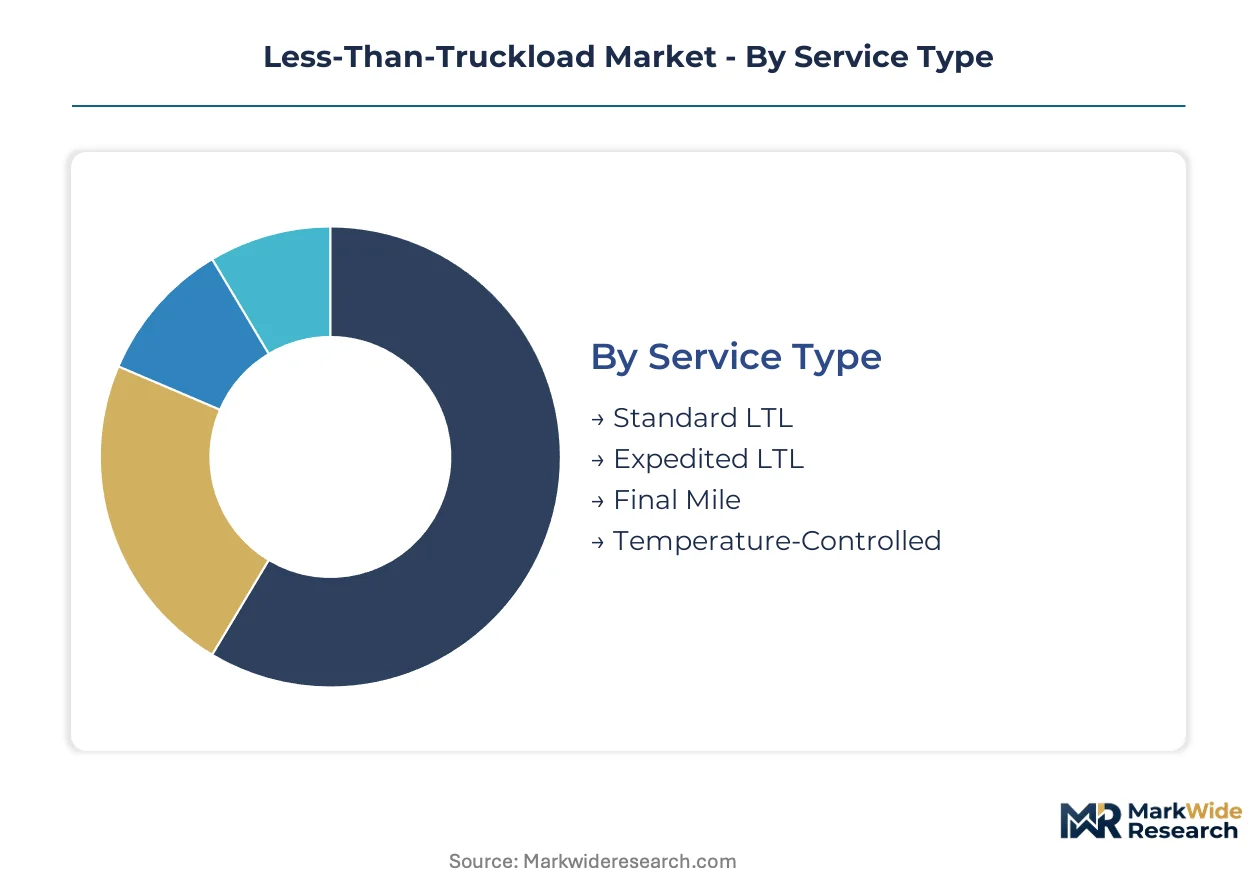
Service differentiation in less-than-truckload markets determines carrier profitability through handling complexity, equipment specialization, and customer retention mechanics. Segmentation reveals where density economics clash with premium service requirements, exposing structural margin pools.
Service Type:
After-sales service intensity varies dramatically across service tiers, with temperature-controlled and expedited segments demanding 24/7 recovery protocols while standard LTL operates on next-business-day resolution cycles.
- Standard LTL:Consolidated freight movement through hub-and-spoke networks using freight class ratings for palletized shipments between 150 and 15,000 pounds. Demand concentrates in Midwest manufacturing corridors where procurement teams prioritize network density over rate minimization, constrained by diesel-electric cost parity gaps delaying fleet turnover.
- Expedited LTL:Time-definite delivery with guaranteed transit windows for manufacturing and healthcare supply chains requiring compressed handling cycles. Demand concentrates among automotive and aerospace Tier 1 suppliers in the Southeast, driven by ISO 9001 procurement filters that create defensive moats for certified operators.
- Final Mile:Heavy goods delivery to residential and commercial endpoints with liftgate and inside delivery options. Parcel carriers backward integrate here to capture unified billing demand.
- Temperature-Controlled:Refrigerated transit maintaining 2-8°C integrity for pharmaceutical biologics and perishables. Equipment scarcity and higher claims exposure create defensive margin pools for qualified operators.
By volume, Standard LTL leads. By growth pace, Temperature-Controlled is ahead.
Delivery Mode:
Equipment specialization separates cost tiers, with flatbed and drop deck commanding premium positioning against commoditized van capacity.
- Van:Enclosed dry freight trailers handling the majority of palletized LTL volume with standard dock height compatibility. E-commerce fulfillment networks in Dallas and Chicago drive density requirements.
- Flatbed:Open-deck trailers for oversized, irregular, or construction materials requiring top or side loading. Demand concentrates in Texas energy corridors and Southeast manufacturing belts.
- Drop Deck:Step-deck configurations bridging standard van and specialized flatbed applications for machinery and equipment. Nearshoring manufacturing relocation generates bonded service demand across Mexico cross-border lanes.
- Intermodal:Rail-truck combination leveraging Class I railroad networks for line-haul efficiency with LTL terminal drayage. EPA Phase 3 standards accelerate electric drayage deployment at Los Angeles and Long Beach port corridors.
Van equipment dominates shipment counts. Drop Deck configurations are expanding most quickly.
End User:
Customer type determines pricing power and contract duration, with healthcare and manufacturing offering longer terms than volatile retail segments.
- E-Commerce:Fulfillment center replenishment and returns consolidation for omnichannel retailers. Sub-24-hour regional coverage requirements fragment traditional hub-and-spoke economics.
- Retail:Store replenishment and distribution center transfers with seasonal volatility and high service expectations. Midwest procurement teams increasingly favor integrated parcel-LTL platforms.
- Manufacturing:Inbound component logistics and outbound finished goods distribution with just-in-time delivery windows. Dynamic pricing algorithms enable real-time lane-level profitability optimization previously unavailable.
- Healthcare:Pharmaceutical, medical device, and laboratory specimen transport with temperature integrity and chain-of-custody documentation. FDA validation requirements and 2-8°C transit standards filter carrier eligibility.
Manufacturing generates the highest freight volume. Healthcare is climbing the fastest.
Pricing Model:
Margin structure varies by pricing mechanism, with contractual arrangements offering volume certainty against spot market volatility.
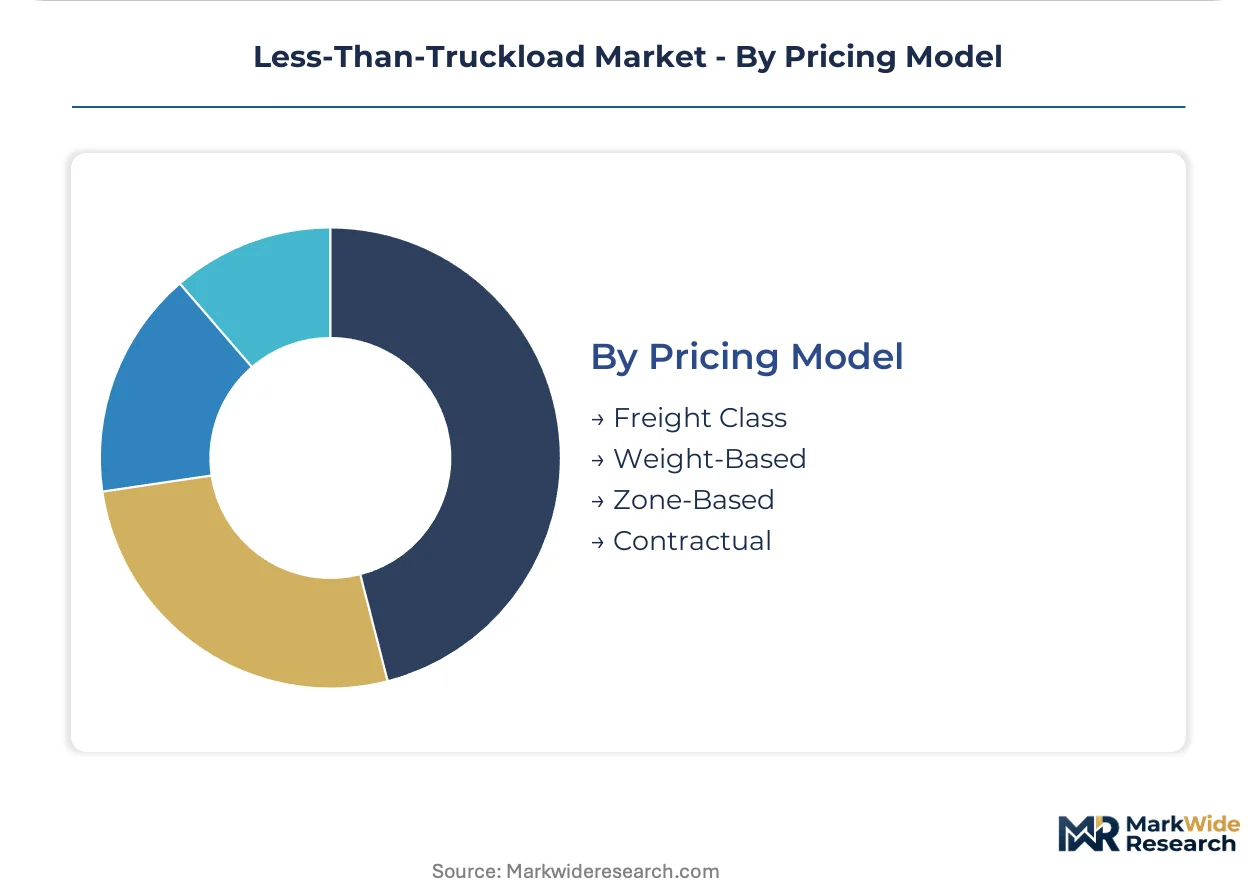
- Freight Class:Density-based NMFC ratings determining rates through stowability, handling, and liability characteristics. Reclassification disputes generate claims liability for high-cube commodities.
- Weight-Based:Per-hundredweight pricing linear to shipment mass with minimum charges and discounts for volume commitments. Machine learning yield management systems optimize this structure.
- Zone-Based:Distance-tiered pricing matrices correlating origin-destination pairs with transit time expectations. E-commerce networks demand granular zone compression.
- Contractual:Negotiated annual or multi-year agreements with volume commitments, service guarantees, and fuel surcharge mechanisms. Enterprise shipper procurement filters prioritize ISO 9001 certification.
Freight Class pricing handles the most volume. Zone-Based models are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates sharply in the United States, where hub-and-spoke terminal density supports premium service premiums, while Canadian operators absorb higher diesel-electric conversion costs without equivalent rate recovery mechanisms.
United States
E-commerce fulfillment networks in Dallas and Chicago drive sub-24-hour regional coverage demands that fragment traditional consolidation economics. The EPA's Phase 3 greenhouse gas standards force accelerated capital deployment into electric tractors and terminal charging infrastructure. Midwest manufacturing corridors anchor procurement patterns favoring network density over rate minimization.
Canada
Cross-border LTL flows with the United States concentrate in Ontario and Quebec manufacturing belts serving automotive and aerospace supply chains. Transport Canada's proposed Clean Fuel Regulations mirror EPA trajectory but lag implementation timelines. Toronto terminal operators face urban infill land scarcity blocking greenfield hub development.
Mexico
Nearshoring manufacturing relocation generates southbound finished goods and northbound component flows requiring bonded LTL services across Nuevo León and Baja California corridors. Mexico's Secretariat of Economy coordinates infrastructure investments supporting automotive cluster expansion. Monterrey anchors the fastest-growing cross-border lane density.
Germany
Industrial machinery and automotive component distribution demands precision transit windows through Rhine-Ruhr and Bavarian logistics clusters. The EU Green Deal's Fit for 55 package mandates heavy-duty fleet decarbonization with stricter timelines than North American counterparts. Stuttgart terminal operators pilot automated sortation retrofitting.
China
Yangtze River Delta and Pearl River Delta manufacturing zones generate massive consolidated freight volumes for domestic distribution and export container drayage. China's Ministry of Ecology and Environment enforces dual carbon goals compressing diesel fleet replacement cycles. Shanghai operators deploy dimensioning technology fastest among Asian markets.
Less-Than-Truckload Market Competitive Environment
Integrated parcel-LTL platforms and standalone freight specialists split the market along customer scale and service complexity lines. Consolidation pressure intensifies as mid-market shippers consolidate vendor relationships around unified visibility platforms. Two archetypes dominate: density-optimized regional networks and integrated multi-modal platforms. Competitive moves concentrate on terminal automation investments and dynamic pricing algorithm deployment.
Within the integrated platform tier, FedEx Freight and XPO Logistics exemplify archetypes combining parcel sortation density with LTL consolidation economics. Old Dominion Freight Line anchors the standalone specialist position, representing disciplined lane-level profitability management without parcel network subsidies. These three occupy positions illustrating the fundamental trade-off between service breadth and operational focus.
| Leading Market Players |
|---|
| FedEx Freight |
| Old Dominion Freight Line |
| Estes Express Lines |
| XPO Logistics |
| ABF Freight |
| R+L Carriers |
| Saia Inc. |
| Schneider National |
| C.H. Robinson |
| Others |
Value Chain & Pricing Dynamics
Dallas-Fort Worth terminal capacity concentration anchors North American LTL pricing power, with hub density in the Texas Triangle directly determining rate premiums for next-day regional coverage. The EPA's Phase 3 compliance costs feed through to fuel surcharge mechanisms, compressing margins for carriers without electric fleet scale.
Pricing Analysis
Configured-to-order expedited pricing commands spreads of 40-60% above standard LTL tariffs, with temperature-controlled and guaranteed-transit tiers extracting premiums from healthcare and automotive supply chains. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 9001 certification status and freight class density ratings. Cost compression in standard LTL is intensifying because diesel-electric capital parity gaps delay fleet turnover for mid-tier carriers. Small and mid-market manufacturers exhibit highest price sensitivity, while pharmaceutical shippers prioritize transit integrity over rate minimization.
Supply Chain Analysis
Terminal real estate concentration in the hands of integrated parcel-LTL platforms—FedEx Freight, XPO Logistics, and Old Dominion Freight Line—locks in capacity advantages for incumbent networks. Equipment manufacturing draws from Mexico, China, and domestic US assembly plants for tractors and trailers. Diesel engine components, lithium battery packs, and automated sortation systems constitute critical input dependencies. Single-source vulnerability concentrates in Class 8 electric tractor platforms where OEM production runs remain constrained. Distribution runs through hub-and-spoke terminal networks with line-haul rail partnerships for intermodal efficiency.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LTL market operates as a defensive-moat business where terminal density creates self-reinforcing network effects that new capital cannot easily replicate. Switching costs for enterprise shippers rise with integrated visibility platform adoption.
For Market Incumbents: Insulate core density economics by accelerating terminal automation investments in Chicago and Atlanta corridors before regional specialists close the service gap. Backward integration into electric charging infrastructure at owned facilities locks in EPA Phase 3 compliance advantages. Priority focus: automated dimensioning systems that compress handling costs per hundredweight below mid-tier competitor thresholds. For New Entrants and Emerging Players: Establish a beachhead in temperature-controlled pharmaceutical lanes where equipment scarcity and FDA validation requirements create defensive margin pools underserved by general freight carriers. Target Mexico cross-border bonded services from Monterrey to Laredo, exploiting nearshoring manufacturing relocation flows. Go-to-market angle: ISO 9001 certification paired with 24/7 recovery protocols for biologics requiring 2-8°C integrity. For Investors and Strategic Acquirers: Carve-out targets emerge from family-owned regional carriers with dense terminal footprints in Southeast manufacturing belts but lacking integrated visibility platforms. Long-term viability favors operators with owned real estate in urban infill locations where greenfield development is now cost-prohibitive. Signal to watch: accelerating consolidation of mid-market shipper procurement around unified parcel-LTL billing platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Terminal Automation Deployment | Automated sortation at Dallas and Chicago hubs compresses handling costs below regional competitor thresholds. |
| Electric Fleet Conversion | Zero-emission tractor deployment ahead of EPA Phase 3 timelines secures procurement advantages with enterprise shippers. |
| Mexico Cross-Border Expansion | Bonded LTL services across Nuevo León corridors capture nearshoring manufacturing relocation flows. |
| ISO 9001 Certification Investment | Quality management certification filters automotive and aerospace procurement eligibility, creating defensive moats. |
| Dynamic Pricing Algorithm Implementation | Machine learning yield management enables real-time lane-level profitability optimization previously unavailable to mid-tier carriers. |
Study Parameters
Desk research of FMCSA regulatory filings, EPA emissions standards documentation, and carrier SEC disclosures preceded structured interviews with terminal operations directors, fleet procurement managers, shipper supply chain executives, and freight brokerage principals. Secondary validation drew from ATA freight tonnage reports, Cass Freight Index data, and SmartWay transport partnership records. Bottom-up shipment volume modeling triangulated against top-down carrier revenue aggregation across the analysis window.
Assumptions held fixed include EPA Phase 3 compliance timelines and diesel-electric capital cost parity trajectories, while variables tested included e-commerce fulfillment network expansion rates and nearshoring manufacturing relocation velocity. Segmentation dimensions modeled encompass service type, delivery mode, end-user industry, and pricing model across the projection horizon. CAGRs derived from historical freight tonnage growth patterns adjusted for electrification capital deployment cycles and terminal automation adoption curves.
Macroeconomic conditions sit as an overlay; deviation in industrial production indices, diesel price volatility, or interest rate environments would shift the trajectory of fleet replacement and terminal investment decisions. Forecasts reflect assumptions about regulatory enforcement consistency and technology cost reduction curves. Quarterly review of carrier operating ratio trends, driver availability indices, and shipper procurement consolidation patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
China Local Courier Market
Logistics and Shipping
Central and Eastern Europe Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Middle East and Africa Freight & Logistics Market
Logistics and Shipping
Renewable Resources Logistics Market
Logistics and Shipping
Europe Automotive Logistics Market
Logistics and Shipping
Mexico Road Freight Transport Market
Logistics and Shipping
Australia Freight Forwarding Market
Logistics and Shipping
Latin America Container Terminal Operations Market
Logistics and Shipping
Hungary Third Party Logistics (3PL) Market
Logistics and Shipping
Qatar Third-Party Logistics (3PL) Market
Logistics and Shipping
Germany Express Delivery Market
Logistics and Shipping
South Korea Third-Party Logistics (3PL) Market
Logistics and Shipping
Indonesia Cold Chain Logistics Market
Logistics and Shipping
Brazil Freight and Logistics Market
Logistics and Shipping
Europe FMCG Logistics Market
Logistics and Shipping
Europe Domestic Courier Market