
 Polyoxin Market | 2026-2036
Polyoxin Market Size, Share, and Industry Trends Forecast 2026-2036
Polyoxin Market Analysis
Modular bundling of polyoxin with companion biocontrol agents is rebalancing how crop protection buyers configure their fungicide programs. Kaken Pharmaceutical leverages its Japanese manufacturing base to sustain specialized fermentation capacity for nucleoside antibiotic production. Certis anchors North American distribution through its biocontrol-focused channel network, while Jiangsu Fengyuan Bioengineering competes on cost-optimized powder formulations for domestic Chinese farming cooperatives.
Polyoxin denotes a family of nucleoside peptide antibiotics produced via Streptomyces cacaoi fermentation, characterized by chitin synthase inhibition with molecular weights typically ranging from 600 to 700 Daltons. These compounds disrupt fungal cell wall formation in phytopathogens, serving as targeted agricultural fungicides against powdery mildew and gray mold in high-value horticultural crops. Powder formulations currently occupy the largest share of product-type revenue owing to storage stability and ease of tank-mixing, while liquid forms represent the fastest-expanding configuration as precision-spray equipment penetrates commercial greenhouse operations. Agricultural fungicides dominate application-level demand, though soil treatment is gaining traction where integrated pest management protocols restrict conventional chemical loading.
Japan's Ministry of Agriculture, Forestry and Fisheries enforces stringent maximum residue limits that constrain import eligibility for polyoxin-treated produce, while China's Ministry of Ecology and Environment monitors fermentation effluent under dual carbon goals. The EU's F-Gas Regulation and REACH frameworks indirectly shape competitive dynamics by elevating compliance costs for synthetic fungicide alternatives. Stakeholders must monitor evolving residue tolerance harmonization between major importing jurisdictions to anticipate formulation reformulation requirements and registration pathway investments.
Market Dynamics
Fermentation capacity concentration in East Asian manufacturing clusters is tightening polyoxin supply elasticity, while residue limit harmonization between Japan's MAFF standards and China's GB frameworks forces simultaneous multi-jurisdictional compliance investments from producers.
Growth Catalysts
- Dual carbon goals under China's MEE:Fermentation-based biocontrol agents gain preferential treatment over synthetic chemistries in carbon accounting protocols for agricultural inputs.
- Powdery mildew pressure in protected cultivation:Greenhouse strawberry and cucumber growers in Shandong province are expanding prophylactic polyoxin programs as climate-controlled environments intensify fungal pathogen cycles.
- Chitin synthase inhibition specificity:Targeted mode-of-action compounds face reduced resistance development timelines compared to broad-spectrum azole alternatives, preserving efficacy windows.
Market Restraints
- Streptomyces cacaoi strain supply concentration:Master seed banks and specialized fermentation infrastructure cluster in Japanese and select Chinese facilities, creating single-source vulnerability for nucleoside antibiotic production.
- Japan's MAFF residue enforcement:Sub-ppm maximum residue limits for polyoxin B and D isomers on imported horticultural produce block market access for exporters lacking dedicated analytical certification.
- Synthetic fungicide price compression:Generic triazole and strobilurin alternatives maintain cost advantages in price-sensitive row-crop segments, limiting polyoxin penetration outside high-value horticulture.
Strategic Opportunities
- Soil treatment application expansion:Drench formulations for rhizosphere protection against soil-borne chitin-containing pathogens represent underdeveloped usage outside foliar spray protocols.
- Liquid formulation precision-spray compatibility:Commercial greenhouse automation in the Netherlands and Belgium creates demand for tank-mix-stable soluble concentrates compatible with sensor-guided application systems.
- EU F-Gas Regulation displacement:Synthetic fumigant restrictions in protected cultivation structures open substitution pathways for microbial fungicide programs in tomato and pepper production.
Industry Challenges
- Multi-jurisdictional registration synchronization:Divergent data requirements between Japan's PMDA agricultural chemical division and China's ICAMA extend commercialization timelines for new polyoxin analogs.
- Fermentation titer optimization expertise:Industrial microbiology talent capable of scaling Streptomyces secondary metabolite production remains concentrated in legacy pharmaceutical biotechnology clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyoxin Market |
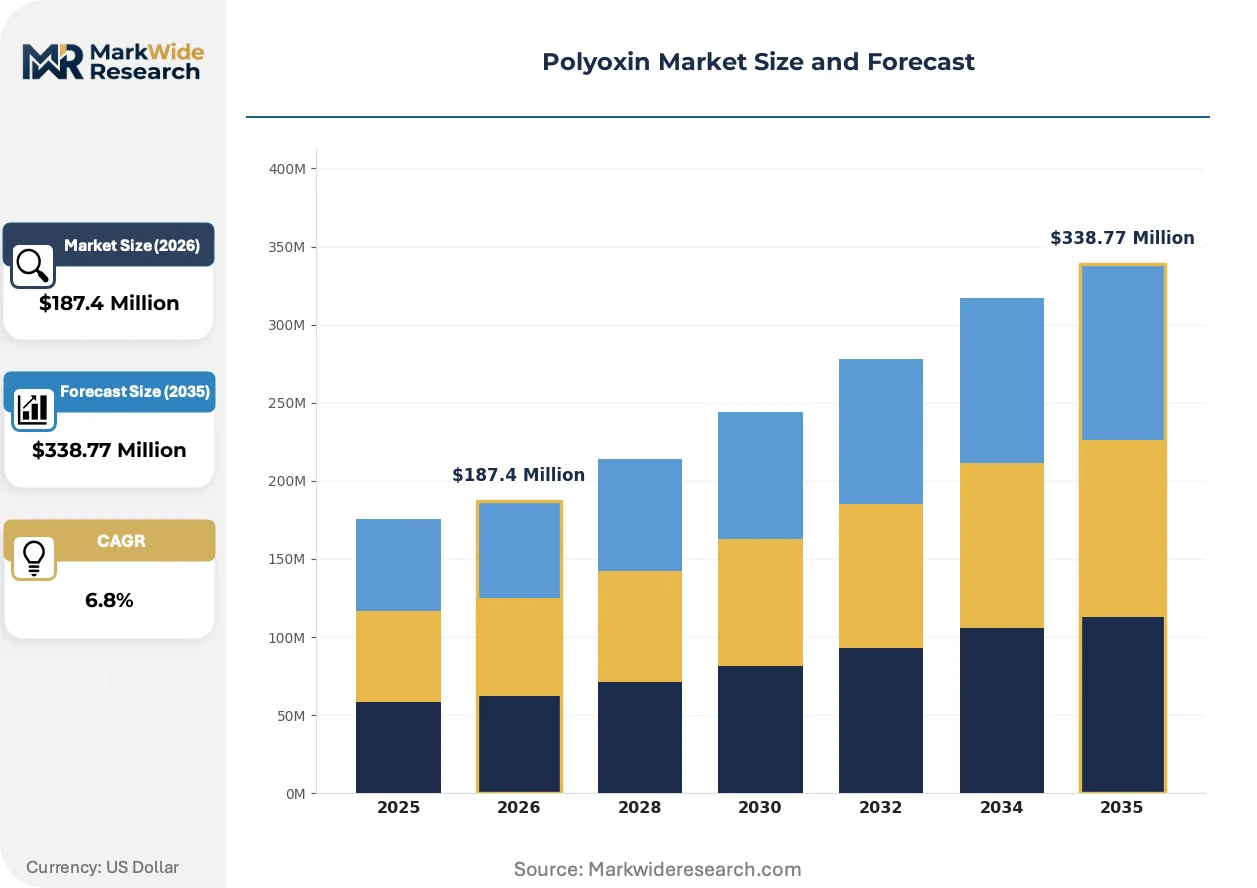
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Liquid Form, Powder, Suspension Application: Agricultural Fungicides, Crop Protection, Soil Treatment, Plant Growth Regulators End User: Farming, Horticulture, Agrochemical Companies, Research Institutions Distribution Channel: Retail, Direct Sales, Online Platforms, Wholesale |
| Companies Covered | Kaken Pharmaceutical, Certis, Jiangsu Fengyuan Bioengineering, OHP Inc, Cleary Chemical Corp, Shanxi Lvhai Agrochemicals, Nufarm Limited, Beijing Green Agrosino, Arysta LifeScience, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyoxin Market Emerging Trajectories
Bioprocess engineering advances are compressing production economics for nucleoside peptide antibiotics while regulatory chemistry is narrowing acceptable residue thresholds. These forces are reshaping how manufacturers configure formulation portfolios and which geographies they prioritize for registration investment.
Encapsulation technology using lignin-based matrices is integrating polyoxin active ingredients into controlled-release granules. Large-scale vegetable cooperatives in China's Jiangsu province are adopting these formulations to reduce application frequency in labor-constrained growing seasons. This integration is compressing the total cost of ownership gap between biological and synthetic fungicide programs.
REACH framework amendments under the EU's CLP Regulation are reclassifying certain nucleoside antibiotic metabolites as substances of very high concern based on aquatic toxicity profiles. Formulation houses serving Dutch greenhouse exporters are reformulating to exclude specific polyoxin D isomers from tank-mix combinations. The protected cultivation segment is responding by demanding certificates of analysis with expanded metabolite panels.
Buyer consolidation among European supermarket chains is concentrating procurement authority for residue-compliant produce. German and French retail compliance departments now mandate third-party polyoxin residue testing before contract signing, displacing grower self-certification. This behavioral shift is most visible in Spanish Almería greenhouse operations supplying northern European markets.
Polyoxin Market Segmentation
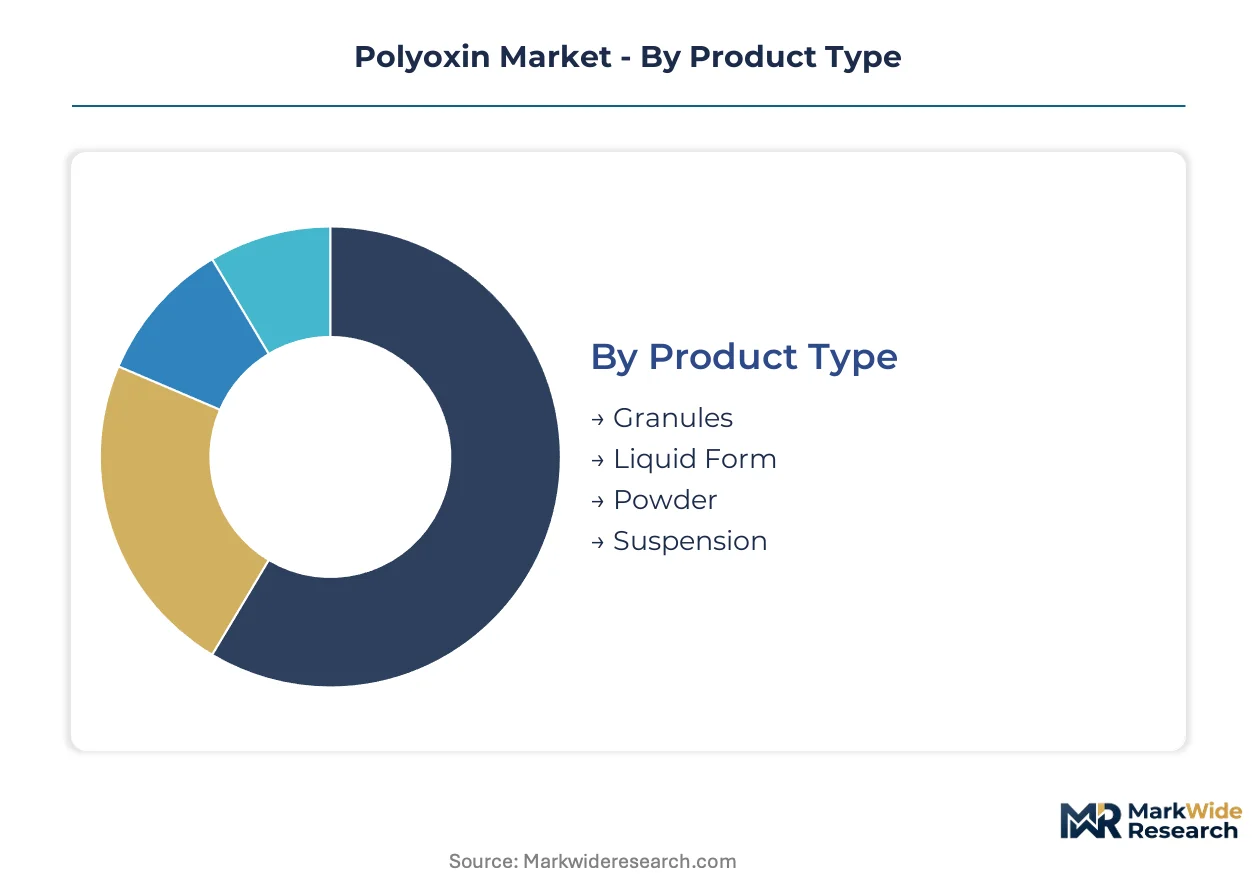
Segmentation in the polyoxin market reflects divergent buyer priorities across cultivation scale, regulatory exposure, and equipment compatibility. Formulation choice directly determines tank-mix flexibility, residue compliance burden, and application labor requirements for end users.
Product Type:
Buyers select formulation based on storage infrastructure, spray equipment compatibility, and labor availability during peak disease pressure windows.
- Powder:Dry concentrates offer extended shelf stability without cold chain requirements and simplify bulk transport for farming cooperatives in China's Shandong province. Demand concentrates among vegetable growers lacking precision-spray infrastructure, though dust exposure during mixing drives protective equipment costs.
- Liquid Form:Soluble concentrates integrate with automated greenhouse dosing systems in Dutch and Belgian protected cultivation operations. Commercial tomato and cucumber producers in Almería, Spain are adopting liquid polyoxin for sensor-guided application compatibility, compressing labor inputs during labor-constrained harvest periods.
- Granules:Controlled-release matrices using lignin encapsulation reduce application frequency for labor-scarce growing seasons.
- Suspension:Aqueous suspensions improve wetting on waxy leaf surfaces in high-humidity greenhouse environments.
Volume sits with powder formulations; growth tilts toward liquid forms compatible with precision agriculture infrastructure.
Application:
Application modality determines regulatory pathway complexity and resistance management protocol requirements for commercial growers.
- Agricultural Fungicides:Foliar spray programs targeting powdery mildew and gray mold dominate commercial horticulture in Japan's greenhouse strawberry sector. Prophylactic application cycles in climate-controlled environments intensify demand as pathogen pressure accelerates under elevated humidity.
- Soil Treatment:Drench formulations for rhizosphere protection against soil-borne chitin-containing pathogens remain underdeveloped outside foliar protocols. China's Jiangsu province vegetable cooperatives are piloting soil-directed polyoxin for integrated pest management compliance under MEE carbon accounting frameworks.
- Crop Protection:Tank-mix combinations with companion biocontrol agents rebalance fungicide program configuration for resistance-prone operations.
- Plant Growth Regulators:Auxin-interaction effects at sub-fungicidal concentrations support specialized nursery applications.
Revenue concentrates in foliar fungicide applications; expansion is steepest in soil treatment protocols as chemical loading restrictions tighten.
End User:
End-user category shapes procurement scale, technical support requirements, and formulation customization demands.
- Farming:Smallholder vegetable producers in China's production clusters purchase through cooperative aggregation channels with limited technical advisory access. Price sensitivity drives generic powder formulation preference over branded liquid alternatives.
- Horticulture:Protected cultivation specialists in Japan and the Netherlands require residue certification for supermarket chain procurement compliance. German and French retail mandates for third-party polyoxin testing displace grower self-certification in Spanish export operations.
- Agrochemical Companies:Formulation houses seek active ingredient supply for proprietary biocontrol blend development.
- Research Institutions:Academic programs evaluate novel polyoxin analogs and resistance mechanism studies.
Procurement volume aggregates through farming cooperatives; margin capture concentrates in horticulture channels with certification requirements.
Distribution Channel:
Channel selection reflects buyer scale, geographic concentration, and technical service requirements for application guidance.
- Wholesale:Bulk powder formulations move through agricultural supply cooperatives serving China's domestic production clusters. Concentrated demand in Shandong and Jiangsu provinces supports localized inventory positioning.
- Direct Sales:Technical specialists from fermentation manufacturers engage large greenhouse operators for customized formulation development. Kaken Pharmaceutical's Japanese base sustains direct relationships with domestic horticultural exporters facing MAFF residue enforcement.
- Retail:Small-package liquid formulations reach hobby-scale producers through garden center networks.
- Online Platforms:E-commerce penetration remains limited for biological fungicides requiring cold chain and technical support.
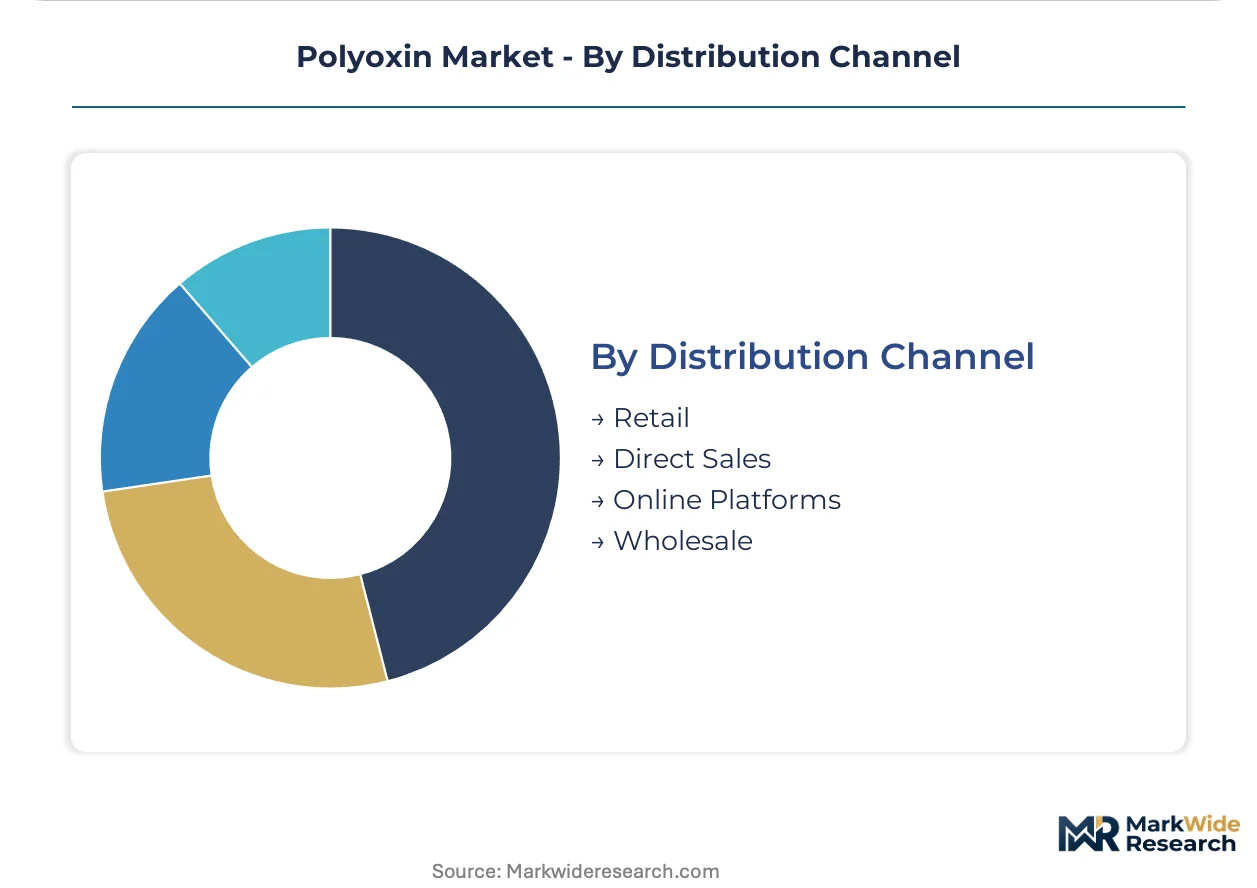
Wholesale channels capture the largest transaction volume; direct sales expand fastest among export-oriented greenhouse operations requiring residue compliance documentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate fermentation capacity for nucleoside antibiotic production, attracting agrochemical manufacturers through tax incentives and streamlined environmental permitting under MEE dual carbon protocols.
China
Shandong and Jiangsu provinces host domestic agrochemical production clusters supporting localized supply chains for polyoxin-based formulations. GB standards under SAMR enforce stricter residue limits that tighten compliance thresholds for manufacturers serving export markets. Vegetable cooperatives in Jiangsu pilot soil-directed polyoxin applications for integrated pest management compliance.
Japan
MAFF enforces sub-ppm maximum residue limits for polyoxin B and D isomers on imported horticultural produce, blocking market access for exporters lacking dedicated analytical certification. Kaken Pharmaceutical leverages its domestic manufacturing base to sustain specialized fermentation capacity. Greenhouse strawberry growers in Kanto expand prophylactic polyoxin programs as climate-controlled environments intensify fungal pathogen cycles.
United States
EPA registration pathways for biological fungicides create compliance complexity for nucleoside antibiotic entrants relative to conventional synthetic alternatives. Certis anchors North American distribution through its biocontrol-focused channel network. California specialty crop producers face residue monitoring requirements under state Department of Pesticide Regulation protocols for export-bound produce.
Netherlands
Commercial greenhouse automation in the Netherlands and Belgium creates demand for tank-mix-stable soluble concentrates compatible with sensor-guided application systems. ECHA REACH framework amendments under CLP Regulation reclassify certain nucleoside antibiotic metabolites as substances of very high concern. Dutch formulation houses serving greenhouse exporters reformulate to exclude specific polyoxin D isomers from tank-mix combinations.
Spain
Almería greenhouse operations supplying northern European markets respond to German and French retail mandates for third-party polyoxin residue testing before contract signing. EU F-Gas Regulation restrictions on synthetic fumigants in protected cultivation structures open substitution pathways for microbial fungicide programs. Commercial tomato and cucumber producers adopt liquid polyoxin for sensor-guided application compatibility.
Polyoxin Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the polyoxin value chain. The market structure tilts toward concentration among fermentation-capable manufacturers with legacy pharmaceutical biotechnology expertise. Three archetypes dominate: Japanese pharmaceutical-origin producers with captive seed banks, Chinese cost-optimized powder formulators serving domestic cooperatives, and North American biocontrol distributors with residue certification capabilities. Capacity expansion and strategic partnerships represent the dominant competitive moves as players navigate multi-jurisdictional registration requirements.
Within the pharmaceutical-origin tier, Kaken Pharmaceutical exemplifies specialized fermentation expertise concentrated in Japanese manufacturing infrastructure. Among Chinese domestic formulators, Jiangsu Fengyuan Bioengineering occupies a position serving cost-sensitive farming cooperatives through powder formulation supply. On the distribution-specialist vector, Certis anchors North American market access through biocontrol-focused channel relationships.
| Leading Market Players |
|---|
| Kaken Pharmaceutical |
| Certis |
| Jiangsu Fengyuan Bioengineering |
| OHP Inc |
| Cleary Chemical Corp |
| Shanxi Lvhai Agrochemicals |
| Nufarm Limited |
| Beijing Green Agrosino |
| Arysta LifeScience |
| Others |
Supply Flow & Price Mechanics
Fermentation substrate cost indices, particularly corn steep liquor and soybean meal benchmarks tracked in East Asian commodity exchanges, cascade through polyoxin manufacturing into three distinct pricing tiers serving export-certified horticulture, domestic cooperative farming, and generic powder bulk buyers.
Pricing Analysis
Margin tightening in domestic Chinese powder formulations reflects starch-based substrate price volatility and compressed procurement budgets at Shandong vegetable cooperatives. Three-tier pricing structure across certified-export, standard-registration, and economy-generic levels differentiates Japanese pharmaceutical-origin supply from Jiangsu cost-optimized alternatives. Pricing pressure stems from synthetic triazole fungicide price compression in row-crop segments. Export-oriented Dutch greenhouse operators exhibit lowest price sensitivity due to supermarket chain residue mandates, while Chinese smallholders drive aggressive cost-down negotiations.
Supply Chain Analysis
China's dual carbon protocols under MEE are reshaping raw-material sourcing toward domestic fermentation feedstock suppliers with verified carbon accounting. Manufacturing gravity centers on Japan, China, and select South Korean facilities with legacy Streptomyces cultivation expertise. Production draws from specialized master seed banks, pharmaceutical-grade fermentation infrastructure, and chitin synthase assay capabilities. Single-source vulnerability concentrates in Japanese strain repositories. Distribution runs through biocontrol-focused channel networks in North America and cooperative aggregation systems in China's production clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation capacity scarcity among Streptomyces cacaoi specialists props pricing power for incumbent manufacturers with validated seed banks and multi-jurisdictional registration portfolios.
For Market Incumbents: Anticipate regulatory chemistry narrowing under ECHA REACH amendments by reformulating to exclude SVHC-classified polyoxin D isomers ahead of compliance deadlines. Secure backward integration into lignin encapsulation technology for controlled-release granule production. Prioritize capacity expansion in China's Yangtze River Delta special economic zones to exploit MEE dual carbon preferential treatment. For New Entrants and Emerging Players: Capture soil treatment application white space where integrated pest management protocols restrict conventional chemical loading, particularly in Jiangsu province vegetable cooperatives piloting rhizosphere protection programs. Target precision-spray compatible liquid formulation development for Dutch and Belgian greenhouse automation infrastructure. Pursue partnership pathways with established fermentation houses lacking formulation expertise rather than greenfield capacity investment. For Investors and Strategic Acquirers: Distressed-cycle entries favor pharmaceutical-origin manufacturers with captive Japanese fermentation infrastructure and MAFF residue certification capabilities during periods of generic price compression. Evaluate targets through the lens of ten-year registration asset viability under tightening global residue harmonization. Monitor ECHA SVHC list expansion velocity as the critical inflection signal for formulation reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Additional fermentation lines in China's MEE-designated zones secure preferential carbon accounting for biological fungicide output. |
| Backward Integration | In-house lignin encapsulation technology reduces application frequency costs for labor-constrained growing seasons. |
| Regulatory Approval Pathway | Synchronized PMDA and ICAMA submissions compress commercialization timelines for novel polyoxin analogs. |
| Long-term Supply Agreement | Contracted master seed bank access mitigates single-source vulnerability in Streptomyces cacaoi strain supply. |
| Joint Venture | Partnerships between Japanese fermentation specialists and Chinese powder formulators bridge cost-optimization with residue compliance. |
Methodological Framework
Multi-period observation of fermentation capacity utilization rates, residue limit harmonization trajectories, and greenhouse automation penetration anchored the trend analysis, supplemented by interviews with plant managers at nucleoside antibiotic manufacturing facilities, procurement leads at Dutch horticultural exporters, regulatory affairs specialists navigating PMDA and ICAMA pathways, and technical R&D directors optimizing Streptomyces titer yields. Secondary validation drew from customs and trade data, SEC filings of diversified agrochemical conglomerates, ECHA substance registration databases, and Japan's MAFF agricultural chemical residue monitoring reports. Bottom-up volume modeling triangulated against top-down market sizing across formulation type, application modality, and end-user procurement channel.
Input-output matrices mapped fermentation substrate costs, regulatory compliance expenditure, and precision agriculture equipment compatibility against output pricing tiers and geographic demand concentration. Segmentation dimensions modeled included product formulation, application protocol, cultivation system type, and regional regulatory cluster. CAGRs were derived from trend extrapolation adjusted for capacity constraint elasticity and substitution threat velocity. Industry-specific forecast inputs incorporated ECHA SVHC reclassification probability and MEE dual carbon protocol implementation pace.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to residue limit harmonization failures between Japan's MAFF and China's GB frameworks, fermentation substrate commodity price spikes, and breakthrough resistance development in target phytopathogen populations. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Thiocolchicoside Market
Specialty Compounds
Putty Fillers Market
Specialty Compounds
Polyurea Market
Specialty Compounds
North America Customized Premixes Market
Specialty Compounds
Global Quaternary Ammonium Compounds Market
Specialty Compounds
Global Customized Premixes Market
Specialty Compounds
Special Effect Masterbatches Market
Specialty Compounds
Global Zinc Acetylacetonate Market
Specialty Compounds
Global Polymer Clay Market
Specialty Compounds
United States Hydroxypropyl Methylcellulose (HPMC) Market
Specialty Compounds
Toner Resins Market
Specialty Compounds
Strontium Nitrate Market
Specialty Compounds
Acetyl Tyrosine Market
Specialty Compounds
Flexible Foam Market
Specialty Compounds
Global Heat Stabilizers Market
Specialty Compounds
Propoxylates Market