
 Corn Peptide Market | 2026-2036
Corn Peptide Market Size, Share, and Industry Trends Forecast 2026-2036
Corn Peptide Market Analytics
Enzymatic hydrolysis refinement is rewriting corn peptide production economics, replacing older acid-based methods with gentler extraction protocols that preserve bioactivity. SmartPEP Biotech leverages proprietary fermentation platforms to anchor its position in functional peptide grades. Zhongshi Duqing (Shandong) Biotech Co., Ltd dominates domestic Chinese supply through captive corn milling capacity. CRESCENT BIOTECH navigates European regulatory complexity with dedicated EFSA-compliant documentation streams.
Corn peptides are short-chain amino acid sequences derived from zein-rich corn gluten meal through controlled enzymatic cleavage, typically yielding fractions below 10 kDa molecular weight with demonstrable antioxidant and angiotensin-converting enzyme inhibitory properties. Hydrolyzed peptides occupy the volume core as established feed and food additives, while functional peptides command premium positioning in cardiovascular-targeted nutraceutical formulations. Bioactive peptides represent the fastest-expanding category, though isolated peptides retain concentrated margin pools due to purity certification requirements from dietary supplement companies.
China's SAMR enforces GB standards for peptide content labeling and contaminant thresholds, while Japan's Consumer Affairs Agency administers FOSHU claims that determine market access for blood-pressure-modifying products. The EU EFSA Novel Food catalog creates pre-market authorization barriers for non-traditional peptide sources entering European nutraceutical channels. Stakeholders must monitor evolving peptide-specific health claim databases across multiple jurisdictions to align R&D pipelines with approvable positioning.
Market Dynamics
Enzymatic hydrolysis refinement is compressing production costs while preserving bioactive fractions, enabling nutraceutical formulators to displace soy and dairy peptides in cardiovascular-targeted formulations. This technological inflection is redrawing competitive boundaries between acid-based legacy producers and precision-fermentation specialists.
Growth Catalysts
- FOSHU Framework Alignment:Japan's Consumer Affairs Agency approval pathway for blood-pressure-modifying functional foods creates premium positioning for ACE-inhibitory peptide fractions, accelerating nutraceutical adoption.
- Protein Fortification Mandates:Sports nutrition and clinical nutrition formulators in China and South Korea are integrating corn peptides into meal-replacement formulations to meet amino acid completeness standards.
- Zein Recovery Economics:Wet-milling operators in Shandong and Jilin provinces are retrofitting facilities to capture value from corn gluten meal streams previously directed to low-margin feed applications.
Market Restraints
- Input Cost Volatility:Corn gluten meal prices fluctuate with ethanol production cycles and drought patterns in the US Corn Belt, compressing margin predictability for non-integrated peptide processors.
- EFSA Novel Food Authorization:The EU's pre-market safety assessment for non-traditional protein sources creates 18-24 month entry delays and documentation costs that deter mid-cap Asian producers.
- Enzyme Substitution Threat:Microbial fermentation-derived peptides from precision biotech platforms offer batch-to-batch consistency that challenges agricultural-derived supply chains.
Strategic Opportunities
- Geriatric Nutrition Penetration:Japan's super-aged demographic and South Korea's expanding silver economy create addressable white space for sarcopenia-targeted peptide formulations with muscle-protein-synthesis claims.
- Clean-Label Pet Nutrition:Premium pet food brands in North America are sourcing corn peptides as hypoallergenic alternatives to common animal proteins, opening non-human channels.
- Dual Carbon Policy Tailwinds:China's MEE carbon intensity targets incentivize bioactive recovery from agricultural waste streams, aligning peptide production with circular economy mandates.
Industry Challenges
- Bioanalytical Talent Scarcity:Peptide characterization laboratories face acute shortages of mass spectrometry specialists capable of validating molecular weight distributions below 3 kDa for functional-grade certification.
- Cross-Jurisdictional Claim Harmonization:Divergent blood-pressure health claim databases between Japan's FOSHU, China's SAMR, and US FDA enforcement discretion force parallel clinical study designs and duplicate dossier preparation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corn Peptide Market |
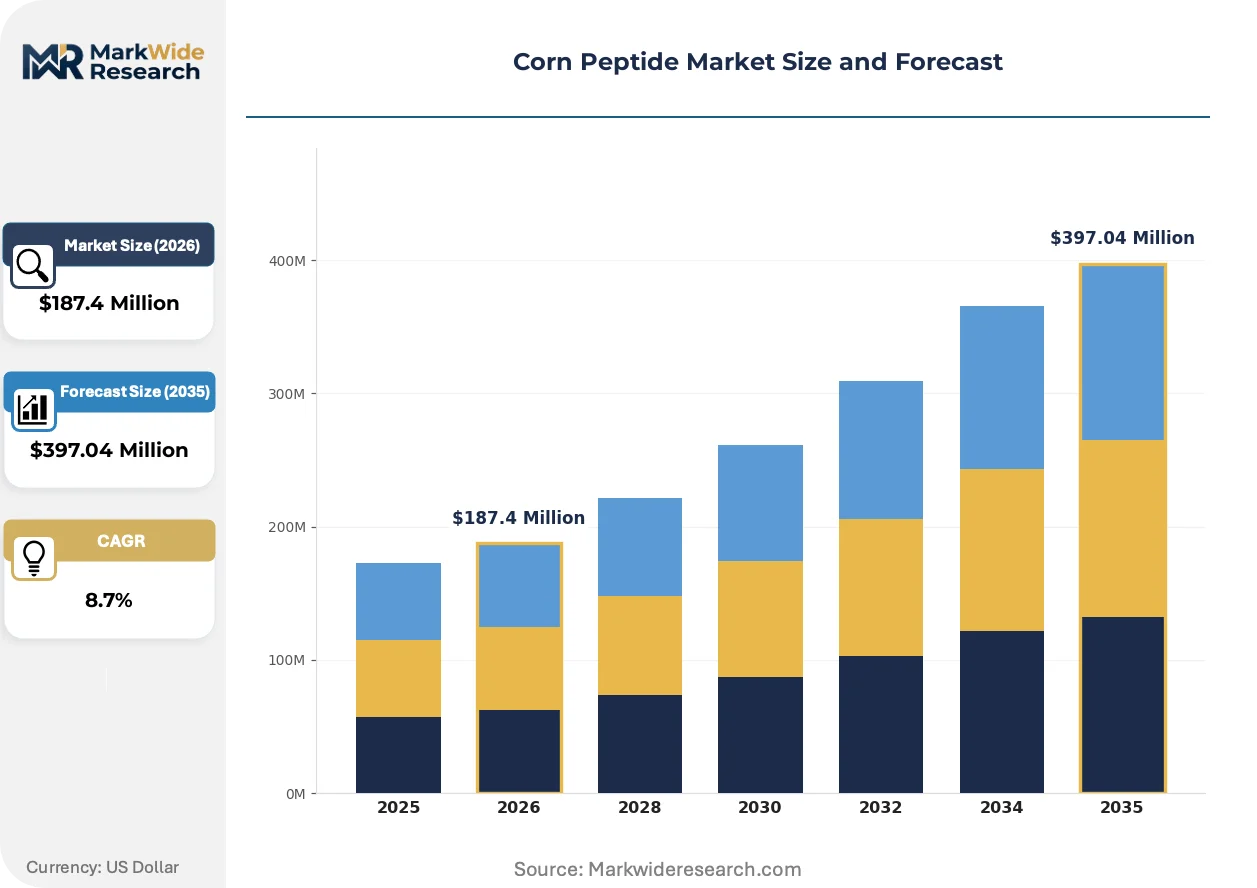
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Peptides, Isolated Peptides, Functional Peptides, Bioactive Peptides Application: Food & Beverages, Nutraceuticals, Cosmetics, Animal Feed End User: Food Manufacturers, Dietary Supplement Companies, Cosmetic Brands, Pet Food Producers Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Foodchem, ETChem, SmartPEP Biotech, WaterSolubleProtein, Yasin Gelatin, CRESCENT BIOTECH, Innova Flavors, Hubei Nutratide Biotech Co., Ltd, Zhongshi Duqing (Shandong) Biotech Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corn Peptide Market Evolving Landscape
Bioprocess intensification and regulatory claim specialization are fragmenting the competitive landscape into three capability tiers: commodity hydrolysate suppliers, functional-grade certifiers, and clinical-peptide developers. Each tier demands distinct capital deployment and technical staffing models.
Membrane filtration cascades with molecular-weight cut-offs below 5 kDa are migrating from pharmaceutical-grade albumin fractionation into corn peptide purification workflows. Nutraceutical contract manufacturers in China and Germany are retrofitting tangential-flow systems previously deployed for whey protein isolate production. This technology migration is enabling sub-1 kDa peptide isolation at tonnage scale, collapsing the historical purity-volume tradeoff that constrained cardiovascular-targeted applications.
EFSA's 2023 updated guidance on protein hydrolysate Novel Food submissions is tightening toxicological data requirements for peptide mixtures above 10 amino acid residues. European entrants must now submit full amino acid sequencing and in-silico allergenicity assessments, extending authorization timelines. Small-volume functional food innovators are responding by partnering with established Novel Food holders rather than pursuing independent dossiers, consolidating market access around incumbent regulatory specialists.
Certification-driven procurement is displacing commodity spot purchasing in dietary supplement channels. Large North American and European brands are mandating ISO 17025-accredited third-party testing for peptide content, heavy metals, and microbial specifications before contract execution. This behavioral shift is most visible in direct-to-consumer cardiovascular supplement verticals, where Amazon-driven review sensitivity amplifies quality failure risks and drives supplier consolidation toward documented GMP facilities.
Corn Peptide Market Segmentation
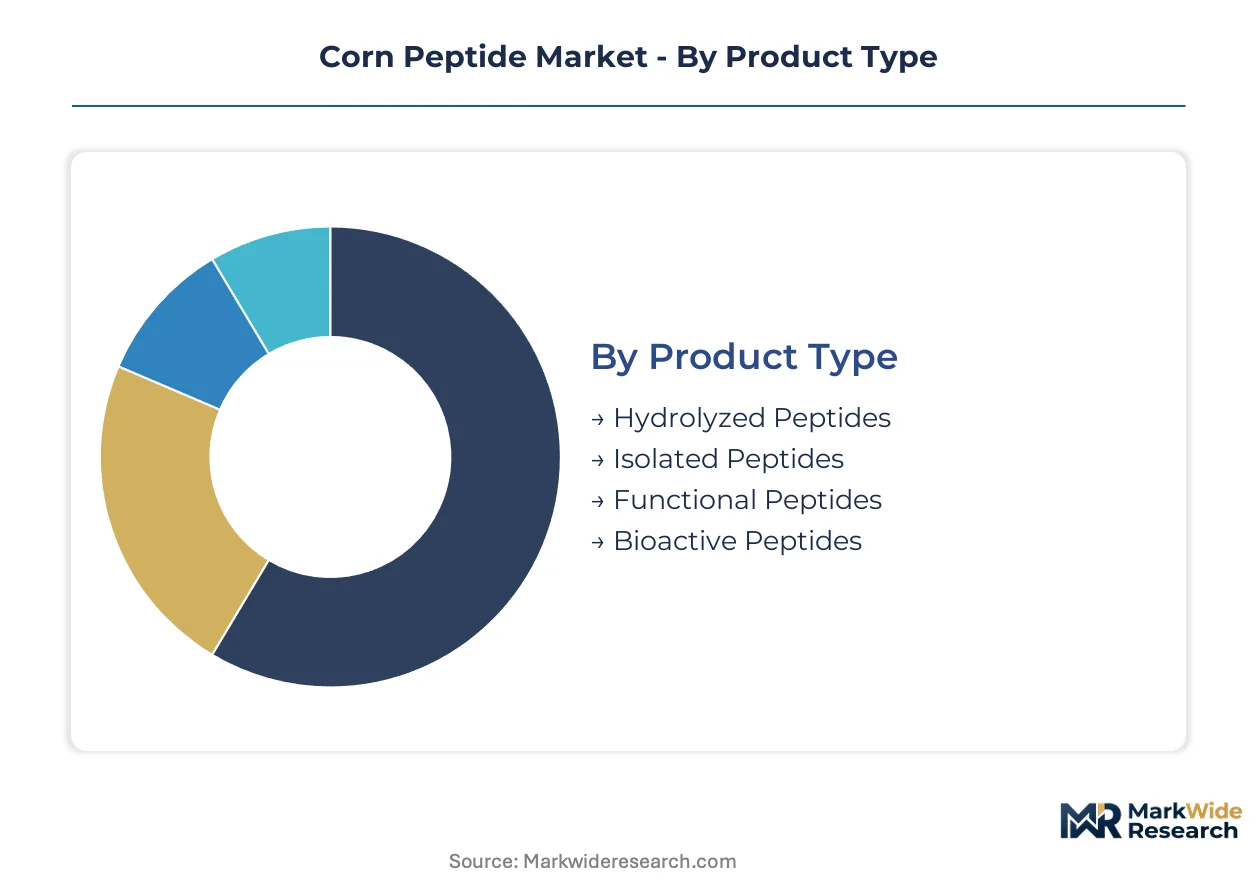
Corn peptide suppliers configure technical service teams differently across product tiers. Hydrolyzed grades demand minimal application support, while isolated and bioactive fractions require formulation guidance and regulatory documentation assistance.
Product Type:
After-sales intensity escalates sharply with purity tier. Hydrolyzed peptide buyers rarely request technical intervention beyond certificate-of-analysis verification. Isolated and functional grades trigger sustained engagement around stability testing and claim substantiation.
- Hydrolyzed Peptides:These constitute bulk enzymatic hydrolysates with molecular weight distributions typically spanning 1-10 kDa and protein content specifications above 80%. Demand concentrates in Shandong Province wet-milling corridors where corn gluten meal feedstock costs anchor regional supply economics.
- Isolated Peptides:Chromatography-purified fractions with defined molecular weight cut-offs below 3 kDa command premium positioning. Dietary supplement companies in Osaka and Tokyo drive procurement, requiring Japan Consumer Affairs Agency FOSHU dossier preparation support from suppliers.
- Functional Peptides:ACE-inhibitory and antioxidant fractions with validated bioactivity markers serve cardiovascular-targeted formulations.
- Bioactive Peptides:Emerging category of peptide sequences with demonstrated in-vivo physiological effects beyond basic nutritional value.
By volume, Hydrolyzed Peptides leads. By growth pace, Bioactive Peptides is ahead.
Application:
Application selection determines margin architecture and regulatory pathway complexity. Food and beverage channels prioritize cost efficiency and GRAS self-affirmation. Nutraceutical and cosmetic routes demand extensive safety documentation and claim validation.
- Food & Beverages:Protein fortification applications in meal-replacement bars and beverages leverage corn peptides for amino acid completeness. South Korean food manufacturers integrate these into products targeting MFDS labeling requirements for protein content claims.
- Nutraceuticals:Blood-pressure-modifying supplements and sports nutrition formulations represent the highest-value application tier. China's SAMR enforcement of GB standards for peptide purity creates compliance thresholds that filter supplier participation.
- Cosmetics:Topical antioxidant and anti-aging applications utilize low-molecular-weight fractions for dermal penetration.
- Animal Feed:Premium pet nutrition brands specify corn peptides as hypoallergenic protein alternatives to poultry and fish meals.
Food & Beverages commands absolute tonnage. Nutraceuticals generates the steepest margin expansion.
End User:
End-user sophistication shapes procurement modality and contract structure. Large food manufacturers negotiate annual volume agreements with indexed pricing. Dietary supplement companies operate on shorter procurement cycles with intensive quality auditing.
- Food Manufacturers:Industrial-scale buyers in China's processed food sector purchase hydrolyzed peptides by container load with standardized specification sheets.
- Dietary Supplement Companies:North American and European brands mandate ISO 17025-accredited third-party testing and GMP facility certification before contract execution.
- Cosmetic Brands:Korean beauty conglomerates and European natural cosmetics specialists source functional peptides for anti-aging serum formulations.
- Pet Food Producers:Premium pet nutrition manufacturers in the United States specify corn peptides for limited-ingredient diet lines targeting food-sensitive companion animals.
Food Manufacturers dominates procurement volume. Dietary Supplement Companies drives specification intensity and documentation requirements.
Distribution Channel:
Channel selection reflects buyer scale and technical support requirements. Direct sales relationships prevail for industrial volumes requiring customized peptide profiles. Online retail serves small-batch nutraceutical formulators with standardized catalog offerings.
- Online Retail:Alibaba and specialty ingredient platforms connect mid-size dietary supplement manufacturers with Chinese peptide suppliers, enabling sample procurement and small-volume orders without established direct relationships.
- Supermarkets:Mass-market protein powder and meal-replacement products reach consumers through retail shelf placement, with peptides embedded as undisclosed ingredients in finished goods.
- Health Stores:Specialized retailers in Japan and South Korea stock FOSHU-labeled cardiovascular supplements containing specified peptide fractions.
- Direct Sales:Long-term supply agreements between wet-milling operators and major food manufacturers bypass intermediary channels entirely.
Direct Sales captures the largest transaction values. Online Retail is expanding most quickly among emerging formulators lacking procurement scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nutraceutical formulators in East Asia drive procurement intensity, while European and North American buyers prioritize certification documentation. Wet-milling infrastructure and regulatory claim pathways shape geographic production advantages.
China
Shandong and Jilin provinces host concentrated wet-milling corridors where corn gluten meal recovery economics anchor peptide supply chains. SAMR enforces GB standards for peptide purity labeling and contaminant thresholds that filter supplier participation. Zhongshi Duqing leverages captive milling capacity in Shandong to dominate domestic hydrolyzed peptide volumes.
Japan
Osaka and Tokyo dietary supplement manufacturers drive premium procurement of isolated peptide fractions below 3 kDa molecular weight. Consumer Affairs Agency FOSHU approval for blood-pressure-modifying claims creates premium positioning for ACE-inhibitory sequences. Kansai-region formulators integrate these peptides into cardiovascular-targeted functional foods with documented clinical dossiers.
South Korea
Seoul-based sports nutrition and clinical nutrition companies integrate corn peptides into meal-replacement formulations to meet MFDS protein content labeling requirements. The expanding silver economy generates demand for sarcopenia-targeted peptide applications. Busan-Ulsan industrial clusters support contract manufacturing scale for regional nutraceutical brands.
Germany
EFSA Novel Food authorization requirements create 18-24 month entry delays for non-traditional peptide sources entering European nutraceutical channels. Bavaria and North Rhine-Westphalia host contract manufacturers retrofitting tangential-flow filtration systems for sub-1 kDa peptide isolation. German brands mandate ISO 17025-accredited third-party testing before contract execution.
United States
North American premium pet nutrition manufacturers specify corn peptides as hypoallergenic alternatives to poultry and fish meals for limited-ingredient diet lines. FDA enforcement discretion on structure-function claims shapes cardiovascular supplement positioning. Direct-to-consumer brands drive supplier consolidation toward documented GMP facilities through intensive quality auditing protocols.
Corn Peptide Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three capability tiers: commodity hydrolysate suppliers, functional-grade certifiers, and clinical-peptide developers. Wet-milling operators with captive corn gluten meal supply dominate volume positions, while fermentation-based specialists capture premium functional grades. Strategic moves center on regulatory dossier partnerships and membrane filtration capacity expansion.
Within the fermentation-specialist tier, SmartPEP Biotech occupies a position exemplifying proprietary platform approaches to functional peptide grades. Among Chinese wet-milling integrated players, Zhongshi Duqing (Shandong) Biotech Co., Ltd anchors domestic supply through upstream control over corn processing infrastructure. CRESCENT BIOTECH represents the regulatory-specialist archetype navigating European EFSA compliance documentation for market access.
| Leading Market Players |
|---|
| Foodchem |
| ETChem |
| SmartPEP Biotech |
| WaterSolubleProtein |
| Yasin Gelatin |
| CRESCENT BIOTECH |
| Innova Flavors |
| Hubei Nutratide Biotech Co., Ltd |
| Zhongshi Duqing (Shandong) Biotech Co., Ltd |
| Others |
Value Network & Pricing Analysis
Shandong Province wet-milling corridors anchor global corn peptide supply capacity, with captive corn gluten meal recovery economics translating directly into downstream pricing power for integrated processors. Zhongshi Duqing's upstream control over milling infrastructure enables indexed contract structures that buffer margin volatility for buyers while locking in volume commitments.
Pricing Analysis
Cost-plus contracts with corn gluten meal indexation dominate procurement between Shandong wet-millers and Chinese food manufacturers. Three-tier pricing structure across functional-grade certifiers, standard hydrolysate suppliers, and economy feed-grade producers reflects purity certification and FOSHU dossier support bundling. Cost compression in standard hydrolysate tiers is intensifying because membrane filtration technology migration collapses historical purity-volume tradeoffs. Dietary supplement companies in Japan and North America exhibit lowest price sensitivity due to mandatory ISO 17025 third-party testing requirements that filter supplier pools.
Supply Chain Analysis
Export-control scrutiny on precision fermentation platforms and enzymatic bioprocessing equipment from Germany and the United States constrains technology transfer into Chinese peptide production facilities. Supply concentrates in China, Japan, and South Korea, with raw material flows drawing from corn gluten meal streams, pharmaceutical-grade enzyme supplies, and chromatography resin stocks. Single-source vulnerability around Shandong wet-milling infrastructure creates geographic concentration risk. Distribution runs through direct long-term supply agreements for industrial volumes, with Alibaba and specialty ingredient platforms serving emerging formulators lacking procurement scale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Peptide characterization laboratories face acute shortages of mass spectrometry specialists capable of validating molecular weight distributions below 3 kDa, creating a bottleneck that constrains functional-grade certification capacity expansion.
For Market Incumbents: Harden regulatory dossier partnerships with established Novel Food holders to bypass EFSA authorization delays that deter mid-cap Asian competitors. Deepen backward integration into captive enzyme production to reduce dependency on pharmaceutical-grade bioprocessing supply chains threatened by export-control tightening. For New Entrants and Emerging Players: Establish a beachhead in North American premium pet nutrition channels where hypoallergenic protein positioning commands price premiums and quality auditing protocols remain less stringent than human nutraceutical certification. Target direct-to-consumer cardiovascular supplement verticals through Amazon-enabled distribution, leveraging review sensitivity to displace undocumented GMP suppliers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-specialist consolidation play because EFSA Novel Food authorization timelines and FOSHU dossier complexity create durable moats around incumbent documentation capabilities. The signal to watch is membrane filtration capacity expansion announcements in Bavaria and North Rhine-Westphalia, indicating European contract manufacturers' ability to isolate sub-1 kDa fractions at tonnage scale.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Capacity Expansion | Enables sub-1 kDa peptide isolation at tonnage scale for cardiovascular-targeted formulations. |
| FOSHU Dossier Partnership | Accelerates Japan market access for blood-pressure-modifying functional food claims. |
| Backward Integration into Enzyme Production | Reduces dependency on pharmaceutical-grade bioprocessing supply chains facing export constraints. |
| ISO 17025 Accreditation Investment | Meets North American and European dietary supplement quality auditing mandates. |
| Dual Carbon Policy Alignment | Positions peptide recovery from agricultural waste streams for China's MEE carbon intensity incentives. |
Research Methodology
A spread of perspectives from wet-milling operations managers, nutraceutical formulators, regulatory affairs specialists, and peptide characterization laboratory directors converged on the working assumptions driving this analysis. Primary fieldwork combined with secondary validation from SAMR GB standard filings, FOSHU approval databases, EFSA Novel Food catalogs, and customs trade records anchored supply-side and demand-side estimates. Bottom-up capacity assessments and top-down demand modeling were triangulated against enzymatic hydrolysis yield benchmarks.
Demand-supply balance dynamics across hydrolyzed, isolated, functional, and bioactive peptide tiers shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include molecular weight distribution, application channel complexity, end-user certification requirements, and regional regulatory pathway maturity. CAGRs were derived from peptide-specific adoption curves in cardiovascular and geriatric nutrition verticals, with input from zein recovery economics and membrane filtration technology diffusion rates.
Stress conditions across corn gluten meal price volatility, EFSA authorization timeline extensions, and precision fermentation substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding FOSHU claim harmonization and enzymatic hydrolysis cost compression trajectories. Material shifts in export-control enforcement on bioprocessing equipment or SAMR peptide purity threshold revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Orange Powder Market
Ingredients
Organic Edible Oil Market
Ingredients
Malted Wheat Flour Market
Ingredients
Mexico Sodium Reduction Ingredients Market
Ingredients
North America Soy Protein Concentrate Market
Ingredients
Synephrine Market
Ingredients
Green Gram Powder Market
Ingredients
Torula Yeast Market
Ingredients
Global Bioactive Ingredients Market
Ingredients
North America Milk Protein Market
Ingredients
North America Rice Bran Oil Market
Ingredients
Rapid-Set Gelatin Market
Ingredients
Grape Skin Extract Market
Ingredients
Amylase Market
Ingredients
Carotenoids Market
Ingredients
Edible Peanut Oil and Soybean Oil Market