
 Organic Virgin Coconut Oil Market | 2026-2036
Organic Virgin Coconut Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Virgin Coconut Oil Market Outlook
Philippines coconut processing capacity is reconfiguring export flows toward higher-margin organic virgin grades. Nutiva Inc. leverages direct farmer partnerships in Southeast Asia to secure raw material traceability. The Hain Celestial Group, Inc. sustains North American retail shelf presence through multi-channel distribution. Barlean's Organic Oils, LLC differentiates via cold-pressed specialization and transparency-focused branding.
Organic virgin coconut oil denotes unrefined oil extracted from fresh coconut meat without chemical solvents, retaining lauric acid concentrations typically between 45% and 53% and a smoke point near 177°C, serving food, cosmetic, and therapeutic applications. Cold-pressed variants command premium positioning in personal care formulations where nutrient retention justifies higher input costs. Expeller-pressed grades occupy mid-market food service channels where throughput economics outweigh extraction delicacy. Glass bottle packaging dominates premium cosmetic and gift segments, while plastic containers anchor mass-market food retail due to logistics efficiency.
USDA Organic certification governs U.S. market access, while EU Organic regulation and EFSA safety standards shape European import requirements, with both frameworks intensifying documentation demands on tropical-origin suppliers. FDA food safety oversight and cosmetic ingredient labeling rules add compliance layers for cross-border sellers. Stakeholders must monitor evolving organic integrity protocols and origin verification technologies to sustain supply chain credibility.
Market Dynamics
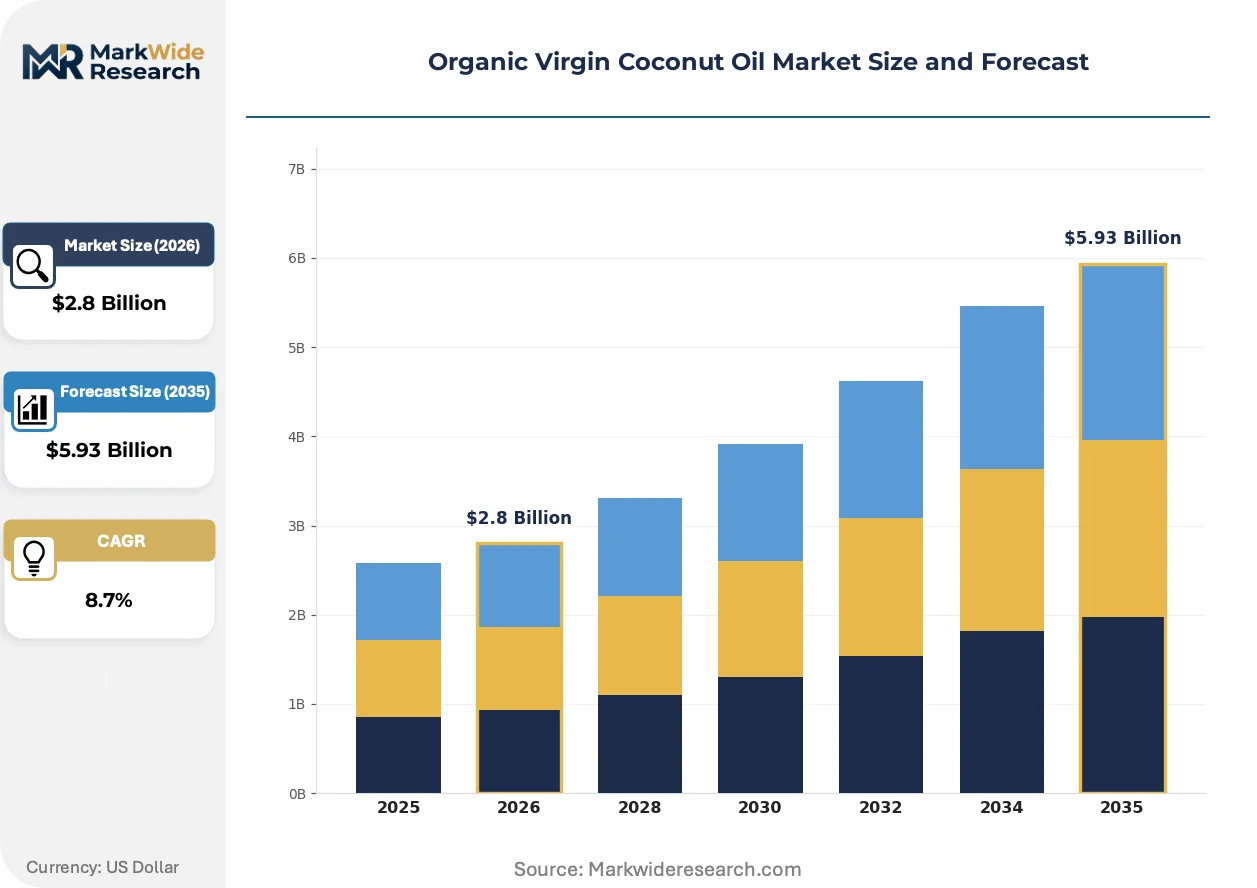
USDA Organic traceability mandates are forcing Southeast Asian processors to rebuild documentation infrastructure, while cold-pressed extraction capacity investments in the Philippines and Sri Lanka are reconfiguring competitive positioning toward premium cosmetic-grade supply.
Growth Catalysts
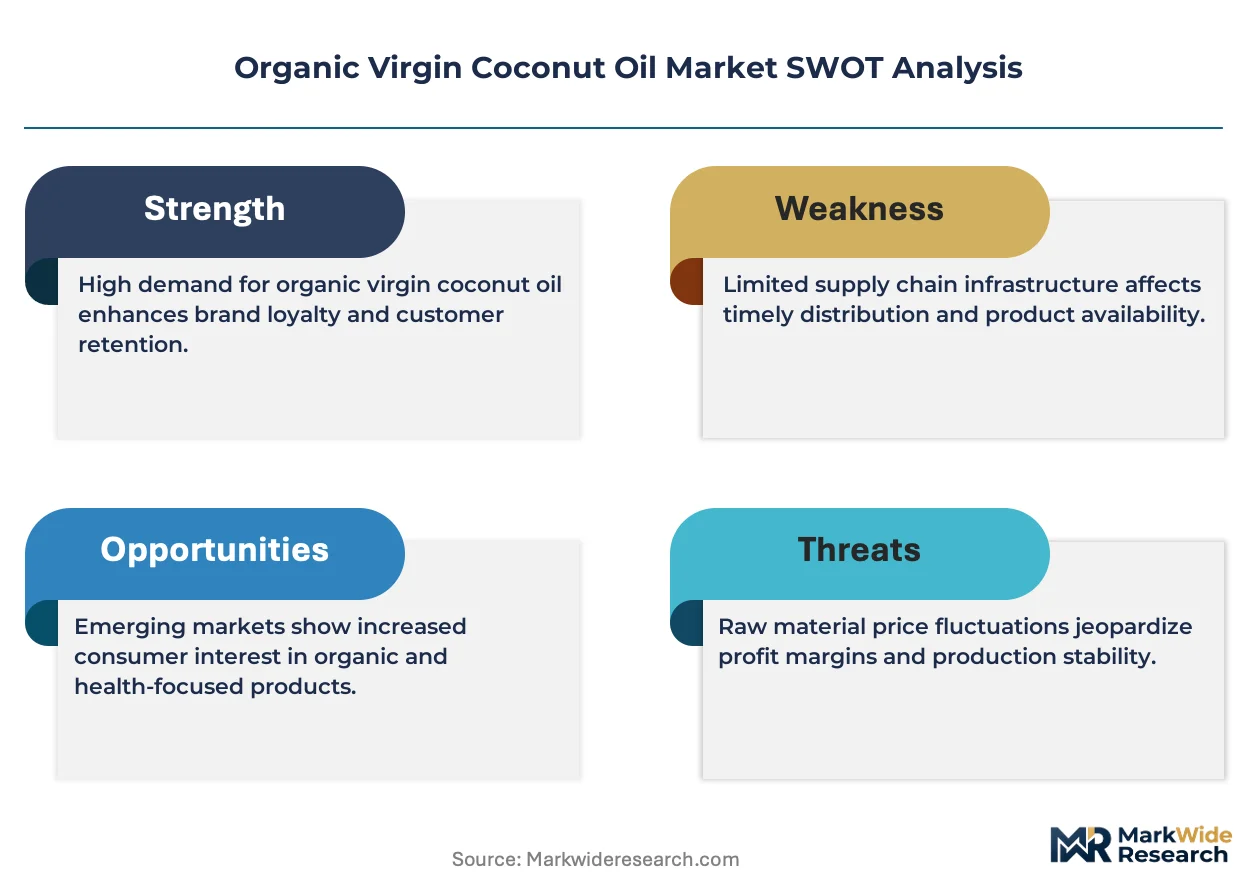
- Clean-label cosmetic formulation:Personal care brands in North America and Europe are reformulating with cold-pressed organic virgin coconut oil to replace petroleum-derived emollients.
- EU Organic regulation tightening:Enhanced documentation requirements for tropical-origin suppliers are accelerating digitization of farm-to-bottle traceability systems.
- Copra-processing cluster expansion:Established processing hubs in Indonesia are scaling cold-pressed capacity to capture higher-margin export segments.
Market Restraints
- Copra supply volatility:Weather-driven yield fluctuations in Philippine coconut estates create raw material cost instability for organic-certified processors.
- Extraction technology capex:Cold-pressed equipment requires substantially higher capital deployment than expeller-pressed alternatives, limiting processor upgrade velocity.
- Substitution by fractionated MCT oils:Cosmetic formulators in price-sensitive segments are switching to palm-derived caprylic/capric triglycerides for certain emollient applications.
Strategic Opportunities
- Pharmaceutical-grade lauric acid extraction:Therapeutic applications targeting antimicrobial and metabolic health properties remain underdeveloped relative to food and cosmetic uses.
- Direct-to-consumer subscription channels:E-commerce platforms enable bypass of conventional retail slotting fees for premium organic virgin grades.
- Carbon credit monetization:Philippine and Indonesian smallholder cooperatives can access voluntary carbon markets through regenerative coconut cultivation certification.
Industry Challenges
- Organic certification timeline compression:USDA Organic and EU Organic transition periods create multi-year revenue gaps for conventional-to-organic farm conversions.
- Cold-chain integrity for cosmetic-grade shipments:Temperature-controlled logistics from tropical origin to temperate-zone formulation facilities adds complexity and spoilage risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Virgin Coconut Oil Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold-Pressed, Expeller-Pressed, Refining Process, Organic Packaging Type: Glass Bottles, Plastic Containers, Tetra Packs, Pouches Application: Food Industry, Cosmetic Products, Pharmaceutical, Biofuels Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops |
| Companies Covered | Nutiva Inc., The Hain Celestial Group, Inc., Barlean's Organic Oils, LLC, Celebes Coconut Corporation, Greenville Agro Corporation, SPECTRUM ORGANIC PRODUCTS, LLC, Garden of Life, La Tourangelle, Carrington Farms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Virgin Coconut Oil Market Strategic Shifts
Extraction technology convergence with blockchain traceability systems is reshaping how organic integrity gets verified and monetized across tropical supply chains.
Cold-pressed centrifuge systems is hybridizing with IoT-enabled process monitoring to enable real-time quality parameter tracking during extraction. Cosmetic formulators in European personal care are adopting these instrumented lines fastest, typically completing equipment transitions within 18-month cycles. This technology convergence is compressing the premium-versus-commodity grade price spread by reducing batch-to-batch variability penalties.
EU Organic regulation documentation intensification is mandating granular farm-level record-keeping for all tropical-origin shipments entering European customs. Processors in Sri Lanka and the Philippines are deploying satellite-linked farm management systems to satisfy audit trail requirements. Smallholder-dependent supply chains face the steepest compliance cost escalation, driving consolidation toward estate-based sourcing models.
Ingredient provenance disclosure expectations among North American natural product retailers are forcing reformulation commitments with named cooperative partnerships. Clean-label skincare brands are replacing anonymous bulk sourcing with origin-specific storytelling on primary packaging. This behavioral shift concentrates procurement power with vertically integrated processors maintaining direct farmer relationships in Mindanao and Sulawesi.
Organic Virgin Coconut Oil Market Segmentation
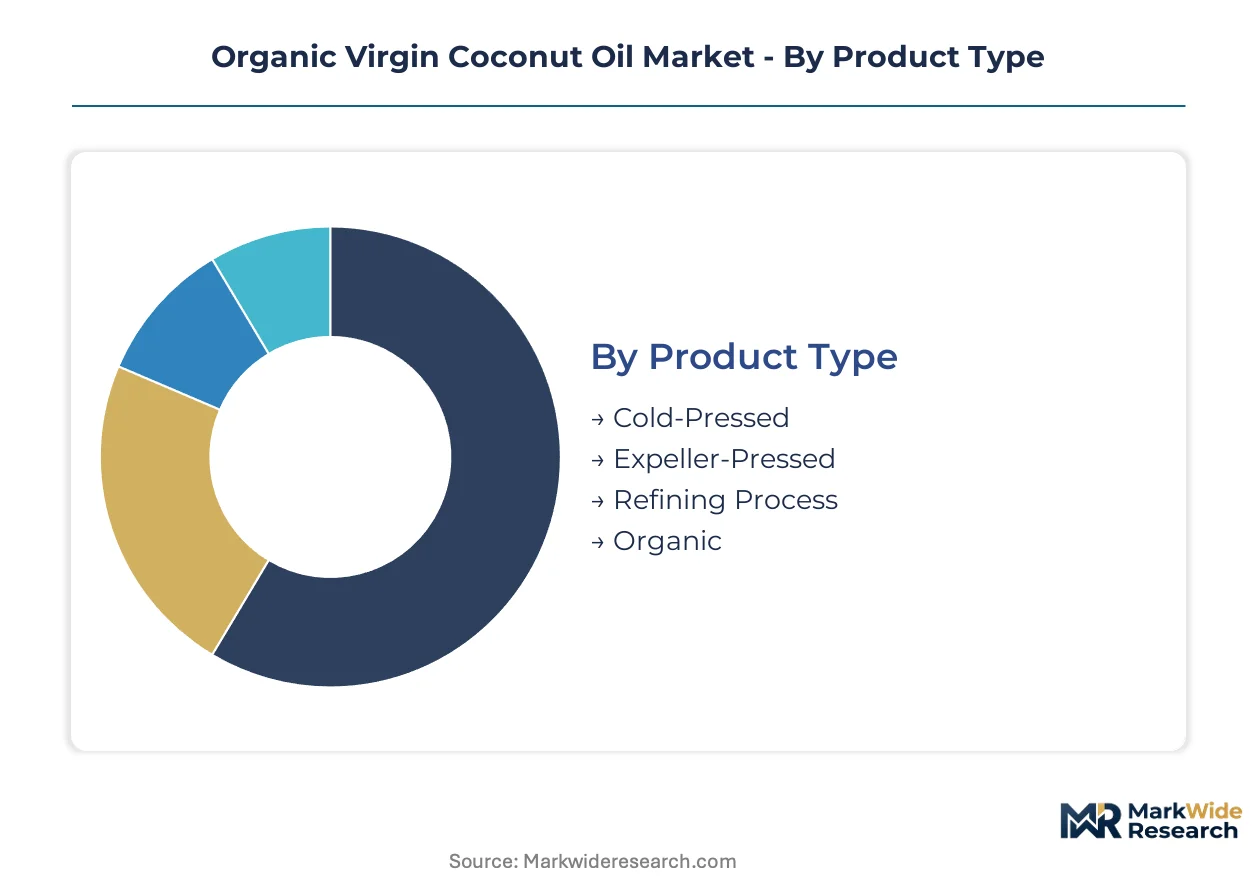
Organic virgin coconut oil pricing and procurement patterns diverge sharply across extraction methods, packaging formats, and end-use specifications. Understanding these segment boundaries reveals where margin compression concentrates and where premium positioning remains defensible.
Product Type:
Extraction technology defines the cost tier hierarchy, with mechanical delicacy and temperature control separating commodity grades from cosmetic-qualified output.
- Cold-Pressed:Fresh coconut meat undergoes mechanical pressing below 49°C, preserving lauric acid integrity above 50% and antioxidant profiles for cosmetic formulators in France and Germany. EU Organic documentation requirements for this grade are tightening fastest, driving Philippine processors toward IoT-enabled extraction monitoring.
- Expeller-Pressed:Higher-temperature mechanical extraction generates greater throughput volumes for food service channels, sacrificing some volatile compound retention. Indonesian copra-processing clusters dominate this mid-tier segment, serving Southeast Asian commercial bakery and frying oil markets.
- Refining Process:Minimal processing removes free fatty acids and moisture without solvent intervention; this segment bridges food-grade purity with cosmetic stability requirements.
- Organic:Certification compliance spans USDA Organic and EU Organic frameworks, with farm-level traceability systems now mandatory for market access rather than premium positioning alone.
Cold-pressed grades command the established base. The steepest expansion runs through certified organic segments as regulatory documentation intensifies.
Packaging Type:
Packaging selection maps directly to shelf positioning, with material cost and logistics efficiency trading off against premium perception and oxidation protection.
- Glass Bottles:Amber and cobalt glass dominates North American natural product retail, where UV protection and tactile quality signal cosmetic-grade purity. Direct-to-consumer subscription channels favor this format for unboxing experience differentiation.
- Plastic Containers:High-density polyethylene anchors mass-market food retail in the Philippines and Indonesia, where humidity resistance and drop-shipping durability outweigh aesthetic considerations.
- Tetra Packs:Aseptic carton formats extend shelf stability for tropical climate distribution without refrigeration dependency.
- Pouches:Flexible packaging reduces freight cube for bulk food service and private-label cosmetic manufacturing inputs.
Glass bottles retain margin leadership in cosmetic channels. Pouch formats are gaining share fastest in food service bulk procurement.
Application:
End-use specifications create divergent purity thresholds, with pharmaceutical and cosmetic segments imposing stricter contaminant limits than food processing.
- Food Industry:Virgin grades compete with refined coconut oil in baking, confectionery, and premium frying applications; smoke point stability near 177°C determines suitability for high-heat processing.
- Cosmetic Products:Cold-pressed organic grades replace petroleum-derived emollients in clean-label skincare, with lauric acid antimicrobial properties driving formulation interest among French and German personal care brands.
- Pharmaceutical:Lauric acid extraction for antimicrobial and metabolic health applications remains underdeveloped relative to food and cosmetic volumes.
- Biofuels:Virgin oil diversion into fuel applications remains marginal given premium pricing versus refined commodity alternatives.
Food industry volumes anchor current demand. Cosmetic product applications are climbing the fastest as clean-label reformulation accelerates.
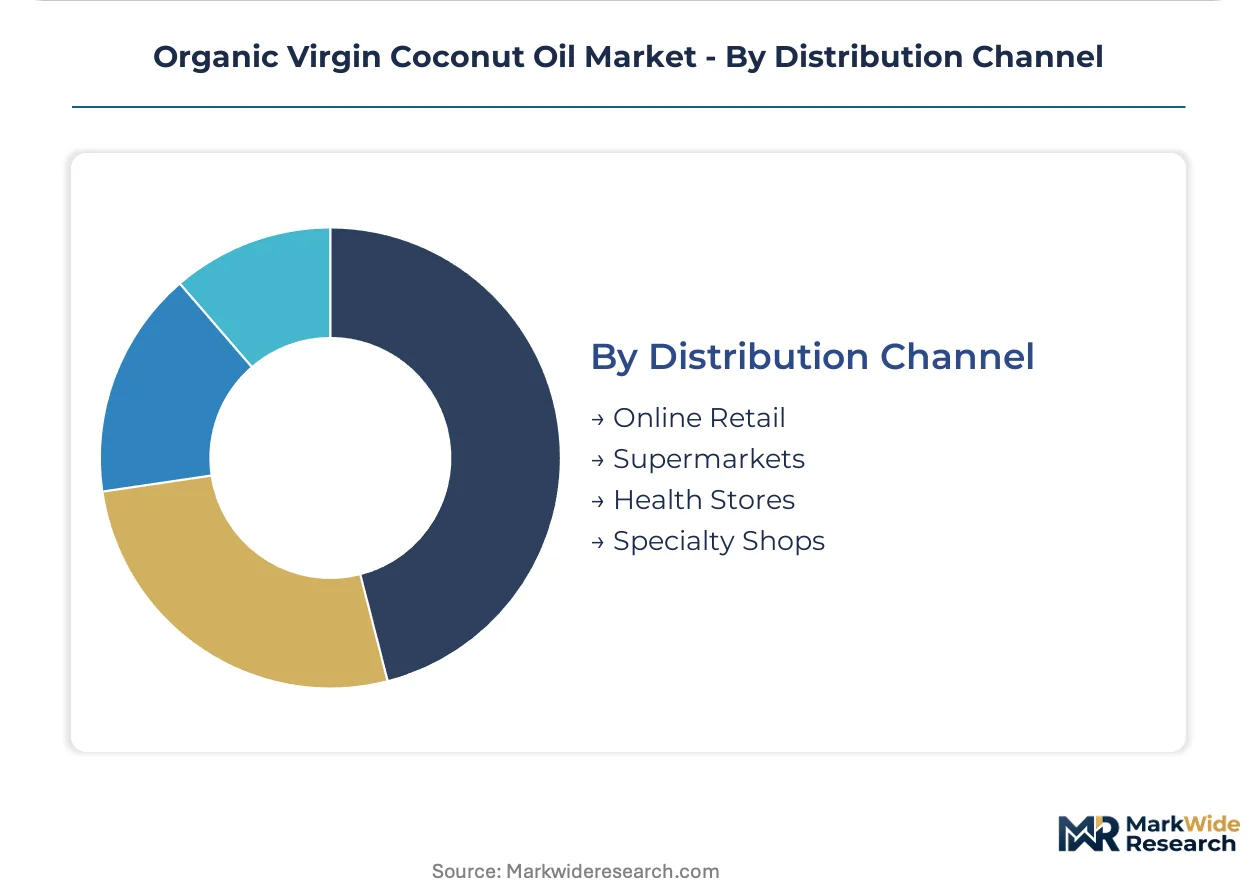
Distribution Channel:
Channel selection determines margin capture and brand control, with direct access enabling origin storytelling that anonymous bulk sourcing cannot support.
- Online Retail:E-commerce platforms bypass conventional retail slotting fees, enabling Philippine and Sri Lankan processors to build direct consumer relationships with full traceability disclosure.
- Supermarkets:Mass-market food retail in the United States and Germany concentrates volume through private-label programs, pressuring branded margin structures.
- Health Stores:Natural product retailers in North America demand named cooperative partnerships on primary packaging, concentrating procurement with vertically integrated Southeast Asian processors.
- Specialty Shops:Gourmet and cosmetic boutiques sustain premium pricing through curated assortment and educated staff recommendation.
Supermarket channels dominate volume throughput. Online retail is expanding most quickly as subscription models and direct origin storytelling reshape procurement relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copra-processing clusters in the Philippines, Sri Lanka, and Indonesia dominate organic virgin coconut oil supply chains, with each jurisdiction developing distinct regulatory and infrastructure responses to EU Organic documentation mandates and USDA traceability requirements.
Philippines
Mindanao-based cooperatives supply cold-pressed grades to North American cosmetic formulators seeking lauric acid retention above 50%. The Department of Agriculture's Organic Agriculture Program subsidizes farm-level certification transitions. Davao del Sur processors deploy satellite-linked farm management systems to satisfy EU Organic audit trail requirements for European-bound shipments.
Sri Lanka
German and French personal care brands source centrifuge-extracted organic grades from Gampaha and Kurunegala districts for clean-label skincare lines. The Sri Lanka Standards Institution enforces SLS 1329 for virgin coconut oil quality alongside EU Organic equivalence agreements. Southern Province estates consolidate smallholder supply through vertically integrated processing to reduce compliance cost burdens.
Indonesia
Sulawesi and North Sumatra copra clusters scale cold-pressed capacity to capture premium export segments previously served by Philippine suppliers. The Ministry of Agriculture's Organic Certification Agency coordinates with EU regulation updates on tropical-origin documentation. Manado processors invest in IoT-enabled extraction monitoring to reduce batch-to-batch variability penalties in cosmetic-grade contracts.
United States
California and Florida-based natural product retailers drive demand for glass-bottled, origin-specific organic virgin grades with named cooperative partnerships on primary packaging. FDA food safety oversight and cosmetic ingredient labeling rules add compliance layers for Southeast Asian exporters. Los Angeles and Miami distribution hubs specialize in temperature-controlled logistics for cosmetic-grade shipments from tropical origins.
Germany
EFSA safety standards and EU Organic regulation shape import requirements for Philippine and Sri Lankan shipments entering Rotterdam and Hamburg ports. Bavarian and Baden-Württemberg personal care manufacturers reformulate with cold-pressed organic grades to replace petroleum-derived emollients. Frankfurt-area importers digitize farm-to-bottle traceability systems to satisfy intensified documentation demands.
Organic Virgin Coconut Oil Market Competitive Environment
Vertically integrated Southeast Asian processors and North American brand-holders split the market between origin-controlled supply chains and retail channel dominance. The vendor base concentrates around three strategic archetypes: estate-based processors with direct farmer relationships, multi-channel brand-holders with supermarket and e-commerce presence, and cold-pressed specialists with transparency-focused positioning. Capacity expansion in Philippine and Sri Lankan extraction facilities and strategic partnerships for traceability technology licensing represent the dominant competitive moves.
Within the estate-processor archetype, Celebes Coconut Corporation and Greenville Agro Corporation represent Philippine and Indonesian sourcing consolidation. Among North American brand-holders, Nutiva Inc. and The Hain Celestial Group, Inc. occupy positions spanning retail shelf presence and direct-to-consumer channels. Barlean's Organic Oils, LLC exemplifies the cold-pressed specialization vector with transparency-focused branding. These named entities anchor industry-level commentary without implying specific strategic actions beyond archetype representation.
| Leading Market Players |
|---|
| Nutiva Inc. |
| The Hain Celestial Group, Inc. |
| Barlean's Organic Oils, LLC |
| Celebes Coconut Corporation |
| Greenville Agro Corporation |
| SPECTRUM ORGANIC PRODUCTS, LLC |
| Garden of Life |
| La Tourangelle |
| Carrington Farms |
| Others |
Value Chain & Pricing Dynamics
Davao del Sur's cold-pressed extraction cluster expansion is compressing premium grade premiums as Philippine processors add centrifuge capacity to serve EU Organic documentation requirements. USDA Organic traceability mandates and EU regulation tightening are forcing Southeast Asian suppliers to absorb compliance costs that downstream cosmetic formulators in Germany and France partially resist passing through.
Pricing Analysis
EU Organic regulation dictates the pricing tier structure across the organic virgin coconut oil market, separating cold-pressed cosmetic grades from expeller-pressed food service alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects extraction delicacy, lauric acid retention thresholds, and glass versus plastic packaging formats. Price differentiation hinges on named cooperative partnerships for North American health store channels versus anonymous bulk sourcing for supermarket private-label programs. Cost compression in mid-tier expeller-pressed segments is intensifying because Indonesian copra-processing clusters scale throughput capacity. Food service buyers demonstrate highest price sensitivity, while French and German cosmetic formulators accept premium positioning for traceability-verified cold-pressed grades.
Supply Chain Analysis
Export-control regimes on cold-press extraction technology limit equipment flows to Southeast Asian processors, constraining capacity upgrade velocity in Philippine and Sri Lankan facilities. Geographic supply concentration centers on the Philippines, Sri Lanka, and Indonesia as established copra-processing clusters. Raw material dependencies draw from Mindanao and Sulawesi smallholder cooperatives, Sulawesi estate-based sourcing models, and North Sumatra copra drying operations. Single-source vulnerability runs through weather-exposed Philippine coconut estates where typhoon damage disrupts organic-certified nut flows. Distribution runs through Rotterdam and Hamburg port entry for EU-bound cosmetic grades, Los Angeles and Miami temperature-controlled hubs for North American health store channels, and direct-to-consumer subscription platforms bypassing retail slotting fees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as palm-derived caprylic/capric triglycerides capture price-sensitive cosmetic emollient applications from virgin coconut oil. Fractionated MCT oils threaten volume retention in mid-market personal care segments.
For Market Incumbents: Harden organic certification moats by accelerating farm-level traceability digitization in Mindanao and Sulawesi to satisfy EU Organic audit trail compression. Deepen backward integration into estate-based sourcing models that reduce smallholder-dependent compliance cost escalation. Cold-pressed extraction capacity addition in Davao del Sur and Gampaha districts reinforces premium grade positioning against Indonesian throughput competitors. For New Entrants and Emerging Players: Pursue pharmaceutical-grade lauric acid extraction as an underdeveloped therapeutic application with antimicrobial and metabolic health properties. Direct-to-consumer subscription channels represent the most penetrable white space, enabling Philippine and Sri Lankan processors to bypass supermarket private-label margin compression. Go-to-market execution should anchor on blockchain-verified origin storytelling for North American natural product retailers demanding named cooperative partnerships. For Investors and Strategic Acquirers: Long-term, this sits as a certification-anchored specialty ingredients play because organic integrity protocols and traceability technology investments compound competitive positioning over multi-year horizons. Acquisition target archetype: vertically integrated Southeast Asian processors with direct farmer relationships and IoT-enabled extraction monitoring deployed. Watch EU Organic regulation enforcement intensity at Rotterdam customs as the signal for margin expansion or compression inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Pressed Capacity Expansion | Philippine processors in Davao del Sur deploy centrifuge systems to capture EU Organic cosmetic-grade contracts. |
| Blockchain Traceability Implementation | Satellite-linked farm management systems satisfy EU regulation documentation demands for tropical-origin shipments. |
| Direct-to-Consumer Channel Launch | E-commerce platforms enable Sri Lankan processors to bypass supermarket slotting fees with origin storytelling. |
| Pharmaceutical-Grade Extraction Investment | Lauric acid isolation for antimicrobial applications diversifies revenue beyond food and cosmetic segments. |
| Regenerative Cultivation Certification | Philippine and Indonesian cooperatives access voluntary carbon markets through sustainable farming protocols. |
Study Parameters
Operator-level perspectives from coconut processing plant managers, EU cosmetic formulator procurement leads, North American natural product retailer category buyers, organic certification auditors, and cold-press equipment manufacturers anchored the qualitative base. Secondary validation drew from USDA Organic integrity databases, EU Organic regulation filings, Sri Lanka Standards Institution quality certifications, Philippine Department of Agriculture subsidy records, and customs trade documentation. Bottom-up volume modeling triangulated against top-down market sizing across extraction method, packaging format, and end-use application segments.
Scenario-bracketing framed the analytical approach across the analysis window, with base, optimistic, and conservative trajectories reflecting regulatory enforcement intensity and substitution elasticity assumptions. Segmentation dimensions modeled include extraction technology tier, certification framework, packaging material, end-use purity specification, and distribution channel control structure. CAGRs derived from historical volume trajectories adjusted for capacity expansion announcements and organic farm conversion timelines. Forecast inputs incorporated copra yield volatility patterns and EU Organic documentation compliance cost escalation curves.
Sensitivities concentrate around EU regulation enforcement timing, Philippine weather-driven supply disruptions, and MCT oil substitution elasticity in cosmetic applications. Forecasts reflect documented assumptions on organic farm conversion rates and cold-pressed equipment deployment schedules. Material shifts in EU Organic tropical-origin documentation requirements or Philippine typhoon frequency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Egg Yolk Lecithin Market
Ingredients
Cooking Coconut Milk Market
Ingredients
Corn Peptide Market
Ingredients
Global Personal Care Active Ingredients Market
Ingredients
Gluten-Free Flour Market
Ingredients
Shortening Fats Market
Ingredients
Plant Based Thickener Market
Ingredients
Europe Edible Oil Market
Ingredients
Germany Gelatin Market
Ingredients
Glucomannan Market
Ingredients
Asia-Pacific Fats and Oil Market
Ingredients
Ingredients Market
Ingredients
Asia-Pacific Soy Protein Market
Ingredients
Europe Feed Yeast Market
Ingredients
Asia-Pacific Dairy Ingredients Market
Ingredients
Oak Extract Market