
 Vitex Agnus Castus Extract Market | 2026-2036
Vitex Agnus Castus Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Vitex Agnus Castus Extract Market Analytics
The EU Green Deal is realigning sourcing requirements for botanical extracts across European supply chains. Indena leverages its phytochemical extraction expertise to serve pharmaceutical clients seeking standardized vitexin content. Martin Bauer Group anchors its position through backward integration into raw herb cultivation across Mediterranean growing regions. Naturex competes on certified organic and sustainably wild-crafted supply tiers.
Vitex Agnus Castus extract is a lipophilic botanical concentrate derived from the dried fruit of Vitex agnus-castus L., typically standardized to 0.5% agnuside and 0.6% aucubin measured by HPLC, and functions primarily as a selective dopaminergic modulator for gynecological and endocrine applications. Capsule and tablet formats dominate volume due to dosing precision and shelf stability, while liquid extracts capture premium positioning in practitioner-channel distribution. The dietary supplements end-user segment leads absolute consumption, though pharmaceutical applications command higher purity premiums and stricter pharmacopeial compliance.
EMA guidelines on herbal medicinal products and the EU Traditional Herbal Medicinal Products Directive shape registration pathways and quality benchmarks for market access across member states. EFSA's evolving stance on botanical health claims is forcing reformulators to invest in clinical substantiation or pivot to generic wellness positioning. Stakeholders must monitor regulatory divergence between centralized EU procedures and national competent authority interpretations that fragment commercialization timelines.
Market Dynamics
EMA's tightening pharmacopeial standards for herbal medicinal products are compressing supplier qualification timelines and forcing extractors to invest in HPLC-standardized output. This regulatory pressure is redrawing competitive boundaries between pharmaceutical-grade and dietary supplement tiers.
Growth Catalysts
- EU Traditional Herbal Medicinal Products Directive:Centralized registration pathways in Germany and Austria are accelerating market access for standardized vitexin formulations.
- Dopaminergic modulation research:Expanding clinical validation for gynecological endocrine applications is pulling pharmaceutical procurement toward higher-purity extracts.
- Mediterranean cultivation clusters:Backward integration into raw herb sourcing across Spain and Greece is securing agnuside content consistency for premium suppliers.
Market Restraints
- Wild-crafted supply volatility:Climate stress on Vitex agnus-castus L. stands in Balkan harvesting zones is creating raw material lot-to-lot variation.
- EFSA health claims substantiation:The Nutrition and Health Claims Regulation's evidentiary demands are blocking label positioning for mid-tier extractors lacking clinical trial budgets.
- Synthetic hormone substitutes:Conventional pharmaceutical alternatives for menstrual disorders retain reimbursement advantages in several EU member states.
Strategic Opportunities
- Practitioner-channel liquid extracts:Compounding pharmacies in Switzerland and the Netherlands are building demand for non-capsule delivery formats with dosing flexibility.
- CSRD-aligned sustainable sourcing:The EU Corporate Sustainability Reporting Directive is creating procurement preference for certified organic and traceable wild-crafted supply tiers.
- Menopausal wellness positioning:Reformulation toward peri-menopausal symptom management is opening shelf space in pharmacy retail chains previously dominated by generic supplements.
Industry Challenges
- Phytochemical analytical talent scarcity:Qualified HPLC method development specialists are concentrated among contract research organizations, inflating in-house validation costs.
- Multi-jurisdictional dossier fragmentation:Divergent national competent authority interpretations of EMA herbal guidelines are extending registration timelines in Italy and France.
- Legacy extraction equipment retrofitting:Supercritical CO2 system upgrades required for residual solvent compliance are straining mid-capitalization processor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitex Agnus Castus Extract Market |
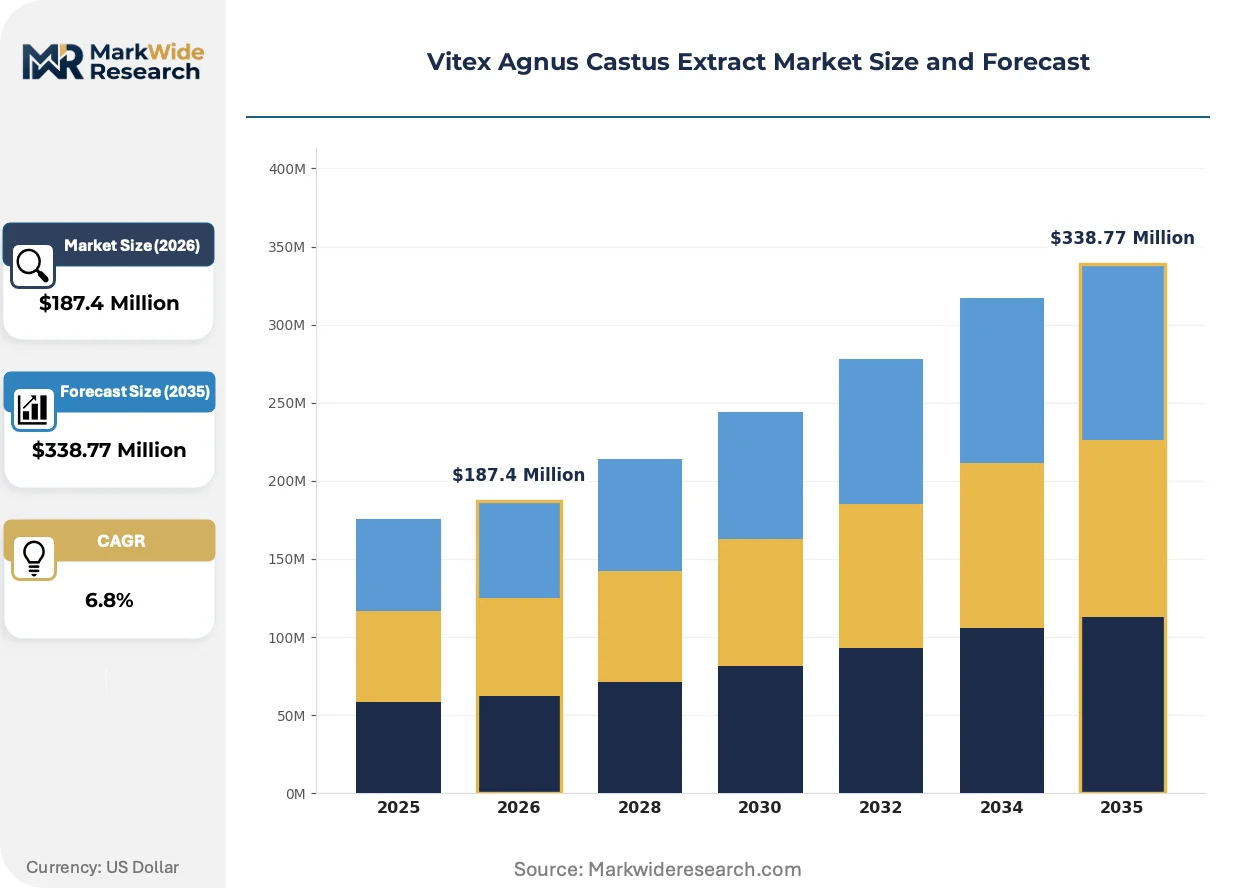
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Tablets, Liquid Extracts, Powders End User: Pharmaceuticals, Nutraceuticals, Cosmetics, Dietary Supplements Application: Menstrual Disorders, Hormonal Balance, Menopause Relief, PMS Management Distribution Channel: Online Retail, Health Stores, Pharmacies, Supermarkets |
| Companies Covered | Indena, Naturex, Martin Bauer Group, Pharmavit, Euromed, Blackmores, Swanson Health Products, Gaia Herbs, Now Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitex Agnus Castus Extract Market Evolving Landscape
Supercritical fluid extraction platforms are displacing conventional solvent-based methods, compressing processing timelines while aligning with EU Green Deal solvent reduction mandates. This technological pivot is redrawing cost structures across pharmaceutical and nutraceutical supply tiers.
Supercritical CO2 extraction technology is integrating selective agnuside recovery with tunable pressure parameters that preserve heat-sensitive aucubin fractions. German pharmaceutical contract manufacturers are adopting these systems at accelerated replacement cycles. The technology is integrating pharmaceutical-grade purity thresholds into mid-volume production runs previously confined to dietary supplement specifications.
REACH registration requirements for residual solvent profiling are forcing extractors to document sub-ppm n-hexane and ethanol traces across batch records. Industrial consequence includes mandatory third-party analytical certification for supply into medicinal product channels. Central European formulators are responding by consolidating supplier panels to pre-qualified extractors with dedicated quality control laboratories.
Direct procurement relationships between dietary supplement brands and Mediterranean cultivation cooperatives are disintermediating traditional herb traders. This channel compression is most visible in Austrian and German markets where origin transparency commands shelf price premiums. Practitioner-dispensed liquid formats are capturing preference share from retail capsule SKUs in Swiss and Dutch pharmacy networks.
Vitex Agnus Castus Extract Market Segmentation
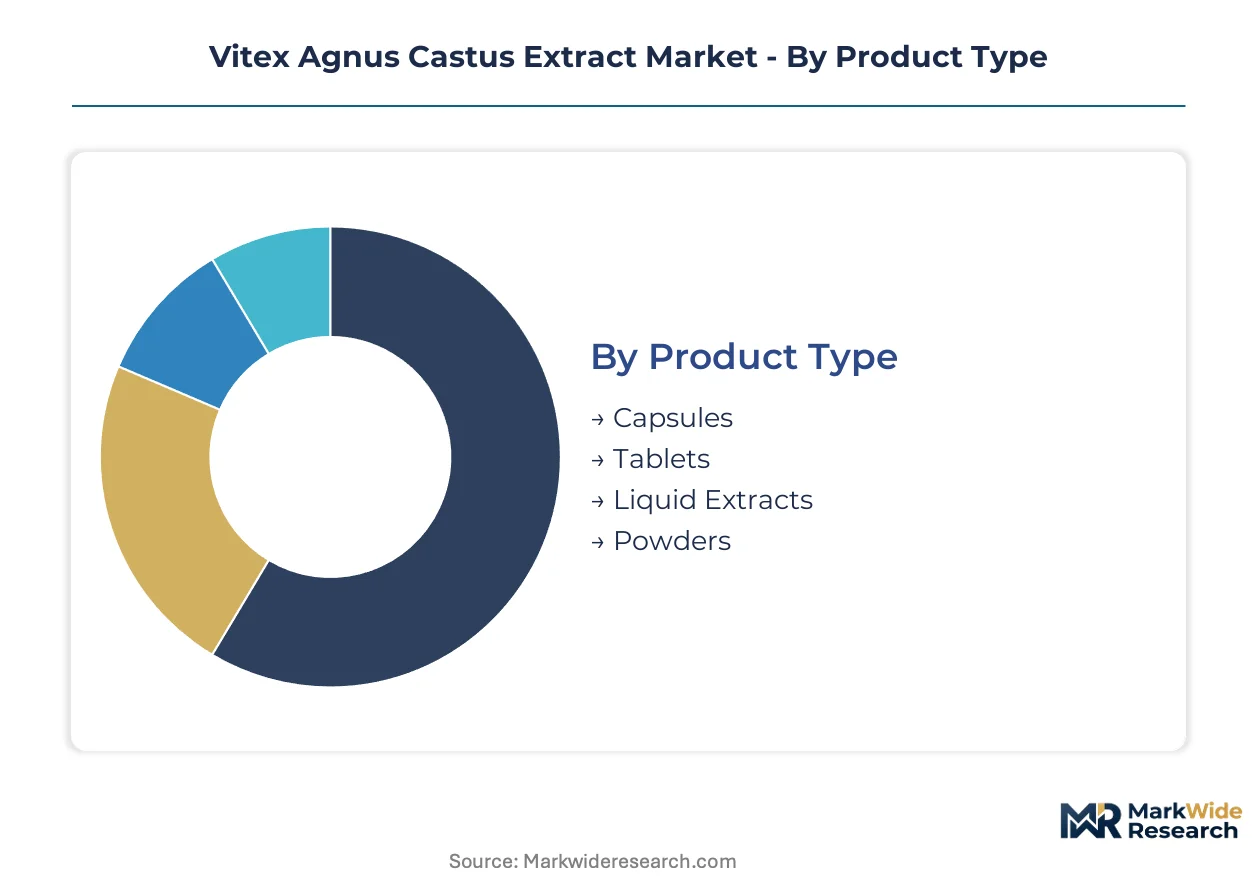
Segmentation in the Vitex Agnus Castus Extract Market reflects divergent purity requirements across pharmaceutical and wellness channels. Product format, end-use compliance tiers, and distribution access points each create distinct competitive battlegrounds for extractors and formulators.
Product Type:
Standalone single-herb formats dominate practitioner and pharmacy channels, while combination formulations embed vitex into broader hormonal wellness blends.
- Capsules:Hard gelatin and HPMC shells deliver precise unit dosing of 4-20mg standardized extract, with German pharmacies preferring blister-pack compliance formats. Demand concentrates in Central European retail pharmacy chains where EMA herbal registration supports reimbursement positioning.
- Tablets:Compressed matrices with binders and disintegrants enable higher payload per unit, serving cost-optimized dietary supplement SKUs. Austrian and German mass-market retailers drive procurement volumes for film-coated variants with extended shelf stability.
- Liquid Extracts:Hydroalcoholic tinctures with 1:5 or 1:10 concentration ratios capture Swiss and Dutch practitioner-channel preference for dosing flexibility.
- Powders:Bulk standardized extract with defined agnuside content serves contract manufacturers producing combination capsules and functional foods.
Capsules lead volumes today; liquid extracts are gaining share fastest in premium practitioner channels.
End User:
Regulatory compliance depth separates pharmaceutical-grade requirements from flexible nutraceutical positioning.
- Pharmaceuticals:EMA-registered herbal medicinal products demand full pharmacopeial compliance with documented HPLC batch release. German and Austrian national competent authorities enforce the strictest dossier requirements, compressing supplier qualification timelines to pre-qualified extractors only.
- Nutraceuticals:Food supplement frameworks under EFSA jurisdiction permit broader health positioning with reduced clinical substantiation burdens. German dietary supplement brands leverage this tier for peri-menopausal wellness SKUs lacking THR registration.
- Cosmetics:Topical applications in hormonal skin care utilize lower-concentration extracts with dermal safety documentation.
- Dietary Supplements:Generic wellness positioning captures volume in supermarket and online channels with minimal regulatory friction.
Pharmaceuticals command margin premiums; nutraceuticals expand volume fastest through pharmacy retail consolidation.
Application:
Clinical validation depth determines pricing power across symptom-specific positioning.
- Menstrual Disorders:Dysmenorrhea and irregular cycle management with dopaminergic prolactin suppression represents the most substantiated indication. German gynecological prescribing patterns favor standardized extracts with documented agnuside-aucubin ratios.
- Hormonal Balance:Broad endocrine modulation claims serve wellness-positioned SKUs with lighter evidentiary requirements.
- Menopause Relief:Peri-menopausal vasomotor symptom targeting opens pharmacy shelf space previously dominated by soy isoflavones and black cohosh.
- PMS Management:Premenstrual syndrome formulations compete with conventional selective serotonin reuptake inhibitors in reimbursement-sensitive markets.
Menstrual disorders anchor current volumes; menopause relief applications are expanding most quickly through pharmacy chain listings.
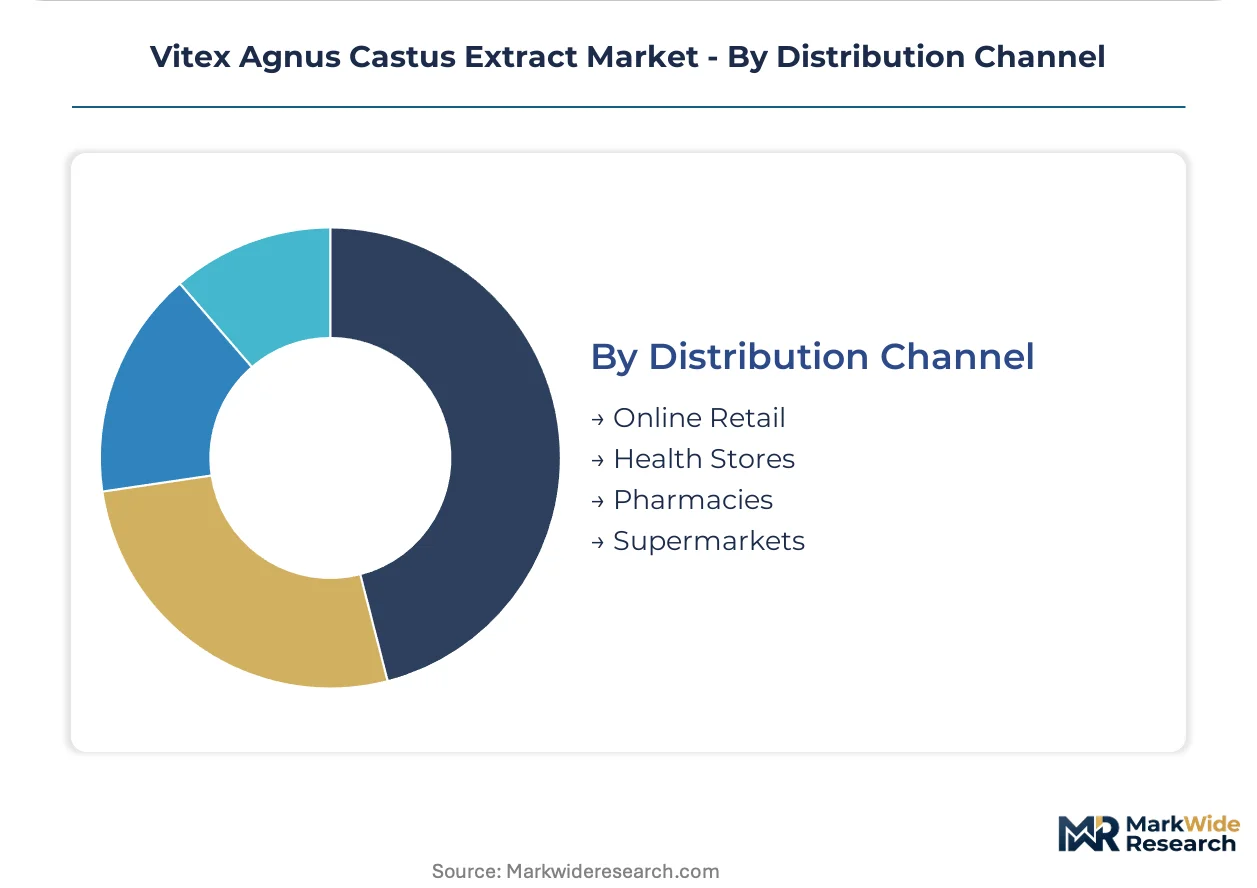
Distribution Channel:
Channel selection locks in margin structure and regulatory exposure simultaneously.
- Online Retail:Direct-to-consumer platforms bypass pharmacy margin stacking but face intensified EFSA health claim enforcement for botanical positioning. German and Austrian e-commerce operators invest in substantiation documentation to defend against competitor complaints.
- Health Stores:Specialized retailers with trained staff support premium liquid extract and practitioner-grade capsule formats. Swiss health store networks emphasize origin transparency and organic certification tiers.
- Pharmacies:Brick-and-mortar pharmacy chains in Germany and Austria maintain gatekeeper status for THR-registered products with reimbursement access.
- Supermarkets:Mass-market grocery channels drive commoditized capsule volumes with price-competitive positioning and minimal staff intervention.
Pharmacies retain the highest value concentration; online retail channels are climbing the fastest through subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade botanical extraction took root in Central Europe during the post-war era, with German and Austrian laboratories pioneering standardized vitexin isolation protocols that later diffused across Mediterranean cultivation zones.
Germany
EMA herbal registration pathways drive procurement of HPLC-standardized extracts with documented agnuside-aucubin ratios. The Federal Institute for Drugs and Medical Devices enforces strict pharmacopeial compliance for Traditional Herbal Medicinal Products. Bavarian contract manufacturers cluster around Munich and Nuremberg, upgrading supercritical CO2 systems to meet residual solvent thresholds.
Austria
Pharmacy retail chains in Vienna and Salzburg anchor demand for blister-pack capsule formats with reimbursement positioning. The national competent authority interprets THR directive requirements with particular rigor on clinical substantiation. Styrian processing facilities specialize in liquid extract compounding for practitioner-channel distribution.
Switzerland
Swissmedic registration creates parallel demand for both pharmaceutical-grade tablets and hydroalcoholic tinctures with dosing flexibility. The country's dual-track regulatory framework permits wellness positioning alongside medicinal claims. Zurich and Basel pharmacy networks emphasize origin transparency and organic certification tiers.
Spain
Mediterranean cultivation cooperatives in Valencia and Murcia supply raw herb with agnuside content consistency for premium extractors. Spanish agricultural regulators monitor organic certification compliance under EU Green Deal sustainable sourcing mandates. Andalusian extraction facilities serve as secondary processing hubs for Central European formulators.
Netherlands
Compounding pharmacies in Amsterdam and Rotterdam build procurement volumes for non-capsule delivery formats. The Dutch Medicines Evaluation Board applies EMA guidelines with streamlined registration timelines for standardized botanicals. Rotterdam port infrastructure facilitates bulk extract transit from Mediterranean suppliers.
Vitex Agnus Castus Extract Market Competitive Landscape
Capital-heavy extraction specialists compete with asset-light formulation brands for margin capture across pharmaceutical and nutraceutical tiers. The supplier base concentrates among pre-qualified extractors with dedicated quality control laboratories and backward integration into raw herb sourcing. Three archetypes dominate: Mediterranean-integrated cultivation specialists, Central European pharmaceutical-grade processors, and North American direct-to-consumer brands. Consolidation pressures favor M&A between extraction capacity and branded distribution, while technology licensing agreements spread supercritical CO2 platform adoption.
Within the pharmaceutical-grade tier, Indena and Martin Bauer Group exemplify extraction specialists with captive supply chain control, while Naturex occupies a position bridging certified organic and sustainably wild-crafted supply tiers. These three anchors represent divergent strategic postures on standardization depth and regulatory compliance investment.
| Leading Market Players |
|---|
| Indena |
| Naturex |
| Martin Bauer Group |
| Pharmavit |
| Euromed |
| Blackmores |
| Swanson Health Products |
| Gaia Herbs |
| Now Foods |
| Others |
Value Network & Pricing Analysis
Pharmaceutical-grade versus dietary supplement certification divergence creates parallel pricing architectures that reshape procurement patterns across Central European markets. EMA-registered THR products command three-to-five-fold premiums over generic wellness SKUs, while backward integration into Mediterranean cultivation clusters determines which extractors capture margin at each tier.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the market by pharmacopeial compliance depth and agnuside content consistency. Premium pharmaceutical-grade extracts with HPLC batch documentation and EMA registration capture the highest margins from German and Austrian pharmacy chains. Cost compression in the economy tier intensifies as mass-market dietary supplement brands consolidate supplier panels to pre-qualified extractors with dedicated quality control laboratories. Hospital procurement committees demonstrate lowest price sensitivity for documented efficacy, while supermarket buyers drive commoditization of unstandardized capsule formats.
Supply Chain Analysis
Raw herb supply rests on Mediterranean cultivation cooperatives in Spain, Greece, and Albania, with agnuside content variability creating lot-to-lot quality challenges for processors. Supercritical CO2 extraction equipment, HPLC analytical reagents, and pharmaceutical-grade packaging materials constitute critical input dependencies. Single-source vulnerability concentrates in Balkan wild-crafted harvesting zones exposed to climate stress and regulatory harvesting restrictions. Distribution runs through Rotterdam port infrastructure for bulk extract transit, with final-mile delivery splitting between pharmacy chain distribution centers and direct-to-compounder relationships in Switzerland and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as regulatory tightening on botanical health claims forces sustained investment in clinical substantiation, creating durable competitive moats for compliant operators.
For Market Incumbents: Lock in supplier qualification advantages by deepening backward integration into Spanish and Greek cultivation clusters before REACH residual solvent requirements expand. Invest in supercritical CO2 capacity upgrades to defend against mid-capitalization processors seeking pharmaceutical-grade tier access. Consolidate compounding pharmacy relationships in Switzerland and the Netherlands to preserve practitioner-channel premium positioning against liquid extract entrants. For New Entrants and Emerging Players: Supercritical fluid extraction technology with tunable pressure parameters offers entry into practitioner-channel liquid formats where dosing flexibility commands shelf price premiums. Target Dutch compounding pharmacies and Swiss health store networks with certified organic supply tiers aligned to CSRD procurement mandates. Build direct procurement relationships with Valencia and Murcia cultivation cooperatives to disintermediate traditional herb traders and capture origin transparency premiums. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-capitalization processors lack balance sheet capacity for supercritical CO2 system retrofits required by EMA residual solvent thresholds. The market reads as a 5-10 year compounder anchored by irreversible regulatory compliance depth and pharmacy channel gatekeeper dynamics. Monitor EFSA health claim enforcement intensity as the inflection signal: accelerated substantiation demands will accelerate supplier panel consolidation toward pre-qualified extractors with captive quality control infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mediterranean Cultivation | Spanish and Greek cooperatives secure agnuside content consistency for EMA-registered supply tiers. |
| Supercritical CO2 Capacity Expansion | German contract manufacturers compress processing timelines while meeting EU Green Deal solvent reduction mandates. |
| Clinical Substantiation Investment | EFSA health claim compliance opens pharmacy shelf space previously blocked for mid-tier extractors. |
| Practitioner-Channel Liquid Format Development | Swiss and Dutch compounding pharmacies build procurement volumes for non-capsule delivery with dosing flexibility. |
| CSRD-Aligned Sustainable Sourcing Certification | Certified organic and traceable wild-crafted tiers capture procurement preference under EU Corporate Sustainability Reporting Directive. |
Research Methodology
Direct dialogue with extraction facility managers, EMA regulatory affairs specialists, pharmacy procurement directors, and botanical cultivation cooperative leaders grounded the qualitative foundation. Secondary validation drew from EMA herbal medicinal product registrations, EU Nutrition and Health Claims Regulation submissions, REACH residual solvent documentation, and Mediterranean agricultural export statistics. Bottom-up volume modeling across product formats and end-use tiers triangulated against top-down market sizing from trade flow analysis.
Bottom-up segment-level modeling across capsules, tablets, liquid extracts, and powder formats integrated with end-user stratification by pharmaceutical, nutraceutical, and dietary supplement compliance tiers. The analytical framework projected value expansion throughout the forecast period using CAGRs derived from historical pricing trajectory analysis and penetration rate assumptions for menopause relief applications. Key inputs included EMA registration timeline data, supercritical CO2 adoption curves among Central European processors, and pharmacy chain SKU listing velocity for THR-registered products.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA health claim enforcement intensity, climate stress on Balkan wild-crafted stands, and synthetic hormone substitute reimbursement policy shifts. A small set of triggers—EMA pharmacopeial standard revisions, CSRD procurement mandate expansion, and supercritical CO2 equipment financing availability—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Asia-Pacific Fats and Oil Market
Ingredients
North America Wheat Protein Ingredients Market
Ingredients
Asia-Pacific Lipids Market
Ingredients
Medium Chain Triglyceride (MCT) Oil Market
Ingredients
Fish Gelatin Market
Ingredients
Fermented Rennet Market
Ingredients
Mung Bean Protein Market
Ingredients
Egg Replacement Ingredients Market
Ingredients
Europe Whey Protein Ingredients Market
Ingredients
Salt Content Reduction Ingredients Market
Ingredients
India Bakery Ingredients Market
Ingredients
Potato Protein Market
Ingredients
Green Gram Powder Market
Ingredients
Horehound Extract Market
Ingredients
EPA and DHA Omega-3 Ingredient Market
Ingredients
GCC Bakery Ingredients Market