
 North America Rice Bran Oil Market | 2026-2036
North America Rice Bran Oil Market Size, Share, and Industry Trends Forecast 2026-2036
North America Rice Bran Oil Market Intelligence
Aftermarket nutritional consulting and private-label formulation services is rewriting margin capture across the value chain. Riceland Foods leverages its integrated milling and refining infrastructure across Arkansas and Louisiana to control supply from paddy to bottle. Cargill Corporation competes through bulk oil distribution networks that sustain volume relationships with major foodservice operators. California Rice Oil Company specializes in cold-pressed variants that occupy premium shelf positions in West Coast health food retail.
North America rice bran oil is a refined vegetable lipid extracted from the outer bran layer of Oryza sativa, containing gamma-oryzanol at concentrations between one and two percent and a smoke point of approximately 232 degrees Celsius for refined grades. The oil serves commercial food processing, cosmetic emulsion manufacturing, and pharmaceutical excipient applications where oxidative stability and neutral flavor profiles matter. Refined oil dominates volume throughput due to its suitability for frying and industrial baking, while cold-pressed oil commands premium positioning among clean-label consumers seeking minimal processing. The food industry application anchors overall demand through fryer oil replacement programs in quick-service restaurant chains, though cosmetics represents the fastest-growing outlet as formulators replace mineral oil in skin-care products.
The FDA governs nutritional content claims and GRAS status determinations that shape product positioning and label architecture for rice bran oil sold in the United States. Health Canada and the PMRA coordinate on maximum residue limits for imported bran feedstocks, while the USDA oversees organic certification pathways that premium brands pursue. Stakeholders must monitor evolving trans-fat disclosure rules and sustainable sourcing mandates that will determine which suppliers retain access to major retail and foodservice accounts.
Market Dynamics
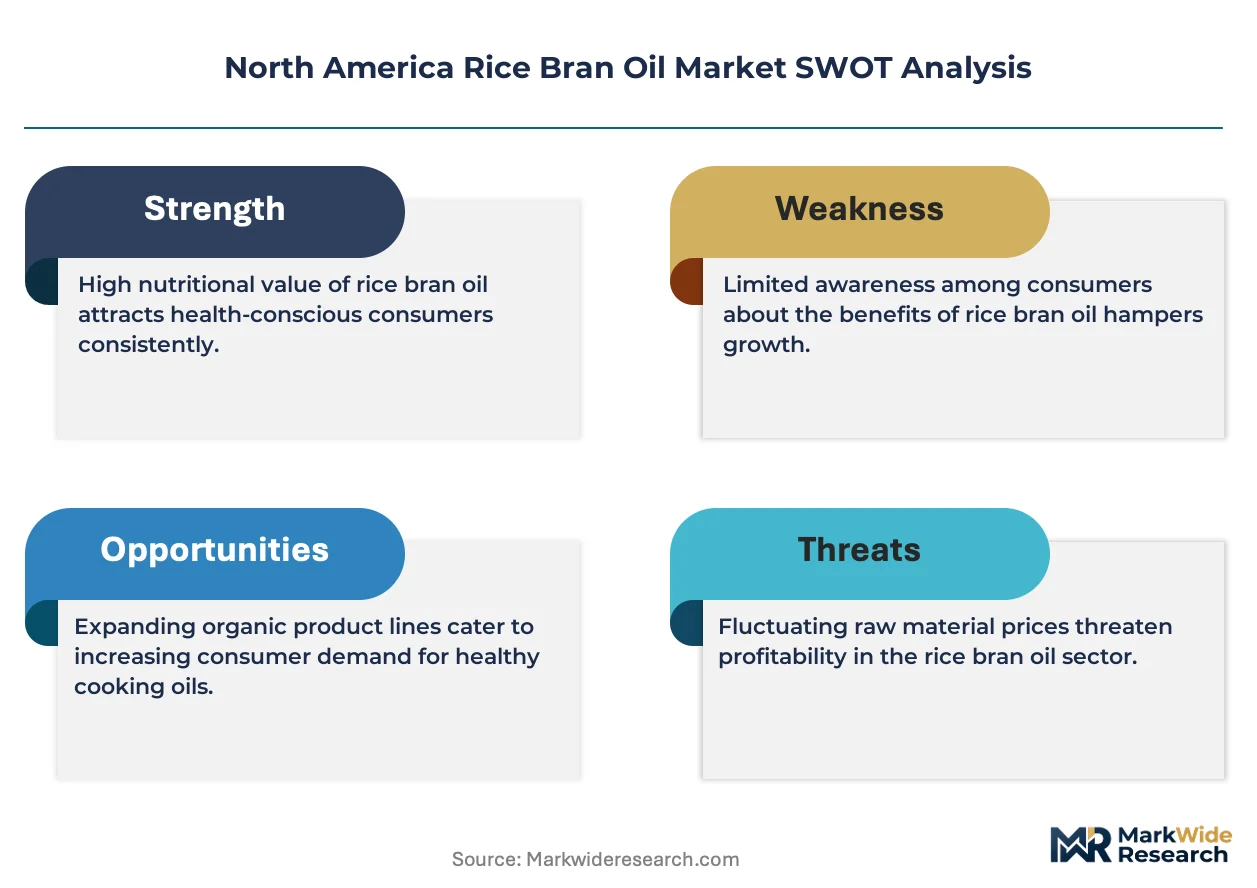
Integrated milling-refining infrastructure in Arkansas and Louisiana is compressing supply chain margins and locking out smaller traders who lack captive bran sourcing. This consolidation is forcing independent refiners toward tolling arrangements or specialty cold-pressed positioning.
Growth Catalysts
- High-heat cooking adoption:Quick-service restaurant chains across California's Central Valley are replacing soybean and palm oils with rice bran oil for fryer applications, drawn to its 232°C smoke point and neutral flavor profile.
- FDA nutritional labeling updates:Trans-fat disclosure requirements are accelerating reformulation decisions among packaged food manufacturers seeking plant-based lipid alternatives with favorable fatty acid profiles.
- Cosmetic mineral oil displacement:Formulators in skin-care emulsions are substituting rice bran oil for mineral oil, leveraging gamma-oryzanol content at 1-2% concentration for antioxidant claims.
Market Restraints
- Input cost volatility:Rice bran availability fluctuates with paddy harvest cycles in the U.S. Gulf Coast corridor, creating feedstock pricing instability for non-integrated refiners.
- Supply concentration risk:Arkansas and Louisiana control the majority of North American milling capacity, creating geographic single-point vulnerability for bulk oil procurement.
- Substitution threat:High-oleic sunflower oil and refined avocado oil compete directly for premium frying and clean-label positioning, often at lower unit costs.
Strategic Opportunities
- Canadian market underpenetration:Health Canada and PMRA coordination on residue limits has slowed entry, but organic certification pathways through the USDA offer premium positioning for West Coast brands expanding north.
- Pharmaceutical excipient applications:Oxidative stability and neutral flavor profiles position rice bran oil as a replacement for synthetic excipients in soft-gel formulations.
- Direct-to-foodservice distribution:Bulk oil distributors are bypassing traditional retail channels to establish volume relationships with regional restaurant chains and institutional buyers.
Industry Challenges
- Organic certification timelines:USDA organic pathways for rice bran oil require multi-year field history documentation and third-party audit cycles that delay premium product launches.
- Capex intensity for cold-pressed capacity:Mechanical pressing equipment and temperature-controlled storage infrastructure demand capital outlays that strain mid-scale entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Rice Bran Oil Market |
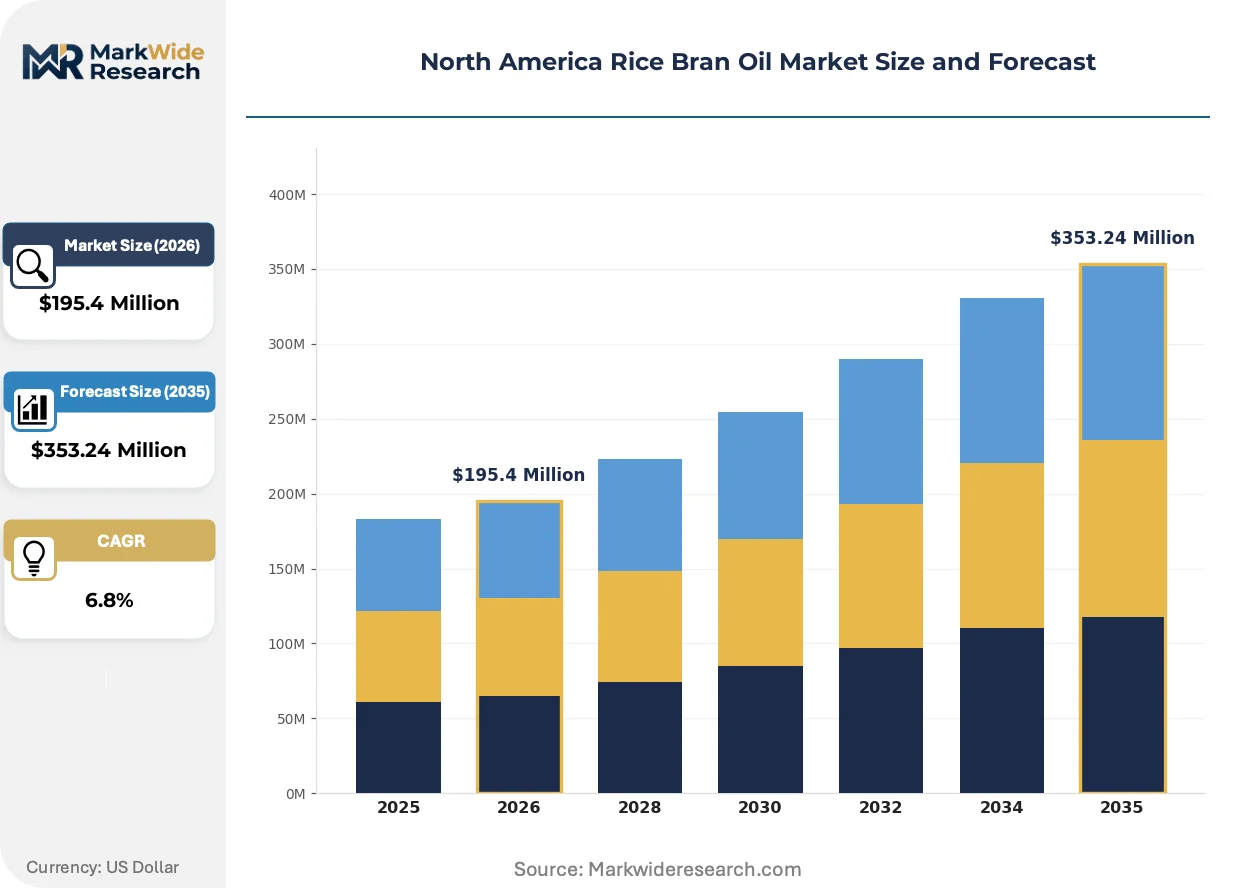
| Market Size in 2026 | $195.4 Million |
| Market Size in 2035 | $353.24 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Oil, Crude Oil, Cold-Pressed Oil, Unrefined Oil Application: Food Industry, Cosmetics, Pharmaceuticals, Biofuels Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops Form: Bottled Oil, Bulk Oil, Packaged Oil, Spray Oil |
| Companies Covered | Riceland Foods, King Rice Oil Group, Cargill Corporation, Ricela Health Foods Ltd., Marico Limited, California Rice Oil Company, RiceBran Technologies, 3F Industries Ltd., Conagra Brands, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Rice Bran Oil Market Strategic Shifts & Innovations
Processing technology and regulatory disclosure requirements are restructuring how rice bran oil moves from bran layer to end-use formulation. These shifts are compressing traditional trading margins while opening specialty positioning for differentiated grades.
Enzymatic degumming and membrane filtration systems are replacing conventional chemical refining for high-value cosmetic and pharmaceutical grades. California-based specialty refiners are adopting these systems to preserve gamma-oryzanol integrity and achieve clean-label certification. Chemical refining infrastructure is rendering obsolete for premium segment supply, forcing conventional refiners toward commodity foodservice volume or equipment write-downs.
Health Canada and PMRA coordination on maximum residue limits for imported bran feedstocks is tightening entry protocols for non-domestic supply. This regulatory friction is elevating traceability requirements and lot-level documentation burdens across the value chain. U.S. Gulf Coast integrated millers with captive paddy sourcing are capturing margin expansion as cross-border feedstock flows face extended clearance timelines.
Clean-label preference is rotating procurement authority from commodity traders to formulation consultants who specify oil grades by processing method and fatty acid profile. West Coast health food retail and specialty food manufacturers are contracting directly with California Rice Oil Company and similar cold-pressed specialists, bypassing traditional bulk distributors. This disintermediation concentrates in California's Central Valley and coastal metropolitan markets where consumer literacy on processing methods is highest.
North America Rice Bran Oil Market Segmentation
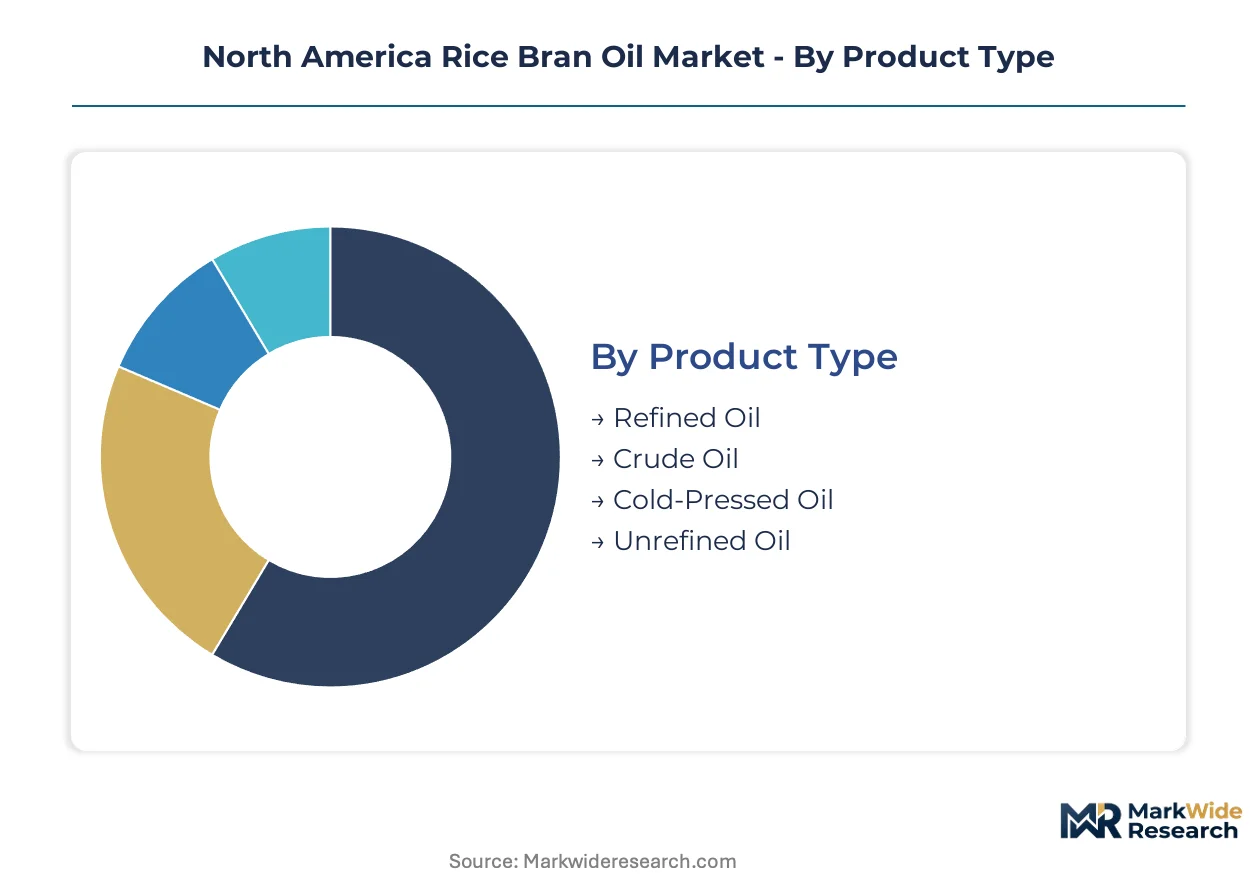
Segmentation in North American rice bran oil markets reveals how processing methods, end-use specifications, and channel economics split value capture across vastly different margin structures. Each dimension carries distinct regulatory footprints and capital requirements that determine viable competitive positioning.
Product Type:
Processing intensity spans from minimal mechanical extraction to full chemical refinement, creating four distinct value tiers with incompatible equipment footprints.
- Refined Oil:Chemical or physical refining removes free fatty acids and phospholipids, yielding a 232°C smoke point suitable for high-heat frying. Arkansas and Louisiana integrated millers dominate supply to quick-service restaurant chains across the U.S. Gulf Coast corridor, where fryer oil replacement programs drive volume procurement.
- Cold-Pressed Oil:Mechanical extraction below 50°C preserves gamma-oryzanol at 1-2% concentration for antioxidant positioning. California's Central Valley health food retailers and West Coast specialty manufacturers contract directly with California Rice Oil Company, bypassing commodity distributors for clean-label claims.
- Crude Oil:Initial expeller output retains waxes and gums, serving as feedstock for downstream refiners or niche industrial applications requiring minimal processing.
- Unrefined Oil:Filtered only for particulates, this grade carries pronounced bran flavor and limited shelf stability, appealing to ethnic food processors and traditional cooking segments.
The dominant share belongs to Refined Oil, while Cold-Pressed Oil is closing the gap fastest.
Application:
End-use requirements diverge sharply on oxidative stability, flavor neutrality, and regulatory certification burdens.
- Food Industry:Fryer oil replacement programs in quick-service restaurants and industrial baking operations anchor volume demand. FDA nutritional labeling updates on trans-fat disclosure accelerate reformulation toward rice bran oil's favorable fatty acid profile in packaged food manufacturing.
- Cosmetics:Skin-care formulators substitute rice bran oil for mineral oil, leveraging gamma-oryzanol content in emulsion products. California-based specialty refiners deploy enzymatic degumming and membrane filtration to achieve clean-label certification for premium cosmetic grades.
- Pharmaceuticals:Oxidative stability and neutral flavor profiles position the oil as a replacement for synthetic excipients in soft-gel formulations.
- Biofuels:High free fatty acid crude streams feed renewable diesel and biodiesel production, though competition with food-grade valorization limits dedicated supply.
Food Industry commands the volume base, yet Cosmetics is expanding most quickly as mineral oil displacement accelerates.
Distribution Channel:
Channel selection determines margin capture and brand control, with direct relationships displacing traditional wholesale in premium tiers.
- Online Retail:Direct-to-consumer platforms enable West Coast cold-pressed specialists to reach health-literate buyers nationwide, bypassing retail slotting fees and capturing full margin.
- Supermarkets:Mass retail placement demands price-competitive refined grades and supplier-funded promotional support, favoring integrated millers with scale economies.
- Health Food Stores:California coastal metropolitan markets concentrate procurement authority with formulation consultants who specify processing methods and fatty acid profiles.
- Specialty Shops:Ethnic grocery and gourmet retailers stock unrefined and cold-pressed variants for niche cooking and gift segments.
Supermarkets retain the largest throughput, though Online Retail is gaining share fastest as disintermediation reshapes premium segment access.
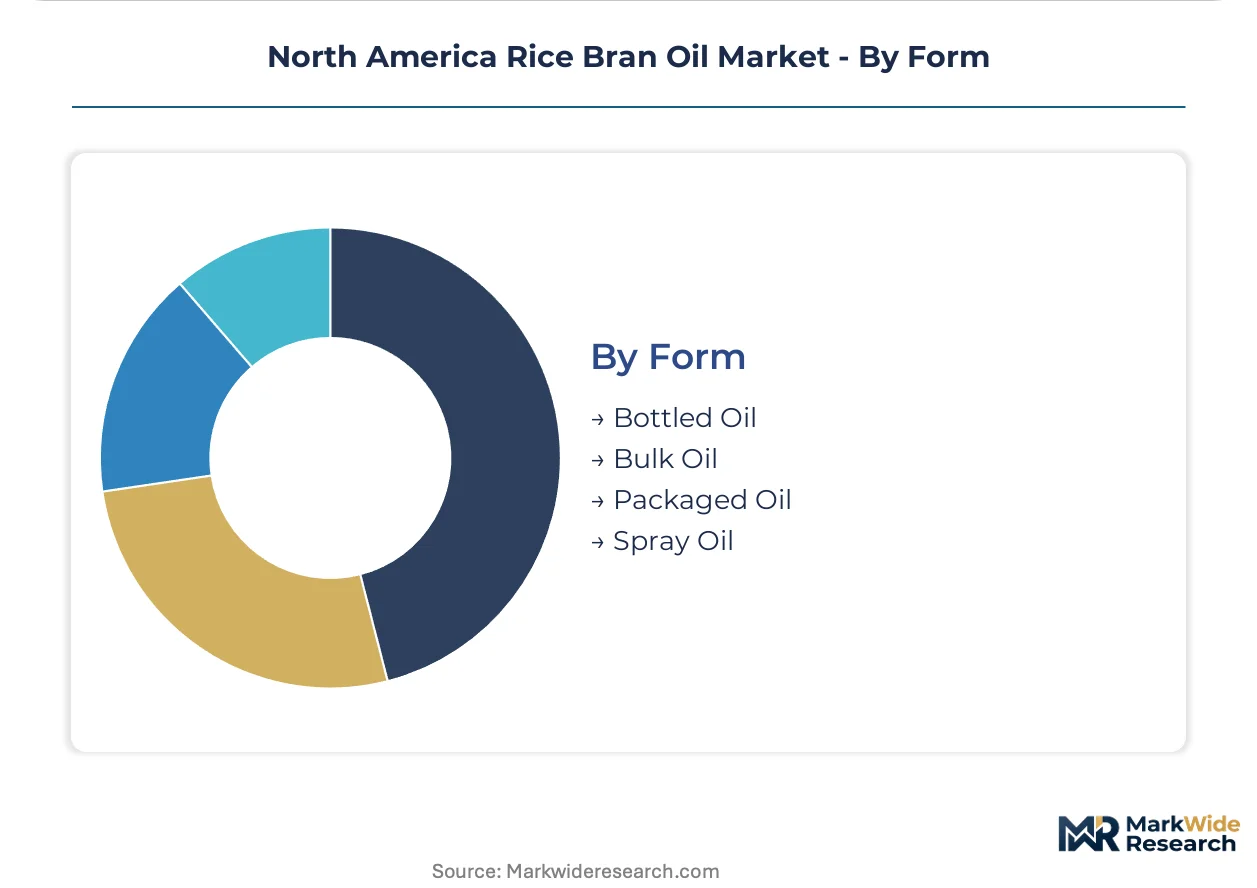
Form:
Packaging configuration aligns with customer scale, usage patterns, and storage infrastructure requirements.
- Bulk Oil:Tanker and drum delivery serves foodservice operators and industrial processors across California's Central Valley and the U.S. Gulf Coast rice milling corridor, where fryer volume justifies dedicated storage.
- Bottled Oil:Retail-ready packaging in 500ml to 5L formats targets household consumers and small commercial kitchens, with label architecture emphasizing smoke point or gamma-oryzanol content.
- Packaged Oil:Flexible pouches and bag-in-box formats reduce shipping cost for institutional buyers with on-site dispensing systems.
- Spray Oil:Aerosol and pump formulations address portion-controlled cooking applications in foodservice and home use.
Bulk Oil leads on volume moved, while Bottled Oil is climbing the fastest as retail premiumization expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated milling-refining complexes in Arkansas and Louisiana compress supply chain margins while California's specialty refiners exploit premium positioning. The U.S. Gulf Coast corridor and California's Central Valley anchor divergent competitive strategies. Health Canada and PMRA coordination shapes cross-border feedstock flows.
United States
Quick-service restaurant chains across California's Central Valley deploy fryer oil replacement programs utilizing rice bran oil's 232°C smoke point. FDA trans-fat disclosure requirements accelerate packaged food reformulation toward plant-based lipid alternatives. Arkansas and Louisiana integrated millers control captive bran sourcing from paddy to refined bottle.
Canada
Health Canada and PMRA residue limit coordination slows imported bran feedstock entry, elevating traceability documentation burdens. USDA organic certification pathways offer premium positioning for West Coast brands expanding northward. Ontario and British Columbia health food retailers contract directly with cold-pressed specialists bypassing commodity distributors.
Mexico
Bulk oil distributors establish volume relationships with regional restaurant chains in Mexico City and Guadalajara metro areas. The country's national food safety regulator enforces maximum residue limits on imported feedstocks. Northern border states concentrate industrial baking operations seeking oxidative stability in frying applications.
North America Rice Bran Oil Market Key Industry Players
Integrated agricultural processors and specialty cold-pressed refiners split the market into incompatible margin structures. Arkansas and Louisiana-based millers leverage captive paddy sourcing to lock in foodservice volume contracts. Three strategic archetypes dominate: vertically integrated agribusiness conglomerates, regional specialty oil processors, and tolling-dependent independent refiners. Competitive moves concentrate on backward integration into bran sourcing and enzymatic refining technology licensing.
Within the integrated agribusiness tier, Riceland Foods and Cargill Corporation represent scale-driven archetypes with milling-refining infrastructure spanning multiple states. California Rice Oil Company exemplifies the specialty cold-pressed positioning that commands premium shelf placement through direct retail relationships. King Rice Oil Group anchors the mid-scale independent segment dependent on tolling arrangements or imported feedstock sourcing.
| Leading Market Players |
|---|
| Riceland Foods |
| King Rice Oil Group |
| Cargill Corporation |
| Ricela Health Foods Ltd. |
| Marico Limited |
| California Rice Oil Company |
| RiceBran Technologies |
| 3F Industries Ltd. |
| Conagra Brands |
| Others |
Cost & Logistics Intelligence
Undercapacity in California cold-pressed refining is compressing premium-grade availability while Arkansas-Louisiana integrated millers exploit full utilization to enforce contract discipline across foodservice accounts. This utilization asymmetry between specialty and commodity tiers shapes how suppliers negotiate volume commitments and how buyers trade off price against processing integrity.
Pricing Analysis
Aftermarket formulation consulting and private-label specification services now capture margin that once accrued to bulk oil traders. Three-tier pricing structure across cold-pressed premium, refined standard, and crude economy levels separates California health food retail from Gulf Coast foodservice volume. Cost compression in refined grades is intensifying because King Rice Oil Group and similar independents lack captive bran sourcing. Quick-service restaurant chains show highest price sensitivity due to fryer oil replacement program scale, while West Coast cosmetic formulators accept premium positioning for gamma-oryzanol retention.
Supply Chain Analysis
Upstream rice bran availability draws from Arkansas, Louisiana, and California paddy harvest cycles, with Gulf Coast milling infrastructure controlling the majority of North American capacity. Feedstock sourcing rests on seasonal harvest timing, moisture content at extraction, and transportation economics from mill to refiner. Single-source geographic concentration creates vulnerability when Mississippi River logistics face disruption. Distribution runs through bulk tanker networks for foodservice operators and direct container delivery for West Coast specialty refiners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as clean-label procurement authority shifts from commodity traders to formulation consultants specifying processing methods, creating niche entry points for differentiated positioning.
For Market Incumbents: Harden captive bran sourcing through long-term paddy supply agreements in Arkansas and Louisiana, insulating against feedstock volatility that threatens non-integrated refiners. Invest in enzymatic degumming and membrane filtration licensing to defend premium cosmetic and pharmaceutical positioning against California cold-pressed specialists. FDA trans-fat disclosure acceleration and Health Canada residue limit coordination represent regulatory leverage points to lock out cross-border feedstock competitors. For New Entrants and Emerging Players: Pursue Canadian market expansion through USDA organic certification pathways, exploiting Health Canada and PMRA coordination delays that slow incumbent entry. Target Ontario and British Columbia health food retailers with direct contracting models that bypass commodity distributors. Pharmaceutical excipient applications offer the most penetrable white-space given oxidative stability requirements and synthetic replacement demand. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cold-pressed capacity as mechanical pressing equipment and temperature-controlled storage infrastructure demands strain mid-scale entrants. Long-term viability favors acquisition targets with established enzymatic refining technology or direct retail relationships in California coastal metropolitan markets. Monitor FDA organic certification timeline acceleration as the signal indicating when premium positioning barriers will shift.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Paddy Sourcing | Arkansas and Louisiana integrated millers lock in feedstock security against harvest cycle volatility. |
| Enzymatic Refining Technology Licensing | California specialty refiners preserve gamma-oryzanol integrity for cosmetic clean-label certification. |
| Direct-to-Foodservice Distribution Expansion | Bulk oil distributors bypass retail slotting fees to capture volume relationships with regional restaurant chains. |
| USDA Organic Certification Investment | West Coast brands exploit multi-year field history documentation to establish premium positioning in Canadian markets. |
| Pharmaceutical Excipient Grade Development | Specialty refiners target soft-gel formulation replacement for synthetic excipients leveraging oxidative stability profiles. |
Research Approach
A spread of perspectives from rice mill operations managers, quick-service restaurant procurement directors, cosmetic formulation chemists, and health food retail category buyers converged on the working assumptions driving supply and demand modeling. Primary interview intelligence combined with secondary validation from USDA organic certification records, FDA GRAS determination filings, Health Canada residue limit documentation, and U.S. Gulf Coast customs trade data. Bottom-up volume triangulation across processing tiers reconciled against top-down market sizing from integrated agribusiness disclosures.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning processing method intensity, end-use application requirements, and distribution channel economics. CAGRs were derived from modeled volume trajectories by tier, incorporating inputs from fryer oil replacement program adoption curves and cosmetic mineral oil displacement rates. Enzymatic refining capacity expansion timelines and organic certification pathway completion rates provided industry-specific forecast calibration.
Sensitivities concentrate around FDA trans-fat disclosure enforcement intensity, Mississippi River logistics disruption frequency, and Health Canada-PMRA coordination timeline shifts. Cross-checking against USDA National Agricultural Statistics Service harvest data and U.S. Census Bureau refined oil trade flows is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Confectionery Ingredients Market
Ingredients
Ximenia Oil Market
Ingredients
Global Antimicrobial (Enzymatic) Protein Hydrolysates Market
Ingredients
Borage Oil Market
Ingredients
Lupin Flour Market
Ingredients
GCC Bakery Ingredients Market
Ingredients
Canada Whey Protein Ingredients Market
Ingredients
Europe Insoluble Dietary Fibers Market
Ingredients
Chickpea Protein Market
Ingredients
Dry Mixes Market
Ingredients
Global Pea Protein Ingredients Market
Ingredients
Omega Ingredients Market
Ingredients
Self-Rising Flour Market
Ingredients
Global Distillers Corn Oil Market
Ingredients
Rose Extract Market
Ingredients
South America Fermented Ingredients Market