
 Wheel and Tire Service Equipment Market | 2026-2036
Wheel and Tire Service Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Wheel and Tire Service Equipment Market Analytics
Aftermarket service revenue is tilting from basic tire replacement toward precision wheel alignment and diagnostic services. Hunter Engineering Company dominates the alignment equipment segment through its geographic footprint across North American automotive workshops. Bosch Automotive Service Solutions leverages its integrated diagnostic platform to anchor recurring software subscription revenue alongside hardware sales. Snap-on Incorporated controls premium distribution channels through its mobile franchise network, sustaining higher-margin service equipment placement.
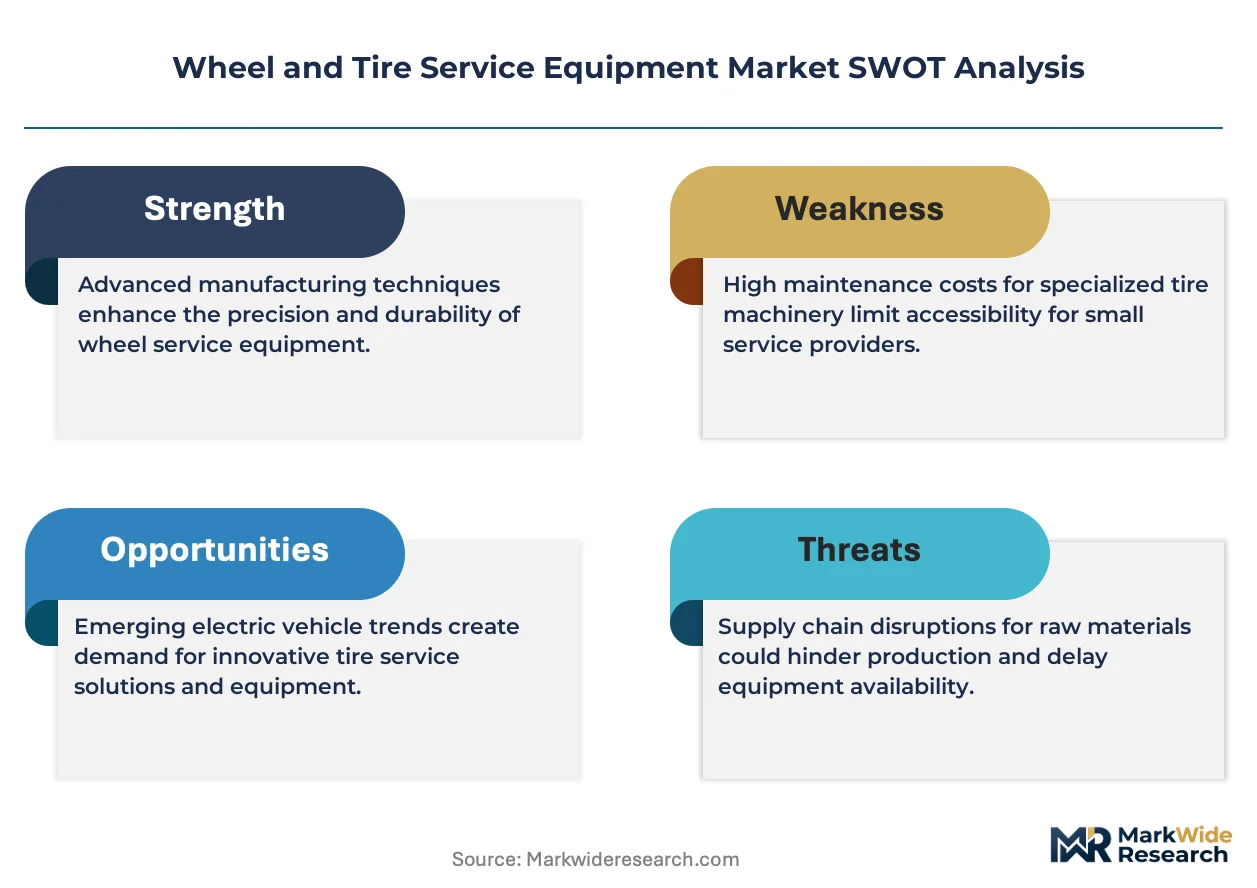
Wheel and tire service equipment encompasses machinery designed to mount, demount, balance, and align vehicle wheels with precision tolerances typically within 0.1 ounces for balance and 0.1 degrees for camber adjustment, serving collision repair centers and high-volume tire retail operations. Tire changers and wheel balancers represent mature equipment categories where replacement demand tracks vehicle age distribution and shop throughput expansion. Alignment machines and diagnostic tools capture faster expansion as advanced driver assistance system recalibration requirements extend service complexity. Fully automatic technology variants command premium positioning while manual equipment persists in emerging market entry-level installations.
EPA tailpipe standards and NHTSA fuel economy regulations tighten wheel maintenance protocols for commercial fleets, directly lifting alignment service frequency and equipment utilization rates. OSHA workplace safety requirements govern tire inflation cage specifications and technician training standards, shaping equipment certification and shop compliance investment. ISO quality management standards influence procurement criteria for fleet operators consolidating supplier relationships. Stakeholders must monitor ADAS proliferation and electric vehicle weight distribution shifts as these force recalibration of service equipment specifications and technician competency requirements.
Market Dynamics
Commercial fleet operators are consolidating service contracts around integrated tire management platforms that bundle predictive analytics with alignment scheduling, compressing procurement cycles from annual to quarterly review periods.
Growth Catalysts
- EPA Phase 3 GHG Standards:Heavy-duty truck manufacturers face tightened emissions thresholds that elevate tire rolling resistance as a compliance variable, forcing fleet alignment frequency increases.
- ADAS sensor recalibration mandates:Collision repair centers now require alignment systems with integrated camera and radar calibration modules to service lane-keeping and automatic emergency braking systems.
- Electric vehicle weight redistribution:Battery pack placement alters axle load profiles, creating specialized wheel balancing protocols for EV-specific service bays.
Market Restraints
- Steel tariff volatility:Wheel balancer spindle and tire changer component costs fluctuate with Section 232 duty adjustments, squeezing mid-tier equipment margins.
- Semiconductor allocation constraints:Alignment machine sensor arrays face extended lead times from automotive-grade chip foundry capacity concentration in Taiwan.
- Manual equipment substitution persistence:Emerging market independent garages retain lever-operated tire changers due to technician training cost barriers and low labor rates.
Strategic Opportunities
- India commercial vehicle fleet expansion:The country's PLI scheme for automotive manufacturing is accelerating truck production, creating first-mover positioning for automated service equipment distributors.
- Subscription-based diagnostic software:Cloud-connected alignment platforms enable recurring revenue streams through over-the-air calibration database updates and remote technician support.
- OSHA silica dust rule expansion:Tire shredding and retreading facilities face new ventilation and containment requirements, driving demand for enclosed inflation systems and dust extraction attachments.
Industry Challenges
- ADAS calibration technician certification gaps:I-CAR and OEM-specific training programs lag behind sensor proliferation, creating liability exposure for shops performing recalibration without documented competency.
- Legacy equipment integration friction:Older wheel balancers lack CAN bus connectivity for modern vehicle communication protocols, forcing partial fleet replacement rather than modular upgrade paths.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wheel and Tire Service Equipment Market |
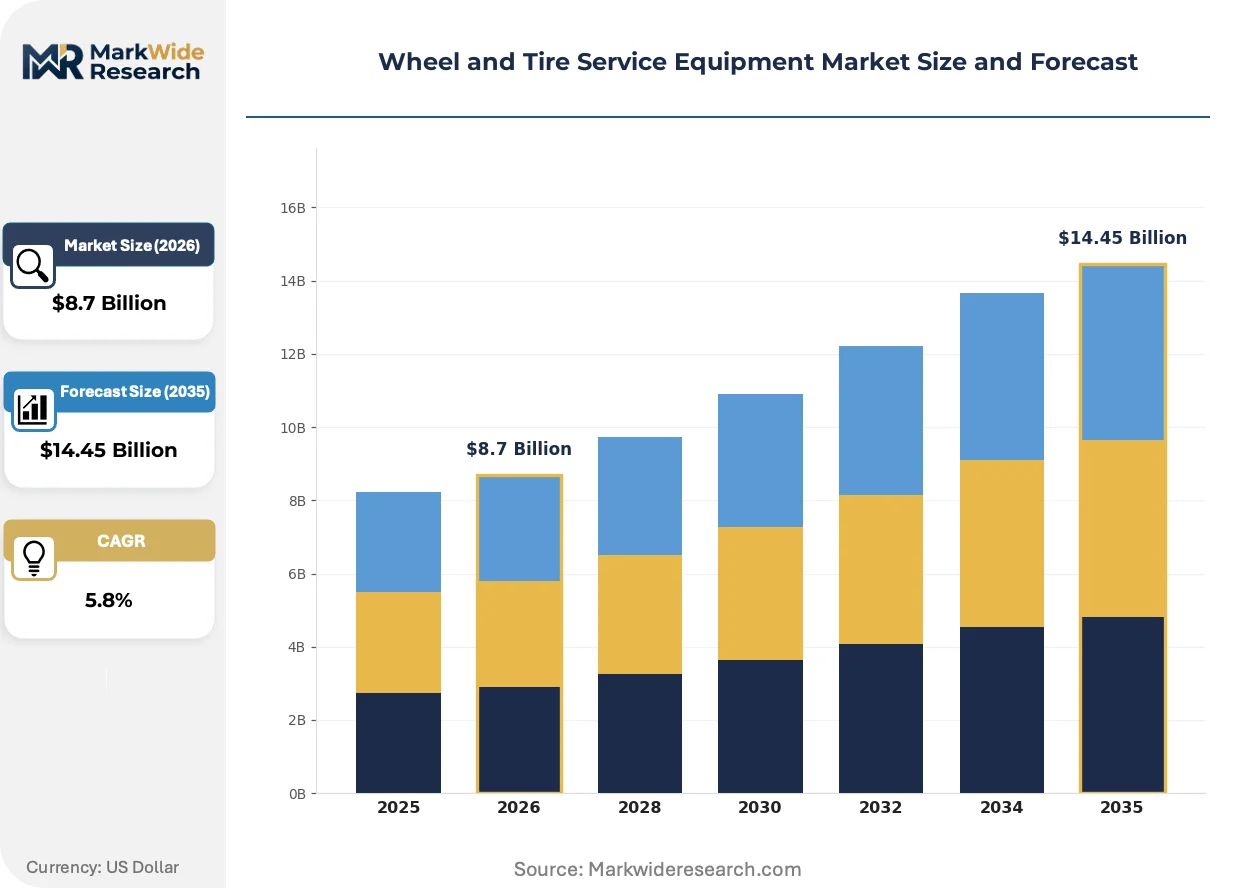
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tire Changers, Wheel Balancers, Alignment Machines, Diagnostic Tools End User: Automotive Workshops, Service Stations, Tire Retailers, Fleet Operators Technology: Manual, Semi-Automatic, Fully Automatic, Electric Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Vehicles, Specialty Equipment |
| Companies Covered | Hennessy Industries, CEMB, Hunter Engineering Company, Giuliano Industrial, Ravaglioli, Snap-on Incorporated, Corghi, Beissbarth, Bosch Automotive Service Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wheel and Tire Service Equipment Market Evolving Landscape
Service equipment architecture is migrating toward software-defined functionality where hardware platforms host expandable diagnostic modules, decoupling capital investment from feature evolution.
Digital twin technology is virtualizing wheel alignment workflows by creating three-dimensional tire and suspension models from optical scanning arrays. High-volume tire retailers are deploying these systems to reduce physical measurement cycles and compress bay turnaround times. The technology is virtualizing traditional mechanical gauge sets and eliminating technician-dependent measurement variance.
NHTSA's updated Federal Motor Vehicle Safety Standards for tire pressure monitoring systems now mandate sensor registration protocols during wheel service procedures. Alignment equipment manufacturers must integrate TPMS relearn functionality to maintain regulatory compliance certification. Independent repair shops in the United States are prioritizing dual-purpose machines that consolidate alignment and sensor registration to avoid redundant capital expenditure.
Fleet procurement departments are unbundling equipment purchases from service contracts, negotiating direct relationships with alignment system vendors while retaining third-party maintenance providers. This disintermediation compresses distributor margins and shifts technical training responsibility to end-users. Large commercial fleet operators in Germany and the United States are piloting this model to standardize equipment specifications across multi-state service networks.
Wheel and Tire Service Equipment Market Segmentation
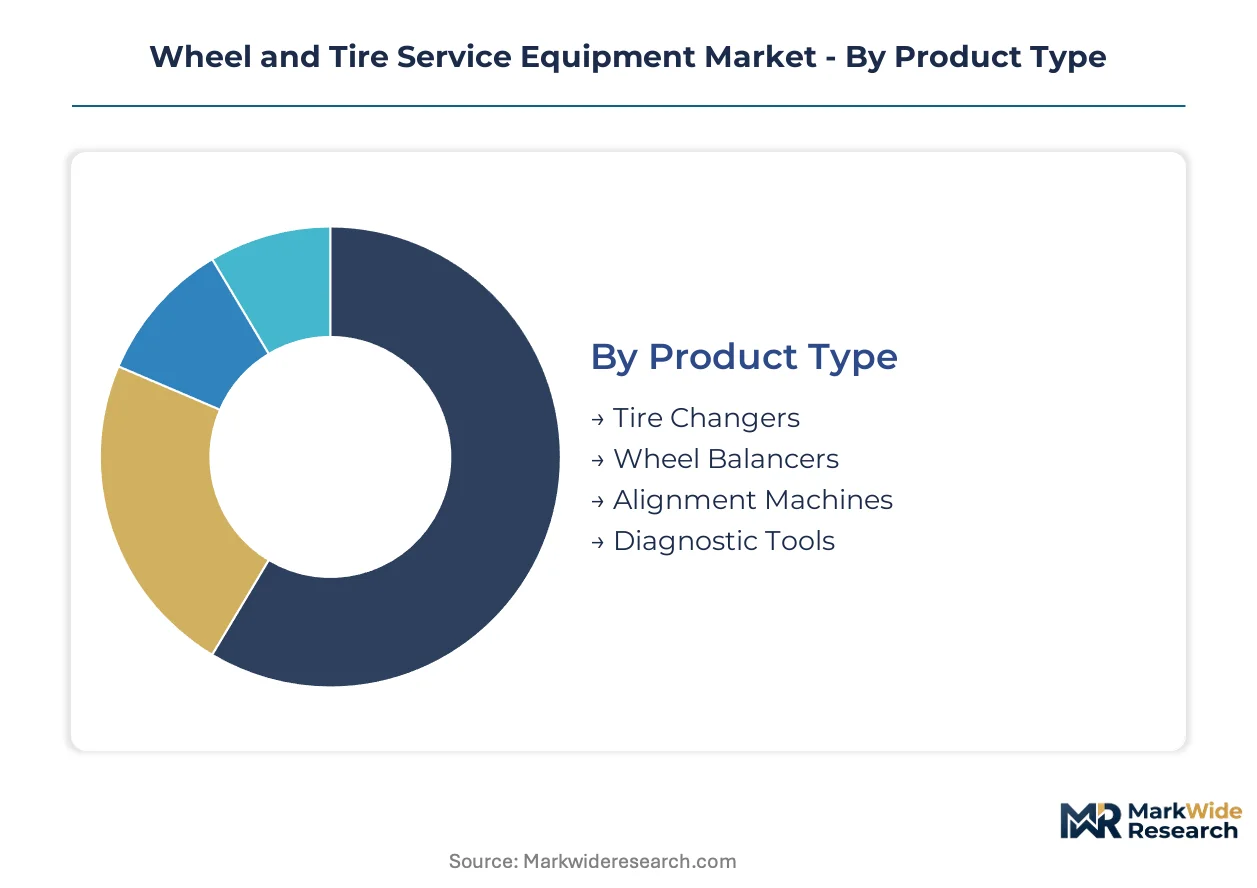
Equipment replacement cycles vary dramatically across wheel and tire service categories, with high-throughput tire retailers demanding faster refresh rates than collision repair centers. Understanding these temporal patterns reveals where procurement budgets concentrate and how technology transitions propagate through different customer tiers.
Product Type:
Tire changers and wheel balancers turn over fastest at high-volume retail operations, while alignment machines and diagnostic platforms command longer depreciation schedules tied to software update cycles.
- Tire Changers:Lever-operated and fully automatic variants demount and mount tires across rim diameters from 10 to 30 inches. Fleet service networks in the United States drive replacement demand as throughput expansion outpaces equipment durability.
- Wheel Balancers:Optical laser and force-measurement systems detect imbalance within 0.1-ounce tolerances. Commercial vehicle specialists prioritize these units as EPA Phase 3 standards elevate rolling resistance sensitivity.
- Alignment Machines:Camera-based measurement arrays calibrate camber, caster, and toe angles. ADAS recalibration mandates are extending service complexity for collision repair centers.
- Diagnostic Tools:TPMS relearn and sensor registration devices integrate with alignment platforms. Independent repair shops seek dual-purpose configurations to consolidate capital expenditure.
Tire changers anchor the volume base while alignment machines gain share at the steepest rate.
End User:
Procurement authority concentrates differently across customer types, with fleet operators consolidating vendor relationships while independent garages retain fragmented purchasing patterns.
- Automotive Workshops:Full-service repair facilities mount, balance, and align wheels alongside mechanical repairs. These operations in Germany and the United States are piloting direct equipment procurement from alignment system vendors.
- Service Stations:Quick-lube and express maintenance outlets perform basic tire services with limited bay space. High throughput demands drive preference for automatic tire changers with touchless mounting arms.
- Tire Retailers:High-volume replacement specialists operate dedicated wheel service bays. Digital twin technology is compressing measurement cycles at these facilities to maximize bay utilization.
- Fleet Operators:Commercial vehicle managers bundle predictive analytics with alignment scheduling. Quarterly procurement reviews are replacing annual equipment replacement cycles.
Tire retailers command the largest installed base while fleet operators are expanding most quickly.
Technology:
Capital intensity stratifies sharply across automation levels, with manual equipment persisting where labor rates suppress payback calculations for automated alternatives.
- Manual:Lever-operated tire changers and bubble-level balancers require technician physical effort. Independent garages in emerging markets retain these units due to training cost barriers.
- Semi-Automatic:Power-assisted mounting and demounting reduces technician strain while retaining manual positioning. Mid-tier automotive workshops balance capital constraints with throughput requirements.
- Fully Automatic:Touchless mounting arms and self-calibrating balancers minimize operator intervention. Premium tire retailers deploy these systems to reduce technician-dependent variance.
- Electric:Battery-powered and corded electric variants serve mobile service applications and fixed installations. EV-specific service bays are adopting specialized protocols for battery pack weight distribution.
Semi-automatic systems dominate unit shipments while fully automatic configurations climb the fastest.
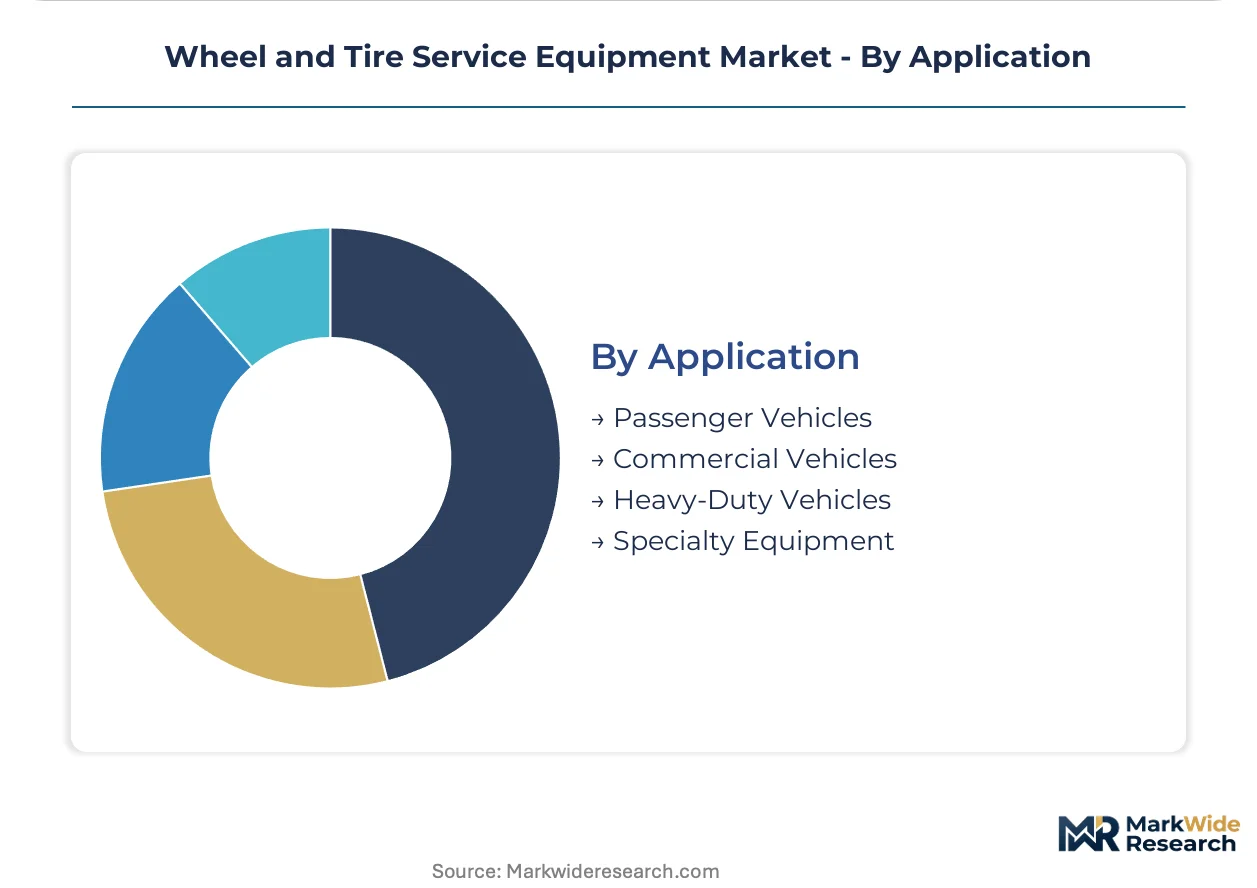
Application:
Vehicle weight classes dictate equipment specifications, with heavy-duty applications demanding reinforced chassis and expanded capacity ranges.
- Passenger Vehicles:Standard passenger car and light truck service represents the foundational volume segment. Alignment equipment here integrates TPMS relearn functionality to satisfy NHTSA registration protocols.
- Commercial Vehicles:Medium-duty trucks and delivery fleets require extended capacity tire changers and heavy-duty balancers. EPA emissions standards are accelerating alignment frequency for this category.
- Heavy-Duty Vehicles:Class 8 trucks and construction equipment demand specialized mounting systems for 22.5-inch and 24.5-inch rims. OSHA tire inflation cage specifications govern equipment certification.
- Specialty Equipment:Agricultural tractors, mining vehicles, and off-road machinery require custom adapters and extended reach configurations. Low volume and high customization sustain premium pricing.
Passenger vehicle applications anchor the volume base while commercial vehicle equipment gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across procurement tiers: fleet operators negotiate volume discounts aggressively while independent garages absorb higher per-unit costs. Mature markets favor precision equipment with software integration; emerging markets prioritize manual durability over automation.
United States
Commercial fleet networks drive replacement cycles for high-throughput tire changers and alignment systems. NHTSA mandates TPMS sensor registration protocols during wheel service procedures. Dallas-Fort Worth and Chicago host dense concentrations of fleet maintenance depots consolidating vendor relationships.
Germany
Automotive workshops pilot direct procurement from alignment system vendors, bypassing traditional distribution channels. KBA enforces strict equipment certification standards for commercial vehicle service bays. The Stuttgart industrial corridor anchors specialized manufacturing of precision wheel balancers for export markets.
China
Domestic truck production expansion creates first-mover positioning for automated tire service equipment distributors. MIIT coordinates GB standards for commercial vehicle maintenance equipment interoperability. Yangtze River Delta manufacturing clusters produce cost-competitive tire changers for Southeast Asian export markets.
India
Commercial vehicle fleet expansion accelerates demand for heavy-duty wheel balancers and alignment machines. The PLI scheme for automotive manufacturing subsidizes domestic production of service equipment components. Tamil Nadu's Sriperumbudur belt concentrates tire retreading facilities requiring OSHA-compliant inflation systems.
Japan
Premium automotive workshops prioritize fully automatic tire changers with touchless mounting technology. METI promotes JIS standards for wheel service equipment precision tolerances. Nagoya's Chubu region maintains specialized suppliers for optical laser balancing systems serving domestic OEM service networks.
Wheel and Tire Service Equipment Market Competitive Landscape
Capability concentration sits with integrated diagnostic platform providers; scale advantage sits with established workshop equipment fabricators. The vendor base stratifies across three tiers: premium precision equipment specialists, mid-market diversified industrial groups, and emerging-market cost-optimized manufacturers. Dominant competitive moves include geographic expansion through distribution partnerships and technology licensing for ADAS calibration module integration.
Among North American equipment specialists, Hunter Engineering Company and Snap-on Incorporated occupy positions anchoring premium-tier alignment and diagnostic segments. European industrial groups CEMB and Ravaglioli exemplify mid-market diversification across tire changer and wheel balancer categories. Bosch Automotive Service Solutions represents the integrated platform archetype, bundling hardware with recurring software subscription revenue streams.
| Leading Market Players |
|---|
| Hennessy Industries |
| CEMB |
| Hunter Engineering Company |
| Giuliano Industrial |
| Ravaglioli |
| Snap-on Incorporated |
| Corghi |
| Beissbarth |
| Bosch Automotive Service Solutions |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta freight corridor channels steel and electronic components from Chinese manufacturing clusters to assembly plants, with container rate volatility directly compressing mid-tier equipment margins while amplifying price differentiation between premium automated systems and manual alternatives.
Pricing Analysis
Software subscription and calibration database renewals now drive lifetime value beyond initial hardware placement. Three-tier pricing structure across premium, standard, and economy levels separates fully automatic alignment platforms with integrated ADAS modules from semi-automatic tire changers and lever-operated entry units. Cost compression in the mid-tier is intensifying because steel tariff fluctuations squeeze component sourcing. Fleet operators exhibit lowest price sensitivity due to bundled predictive analytics contracts, while independent garages in emerging markets absorb highest per-unit costs.
Supply Chain Analysis
Steel feedstock and semiconductor sensor arrays draw from China, Taiwan, and Germany as primary sourcing nodes. Wheel balancer spindles rely on alloy steel grades, alignment machine camera modules hinge on automotive-grade image sensors, and tire changer hydraulic systems rest on precision-machined castings. Single-source vulnerability concentrates in Taiwan semiconductor foundry capacity for optical measurement arrays. Distribution runs through authorized dealer networks and direct procurement channels serving fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from cloud-connected calibration platforms and predictive maintenance software is expanding faster than hardware unit sales, repositioning capital equipment vendors as recurring-revenue enterprises.
For Market Incumbents: Entrench platform dominance by deepening backward integration into sensor module production and securing exclusive TPMS database licensing from NHTSA-compliant registration systems. Defensive consolidation should prioritize acquiring regional calibration software specialists before emerging diagnostic platforms achieve critical mass.
For New Entrants and Emerging Players: India's commercial vehicle fleet expansion offers white-space positioning for automated tire service equipment distributors lacking established dealer networks. Target EV-specific service bays with battery-pack-aware balancing protocols as the most penetrable application segment. Partner with domestic component manufacturers under India's PLI scheme to neutralize import duty exposure.
For Investors and Strategic Acquirers: Cloud-native diagnostic platform developers with established OEM certification relationships represent the highest-conviction acquisition archetype. Long-term viability rests on software-defined functionality decoupling hardware refresh cycles from feature evolution. Monitor ADAS sensor proliferation rates as the inflection indicator for alignment equipment replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| ADAS Calibration Module Integration | Alignment platforms with embedded camera and radar recalibration capture collision repair center procurement. |
| Subscription-Based Diagnostic Software | Recurring revenue from over-the-air calibration databases stabilizes cash flow beyond hardware sales cycles. |
| Direct Fleet Procurement Channels | Bypassing traditional distributors compresses margins but secures multi-state equipment standardization contracts. |
| EV-Specific Service Bay Certification | Battery pack weight distribution protocols differentiate service offerings as electric vehicle penetration accelerates. |
| Regional Manufacturing Footprint Expansion | Local assembly in India and Southeast Asia neutralizes Section 232 steel tariff exposure for export markets. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet maintenance directors, automotive workshop owners, tire retailer operations managers, and equipment distributor principals. Secondary validation drew from NHTSA regulatory filings, EPA emissions standard documentation, OSHA workplace safety directives, and commercial vehicle production databases. Bottom-up equipment shipment estimates triangulated against top-down fleet service expenditure patterns.
Calibration against historical replacement cycles and regulatory mandate timelines anchored projections across the analysis window. Segmentation dimensions modeled include equipment automation level, end-user procurement authority, vehicle weight class application, and regional regulatory compliance tier. CAGRs were derived from weighted average of equipment category growth rates and service revenue expansion trajectories. Forecast inputs incorporated ADAS penetration curves and commercial fleet preventive maintenance program adoption.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by semiconductor-limited equipment vendors would shift outcomes beyond modeled ranges. Cross-checking against commercial vehicle mileage accumulation data and collision repair center throughput statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Zeropressure Tires Market
Tires and Wheels
Global High Performance Tires Market
Tires and Wheels
Self-Healing Tire Market
Tires and Wheels
North America OTR Tire Market
Tires and Wheels
Automotive Wheel Coating Market
Tires and Wheels
Saudi Arabia Tire Market
Tires and Wheels
Tire Carousel Market
Tires and Wheels
Global Pneumatic Tires Market
Tires and Wheels
Industrial Tire Market
Tires and Wheels
Green Tires Market
Tires and Wheels
Europe Tire Market
Tires and Wheels
Bias Tire Market
Tires and Wheels
Global Tires Market
Tires and Wheels
Automotive Wheel Rims Market
Tires and Wheels
Europe 2-Wheeler Replacement Tire Market
Tires and Wheels
Asia-Pacific Alloy Wheels Market