
 Global Aircraft Tire Market | 2026-2036
Global Aircraft Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aircraft Tire Market Analysis
Operating lease proliferation for narrow-body fleets is fragmenting capital deployment across the aircraft tire supply chain. Michelin leverages its vertically integrated rubber compounding operations to sustain premium positioning in OEM channels. Bridgestone Corporation anchors its competitiveness through geographic dominance across Asia-Pacific MRO networks. Goodyear Tire & Rubber Company differentiates via specialized military aviation tire portfolios that command higher technical barriers.
Aircraft tires are engineered elastomer structures reinforced with nylon, aramid, or steel cord plies, designed to withstand dynamic loads exceeding multiple aircraft weights during takeoff, landing, and taxi operations while dissipating extreme thermal stresses. Radial constructions now lead commercial aviation procurement due to their extended cycle life and reduced heat buildup under high-speed loads, while bias-ply designs retain entrenched positions in regional turboprop and legacy military platforms where retread economics favor simpler crown architectures. The aftermarket channel captures substantial margin pools as airlines extend on-wing intervals and third-party MRO providers consolidate purchasing volumes.
FAA Technical Standard Orders and EASA Certification Specifications govern tire approval, retread integrity, and burst-pressure thresholds, compelling manufacturers to maintain dual compliance architectures for transatlantic fleet compatibility. China's CAAC aligns with GB standards and NMPA oversight for domestic COMAC programs, adding a third regulatory pillar that suppliers must navigate for market access. Stakeholders must monitor how sustainable aviation fuel adoption and heavier electric taxi systems alter load-rating requirements before next-generation tire specifications crystallize.
Market Dynamics
Radial tire architectures are displacing bias-ply dominance in commercial aviation procurement as airlines prioritize extended cycle life and reduced thermal degradation during high-speed operations. This structural migration compresses retread economics for legacy crown designs while elevating performance thresholds for new rubber compound formulations.
Growth Catalysts
- FAA Technical Standard Orders:Tightened burst-pressure thresholds and retread integrity mandates compel fleet operators to accelerate replacement schedules, expanding aftermarket volume pools.
- Operating lease proliferation:Narrow-body fleet financing fragmentation spreads capital deployment across multiple lessors, each maintaining independent tire procurement protocols that multiply addressable customer touchpoints.
- Aramid-reinforced carcass plies:Advanced fiber integration enables higher load ratings without weight penalties, supporting electric taxi system adoption and heavier next-generation landing gear configurations.
Market Restraints
- Natural rubber price volatility:Southeast Asian supply concentration exposes compounders to climate-driven harvest disruptions and futures market speculation that compress margin predictability.
- Dual compliance architectures:Transatlantic fleet operators must simultaneously satisfy FAA and EASA certification specifications, doubling qualification timelines and testing expenditures for new product introductions.
- Retread substitution ceiling:Extended on-wing intervals for radial constructions reduce retread cycle frequency, limiting revenue capture for third-party MRO providers dependent on volume-based refurbishment economics.
Strategic Opportunities
- India's MRO infrastructure buildout:Greenfield maintenance hubs near Delhi and Mumbai create captive demand for localized tire distribution and rapid-turn retreading services.
- Sustainable aviation fuel compatibility:Altered aircraft weight distributions and taxi thermal profiles require recalibrated load-rating specifications that first-mover compounders can shape before standards crystallize.
- Direct-to-lessor distribution channels:Operating lease aggregators consolidate purchasing power across fragmented airline portfolios, enabling volume-tier pricing structures that bypass traditional airline procurement hierarchies.
Industry Challenges
- Elastomer formulation expertise scarcity:Specialized polymer science and dynamic load simulation capabilities concentrate within a narrow talent pool, constraining R&D velocity for mid-tier suppliers.
- CAAC-GB standard harmonization:China's distinct certification pathway for COMAC programs demands parallel testing protocols, extending time-to-market for suppliers seeking tripartite FAA-EASA-CAAC approval.
- Legacy bias-ply platform support:Regional turboprop and military operators require continued supply of obsolescent architectures, forcing manufacturers to maintain dual production lines with diverging tooling and quality systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aircraft Tire Market |
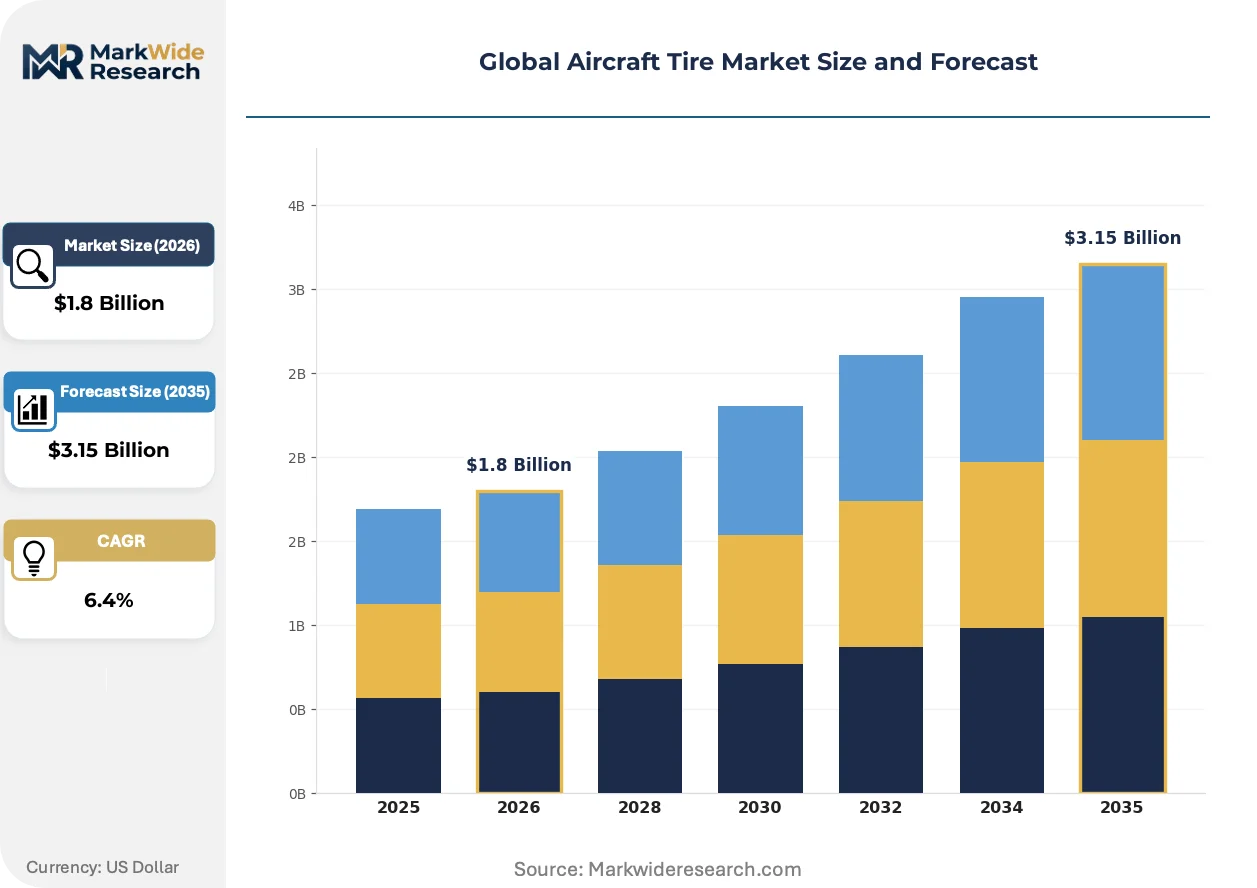
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial, Bias, Cross-Ply, Specialty End User: Commercial Aviation, Military Aviation, Cargo, Private Jets Size: Small, Medium, Large, Oversized Distribution Channel: Direct Sales, Distributors, Online Retail, Aftermarket |
| Companies Covered | Dunlop Aircraft Tyres Ltd., Desser Holding Company LLC, Michelin, Petlas Tire Corporation, Qingdao Sentury Tire Co., Ltd., Goodyear Tire & Rubber Company, Specialty Tires of America, Wilkerson Company Inc., Bridgestone Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aircraft Tire Market Emerging Trajectories
Active materials science and regulatory stringency are converging to redefine tire specification boundaries. Manufacturers now face simultaneous pressure to extend service intervals, reduce rolling resistance, and accommodate electrified ground propulsion systems that alter thermal and mechanical load profiles.
Silica-reinforced tread compounds are migrating from passenger vehicle adaptation into aviation-grade formulations, where they reduce hysteresis heat generation during repeated high-speed touchdown cycles. Commercial carriers with high-frequency short-haul operations are adopting these compounds fastest. The technology is migrating from premium long-haul specifications into narrow-body fleet standards, compressing the performance gap between tier-one and tier-two supplier offerings.
REACH substance restrictions and the EU Green Deal's carbon-border adjustment mechanisms are forcing reformulation of aromatic oil plasticizers and carbon black feedstocks. Compounders must now validate alternative curatives and fillers through accelerated aging protocols. European-registered lessors and flag carriers face the steepest compliance cost escalation, driving preference for suppliers with pre-certified sustainable material streams.
Airline engineering departments are consolidating tire procurement under fleet-wide lifecycle cost contracts that bundle initial fitment, scheduled replacement, and scrap credit recovery into single vendor relationships. This unbundles traditional MRO channel intermediaries and transfers inventory risk to manufacturers. The model is most visible among Gulf-based mega-carriers with centralized technical operations and uniform fleet configurations.
Global Aircraft Tire Market Segmentation
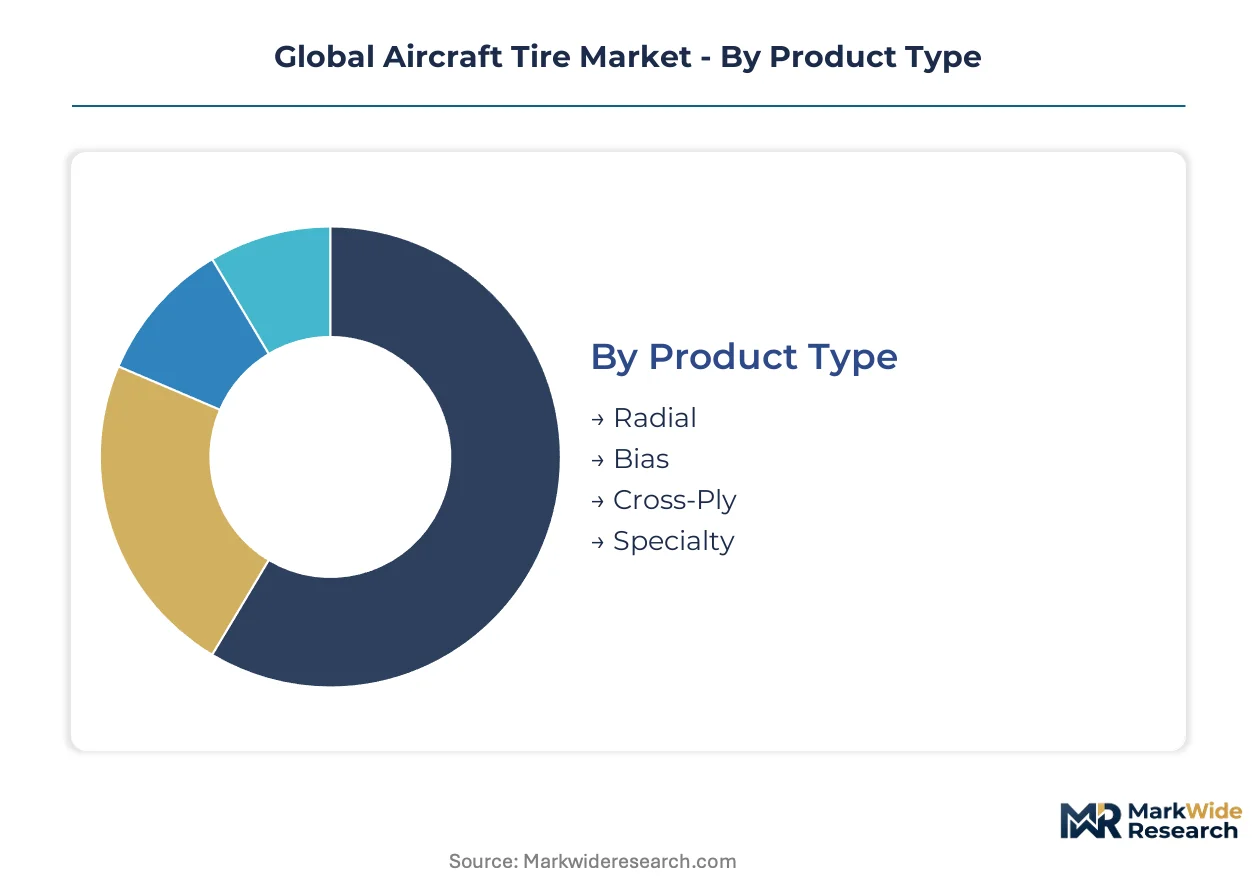
Aircraft tire procurement stratifies across construction methodology, operational duty cycles, and fleet scale requirements. Understanding these segment boundaries clarifies how compounders allocate R&D resources and how lessors structure lifecycle cost contracts.
Product Type:
Mature radial architectures now dominate commercial aviation procurement while bias-ply and cross-ply constructions retain entrenched positions in specialized applications.
- Radial:Nylon or aramid cord plies arranged perpendicular to the direction of travel enable extended cycle life and superior heat dissipation during high-speed operations. Airlines operating narrow-body fleets on short-haul routes in the United States and China concentrate procurement here as they prioritize reduced landing gear maintenance intervals.
- Bias:Diagonal cord ply orientation creates a simpler crown architecture suited to lower-speed operations and cost-sensitive retread economics. Regional turboprop operators in Germany and legacy military platforms sustain demand despite radial displacement in mainstream commercial channels.
- Cross-Ply:Multi-angle ply layering delivers enhanced sidewall stability for rough-field landing gear configurations.
- Specialty:Custom-engineered compounds address extreme thermal profiles from heavy electric taxi systems or unpaved runway operations.
Radial retains volume leadership; Specialty holds the steepest expansion curve.
End User:
Customer archetypes span from high-frequency scheduled carriers to intermittent-use private operators with diverging specification priorities.
- Commercial Aviation:Scheduled airlines with centralized technical operations drive standardized procurement at fleet scale. Carriers in the United States and China negotiate lifecycle cost contracts bundling initial fitment, replacement scheduling, and scrap credit recovery.
- Military Aviation:Specialized load ratings and burst-pressure thresholds for combat maneuvering create technical barriers that sustain premium positioning. Procurement flows through defense ministries with multi-year framework agreements.
- Cargo:All-cargo operators prioritize durability under maximum ramp weights and extended taxi distances.
- Private Jets:Fragmented owner-operator bases and maintenance-on-condition protocols favor distributor-channel purchasing over direct OEM relationships.
Commercial Aviation commands the largest revenue pool; Military Aviation maintains the highest specification premiums.
Size:
Dimensional scaling correlates directly with aircraft maximum takeoff weight and landing gear configuration complexity.
- Large:Wide-body main landing gear tires must withstand dynamic loads exceeding multiple aircraft weights during rejected takeoff scenarios. Demand concentrates at major assembly lines and MRO hubs in the United States, Germany, and China where long-haul fleets undergo heavy maintenance checks.
- Medium:Narrow-body specifications balance load capacity against weight minimization for fuel efficiency optimization.
- Small:Regional aircraft and business jet nose gear applications require precision-engineered profiles for steering responsiveness.
- Oversized:Custom-engineered solutions for freighter conversions and specialty transport aircraft operate at the boundary of standard certification protocols.
Large sizes generate the highest unit margins; Medium sizes drive aggregate volume through fleet ubiquity.
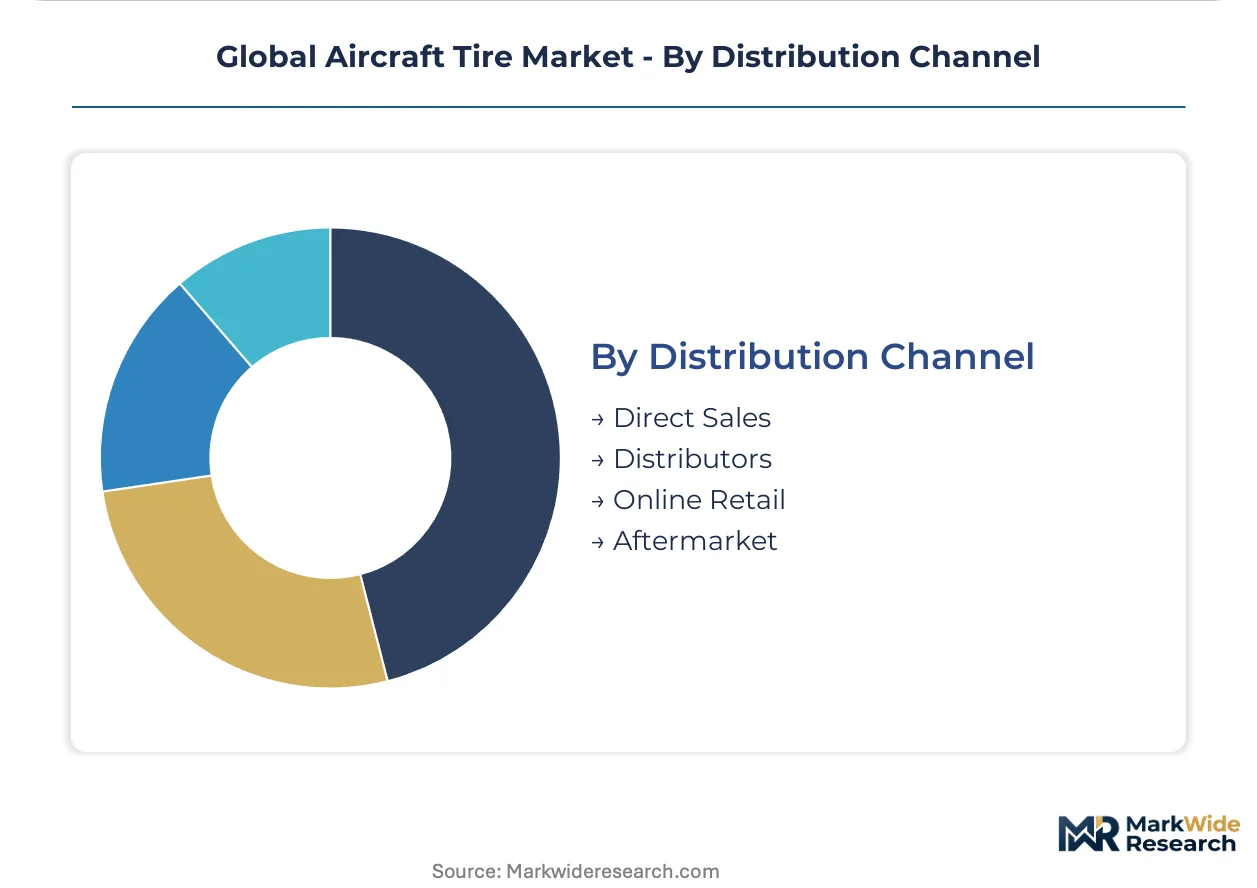
Distribution Channel:
Channel configuration determines inventory risk allocation and margin capture between manufacturers and intermediaries.
- Aftermarket:Third-party MRO providers consolidate purchasing volumes for retread services and replacement scheduling, capturing substantial margin pools as airlines extend on-wing intervals. Independent maintenance hubs in India and Germany source through this channel to bypass OEM-direct minimum order constraints.
- Direct Sales:Major lessors and flag carriers with uniform fleet configurations negotiate manufacturer-direct relationships that transfer inventory risk upstream.
- Distributors:Regional stocking locations serve fragmented operator bases with rapid-turn availability requirements.
- Online Retail:Digital procurement platforms emerge for standardized small-size specifications and emergency AOG replacement scenarios.
Aftermarket channels capture the widest customer touchpoint coverage; Direct Sales concentrate the highest contract values.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Major lessors and flag carriers with centralized technical operations concentrate procurement decisions in the United States, China, and Germany, where MRO infrastructure and OEM assembly lines cluster most densely.
United States
Domestic narrow-body fleets operating high-frequency short-haul routes drive radial tire replacement volumes. FAA Technical Standard Orders govern burst-pressure thresholds and retread integrity mandates, accelerating replacement schedules across commercial operators. Atlanta and Dallas-Fort Worth host major MRO hubs where third-party providers consolidate purchasing volumes for rapid-turn services.
China
COMAC program expansion and domestic airline fleet growth generate sustained OEM and aftermarket demand. CAAC alignment with GB standards and NMPA oversight creates a distinct certification pathway requiring parallel testing protocols for suppliers. Shanghai and Tianjin cluster final assembly lines and heavy maintenance facilities that anchor regional distribution networks.
Germany
Lufthansa Technik and consolidated flag carrier operations drive lifecycle cost contracting for wide-body main landing gear specifications. EASA Certification Specifications and REACH substance restrictions compel reformulation of aromatic oil plasticizers and carbon black feedstocks. Hamburg and Frankfurt concentrate MRO infrastructure where retread economics favor radial architectures with extended on-wing intervals.
India
Greenfield maintenance hubs near Delhi and Mumbai create captive demand for localized tire distribution and rapid-turn retreading services. BIS standards and PLI scheme incentives support domestic manufacturing capacity buildout for aviation rubber compounds. The Delhi-Mumbai industrial corridor attracts regional stocking locations serving fragmented operator bases with rapid AOG replacement availability.
Japan
Specialized military aviation procurement and legacy regional turboprop operations sustain demand for bias-ply architectures with simpler crown designs. METI industrial policy and JIS standards govern elastomer formulation requirements for defense ministry framework agreements. Nagoya and Osaka host precision manufacturing clusters where aramid-reinforced carcass ply expertise concentrates within a narrow talent pool.
Global Aircraft Tire Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a consolidated tier-one segment and fragmented mid-tier base. Michelin, Bridgestone, and Goodyear anchor the premium OEM channel through vertically integrated rubber compounding and geographic dominance across MRO networks. Three archetypes define competitive positioning: vertically integrated compounders with captive raw material supply, regional specialists serving narrow retread niches, and diversified tire manufacturers leveraging passenger vehicle technology crossovers. Dominant competitive moves include backward integration into aramid fiber sourcing and strategic partnerships with lessor aggregators to secure fleet-wide lifecycle contracts.
Within the vertically integrated tier, Michelin and Bridgestone Corporation exemplify channel-controlling archetypes that sustain premium positioning through rubber compounding operations and Asia-Pacific MRO network coverage. Goodyear Tire & Rubber Company occupies a specialization position anchored in military aviation portfolios that command higher technical barriers. Among mid-tier fabricators, Dunlop Aircraft Tyres Ltd. and Petlas Tire Corporation represent regional specialists serving legacy platform support requirements and cost-sensitive retread economics. Qingdao Sentury Tire Co., Ltd. exemplifies the scale-driven entrant archetype leveraging domestic manufacturing capacity for narrow-body fleet penetration.
| Leading Market Players |
|---|
| Dunlop Aircraft Tyres Ltd. |
| Desser Holding Company LLC |
| Michelin |
| Petlas Tire Corporation |
| Qingdao Sentury Tire Co., Ltd. |
| Goodyear Tire & Rubber Company |
| Specialty Tires of America |
| Wilkerson Company Inc. |
| Bridgestone Corporation |
| Others |
Supply Flow & Price Mechanics
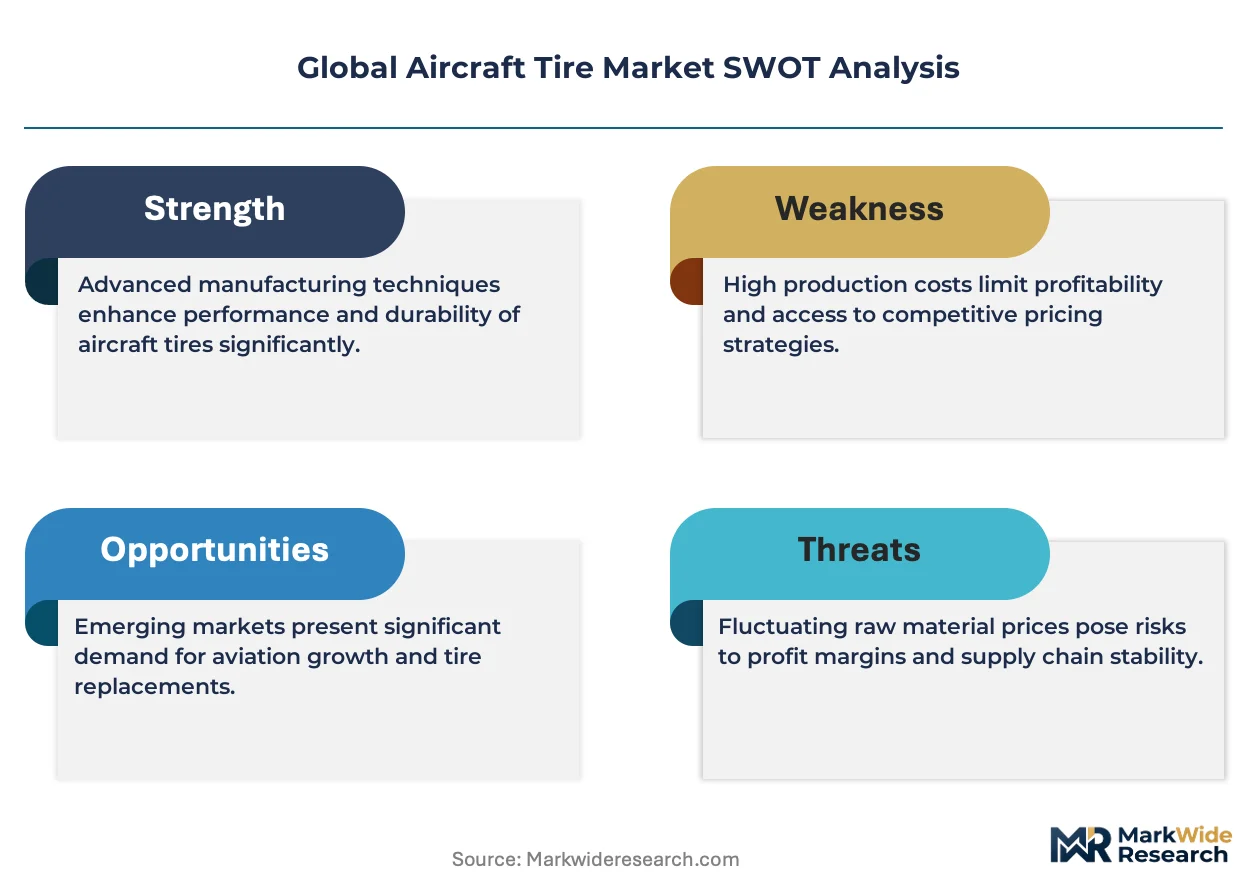
Southeast Asian natural rubber harvest concentration in Thailand, Indonesia, and Vietnam anchors raw material cost volatility that cascades through compounder margins and concentrates pricing power with vertically integrated manufacturers holding captive rubber processing operations.
Pricing Analysis
Certification level creates the primary spread between FAA-EASA dual-qualified specifications and single-jurisdiction alternatives, with three-tier pricing structure across OEM-fitment, fleet-lifecycle contracts, and spot aftermarket purchases. Brand premiums attach to aramid-reinforced radial architectures qualified for extended on-wing intervals, while price erosion runs through bias-ply retread services as cycle frequency compresses. Cargo operators and regional turboprop fleets exhibit highest price sensitivity; military aviation and wide-body flag carriers show lowest.
Supply Chain Analysis
Natural rubber latex processing concentrates in Thailand, Indonesia, and Malaysia, with synthetic polymer feedstocks drawing from South Korean and Japanese petrochemical complexes. Aramid fiber carcass reinforcements hinge on DuPont and Teijin supply allocations, while carbon black and silica fillers face REACH-driven reformulation pressures. Single-source vulnerability concentrates in aramid cord ply supply. Distribution runs through lessor-aggregator direct contracts, third-party MRO procurement consortia, and regional distributor stocking locations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Operating lease platform consolidation is redefining procurement aggregation, with lessor technical interoperability standards creating ecosystem lock-in effects that favor compounders embedding predictive tire monitoring into lifecycle contracts.
For Market Incumbents: Harden defensible positions through backward integration into aramid fiber sourcing and captive rubber compounding capacity in Southeast Asia to insulate margin pools from harvest volatility. Accelerate CAAC-GB certification parallel-track investments before COMAC program volumes scale, as dual-compliance capability gaps expose share vulnerability to integrated domestic suppliers. For New Entrants and Emerging Players: India's greenfield MRO corridor near Delhi and Mumbai offers the most penetrable geographic entry point, with BIS-standard qualification pathways shorter than FAA-EASA dual tracks. Target rapid-turn retread services for narrow-body fleets through localized distribution partnerships rather than OEM-fitment competition. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional retread specialists holding fleet-lifecycle contracts with narrow-body lessors. Five-to-ten-year viability hinges on radial architecture displacement velocity and electric taxi system qualification timing. Monitor CAAC certification backlog clearance rates as inflection signal for tripartite approval capacity constraints easing.| Strategic Initiative | Industry Significance |
|---|---|
| Aramid Fiber Backward Integration | Captive supply of Teijin or DuPont fiber allocations insulates compounders from aerospace-grade aramid shortages. |
| CAAC-GB Parallel Certification Investment | Dual-track testing protocols unlock COMAC C919 and ARJ21 program access before domestic suppliers consolidate. |
| Predictive Tire Monitoring Platform | Embedded sensor integration enables outcome-based lifecycle contracting with lessor-aggregator procurement platforms. |
| India MRO Corridor Joint Venture | Greenfield retread capacity near Delhi-Mumbai industrial corridor captures localized demand from IndiGo and Air India narrow-body fleets. |
| Sustainable Compound Reformulation | Pre-certified REACH-compliant aromatic oil alternatives secure European lessor preference before carbon-border adjustment enforcement. |
Methodological Framework
Desk research of FAA Technical Standard Order databases, EASA Certification Specification filings, and customs trade flow records preceded structured interviews with airline fleet engineering directors, MRO procurement managers, lessor technical operations leads, and rubber compounding R&D heads. Secondary validation drew from tire manufacturer SEC filings, COMAC supplier qualification announcements, and BIS/GB standards documentation. Bottom-up fleet replacement schedule modeling triangulated against top-down OEM delivery projections.
Assumptions held natural rubber price volatility within historical bands and certification timeline durations at observed averages across the analysis window. Segmentation dimensions modeled include construction methodology, end-user operational profile, dimensional sizing tier, and distribution channel configuration. CAGRs derived from fitted growth curves applied to replacement cycle frequency data and fleet expansion schedules, with electric taxi system adoption rates and sustainable aviation fuel weight distribution impacts treated as scenario variables.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Qingdao Sentury or Petlas in CAAC-qualified radial architectures would shift outcomes. Quarterly review of COMAC program delivery rates, India PLI scheme beneficiary announcements, and REACH substance restriction enforcement timing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Passenger Tire Market
Tires and Wheels
Performance Tires Market
Tires and Wheels
Global Advanced Tires Market
Tires and Wheels
Automotive Racing Slicks Tire Market
Tires and Wheels
Global Commercial Vehicle Run Flat Tire Inserts Market
Tires and Wheels
Wheel and Tire Service Equipment Market
Tires and Wheels
Re-Tread Tires Market
Tires and Wheels
Global Winter Tires Market
Tires and Wheels
Europe Tire Market
Tires and Wheels
Automotive Intelligent Tires Market
Tires and Wheels
E-Bike Tire Market
Tires and Wheels
Automotive Wheel Rims Market
Tires and Wheels
Low Rolling Resistance Tire Market
Tires and Wheels
Global Ultra High Performance Tire Market
Tires and Wheels
United States Tire Market
Tires and Wheels
Heavy Duty Tire Market