
 Heavy Duty Tire Market | 2026-2036
Heavy Duty Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy Duty Tire Market Foresight
Independent dealer networks is tilting toward fleet-direct contracts as volume buyers consolidate procurement. Bridgestone Corporation leverages its captive retread infrastructure to lock in construction fleet accounts across North America. Michelin anchors premium radial positions in European mining contracts through long-term service agreements. Continental Tires competes on integrated telematics packages that tie tire performance data to fleet management systems.
Heavy duty tires are engineered elastomer structures reinforced with steel belts and textile plies, designed to sustain loads exceeding 2,500 kg per tire under severe duty cycles including abrasion, heat buildup, and puncture exposure. Their primary purpose is to maintain operational uptime in commercial vehicles and off-highway equipment where failure costs dwarf replacement expense. Radial tires command the dominant share of replacement value in long-haul trucking due to fuel efficiency and mileage advantages, while off-road tires capture concentrated margin pools in mining and quarry applications where downtime penalties structure buyer willingness to pay. Bias tires retain structural relevance in emerging-market construction fleets where initial acquisition cost overrides lifecycle economics.
The US Department of Transportation enforces FMVSS 119 standards for truck tire performance, while the EPA regulates retread facility emissions under Clean Air Act provisions. Brazil's INMETRO certification mandates rolling resistance labeling for commercial tires sold domestically, reshaping import compliance costs for Asian manufacturers. Stakeholders must monitor how regional emissions enforcement divergence affects retread economics versus new tire substitution across their installed base.
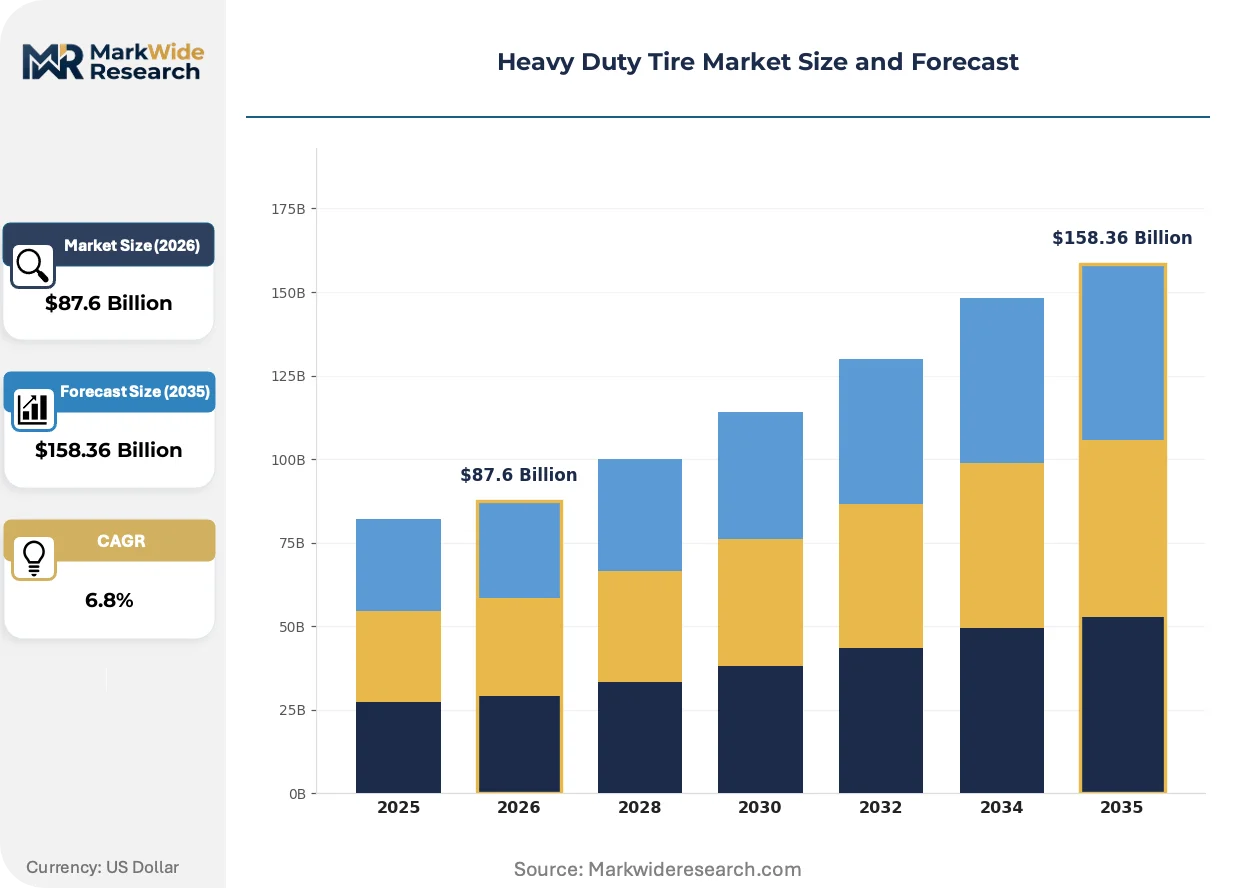
Market Dynamics
Fleet operators are compressing replacement cycles and demanding integrated tire-as-a-service contracts that bundle hardware, monitoring, and maintenance into single-source agreements, restructuring how manufacturers capture lifetime value.
Growth Catalysts
- EPA emissions rules:Tighter retread certification standards under Clean Air Act provisions are accelerating facility upgrades and consolidating compliant supply capacity.
- Mining fleet expansion:Chilean and Peruvian earthmover operations are extending replacement intervals, creating sustained demand for abrasion-resistant radial constructions.
- Telematics integration:Sensor-embedded tires transmitting pressure, temperature, and tread-wear data enable predictive maintenance and reduce unplanned downtime penalties.
Market Restraints
- Natural rubber price volatility:Thai and Indonesian supply disruptions transmit directly to compound costs, squeezing margin on high-volume bias-ply segments.
- Retread facility concentration:North American remanufacturing capacity clusters in the US Southeast, creating geographic vulnerability to hurricane-related production interruptions.
- Bias-ply substitution ceiling:Structural load limits prevent bias constructions from penetrating mining haul-truck applications above 100-ton payload classes.
Strategic Opportunities
- Brazilian agricultural belt:High-flotation harvester tire demand concentrates in Mato Grosso and Goiás, where soy and corn mechanization outpaces domestic supply response.
- EU Green Deal alignment:Rolling resistance labeling mandates under ECHA frameworks create premium positioning for low-hysteresis compounds in German and French long-haul fleets.
- Direct-to-fleet digital platforms:Procurement consolidation among 500-plus unit operators enables bypass of traditional dealer networks and capture of service revenue.
Industry Challenges
- Compound formulation expertise:Shortage of rubber chemists capable of balancing heat dissipation, cut resistance, and rolling resistance in custom mining specifications.
- Telematics-legacy fleet integration:Retrofitting sensor systems onto existing vehicle management platforms requires proprietary API development and extended pilot timelines.
- Multi-jurisdiction certification:Simultaneous compliance with US FMVSS 119, Brazil INMETRO, and EU labeling rules extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy Duty Tire Market |
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial Tires, Bias Tires, All-Weather Tires, Off-Road Tires End User: Fleet Operators, Construction Companies, Agriculture Equipment, Mining Sector Distribution Channel: Direct Sales, Online Retail, Authorized Dealers, Independent Retailers Application: Construction, Agriculture, Mining, Logging |
| Companies Covered | Michelin, Continental Tires, Balkrishna Industries Limited (BKT), Titan Tire Corporation, Sumitomo Rubber Industries, Bridgestone Corporation, Goodyear, Trelleborg AB, Yokohama, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy Duty Tire Market Shifts & Advancements
Material science advances and embedded intelligence are redefining performance benchmarks, while regulatory pressure and buyer consolidation force simultaneous investment in sustainability credentials and service infrastructure.
Intelligent tire systems integrating pressure, temperature, and RFID-based asset tracking are migrating from premium long-haul segments into mid-tier construction and municipal fleet applications. Regional operators with 50-200 unit fleets are piloting these systems at 15-20% annual adoption rates. The technology is migrating from diagnostic tools into integrated fleet management platforms that compress maintenance scheduling and warranty claim resolution.
Brazil's INMETRO certification mandates rolling resistance labeling for all commercial tires sold domestically, reshaping import compliance costs for Asian manufacturers. The regulation forces reformulation of entry-level radial lines to meet C-grade thresholds or accept margin-eroding price penalties. Domestic distributors are responding by consolidating supplier relationships around manufacturers with certified in-house testing laboratories.
Fleet-direct contracting is displacing traditional dealer-mediated procurement among volume buyers consolidating maintenance spend under single-source agreements. Independent dealer networks face margin compression as construction and waste-hauling operators in Texas, Alberta, and Queensland negotiate multi-year tire supply bundled with telematics and roadside service. This pattern is most visible in North American construction aggregates, where equipment utilization rates above 85% make uptime guarantees the decisive selection criterion.
Heavy Duty Tire Market Segmentation
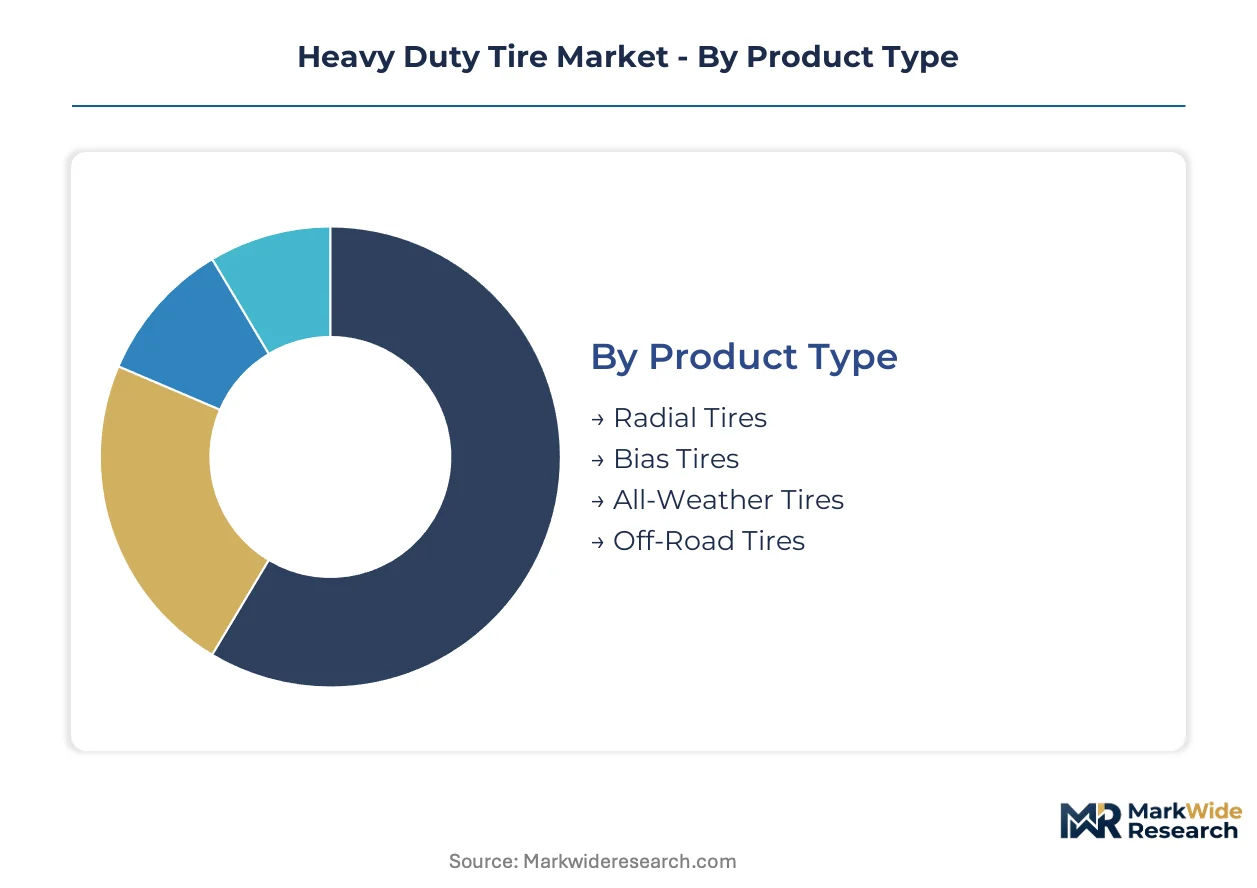
Heavy duty tire segmentation reveals how load-bearing requirements, duty cycle severity, and procurement consolidation reshape competitive positioning. Buyers sort across construction, mining, and agricultural applications where downtime costs and terrain exposure dictate specification choices.
Product Type:
Use cases span highway efficiency demands, severe off-road abrasion, and cost-constrained emerging market fleets where lifecycle economics diverge sharply.
- Radial Tires:Steel-belted constructions with circumferential plies reduce heat buildup and improve fuel efficiency in long-haul trucking. Demand concentrates in North American and European fleet contracts where mileage warranties and rolling resistance ratings determine procurement awards.
- Off-Road Tires:Reinforced sidewalls and deep-tread compounds withstand rock penetration and sustained load deformation in surface mining. Chilean copper operations and Australian iron ore haul roads specify these for 100-ton payload trucks where structural failure triggers production line stoppages.
- Bias Tires:Cross-ply nylon or polyester constructions retain relevance in emerging-market construction where acquisition cost overrides total cost of ownership calculations.
- All-Weather Tires:Compromise tread patterns and intermediate rubber hardness serve mixed-use municipal fleets in temperate climates with moderate seasonal variation.
The dominant share belongs to Radial Tires, while Off-Road Tires is closing the gap fastest.
End User:
Procurement scale and technical sophistication separate volume buyers negotiating service-integrated contracts from fragmented operators purchasing through dealer networks.
- Fleet Operators:Consolidated trucking and logistics companies with 500-plus unit holdings demand predictive maintenance integration and single-source accountability. These buyers compress supplier margins through multi-year agreements bundling tires, telematics, and roadside service.
- Mining Sector:Integrated resource extraction companies operate specialized procurement desks specifying custom compounds for haul-truck and loader applications. Surface operations in Peru and South Africa extend replacement intervals through condition monitoring, sustaining premium radial demand.
- Construction Companies:Project-based contractors with seasonal utilization patterns prioritize availability and credit terms over performance specifications.
- Agriculture Equipment:Mechanized farming operations in Brazil and Ukraine specify high-flotation designs to reduce soil compaction in no-till cultivation systems.
Fleet Operators command the largest procurement volume, though Mining Sector buyers capture the highest margin per unit.
Distribution Channel:
Channel selection reflects buyer scale, technical service requirements, and geographic proximity to retread infrastructure.
- Direct Sales:Manufacturer-account relationships bypass intermediaries for national fleet contracts requiring dedicated inventory positioning and field engineering support. Bridgestone and Michelin deploy direct teams for construction aggregates and waste hauling operators in Texas and Alberta.
- Authorized Dealers:Branded networks provide warranty adjudication, alignment services, and scrap tire recovery compliant with EPA regulations. These channels retain construction and municipal fleet relationships where technical consultation influences specification.
- Independent Retailers:Unaffiliated dealers serve owner-operators and small contractors through price-competitive sourcing and flexible credit.
- Online Retail:Digital platforms capture price-transparent replacement demand from independent truckers and regional maintenance shops.
Direct Sales channels are expanding most quickly, while Authorized Dealers defend position through service integration.
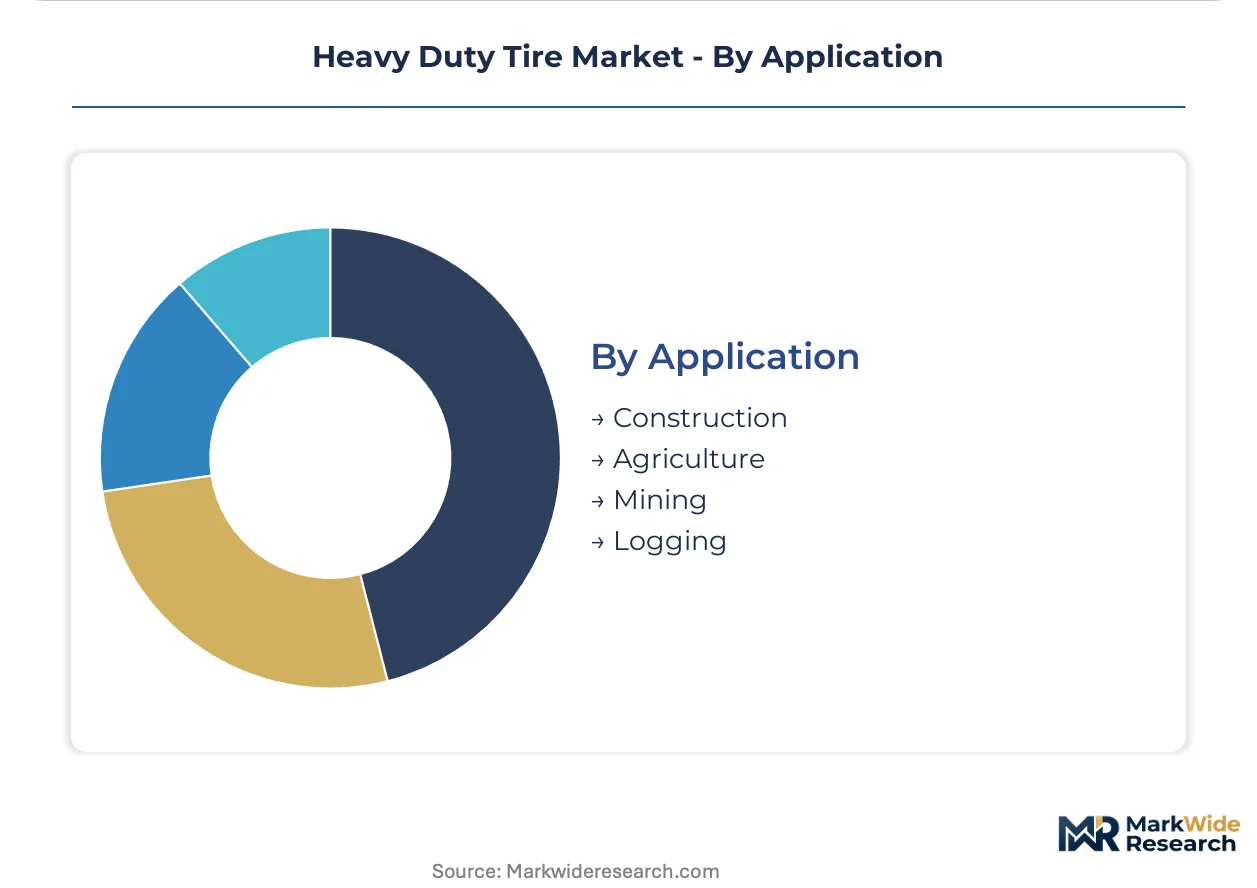
Application:
Terrain severity and equipment utilization rates structure compound formulation priorities and buyer willingness to pay for durability premiums.
- Mining:Surface extraction operations impose the harshest duty cycles with rock abrasion, sustained heavy loads, and heat accumulation. Custom specifications for copper and iron ore haul roads command substantial price premiums over standard commercial offerings.
- Construction:Aggregates, demolition, and infrastructure projects require cut-resistant compounds for loader and articulated truck applications. Equipment utilization above 85 percent makes uptime guarantees decisive in supplier selection.
- Agriculture:Seasonal harvest windows and field flotation requirements drive demand for large-diameter, low-pressure configurations in grain and oilseed production regions.
- Logging:Forest extraction operations in British Columbia and Scandinavia specify reinforced sidewalls to withstand stump penetration and cable damage.
Mining applications sustain the highest absolute margins, while Agriculture is gaining share fastest through mechanization in Brazil and Eastern Europe.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium radial pricing in Germany and France commands 35-40% markups over equivalent specifications in India and Thailand, creating a two-tier procurement landscape. This asymmetry reflects divergent regulatory stringency, fleet consolidation rates, and retread infrastructure maturity across markets.
United States
Construction aggregates and waste-hauling fleets in Texas and Alberta compress replacement cycles through telematics-integrated service contracts. EPA Clean Air Act enforcement tightens retread facility emissions standards, consolidating compliant supply capacity in the US Southeast. Fleet-direct procurement bypasses traditional dealer networks among operators with 500-plus unit holdings.
Germany
Long-haul trucking fleets prioritize rolling resistance ratings under EU Green Deal frameworks, favoring low-hysteresis compounds. ECHA labeling mandates create premium positioning for A-grade certified radials. Industrial clusters in Baden-Württemberg and Lower Saxony anchor retread technology development for cross-border export.
Brazil
Mechanized soy and corn operations in Mato Grosso and Goiás drive high-flotation harvester tire demand that outpaces domestic supply response. INMETRO certification mandates rolling resistance labeling, reshaping import compliance costs for Asian manufacturers. São Paulo-based distributors consolidate supplier relationships around certified in-house testing laboratories.
Chile
Surface copper mining operations extend earthmover replacement intervals through condition monitoring, sustaining premium radial demand. National mining codes enforce environmental liability provisions that condition operating permits on equipment maintenance standards. Antofagasta and Calama haul roads specify custom compounds for 100-ton payload trucks.
China
Domestic mining and construction equipment production scales bias-ply output for cost-constrained emerging market export. MIIT industrial standards harmonize with GB certification protocols for commercial vehicle tires. Shandong Province manufacturing clusters supply replacement demand across Southeast Asia and Africa.
Heavy Duty Tire Market Competitive Landscape
Integrated tire-as-a-service providers and compound-specialist manufacturers split the market along the fault line of fleet scale and application severity. Three archetypes dominate: captive retread networks locking in construction accounts through maintenance bundling; premium radial specialists anchoring European mining contracts via long-term service agreements; and integrated telematics packagers tying tire performance data to fleet management platforms. Consolidation accelerates through multi-year procurement contracts and geographic retread capacity expansion.
Among Japan-based rubber conglomerates, Bridgestone Corporation and Sumitomo Rubber Industries exemplify the captive infrastructure archetype. Continental Tires anchors the European premium positioning tier. These three occupy positions that reflect divergent strategic bets on service integration versus compound specialization.
| Leading Market Players |
|---|
| Michelin |
| Continental Tires |
| Balkrishna Industries Limited (BKT) |
| Titan Tire Corporation |
| Sumitomo Rubber Industries |
| Bridgestone Corporation |
| Goodyear |
| Trelleborg AB |
| Yokohama |
| Others |
Supply & Pricing Matrix
Thai and Indonesian natural rubber supply concentration funnels directly into margin pools at mining and quarry applications, where compound costs represent a smaller fraction of buyer willingness to pay for abrasion resistance and structural integrity. This upstream geography-to-downstream-margin linkage shapes how manufacturers allocate formulation expertise across customer tiers.
Pricing Analysis
The customization-premium spread separates configured-to-order mining specifications from standard commercial radial lines by substantial multiples, reflecting compound development costs and batch production economics. Three-tier pricing structure across premium, standard, and economy levels aligns with certification grade and after-sales service bundling, with EU Green Deal A-grade rolling resistance ratings commanding substantial premiums in German long-haul procurement. Price erosion runs through entry-level bias-ply segments as Asian manufacturers absorb INMETRO compliance costs to maintain Brazilian market access. Fleet operators with 500-plus unit holdings exhibit lowest price sensitivity due to uptime guarantee valuation, while emerging-market construction contractors prioritize acquisition cost over lifecycle economics.
Supply Chain Analysis
Export-control regimes limiting advanced sensor technology flows create friction in telematics-embedded tire sourcing for certain fleet management integrations. Manufacturing gravity centers on Thailand and Indonesia for natural rubber processing, China for steel cord and textile ply production, and Germany for specialized compound mixing equipment. Raw material dependencies encompass Thai RSS3 rubber grades, Belgian steel belt wire, and carbon black from US Gulf Coast petrochemical complexes. Single-source vulnerability concentrates in Southeast Asian rubber processing capacity exposed to monsoon disruption patterns. Distribution runs through captive retread networks for construction fleet accounts and authorized dealer channels for municipal and independent operator segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against tire-as-a-service platform entrants bundling predictive maintenance and roadside assistance into hardware procurement, threatening traditional transactional margin capture.
For Market Incumbents: Insulate core fleet accounts through captive retread infrastructure expansion in the US Southeast and Alberta construction corridors, locking in multi-year service contracts before digital-native competitors achieve scale. Compound formulation R&D investment in low-hysteresis mining specifications anchors European mining contracts against premium radial specialists. Vertical integration into sensor-embedded tire production defends against telematics-platform disintermediation threats. For New Entrants and Emerging Players: Mid-market municipal fleets in Eastern Europe and Southeast Asia represent the most penetrable entry point, where telematics adoption lags and price transparency remains limited. Brazilian agricultural distributors lacking certified in-house testing laboratories offer channel partnership opportunities for INMETRO-compliant product lines. Direct-to-fleet digital platforms bypassing traditional dealer networks enable rapid scale among 50-200 unit regional operators piloting intelligent tire systems. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across telematics-integrated manufacturing footprints, favoring scaled players with existing sensor partnerships and API development capabilities. Acquisition targets should emphasize compound-specialist manufacturers with mining sector relationships and in-house rubber chemistry expertise. The signal to watch is consolidation velocity among independent dealer networks facing margin compression from fleet-direct procurement trends.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Retread Network Expansion | Locks in construction fleet accounts through bundled maintenance and uptime guarantees in Texas aggregates. |
| Telematics Platform Integration | Ties tire performance data to fleet management systems via Continental Tires' embedded sensor architectures. |
| INMETRO Certification Investment | Enables Brazilian market access for Asian manufacturers facing rolling resistance labeling mandates. |
| Low-Hysteresis Compound Development | Captures EU Green Deal premium positioning in German and French long-haul fleet contracts. |
| Direct-to-Fleet Digital Platform Launch | Bypasses dealer margin extraction among 500-plus unit operators consolidating procurement spend. |
Research Methodology
A spread of perspectives from fleet procurement directors, mining sector maintenance engineers, retread facility operators, and rubber compound chemists converged on the working assumptions governing demand elasticity and substitution dynamics. Primary interviews with construction aggregates managers and agricultural equipment distributors in Brazil and Eastern Europe were cross-referenced against customs trade data, EPA Clean Air Act enforcement records, and INMETRO certification databases. Secondary validation drew from tire manufacturer technical specifications, mining sector equipment utilization reports, and EU ECHA rolling resistance labeling registries. Bottom-up unit economics and top-down sectoral demand aggregation were reconciled through iterative triangulation.
Demand-supply balance framing anchored the analytical framework across the analysis window, with segmentation modeling spanning radial versus bias-ply construction types, mining versus construction versus agricultural end-uses, and direct sales versus dealer-mediated distribution channels. CAGRs were derived from replacement cycle compression rates, mechanization penetration curves in Brazilian soy production, and fleet telematics adoption velocity. Industry-specific forecast inputs encompassed Chilean copper haul road tire consumption patterns and EPA retread facility emissions compliance timelines.
Macroeconomic conditions sit as an overlay; deviation in Thai natural rubber export volumes, Chinese steel cord pricing, or Brazilian agricultural credit availability would shift the trajectory. Forecasts reflect documented assumptions regarding fleet consolidation rates and regulatory enforcement intensity. Material shifts in EPA Clean Air Act retread certification stringency or EU ECHA labeling threshold adjustments would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Tubeless Tire Market
Tires and Wheels
Carbon Wheels Market
Tires and Wheels
Asia-Pacific Aircraft Tires Market
Tires and Wheels
Automotive Wheel Market
Tires and Wheels
Automotive Wheel Cap Market
Tires and Wheels
Intelligent Tire Market
Tires and Wheels
Cargo Bike Tire Market
Tires and Wheels
GCC Tire Market
Tires and Wheels
Automotive Tire Chains Market
Tires and Wheels
Bicycle Rim Market
Tires and Wheels
Automotive Tubeless Tire Market
Tires and Wheels
Indirect Tire Pressure Monitoring System Market
Tires and Wheels
Automotive Alloy Wheels Market
Tires and Wheels
Low Rolling Resistance Tire Market
Tires and Wheels
Wheel Market
Tires and Wheels
Passenger Tire Market