
 EV Tire Market | 2026-2036
EV Tire Market Size, Share, and Industry Trends Forecast 2026-2036
EV Tire Market Insights
Ultra-low rolling resistance specifications is collapsing the gap between premium efficiency benchmarks and mass-market EV platforms. Continental AG leverages captive rubber compounding facilities to secure compound consistency across its European plants. Bridgestone Corporation anchors its position through integrated silica dispersion R&D in Japan. Michelin differentiates via acoustic foam-lined architectures that address cabin noise thresholds specific to electric drivetrains.
An EV tire is a pneumatic or solid tire engineered with reinforced sidewalls, specialized tread compounds, and optimized contact patches to withstand higher instantaneous torque loads and extended wear cycles characteristic of battery-electric vehicles; its primary purpose is to maximize range efficiency while maintaining safety under regenerative braking stress. Low rolling resistance technology captures the dominant margin pool as OEMs prioritize range certification figures, while smart tires embedding pressure and temperature sensors represent the fastest-expanding segment due to fleet telematics integration. All-season tires retain volume leadership in temperate climates, though performance tires gain share in premium EV segments where acceleration ratings drive replacement cycles.
The EPA regulates tire fuel efficiency ratings under its tire labeling program, while REACH restricts aromatic oils and high-priority substances in European tire manufacturing, and China's GB standards mandate rolling resistance and wet grip classifications for domestic tire sales. These frameworks collectively elevate compliance costs for non-integrated manufacturers while creating preferential market access for suppliers with certified sustainable material supply chains. Stakeholders must monitor evolving battery-electric vehicle weight distributions and their implications for load index recalibration in next-generation tire architectures.
Market Dynamics
Instantaneous torque loads from battery-electric drivetrains are forcing tire architectures to accommodate sustained high-stress contact patches without sacrificing rolling efficiency targets. Load index recalibration now dominates OEM specification sheets as vehicle weights climb with larger battery packs.
Growth Catalysts
- EU F-Gas Regulation:Phase-down schedules for fluorinated greenhouse gases are accelerating R&D investment in sustainable tire compounds across European manufacturing facilities.
- Fleet telematics integration:Commercial operators deploying electrified logistics vehicles are mandating sensor-embedded tires for real-time pressure and temperature monitoring.
- China GB standards:Mandatory rolling resistance and wet grip classifications for domestic tire sales are elevating technical entry barriers and consolidating supplier relationships with certified compound producers.
Market Restraints
- Natural rubber price volatility:Concentrated sourcing from Southeast Asian plantations exposes compounders to climate-driven supply disruptions and input cost spikes.
- Silica dispersion technical ceiling:Current wet-grip formulations face performance plateaus that limit simultaneous optimization of rolling resistance and hydroplaning resistance.
- REACH aromatic oil restrictions:Substitution costs for compliant process oils compress margin structures for non-integrated compound manufacturers serving European OEMs.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for advanced automotive components are attracting greenfield tire capacity targeting domestic EV assembly lines.
- Acoustic foam-lined architectures:Cabin noise thresholds specific to electric drivetrains are creating premium replacement demand distinct from legacy internal-combustion specifications.
- Regenerative braking stress modeling:Tire-wear prediction algorithms integrated with vehicle telematics systems enable predictive maintenance contracts for fleet operators.
Industry Challenges
- Compound formulation talent scarcity:Specialized rubber chemists capable of balancing silica-silane coupling efficiency with sustainable material ratios command premium compensation packages.
- Dual certification timelines:Simultaneous EPA fuel efficiency labeling and REACH substance compliance create extended validation cycles for new product launches.
- Retooling capex intensity:Modernizing calendering and extrusion lines for ultra-low rolling resistance profiles requires substantial capital deployment with multi-year payback horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Tire Market |
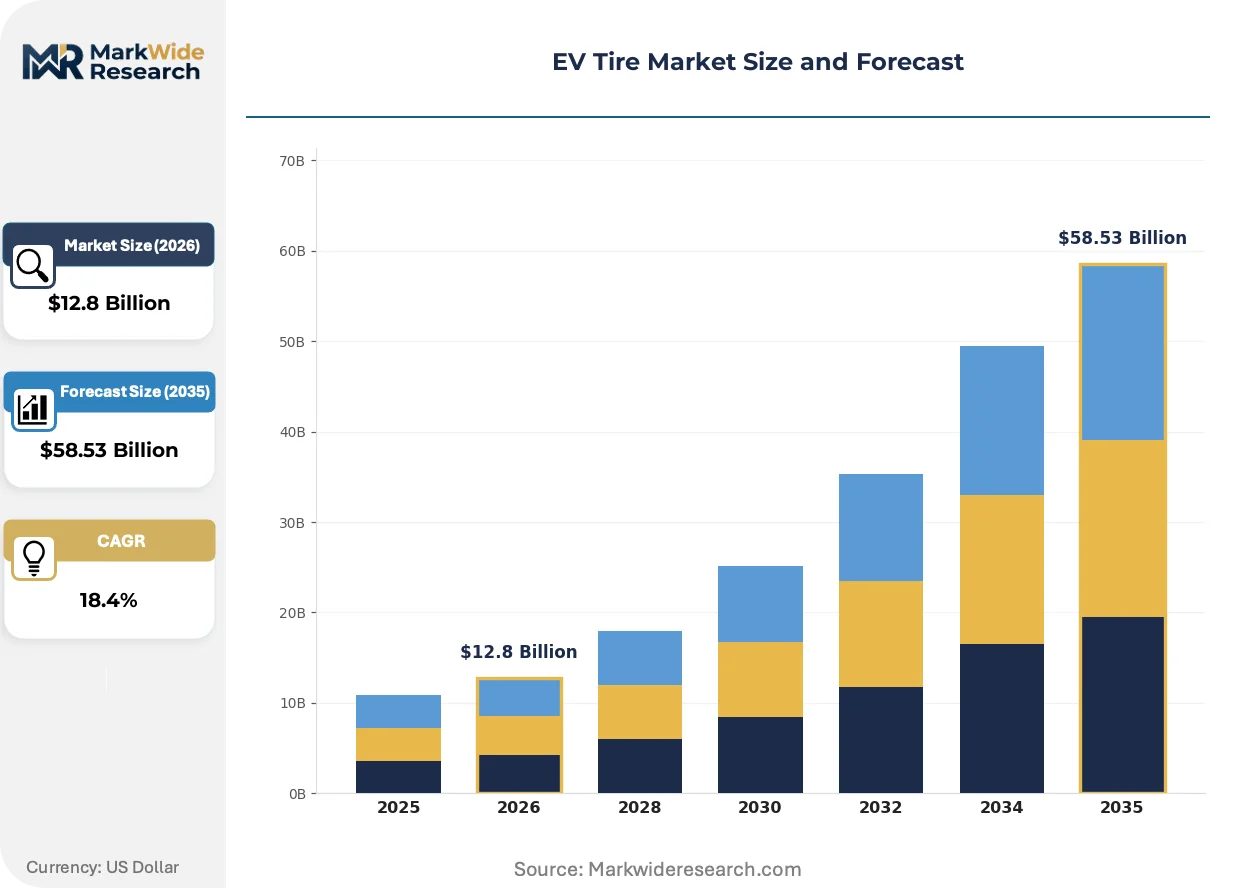
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $58.53 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: All-Season Tires, Performance Tires, Winter Tires, Off-Road Tires Technology: Run-Flat Technology, Low Rolling Resistance, Smart Tires, Eco-Friendly Materials End User: OEMs, Aftermarket Providers, Fleet Operators, Car Enthusiasts Application: Urban Driving, Highway Usage, Off-Road Driving, Racing |
| Companies Covered | Michelin, Bridgestone Corporation, Goodyear Tire and Rubber Company, Continental AG, Pirelli, Hankook Tire and Technology, Yokohama Rubber, Nokian Tyres, Apollo Tyres, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Tire Market Trends and Innovations
Material science breakthroughs and embedded sensor architectures are redefining how tire performance is measured, monetized, and maintained across passenger and commercial EV deployments. Specification convergence between efficiency mandates and durability requirements is compressing traditional product lifecycle assumptions.
Silica-silane coupling technology is fragmenting the traditional trade-off between wet grip and rolling resistance. Premium OEM platforms are adopting third-generation functionalized silanes at accelerated procurement cycles. This chemistry is fragmenting legacy compound hierarchies by enabling single-tire solutions that previously required seasonal swaps.
REACH substance restrictions and the EU Green Deal carbon border adjustments are tightening material provenance requirements for tires sold into European markets. Compounders must now document sustainable natural rubber sourcing and recycled content percentages. Commercial vehicle segments face the steepest compliance cost escalations as fleet operators prioritize total-cost-of-ownership certifications.
Fleet procurement departments are consolidating supplier relationships around integrated tire-and-telemetry service bundles. Traditional wholesale distribution channels face disintermediation pressure as direct OEM-fleet contracts capture volume commitments with embedded sensor maintenance. China-based logistics operators are pioneering this consolidation, leveraging domestic telematics platform integration to compress replacement cycle variability.
EV Tire Market Segmentation
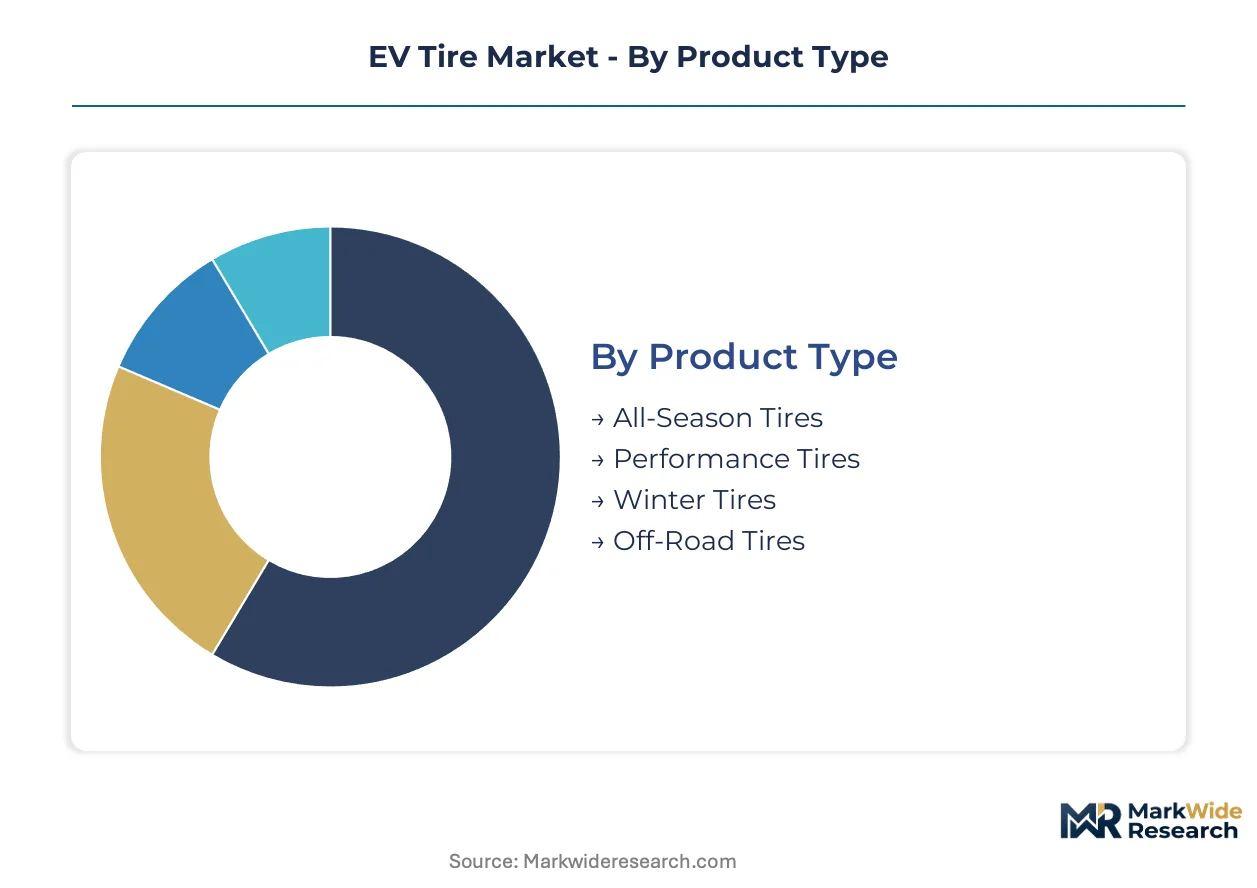
EV tire segmentation reflects divergent technical requirements between range-optimized passenger vehicles and durability-focused commercial fleets. Specification fragmentation accelerates as battery-electric drivetrains impose novel stress profiles on contact patches and sidewall architectures.
Product Type:
Winter tires face acute substitution pressure from advancing all-season silica formulations that narrow the cold-weather performance gap.
- All-Season Tires:Multi-compound tread architectures balance wet grip coefficients with rolling resistance targets across temperature bands. OEM procurement in China concentrates volume here as domestic EV platforms prioritize year-round certification compliance over seasonal swap logistics.
- Performance Tires:Reinforced carcass constructions withstand instantaneous torque delivery from dual-motor configurations without sacrificing lateral stiffness ratings. Premium EV segments in Germany and South Korea drive replacement cycle compression as acceleration benchmarks intensify wear rates.
- Winter Tires:Specialized soft compounds maintain elasticity below 7°C thresholds for Nordic and Alpine markets.
- Off-Road Tires:Aggressive tread blocks and puncture-resistant sidewalls serve electric pickup and SUV segments in rural Australia and the US Mountain West.
All-Season tires retain volume leadership; Performance tires hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium sensor-embedded platforms from commodity efficiency treatments.
- Low Rolling Resistance:Silica-dominant tread formulations and optimized contact patch geometries maximize range certification figures. Regulatory mandates under China's GB standards and EPA fuel efficiency labeling compel baseline adoption across mass-market EV assembly lines.
- Smart Tires:Pressure, temperature, and accelerometer sensors transmit real-time data via Bluetooth Low Energy or UWB protocols. Fleet operators in California and the Netherlands mandate these systems for predictive maintenance contracts on electrified logistics vehicles.
- Run-Flat Technology:Self-supporting sidewall constructions enable limited mobility post-puncture for premium passenger segments.
- Eco-Friendly Materials:Bio-sourced rubber fractions and recycled carbon black satisfy REACH substance restrictions and EU Green Deal provenance requirements.
Low Rolling Resistance commands the widest installed base; Smart Tires are climbing the fastest.
End User:
Procurement pattern divergence separates integrated OEM-fleet contracts from fragmented retail replacement channels.
- OEMs:Direct specification control over load index, rolling resistance coefficients, and acoustic performance thresholds. European and Chinese automakers consolidate supplier relationships around multi-year platform commitments with embedded sustainability certification.
- Fleet Operators:Electrified logistics and ride-hail fleets in India and Brazil negotiate tire-and-telemetry service bundles with total-cost-of-ownership guarantees. Telematics integration compresses replacement cycle variability and shifts procurement toward outcome-based contracts.
- Aftermarket Providers:Independent distributors serve replacement demand through wholesale and retail channels.
- Car Enthusiasts:Niche demand for track-day and aesthetic customization drives premium pricing in aftermarket segments.
OEMs retain volume leadership; Fleet Operators hold the steepest expansion curve.
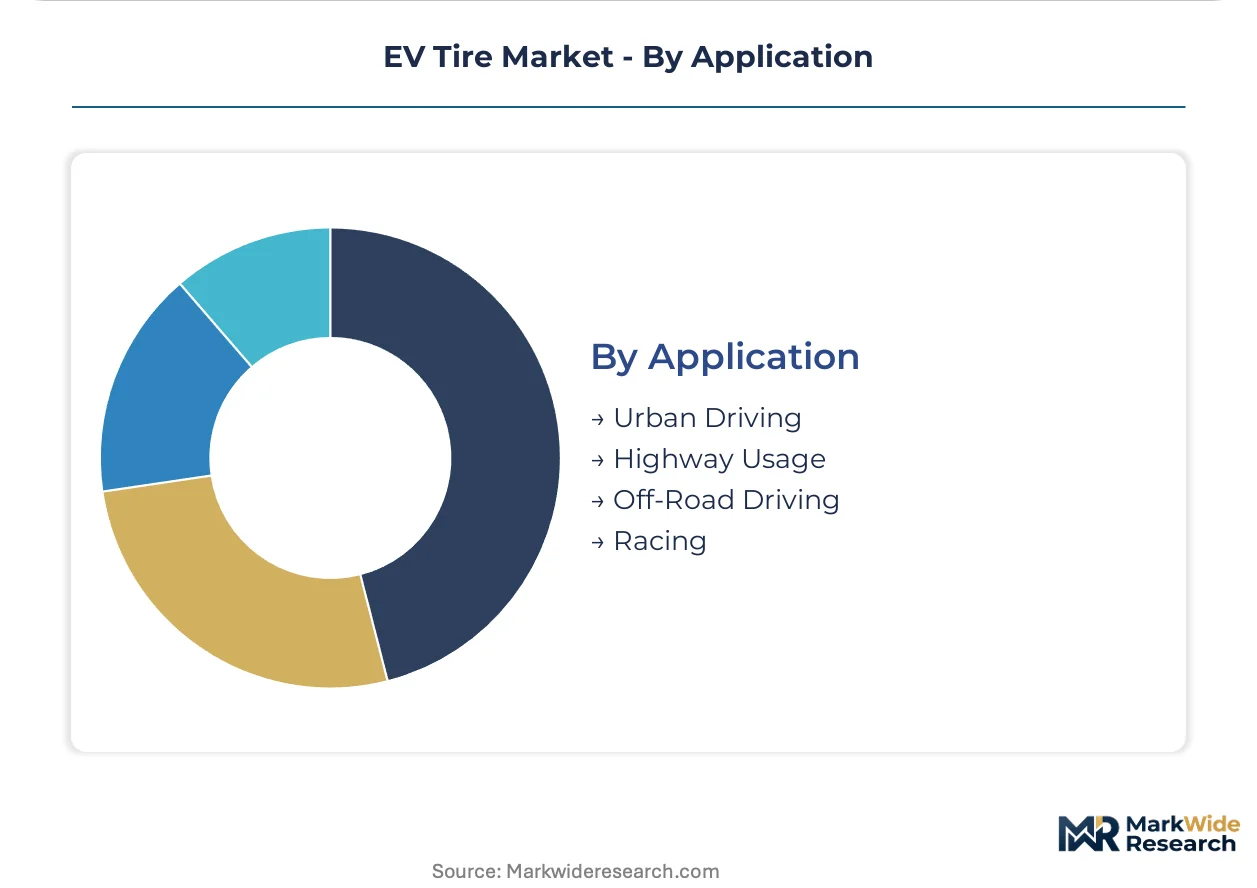
Application:
Geography-driven stress profiles dictate compound hardness and tread pattern optimization priorities.
- Urban Driving:Stop-start regenerative braking cycles and pothole impact resistance dominate specification sheets. High-density EV adoption in London, Singapore, and São Paulo concentrates demand for reinforced sidewalls and noise-dampening foam liners.
- Highway Usage:Sustained speed stability and hydroplaning resistance at elevated velocities require stiffer belt packages. German autobahn-rated and US interstate-certified tires carry premium positioning for long-range EV platforms.
- Off-Road Driving:Mud, gravel, and rock traction requirements conflict with efficiency targets for electric truck segments.
- Racing:Extreme grip compounds with accelerated wear trade-offs serve closed-circuit competition formats.
Urban Driving retains volume leadership; Highway Usage holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates in Chinese tire manufacturing corridors serving domestic EV assembly lines, with compound formulation expertise clustering in European industrial regions facing REACH compliance deadlines. Secondary capacity expansions target Indian and Southeast Asian markets through production-linked incentive schemes.
China
Domestic EV production volumes dominate global output, concentrating demand for GB-standard certified tires in the Yangtze River Delta and Pearl River Delta manufacturing belts. MIIT rolling resistance mandates elevate technical entry barriers for foreign suppliers. Qingdao and Shanghai anchor integrated tire-and-vehicle supply chains where compounders co-locate with EV OEMs.
Germany
Premium EV platforms from Stuttgart and Munich drive specification intensity for acoustic foam-lined architectures and autobahn-rated performance thresholds. KBA certification requirements and EU F-Gas Regulation phase-down schedules compress product validation timelines. The Ruhr Valley and Baden-Württemberg host captive rubber compounding facilities serving Continental AG's European plant network.
United States
EPA fuel efficiency labeling programs and California fleet electrification mandates shape procurement criteria for light-duty and commercial EV tires. Tesla's Texas Gigafactory and Rivian's Illinois operations concentrate OEM specification power. Detroit-area testing facilities validate load index recalibrations for heavier battery-electric pickup platforms.
India
PLI scheme incentives attract greenfield tire capacity targeting domestic EV assembly lines in Tamil Nadu and Gujarat. BIS standards for rolling resistance and wet grip classifications align with GB standard harmonization efforts. Chennai and Pune industrial corridors concentrate logistics fleet deployments mandating sensor-embedded tire contracts.
Japan
Integrated silica dispersion R&D clusters in Kansai and Chubu regions supply premium compound formulations to domestic and export markets. METI carbon neutrality roadmaps accelerate sustainable material substitution timelines. Yokohama and Osaka anchor tire maker headquarters co-located with automotive OEM engineering centers.
EV Tire Market Competitive Landscape
Concentration sits with integrated multinational tire manufacturers possessing captive rubber compounding and silica dispersion capabilities. Three structural archetypes dominate: full-line global suppliers with OEM platform commitments, regional specialists leveraging proximity to domestic EV assembly lines, and technology-focused players emphasizing smart tire sensor integration. Competitive moves center on backward integration into sustainable natural rubber sourcing and multi-year fleet service contracts with embedded telemetry maintenance.
Among European-headquartered manufacturers, Continental AG and Michelin occupy positions representing integrated compound-to-tire production archetypes. Bridgestone Corporation anchors the Asia-based multinational tier with Japanese R&D heritage. These three exemplify how scale and formulation expertise consolidate specification control over premium OEM platforms and fleet telematics-integrated contracts.
| Leading Market Players |
|---|
| Michelin |
| Bridgestone Corporation |
| Goodyear Tire and Rubber Company |
| Continental AG |
| Pirelli |
| Hankook Tire and Technology |
| Yokohama Rubber |
| Nokian Tyres |
| Apollo Tyres |
| Others |
Pricing and Supply Chain Analysis
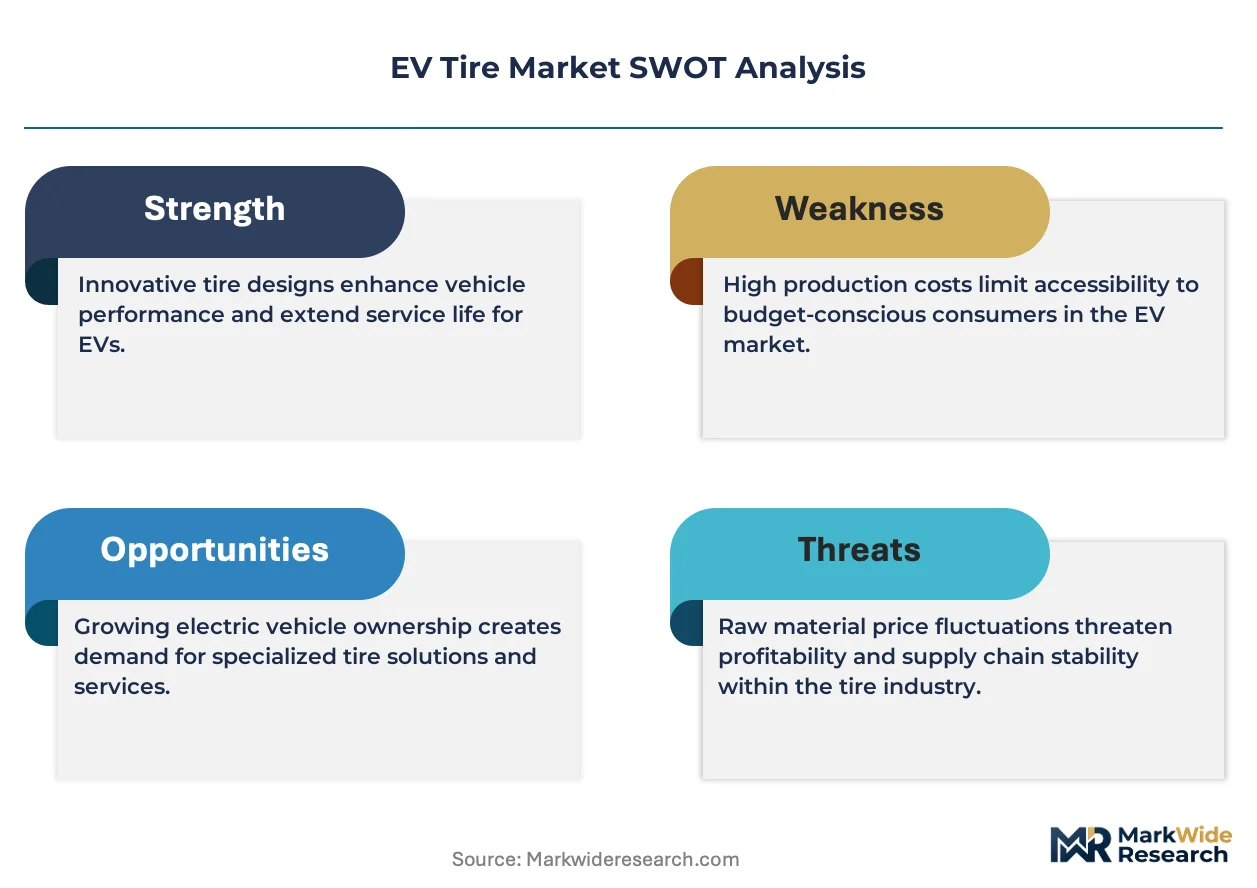
Long-term offtake contracts between compound manufacturers and Southeast Asian natural rubber plantations lock in supply access while dampening spot price volatility for European tire makers facing REACH aromatic oil substitution mandates. These arrangements tether procurement costs to plantation yield cycles and climate risk, compressing margin flexibility for non-integrated compounders serving OEM platform commitments.
Pricing Analysis
China's GB standards dictate the pricing tier structure across domestic EV assembly lines, separating certified low-rolling-resistance compounds from commodity grades. Three-tier pricing structure across premium acoustic-foam architectures, standard silica-dominant formulations, and economy wet-grip alternatives stratifies procurement. Cost compression in economy tiers intensifies because of natural rubber price volatility and REACH-compliant process oil premiums. Fleet operators exhibit highest price sensitivity due to total-cost-of-ownership modeling, while premium OEM platforms absorb certification premiums for range certification figures.
Supply Chain Analysis
Container availability constraints on Southeast Asian trade lanes elevate inbound logistics costs for natural rubber shipments to European compounding facilities. Supply concentrates in Thailand, Indonesia, and Vietnam for natural rubber feedstock, with silica sourcing anchored in China and high-purity grades from Japan. Raw material dependencies center on natural rubber latex, precipitated silica, and sustainable carbon black fractions. Single-source vulnerability concentrates in plantation geography exposed to climate-driven yield disruptions. Distribution runs through integrated OEM-fleet direct contracts and fragmented aftermarket wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EV tire demand sits in early-cycle expansion as fleet electrification mandates accelerate replacement cycle compression beyond historical internal-combustion baselines. Battery-electric vehicle production volumes in China and Europe outpace installed tire capacity for certified compound supply.
For Market Incumbents: Compound backward integration into sustainable natural rubber sourcing to secure REACH and EU Green Deal provenance documentation. Expand captive silica dispersion capacity in Baden-Württemberg or Kansai industrial corridors to defend formulation expertise premiums against emerging Asian compounders. Prioritize multi-year fleet telemetry service bundles to lock in replacement demand before channel disintermediation accelerates. For New Entrants and Emerging Players: Predictive maintenance algorithm gaps in commercial fleet contracts present white-space where incumbents under-serve. Target India's PLI-subsidized greenfield capacity zones in Tamil Nadu and Gujarat for domestic OEM platform qualification. Pursue telematics-native tire architectures with Bluetooth Low Energy sensor integration as the primary go-to-market angle against legacy wholesale distribution. For Investors and Strategic Acquirers: Capital is best deployed toward compound formulation specialists with certified sustainable material supply chains and captive rubber compounding infrastructure. Long-term viability favors assets positioned for REACH substance restriction compliance and EU F-Gas Regulation phase-down timelines. Monitor GB standard harmonization progress across BIS and MIIT regulatory frameworks as the inflection signal for cross-border platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sustainable Rubber Sourcing | REACH and EU Green Deal provenance requirements elevate certified supply chain premiums for European OEM access. |
| Silica Dispersion R&D Capacity Expansion | Third-generation functionalized silane chemistry fragments legacy wet-grip versus rolling-resistance trade-offs. |
| Fleet Telematics Service Bundle Launch | California and Netherlands logistics operators mandate sensor-embedded tire contracts for predictive maintenance. |
| Acoustic Foam-Lined Architecture Development | Electric drivetrain cabin noise thresholds create premium replacement demand distinct from legacy specifications. |
| India PLI Scheme Manufacturing Footprint | Tamil Nadu and Gujarat greenfield capacity targets domestic EV assembly line procurement consolidation. |
Research Methodology
Cross-validation between primary interviews with tire compound R&D directors, OEM platform procurement leads, fleet telematics operators, and aftermarket distribution managers anchors the qualitative findings against secondary validation. Secondary sources include MIIT production databases, EPA fuel efficiency labeling registries, REACH substance restriction filings, customs trade data for natural rubber imports, and IHS Markit vehicle registration datasets. Bottom-up segment sizing triangulates with top-down market boundary checks across product type, technology tier, and end-user procurement pattern dimensions.
Sensitivity analysis frameworks test forecast outputs against variable adoption rates for smart tire sensor integration and fleet electrification penetration scenarios across the projection horizon. Segmentation dimensions modeled encompass product type architecture, compound technology tier, end-user procurement structure, and application stress profile. CAGRs derive from logistic curve fitting to technology adoption patterns and OEM platform rollout schedules. Industry-specific inputs include battery-electric vehicle weight distribution trajectories and regenerative braking cycle intensity assumptions.
Underlying assumptions cover sustained OEM platform electrification commitments, REACH substance restriction enforcement timelines, and natural rubber plantation yield stability, with deviation risk concentrated in climate-driven supply disruptions and regulatory harmonization delays between GB, BIS, and EPA certification frameworks. Practitioners should keep alternative scenarios live as fleet telematics integration rates and sustainable material substitution cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Steel Cord for Tire Reinforcement Market
Tires and Wheels
North America 2-Wheeler Tire Market
Tires and Wheels
Carbon Wheels Market
Tires and Wheels
Tubeless Tire Market
Tires and Wheels
Asia-Pacific Alloy Wheels Market
Tires and Wheels
Tire Cord Market
Tires and Wheels
Global Aircraft Tire Market
Tires and Wheels
Asia Pacific 2-Wheeler Tire Market
Tires and Wheels
Global OTR Tires Market
Tires and Wheels
Automotive Winter Tire Market
Tires and Wheels
High Performance Wheels Market
Tires and Wheels
Asia-Pacific Aircraft Tires Market
Tires and Wheels
Global Electric Vehicle Tire Market
Tires and Wheels
Tire Changers Market
Tires and Wheels
Solid Tire Market
Tires and Wheels
Truck and Bus Radial (TBR) Tire Market