
 Southeast Asia Waste-To-Energy Market | 2026-2036
Southeast Asia Waste-To-Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Waste-To-Energy Market Analytics
Municipal procurement of waste-to-energy capacity is collapsing toward large-scale integrated operators and away from fragmented local developers. Keppel Corporation leverages its Singapore engineering base to anchor EPC contracts across ASEAN utility-scale projects. Mitsubishi Heavy Industries Ltd competes on advanced stoker grate technology for high-moisture tropical waste streams. Veolia Environment SA extends its operational footprint through long-term service contracts with municipal clients in Indonesia and Thailand.
Waste-to-energy converts combustible refuse into electricity or heat through thermal or biological processes, with modern incineration plants achieving combustion temperatures above 850 degrees Celsius to ensure complete pollutant breakdown and energy recovery. The technology serves dual industrial purposes: reducing landfill volume by approximately 90 percent while generating baseload power for grid-connected or captive industrial use. Incineration occupies the dominant share of installed capacity due to proven reliability with mixed municipal solid waste, yet gasification is gaining structural momentum as industrial consumers seek higher electrical efficiency and lower bottom ash residues. Anaerobic digestion captures distinct margin pools in agricultural residue applications across palm oil processing clusters, where organic feedstock concentration supports distributed biogas generation.
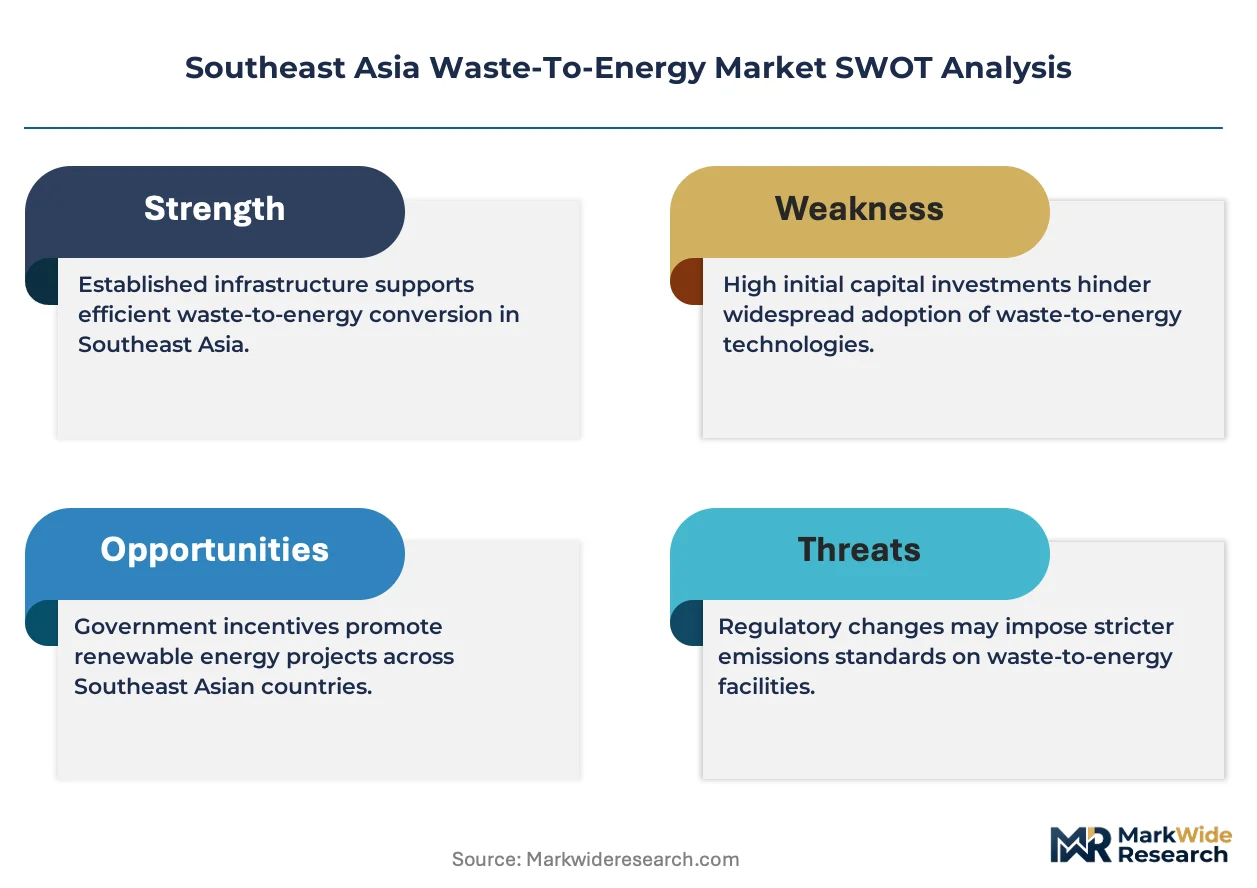
Indonesia's Ministry of Environment and Forestry enforces landfill reduction targets that directly mandate waste-to-energy adoption in provincial capitals, while Thailand's Provincial Electricity Authority integrates feed-in tariff structures that shape project finance viability for private developers. Vietnam's MONRE implements emission standards aligned with ASEAN environmental protocols, creating compliance barriers for imported subcritical technologies. Stakeholders must monitor regulatory divergence on carbon accounting methodologies, as divergent treatment of biogenic emissions across national frameworks will determine which technology configurations secure long-term offtake contracts.
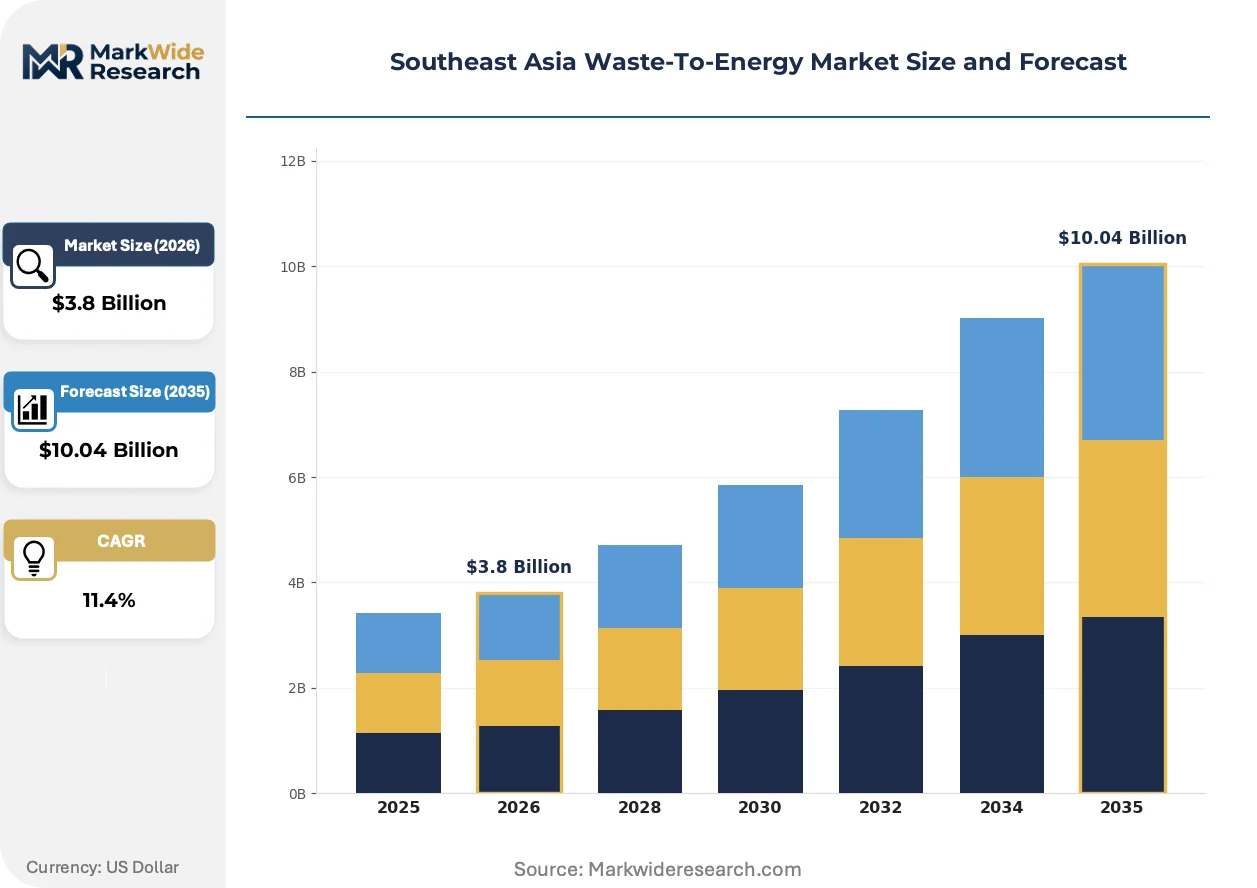
Market Dynamics
Municipal procurement consolidation around integrated EPC operators is compressing margins for fragmented local developers while accelerating project execution timelines across Indonesia, Thailand, and Vietnam.
Growth Catalysts
- Landfill Diversion Mandates:Indonesia's Ministry of Environment and Forestry enforces provincial capital reduction targets that directly compel waste-to-energy procurement.
- Feed-in Tariff Structures:Thailand's Provincial Electricity Authority integrates preferential pricing mechanisms that improve project finance viability for private developers.
- Industrial Zone Clustering:Palm oil processing facilities in Malaysia's Peninsular region concentrate organic feedstock for distributed anaerobic digestion deployment.
Market Restraints
- High-Moisture Waste Handling:Tropical municipal solid waste streams exceed 60% moisture content, degrading combustion efficiency and requiring advanced stoker grate modifications.
- Technology Import Dependence:Critical combustion and gasification equipment concentrates supply among Japanese and European engineering conglomerates, exposing projects to currency volatility and extended lead times.
- Emission Standard Divergence:Vietnam's MONRE implements ASEAN-aligned protocols that create compliance barriers for subcritical imported systems, fragmenting equipment qualification requirements.
Strategic Opportunities
- Gasification Technology Convergence:Plasma-assisted gasification combined with syngas cleaning systems enables higher electrical efficiency and near-zero bottom ash output for industrial captive power users.
- Philippines Archipelago Deployment:Island municipalities outside Luzon face acute landfill capacity constraints and limited grid interconnection, creating distributed generation opportunities.
- Carbon Accounting Clarity:Divergent national treatment of biogenic emissions presents first-mover advantage for developers securing methodologies that qualify for international offset mechanisms.
Industry Challenges
- Waste Characterization Expertise Gap:Local engineering teams lack calibrated sampling protocols for heterogeneous tropical waste streams, leading to plant design mismatches and operational underperformance.
- Residue Management Infrastructure:Bottom ash and air pollution control residue disposal requires hazardous waste landfill partnerships that remain underdeveloped outside Jakarta, Bangkok, and Ho Chi Minh City corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Waste-To-Energy Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Incineration, Gasification, Anaerobic Digestion, Pyrolysis Feedstock Type: Municipal Solid Waste, Agriculture Residue, Industrial Waste, Biomass End User: Energy Providers, Waste Management Companies, Municipalities, Industrial Consumers Regulatory Framework: National Policies, Local Regulations, Environmental Standards, Incentive Programs |
| Companies Covered | Mitsubishi Heavy Industries Ltd, Keppel Corporation, Veolia Environment SA, Hitachi Zosen Corp, China Everbright Environment Group, PT Yokogawa Indonesia, Babcock & Wilcox Volund, Martin GmbH, Welle Environmental Group, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Waste-To-Energy Market Evolving Landscape
Technology trajectories in Southeast Asian waste-to-energy are pivoting from conventional mass-burn incineration toward higher-efficiency thermal conversion and digital operational integration, driven by industrial buyer demands and tightening emission benchmarks.
Advanced stoker grate systems with automated combustion control and real-time flue gas monitoring are displacing fixed-grate configurations in municipal procurement specifications. Provincial utilities in Thailand and Vietnam now mandate these systems for projects above 10 MW capacity, compressing market space for basic imported equipment and elevating lifecycle service contract value.
Indonesia's Ministry of Environment and Forestry has tightened landfill reduction timelines for provincial capitals, forcing municipal governments to accelerate waste-to-energy procurement or face enforcement penalties. This regulatory pressure is reshaping project structuring, with Jakarta and Surabaya municipalities now prioritizing operational track record over lowest-capital-cost bids in vendor selection.
Long-term service and availability-based contracts are replacing traditional EPC-only procurement for utility-scale plants. Thailand's Provincial Electricity Authority and Vietnam's state grid operators now require 15-20 year O&M commitments as condition of offtake approval, consolidating vendor relationships around integrated operators with regional maintenance infrastructure.
Southeast Asia Waste-To-Energy Market Segmentation
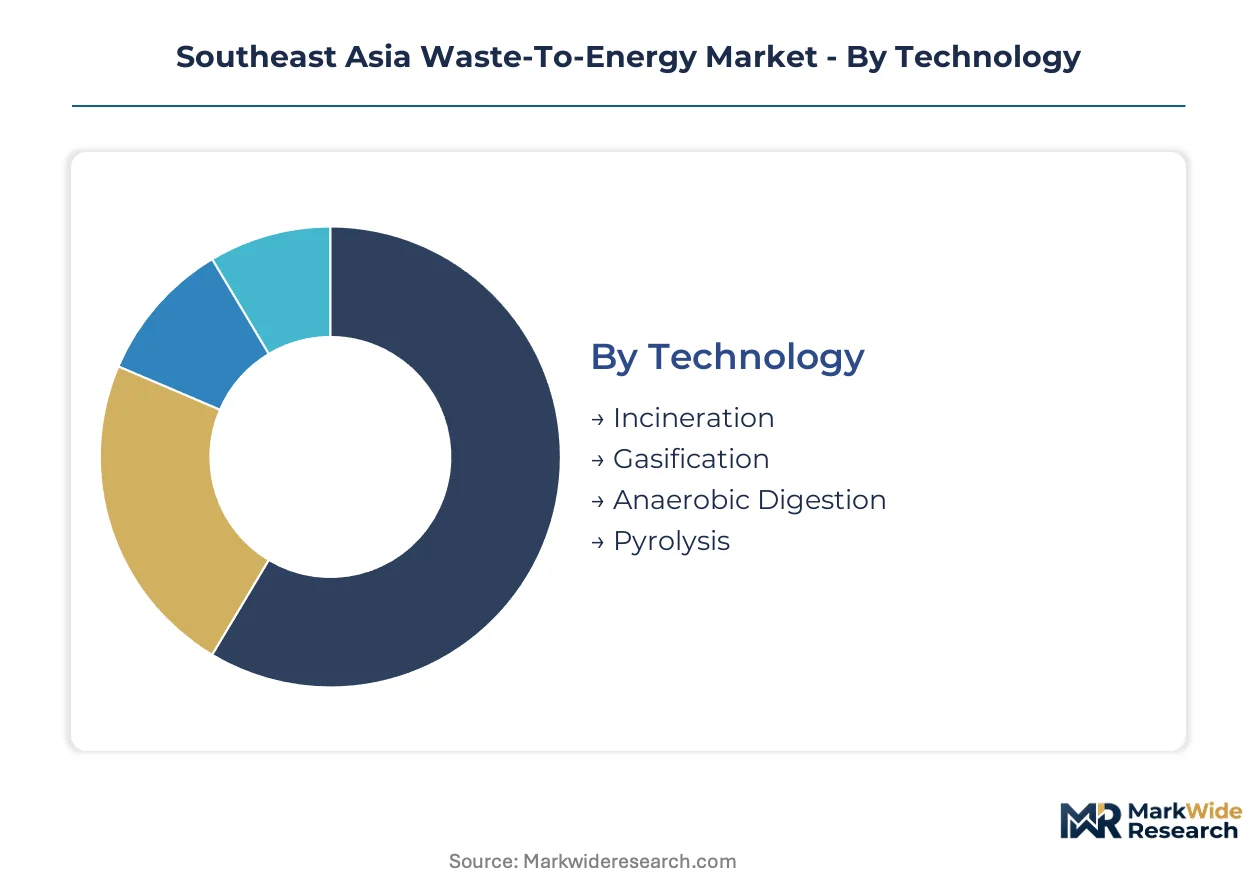
Technology configuration and feedstock characteristics determine project economics across Southeast Asia's heterogeneous waste streams. Procurement patterns diverge sharply between municipal tenders seeking proven reliability and industrial buyers prioritizing efficiency gains.
Technology:
Domestic demand concentrates in mass-burn systems with established local O&M capabilities, while export-led technology flows originate from Japanese and European engineering conglomerates supplying advanced thermal conversion equipment.
- Incineration:Mass-burn systems with stoker grate configurations achieve combustion temperatures above 850 degrees Celsius, ensuring complete pollutant breakdown. Thai Provincial Electricity Authority and Indonesian provincial capitals concentrate procurement here, driven by landfill diversion mandates with enforcement penalties for non-compliance.
- Gasification:Plasma-assisted and conventional gasification systems convert waste to syngas for higher electrical efficiency. Industrial zones in Vietnam and Malaysia's Peninsular region deploy these systems, seeking lower bottom ash residues and captive power generation.
- Anaerobic Digestion:Biological decomposition captures methane from organic feedstock; palm oil processing clusters in Malaysia concentrate distributed biogas deployment.
- Pyrolysis:Thermal decomposition in oxygen-absent environments produces liquid fuel and char; pilot installations focus on plastic waste streams in Indonesian special economic zones.
Incineration holds the largest share; momentum sits with gasification as industrial buyers seek efficiency advantages.
Feedstock Type:
Moisture content and calorific value create distinct processing economics, with tropical waste streams above 60 percent moisture requiring specialized pre-treatment systems.
- Municipal Solid Waste:Heterogeneous mixed waste streams dominate procurement volumes. Jakarta, Bangkok, and Ho Chi Minh City municipalities drive demand through landfill reduction targets, though high moisture degrades combustion efficiency without advanced grate modifications.
- Agriculture Residue:Palm oil empty fruit bunches and rice husks offer concentrated organic feedstock. Malaysia's processing clusters and Vietnam's Mekong Delta regions anchor anaerobic digestion deployment with predictable supply chains.
- Industrial Waste:Manufacturing byproducts and hazardous streams require specialized thermal treatment. Vietnamese industrial zones and Thai Eastern Economic Corridor facilities generate captive demand for high-temperature destruction systems.
- Biomass:Dedicated energy crops and forestry residues supplement waste-derived feedstock; Indonesian state utility procurement includes co-firing mandates for existing coal plants.
Municipal solid waste anchors volume; agriculture residue offers the steepest expansion trajectory as plantation clusters consolidate biogas infrastructure.
End User:
Contract structures diverge between public-sector offtake agreements with 15-20 year terms and industrial captive power arrangements with shorter payback horizons.
- Energy Providers:State utilities and independent power producers purchase electricity under feed-in tariff structures. Thailand's Provincial Electricity Authority and Vietnam's EVN shape project finance viability through preferential pricing mechanisms and grid interconnection standards.
- Waste Management Companies:Integrated operators secure long-term service contracts extending beyond EPC delivery. Veolia and regional specialists compete on operational track record for Indonesian and Thai municipal clients.
- Municipalities:Provincial capitals face direct regulatory pressure with landfill reduction timelines enforced by Indonesia's Ministry of Environment and Forestry.
- Industrial Consumers:Manufacturing facilities and plantation operators seek captive power with residue minimization; Malaysian palm oil processors and Vietnamese textile zones drive distributed generation demand.
Energy providers dominate contracted capacity; industrial consumers are gaining share fastest as captive power economics improve.
Regulatory Framework:
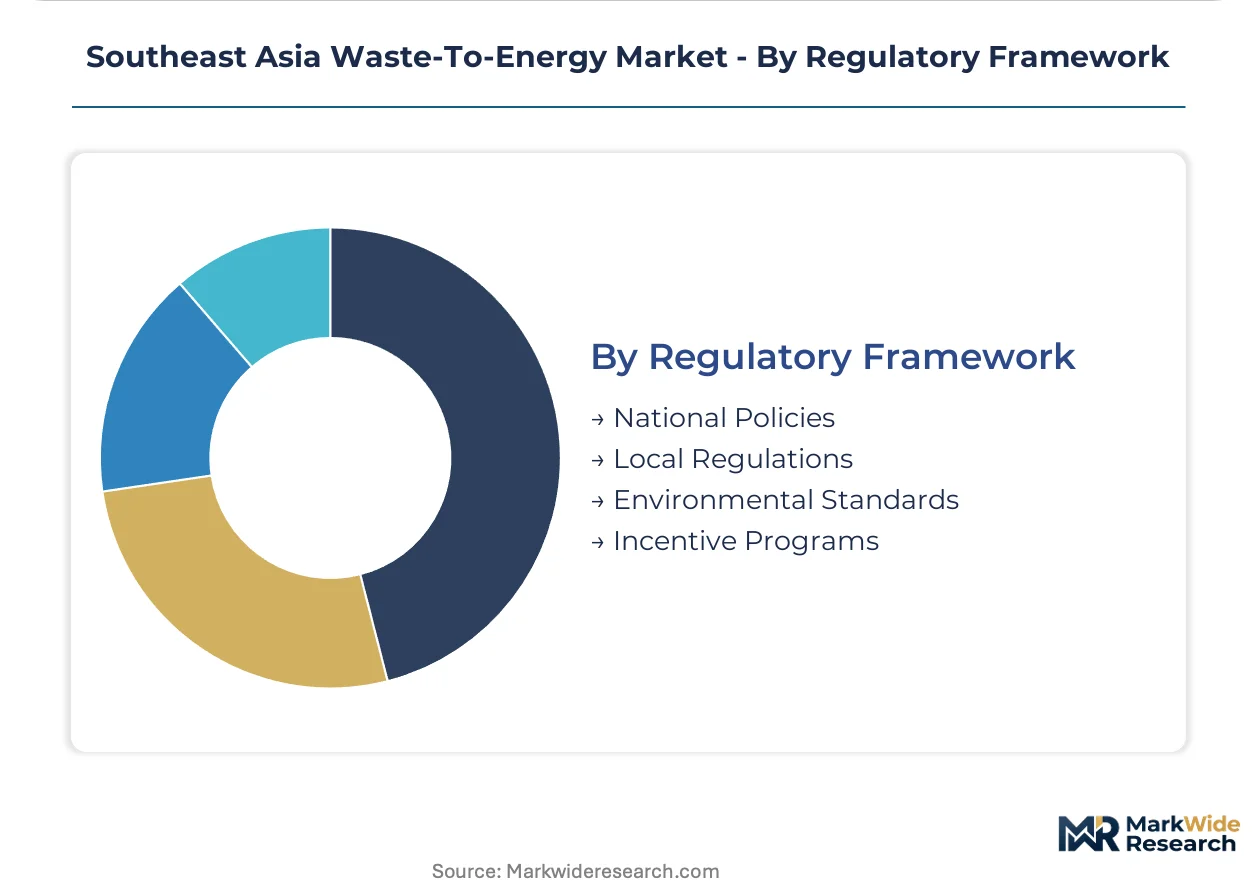
Compliance requirements fragment across national boundaries, with equipment qualification standards diverging on emission protocols and carbon accounting methodologies.
- National Policies:Indonesia's Ministry of Environment and Forestry mandates waste-to-energy adoption in provincial capitals with enforcement mechanisms. Thailand integrates national energy planning with waste management through coordinated ministerial frameworks.
- Local Regulations:Provincial and municipal ordinances determine site permitting, residue disposal requirements, and public consultation processes; Jakarta and Surabaya have accelerated approval timelines under emergency landfill capacity declarations.
- Environmental Standards:Vietnam's MONRE implements ASEAN-aligned emission protocols that exclude subcritical imported systems. Stack monitoring, dioxin limits, and bottom ash leachate testing create compliance barriers for basic equipment configurations.
- Incentive Programs:Feed-in tariffs, tax holidays, and carbon offset eligibility shape investor returns; divergent national treatment of biogenic emissions creates methodology uncertainty for international offset mechanisms.
National policies structure the largest procurement volumes; incentive programs present the most volatile variable as carbon accounting methodologies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese engineering conglomerates export advanced stoker grate systems to Indonesian and Thai utility buyers, while Singapore-based integrated operators anchor EPC contracts across ASEAN municipal tenders.
Indonesia
Jakarta and Surabaya municipalities drive procurement volumes through landfill reduction mandates enforced by the Ministry of Environment and Forestry. Provincial capitals face compliance deadlines that compress vendor selection timelines toward operators with operational track records. The Jababeka industrial zone outside Jakarta clusters captive power demand from textile and food processing facilities.
Thailand
The Provincial Electricity Authority shapes project economics through feed-in tariff structures that improve private developer returns. Bangkok Metropolitan Administration accelerates procurement under national energy planning frameworks coordinated across ministerial portfolios. The Eastern Economic Corridor concentrates industrial waste streams from automotive and electronics manufacturing zones.
Vietnam
MONRE implements emission standards aligned with ASEAN protocols that exclude subcritical imported combustion systems. Ho Chi Minh City and Hanoi municipalities dominate utility-scale procurement under provincial landfill capacity constraints. The southern industrial zones around Bình Dương and Đồng Nai generate captive demand for high-temperature thermal treatment systems.
Singapore
The National Environment Agency maintains strict emission benchmarks that elevate technology qualification barriers for equipment suppliers. Tuas Nexus integrates waste-to-energy with water reclamation in a single facility, demonstrating multi-utility operational models. Singapore-based engineering firms leverage domestic project experience to anchor regional EPC contract bids.
Malaysia
Palm oil processing clusters in Peninsular Malaysia concentrate organic feedstock for distributed anaerobic digestion deployment. The Sustainable Energy Development Authority administers feed-in tariff mechanisms for biogas generation projects. Johor and Pahang states anchor plantation-linked biogas infrastructure with predictable agricultural residue supply chains.
Southeast Asia Waste-To-Energy Market Competitive Landscape
Listed leaders compete with private specialists across engineering capability and operational track record dimensions. The vendor base concentrates around integrated EPC operators with regional maintenance infrastructure and specialized equipment fabricators serving niche technology segments. Three archetypes dominate: Singapore-based integrated operators anchoring utility-scale contracts, Japanese engineering conglomerates supplying advanced combustion systems, and European environmental services firms extending through long-term O&M agreements. Competitive moves center on 15-20 year service contract capture and technology licensing partnerships that accelerate local equipment qualification.
Within the integrated operator tier, Keppel Corporation and Mitsubishi Heavy Industries Ltd occupy positions shaped by geographic proximity to core markets. Keppel leverages Singapore engineering bases to anchor ASEAN utility-scale EPC contracts, while Mitsubishi Heavy Industries Ltd competes on stoker grate configurations adapted for high-moisture tropical waste streams. Veolia Environment SA exemplifies the environmental services archetype, extending operational footprints through municipal service contracts in Indonesia and Thailand.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries Ltd |
| Keppel Corporation |
| Veolia Environment SA |
| Hitachi Zosen Corp |
| China Everbright Environment Group |
| PT Yokogawa Indonesia |
| Babcock & Wilcox Volund |
| Martin GmbH |
| Welle Environmental Group |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Japanese and European fabrication facilities shapes both supply concentration and price floors for advanced stoker grate and gasification systems. Scale advantages in combustion equipment production compress margins for second-tier suppliers while elevating lifecycle service contract value for integrated operators with regional maintenance infrastructure.
Pricing Analysis
Current-generation plasma-assisted gasification commands premium positioning over conventional mass-burn incineration and legacy fixed-grate configurations. Project-based EPC contracting dominates municipal procurement, with price differentiation driven by equipment certification tier and bundled O&M commitment length. Cost compression in standard incineration packages is intensifying as Indonesian and Thai utilities consolidate vendor lists around proven operators. Industrial captive power buyers exhibit lowest price sensitivity due to residue minimization and efficiency premiums, while provincial municipalities face acute budget constraints.
Supply Chain Analysis
Japan and Germany anchor precision fabrication of stoker grate combustion systems and syngas cleaning equipment. Critical supply draws from specialty steel foundries in Austria and ceramic filter manufacturers in France for high-temperature flue gas treatment. Single-source vulnerability concentrates in advanced plasma torch assemblies and automated combustion control systems. Distribution runs through Singapore-based engineering firms that coordinate EPC delivery across ASEAN municipal tenders and industrial zone deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Long-term service contracts and availability-based O&M agreements expand faster than hardware sales, creating substantial recurring-revenue pools for operators with regional maintenance infrastructure.
For Market Incumbents: Fortify defensive positioning through backward integration into critical combustion component supply and accelerated certification investment for Vietnam's MONRE emission protocols. Emerging Chinese EPC contractors threaten margin structures in standard incineration tiers. Capacity addition in Thailand's Eastern Economic Corridor secures anchor client relationships before competitive entry intensifies. For New Entrants and Emerging Players: Lead with distributed anaerobic digestion deployment in Malaysia's palm oil processing clusters where feedstock concentration supports predictable biogas generation economics. Philippine island municipalities outside Luzon present the most penetrable geography due to acute landfill constraints and limited incumbent presence. Partner with established plantation operators for captive power offtake rather than competing for utility-scale tenders. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated operators with 15-20 year O&M contract backlogs and regional spare parts warehousing. Long-term viability across the projection horizon hinges on carbon accounting methodology clarity for biogenic emissions qualification. Acquisition targets should demonstrate operational track record in high-moisture tropical waste streams. The signal to watch is regulatory harmonization on emission standards across Indonesia, Thailand, and Vietnam.| Strategic Initiative | Industry Significance |
|---|---|
| Long-Term Service Contract Capture | Thailand's Provincial Electricity Authority now mandates 15-20 year O&M commitments as condition of offtake approval. |
| Technology Licensing Partnership | Japanese engineering conglomerates accelerate local equipment qualification through joint ventures with Indonesian fabricators. |
| Regional Maintenance Infrastructure | Singapore-based operators leverage domestic project experience to anchor ASEAN utility-scale EPC contract bids. |
| Carbon Accounting Methodology Investment | First-mover advantage accrues to developers securing biogenic emission treatment qualifying for international offset mechanisms. |
| Industrial Zone Clustering | Vietnamese manufacturing zones around Bình Dương generate captive demand for high-temperature thermal treatment systems. |
Research Methodology
Operator-level perspectives from EPC contractors, municipal procurement officers, plantation facility managers, and state utility planning directors anchored the qualitative base. Primary interviews combined with secondary validation from Indonesia's Ministry of Environment and Forestry policy circulars, Thailand Provincial Electricity Authority tariff filings, Vietnam MONRE emission protocols, and ASEAN energy planning frameworks. Bottom-up project pipeline analysis triangulated against top-down national waste generation forecasts.
Sensitivity analysis tested forecast robustness across feedstock availability scenarios, currency volatility exposure, and regulatory implementation delays. Segmentation dimensions modeled include technology configuration, feedstock moisture content tier, end-user contract structure, and national regulatory framework cluster. CAGRs derived from installed capacity buildout trajectories and unit economics evolution across the projection horizon. Forecast inputs incorporate landfill diversion mandate enforcement timelines and industrial zone development pace.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement pressure and feed-in tariff stability would require recalibration. Forecasts reflect documented assumptions on technology cost curves and residue disposal infrastructure development. Recalibration cycles align with material shifts in national carbon accounting methodologies and emission standard harmonization across ASEAN markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste to Energy Systems
ORC Waste Heat to Power Market
Waste to Energy Systems
Asia-Pacific Waste-To-Energy Market
Waste to Energy Systems
ORC Industrial Waste Heat to Power Market
Waste to Energy Systems
Nuclear Waste Recycling Market
Waste to Energy Systems
Anaerobic Digestion Equipment Market
Waste to Energy Systems
Energy Recovery Technologies Market
Waste to Energy Systems
Netherlands Waste to Energy Market
Waste to Energy Systems
Global Waste to Fuel Technology Market
Waste to Energy Systems
China Waste to Energy Market
Waste to Energy Systems
Drilling Waste Management Services Market
Waste to Energy Systems
Agricultural Waste to Energy Market
Waste to Energy Systems
Waste to Diesel Market
Waste to Energy Systems
Waste Heat to Power Market
Waste to Energy Systems
Global Waste-To-Energy Technologies Market
Waste to Energy Systems
APAC Waste Heat Recovery Systems Market
Waste to Energy Systems
Nuclear Waste Management Market