
 Polytrimethylene Terephthalate Market | 2026-2036
Polytrimethylene Terephthalate Market Size, Share, and Industry Trends Forecast 2026-2036
Polytrimethylene Terephthalate Market Outlook
Polyester resin compounding is fragmenting as specialty polymer houses and integrated fiber producers compete for the same feedstock and end-user relationships. TORAY INDUSTRIES, INC anchors its position through captive dimethyl terephthalate supply and downstream filament spinning operations. Teijin Limited differentiates via high-tenacity industrial yarn formulations and automotive upholstery partnerships. Asahi Kasei Corporation leverages its bio-PDO platform to serve European textile brands seeking reduced petrochemical content.
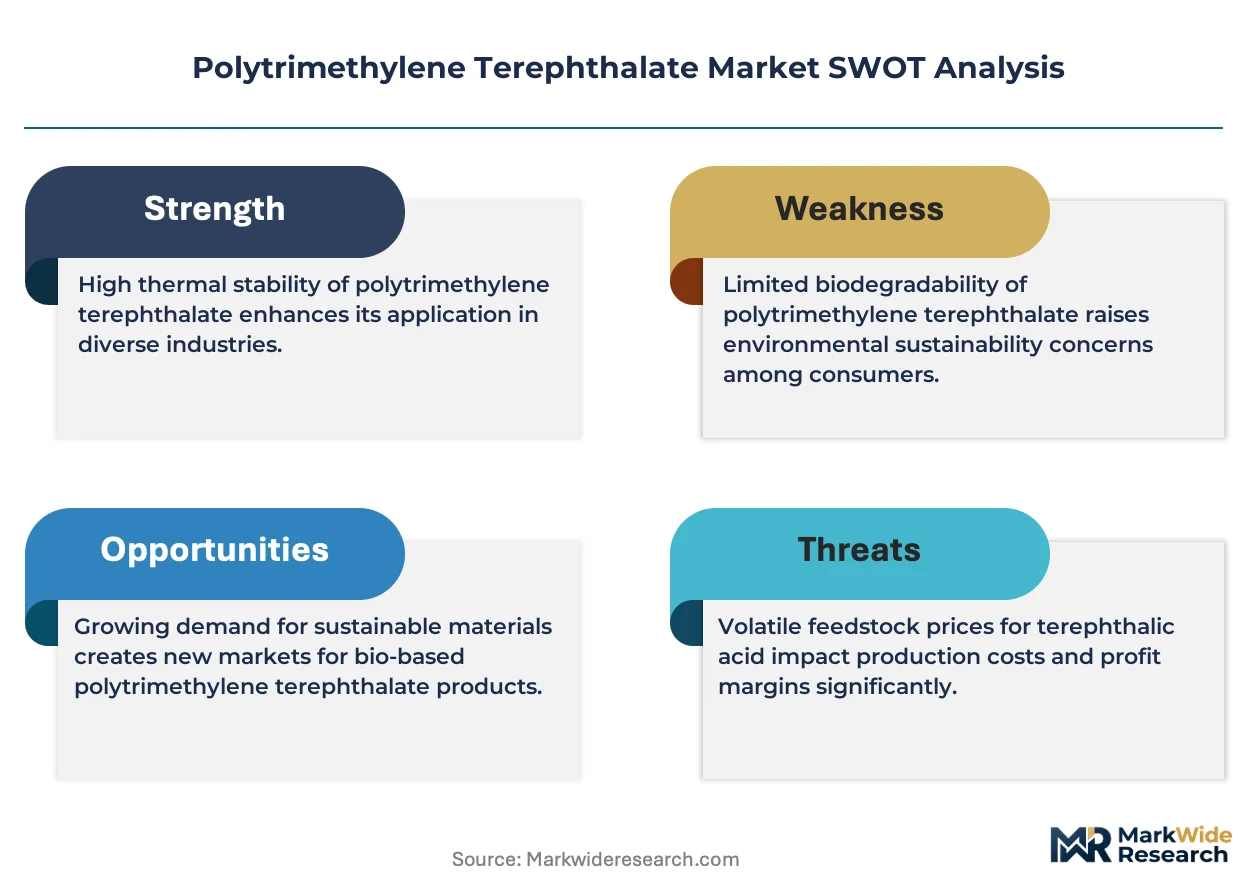
Polytrimethylene terephthalate is a semi-crystalline thermoplastic polyester produced via polycondensation of 1,3-propanediol and purified terephthalic acid, exhibiting a melting point near 228°C and superior elastic recovery compared to standard PET. Its primary commercial purpose centers on replacing nylon 6 and PET in carpet fiber, stretch textiles, and engineering resin applications where resilience and dyeability matter. Resin formulations currently command the deepest margin pools as compounders capture value from automotive and packaging grade certifications, while bio-based technology lines are expanding fastest as brand owners enforce supply chain carbon accounting. Conventional petroleum-based routes still dominate volume but face margin compression from propylene oxide feedstock volatility.
REACH registration requirements and the EU Green Deal's embodied carbon thresholds are restricting market access for non-compliant Asian resin imports, while FDA food-contact approvals govern PTT bottle and tray applications in the United States. Japan's METI has incorporated bio-based polymer content targets into its national plastics circularity roadmap, directly influencing Teijin and TORAY investment priorities. Stakeholders must monitor PDO feedstock origin certification and regional blending ratio mandates as the primary variables determining plant economics and customer qualification timelines.
Market Dynamics
PDO feedstock origin certification has become the decisive filter for supplier qualification, as automotive OEMs and European textile houses enforce mass-balance chain-of-custody requirements that disqualify conventional petroleum-based resin streams.
Growth Catalysts
- EU Green Deal bio-content mandates:Embodied carbon thresholds in automotive upholstery specifications are redirecting compounder procurement toward certified bio-PDO supply streams.
- Carpet fiber resilience specifications:Superior elastic recovery versus PET is capturing specification share in commercial flooring installations where crush resistance determines warranty terms.
- China integrated filament capacity:Shenghong Group and domestic converters are consolidating dimethyl terephthalate-to-yarn production, compressing regional logistics costs.
Market Restraints
- Propylene oxide feedstock volatility:Conventional petroleum-based PTT routes face margin compression from olefins pricing swings that compounders cannot pass through to fixed-price automotive contracts.
- REACH registration friction:Non-compliant Asian resin imports encounter market access barriers as ECHA enforcement tightens downstream due diligence obligations on European compounders.
- Nylon 6 technical performance ceiling:High-tenacity industrial yarn applications retain specification lock-in where PTT modulus characteristics fall short of aramid-reinforced benchmarks.
Strategic Opportunities
- India technical textile expansion:BIS certification pathways for automotive interior materials remain underdeveloped, creating first-mover positioning for bio-based resin suppliers.
- Food-contact tray applications:FDA approval for PTT bottle and thermoformed packaging grades opens substitution potential against crystallized PET in refrigerated ready-meal segments.
- Japan METI circularity targets:National plastics roadmap bio-content thresholds are accelerating Teijin and TORAY investment in fermentation-derived PDO capacity.
Industry Challenges
- Mass-balance auditor scarcity:Third-party certification bodies capable of validating bio-PDO chain-of-custody are concentrated in Western Europe, elongating Asian supplier qualification timelines.
- Automotive grade certification cycles:OEM interior material approvals require 18-24 month validation protocols that freeze formulation changes and lock compounders into incumbent feedstock relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polytrimethylene Terephthalate Market |
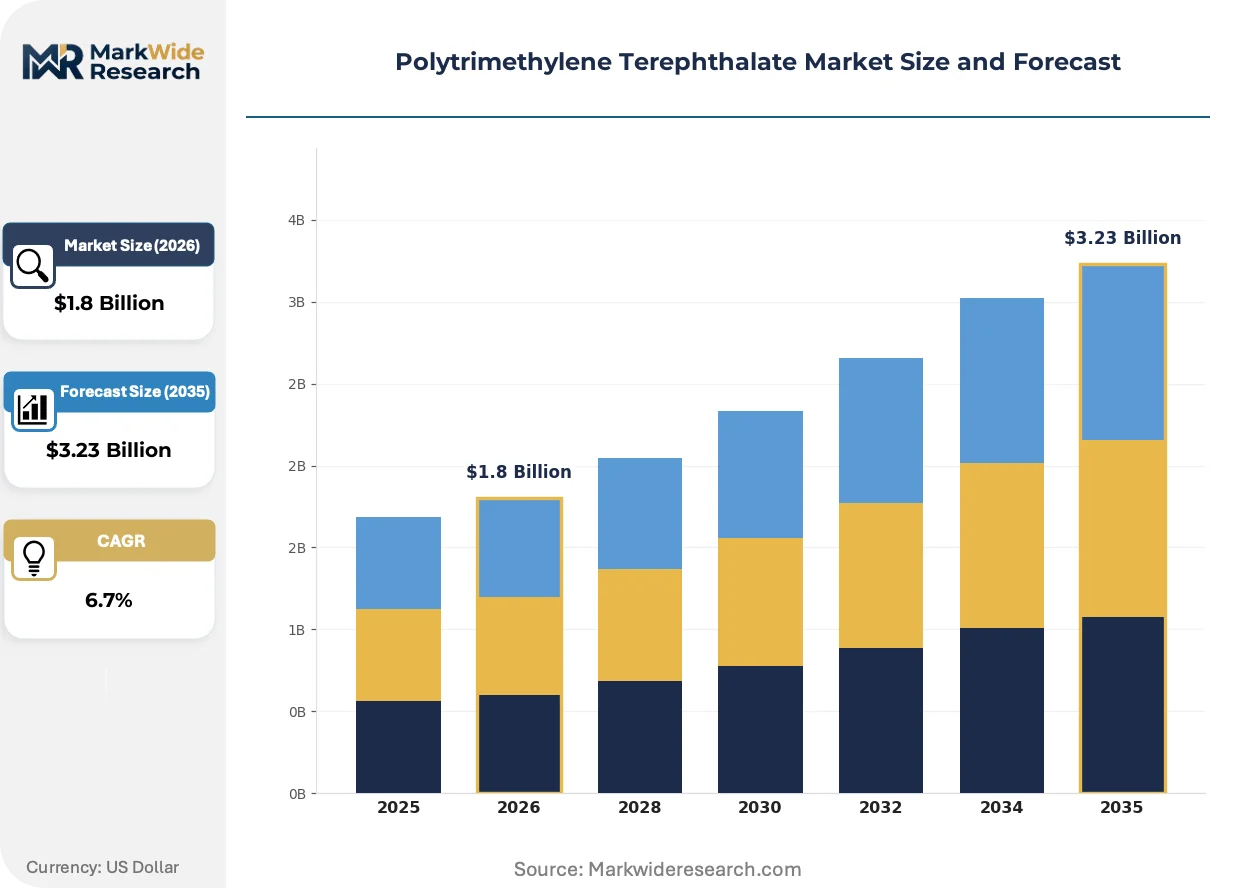
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filament, Staple Fiber, Resin, Film End Use: Textiles, Automotive, Packaging, Consumer Goods Application: Clothing, Carpets, Upholstery, Bottles Technology: Conventional, Bio-based, Recycled, Blending |
| Companies Covered | TORAY INDUSTRIES, INC, Asahi Kasei Corporation, DuPont, GLORY, RTP Company, Shenghong Group, Teijin Limited, Teijin Frontier, Huvis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polytrimethylene Terephthalate Market Strategic Shifts
Bio-based fermentation routes and advanced polymerization control systems are compressing the cost gap between petroleum-derived and renewable PTT, while regulatory carbon accounting is rewriting procurement specifications across automotive and apparel value chains.
Continuous bio-PDO production from glycerol fermentation is rendering obsolete batch-mode propylene oxide conversion economics. German automotive seating suppliers have shifted specification requirements to mass-balance certified resin within 24-month contract windows. This technology transition is compressing margins for conventional petroleum-based compounders locked into legacy dimethyl terephthalate supply agreements.
REACH registration dossier completeness requirements now mandate full supply chain disclosure for terephthalic acid precursors. European compounders face downstream liability exposure from Asian resin imports lacking ECHA-compliant substance characterization. Automotive interior grade certifications are migrating toward ISO 14064-aligned carbon footprint declarations that disqualify uncertified imports.
Automotive OEMs now require tier-one compounders to maintain dual-qualified bio-based and conventional resin streams to hedge against feedstock disruption. This specification redundancy is fragmenting procurement volumes and extending compounder inventory cycles. The practice is most pronounced in German and Japanese automotive supply chains where just-in-time delivery obligations conflict with certification lead times.
Polytrimethylene Terephthalate Market Segmentation
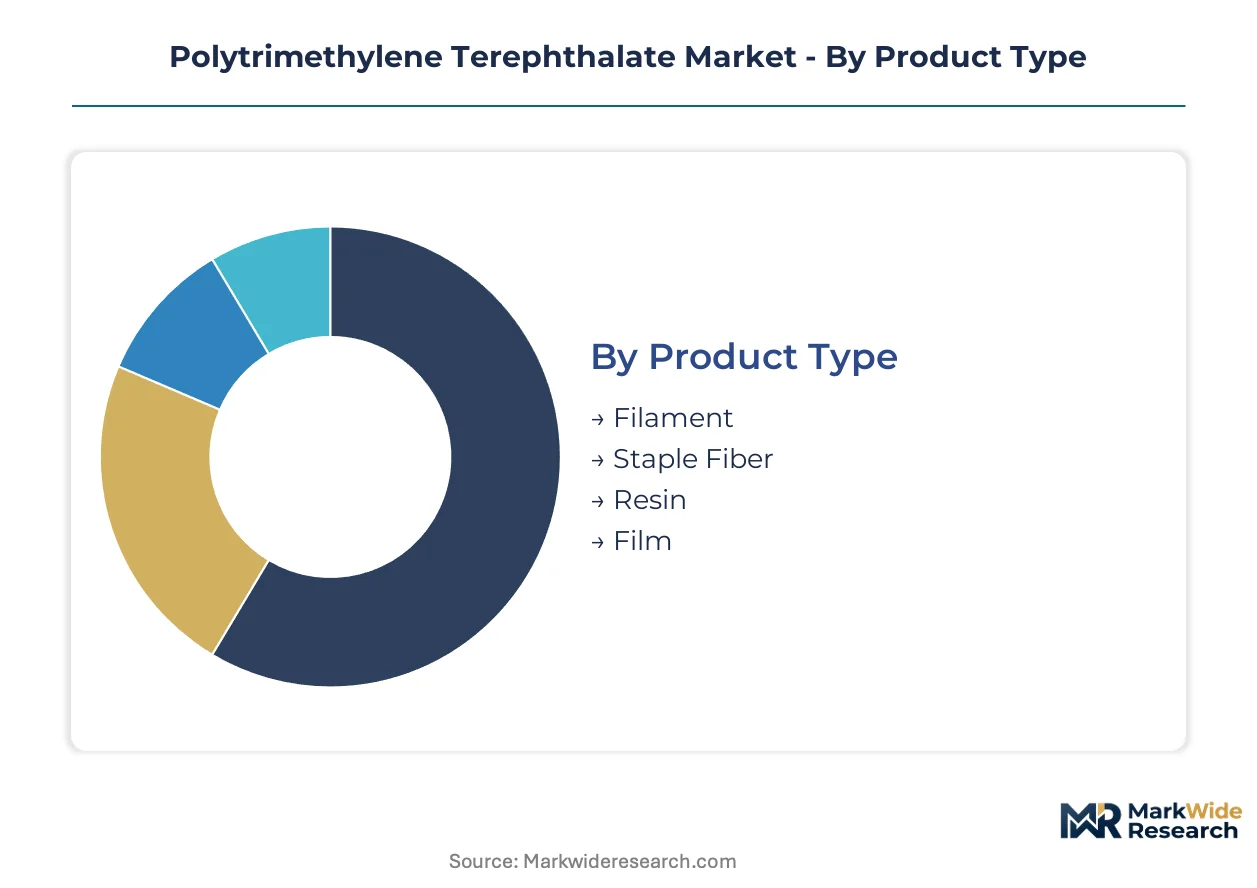
PTT market segmentation reveals how material properties align with distinct performance premiums across fiber, resin, and film formats. Each product category carries unique certification burdens and feedstock qualification requirements that reshape supplier economics.
Product Type:
Cost tier separation across filament, staple, resin, and film reflects divergent margin pools and capital intensity requirements in downstream processing.
- Filament:Continuous fiber extrusions with denier control precision serve high-tenacity industrial yarn and premium textile applications. Demand concentrates in Chinese integrated spinning operations where Shenghong Group captures logistics efficiencies from captive dimethyl terephthalate supply.
- Resin:Pelletized polymer formulations for injection molding and extrusion compounding command qualification premiums in automotive interior specifications. European compounders face REACH registration friction that filters non-compliant Asian imports from specification pools.
- Staple Fiber:Short-cut fiber for blended spinning with cotton and wool displaces PET in resilience-critical carpet pile applications.
- Film:Biaxially oriented and cast film grades for thermoformed packaging remain constrained by FDA food-contact approval timelines in United States markets.
Resin commands the established base. The steepest expansion runs through filament as Chinese integrated capacity consolidates.
End Use:
Application maturity varies sharply across textiles, automotive, packaging, and consumer goods, with regulatory thresholds determining market access rather than pure performance metrics.
- Automotive:Interior upholstery and seating fabric specifications now enforce EU Green Deal bio-content mandates that redirect procurement toward certified bio-PDO supply streams. German OEMs require 18-24 month validation protocols that freeze formulation changes.
- Textiles:Stretch apparel and performance sportswear exploit PTT's superior elastic recovery versus PET. Japanese METI circularity targets are accelerating Teijin and TORAY investment in fermentation-derived capacity to serve brand owner carbon accounting requirements.
- Packaging:Bottle and thermoformed tray applications await broader FDA food-contact approvals to unlock substitution against crystallized PET in refrigerated ready-meal segments.
- Consumer Goods:Household textiles and non-woven applications compete on dyeability and hand-feel characteristics where PTT softness premiums justify material cost deltas.
Textiles anchors volume concentration. Automotive generates the fastest margin expansion as bio-certification premiums compound.
Application:
Functional performance requirements across clothing, carpets, upholstery, and bottles create distinct specification tiers with diverging qualification barriers.
- Carpets:Commercial flooring installations exploit crush resistance and elastic recovery specifications that determine warranty terms against PET alternatives. Demand clusters in North American contract flooring where resilience testing protocols favor PTT pile construction.
- Upholstery:Automotive and residential seating applications require flame retardancy and abrasion resistance certifications that extend compounder development cycles.
- Clothing:Stretch woven and knit apparel leverages PTT's dye uptake efficiency and wrinkle recovery in premium casual wear segments.
- Bottles:Blow-molded container applications remain nascent pending broader regulatory clearance for food-contact migration limits.
Carpets command the established base. Upholstery climbs the fastest as automotive bio-content mandates tighten.
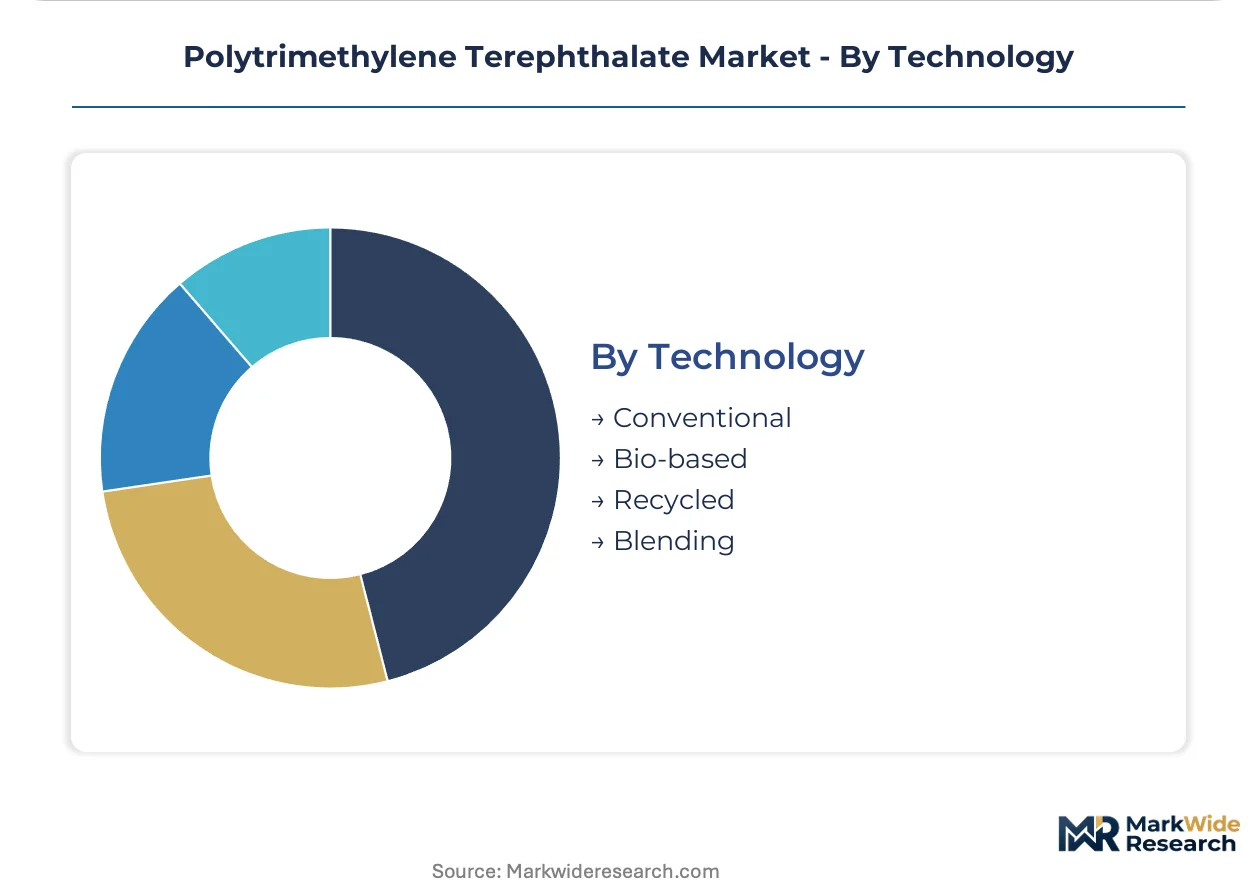
Technology:
Feedstock origin and process architecture now determine supplier qualification status more than unit production economics alone.
- Bio-based:Fermentation-derived 1,3-propanediol from glycerol feedstocks satisfies mass-balance chain-of-custody requirements that German automotive seating suppliers enforce within 24-month contract windows. Asahi Kasei leverages this platform to serve European textile brands seeking reduced petrochemical content.
- Conventional:Petroleum-based propylene oxide routes face margin compression from olefins pricing volatility that compounders cannot pass through to fixed-price automotive contracts.
- Recycled:Post-industrial and post-consumer PTT reprocessing remains limited by collection infrastructure gaps and degradation sensitivity in re-polycondensation.
- Blending:PTT-PET and PTT-nylon alloy formulations optimize cost-performance balance in intermediate specification tiers.
Conventional technology anchors current volume. Bio-based capacity gains share fastest as carbon accounting rewrites procurement specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes PTT primarily as integrated filament for textile exports, while Germany and the United States prioritize bio-certified resin grades for automotive upholstery specifications. This consumption-mix differential reflects divergent regulatory pressures and end-use maturity across major economies.
China
Shenghong Group and domestic textile converters drive filament demand through captive dimethyl terephthalate-to-yarn integration. The country's dual carbon goals under MEE guidance are accelerating fermentation-derived PDO pilot projects in Jiangsu province. Yangtze River Delta clusters concentrate spinning capacity that serves export-oriented apparel supply chains.
Germany
Automotive seating suppliers enforce mass-balance chain-of-custody requirements within compressed contract windows. KBA oversight of interior material safety intersects with EU Green Deal embodied carbon thresholds that filter non-compliant resin imports. Bavaria-based compounders maintain dual-qualified feedstock streams to hedge against certification delays.
United States
Carpet fiber resilience specifications anchor commercial flooring demand, particularly in Georgia and North Carolina contract manufacturing hubs. FDA food-contact approval timelines constrain bottle and thermoformed tray expansion into refrigerated ready-meal segments. EPA industrial chemical oversight shapes terephthalic acid precursor disclosure obligations.
Japan
METI's national plastics circularity roadmap incorporates bio-based polymer content targets that redirect TORAY and Teijin investment priorities. Kanto region filament producers serve domestic stretch apparel brands with carbon accounting requirements. Osaka-Kobe industrial corridors concentrate fermentation-derived PDO technology development.
India
Technical textile expansion in automotive interiors creates first-mover positioning opportunities as BIS certification pathways remain underdeveloped. Maharashtra and Gujarat textile clusters are evaluating bio-based resin qualification for export-oriented upholstery supply chains. DGFT import monitoring affects Asian resin pricing dynamics in regional compounder procurement.
Polytrimethylene Terephthalate Market Competitive Environment
Capability concentration sits with integrated fiber producers commanding captive feedstock supply; scale advantage sits with diversified chemical conglomerates spreading polymerization capacity across multiple polyester chemistries. The market structures around three tiers: petrochemical majors with upstream terephthalic acid control, specialty compounders holding automotive grade certifications, and regional filament spinners consolidating downstream yarn operations. Dominant competitive moves include fermentation-derived PDO capacity licensing and strategic partnerships with mass-balance certification bodies to accelerate supplier qualification timelines.
Within the integrated chemical conglomerate tier, TORAY INDUSTRIES, INC and Teijin Limited occupy positions defined by downstream filament spinning integration and automotive upholstery partnerships respectively. Asahi Kasei Corporation exemplifies the bio-platform specialist archetype, leveraging fermentation-derived PDO supply to serve European textile brand requirements. These three Japanese entities anchor competitive positioning around feedstock origin certification and regional regulatory compliance capabilities.
| Leading Market Players |
|---|
| TORAY INDUSTRIES, INC |
| Asahi Kasei Corporation |
| DuPont |
| GLORY |
| RTP Company |
| Shenghong Group |
| Teijin Limited |
| Teijin Frontier |
| Huvis |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta freight corridors impose cost differentials that amplify supply concentration effects, enabling Chinese integrated filament producers to undercut European compounders on delivered resin prices while bio-certification premiums widen spreads between petroleum-based and fermentation-derived grades.
Pricing Analysis
Long-term offtake contracts dominate automotive upholstery procurement, locking compounders into fixed-price resin supply while spot market exposure concentrates in textile filament trading. Three-tier pricing structure separates REACH-certified automotive grades from standard industrial resin and uncertified commodity streams. Pricing pressure stems from propylene oxide feedstock volatility that compounders cannot pass through to OEM contracts. Tier-one automotive suppliers exhibit lowest price sensitivity due to validation protocol lock-in, while Asian textile converters face acute margin compression from freight cost swings.
Supply Chain Analysis
Extended payment terms from German automotive seating suppliers strain working capital for compounders lacking supply-chain finance facilities, compressing cash conversion cycles for mid-tier resin distributors. PDO feedstock production concentrates in China, the United States, and Germany, with terephthalic acid precursors drawing from integrated petrochemical complexes in each market. Raw material dependencies center on propylene oxide, glycerol fermentation feedstocks, and dimethyl terephthalate intermediates. Single-source vulnerability runs through mass-balance certification bodies concentrated in Western Europe. Distribution runs through captive filament spinning operations in China and compounder networks serving automotive tier-one suppliers in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment around REACH registration and automotive grade certification creates structural barriers that compounder incumbents exploit to capture margin premiums.
For Market Incumbents: Build certification moats by accelerating dual-qualified bio-based and conventional resin streams to hedge against PDO supply disruption, while extending backward integration into captive dimethyl terephthalate production to neutralize propylene oxide price volatility threatening fixed-price automotive contracts. For New Entrants and Emerging Players: India technical textile expansion represents the most penetrable entry point, where underdeveloped BIS certification pathways for automotive interior materials allow bio-based resin specialists to establish qualification precedents before incumbent compounders consolidate positioning, leveraging mass-balance auditor partnerships as the primary go-to-market wedge. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking to divest non-core polyester polymerization assets, with fermentation-derived PDO technology platforms offering the strongest long-term viability through the projection horizon as carbon accounting rewrites procurement specifications; monitor EU Green Deal bio-content mandate enforcement timelines as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation-Derived PDO Capacity Expansion | Teijin and TORAY investments align with METI circularity targets and German OEM mass-balance requirements. |
| Mass-Balance Certification Partnership | Strategic alliances with ISCC or RSB auditors compress Asian supplier qualification timelines for European market access. |
| Automotive Grade Validation Protocol Investment | Eighteen-month OEM approval cycles lock compounders into incumbent feedstock relationships and freeze formulation changes. |
| Captive Dimethyl Terephthalate Integration | Shenghong Group's Yangtze River Delta complex captures logistics efficiencies that regional spinners cannot replicate. |
| India BIS Certification First-Mover Positioning | Early qualification for technical textile applications in Maharashtra clusters establishes precedents before incumbent entry. |
Study Parameters
The analysis maps filament, resin, staple fiber, and film sub-sectors, each validated through primary interviews with polymer plant managers, automotive tier-one procurement leads, textile technical directors, and mass-balance certification auditors, combined with secondary triangulation across REACH registration dossiers, ECHA substance characterization databases, customs trade flows, and SEC filings from integrated chemical conglomerates, employing bottom-up capacity modeling and top-down demand segmentation reconciliation.
Assumption-sets held PDO feedstock cost trajectories and EU Green Deal enforcement timelines fixed across the modeling period while varying propylene oxide price volatility scenarios and China integrated capacity expansion rates. Segmentation dimensions modeled include product type, end-use industry, application function, technology route, and regional production hub. CAGRs derive from weighted average growth rates across segment-level demand drivers and supply-side capacity additions, with automotive bio-content mandate compliance curves and carpet fiber resilience specification adoption serving as primary industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in olefins pricing, freight rate indices, or euro-yuan exchange rate volatility would shift the trajectory. Forecasts reflect documented assumptions around regulatory enforcement intensity and fermentation technology cost curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Thermoplastic Edge Bands Market
Polymers & Resins
Global Alkyd Resin Market
Polymers & Resins
Polyelectrolyte Market
Polymers & Resins
Global Water-Based Resins Market
Polymers & Resins
Polyethylene Wax Market
Polymers & Resins
Epoxy Resin Market
Polymers & Resins
Polyether Ketone (PEK) Market
Polymers & Resins
EVA Copolymer Market
Polymers & Resins
Polyamide 11 & 12 Market
Polymers & Resins
Polychlorotrifluoroethylene (PCTFE) Market
Polymers & Resins
Vinyl Acetate Ethylene Copolymer Powder Market
Polymers & Resins
Middle East Polycarbonate (PC) Market
Polymers & Resins
Starch Polymer Market
Polymers & Resins
Bio-Based and Synthetic Polyamide Market
Polymers & Resins
Polyolefin Foam Market
Polymers & Resins
Bio-Based Polypropylene Market