
 Japan Satellite Connectivity Market | 2026-2036
Japan Satellite Connectivity Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Satellite Connectivity Market Insights
Multi-sourcing of satellite capacity is realigning procurement patterns across Japanese maritime and aviation operators. SKY Perfect JSAT Corporation anchors domestic geostationary coverage through its orbital slot holdings. Mitsubishi Electric leverages integrated satellite manufacturing capabilities to compete on government and defense contracts. NEC Space Technologies Ltd specializes in advanced antenna systems for mobility applications.
Japan satellite connectivity encompasses space-based communication infrastructure delivering broadband, broadcast, and IoT services through radio frequency links operating across C-band, Ku-band, and Ka-band spectra with orbital altitudes ranging from 600 kilometers to 35,786 kilometers. This infrastructure serves remote regions, mobile platforms, and critical services where terrestrial networks prove unavailable or unreliable. Low Earth Orbit technology is displacing legacy geostationary architectures in latency-sensitive applications including telemedicine and maritime IoT. Government end users channel procurement through JAXA-coordinated programs, concentrating margin pools in disaster management and surveillance verticals. IoT connectivity services are expanding fastest among rural utilities and fisheries monitoring networks.
METI spectrum allocation policies and the Radio Law administered by Japan's Ministry of Internal Affairs and Communications govern orbital slot coordination, terminal certification, and interference management across domestic satellite operations. JIS standards for satellite ground equipment shape product compliance requirements and market access conditions for foreign equipment suppliers. Stakeholders must monitor evolving frequency band reassignments and emerging spectrum sharing frameworks between LEO constellations and incumbent geostationary operators.
Market Dynamics
Low Earth Orbit constellation deployment is fragmenting procurement power across Japanese maritime and aviation operators, compressing legacy geostationary contract durations while concentrating terminal manufacturing demand in the Tokyo-Osaka industrial corridor.
Growth Catalysts
- Radio Law Revisions:Japan's Ministry of Internal Affairs and Communications streamlined terminal certification timelines for maritime applications, accelerating fleet retrofit programs among coastal shipping operators.
- Telemedicine Infrastructure:Latency-sensitive rural health networks are adopting LEO-based backhaul to bypass fiber deployment gaps in mountainous prefectures.
- Fisheries Monitoring Mandates:METI's vessel tracking requirements for distant-water fleets are expanding addressable terminal demand across Hokkaido and Kyushu home ports.
Market Restraints
- Orbital Slot Scarcity:Geostationary arc congestion above the Asia-Pacific region limits domestic operator expansion, forcing reliance on hosted payloads and foreign satellite capacity leases.
- Domestic Launch Cost Structure:JAXA's H3 rocket program pricing remains above commercial alternatives, constraining sovereign constellation deployment timelines.
- Spectrum Reallocation Friction:C-band clearing obligations under ITU coordination deadlines compress incumbent operator revenue streams while raising retooling costs for ground segment suppliers.
Strategic Opportunities
- Hokkaido Agriculture Networks:Precision farming IoT deployments in northern Japan remain underserved by terrestrial cellular, creating whitespace for satellite-based soil and equipment monitoring.
- Defense Procurement Reform:Japan's National Security Strategy expansion is opening classified communication satellite contracts to domestic manufacturing consortia previously excluded from military programs.
- LEO-GEO Hybrid Architectures:Maritime operators are piloting multi-orbit terminals that blend Starlink low-latency links with JSAT broadcast services for integrated bridge communications.
Industry Challenges
- RF Engineer Shortage:Domestic universities produce insufficient microwave and antenna specialists to staff ground equipment manufacturing and satellite operations centers.
- Terminal Certification Backlogs:MIC's Radio Law compliance testing queues extend deployment timelines for new mobility antenna designs, particularly for Ka-band phased arrays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Satellite Connectivity Market |
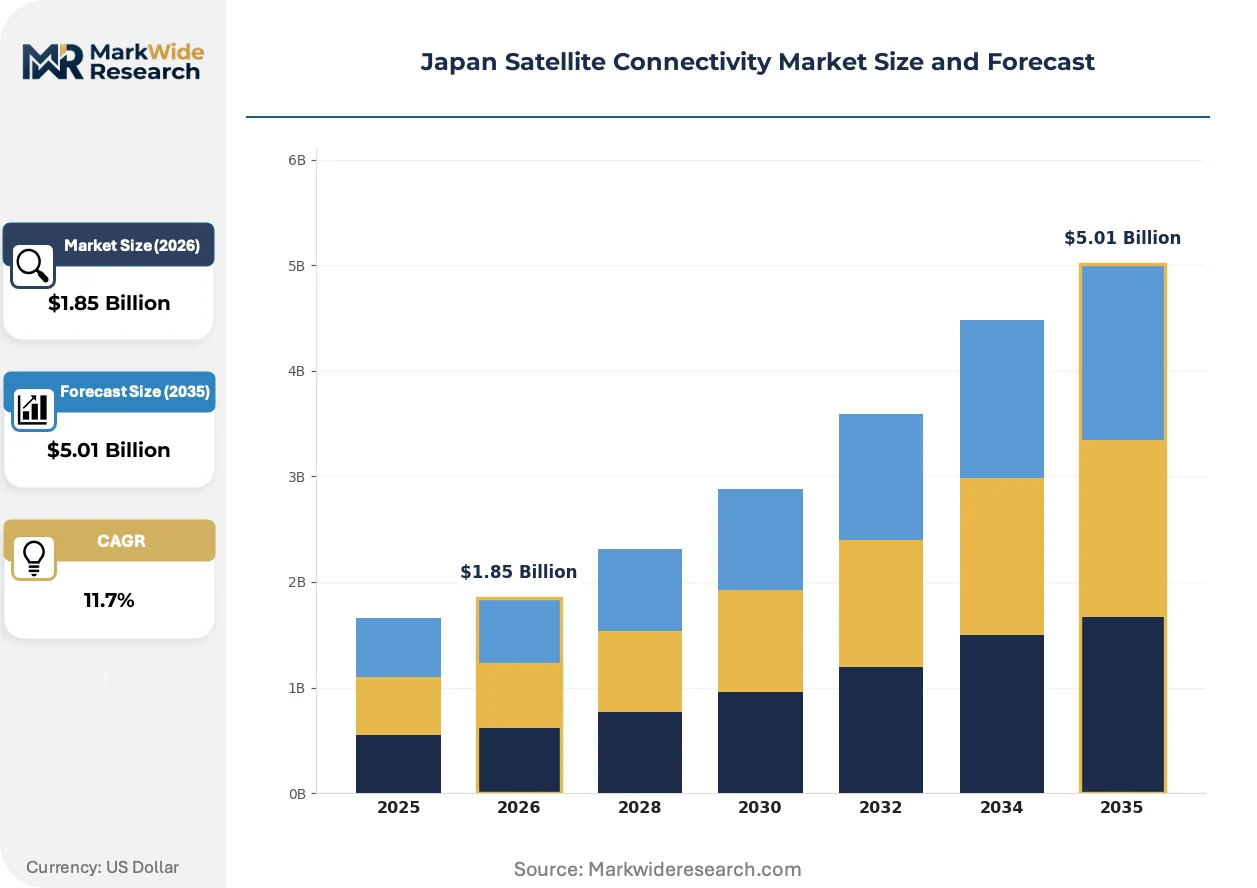
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.01 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | End User: Government, Telecommunications, Aviation, Maritime Service Type: Broadband, Emergency Communications, TV Broadcasting, IoT Connectivity Technology: Geostationary, Low Earth Orbit, Medium Earth Orbit, Hybrid Systems Application: Remote Sensing, Disaster Management, Surveillance, Telemedicine |
| Companies Covered | Axelspace Corporation, New Japan Radio Co., Ltd., SKY Perfect JSAT Corporation, KYOCERA Corporation, Broadcasting Satellite System Corporation, Mitsubishi Electric, Furuno Electric Co., Ltd., Infostellar Inc., NEC Space Technologies Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Satellite Connectivity Market Trends and Innovations
Orbital architecture diversification is compressing the traditional geostationary monopoly while fragmenting buyer power across Japanese connectivity markets.
Phased array flat-panel terminals are electrifying vessel-mounted connectivity by eliminating mechanical steering components. Coastal ferry operators and offshore energy support fleets are retrofitting bridge systems at accelerated replacement cycles. This electrification is compressing maintenance intervals and enabling continuous connectivity during high-motion maritime operations.
METI's spectrum efficiency mandates under the Radio Law are forcing equipment manufacturers toward higher-order modulation schemes and interference-resistant waveforms. Domestic ground segment suppliers must recertify product lines under revised JIS standards for electromagnetic compatibility. Ka-band terminal categories face the steepest redesign timelines as inspectors prioritize millimeter-wave coexistence testing.
Japanese maritime buyers are unbundling satellite capacity from integrated service contracts, separating bandwidth procurement from terminal management and network operations. Fleet operators now source capacity through spot-market mechanisms while retaining antenna assets in-house. This unbundling is most pronounced among Tokyo-headquartered container lines with multi-thousand vessel fleets.
Japan Satellite Connectivity Market Segmentation
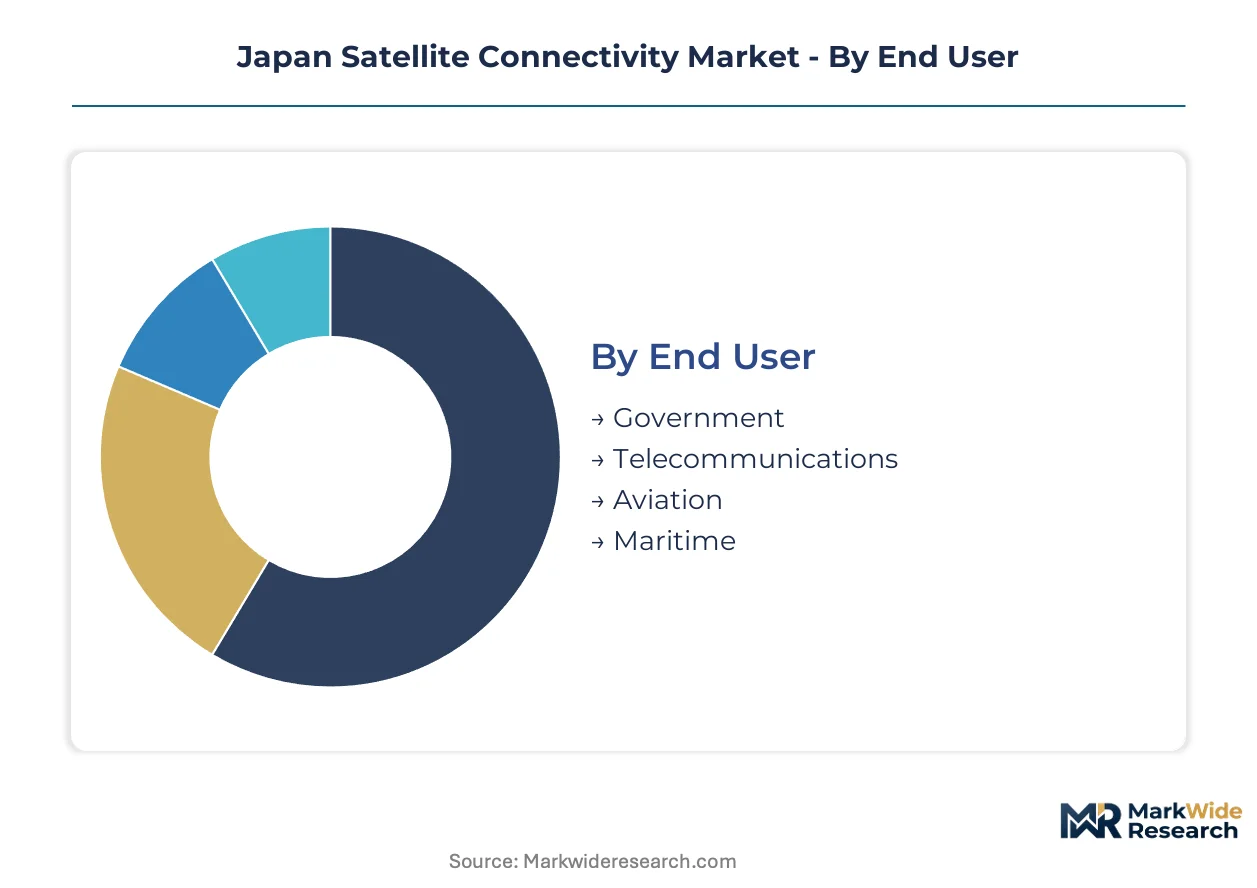
Orbital diversity and regulatory fragmentation across Japan's satellite connectivity market create distinct procurement patterns. End users, service architectures, orbital technologies, and mission applications each concentrate margin pools in different supplier ecosystems and geographic clusters.
End User:
Defense and critical infrastructure procurement concentrates contract value among domestic manufacturing consortia with JAXA coordination credentials.
- Government:JAXA-coordinated programs channel sovereign capacity through disaster management and surveillance verticals. Procurement concentrates margin pools in classified communication satellite contracts opened under Japan's National Security Strategy expansion.
- Telecommunications:Tokyo and Osaka corridor providers drive LEO adoption for latency-sensitive backhaul. Regional carriers in mountainous prefectures bypass fiber gaps through satellite-based infrastructure.
- Aviation:In-flight connectivity procurement fragments across domestic and foreign capacity leases. Fleet retrofit programs accelerate under streamlined MIC terminal certification timelines.
- Maritime:Coastal shipping operators and distant-water fleets expand vessel tracking mandates. Hokkaido and Kyushu home ports generate concentrated terminal demand under METI fisheries monitoring requirements.
Government absorbs the bulk of installed capacity; Telecommunications is expanding most quickly.
Service Type:
Application-specific latency requirements and spectrum allocation policies fragment pricing power across service architectures.
- Broadband:Ka-band and Ku-band capacity serves rural utilities and precision farming networks in Hokkaido. Telemedicine infrastructure in mountainous prefectures drives LEO-based backhaul procurement.
- Emergency Communications:Disaster resilience mandates under METI coordination require interoperable ground segment assets. Prefecture-level emergency operations centers maintain sovereign satellite capacity reserves.
- TV Broadcasting:SKY Perfect JSAT orbital slot holdings anchor domestic geostationary coverage. Broadcast service contracts retain longer durations than maritime or aviation capacity agreements.
- IoT Connectivity:Soil monitoring and equipment tracking in northern Japan agriculture networks remain underserved by terrestrial cellular. Fisheries monitoring mandates expand addressable terminal demand across coastal prefectures.
Broadband retains the largest revenue base; IoT Connectivity is climbing the fastest.
Technology:
Orbital altitude tradeoffs between latency, coverage footprint, and terminal complexity reshape equipment procurement patterns.
- Geostationary:Traditional 35,786 kilometer altitude architecture delivers broadcast and broadband through fixed satellite service terminals. Asia-Pacific orbital arc congestion limits domestic operator expansion and forces hosted payload reliance.
- Low Earth Orbit:Sub-600 kilometer constellations displace legacy architectures in telemedicine and maritime IoT applications. Phased array flat-panel terminals eliminate mechanical steering for high-motion maritime operations.
- Medium Earth Orbit:Intermediate altitude systems balance coverage and latency for specialized government applications. Limited domestic operator investment constrains deployment scale.
- Hybrid Systems:Multi-orbit terminals blend Starlink low-latency links with JSAT broadcast services for integrated bridge communications. Maritime operators pilot these architectures for redundancy-critical operations.
Geostationary retains dominant installed base; Low Earth Orbit is gaining share fastest.
Application:
Mission-critical performance requirements and procurement channel structures concentrate supplier relationships in distinct verticals.
- Remote Sensing:Earth observation data products serve agriculture and maritime domain awareness programs. JAXA satellite coordination supports domestic payload integration.
- Disaster Management:Prefecture-level emergency response networks require resilient backup communications independent of terrestrial infrastructure. METI spectrum policies prioritize interference-resistant waveforms for these deployments.
- Surveillance:National Security Strategy expansion opens classified satellite contracts to previously excluded manufacturing consortia. Defense procurement reform channels sovereign capacity through domestic supply chains.
- Telemedicine:Rural health networks in mountainous prefectures adopt LEO-based backhaul to bypass fiber deployment gaps. Latency-sensitive applications drive orbital architecture displacement.
Disaster Management absorbs the bulk of government procurement; Telemedicine is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for satellite connectivity concentrates in Japan's coastal industrial corridors and northern agricultural prefectures where terrestrial infrastructure remains sparse. Procurement patterns diverge sharply between metropolitan telecommunications clusters and remote maritime operations.
Kanto/Tokyo
Telecommunications providers in the Tokyo corridor drive LEO adoption for latency-sensitive backhaul services. METI spectrum allocation policies under the Radio Law shape terminal certification requirements for regional carriers. The Yokohama-Tokyo industrial belt hosts concentrated ground equipment manufacturing and satellite operations centers serving domestic constellation deployments.
Kansai/Osaka
Maritime operators headquartered in Osaka unbundle satellite capacity procurement from integrated service contracts. Japan's Ministry of Internal Affairs and Communications streamlined terminal certification timelines, accelerating fleet retrofit programs among Kansai-based container lines. The Osaka-Kobe port cluster generates sustained demand for vessel-mounted phased array terminals and bridge communication systems.
Kyushu
Distant-water fishing fleets operating from Kyushu home ports expand vessel tracking mandates under METI fisheries monitoring requirements. The prefecture's maritime terminals support IoT connectivity for equipment monitoring and catch reporting. Fukuoka serves as a distribution hub for satellite ground equipment serving southern Japan maritime operations.
Hokkaido
Precision farming networks in northern Japan remain underserved by terrestrial cellular, creating demand for satellite-based soil and equipment monitoring. Rural utilities deploy IoT connectivity services across agricultural cooperatives and remote infrastructure. Sapporo-based operators pilot hybrid LEO-GEO architectures for redundancy-critical operations in harsh climate conditions.
Chubu/Nagoya
Defense procurement reform channels sovereign satellite capacity through domestic manufacturing consortia with JAXA coordination credentials. The Nagoya industrial corridor concentrates satellite component manufacturing and antenna system production. Mitsubishi Electric leverages integrated manufacturing capabilities to compete on government and defense contracts requiring classified communication infrastructure.
Japan Satellite Connectivity Market Competitive Landscape
Strategic partnerships dominate the current landscape as operators seek multi-orbit capabilities and integrated service offerings. The vendor base organizes around three tiers: established geostationary operators with orbital slot holdings, LEO constellation service providers, and specialized ground equipment manufacturers. Two archetypes define competitive positioning — integrated satellite manufacturers with JAXA program credentials, and antenna specialists serving mobility applications. Portfolio diversification and technology licensing represent the primary competitive vectors as firms seek to bridge legacy GEO and emerging LEO architectures.
Among domestic integrated manufacturers, SKY Perfect JSAT Corporation and Mitsubishi Electric occupy positions anchored by orbital assets and government program access. NEC Space Technologies Ltd exemplifies the specialized antenna tier, concentrating on advanced systems for maritime and aviation mobility. These three firms represent distinct strategic postures within a market transitioning from geostationary monopoly toward multi-orbit competition. Their collective positioning illustrates how Japanese satellite connectivity procurement channels through domestic supply chains even as foreign LEO operators capture latency-sensitive segments.
| Leading Market Players |
|---|
| Axelspace Corporation |
| New Japan Radio Co., Ltd. |
| SKY Perfect JSAT Corporation |
| KYOCERA Corporation |
| Broadcasting Satellite System Corporation |
| Mitsubishi Electric |
| Furuno Electric Co., Ltd. |
| Infostellar Inc. |
| NEC Space Technologies Ltd |
| Others |
Pricing and Supply Chain Analysis
Captive integration into satellite manufacturing and ground equipment production anchors pricing power for domestic Japanese suppliers while insulating them from foreign component volatility. This vertical control over antenna systems and orbital slot holdings allows SKY Perfect JSAT and Mitsubishi Electric to command premium positioning in government and defense procurement channels.
Pricing Analysis
Service bundling with terminal management packages dominates maritime contracts, though Tokyo-headquartered container lines increasingly unbundle capacity procurement to access spot-market mechanisms. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade under MIC Radio Law compliance and volume scale across fleet retrofit programs. Cost compression in Ka-band phased array categories is intensifying because METI spectrum efficiency mandates force equipment redesign cycles. Regional telecommunications carriers in mountainous prefectures exhibit highest price sensitivity, while defense procurement channels show lowest sensitivity due to classified communication requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Kansai-based maritime operators, while specialized distributors serve precision farming networks across Hokkaido agricultural cooperatives. Component manufacturing concentrates in Japan, South Korea, and Taiwan for microwave subsystems and semiconductor content. Gallium nitride power amplifiers, high-frequency printed circuit boards, and precision antenna feed networks constitute critical input dependencies. Single-source vulnerability in phased array chipsets creates exposure to foundry capacity constraints. Distribution runs through JAXA-coordinated program channels for government end users and independent service provider networks for commercial maritime buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as multi-orbit competition and terminal certification backlogs force subscale ground equipment manufacturers toward exit or acquisition. Orbital slot scarcity above the Asia-Pacific region accelerates margin pressure on pure-play geostationary operators lacking LEO partnerships.
For Market Incumbents: Cement multi-orbit service capabilities through technology licensing agreements with LEO constellation operators before foreign providers capture latency-sensitive segments. Deepen backward integration into phased array chipset supply by securing foundry partnerships in Taiwan and South Korea. The RF engineer shortage threatens ground equipment manufacturing timelines; address this through university pipeline investments and specialist recruitment from defense contractor networks. For New Entrants and Emerging Players: Flat-panel terminal electrification for high-motion maritime operations offers a technology-first wedge into the Kansai container line retrofit market. Hokkaido precision farming networks remain underserved by terrestrial cellular infrastructure, presenting penetrable whitespace for IoT connectivity specialists. Target agricultural cooperative procurement channels with outcome-based soil monitoring service bundles rather than pure equipment sales. For Investors and Strategic Acquirers: Exit pathways concentrate in domestic manufacturing consortia with JAXA coordination credentials and classified communication satellite contract access. Long-term viability hinges on positioning within defense procurement reform channels and LEO-GEO hybrid architecture deployment timelines. Watch MIC terminal certification queue lengths as an inflection indicator for ground equipment manufacturer revenue recognition delays.| Strategic Initiative | Industry Significance |
|---|---|
| LEO-GEO Hybrid Architecture Deployment | Maritime operators blend Starlink low-latency links with JSAT broadcast services for integrated bridge communications. |
| Phased Array Terminal Electrification | Coastal ferry operators eliminate mechanical steering components through flat-panel antenna retrofits. |
| Defense Procurement Reform Participation | Domestic consortia gain access to classified communication satellite contracts previously restricted to military programs. |
| Precision Farming IoT Network Expansion | Hokkaido agricultural cooperatives deploy satellite-based soil monitoring where terrestrial cellular remains unavailable. |
| Spectrum Efficiency Recertification | Ground equipment manufacturers redesign Ka-band product lines under revised JIS electromagnetic compatibility standards. |
Research Methodology
Independent corroboration across satellite operator procurement officers, ground equipment manufacturing executives, and maritime fleet technology managers underwrites the qualitative findings. Primary interviews with JAXA program coordinators, MIC Radio Law compliance inspectors, and METI spectrum policy officials combined with secondary validation from MIC regulatory filings, JAXA mission documentation, and ITU coordination records. Bottom-up terminal demand modeling across Hokkaido and Kyushu home ports triangulates against top-down capacity lease value estimates from Tokyo and Osaka corridor telecommunications providers.
Comparable-period anchoring to historical fleet retrofit cycles and sovereign constellation deployment timelines structures the projection framework across the analysis window. Segmentation dimensions modeled include orbital altitude tier, end-user procurement channel, service architecture type, and prefecture-level infrastructure maturity. CAGRs derive from installed base replacement rates and new addressable terminal penetration curves. Forecast inputs incorporate MIC certification timeline distributions and METI fisheries monitoring mandate compliance deadlines.
Several conditions sit outside the modeled scope, including unannounced LEO constellation launch failures, sudden Radio Law revisions affecting Ka-band terminal categories, and geopolitical disruptions to Taiwan-foundry supply chains. Forecasts reflect assumptions regarding JAXA H3 rocket program pricing convergence with commercial alternatives. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
LEO Satellite Constellation Market
Satellite
North America Satellite Attitude and Orbit Control System Market
Satellite
Satellite Operation Service Market
Satellite
Nanosatellite Market
Satellite
Latin America Satellite Connectivity Market
Satellite
Satellite Compass Market
Satellite
South Korea Satellite Connectivity Market
Satellite
Asia-Pacific Satellite Bus Market
Satellite
Flat Panel Satellite Antenna Market
Satellite
Global Commercial Satellite Broadband Market
Satellite
VSAT Maritime Satellite Communication Market
Satellite
Fixed Satellite Services (FSS) Market
Satellite
UK Satellite Imagery Services Market
Satellite
Israel Satellite-Based Earth Observation Market
Satellite
Tactical Satellite Market
Satellite
France Satellite-Based Earth Observation Market