
 Germany Demand Response Management Systems Market | 2026-2036
Germany Demand Response Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Demand Response Management Systems Market Foresight
German grid-scale battery and virtual power plant operators is restructuring procurement patterns for demand response software as renewable intermittency strains transmission networks. Siemens AG leverages its domestic manufacturing base to anchor utility relationships across Bundesnetzagentur-regulated zones. Schneider Electric differentiates through cloud-native distributed energy resource management platforms that compete with legacy SCADA architectures. ABB Ltd sustains technology leadership in machine learning algorithms for load forecasting across industrial substations.
Demand Response Management Systems comprise software platforms that aggregate, dispatch, and monetize flexible electricity loads through automated signals to end-use equipment, typically operating with response latencies under four seconds for frequency regulation services. These systems integrate advanced metering infrastructure with IoT sensors and cloud computing layers to enable real-time pricing signals that shave peak demand for electric utilities. Automated Load Control dominates solution offerings as the most mature revenue pool, while Distributed Energy Resource Management captures the fastest expansion as prosumer solar and battery assets proliferate. Machine Learning Algorithms within the technology dimension concentrate margin pools where predictive accuracy directly determines settlement values in ancillary services markets.
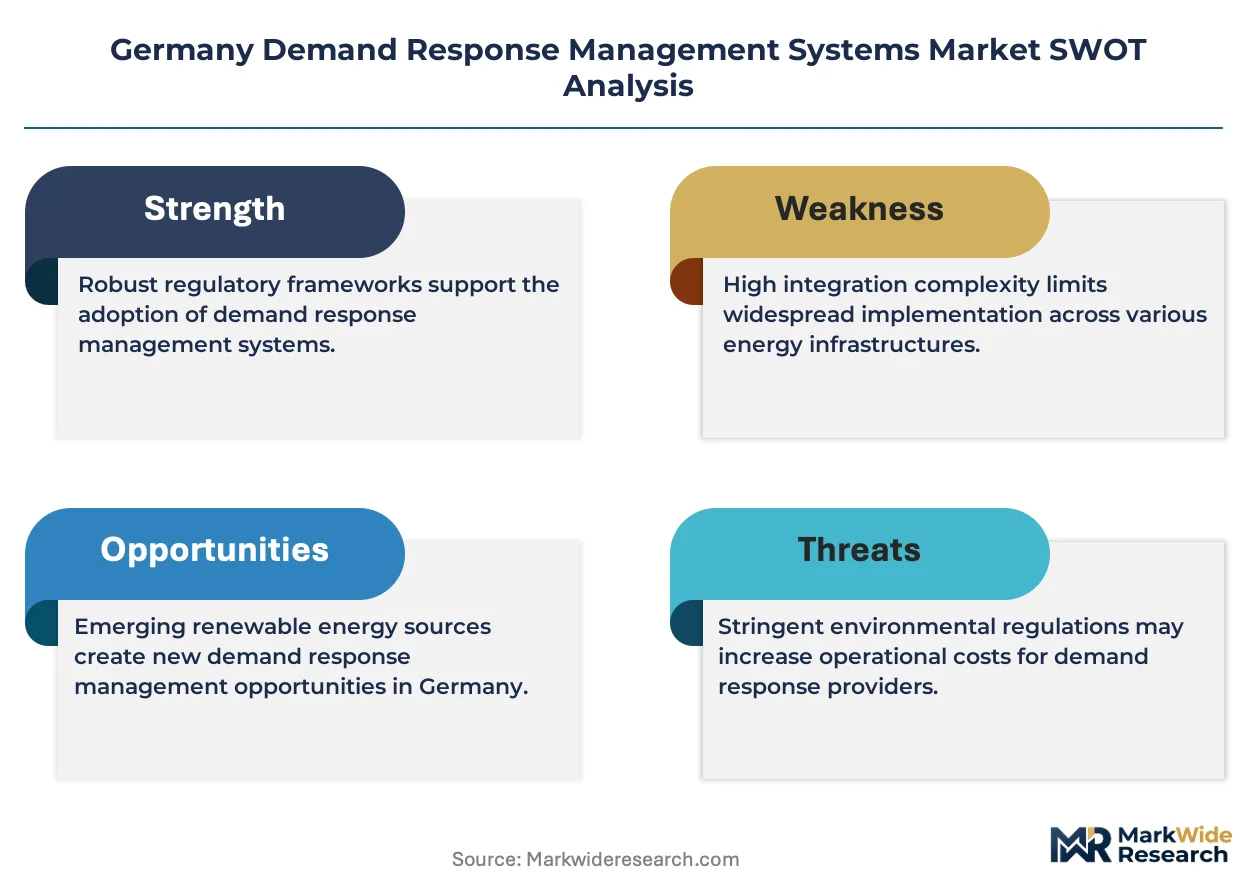
The Bundesnetzagentur enforces grid codes under the Energiewirtschaftsgesetz that mandate demand-side flexibility participation, while EU Green Deal carbon pricing mechanisms reshape commercial facility investment timelines. CE marking requirements under EU cybersecurity frameworks constrain market access for non-compliant platform vendors. Stakeholders must monitor how Germany's implementation of the EU Electricity Market Design reform recalibrates compensation structures for peak load shaving versus voltage regulation services.
Market Dynamics
German transmission system operators face mounting pressure from renewable intermittency, forcing accelerated procurement of automated load control platforms that can dispatch industrial demand within four-second frequency regulation windows.
Growth Catalysts
- EnWG Grid Modernization Mandates:Germany's Energiewirtschaftsgesetz requires demand-side flexibility participation, compelling utilities to deploy automated response systems across Bundesnetzagentur-regulated zones.
- Industrial Data Center Clustering:Bavaria's automotive corridor hosts expanding hyperscale facilities that monetize flexible loads through ancillary services markets.
- EU Green Deal Carbon Pricing:Commercial facility investment timelines compress as carbon border adjustment mechanisms reshape operational cost structures.
Market Restraints
- CE Marking Compliance Burden:EU cybersecurity frameworks constrain platform vendor market access through certification timelines that extend eighteen to twenty-four months.
- Legacy SCADA Integration Friction:Brownfield industrial substations require costly retrofitting to interface with cloud-native distributed energy resource architectures.
- Silicon Supply Concentration:Advanced metering infrastructure chipsets depend on concentrated Asian foundry capacity, exposing procurement cycles to geopolitical disruption.
Strategic Opportunities
- Rhineland-Palatinate Prosumer Expansion:Residential solar-plus-storage penetration creates untapped aggregation potential for virtual power plant operators.
- EU Electricity Market Design Reform:Recalibrated compensation structures for voltage regulation services will favor machine learning-enabled predictive dispatch platforms.
- IoT Sensor Convergence:Edge computing layers combined with 5G industrial networks enable sub-second latency response previously unattainable through cellular backhaul.
Industry Challenges
- Machine Learning Talent Scarcity:Load forecasting algorithm development requires specialized data science competencies that compete with fintech and autonomous vehicle sectors.
- Multi-Vendor Interoperability:Proprietary communication protocols between OEM hardware and third-party software platforms create integration bottlenecks.
- Ancillary Services Settlement Complexity:Real-time pricing signal verification demands granular metering infrastructure that strains capex budgets for mid-sized commercial facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Demand Response Management Systems Market |
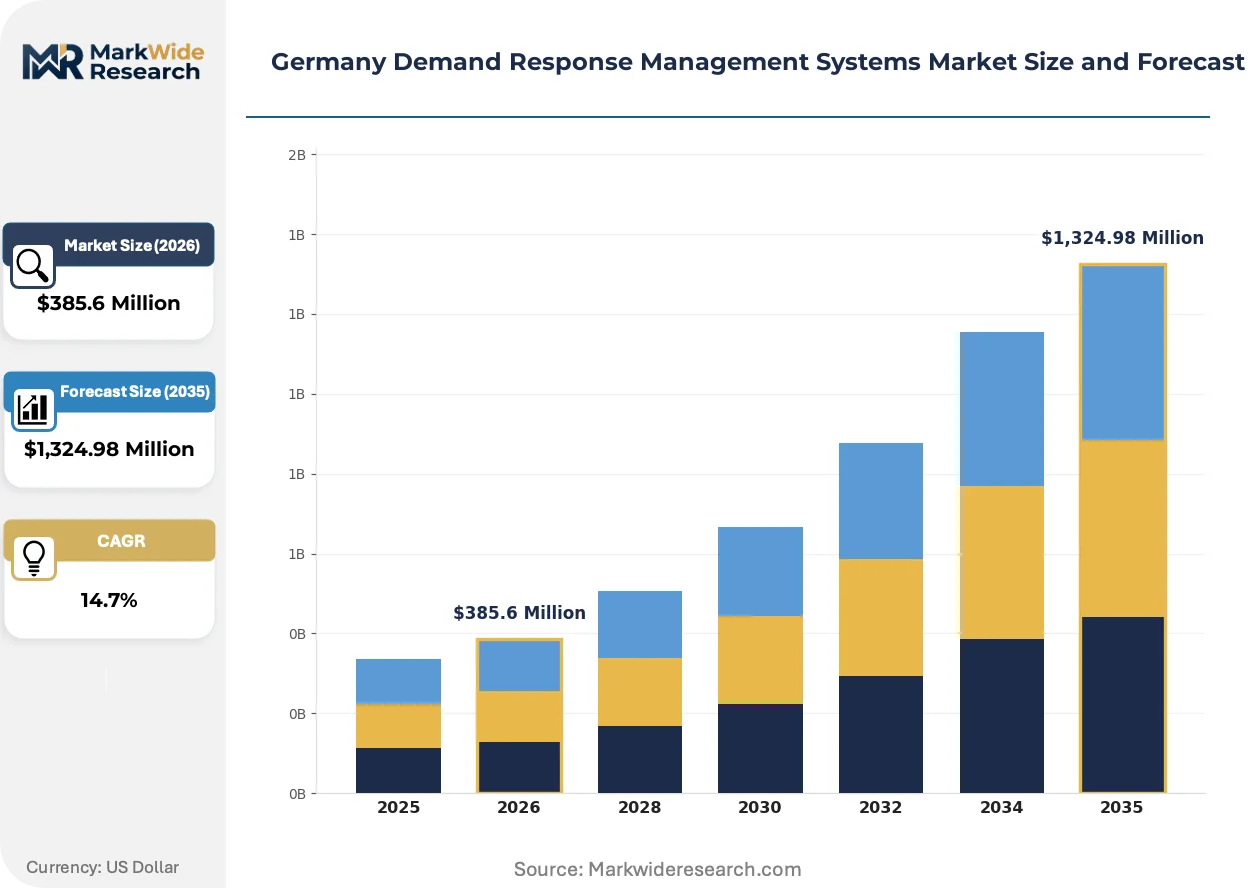
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,324.98 Million |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Offering: Automated Load Control, Real-Time Pricing, Demand Forecasting, Distributed Energy Resource Management, Grid Optimization Technology: Advanced Metering Infrastructure, SCADA Systems, IoT Sensors, Cloud Computing, Machine Learning Algorithms Application: Peak Load Shaving, Ancillary Services, Energy Theft Detection, Voltage Regulation, Load Balancing End User: Electric Utilities, Independent System Operators, Energy Traders, Commercial Facilities, Data Centers |
| Companies Covered | ABB Ltd, Centrica PLC, Siemens AG, Autogrid Systems Inc, REGEN Energy, Schneider Electric, Enel X Inc, Schneider Electric SE, Eaton Corporation PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Demand Response Management Systems Market Shifts & Advancements
Software-defined grid architectures are displacing hardware-centric control systems, compressing deployment timelines while expanding the addressable base of controllable loads beyond traditional industrial consumers.
Cloud-native distributed energy resource management platforms are unifying previously siloed SCADA, advanced metering infrastructure, and IoT sensor data streams into single-pane visibility systems. Automotive plants in Baden-Württemberg deploy these architectures to coordinate on-site battery storage with production line scheduling. The technology is unifying operational technology and information technology budgets that historically procured through separate channels.
EU AI Act risk classification requirements are reshaping algorithm deployment protocols for machine learning-based load forecasting systems. Industrial platform vendors must document training data provenance and model interpretability to maintain CE marking validity. German utilities operating cross-border balancing areas face the steepest compliance burden as they harmonize national grid codes with supranational AI governance frameworks.
Facility energy managers increasingly bundle demand response participation with behind-the-meter solar and storage procurement decisions. Engineering-procurement-construction firms in North Rhine-Westphalia report compressed sales cycles as commercial buyers seek integrated flexibility solutions rather than standalone software licenses. This pattern concentrates most visibly among pharmaceutical manufacturing campuses pursuing 24/7 carbon-free electricity matching commitments.
Germany Demand Response Management Systems Market Segmentation
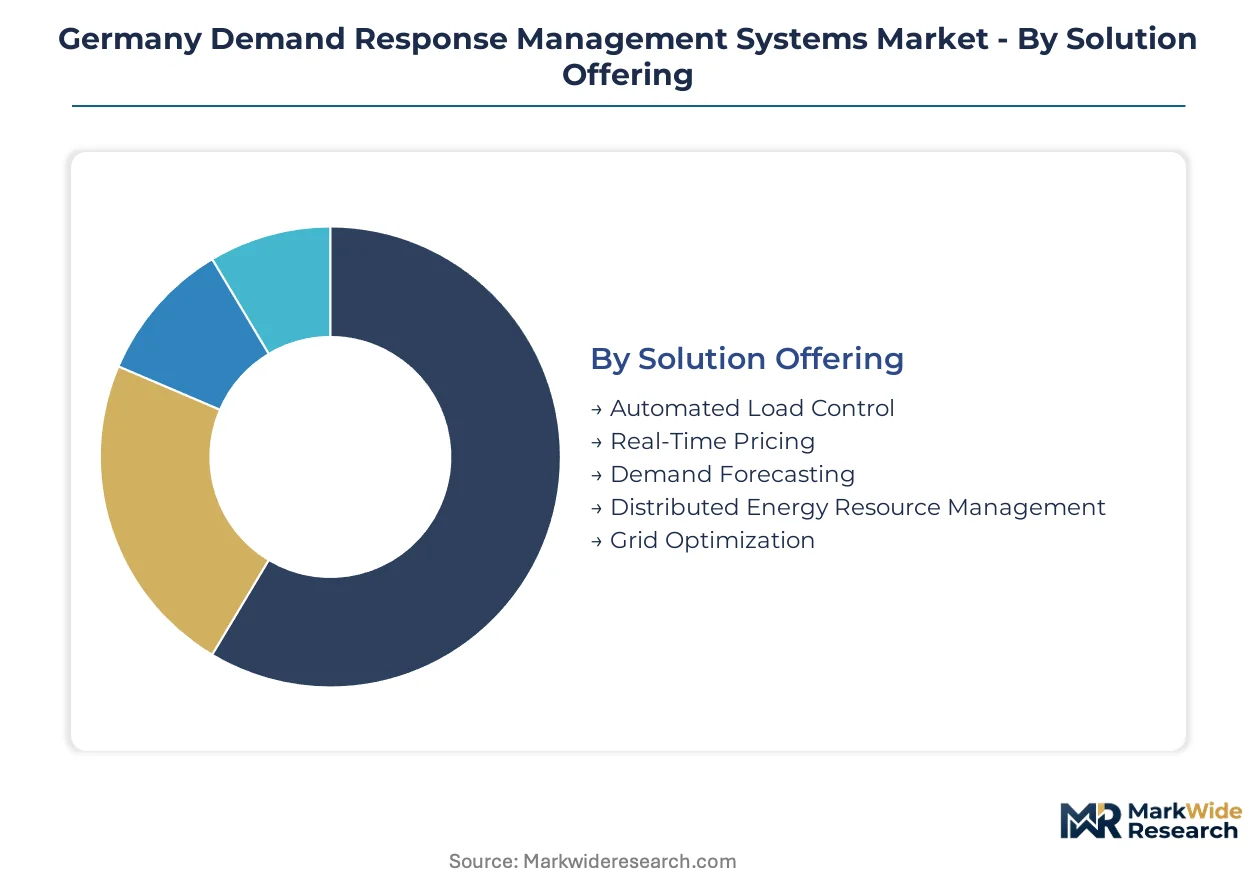
Segmentation in the German demand response market reveals how procurement decisions split across technical maturity, regulatory compliance burden, and end-use flexibility requirements. Each axis carries distinct margin profiles and vendor qualification thresholds that shape competitive positioning.
Solution Offering:
Technical sophistication determines deployment velocity and integration complexity across German utility procurement cycles.
- Automated Load Control:Hardware-software systems dispatch industrial loads within four-second frequency regulation windows mandated by Bundesnetzagentur grid codes. Bavarian automotive plants and hyperscale data centers anchor demand as these facilities monetize flexibility through ancillary services markets.
- Distributed Energy Resource Management:Cloud-native platforms aggregate prosumer solar-plus-battery assets into virtual power plant architectures. Rhineland-Palatinate residential clusters and North Rhine-Westphalia commercial campuses drive fastest expansion as behind-the-meter procurement accelerates.
- Real-Time Pricing:Dynamic tariff engines translate wholesale market signals into automated demand curtailment instructions.
- Demand Forecasting:Predictive analytics modules optimize load dispatch timing against day-ahead and intraday electricity prices.
- Grid Optimization:Network-level voltage and reactive power management tools for transmission system operators.
Mature deployment sits with Automated Load Control. Newer deployment is concentrated in Distributed Energy Resource Management.
Technology:
Technology choices reflect trade-offs between legacy infrastructure compatibility and cloud-native scalability.
- Machine Learning Algorithms:Predictive models for load forecasting and price arbitrage determine settlement accuracy in ancillary services markets. EU AI Act documentation requirements for training data provenance and model interpretability constrain vendor qualification timelines.
- Advanced Metering Infrastructure:Smart meter networks provide granular consumption telemetry for real-time dispatch decisions. Silicon supply concentration in Asian foundries exposes German utility procurement cycles to geopolitical disruption risks.
- SCADA Systems:Legacy supervisory control architectures persist in brownfield industrial substations requiring costly retrofitting.
- IoT Sensors:Edge-deployed devices enable sub-second latency response when combined with 5G industrial networks.
- Cloud Computing:Centralized data processing layers unify previously siloed operational and information technology systems.
Margin concentration aligns with Machine Learning Algorithms where predictive accuracy directly determines market settlement values. Fastest capability expansion is occurring in IoT Sensors as edge computing converges with private 5G deployments.
Application:
Application segmentation maps directly to compensation structures under Germany's implementation of EU Electricity Market Design reform.
- Peak Load Shaving:Demand curtailment during network congestion events reduces capacity charges for large commercial consumers. Pharmaceutical manufacturing campuses in Baden-Württemberg bundle this capability with 24/7 carbon-free electricity matching commitments.
- Ancillary Services:Frequency regulation and voltage support participation requires sub-four-second response latency certification. Bavarian industrial clusters concentrate procurement as automotive plants and data centers monetize flexible loads.
- Voltage Regulation:Reactive power dispatch maintains grid stability as renewable intermittency strains transmission networks.
- Load Balancing:Intra-day demand shifting smooths wholesale price volatility for energy traders.
- Energy Theft Detection:Anomaly detection algorithms flag non-technical losses in distribution networks.
Revenue stability favors Ancillary Services with regulated compensation frameworks. Steepest expansion trajectory belongs to Voltage Regulation as machine learning-enabled predictive dispatch platforms capture reform-recalibrated tariffs.
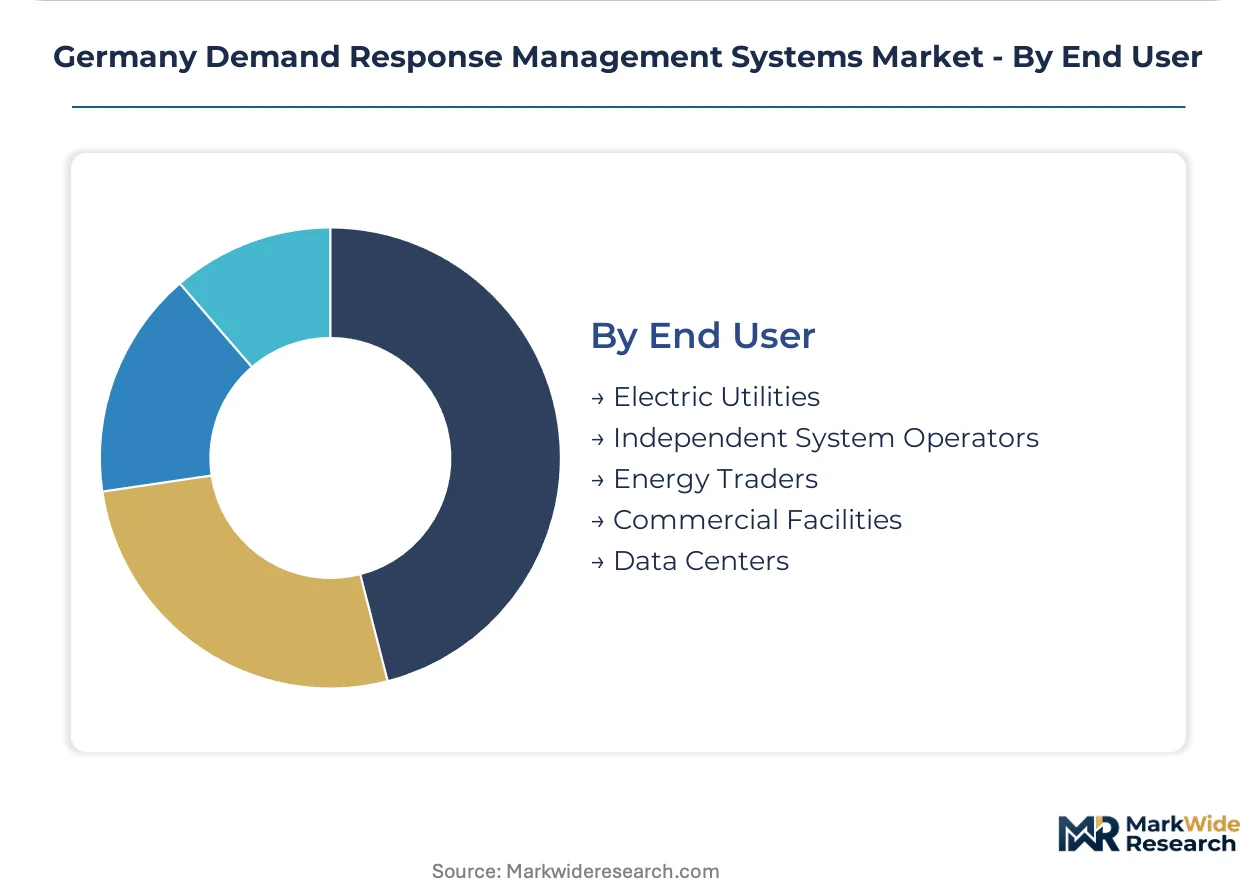
End User:
End-user categories reflect divergent procurement authority and technical integration depth.
- Electric Utilities:Vertically integrated operators deploy demand response as network investment deferral mechanisms under EnWG modernization mandates. Bundesnetzagentur-regulated procurement cycles favor established vendors with domestic manufacturing footprints.
- Commercial Facilities:Manufacturing campuses and logistics centers pursue integrated flexibility solutions bundling solar, storage, and automated load control. Engineering-procurement-construction firms report compressed sales cycles as buyers consolidate vendor relationships.
- Data Centers:Hyperscale facilities in Bavaria's automotive corridor monetize uninterrupted power supply infrastructure for grid services participation.
- Independent System Operators:Transmission balancing area coordinators procure aggregated flexibility resources.
- Energy Traders:Financial intermediaries optimize dispatch timing against wholesale market price spreads.
Procurement scale concentrates with Electric Utilities. Fastest decision velocity is appearing in Commercial Facilities where sustainability commitments compress vendor selection timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lignite deposits in the Rhineland anchor Germany's industrial power base, while silicon foundry concentration in Asia shapes component procurement cycles for domestic demand response vendors.
Bavaria
Hyperscale data centers and automotive assembly plants cluster along the A9 corridor between Munich and Nuremberg, monetizing uninterruptible power supply infrastructure for frequency regulation markets. Bundesnetzagentur grid codes under EnWG mandate sub-four-second response latency certification for ancillary services participation. Ingolstadt's manufacturing campuses anchor procurement scale for automated load control platforms.
North Rhine-Westphalia
Engineering-procurement-construction firms report compressed sales cycles as pharmaceutical manufacturing campuses pursue bundled solar-storage-load control solutions. EU Green Deal carbon pricing mechanisms compress investment timelines for 24/7 carbon-free electricity matching commitments. Cologne-Düsseldorf industrial zones concentrate demand for cloud-native distributed energy resource management platforms.
Baden-Württemberg
Automotive plants deploy unified operational technology and information technology architectures to coordinate on-site battery storage with production line scheduling. EU AI Act risk classification requirements reshape algorithm deployment protocols for machine learning-based load forecasting systems. Stuttgart's industrial suburbs host the densest concentration of brownfield SCADA retrofit projects.
Rhineland-Palatinate
Residential solar-plus-storage penetration creates untapped aggregation potential for virtual power plant operators targeting prosumer flexibility pools. CE marking requirements under EU cybersecurity frameworks constrain platform vendor qualification timelines through eighteen-to-twenty-four-month certification windows. Ludwigshafen's chemical corridor edges into demand response participation as behind-the-meter procurement accelerates.
Lower Saxony
Wind power intermittency from North Sea offshore clusters strains transmission networks, forcing accelerated utility procurement of predictive dispatch platforms. Germany's implementation of EU Electricity Market Design reform recalibrates compensation structures for voltage regulation services. Hanover-Braunschweig industrial zones concentrate grid optimization software demand among municipal utilities.
Germany Demand Response Management Systems Market Competitive Landscape
Global majors compete with regional champions across technology licensing and domestic manufacturing footprint dimensions. Siemens AG leverages its domestic production base to anchor utility relationships across Bundesnetzagentur-regulated zones. The vendor base stratifies into three tiers: integrated industrial conglomerates with captive software stacks, pure-play demand response specialists, and cloud-native distributed energy resource platform vendors. Competitive moves concentrate on strategic partnerships with transmission system operators and portfolio diversification into virtual power plant aggregation.
Within the integrated industrial tier, Siemens AG and ABB Ltd exemplify archetypes combining hardware manufacturing depth with algorithm development capabilities. Schneider Electric occupies a position bridging legacy SCADA retrofit expertise and cloud-native platform architecture. Among specialist operators, Autogrid Systems Inc represents the pure-play software model focused on utility-scale aggregation. Centrica PLC anchors the energy retailer pivot into flexibility services. Eaton Corporation PLC sits within the power quality and backup power equipment segment that feeds into demand response infrastructure.
| Leading Market Players |
|---|
| ABB Ltd |
| Centrica PLC |
| Siemens AG |
| Autogrid Systems Inc |
| REGEN Energy |
| Schneider Electric |
| Enel X Inc |
| Schneider Electric SE |
| Eaton Corporation PLC |
| Others |
Supply & Pricing Matrix
Captive software development within German industrial conglomerates anchors both supply security and pricing power, as domestic vendors bundle algorithm licensing with hardware manufacturing depth to defend margin positions against cloud-native entrants.
Pricing Analysis
Warranty and service bundling separates premium-tier vendors from economy-positioned competitors, with machine learning-enabled predictive dispatch platforms commanding higher subscription rates due to EU AI Act compliance documentation requirements. Price differentiation hinges on Bundesnetzagentur certification tier and vertical integration depth, with fully integrated hardware-software stacks extracting premium positioning. Pricing pressure stems from cloud-native distributed energy resource platforms unbundling legacy SCADA retrofit services. Mid-sized commercial facilities exhibit highest price sensitivity due to strained capex budgets for granular metering infrastructure.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for advanced metering infrastructure chipsets, exposing German utility procurement cycles to geopolitical disruption risks. Silicon foundry concentration in East Asia combines with rare earth processing dependency on China to constrain component availability. Supply chain risk centers on concentrated Asian foundry capacity subject to export restriction scenarios. Distribution runs through authorized system integrators and engineering-procurement-construction firms that manage brownfield retrofit complexity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where CE marking compliance timelines extending eighteen to twenty-four months force weaker platform vendors toward exit or acquisition.
For Market Incumbents: Anchor utility relationships through Bundesnetzagentur-regulated procurement cycles by deepening domestic manufacturing footprints. Defend against cloud-native entrants by accelerating machine learning algorithm development for voltage regulation services. Prioritize backward integration into IoT sensor production to reduce silicon supply exposure. For New Entrants and Emerging Players: Capture untapped aggregation potential in Rhineland-Palatinate residential solar-plus-storage clusters where incumbent presence remains thin. Target pharmaceutical manufacturing campuses in North Rhine-Westphalia pursuing bundled flexibility solutions. Pursue partnership routes with engineering-procurement-construction firms to bypass direct utility sales cycles. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to industrial conglomerates seeking software-defined grid capabilities. Long-term viability favors vendors with documented EU AI Act training data provenance and machine learning talent retention. Monitor Germany's implementation of EU Electricity Market Design reform as the critical inflection signal for compensation structure shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies SCADA, AMI, and IoT streams into single-pane visibility for automotive plants. |
| Backward Integration | Captive sensor production reduces silicon supply exposure for German vendors. |
| Strategic Partnership | Transmission system operator alliances accelerate frequency regulation certification. |
| Acquisition of Specialist Firm | Machine learning talent acquisition addresses algorithm development scarcity. |
| Geographic Expansion | Rhineland-Palatinate prosumer aggregation targets untapped virtual power plant pools. |
Research Methodology
Multi-period observation of Bundesnetzagentur procurement cycles, EnWG implementation timelines, and ancillary services market settlements anchored the trend analysis, supplemented by interviews with utility planning officers, grid operators, EPC contractors, and platform engineering leads. Secondary validation drew from FERC filings, IEA grid flexibility reports, EU regulatory databases, and customs records for advanced metering infrastructure trade flows. Bottom-up segment sizing triangulated against top-down utility capex disclosures.
Segment-weighting across solution offering, technology, application, and end-user dimensions shaped the analytical framework throughout the projection horizon. Deployment velocity assumptions for automated load control and distributed energy resource management platforms informed CAGR derivation, calibrated against renewable intermittency stress projections and EU Green Deal carbon pricing trajectory.
The model holds under stable EnWG enforcement and continued EU AI Act documentation requirements; deviation in silicon supply availability or Bundesnetzagentur grid code recalibration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management
Power SCADA Market
Energy Management
Australia Energy-As-A-Service Market
Energy Management
Europe Energy Management Systems Market
Energy Management
Heat Meter Market
Energy Management
Smart Energy Solutions Market
Energy Management
Global Energy Consumption Market
Energy Management
Industrial Demand Response Management Systems Market
Energy Management
Microgrid Control System Market
Energy Management
Electric Service Companies (Escos) Market
Energy Management
Energy ESO Market
Energy Management
Asia-Pacific Exhaust Heat Recovery System Market
Energy Management
South Korea Residential Heat Pump Market
Energy Management
Electric Sub-Meter Market
Energy Management
Residential Demand Response Management Systems Market
Energy Management
Smart Power Management Market
Energy Management
APAC Building Energy Management Systems Market