
 US Geothermal Heat Pump Market | 2026-2036
US Geothermal Heat Pump Market Size, Share, and Industry Trends Forecast 2026-2036
US Geothermal Heat Pump Market Analysis
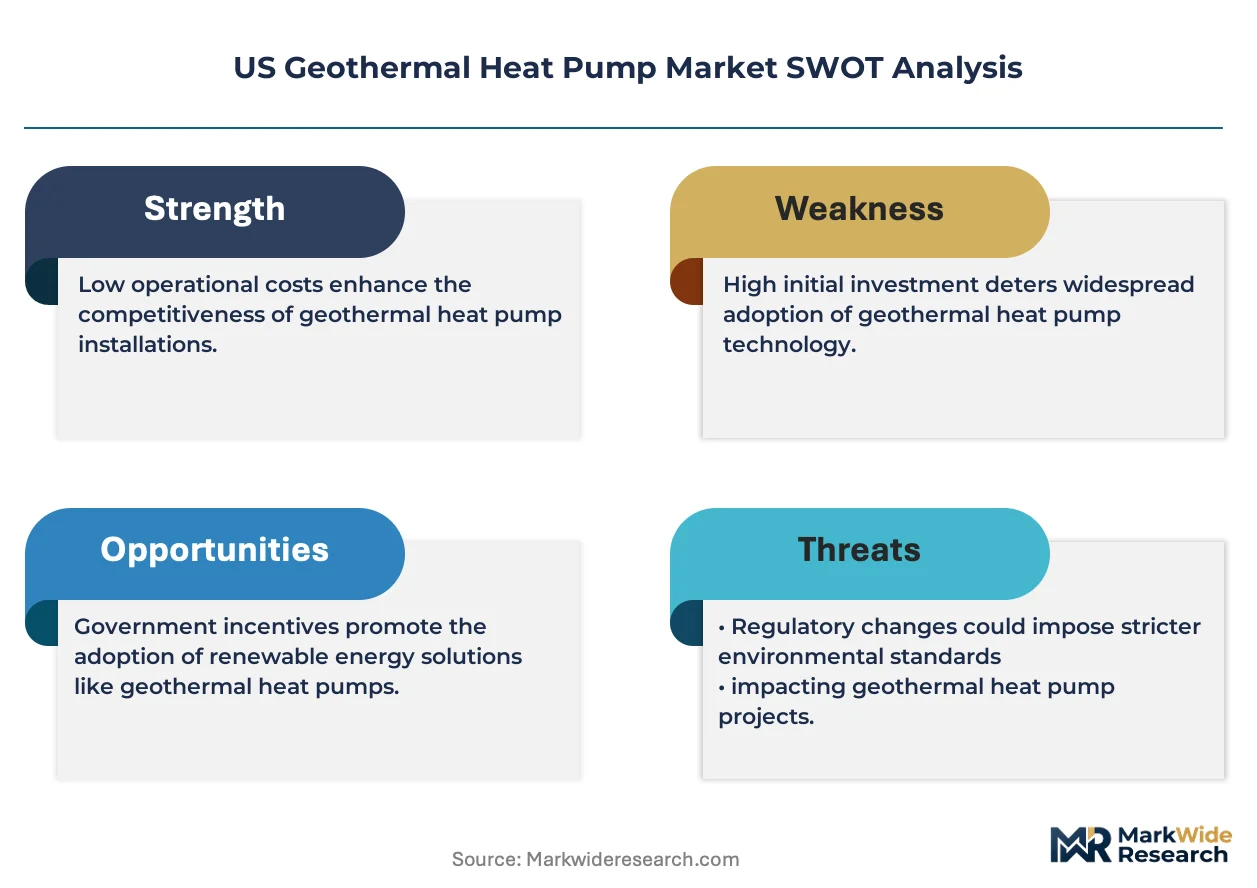
Residential new construction is rebalancing toward geothermal installations as builders face stricter energy codes and homeowner preference shifts toward electrification. WaterFurnace International leverages its domestic manufacturing footprint to anchor supply for the Midwest housing corridor. ClimateMaster competes through specialized water-to-water systems for commercial districts. Bosch Thermotechnology sustains R&D intensity in inverter-driven compressor technology for variable-speed ground loops.
A geothermal heat pump transfers thermal energy between the earth's stable subsurface temperatures and indoor spaces using a refrigerant cycle, typically achieving coefficient of performance ratings between three and five depending on loop configuration and soil conductivity. Closed-loop vertical systems dominate the commercial segment where land constraints prevent horizontal trenching, while residential demand flows toward professional installation in new construction where loop field integration occurs during foundation work. The retrofit installation category remains structurally limited by the cost of existing landscape disruption, concentrating margin pools in new-build channels.
The Inflation Reduction Act, administered through the Department of Energy and Internal Revenue Service, shapes demand through extended tax credits that reduce upfront system costs for qualified geothermal property. DOE efficiency standards and ASHRAE 90.1 building code benchmarks compel manufacturers to certify performance at specified entering water temperatures. Stakeholders must monitor state-level utility commission rulings on interconnection tariffs and renewable thermal credit programs that determine payback periods in key markets.
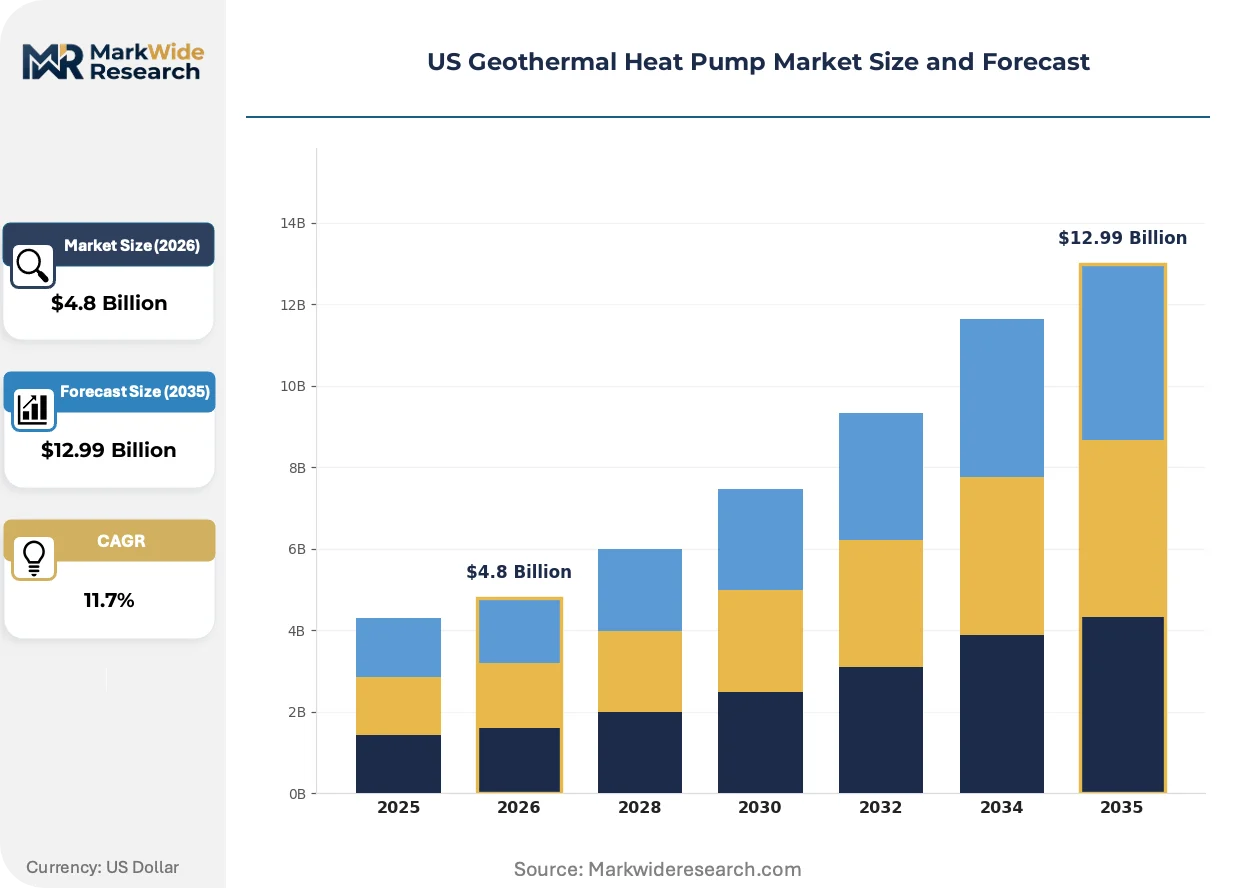
Market Dynamics
The US geothermal heat pump market pivots on the Inflation Reduction Act's 30% residential clean energy credit, which compresses payback periods and redirects builder procurement toward ground-source systems in new construction corridors.
Growth Catalysts
- IRA Tax Credit Extension:The Inflation Reduction Act's Section 25D credit locks in decade-long incentives for residential geothermal property, anchoring demand visibility for Midwest and Northeast housing developers.
- Electrification Mandates:State-level building performance standards in California, New York, and Massachusetts prohibit fossil fuel heating in new construction, forcing specification shifts toward ground-source heat pumps.
- Utility Rate Stacking:Midcontinent and Northeastern utility commission rulings layer demand-response rebates atop federal credits, cutting effective installed costs in high-load climate zones.
Market Restraints
- Copper Loop Material Volatility:Closed-loop vertical systems depend on copper tubing and high-density polyethylene, exposing project economics to commodity swings in construction-grade metals.
- Drilling Contractor Concentration:Certified ground-loop installation capacity clusters in the Upper Midwest and Texas shale corridors, creating regional bottlenecks when housing starts surge.
- Retrofit Site Disturbance:Horizontal trenching requirements render existing-landscape installations structurally uneconomical, capping addressable demand to new-build channels.
Strategic Opportunities
- Southeast Cooling-Dominant States:Florida, Georgia, and the Carolinas remain underpenetrated for geothermal despite high cooling loads, presenting white space for water-to-air systems sized for dehumidification performance.
- Federal Green Building Mandates:The General Services Administration's net-zero federal building portfolio directive forces geothermal specification in civilian agency new construction and major renovation contracts.
- Hybrid Solar-Thermal Integration:Photovoltaic-to-heat-pump load matching is automating dispatch optimization for net-zero residential developments in Colorado and Arizona solar corridors.
Industry Challenges
- Certified Loop Field Design Shortage:IGSHPA-accredited designers and drillers remain scarce outside established Midwest markets, extending project timelines in expansion states.
- Interconnection Tariff Uncertainty:State utility commission rulings on standby charges and net metering for electrically-intensive geothermal systems create permitting friction in deregulated Texas and Northeast ISO markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Geothermal Heat Pump Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Closed Loop, Open Loop, Pond Loop, Vertical Loop End User: Residential, Commercial, Industrial, Municipal Installation Type: New Construction, Retrofit, DIY, Professional Distribution Channel: Online Retail, Direct Sales, Distributors, Retail Stores |
| Companies Covered | ClimateMaster, Viessmann, Carrier, NIBE Energy Systems, Bosch Thermotechnology, Trane, Daikin North America, Enertech Global, WaterFurnace International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Geothermal Heat Pump Market Emerging Trajectories
Ground-loop system design is converging with building information modeling and inverter-driven compressor controls, compressing commissioning timelines and enabling precision load matching previously unattainable with fixed-speed equipment.
Variable-speed inverter technology is automating compressor modulation across partial-load conditions, allowing ground-source units to modulate output between 25% and 100% capacity without cycling losses. Residential developers in Minnesota and Wisconsin are specifying these systems for net-zero subdivisions where tight envelopes reduce peak loads. The technology is automating demand-response participation by enabling real-time utility signal integration through smart thermostat backbones.
The Inflation Reduction Act's domestic content bonus credit is reshaping supply chain geography, requiring steel, iron, and manufactured products to originate from US production for full incentive capture. Manufacturers are requalifying compressor castings and heat exchanger tubing through domestic foundries to preserve margin. The provision most acutely affects commercial vertical systems where imported components previously dominated specification-grade equipment.
Builder procurement is consolidating around design-build geothermal contractors who bundle loop field engineering, drilling, and mechanical installation under single-source accountability. National production homebuilders in the Chicago and Indianapolis corridors are abandoning split-contract models that separated HVAC from earthwork. This consolidation is most visible in master-planned communities where foundation schedules demand synchronized loop installation before slab pour.
US Geothermal Heat Pump Market Segmentation
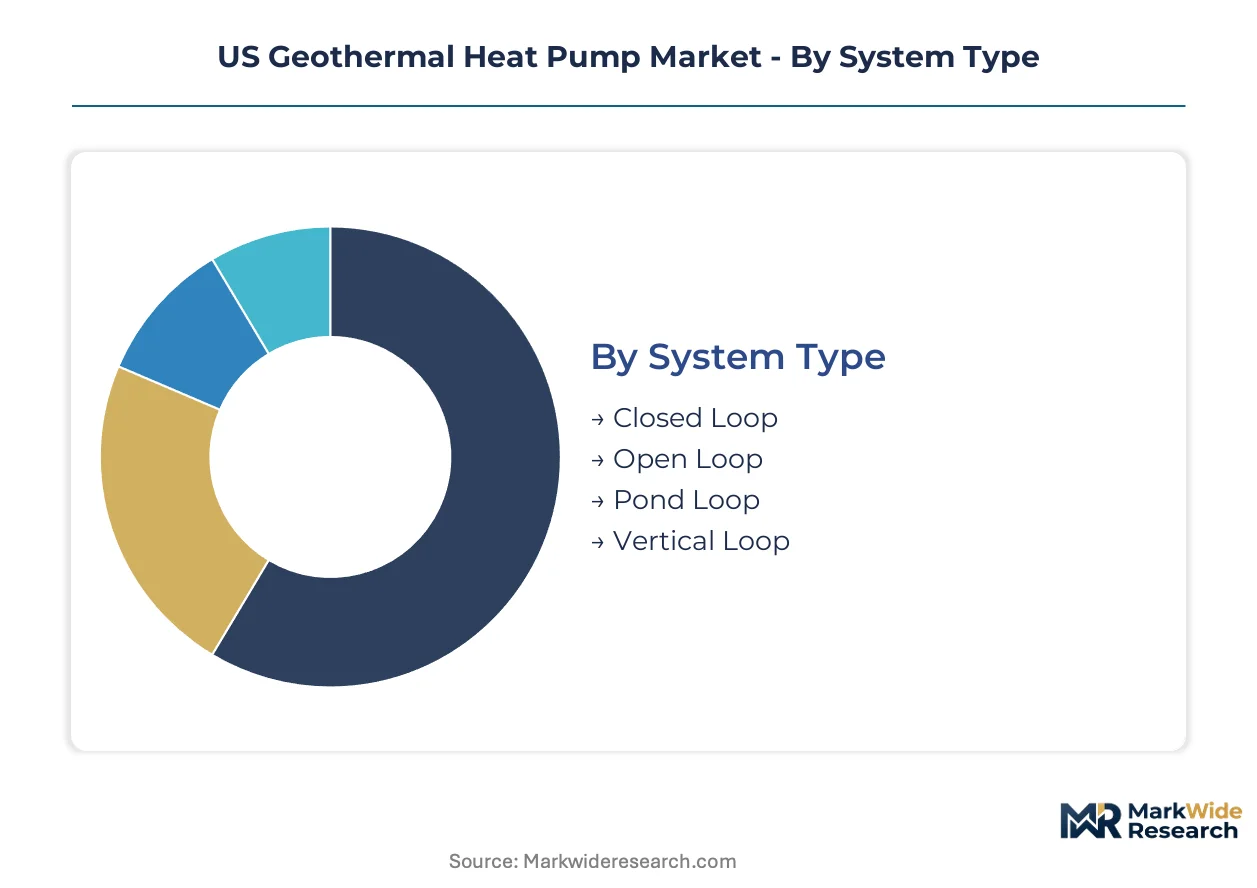
Geothermal heat pump market segmentation reveals how capital requirements, site constraints, and regulatory incentives reshape procurement patterns across system architectures and customer categories. Understanding these divisions exposes where margin pools concentrate and which installation channels face structural barriers to scale.
System Type:
Capital intensity varies sharply across loop configurations, with vertical bore systems demanding drilling expenditures that horizontal alternatives avoid entirely.
- Closed Loop:Sealed piping circuits circulate antifreeze solution through buried polyethylene loops, eliminating groundwater interaction. Residential developers in Minnesota and Wisconsin specify these for subdivisions where soil conditions permit horizontal trenching, compressing payback periods through IRA credit stacking.
- Vertical Loop:Deep boreholes drilled 150-400 feet accommodate high-density polyethylene U-bends in constrained sites. Commercial installations in downtown Chicago and Boston mandate these systems where surface area is unavailable, though drilling contractor scarcity extends project timelines.
- Open Loop:Direct groundwater extraction through supply and discharge wells achieves superior thermal conductivity where aquifer permits allow. Michigan lakefront properties and rural Pennsylvania farms deploy these where water rights are secured.
- Pond Loop:Submerged coil systems leverage stable water body temperatures for coastal Maine and Finger Lakes vacation properties with waterfront access.
Most installed capacity flows through Closed Loop systems. Expansion is steepest in Vertical Loop configurations where urban density constraints eliminate horizontal alternatives.
End User:
Customer archetypes diverge on procurement sophistication, with institutional buyers leveraging design-build contracts that residential purchasers cannot replicate.
- Residential:Single-family and multifamily housing developers specify geothermal during foundation work to minimize landscape disruption. Production homebuilders in Indianapolis and Columbus corridors bundle ground-source HVAC into base pricing as electrification mandates tighten.
- Commercial:Office, retail, and hospitality developers pursue LEED certification and utility demand-response revenue through centralized water-to-water systems. GSA net-zero mandates now require geothermal in federal new construction.
- Industrial:Manufacturing facilities with process heating and cooling loads deploy large-tonnage systems where waste heat recovery compounds efficiency gains.
- Municipal:School districts and municipal buildings in Ohio and Illinois exploit tax-exempt financing to spread capital costs across bond maturities.
Residential channels absorb the greatest unit volume. Commercial applications deliver the highest revenue per project.
Installation Type:
Site conditions and timing relative to construction sequencing determine which installation mode is economically viable.
- New Construction:Loop field integration during excavation and foundation phases eliminates surface restoration costs. National builders in the Chicago corridor now specify geothermal as standard in master-planned communities.
- Retrofit:Existing-structure installations face prohibitive landscape disruption and mechanical room constraints, limiting addressable demand to properties with accessible basements and minimal hardscaping.
- DIY:Self-installation remains marginal due to IGSHPA certification requirements for loop field design and EPA Section 608 refrigerant handling credentials.
- Professional:Licensed contractors bundle earthwork, mechanical, and commissioning under single-source accountability, dominating specification in production housing.
New Construction commands the dominant share of ground-loop deployments. Professional installation is gaining share fastest as builder procurement consolidates around design-build accountability.
Distribution Channel:
Channel selection tracks project scale and buyer sophistication, with institutional purchasers bypassing retail intermediaries entirely.
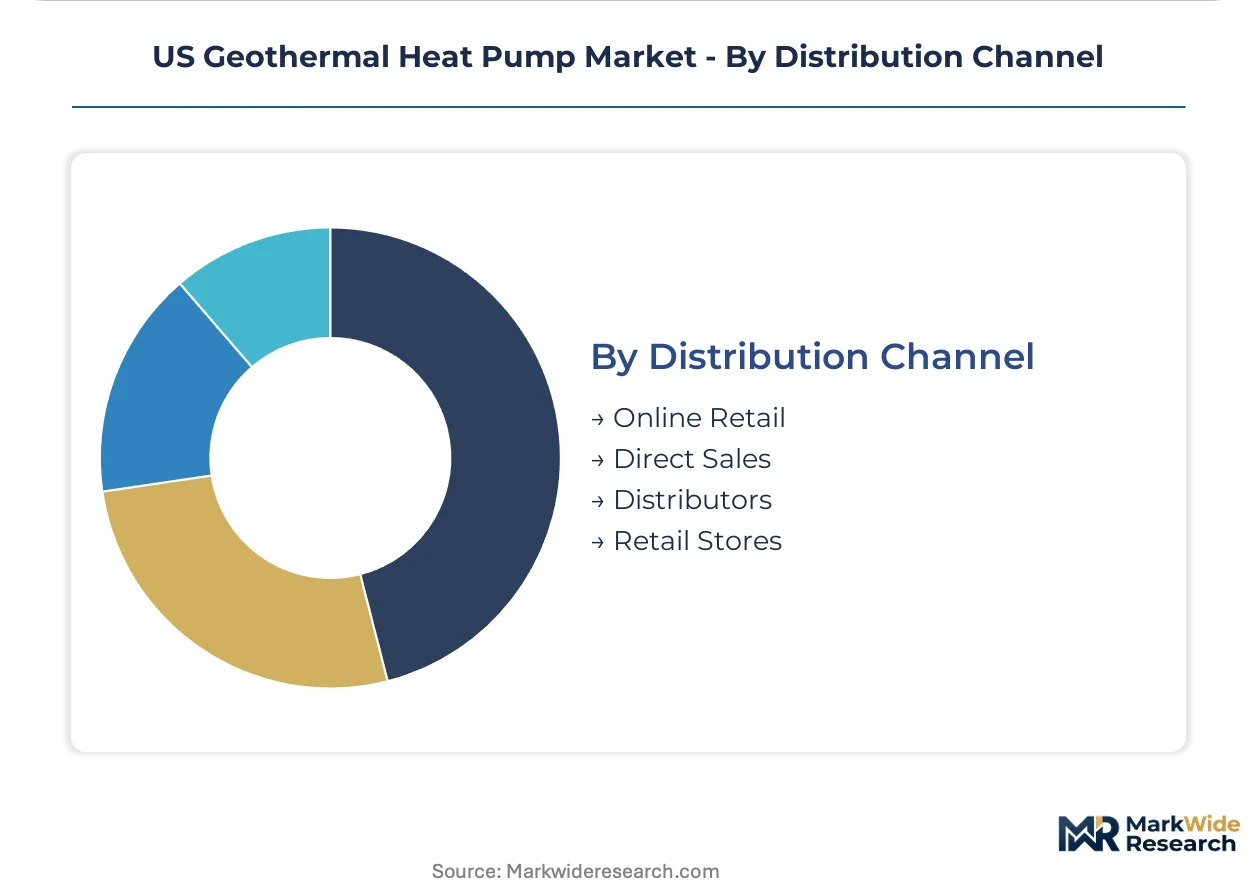
- Direct Sales:Manufacturers like WaterFurnace and ClimateMaster maintain factory-direct relationships with national production builders, securing specification lock-in through volume commitments.
- Distributors:Regional HVAC wholesalers stock inventory and provide contractor training, anchoring supply in established Midwest markets where dealer density is highest.
- Online Retail:E-commerce platforms serve equipment-only purchases for rural properties where local distribution is absent, though loop field engineering remains a separate procurement.
- Retail Stores:Big-box home improvement channels carry limited geothermal SKUs, constrained by the complexity of site-specific system sizing.
Distributors move the greatest equipment volume. Direct Sales channels are expanding most quickly as builder consolidation favors national account structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage around the IRA's domestic content bonus credit is redirecting manufacturing investment toward states with established metalworking infrastructure, compressing cost differentials between imported and domestically sourced heat pump components.
Midwest
Indiana and Ohio production homebuilders specify geothermal as standard equipment in master-planned communities where foundation schedules synchronize loop installation. The IRA's Section 25D credit stacks with utility demand-response rebates from Midcontinent Independent System Operator member utilities. Indianapolis and Columbus corridors anchor the highest residential installation density nationwide.
Northeast
New York and Massachusetts building performance standards prohibit fossil fuel heating in new construction, forcing specification shifts toward ground-source systems. The states' public service commissions layer renewable thermal credit programs atop federal incentives. Boston and Albany metropolitan areas concentrate commercial vertical loop deployments where land constraints eliminate horizontal alternatives.
Southeast
Florida and Georgia cooling loads drive water-to-air system demand despite historically low geothermal penetration. The region's public utility commissions have not standardized interconnection tariffs for electrically-intensive heat pumps, creating permitting friction. Atlanta and Charlotte emerging as test markets for dehumidification-optimized equipment.
Mountain West
Colorado and Arizona net-zero residential developments integrate photovoltaic-to-heat-pump load matching for automated dispatch optimization. The region's geological stability permits horizontal trenching at reduced depths. Denver and Phoenix solar corridors attract design-build contractors bundling loop field engineering with mechanical installation.
Pacific Northwest
Oregon and Washington state energy codes tighten envelope requirements that reduce peak loads and enable smaller-capacity geothermal systems. The Bonneville Power Administration's conservation programs layer incentives atop IRA credits. Portland and Seattle metropolitan areas concentrate municipal school district deployments exploiting tax-exempt financing.
US Geothermal Heat Pump Market Vendor Landscape
Strategic partnerships dominate the current landscape as manufacturers secure drilling contractor networks and design-build installation capacity. The market structures around three tiers: domestic specialists with captive loop field service arms, diversified HVAC conglomerates with geothermal product lines, and European imports competing on inverter technology. Capacity expansion and vertical integration into compressor manufacturing represent the dominant competitive moves as firms qualify components for domestic content bonus credits.
Among domestic specialists, WaterFurnace International and ClimateMaster exemplify the integrated model combining equipment fabrication with regional drilling partnerships. Carrier and Trane occupy positions within the diversified conglomerate tier, leveraging established distribution networks. Bosch Thermotechnology represents the European technology anchor, competing through inverter-driven compressor platforms.
| Leading Market Players |
|---|
| ClimateMaster |
| Viessmann |
| Carrier |
| NIBE Energy Systems |
| Bosch Thermotechnology |
| Trane |
| Daikin North America |
| Enertech Global |
| WaterFurnace International |
| Others |
Supply Flow & Price Mechanics
Captive integration into domestic compressor manufacturing anchors both supply security and pricing power for equipment vendors qualifying for IRA domestic content bonus credits. This backward integration choice compresses cost differentials between imported and US-sourced components while preserving margin pools threatened by commodity volatility in copper tubing and high-density polyethylene.
Pricing Analysis
Distributor margin compression runs through the Midwest and Northeast corridors where dealer density is highest and volume commitments extract preferential pricing. Project-based transactional pricing dominates commercial vertical loop deployments, while residential new construction channels favor bundled design-build contracts that obscure equipment-versus-installation splits. Price differentiation hinges on IGSHPA certification tier and inverter-driven compressor technology grade, with variable-speed systems commanding premium positioning over fixed-speed alternatives. Cost compression in standard-efficiency tiers is intensifying as national production builders consolidate procurement around single-source accountability, squeezing regional HVAC wholesalers.
Supply Chain Analysis
Freight cost escalation from Asian component sources is accelerating domestic requalification of heat exchanger castings and compressor assemblies through Midwest foundries. Manufacturing concentration centers on Indiana, Ohio, and Oklahoma where metalworking infrastructure supports IRA-compliant production. Raw material dependencies draw from Chilean copper concentrate, Gulf Coast petrochemical complexes for polyethylene resin, and domestic steel mills for cabinet fabrication. Single-source vulnerability in certified ground-loop drilling equipment exposes project timelines to regional bottlenecks when housing starts surge. Distribution runs through manufacturer-direct national accounts with production builders, bypassing wholesale intermediaries for volume commitments above defined thresholds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by builder procurement consolidation around design-build contractors with IGSHPA-certified loop field engineering capabilities. Residential electrification mandates in California, New York, and Massachusetts are forcing specification shifts toward premium inverter-driven systems with demand-response integration.
For Market Incumbents: Deepen captive control over compressor manufacturing to preserve domestic content bonus credit eligibility as European competitors requalify supply chains. Anchor drilling contractor partnerships in the Southeast expansion corridor before certified installer scarcity extends project timelines. Defend against emerging HVAC-as-a-service entrants by bundling performance guarantees into long-term residential service contracts.
For New Entrants and Emerging Players: Municipal school districts in Ohio and Illinois present the most penetrable buyer archetype, exploiting tax-exempt financing capacity and predictable bond-funded replacement cycles. Target the Southeast cooling-dominant states where utility interconnection tariff standardization remains incomplete and incumbent service coverage is thinnest. Pursue GSA federal building contracts where net-zero mandates now require geothermal specification in new construction and major renovation awards.
For Investors and Strategic Acquirers: Roll-up economics work for regional design-build contractors because builder procurement consolidation favors single-source accountability spanning loop engineering, drilling, and mechanical installation. The 5-10 year viability window hinges on IRA credit extension beyond current statutory sunset and state-level building performance standard adoption velocity. Monitor utility commission rulings on renewable thermal credit program expansion as the inflection signal for addressable market scaling beyond new construction corridors.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Content Qualification | IRA bonus credit eligibility preserves margin pools threatened by Asian component sourcing. |
| Drilling Contractor Acquisition | Certified installer capacity in expansion states compresses project timelines and captures housing start surges. |
| Inverter Technology Licensing | Variable-speed compressor platforms enable demand-response participation and utility rebate stacking. |
| Design-Build Consolidation | Single-source accountability aligns with national production builder procurement standardization. |
| Federal Contracting Certification | GSA net-zero mandates create specification lock-in for civilian agency new construction awards. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with geothermal equipment manufacturing executives, IGSHPA-accredited loop field designers, drilling contractor operations managers, and national production builder procurement directors with secondary validation against Department of Energy efficiency standard filings, FERC interconnection tariff dockets, utility commission renewable thermal credit rulings, and manufacturer SEC disclosures. Bottom-up installation volume estimates triangulated against top-down housing start and electrification mandate adoption projections.
Segment-weighting approaches applied differential growth assumptions across closed-loop, vertical-loop, open-loop, and pond-loop configurations, with end-user splits between residential, commercial, industrial, and municipal categories calibrated to tax credit eligibility and financing mechanism penetration. CAGRs derived from equipment shipment data, loop field permitting records, and builder specification surveys across the projection horizon, with inputs from IRA credit utilization rates and state-level building code adoption timelines.
Inputs from utility commission dockets and manufacturer production disclosures were available through the study window; gaps in real-time drilling contractor capacity utilization introduce uncertainty bands around installation timeline assumptions. Forecasts reflect documented assumptions about federal credit extension, state mandate adoption sequencing, and commodity price trajectory stabilization. Stakeholders should weight assumptions against their own operating context and regional regulatory exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geothermal Energy
Indonesia Geothermal Energy Market
Geothermal Energy
Geothermal Power Infrastructure and Components Market
Geothermal Energy
Netherlands Geothermal Energy Market
Geothermal Energy
Hungary Geothermal Energy Market
Geothermal Energy
Geothermal Energy Market
Geothermal Energy
Asia-Pacific Geothermal Energy Market
Geothermal Energy
Geothermal Power Generation Market
Geothermal Energy
United Kingdom Geothermal Energy Market
Geothermal Energy
Philippines Geothermal Energy Market
Geothermal Energy
Enhanced Geothermal System Market
Geothermal Energy
Sweden Geothermal Energy Market
Geothermal Energy
Global Geothermal Heat Pumps Market
Geothermal Energy
Geothermal Power Infrastructure Market
Geothermal Energy
Geothermal Power Market
Geothermal Energy
Denmark Geothermal Energy Market