
 Smart Power Management Market | 2026-2036
Smart Power Management Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Power Management Market Insights
Southeast Asia's manufacturing corridor is fragmenting as new electronics assembly capacity spreads across Vietnam, Thailand, and Malaysia. Schneider Electric leverages its integrated software-hardware stack to anchor premium positions in industrial microgrid controls. Siemens competes through deep domain expertise in grid automation and digital twin platforms for utility-scale deployments. Texas Instruments sustains component-level dominance by supplying power management ICs that enable edge intelligence in smart meters and load controllers.
Smart Power Management encompasses hardware, firmware, and software systems that monitor, distribute, and optimize electrical power across residential, commercial, and industrial installations, typically operating at voltage ranges from low-voltage distribution (120-480V AC) to medium-voltage grid interconnection levels with response latencies under 100 milliseconds for critical load switching. Its primary purpose is to minimize energy waste, extend equipment lifespan, and enable real-time coordination between distributed generation assets and consumption endpoints. Energy Management Systems command the largest installed base among product categories due to enterprise mandates for carbon accounting and operational expenditure reduction, while IoT-enabled monitoring layers represent the fastest-expanding technology segment as sensor costs decline and wireless protocols standardize. The utilities end-user category concentrates long-term margin pools because procurement cycles favor multi-year service contracts and firmware subscriptions over one-time hardware sales.
The US Department of Energy's appliance efficiency standards and the European Commission's Ecodesign Working Plan shape minimum performance thresholds for networked power devices, directly influencing product development roadmaps and certification costs for manufacturers seeking cross-border market access. China's GB standards for smart grid interoperability and India's BIS certification requirements for electronic energy meters create additional compliance layers that favor established vendors with dedicated regulatory affairs teams. Stakeholders must monitor how fragmented national cybersecurity mandates for critical infrastructure reshape supplier qualification criteria and procurement timelines across major deployment regions.
Market Dynamics
Edge intelligence architectures are compressing response latencies below 50 milliseconds for critical load switching, forcing incumbent vendors to re-architect firmware stacks and opening procurement windows for specialized semiconductor suppliers.
Growth Catalysts
- EU Ecodesign mandates:Minimum efficiency thresholds for networked power equipment are accelerating replacement cycles across German industrial clusters and utility modernization programs.
- Data center load-balancing platforms:Hyperscale operators are deploying intelligent power distribution units to reduce operational expenditures and enable real-time carbon accounting.
- IoT sensor cost declines:Wireless protocol standardization is expanding addressable markets for residential and commercial monitoring layers previously constrained by wiring complexity.
Market Restraints
- Silicon carbide supply concentration:Wafer production for high-efficiency power semiconductors remains geographically concentrated, exposing procurement timelines to single-source risk.
- GB standards compliance costs:China's interoperability certification requirements for smart grid equipment impose dedicated regulatory affairs overhead that disadvantages smaller vendors.
- Legacy analog substitution:Electromechanical relay systems in established industrial installations exhibit replacement inertia due to capital recovery timelines and technician familiarity.
Strategic Opportunities
- India's BIS certification pipeline:Electronic energy meter mandates are creating first-mover advantages for vendors establishing local firmware development centers.
- Digital twin convergence:Integration of physics-based simulation with real-time power telemetry is enabling predictive maintenance contracts in utility-scale deployments.
- Vietnam electronics assembly expansion:Manufacturing corridor fragmentation is generating localized demand for microgrid controls in new industrial parks.
Industry Challenges
- Firmware security certification:Fragmented national cybersecurity mandates for critical infrastructure are elongating supplier qualification timelines and requiring redundant testing protocols.
- Embedded systems talent scarcity:Shortage of engineers proficient in real-time operating systems and power electronics control algorithms is constraining R&D velocity.
- Multi-protocol integration complexity:Legacy Modbus and DNP3 installations resist seamless integration with MQTT-based IoT layers without middleware investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Power Management Market |
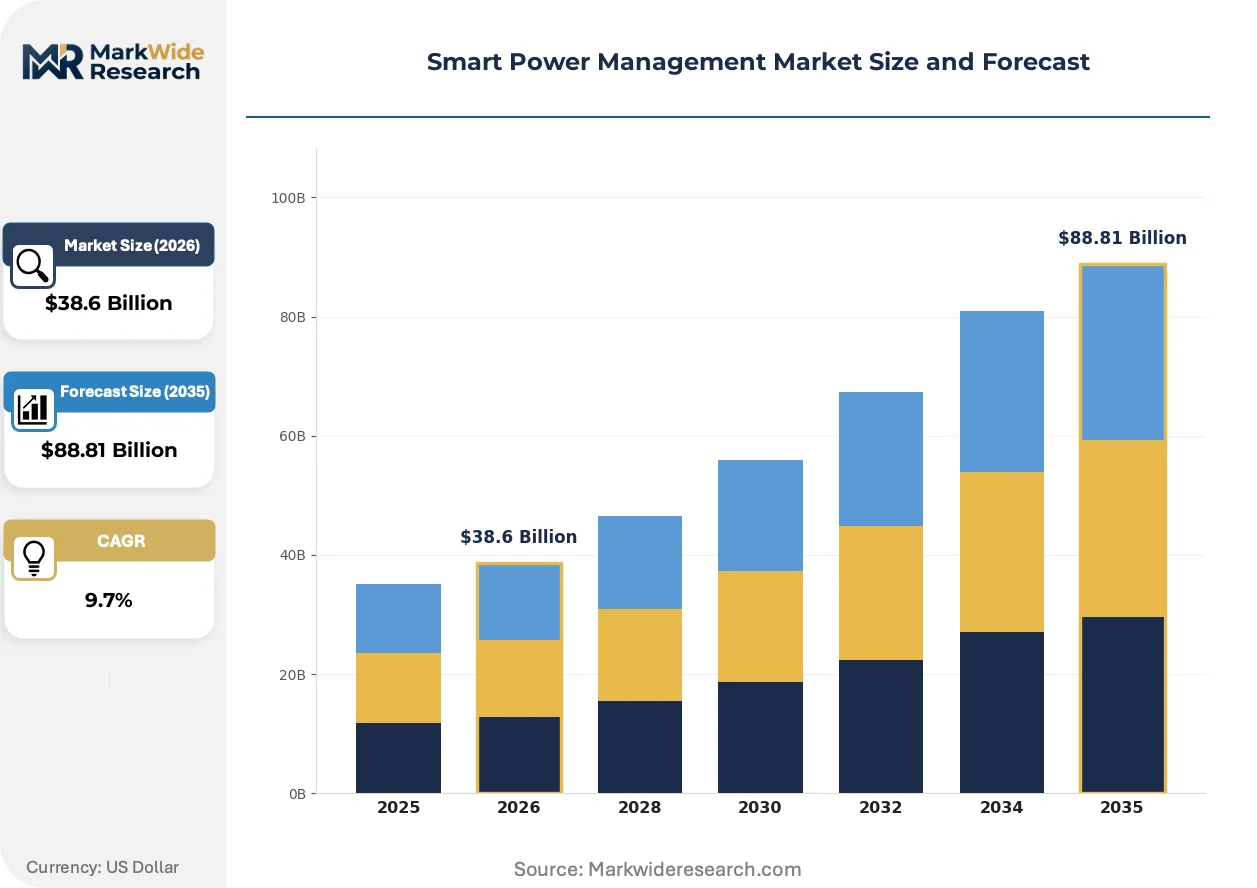
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $88.81 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Monitors, Smart Switches, Energy Management Systems, Smart Meters Technology: IoT, AI, Cloud Computing, Advanced Analytics End User: Residential, Commercial, Industrial, Utilities Application: Load Management, Demand Response, Energy Efficiency, Smart Grid |
| Companies Covered | Schneider Electric, ABB, Siemens, General Electric, Emerson Electric, Eaton Corporation, Honeywell International, Texas Instruments, Infineon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Power Management Market Trends and Innovations
Power electronics architectures are undergoing fundamental restructuring as wide-bandgap semiconductors, edge AI inference, and subscription firmware models converge to redefine value capture mechanisms across the value chain.
Silicon carbide and gallium nitride power devices enable switching frequencies above 100 kHz with thermal losses below silicon equivalents. Data center operators and electric vehicle charging infrastructure developers are adopting these materials fastest. The technology is hybridizing analog and digital control domains, compressing the distinction between discrete power stages and intelligent management systems.
CSRD disclosure requirements are mandating granular energy consumption reporting from large enterprises operating in European Union member states. This regulatory pressure is reshaping procurement specifications to favor equipment with embedded metering and automated data export capabilities. Industrial end-users in Germany and France are prioritizing certified platforms that streamline audit preparation.
Enterprise buyers are unbundling hardware acquisition from ongoing firmware subscription and predictive analytics services. Utilities and large industrial accounts now favor multi-year service contracts with guaranteed uptime commitments over capital expenditure models. This behavioral shift is most pronounced in North American and European markets where operational expenditure visibility outweighs balance sheet optimization.
Smart Power Management Market Segmentation
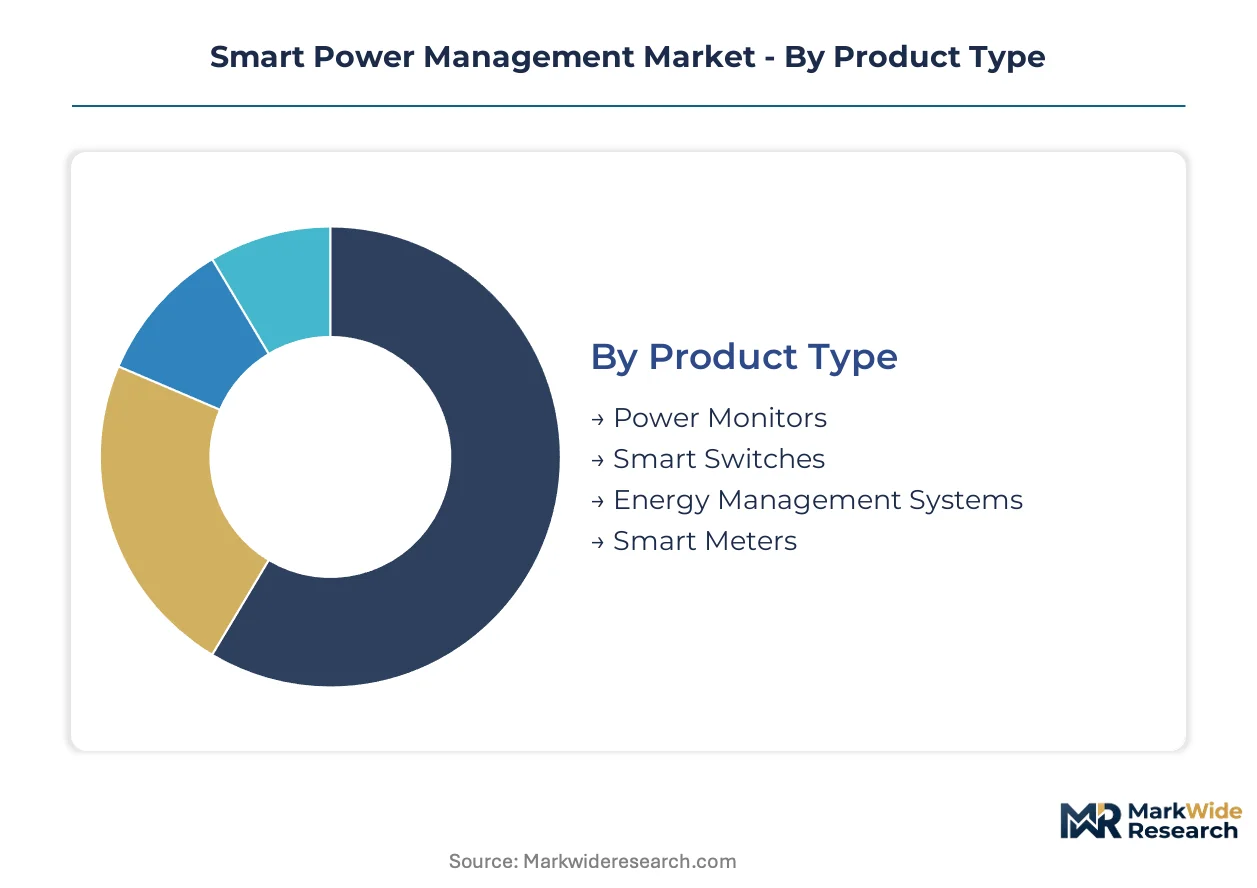
Smart power management deployments vary sharply by operational voltage, latency tolerance, and integration depth with legacy infrastructure. Segmentation reveals where hardware margins concentrate versus where software subscriptions capture lifetime value.
Product Type:
Installations span residential circuit panels through utility-scale substations, with complexity and price points scaling across voltage classes and switching speeds.
- Power Monitors:These devices measure voltage, current, and power factor in real-time across distribution networks. German industrial clusters deploy them for compliance with EU Ecodesign efficiency thresholds. Demand concentrates in retrofit scenarios where embedded metering satisfies CSRD disclosure mandates without full system replacement.
- Energy Management Systems:Enterprise-grade platforms aggregate telemetry from multiple endpoints to automate load scheduling and carbon accounting. Data center operators in Virginia and Frankfurt prioritize these systems to reduce operational expenditures while meeting real-time reporting requirements. These command the largest installed base due to procurement cycles favoring multi-year service contracts.
- Smart Switches:Solid-state and electromechanical devices enabling remote load control with response latencies under 100 milliseconds.
- Smart Meters:Bi-directional communication endpoints supporting time-of-use pricing and distributed generation integration.
Established volume favors Energy Management Systems; emerging adoption favors Power Monitors.
Technology:
Technology selection determines firmware architecture, cybersecurity surface, and whether deployments lean toward edge autonomy or centralized orchestration.
- IoT:Wireless sensor networks using standardized protocols to eliminate wiring complexity in retrofit installations. Vietnam's expanding electronics assembly corridors drive demand for localized microgrid controls using these layers.
- AI:Edge inference engines predicting load patterns and automating switching decisions with sub-50 millisecond latencies. Industrial facilities in Texas and Bavaria deploy these for predictive maintenance contracts that guarantee uptime commitments.
- Cloud Computing:Centralized data lakes enabling cross-facility benchmarking and utility-scale demand aggregation.
- Advanced Analytics:Physics-based digital twins converging with real-time telemetry for asset lifecycle optimization.
Cloud Computing anchors current deployment scale; AI claims the steepest expansion trajectory as switching latency requirements tighten.
End User:
Procurement authority and contract structures diverge dramatically between fragmented residential buyers and concentrated utility accounts.
- Utilities:Transmission and distribution operators with multi-decade asset horizons and regulatory rate-base treatment. These concentrate long-term margin pools through firmware subscriptions and guaranteed uptime service contracts rather than one-time hardware sales.
- Industrial:Manufacturing and process facilities with 24/7 critical loads and technician familiarity with legacy electromechanical systems. India's BIS certification pipeline for electronic energy meters is accelerating first-mover advantages among vendors establishing local firmware development centers.
- Commercial:Office buildings and retail chains prioritizing operational expenditure visibility and automated audit preparation.
- Residential:Single-family and multi-unit dwellings where sensor cost declines and wireless standardization are expanding previously constrained addressable markets.
Utilities dominate contract value; Industrial segments show fastest technology refresh cycles amid efficiency mandate pressure.
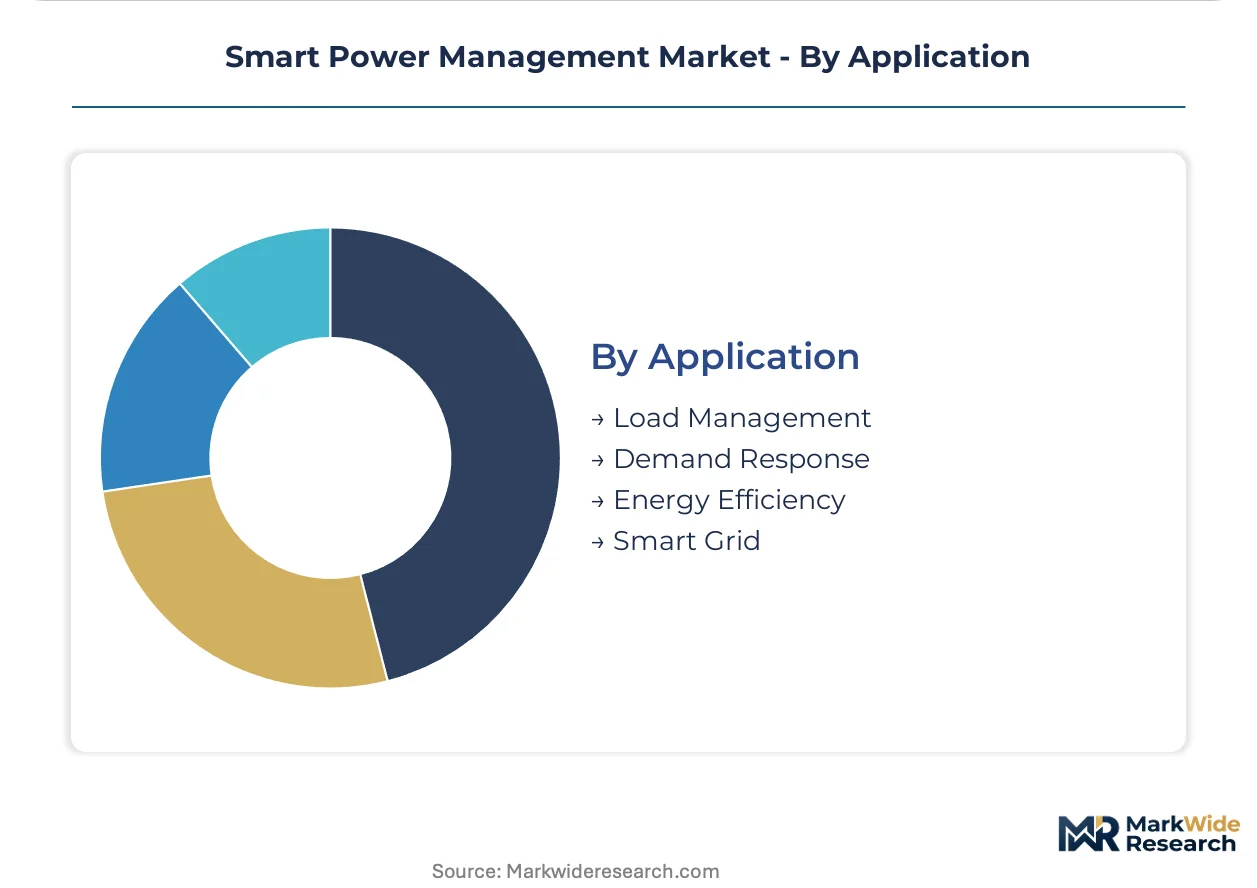
Application:
Functional priorities range from immediate operational cost reduction to grid stability services with regulatory compensation structures.
- Load Management:Real-time balancing of consumption against available generation capacity, including peak shaving and load shifting protocols. Data center operators deploy intelligent power distribution units here to align with carbon accounting requirements.
- Smart Grid:Bi-directional communication infrastructure coordinating distributed energy resources with centralized dispatch. Germany's utility modernization programs and grid-edge intelligence deployments anchor European demand for these integrations.
- Demand Response:Automated curtailment programs providing grid services in exchange for utility incentives or tariff reductions.
- Energy Efficiency:Continuous optimization minimizing waste through equipment scheduling and power factor correction.
Load Management captures current implementation density; Smart Grid infrastructure claims the fastest policy-driven deployment acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The NordLink interconnector underwrites Germany's position as Europe's power trading hub. Texas ERCOT grid isolation drives autonomous microgrid investment. Vietnam's 500kV North-South transmission spine anchors Southeast Asian manufacturing electrification.
United States
Data center operators in Virginia and Texas deploy intelligent power distribution units to reduce operational expenditures. The Department of Energy's appliance efficiency standards shape minimum performance thresholds for networked power devices. ERCOT's isolated grid architecture accelerates grid-edge intelligence deployment in Austin and Dallas industrial corridors.
Germany
Industrial clusters in Bavaria and North Rhine-Westphalia modernize utility infrastructure under EU Ecodesign mandates. The European Commission's Ecodesign Working Plan mandates minimum efficiency thresholds for networked power equipment. Frankfurt's hyperscale data center concentration drives demand for real-time carbon accounting platforms.
China
Smart grid interoperability requirements under GB standards accelerate replacement cycles across Yangtze River Delta manufacturing bases. MIIT's dual carbon goals impose firmware certification overhead favoring established vendors. Shenzhen and Shanghai anchor demand for power management ICs in edge intelligence applications.
India
BIS certification requirements for electronic energy meters create first-mover advantages for vendors establishing local firmware development centers. The CEA's grid modernization programs mandate bi-directional communication endpoints in Maharashtra and Gujarat. Bangalore's technology corridor concentrates demand for IoT-enabled monitoring layers.
Vietnam
Electronics assembly expansion across northern industrial parks generates localized demand for microgrid controls. The national power development plan prioritizes grid-edge intelligence in manufacturing zones. Bac Ninh and Hai Phong anchor deployment of intelligent load-balancing platforms for export-oriented production facilities.
Smart Power Management Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the semiconductor layer. The vendor base stratifies across three tiers: diversified electrical conglomerates with software-hardware stacks, grid automation specialists with digital twin capabilities, and power semiconductor suppliers enabling edge intelligence. Strategic moves concentrate on firmware subscription models and predictive maintenance service contracts.
Among diversified electrical conglomerates, Schneider Electric and Siemens occupy positions spanning industrial microgrid controls through utility-scale automation. Texas Instruments anchors the component tier through power management IC supply. These three exemplify the archetype segmentation between integrated platform vendors and specialized semiconductor suppliers.
| Leading Market Players |
|---|
| Schneider Electric |
| ABB |
| Siemens |
| General Electric |
| Emerson Electric |
| Eaton Corporation |
| Honeywell International |
| Texas Instruments |
| Infineon Technologies |
| Others |
Pricing and Supply Chain Analysis
Shenzhen's power semiconductor foundry cluster dictates downstream pricing power for smart power management systems, with wafer capacity constraints compressing margins for mid-tier vendors while reinforcing premium positioning for integrated platform providers.
Pricing Analysis
EU Ecodesign mandates dictate the pricing tier structure across the European market, separating certified platforms with embedded metering and automated data export capabilities from uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because of silicon carbide supply concentration and firmware development overhead. Data center operators exhibit the least price sensitivity due to operational expenditure visibility priorities, while residential buyers remain most responsive to upfront hardware costs.
Supply Chain Analysis
Extended payment terms from Taiwanese foundry partners and supply-chain finance facilities anchored in Singaporean banking channels lubricate component procurement for established vendors. Manufacturing draws from China, Taiwan, and South Korea for power management ICs, with silicon carbide substrates sourcing from Japan and the United States. Single-source vulnerability concentrates in 200mm silicon carbide wafer production. Distribution runs through authorized industrial distributors and direct enterprise sales teams serving utility and data center accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart power management market fragmentation creates entry niches as edge AI inference requirements split procurement between specialized semiconductor suppliers and integrated platform vendors.
For Market Incumbents: Build firmware subscription moats by converting capital expenditure contracts into multi-year service agreements with guaranteed uptime commitments. Incumbents should anchor backward integration into power management IC design to secure component supply against silicon carbide concentration risks. Certification investment in India's BIS pipeline and China's GB standards compliance will defend position against emerging regional challengers. For New Entrants and Emerging Players: Vietnam's northern industrial parks present underpenetrated demand for localized microgrid controls serving electronics assembly expansion. New entrants should target first-mover positioning in firmware development centers for India's BIS-certified electronic energy meter mandates. A channel partnership with established industrial distributors offers the fastest go-to-market path without direct sales infrastructure investment. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because firmware subscription models and predictive maintenance contracts capture lifetime value beyond hardware depreciation cycles. Acquisition targets should display vertical integration into edge AI inference silicon or captive utility relationships with multi-decade rate-base treatment. The signal to watch is hyperscaler data center capex allocation toward intelligent power distribution units with real-time carbon accounting capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Subscription Conversion | Transforms one-time hardware sales into recurring revenue streams with utility and data center accounts. |
| Silicon Carbide Supply Agreement | Secures wafer allocation from Japanese or US substrate producers against single-source geographic risk. |
| India BIS Certification Pipeline | Establishes regulatory compliance moat for electronic energy meter deployments in Maharashtra and Gujarat. |
| Digital Twin Platform Integration | Converges physics-based simulation with real-time telemetry for predictive maintenance contract offerings. |
| Vietnam Microgrid Localization | Captures demand from Bac Ninh and Hai Phong industrial parks serving export-oriented electronics manufacturing. |
Research Methodology
Initial hypotheses were tested against primary input from utility planning officers, data center infrastructure directors, power electronics procurement leads, and firmware engineering heads, and refined through secondary validation against SEC filings, EIA grid modernization disclosures, EU Ecodesign regulatory texts, and IEA power system transformation reports. Bottom-up segment sizing triangulated with top-down macroeconomic anchoring across voltage classes and end-user categories.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon, with segmentation modeled by product type, technology layer, end-user procurement authority, and application functional priority. CAGRs derived from installed base evolution, replacement cycle compression under efficiency mandates, and subscription revenue conversion rates. Forecast inputs incorporated hyperscaler data center capex trajectories and silicon carbide capacity expansion timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese platform vendors or碳化硅 substrate producers would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management
Smart Energy Solutions Market
Energy Management
Power SCADA Market
Energy Management
Asia-Pacific Exhaust Heat Recovery System Market
Energy Management
APAC Energy Management Systems (EMS) Market
Energy Management
Middle East and Africa Energy Management Systems Market
Energy Management
Energy ESO Market
Energy Management
Thermostat Market
Energy Management
Industrial Demand Response Management Systems Market
Energy Management
European Building Energy Management Systems Market
Energy Management
Electric Sub-Meter Market
Energy Management
Brazil Energy Sector Market
Energy Management
Australia Energy-As-A-Service Market
Energy Management
Testing, Inspection, and Certification (TIC) in the Energy and Power Market
Energy Management
Smart Power Technologies Market
Energy Management
Remote Renewable Management Systems Market
Energy Management
Energy Harvesting System Market