
 South Korea Passenger Vehicles Lubricants Market | 2026-2036
South Korea Passenger Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Passenger Vehicles Lubricants Market Analytics
Asset-light leasing arrangements for commercial fleets is tilting procurement power toward large-scale buyers rather than individual consumers. SK Lubricants Co. Ltd leverages its domestic refining infrastructure to control cost positions across synthetic grades. GS Caltex anchors its market presence through integrated service center partnerships that lock in recurring volume. Hyundai Oilbank competes by aligning lubricant specifications with parent-company vehicle warranty requirements.
Passenger vehicles lubricants are formulated hydrocarbon-based fluids engineered to reduce friction, dissipate heat, and prevent wear across powertrain components, with viscosity grades typically ranging from 0W-16 to 5W-30 for modern gasoline direct-injection engines. Their primary commercial purpose is to extend engine operational life while maintaining fuel economy certification thresholds. Synthetic lubricant formulations command the dominant value share due to OEM fill requirements and extended drain intervals, while engine oil applications generate the largest revenue pool within the application dimension. Service centers remain the critical distribution node, though online retail channels are gaining transaction volume among digitally native vehicle owners.
MFDS oversees chemical substance registration requirements affecting additive package compositions, while KSA administers product quality certifications that lubricant marketers must obtain for domestic sale. South Korea's alignment with EU REACH-equivalent chemical management protocols is raising compliance costs for imported formulations. Stakeholders must monitor how carbon neutrality mandates from the Presidential Committee on Carbon Neutrality reshape base oil sourcing strategies and refinery investment timelines.
Market Dynamics
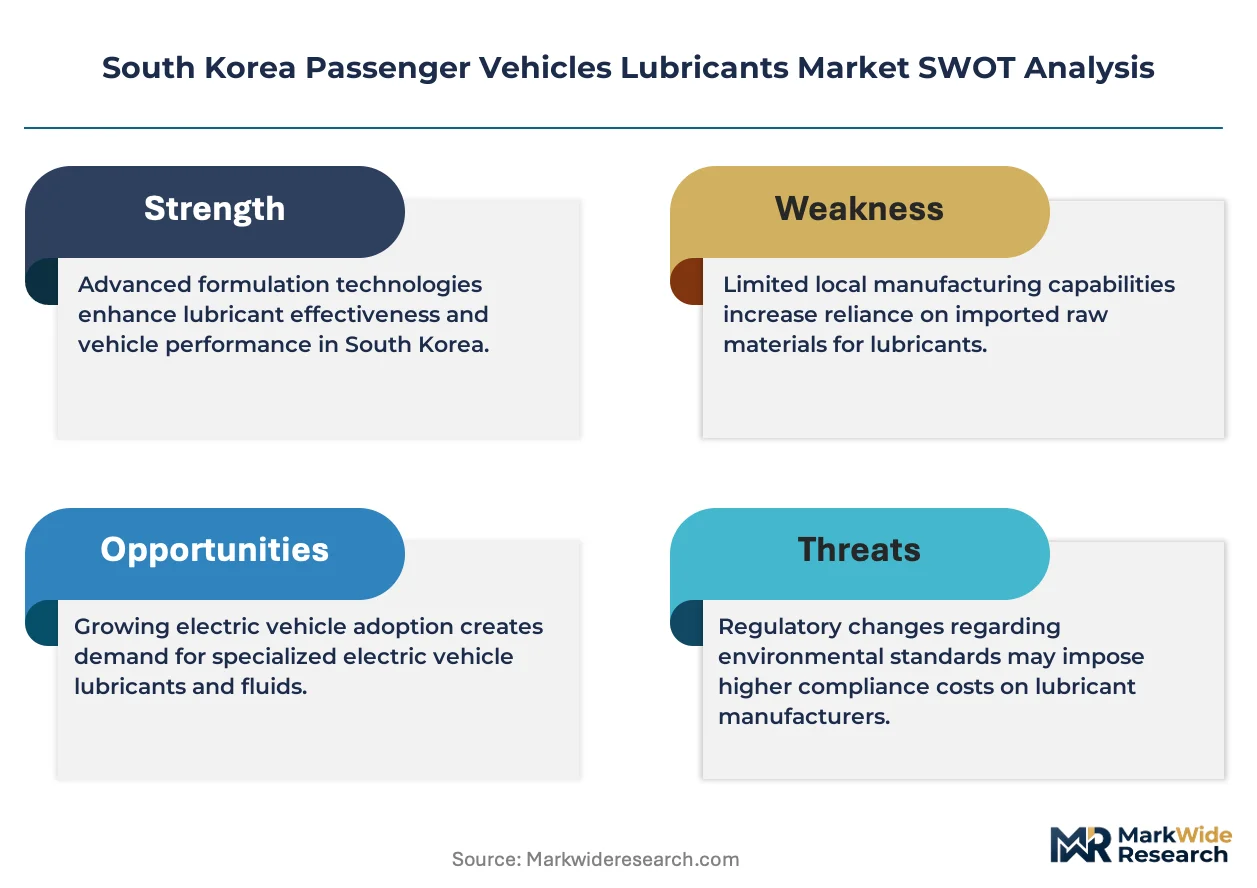
MFDS chemical registration protocols and KSA quality certifications are compressing formulation flexibility while elevating compliance costs for lubricant marketers serving South Korea's passenger vehicle fleet.
Growth Catalysts
- Seoul Metropolitan Concentration:Vehicle density in Seoul and Gyeonggi Province sustains lubricant demand through dense service center networks and high utilization rates among fleet operators.
- Carbon Neutrality Mandates:The Presidential Committee on Carbon Neutrality is redirecting refinery investment toward lower-carbon base oil sourcing, creating procurement pull for synthetic formulations.
- Extended Drain Intervals:Synthetic lubricant technology enables OEM-specified longer service cycles, locking in premium product substitution across gasoline direct-injection engine parc.
Market Restraints
- Base Oil Supply Concentration:Domestic refining infrastructure limits alternative sourcing options when feedstock costs fluctuate, exposing formulators to margin compression.
- REACH-Equivalent Compliance Burden:South Korea's alignment with EU chemical management protocols raises additive package registration costs and extends time-to-market for imported formulations.
- Electric Vehicle Penetration:Battery electric powertrains eliminate engine oil demand entirely, threatening volume erosion in the passenger vehicle lubricant category over the long term.
Strategic Opportunities
- Busan-Ulsan Industrial Corridor:Heavy manufacturing and port logistics clusters in the southeast generate fleet lubricant demand underserved by Seoul-centric distribution networks.
- Online Retail Channel Expansion:Digitally native vehicle owners are migrating lubricant purchases to e-commerce platforms, bypassing traditional service center intermediaries.
- Warranty-Aligned Specifications:OEM fill requirements tied to parent-company vehicle warranties create captive demand for certified lubricant formulations.
Industry Challenges
- Additive Chemist Talent Scarcity:Formulation expertise in low-viscosity, fuel-efficient lubricant design remains concentrated among experienced specialists with limited pipeline replenishment.
- Service Center Integration Complexity:Fleet management software and inventory systems require API-compatible data exchange, creating friction for lubricant marketers without digital platform partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Passenger Vehicles Lubricants Market |
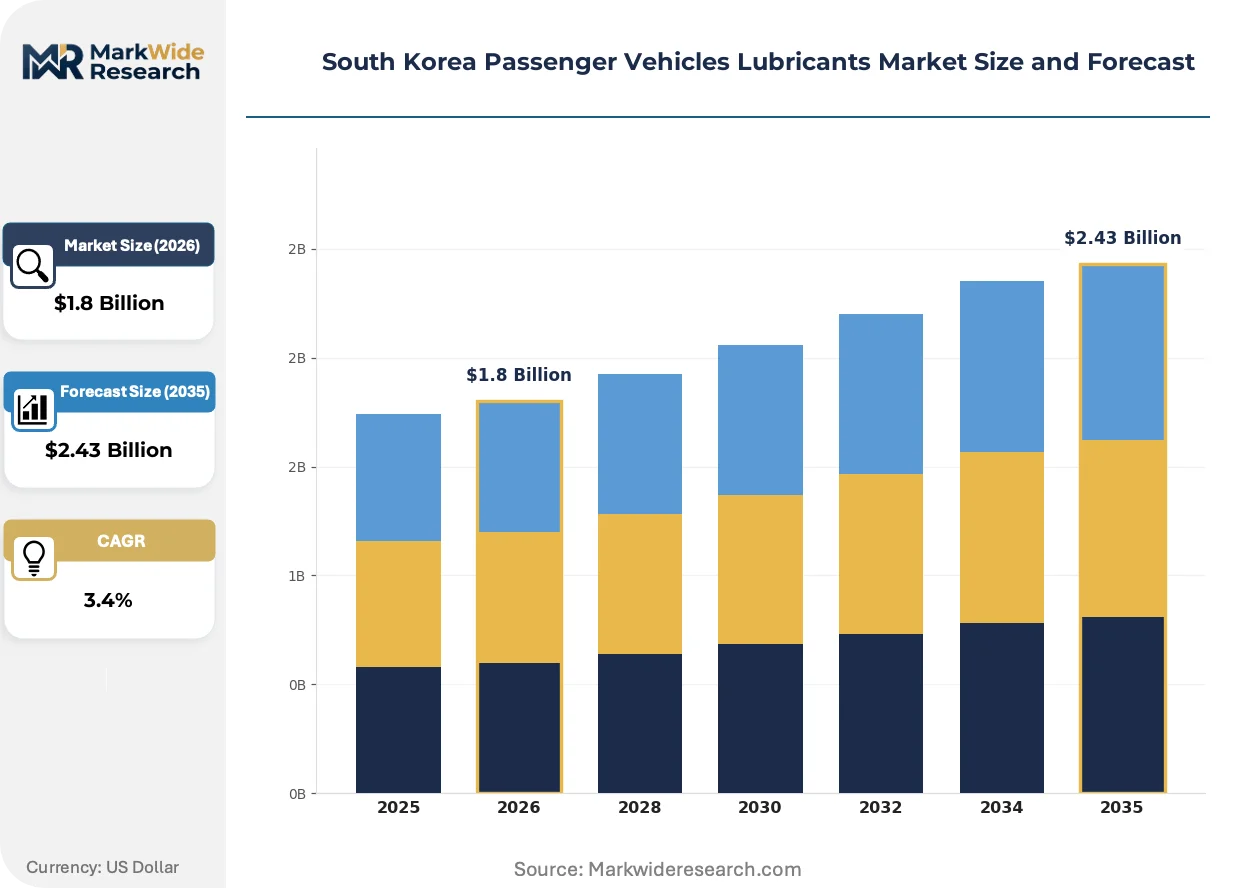
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.43 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Lubricant Type: Synthetic, Conventional, Semi-Synthetic, Biodegradable Vehicle Type: Passenger Car, SUV, Light Truck, Sports Car Application: Engine Oil, Transmission Fluid, Brake Fluid, Grease Distribution Channel: Online Retail, Auto Parts Store, Dealerships, Service Centers |
| Companies Covered | GS Caltex, Hyundai Oilbank, S-Oil Corporation, SK Lubricants Co. Ltd, ExxonMobil Corporation, BP PLC (Castrol), Michang Oil Ind Co. Ltd, Shell plc, AMSOIL Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Passenger Vehicles Lubricants Market Evolving Landscape
Formulation digitization and predictive maintenance integration are redefining how lubricant performance is specified, monitored, and procured across South Korea's passenger vehicle service ecosystem.
Artificial intelligence-driven oil condition monitoring systems are embedding sensors directly into engine architectures to track viscosity degradation and contaminant accumulation in real time. Fleet operators and ride-hailing services are piloting these systems at scale to optimize drain intervals and reduce unscheduled downtime. This sensor layer is digitizing the traditional fixed-interval maintenance model, compressing lubricant volume per vehicle while raising specification precision requirements.
KSA product quality certifications now incorporate stricter chemical substance disclosure requirements aligned with EU REACH-equivalent protocols. Lubricant marketers must submit comprehensive additive package compositions for pre-market approval, extending registration timelines and elevating documentation costs. Domestic formulators with established KSA relationships are responding faster than importers, reshaping competitive access to the South Korean market.
Asset-light leasing structures are centralizing lubricant procurement decisions within fleet management companies and commercial vehicle lessors. Individual vehicle owners are losing purchasing authority as operating lease penetration rises among corporate and private users. This buyer concentration is most visible in the Seoul metropolitan area, where large fleet operators negotiate direct supply agreements with lubricant marketers, bypassing traditional retail and service center channels.
South Korea Passenger Vehicles Lubricants Market Segmentation
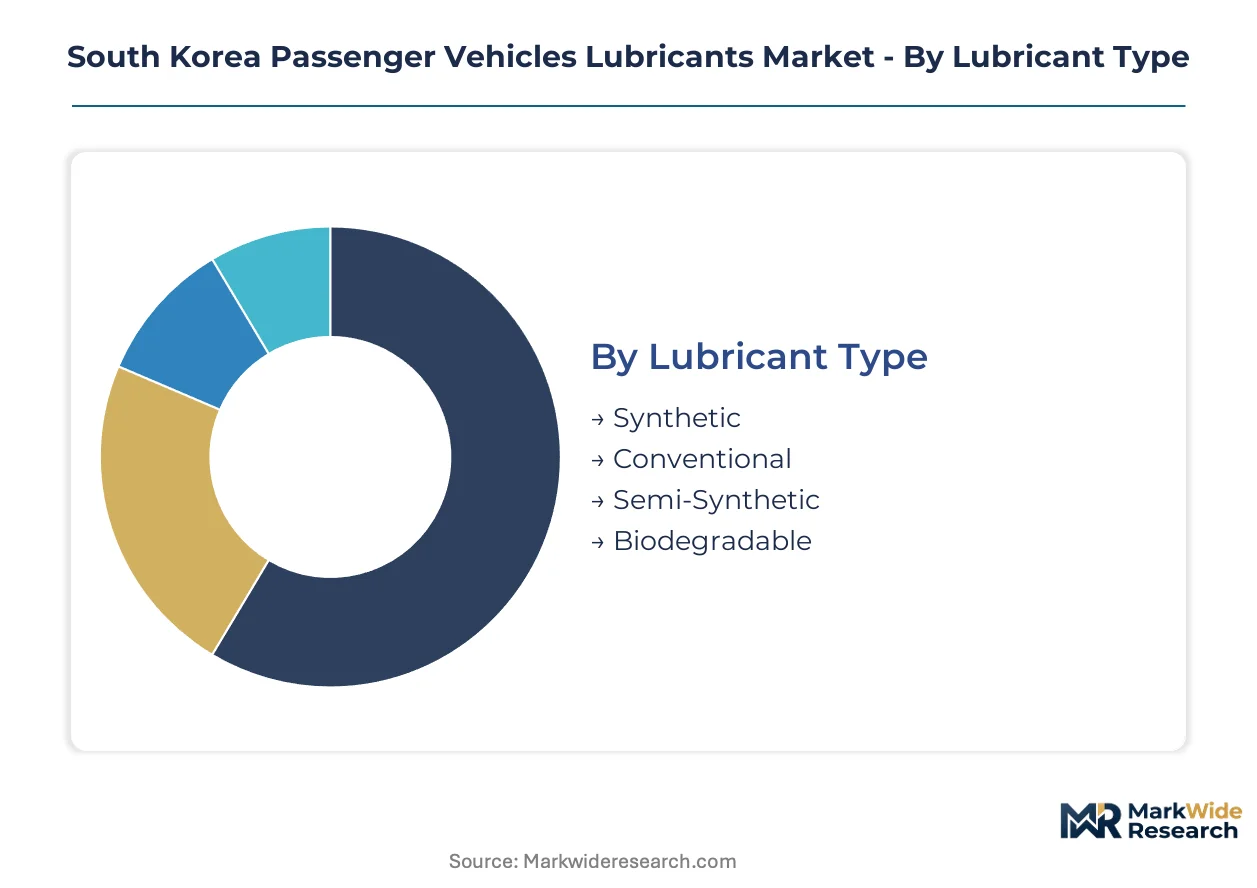
South Korea's passenger vehicle lubricant market fragments across formulation chemistry, vehicle architecture, and procurement channels. Each dimension reflects distinct technical specifications and buyer behaviors shaped by Seoul's dense service infrastructure and Gyeonggi Province's fleet concentration.
Lubricant Type:
Cost tier stratification separates premium synthetic formulations from economy-grade mineral oils, with mid-market semi-synthetics capturing price-sensitive OEM fill requirements.
- Synthetic:Poly-alpha-olefin and ester-based formulations deliver thermal stability for gasoline direct-injection engines under Seoul's stop-and-go traffic conditions. OEM warranty compliance in the Seoul metropolitan area drives procurement concentration among fleet operators seeking extended drain intervals.
- Conventional:Mineral base oils refined from domestic crude streams serve older vehicle parc and budget-conscious independent owners. Demand concentrates in Gyeonggi Province's secondary cities where vehicle age averages higher and service intervals remain shorter.
- Semi-Synthetic:Blended formulations balance cost and performance for mid-tier vehicle segments. Hyundai and Kia dealership service centers specify these grades for out-of-warranty vehicles.
- Biodegradable:Plant-derived base stocks address MFDS environmental compliance for sensitive watershed zones. Limited adoption in Jeju Island's eco-tourism vehicle fleets.
Established volume favors synthetic formulations; emerging adoption favors biodegradable alternatives in regulated zones.
Vehicle Type:
Application intensity varies by powertrain thermal load and operating duty cycle across South Korea's passenger fleet.
- Passenger Car:Compact and mid-size sedans dominate Seoul's vehicle registry with standardized 0W-20 and 5W-30 viscosity requirements. High-density service center networks in the capital sustain predictable lubricant consumption patterns.
- SUV:Larger displacement engines and all-wheel-drive differentials multiply lubricant touchpoints per vehicle. Gyeonggi Province's suburban family households drive replacement demand for transmission fluids and axle greases.
- Light Truck:Commercial utility vehicles in Busan-Ulsan corridor logistics operations stress lubricants under heavy load cycles. Fleet procurement centralizes volume with direct marketer agreements.
- Sports Car:High-performance engines demand ester-full synthetics with racing-grade thermal thresholds. Niche volume concentrates in Gangnam district specialty service centers.
Passenger car volume anchors procurement scale; SUV multi-fluid requirements expand revenue per vehicle.
Application:
Functional criticality and replacement frequency create divergent margin profiles across lubricant touchpoints.
- Engine Oil:Primary friction-reduction fluid for internal combustion powertrains with the shortest standard drain intervals. Synthetic grades command premium positioning through OEM certification requirements.
- Transmission Fluid:Automated manual and dual-clutch systems require specification-precise formulations with extended service life. Technology complexity limits substitution and sustains margins.
- Brake Fluid:Hygroscopic hydraulic fluid requiring periodic replacement per KSA safety protocols. Volume correlates with vehicle age rather than mileage accumulation.
- Grease:Semi-solid lubricants for chassis joints, wheel bearings, and suspension components. Heavy-duty applications in commercial fleets sustain steady demand.
Engine oil generates the largest absolute volume; transmission fluid delivers the highest margin per liter.
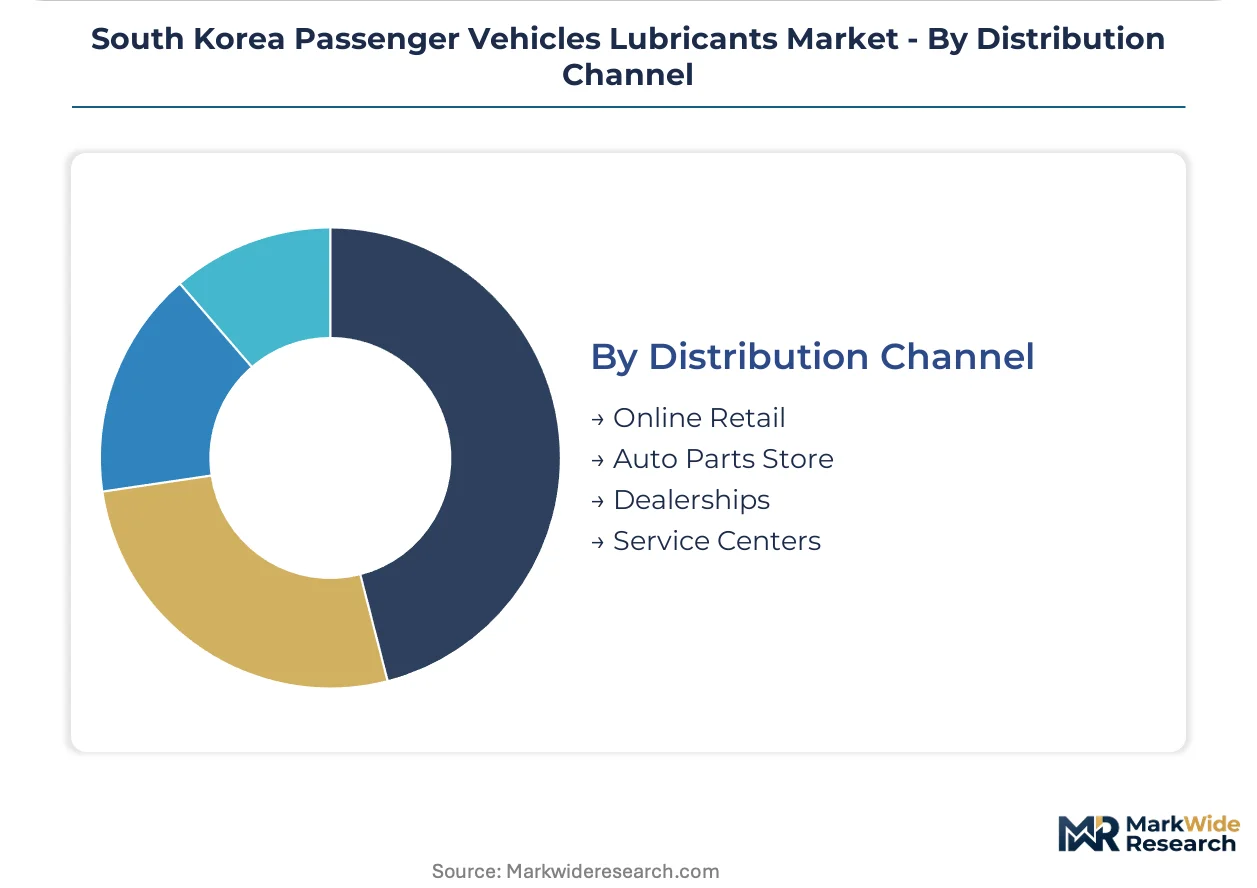
Distribution Channel:
Customer type and purchase urgency determine channel selection across South Korea's lubricant procurement landscape.
- Online Retail:E-commerce platforms capture digitally native vehicle owners in Seoul's younger demographic segments. Subscription-based automatic replenishment models are gaining transaction share.
- Auto Parts Store:Independent retailers serve DIY maintenance culture in secondary cities with price-transparent bulk packaging. Inventory breadth determines competitive positioning.
- Dealerships:Captive service operations enforce OEM-specified lubricant grades to preserve warranty coverage. Parent-company alignment locks in supply relationships.
- Service Centers:Multi-brand maintenance networks dominate Gyeonggi Province with integrated inspection and fluid replacement services. Fleet management software integration is becoming a procurement prerequisite.
Service centers retain the largest volume share; online retail is climbing the fastest among channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's lubricant trade balance tilts toward domestic sufficiency, with base oil refining capacity concentrated on the southeast coast and formulation blending distributed across inland demand clusters. Export volumes flow primarily to Southeast Asian automotive assembly markets, while specialty additive imports satisfy low-viscosity formulation requirements.
Seoul Capital Area
Fleet operators and ride-hailing services in Seoul and Gyeonggi Province drive concentrated lubricant procurement through high vehicle utilization rates. MFDS chemical registration protocols enforce additive package disclosure requirements that extend time-to-market for imported formulations. The dense service center network in Seoul's metropolitan core sustains predictable synthetic lubricant consumption patterns among corporate fleet managers.
Busan-Ulsan
Heavy manufacturing and port logistics clusters generate fleet lubricant demand underserved by Seoul-centric distribution networks. KSA quality certifications administered from national headquarters affect product approval timelines for regional blenders. Ulsan's petrochemical complex anchors domestic base oil supply, reducing feedstock transport costs for southeastern formulators.
Daegu-Gyeongbuk
Automotive component manufacturing in the Daegu-Gyeongbuk region creates industrial lubricant adjacencies to passenger vehicle formulations. The Presidential Committee on Carbon Neutrality mandates are redirecting refinery investment toward lower-carbon base oil sourcing in this industrial corridor. Daegu's machinery sector sustains steady grease demand for equipment maintenance.
Daejeon-Sejong
Government administrative concentration in Sejong drives corporate fleet standardization toward OEM-certified lubricant specifications. Public procurement guidelines favor domestic suppliers meeting KSA certification thresholds. Daejeon's research institutions support additive chemistry development for next-generation low-viscosity formulations.
Gwangju-Honam
Jeju Island's eco-tourism vehicle fleets pilot biodegradable lubricant adoption under MFDS environmental compliance frameworks for sensitive watershed zones. Limited volume concentrates in rental car and tour bus segments. The Honam region's agricultural economy sustains older vehicle parc with conventional mineral oil demand.
South Korea Passenger Vehicles Lubricants Market Competitive Landscape
On the supply side, the industry is consolidated around domestic refining conglomerates with integrated base oil production and captive distribution networks. Three strategic archetypes dominate: refinery-integrated formulators controlling upstream feedstock costs, multinational marketers leveraging global additive technology portfolios, and regional blenders serving price-sensitive secondary markets. Competitive moves center on warranty-aligned OEM partnerships and service center software integration.
Among refinery-integrated players, SK Lubricants Co. Ltd, GS Caltex, and Hyundai Oilbank exemplify the domestic archetype that leverages captive base oil supply and parent-company vehicle warranty specifications. SK Lubricants Co. Ltd occupies a position reflecting synthetic formulation specialization. GS Caltex anchors integrated service center partnerships. Hyundai Oilbank sits within the OEM-captive tier. Multinational representation includes ExxonMobil Corporation, BP PLC (Castrol), and Shell plc, which import additive packages and compete on global technology transfer. S-Oil Corporation and Michang Oil Ind Co. Ltd represent mid-scale domestic blenders with regional distribution density.
| Leading Market Players |
|---|
| GS Caltex |
| Hyundai Oilbank |
| S-Oil Corporation |
| SK Lubricants Co. Ltd |
| ExxonMobil Corporation |
| BP PLC (Castrol) |
| Michang Oil Ind Co. Ltd |
| Shell plc |
| AMSOIL Inc. |
| Others |
Value Network & Pricing Analysis
Busan-Ulsan corridor freight costs feed directly into base oil pricing differentials between southeastern refiners and Seoul-Gyeonggi blenders, concentrating margin advantage with Ulsan petrochemical complex operators who supply synthetic formulations downstream. This logistics geometry enables refinery-integrated players to extract premium positioning through captive feedstock access while independent marketers absorb transport cost layering.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in South Korea's passenger vehicle lubricant market. Price differentiation centers on KSA certification tier and volume procurement scale, with fleet operators commanding steepest discounts through direct supply agreements. Pricing pressure stems from REACH-equivalent additive registration costs elevating importer cost positions against domestic formulators. Independent service centers exhibit highest price sensitivity; OEM-captive dealership channels demonstrate lowest elasticity due to warranty compliance requirements.
Supply Chain Analysis
Extended payment terms from domestic refiners to additive package suppliers compress working capital cycles for formulation blenders without integrated base oil production. Geographic supply concentration rests on South Korea, Japan, and Singapore for Group III+ base oil and performance additive inputs. Raw material dependencies include poly-alpha-olefin base stocks, molybdenum friction modifiers, and viscosity index improvers. Single-source vulnerability concentrates in specialized ester base stocks imported from Japanese chemical producers. Distribution runs through service center networks in Seoul metropolitan area and direct fleet agreements in Busan-Ulsan corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's passenger vehicle lubricant market functions as a service-attach opportunity where predictive maintenance subscriptions and sensor-enabled drain interval optimization expand recurring revenue faster than standalone product sales. Fleet management software integration represents the fastest-growing after-sales layer as operating lease penetration centralizes procurement decisions.
For Market Incumbents: Insulate synthetic formulation margins by deepening backward integration into Group III+ base oil production at Ulsan complex facilities. Secure API-compatible data exchange partnerships with fleet management platforms before independent software vendors capture service center procurement interfaces. Electric vehicle lubricant volume erosion poses the primary substitution threat requiring thermal management fluid diversification.
For New Entrants and Emerging Players: Build out biodegradable lubricant supply relationships with Jeju Island rental fleet operators where MFDS watershed compliance creates protected demand pockets. Target Busan-Ulsan logistics corridor fleet operators underserved by Seoul-centric distribution infrastructure. Pursue KSA certification fast-track programs to compress time-to-market against established domestic formulators.
For Investors and Strategic Acquirers: Regional blenders with Gyeonggi Province service center density and established KSA relationships represent acquisition targets with defensive positioning against multinational entrants. Long-term viability across the projection horizon hinges on thermal management fluid capabilities for hybrid-electric powertrains displacing conventional engine oil volume. Monitor Presidential Committee on Carbon Neutrality refinery investment announcements as inflection signal for base oil sourcing economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Production | Ulsan complex expansion secures feedstock cost advantage against imported Group III+ supply. |
| Fleet Management Software Partnership | API-compatible data exchange locks in recurring procurement from centralized fleet operators. |
| Biodegradable Formulation Certification | MFDS watershed compliance opens protected Jeju Island rental fleet demand segment. |
| KSA Fast-Track Registration Program | Compressed approval timelines enable competitive response to REACH-equivalent burden on importers. |
| Thermal Management Fluid Development | Hybrid-electric powertrain diversification offsets engine oil volume erosion from battery electric penetration. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, KSA certification registries, refinery capacity disclosures, and vehicle registration databases. Primary interviews engaged lubricant formulation chemists, fleet procurement managers at ride-hailing operators, service center network directors, and MFDS regulatory compliance officers. Secondary validation drew from Korea Petroleum Association production statistics, Presidential Committee on Carbon Neutrality policy briefs, and OEM technical service bulletins. Bottom-up volume modeling triangulates against top-down value estimates from channel margin analysis.
Forecast inputs include vehicle parc segmentation by powertrain architecture, synthetic penetration rates by OEM fill specification, and fleet operator consolidation trajectories across the analysis window. Segmentation dimensions span lubricant chemistry tier, vehicle class, application type, and procurement channel. CAGRs derive from regression analysis against historical volume elasticity to vehicle miles traveled and service interval extension trends. Industry-specific inputs incorporate MFDS chemical registration timeline assumptions and electric vehicle adoption curve sensitivity.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese base oil exporters or accelerated battery electric penetration beyond current policy trajectories would shift outcomes. Macroeconomic contraction compressing fleet utilization rates, regulatory tightening on additive chemistries, or breakthroughs in solid-state battery commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Garage Body Shop Equipment Market
Automotive Parts
Automotive Fuel Nozzle Market
Automotive Parts
Automotive Brake by Wire Pedal Simulator Market
Automotive Parts
Global Passenger Vehicles Lubricants Market
Automotive Parts
Mexico Automotive Parts Die Casting Market
Automotive Parts
Autocatalyst Market
Automotive Parts
Luxury Car Hoses Market
Automotive Parts
Global Automotive Leaf Spring Market
Automotive Parts
Automotive Tire Molds Market
Automotive Parts
India Automotive Hydraulic Actuators Market
Automotive Parts
Automotive Seat Adjusters Market
Automotive Parts
Automotive Engine Cooling Fan Market
Automotive Parts
North America Passenger Vehicles Lubricants Market
Automotive Parts
Global Automotive Parts Remanufacturing Market
Automotive Parts
Japan Commercial Vehicles Lubricants Market
Automotive Parts
South Africa Passenger Vehicles Lubricants Market