
 South Korea Luxury Residential Real Estate Market | 2026-2036
South Korea Luxury Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Luxury Residential Real Estate Market Analytics
MFDS green building certification thresholds is hardening the cost-of-entry calculus for new luxury developments in Seoul. Samsung C&T Corporation leverages its integrated design-build capability to pre-certify projects before land acquisition closes. HDC Hyundai Development anchors its pipeline in Hannam-dong and Seongsu-dong through long-dated land banking positions. GS E&C competes on structural engineering depth, particularly for high-rise branded residences exceeding fifty stories.
South Korea luxury residential real estate comprises premium dwelling units commanding price multiples above standard housing, typically featuring reinforced concrete or steel-frame construction with floor-to-ceiling glazing ratios exceeding sixty percent, smart home integration, and concierge-grade service layers designed for wealth preservation and lifestyle utility. Condominiums dominate transaction volume across Seoul's prime districts, while penthouses capture the deepest margin pools per square meter. Single-family homes in Gyeonggi-do's satellite enclaves sustain the fastest price appreciation trajectory as remote-work patterns reshape locational preferences.
MFDS building energy codes, K-LEED certification mandates from the Ministry of Land, Infrastructure and Transport, and Seoul Metropolitan Government's urban planning ordinances collectively elevate material specifications and delay approvals for non-compliant designs. Foreign buyer quotas administered by the Korea Immigration Service restrict transaction velocity in designated zones, channeling demand toward pre-construction allocations. Stakeholders must monitor how Sejong City's special deregulation zone experiments alter the regulatory perimeter for cross-border capital deployment.
Market Dynamics
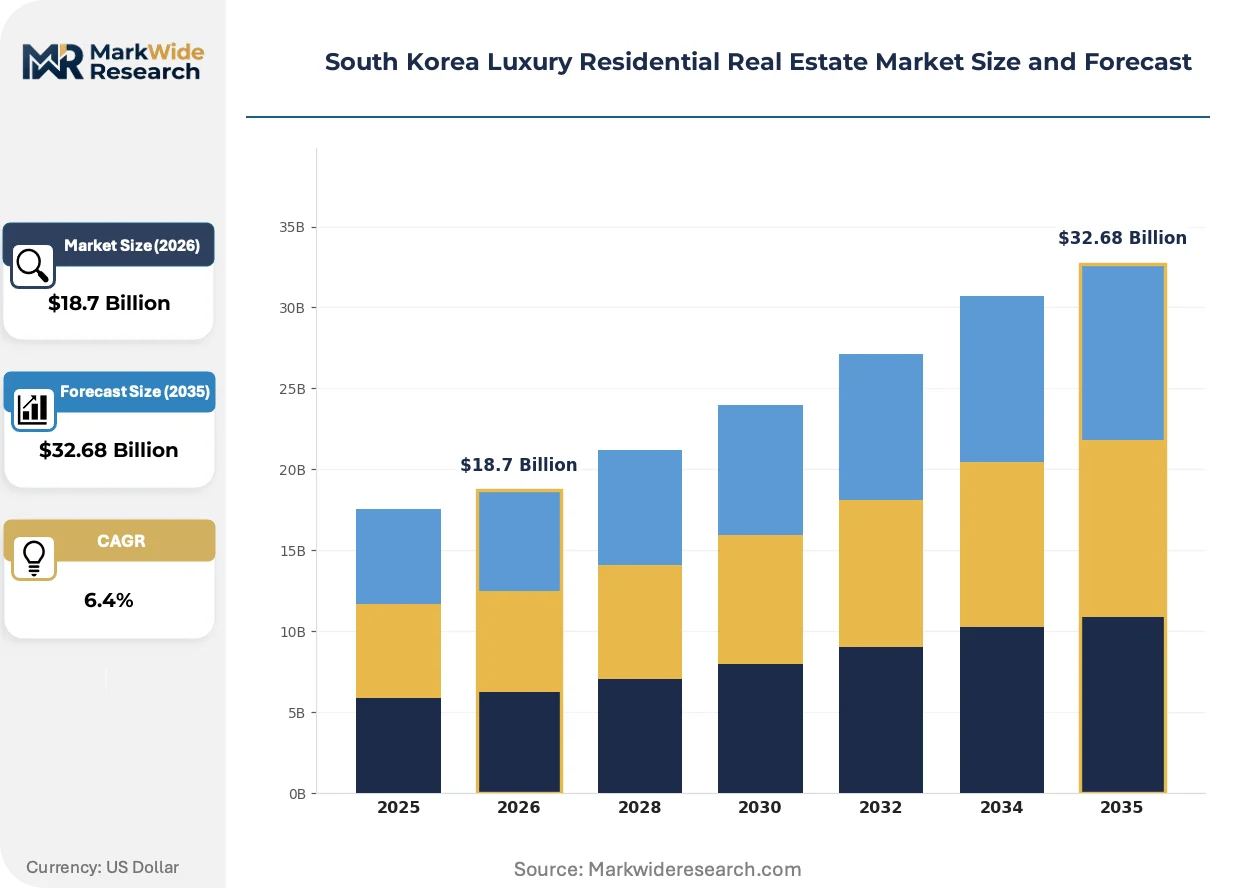
The Ministry of Land, Infrastructure and Transport's floor area ratio enforcement is compressing new supply pipelines while ultra-high-net-worth buyers concentrate demand in Hannam-dong and Seongsu-dong micro-markets. This regulatory tightening against foreign buyer quotas and green certification mandates is restructuring developer capital allocation and pre-construction marketing timelines.
Growth Catalysts
- Branded residence penetration:Ultra-high-net-worth individuals from Gangnam and Sejong corridors are expanding portfolio allocations into managed service-layer dwellings with concierge infrastructure.
- MFDS green certification premiums:K-LEED thresholds are hardening entry calculus and rewarding early certification adopters with pricing power in prime Seoul districts.
- Remote-work locational reshaping:Single-family home demand in Gyeonggi-do satellite enclaves is sustaining price appreciation velocity as household formation patterns decentralize.
Market Restraints
- Floor area ratio compression:Ministry of Land, Infrastructure and Transport enforcement is reducing developable density and extending project timelines for new luxury supply.
- Foreign buyer quota friction:Korea Immigration Service restrictions in designated zones are channeling transaction velocity toward pre-construction allocations with extended settlement risk.
- Material specification cost elevation:MFDS building energy codes and Seoul Metropolitan Government ordinances are elevating glazing and HVAC system costs above standard construction benchmarks.
Strategic Opportunities
- Sejong special deregulation zone:Regulatory perimeter experiments for cross-border capital deployment are creating jurisdictional arbitrage for institutional investors.
- Smart home convergence:Integration of IoT infrastructure with concierge-grade service layers is enabling new revenue streams from dwelling-as-platform models.
- Pre-certification land banking:Developers securing MFDS and K-LEED pre-certification before land acquisition closes are compressing approval timelines and reducing carry costs.
Industry Challenges
- Integrated design-build talent scarcity:Capability gaps in pre-certification project management are extending staffing timelines and inflating compensation for qualified development managers.
- Green certification compliance velocity:MFDS and Seoul Metropolitan Government approval delays for non-compliant designs are compressing developer working capital cycles and pre-sales windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Luxury Residential Real Estate Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Condominiums, Villas, Single-family Homes, Penthouses Amenities: Swimming Pools, Fitness Centers, Private Gardens, Concierge Services Buyer Type: Local Investors, Foreign Buyers, High-net-worth Individuals, expats Development Stage: New Developments, Pre-owned Properties, Under Construction, Renovated Listings |
| Companies Covered | GS E&C, Daewoo Engineering & Construction, Samsung C&T Corporation, Hoban Construction, KyeRyong Construction Industrial, HDC Hyundai Development, POSCO E&C, DL Construction, Lotte E&C, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Luxury Residential Real Estate Market Evolving Landscape
Digital infrastructure integration and regulatory compliance automation are restructuring how luxury residential projects secure approvals and attract capital. Developers are racing to embed certification-ready specifications into earliest design phases.
Building energy management systems with AI-driven HVAC optimization are automating compliance documentation for MFDS and K-LEED submissions. Samsung C&T Corporation and HDC Hyundai Development are deploying these platforms across pre-construction phases to compress approval timelines. The technology is automating previously manual energy modeling workflows that once required six-month consultant engagements.
Seoul Metropolitan Government's urban planning ordinances now mandate post-occupancy energy performance verification for buildings exceeding fifty stories. Developers must install permanent sensor infrastructure rather than relying on design-phase projections. High-rise branded residences in Gangnam and Seongsu-dong are absorbing these capex requirements into base pricing.
Ultra-high-net-worth buyers are consolidating purchase decisions around pre-construction allocations rather than secondary market transactions. Foreign buyer quotas administered by the Korea Immigration Service have disrupted immediate settlement expectations. Hannam-dong and Seongsu-dong developments are responding with extended payment structures and guaranteed buyback clauses to secure early capital commitments.
South Korea Luxury Residential Real Estate Market Segmentation
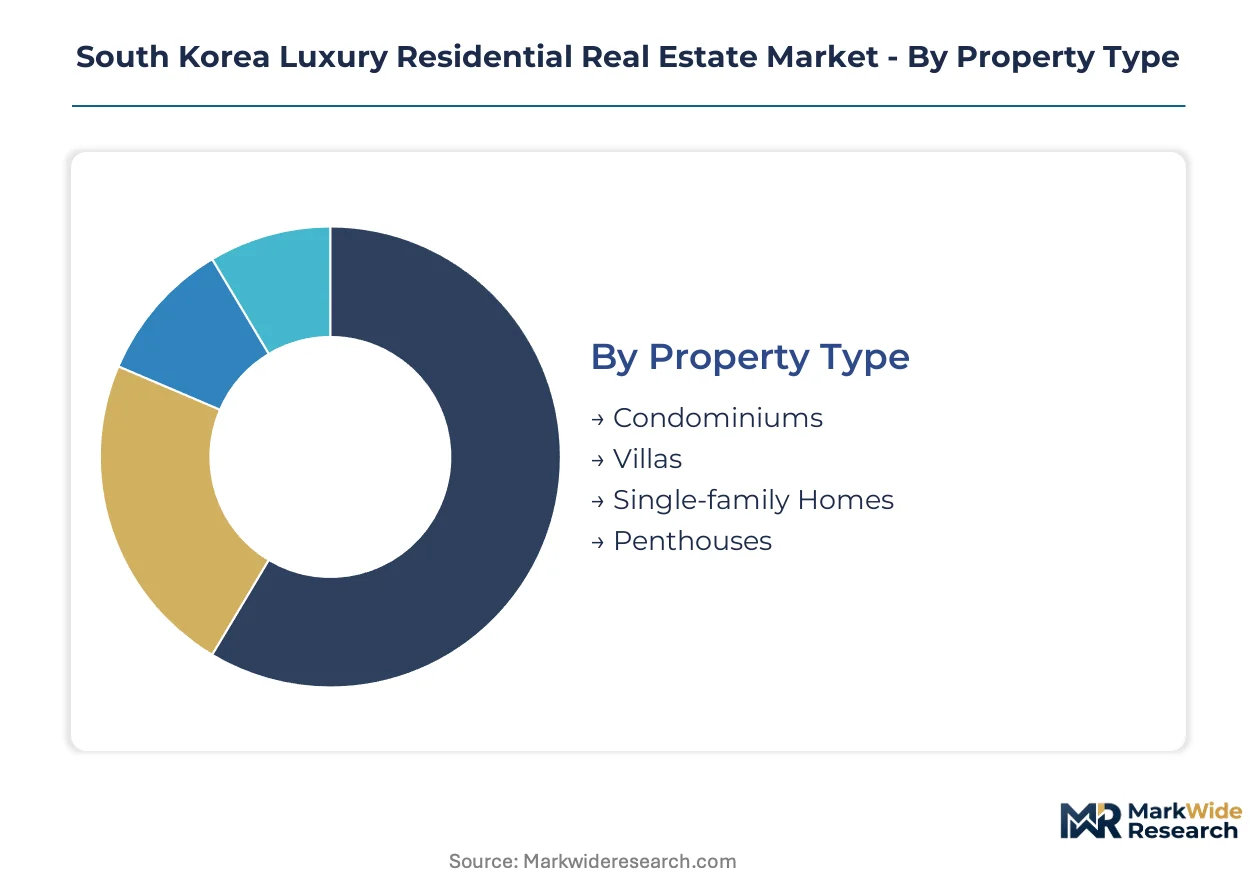
Segmentation reveals how MFDS certification tiers and foreign buyer quotas reshape capital allocation across South Korea's luxury residential pipeline. Developers calibrate pre-construction marketing to match buyer liquidity profiles and settlement timeline preferences.
Property Type:
Buyer liquidity horizons and service-layer expectations differentiate demand across structural categories.
- Condominiums:Reinforced concrete or steel-frame construction with floor-to-ceiling glazing exceeding sixty percent dominates transaction velocity across Seoul's prime districts. Hannam-dong and Seongsu-dong micro-markets concentrate pre-construction allocations as ultra-high-net-worth buyers seek concierge-grade service layers for wealth preservation.
- Penthouses:Top-floor configurations with private elevator access and dedicated HVAC zones capture the deepest margin pools per square meter. Foreign buyer quotas in designated zones channel demand toward extended payment structures with guaranteed buyback clauses.
- Villas:Low-density courtyard configurations in Sejong corridor satellite enclaves attract portfolio diversification from Gangnam-based principals.
- Single-family Homes:Gyeonggi-do satellite enclaves sustain the steepest price appreciation trajectory as remote-work patterns decentralize household formation preferences.
Condominiums lead volumes today; single-family homes are gaining share fastest.
Amenities:
Service-layer sophistication determines pricing power and pre-sales velocity in Seoul's certified developments.
- Concierge Services:Managed service-layer dwellings with 24-hour staffing and lifestyle coordination command premium multiples in branded residence pipelines. Samsung C&T Corporation and HDC Hyundai Development embed these specifications into earliest design phases to compress MFDS approval timelines.
- Private Gardens:Landscaped outdoor space with automated irrigation and climate-controlled greenhouses differentiates ground-floor and villa inventory in Gyeonggi-do enclaves. Seoul Metropolitan Government ordinances mandate permanent sensor infrastructure for post-occupancy verification.
- Swimming Pools:Indoor temperature-controlled configurations with AI-driven energy management automate compliance documentation for K-LEED submissions.
- Fitness Centers:Integrated wellness infrastructure with biometric access and personalized training platforms enables dwelling-as-platform revenue streams.
Concierge services anchor premium positioning; private gardens are expanding most quickly in satellite markets.
Buyer Type:
Capital source and settlement flexibility reshape developer pre-construction marketing timelines.
- High-net-worth Individuals:Domestic principals from Seoul's Gangnam corridor deploy portfolio allocations into pre-certified developments before land acquisition closes. GS E&C targets this segment with structural engineering depth for high-rise inventory exceeding fifty stories.
- Foreign Buyers:Korea Immigration Service quotas in designated zones disrupt immediate settlement expectations and extend capital commitment horizons. Hannam-dong developments respond with phased payment structures securing early allocations.
- Local Investors:Seoul-based principals seeking rental yield concentrate in Seongsu-dong micro-markets with green certification premiums.
- Expats:Corporate assignees prioritize concierge-integrated condominiums with flexible lease-back arrangements.
High-net-worth individuals drive pre-construction absorption; foreign buyers are climbing the fastest despite quota friction.
Development Stage:
Risk-return profiles and certification timing differentiate capital deployment across project lifecycles.
- New Developments:Ground-up construction with integrated MFDS and K-LEED pre-certification compresses approval timelines and reduces developer carry costs. Floor area ratio enforcement from the Ministry of Land, Infrastructure and Transport compresses new supply pipelines and extends project timelines.
- Under Construction:Partially completed inventory with confirmed certification status attracts buyers seeking shorter settlement horizons than greenfield allocations.
- Pre-owned Properties:Secondary market transactions in non-quota zones offer immediate settlement for foreign capital.
- Renovated Listings:Retrofitted inventory with smart home integration and energy management system upgrades targets price-sensitive segments in established districts.
New developments command premium pricing; under construction inventory is expanding most quickly as buyers seek certification certainty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul's concentrated development management talent anchors national pipeline execution, with certified project managers migrating between Gangnam corridor firms and Sejong satellite operations. This workforce mobility transfers pre-certification methodologies across sub-regional markets.
Seoul Capital Area
Hannam-dong and Seongsu-dong micro-markets concentrate ultra-high-net-worth buyer demand for branded residences with concierge infrastructure. Seoul Metropolitan Government urban planning ordinances mandate permanent sensor infrastructure for post-occupancy energy verification in buildings exceeding fifty stories. Gangnam corridor developers leverage integrated design-build capabilities to pre-certify projects before land acquisition closes.
Busan-Ulsan
Maritime industry principals deploy portfolio capital into waterfront condominium developments with smart home integration. MFDS building energy codes elevate glazing specifications for coastal exposure conditions. Haeundae district projects absorb these material cost premiums into base pricing for foreign buyer segments.
Daejeon-Sejong
Sejong City's special deregulation zone experiments attract institutional capital seeking jurisdictional arbitrage for cross-border deployment. Ministry of Land, Infrastructure and Transport floor area ratio enforcement compresses developable density less severely here than in Seoul. Government complex proximity sustains rental yield demand from civil servant households.
Daegu-Gyeongbuk
Textile and electronics manufacturing wealth concentrates demand in low-density villa configurations. K-LEED certification thresholds from the Ministry of Land, Infrastructure and Transport extend approval timelines for non-compliant designs. Gyeongsan satellite enclaves capture decentralizing household formation preferences with single-family home inventory.
Gwangju-Honam
Agricultural and food processing capital seeks portfolio diversification into certified residential developments. Regional MFDS enforcement operates with longer consultant engagement timelines than Seoul Metropolitan Government counterparts. Naju and Suncheon greenfield sites attract pre-construction allocations from yield-focused domestic investors.
South Korea Luxury Residential Real Estate Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across South Korea's luxury residential pipeline. The market structure tiers around three strategic archetypes: integrated design-build conglomerates with captive certification capabilities, mid-scale developers anchoring specific sub-regional corridors, and construction-focused contractors supplying structural engineering depth to third-party projects. Dominant competitive moves include pre-certification land banking to compress approval timelines and long-dated strategic partnerships with foreign capital sources to navigate buyer quota restrictions.
Among Seoul-based integrated conglomerates, Samsung C&T Corporation and HDC Hyundai Development exemplify the design-build archetype with early-phase certification integration. GS E&C occupies a position on the structural engineering specialist tier, particularly for high-rise inventory exceeding fifty stories. These three anchors represent divergent capital deployment strategies: certification-led speed-to-market versus engineering-led vertical complexity.
| Leading Market Players |
|---|
| GS E&C |
| Daewoo Engineering & Construction |
| Samsung C&T Corporation |
| Hoban Construction |
| KyeRyong Construction Industrial |
| HDC Hyundai Development |
| POSCO E&C |
| DL Construction |
| Lotte E&C |
| Others |
Value Network & Pricing Analysis
Steel rebar futures and architectural glass spot indices cascade through South Korea's luxury residential supply chain into three distinct pricing tiers. MFDS certification premiums and floor area ratio scarcity compress margins at the base tier while amplifying pricing power for pre-certified developments in Hannam-dong and Seongsu-dong micro-markets.
Pricing Analysis
Service unbundling separates base construction costs from concierge infrastructure and energy management system premiums. K-LEED certification tiers and smart home integration depth drive price differentiation across Seoul's prime districts. Pricing pressure stems from Ministry of Land, Infrastructure and Transport floor area ratio enforcement extending project timelines and inflating carry costs. Foreign buyers under quota restrictions exhibit lowest price sensitivity due to extended settlement horizons and guaranteed buyback structures, while domestic yield-focused investors in Seongsu-dong resist premium markups without certification certainty.
Supply Chain Analysis
High-performance glazing supply rests on Japanese and German specialty manufacturers with limited South Korean domestic alternatives. Reinforced concrete and steel frame inputs draw from domestic POSCO E&C and imported Chinese structural steel. Single-source vulnerability concentrates in low-emissivity coated glass where three global suppliers dominate Asia-Pacific allocation. Distribution runs through vertically integrated conglomerates like Samsung C&T Corporation and HDC Hyundai Development with captive logistics networks, compressing third-party contractor margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
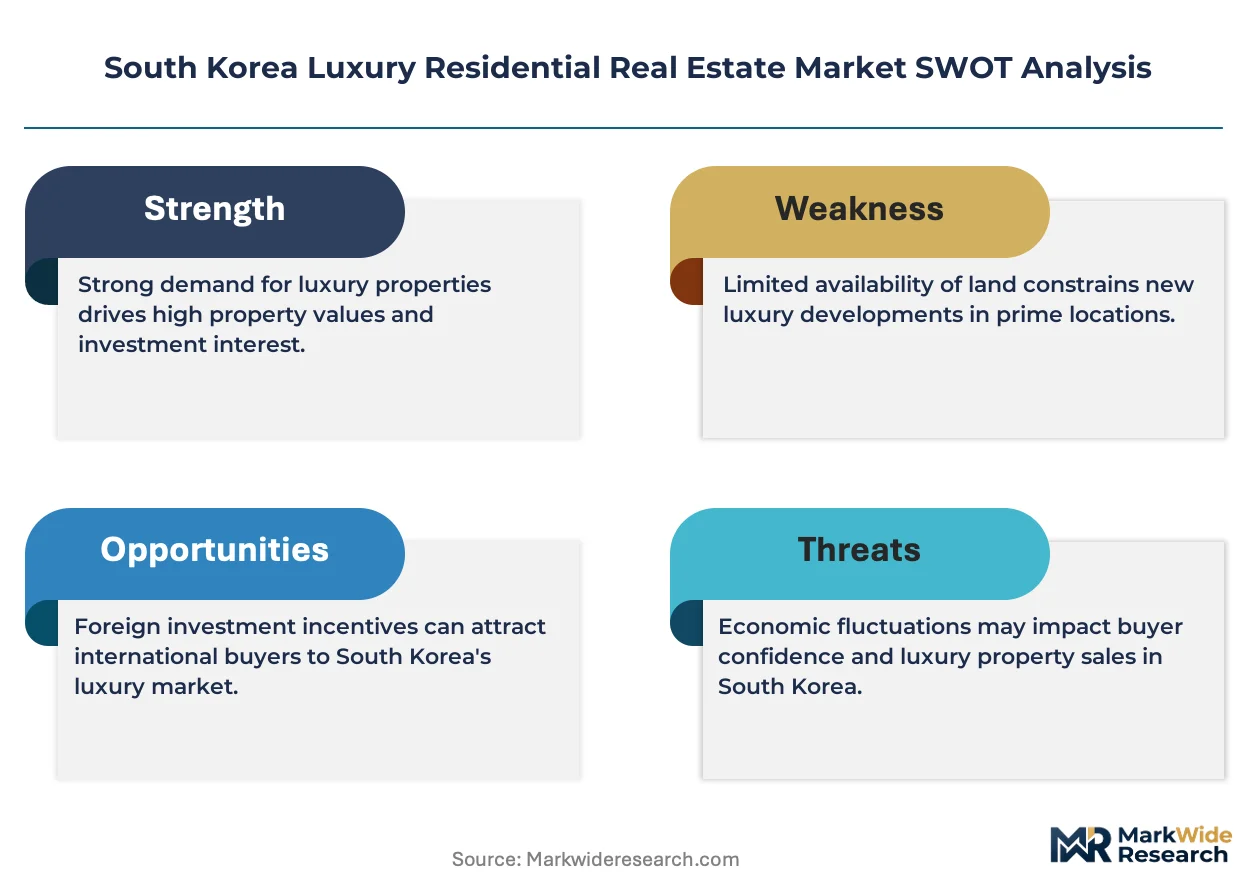
South Korea's luxury residential market functions as a geographic-arbitrage play where Sejong City's special deregulation zone offers floor area ratio relief unavailable in Seoul's compressed supply pipeline. The MFDS certification cost differential between these jurisdictions creates deployable capital advantages for early movers.
For Market Incumbents: Hedge against foreign buyer quota tightening by accelerating pre-construction allocations with extended payment structures. Secure long-dated land banking positions in Sejong corridor satellite enclaves before special zone status normalizes. Vertical integration into AI-driven energy management system development defends margin position against glazing and HVAC cost inflation from Seoul Metropolitan Government ordinances. For New Entrants and Emerging Players: Yield-seeking domestic investors in Seongsu-dong represent an underserved buyer archetype with liquidity for certified inventory below penthouse price thresholds. White-space targets include mid-rise branded residences with concierge-lite service layers and Gyeonggi-do single-family home developments for remote-work households. Go-to-market through pre-certification partnerships with established design-build conglomerates compresses approval timelines without captive capability investment. For Investors and Strategic Acquirers: Consolidation pressure builds where integrated design-build talent scarcity extends project staffing timelines and inflates compensation for qualified development managers. Long-term viability across the analysis window favors developers with captive certification capabilities and Sejong land positions. Acquisition targets include mid-scale regional specialists with Hannam-dong pipeline exposure and pre-certified inventory under construction. Watch MFDS green building code amendments as inflection indicators for capital reallocation between Seoul and satellite markets.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-certification Land Banking | MFDS and K-LEED pre-certification before land acquisition closes compresses approval timelines and reduces carry costs for Seoul developments. |
| Smart Home Platform Integration | IoT infrastructure with concierge-grade service layers enables dwelling-as-platform revenue streams from biometric access and personalized wellness. |
| Sejong Deregulation Zone Positioning | Special zone experiments for cross-border capital deployment create jurisdictional arbitrage with less severe floor area ratio compression. |
| Energy Management System Deployment | AI-driven HVAC optimization automates compliance documentation for MFDS submissions and eliminates six-month consultant engagements. |
| Extended Payment Structure Design | Phased allocations with guaranteed buyback clauses secure early foreign capital commitments despite Korea Immigration Service quota friction. |
Research Methodology
Direct dialogue with luxury residential development executives, MFDS certification consultants, Seoul Metropolitan Government planning officers, and Korea Immigration Service policy leads grounded the qualitative foundation. Secondary validation drew from Ministry of Land, Infrastructure and Transport regulatory filings, Seoul Metropolitan Government urban planning ordinances, K-LEED certification databases, and customs records for structural material imports. Bottom-up project pipeline enumeration and top-down macroeconomic triangulation converged on segment-level estimates.
Bottom-up modeling tracked individual development phases across property type, amenities tier, buyer category, and certification status. Top-down validation referenced national construction permits, foreign buyer transaction quotas, and green building adoption rates. CAGRs emerged from regression against floor area ratio enforcement intensity, remote-work household formation velocity, and branded residence penetration curves. Forecast inputs incorporated MFDS code amendment schedules and Sejong special zone regulatory sunset provisions.
Inputs from regulatory filings and development permit databases were available through the study window; gaps in pre-construction allocation pricing transparency introduce uncertainty bands around foreign buyer segment estimates. Forecasts reflect assumptions regarding continued floor area ratio enforcement and K-LEED threshold escalation. Regulatory relaxation in Sejong, MFDS code delays, or foreign capital flow restrictions could revise trajectory. A small set of triggers—MFDS amendment timing, Sejong zone status renewal, and Gangnam corridor land release volumes—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Residential Real Estate Market
UAE Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Canada Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
United States Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Bahrain Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Italy Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
China Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Oman Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Qatar Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
India Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Switzerland Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Europe Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
China Residential Real Estate Market
Luxury Residential Real Estate Market
Luxury-Minded Retirement Residences Market
Luxury Residential Real Estate Market
Russia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Singapore Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Denmark Luxury Residential Real Estate Market