
 Russia Luxury Residential Real Estate Market | 2026-2036
Russia Luxury Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Luxury Residential Real Estate Market Analytics
Central Bank of Russia mortgage regulation is restructuring the cost-of-entry calculus for luxury buyers, tightening loan-to-value thresholds and stress-testing requirements that filter speculative demand. Capital Group leverages its vertical integration across development and property management to sustain premium pricing power in Moscow's trophy assets. PIK Group anchors its competitive stance through standardized luxury design systems that reduce construction cycle variability. Etalon Group differentiates via geographic diversification across Moscow, Saint Petersburg, and Krasnodar, reducing single-city exposure.
Russia luxury residential real estate comprises high-end dwellings priced above mass-market thresholds, typically featuring premium materials, advanced engineering systems, and concierge-level amenities designed for affluent owner-occupiers and portfolio investors. The construction process emphasizes reinforced concrete monolithic frames, low-rise brick-clad facades, and integrated smart-home infrastructure to meet elevated thermal and acoustic standards. Condominium stock dominates transaction volume in Moscow's central business district, while villa developments in Rublyovka and Istra command the deepest margin pools per square meter. New developments attract the most active capital deployment, though resale inventory in historic Arbat and Patriarch's Ponds retains scarcity premiums due to protected architectural status.
Russia's Federal Service for State Registration oversees title transparency and cadastral valuation, while the Ministry of Construction and Housing sets building codes that mandate seismic resistance and energy efficiency benchmarks for premium developments. The Central Bank's macroprudential framework directly shapes buyer leverage capacity, compressing demand elasticity at the ultra-high end where all-cash transactions prevail. Stakeholders must monitor regulatory calibration between capital control enforcement and wealth preservation demand to anticipate liquidity windows.
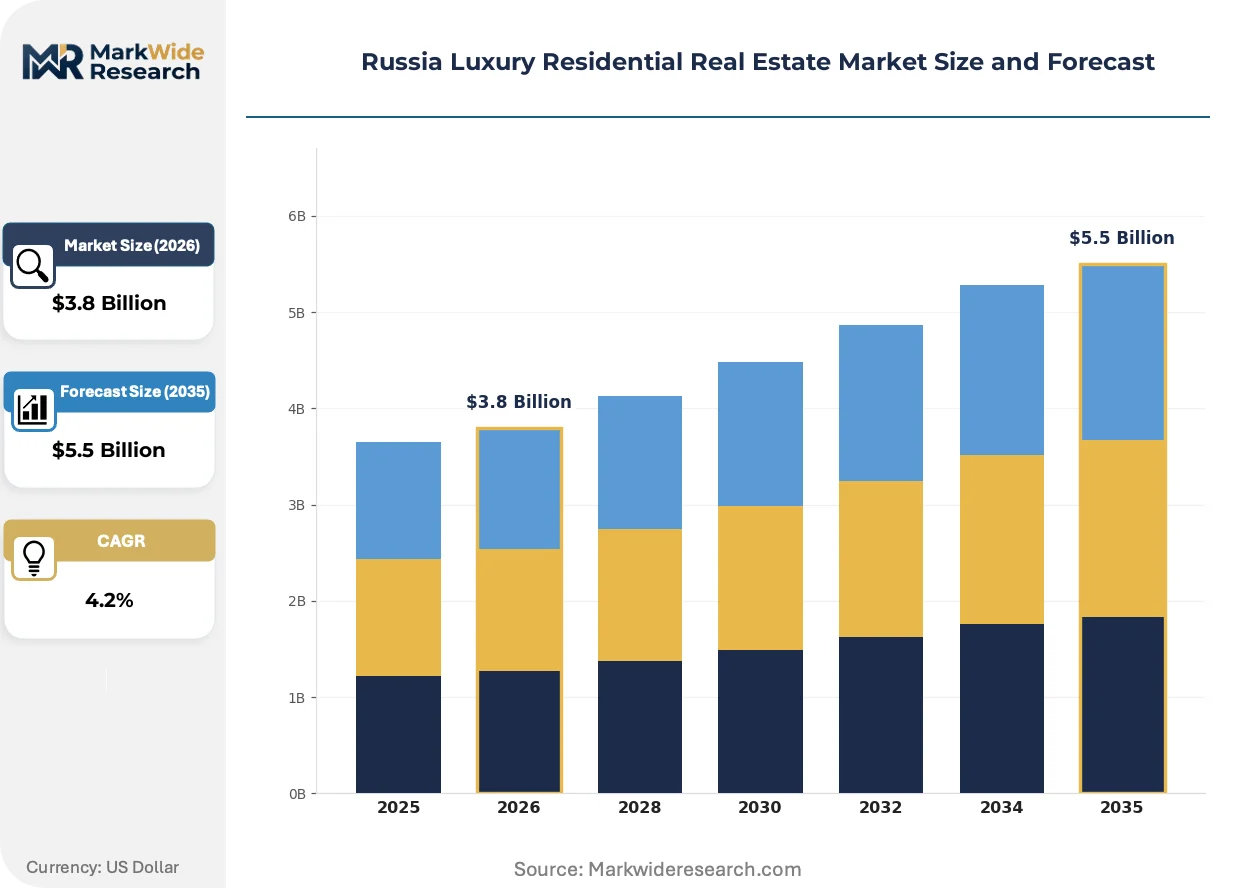
Market Dynamics
The Central Bank of Russia's macroprudential framework is compressing leverage-dependent demand while simultaneously concentrating transaction flow toward all-cash buyers in Moscow's premium corridors. This regulatory calibration is redrawing competitive positioning across developer portfolios.
Growth Catalysts
- Rublyovka corridor scarcity:Protected land-use restrictions around the Istra reservoir zone limit new villa supply, sustaining per-square-meter premiums for existing trophy assets. Moscow-based family offices are consolidating holdings here.
- Smart-home infrastructure mandates:The Ministry of Construction and Housing's updated energy efficiency benchmarks now require integrated building management systems in Class A developments, accelerating technology deployment timelines.
- Wealth preservation demand:Capital control enforcement is redirecting offshore liquidity toward domestically registered real assets, with Moscow City financial district condominiums capturing redirected portfolio allocations.
Market Restraints
- Foreign ownership restrictions:The Federal Law on Foreign Investments in Strategic Enterprises creates title-transfer friction for non-resident buyers, compressing the addressable buyer pool in Saint Petersburg's historic center.
- Construction input volatility:Reinforced concrete and imported facade material costs fluctuate with ruble-denominated procurement exposure, squeezing margin predictability for developers with fixed-price presale contracts.
- Seismic engineering requirements:Updated building codes for high-rise structural resilience add technical complexity and extended approval timelines for Moscow City super-tall projects.
Strategic Opportunities
- Krasnodar corridor expansion:Southern Russia's emerging affluent demographic remains underpenetrated by branded luxury developers, creating first-mover positioning potential for standardized design systems.
- Concierge service unbundling:Property management platforms are disaggregating amenity provisioning from unit sales, enabling recurring revenue streams separate from development cycles.
- Patriarch's Ponds resale arbitrage:Architectural heritage protections prevent new construction in this Moscow micro-district, concentrating scarcity premiums on renovated pre-revolutionary stock.
Industry Challenges
- Cadastral valuation transparency:The Federal Service for State Registration's appraisal methodologies create transaction friction when assessed values diverge from market clearing prices, complicating financing collateralization.
- Project finance tenor compression:Lenders are shortening construction loan durations under macroprudential pressure, forcing developers to accelerate presale velocity or absorb higher working capital costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Luxury Residential Real Estate Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Condominium, Single-Family Home, Townhouse, Villa Market Segment: New Developments, Resale Market, Luxury Rentals, Off-Plan Properties Buyer Type: Domestic Investors, International Buyers, Real Estate Funds, High-Net-Worth Individuals Investment Strategy: Buy and Hold, Short-Term Rentals, Fix-and-Flip, Luxury Development |
| Companies Covered | Etalon Group, Capital Group, PIK Group, Ingrad, SETL Group, LSR Group, Donstroy, Brusnika, Samolet Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Luxury Residential Real Estate Market Evolving Landscape
Digital infrastructure and regulatory calibration are converging to reshape how premium residential assets are designed, transacted, and managed across Russian metropolitan centers.
Integrated building management systems are consolidating climate control, security, and energy monitoring into unified platforms. Developers in Moscow City are specifying these systems as standard fit-out for new condominiums. This technology convergence is integrating operational efficiency into asset valuation models, compressing price premiums for non-smart inventory.
The Central Bank of Russia's stress-testing requirements for high-LTV mortgages are tightening qualification thresholds for luxury buyers. This regulatory calibration is filtering speculative demand from end-user acquisition. Moscow's Rublyovka corridor sees the most pronounced effect, with transaction velocity shifting toward all-cash purchasers.
Buyer behavior is rotating toward turnkey renovation solutions rather than raw-space acquisitions. Moscow and Saint Petersburg developers are responding with design-build packages that compress move-in timelines. This preference shift is most visible among relocated executives in the Moscow City financial district, where time-to-occupancy carries premium value.
Russia Luxury Residential Real Estate Market Segmentation
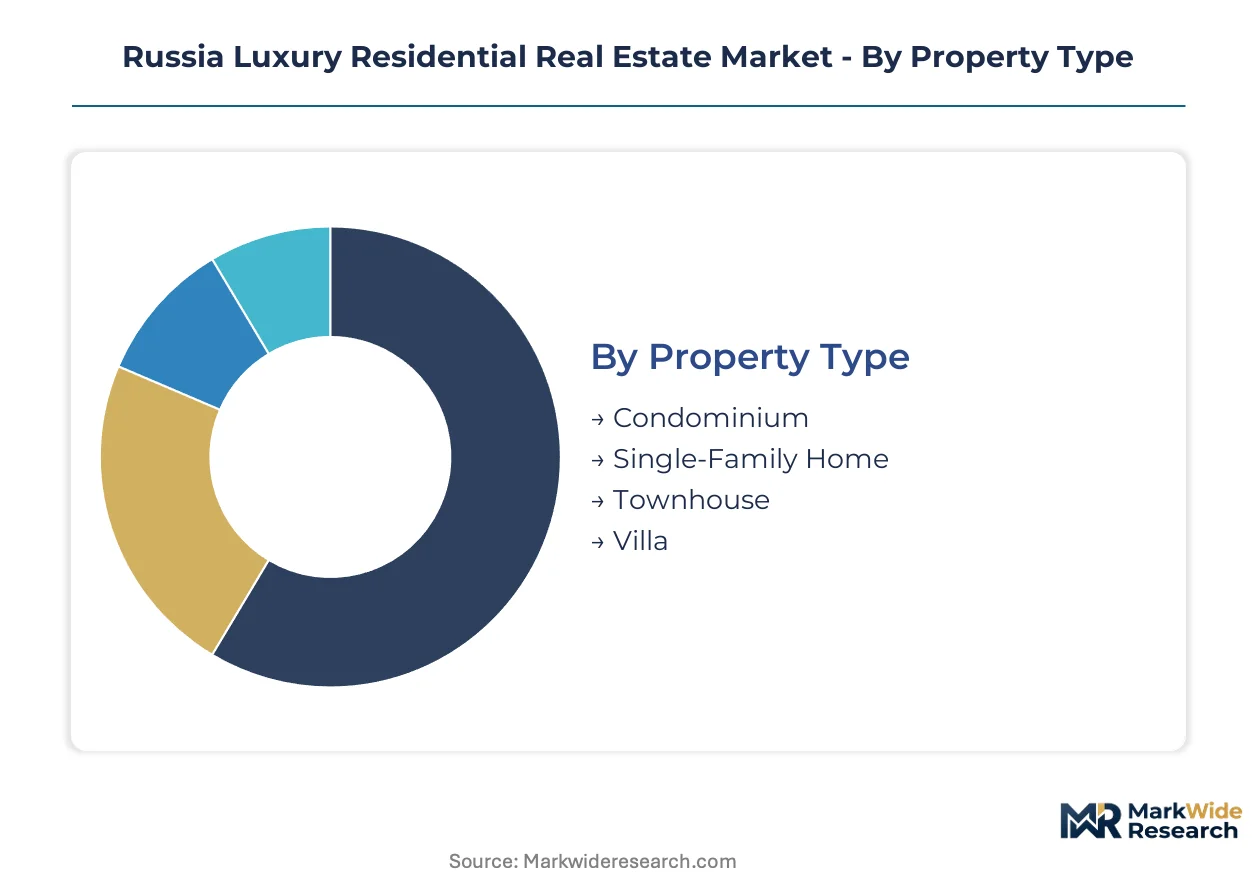
Segmentation in Russia's luxury residential market reveals how capital deployment, regulatory exposure, and buyer liquidity preferences fragment across distinct asset classes. Understanding these divides clarifies where developers concentrate construction pipelines and where transaction velocity concentrates.
Property Type:
Capital intensity peaks with villa construction, where land assembly and bespoke engineering dominate upfront outlays.
- Condominium:Reinforced concrete monolithic frames with integrated smart-home infrastructure dominate Moscow City and central business district developments. Demand concentrates among relocated executives in the financial district where proximity to corporate headquarters compresses time-to-occupancy premiums.
- Single-Family Home:Low-rise brick-clad facades with advanced acoustic engineering characterize Rublyovka corridor offerings. Moscow-based family offices are consolidating holdings here as protected land-use restrictions around the Istra reservoir zone limit new supply.
- Townhouse:Medium-density hybrid construction blending monolithic frames with brick veneer targets Saint Petersburg's emerging affluent demographic.
- Villa:Trophy assets command deepest margin pools per square meter in Istra and select Krasnodar periphery zones.
Most installed capacity flows through Condominium. Expansion is steepest in Villa as scarcity premiums attract portfolio allocations.
Market Segment:
Development risk profiles diverge sharply between presale-dependent new construction and scarcity-constrained resale inventory.
- New Developments:Class A specifications with mandated building management systems attract the most active capital deployment. Moscow developers leverage standardized design systems to reduce construction cycle variability under macroprudential pressure.
- Resale Market:Renovated pre-revolutionary stock in Patriarch's Ponds and historic Arbat retains scarcity premiums due to protected architectural status preventing new construction.
- Luxury Rentals:Concierge-level amenity provisioning targets expatriate executives in Moscow City with turnkey move-in timelines.
- Off-Plan Properties:Fixed-price contracts expose developers to ruble-denominated input volatility while compressing buyer leverage under Central Bank stress-testing requirements.
Transaction volume concentrates in New Developments. Value appreciation is climbing the fastest in Resale Market as heritage protections harden supply constraints.
Buyer Type:
Liquidity sourcing determines transaction velocity and financing structure flexibility across the market.
- Domestic Investors:Wealthy buyers from Moscow and Saint Petersburg are expanding property portfolios despite tighter foreign ownership rules, deploying all-cash to bypass Central Bank leverage constraints.
- International Buyers:Federal Law on Foreign Investments in Strategic Enterprises creates title-transfer friction, compressing the addressable buyer pool in Saint Petersburg's historic center.
- Real Estate Funds:Institutional capital targets stabilized income-producing assets with recurring revenue streams from unbundled concierge services.
- High-Net-Worth Individuals:Capital control enforcement redirects offshore liquidity toward domestically registered real assets, particularly Moscow City condominiums.
Deal flow concentrates with Domestic Investors. Portfolio allocation is expanding most quickly among High-Net-Worth Individuals as wealth preservation demand intensifies.
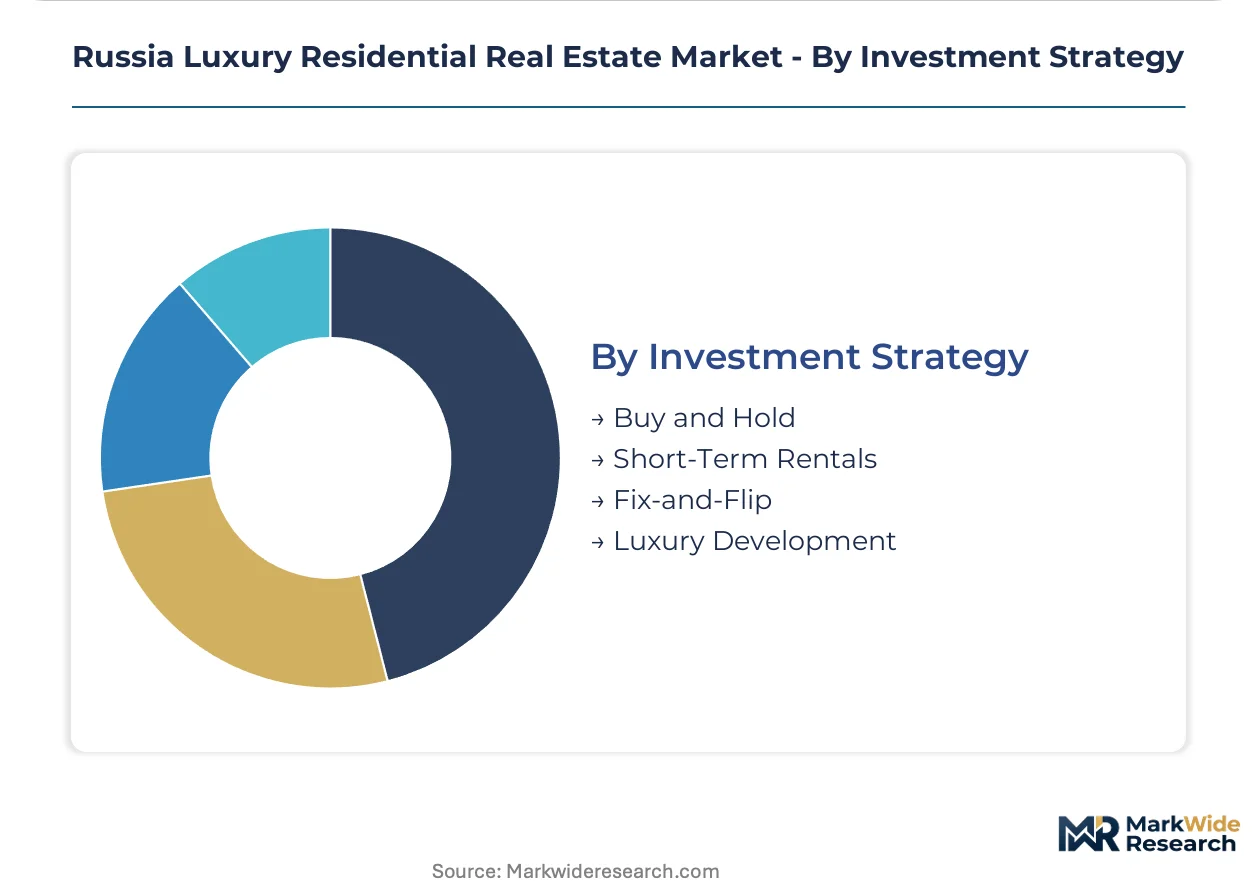
Investment Strategy:
Holding period horizons and operational intensity requirements segment capital into distinct risk-return profiles.
- Buy and Hold:Long-duration ownership captures scarcity premiums in Rublyovka and heritage-protected Moscow micro-districts where supply constraints intensify over time.
- Short-Term Rentals:Operational platforms disaggregate amenity provisioning from unit sales, enabling recurring revenue separate from development cycles.
- Fix-and-Flip:Turnkey renovation solutions compress move-in timelines for time-sensitive buyers in Moscow and Saint Petersburg.
- Luxury Development:Project finance tenor compression under macroprudential policy forces accelerated presale velocity or higher working capital absorption.
Capital deployment concentrates in Buy and Hold. Operational complexity is rising fastest in Short-Term Rentals as service unbundling advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wealthy domestic investors from Moscow and Saint Petersburg anchor the Russia luxury residential real estate market's geographic concentration. The Central Bank of Russia's macroprudential policies on mortgage lending reshape financing access for premium units across key metropolitan corridors.
Moscow
Family offices and high-net-worth individuals drive trophy asset acquisitions in the Rublyovka corridor and Moscow City financial district. The Central Bank of Russia's loan-to-value thresholds filter speculative demand, concentrating transaction flow toward all-cash buyers. Moscow City condominiums capture redirected portfolio allocations as capital control enforcement redirects offshore liquidity toward domestically registered real assets.
Saint Petersburg
Emerging affluent demographics expand property portfolios despite tighter foreign ownership rules under the Federal Law on Foreign Investments in Strategic Enterprises. The Federal Service for State Registration oversees title transparency and cadastral valuation for historic center transactions. Townhouse developments in peripheral districts target buyers seeking medium-density hybrid construction with turnkey move-in timelines.
Krasnodar
Southern Russia's underpenetrated luxury segment attracts first-mover positioning from developers with standardized design systems. The Ministry of Construction and Housing mandates seismic resistance and energy efficiency benchmarks for premium developments in this corridor. Villa projects in select periphery zones command deepening margin pools per square meter as scarcity premiums attract portfolio allocations.
Moscow Oblast
Protected land-use restrictions around the Istra reservoir zone limit new villa supply in the Rublyovka corridor, sustaining per-square-meter premiums. The Ministry of Construction and Housing's updated energy efficiency benchmarks require integrated building management systems in Class A developments. Moscow-based family offices consolidate holdings here as supply constraints intensify over time.
Russia Luxury Residential Real Estate Market Competitive Landscape
The competitive structure tilts toward vertically integrated developers with captive control over construction cycles and property management platforms. A consolidated tier of capital-intensive players dominates Moscow's trophy asset pipeline, while mid-scale specialists occupy geographic diversification niches. Strategic archetypes include integrated development-management platforms, standardized design-system operators, and geographically diversified portfolio builders. Dominant competitive moves encompass backward integration into construction inputs and service unbundling to generate recurring revenue streams separate from development cycles.
Within the integrated platform tier, Capital Group leverages vertical integration across development and property management to sustain premium pricing power in Moscow's trophy assets. PIK Group anchors its competitive stance through standardized luxury design systems that reduce construction cycle variability. Etalon Group exemplifies geographic diversification across Moscow, Saint Petersburg, and Krasnodar, reducing single-city exposure while capturing regional demand fragmentation.
| Leading Market Players |
|---|
| Etalon Group |
| Capital Group |
| PIK Group |
| Ingrad |
| SETL Group |
| LSR Group |
| Donstroy |
| Brusnika |
| Samolet Group |
| Others |
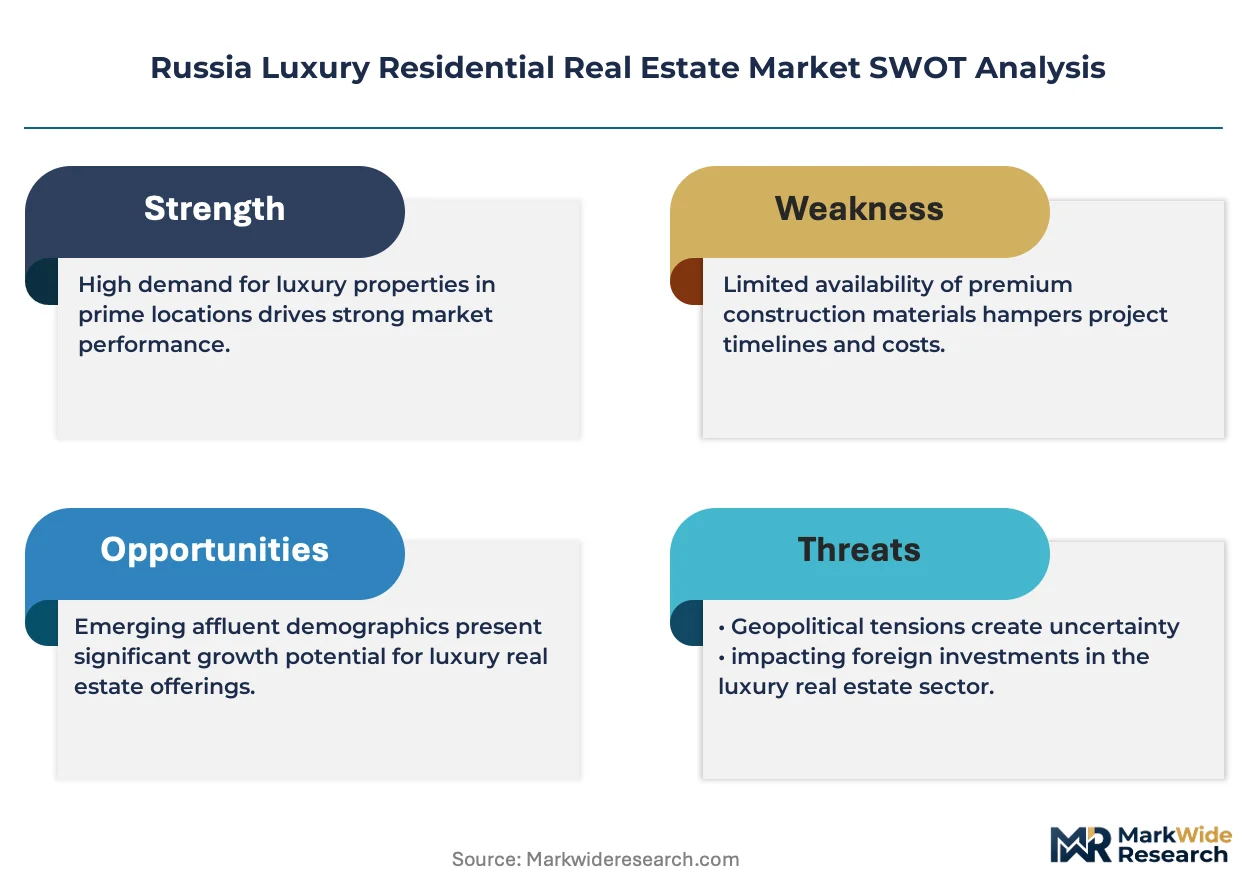
Value Network & Pricing Analysis
Class A specification premiums versus Class B commodity offerings create a sharp bifurcation in Russia's luxury residential market, with this divergence manifesting in both pricing power for trophy assets and supply chain configurations that concentrate high-grade inputs among vertically integrated developers. Moscow City condominiums command unbundled amenity pricing while Rublyovka villas retain bundled land-plus-construction premiums, with each tier sourcing from distinct supplier networks.
Pricing Analysis
Service unbundling now separates base unit pricing from recurring concierge and property management fees. Price differentiation rests on smart-home certification tiers mandated by the Ministry of Construction and Housing and geographic proximity to Moscow's financial district. Pricing pressure stems from ruble-denominated construction input volatility squeezing fixed-price presale margins. Domestic investors show lowest price sensitivity, while leveraged buyers face compressed demand elasticity under Central Bank stress-testing.
Supply Chain Analysis
Direct-to-developer procurement channels handle reinforced concrete and monolithic frame systems for Moscow super-tall projects. Supply concentrates in domestic producers for structural materials, with facade imports drawing from Italy and Germany for premium cladding. Raw material dependencies center on steel reinforcement, low-emissivity glass, and engineered timber. Single-source vulnerability runs through imported building management system controllers. Distribution runs through captive construction subsidiaries at major developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's luxury residential market offers margin expansion through concierge service unbundling and technology-enabled operational efficiency, with premium-tier shift toward turnkey solutions reducing buyer acquisition friction.
For Market Incumbents: Lock in scarcity premiums in Rublyovka and Patriarch's Ponds through accelerated land assembly before regulatory restrictions tighten further. Deepen backward integration into construction inputs to insulate margin predictability from ruble volatility. Threat exposure concentrates in project finance tenor compression forcing accelerated presale velocity or working capital absorption. For New Entrants and Emerging Players: The Ministry of Construction and Housing's updated energy efficiency benchmarks in Moscow Oblast open a window for specialized smart-home system integrators. White-space targets include Krasnodar's underpenetrated villa segment and Saint Petersburg townhouse corridors. Go-to-market positioning should emphasize standardized design-build packages compressing move-in timelines for relocated executives. For Investors and Strategic Acquirers: Consolidation pressure builds where developers lack captive property management platforms and recurring revenue streams. Long-term viability favors vertically integrated players with control over both construction cycles and post-occupancy service monetization. Acquisition target archetype: mid-scale developers with geographic diversification across Moscow, Saint Petersburg, and southern corridors. Signal to watch: Central Bank macroprudential calibration loosening leverage constraints and reactivating mortgage-dependent demand.| Strategic Initiative | Industry Significance |
|---|---|
| Concierge Service Unbundling | Separates amenity revenue from unit sales, creating recurring income streams at Moscow City developments. |
| Smart-Home Platform Integration | Consolidates climate, security, and energy systems to meet Ministry of Construction and Housing mandates. |
| Geographic Expansion to Krasnodar | Captures southern Russia's emerging affluent demographic with standardized villa design systems. |
| Backward Integration into Construction Inputs | Reduces ruble-denominated procurement exposure for developers with fixed-price presale contracts. |
| Heritage Property Renovation Arbitrage | Exploits Patriarch's Ponds supply constraints where architectural protections prevent new construction. |
Research Methodology
Coverage spans Moscow, Saint Petersburg, Krasnodar, and Moscow Oblast, with primary inputs from each metropolitan corridor combined with secondary validation. Interviews with development executives, property management platform operators, Central Bank regulatory affairs specialists, and family office portfolio managers anchor demand-side intelligence. Secondary sources include Federal Service for State Registration cadastral data, Ministry of Construction and Housing building code filings, and Central Bank macroprudential policy circulars. Bottom-up transaction volume analysis triangulates against top-down construction pipeline assessments.
Rate-of-change decomposition separates volume expansion from value appreciation across the projection horizon. Segmentation dimensions modeled include property type, market segment, buyer liquidity sourcing, and investment strategy horizon. CAGRs derive from construction completion schedules, presale velocity patterns, and scarcity premium accumulation in supply-constrained micro-districts. Forecast inputs incorporate Central Bank leverage policy calibration scenarios and capital control enforcement intensity variations.
Revisions become necessary when Central Bank macroprudential thresholds shift, capital control regimes tighten or loosen, or seismic engineering mandates extend approval timelines. Forecasts reflect assumptions about regulatory stability, ruble exchange rate bands, and construction input cost trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Residential Real Estate Market
Saudi Arabia Luxury Market
Luxury Residential Real Estate Market
United States Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
China Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Europe Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Qatar Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Netherlands Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Luxury-Minded Retirement Residences Market
Luxury Residential Real Estate Market
GCC Luxury Market
Luxury Residential Real Estate Market
Japan Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Bahrain Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
China Residential Real Estate Market
Luxury Residential Real Estate Market
Canada Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Oman Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Italy Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Belgium Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Sweden Luxury Residential Real Estate Market