
 Switzerland Luxury Residential Real Estate Market | 2026-2036
Switzerland Luxury Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Switzerland Luxury Residential Real Estate Market Insights
Market Context with Strategic Players
Cross-laminated timber is restructuring construction economics for premium Alpine residences, reducing build timelines by one-third against conventional concrete framing. Savills leverages its Geneva and Zurich office network to control prime listing flow across Lake Geneva waterfront inventory. BARNES International anchors its Swiss operations through specialized ski-property advisory in Verbier and Gstaad. UBS Global Wealth Management differentiates by embedding real estate into integrated wealth structures for ultra-high-net-worth clients.
Technical Definition and Structural Segments
Switzerland luxury residential real estate denotes freehold and leasehold dwellings trading above the upper quintile of cantonal price distributions, typically exceeding CHF 3 million, with premium finishes, concierge infrastructure, and proximity to transit or natural amenities. The market serves wealth preservation, lifestyle consumption, and cross-border capital allocation for individuals with liquid assets above CHF 10 million. Single-family homes and villas dominate transaction value in Vaud and Valais cantons, where scarcity of buildable Alpine terrain protects price floors. Condominiums and penthouses lead velocity in Zurich and Geneva urban cores, attracting expat finance professionals under preferential tax regimes. The ultra-premium tier captures disproportionate margin pools, as broker fees and ancillary service contracts scale non-linearly with transaction size.
Regulatory Framework and Forward Outlook
Swiss cantonal zoning authorities, the Federal Office for Spatial Development (ARE), and Lex Koller restrictions on foreign non-resident purchases collectively shape market access and development intensity. Lex Koller quotas limit non-EU buyer access to 1,500 permits annually, concentrating foreign demand in designated tourist zones like Crans-Montana and St. Moritz. ARE spatial planning guidelines enforce density caps that protect rural landscapes but constrain supply elasticity around Zurich and Geneva. Stakeholders must monitor whether pending revisions to the Federal Act on Acquisition of Real Estate by Persons Abroad will tighten further or create carve-outs for sustainability-certified developments.
Market Dynamics
Lex Koller restrictions and cantonal zoning reforms are compressing foreign buyer access while cross-laminated timber construction methods unlock Alpine development economics previously constrained by concrete logistics.
Growth Catalysts
- Cross-laminated timber adoption:Alpine developers are deploying engineered wood systems that reduce build timelines by one-third against conventional concrete framing, unlocking previously uneconomic hillside parcels in Valais and Graubünden.
- Preferential tax regimes:Lump-sum taxation agreements in Vaud and Ticino cantons attract ultra-high-net-worth finance professionals to Geneva and Lugano urban cores, sustaining condominium velocity above CHF 5 million.
- Asian and Middle Eastern capital rotation:Family offices from Singapore and Dubai are directing allocations into Verbier and Gstaad ski properties as wealth preservation instruments against currency volatility.
Market Restraints
- Lex Koller permit scarcity:The Federal Act on Acquisition of Real Estate by Persons Abroad caps non-EU purchases at 1,500 annual permits, forcing foreign demand concentration into designated tourist zones with inflated clearing prices.
- Alpine terrain scarcity:Buildable land in premium ski domains faces absolute physical constraints, protecting price floors but preventing supply response to demand surges in Crans-Montana and St. Moritz.
- Concrete and steel input volatility:Conventional construction remains exposed to energy-intensive material cost swings that erode developer margins on fixed-price contracts in Zurich lakefront projects.
Strategic Opportunities
- Sustainability-certified development carve-outs:Pending revisions to Lex Koller may create permit exemptions for Minergie-P or SNBS-certified buildings, rewarding early movers in carbon-neutral Alpine construction.
- Geneva Eaux-Vives densification:ARE spatial planning guidelines are relaxing height restrictions near Cornavin station, enabling penthouse inventory expansion for expat banking professionals.
- Integrated wealth structuring convergence:Private banks are embedding real estate into Lombard lending and trust architectures, creating captive demand for trophy assets above CHF 10 million.
Industry Challenges
- Cross-border compliance complexity:Non-resident buyers face multi-jurisdictional tax treaty navigation across EU, Gulf, and Asian domiciles, extending transaction timelines and aborting deals.
- Alpine construction skill scarcity:Specialized timber engineering expertise and certified mountain contractors command premium wages, constraining development velocity in remote Valais locations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Switzerland Luxury Residential Real Estate Market |
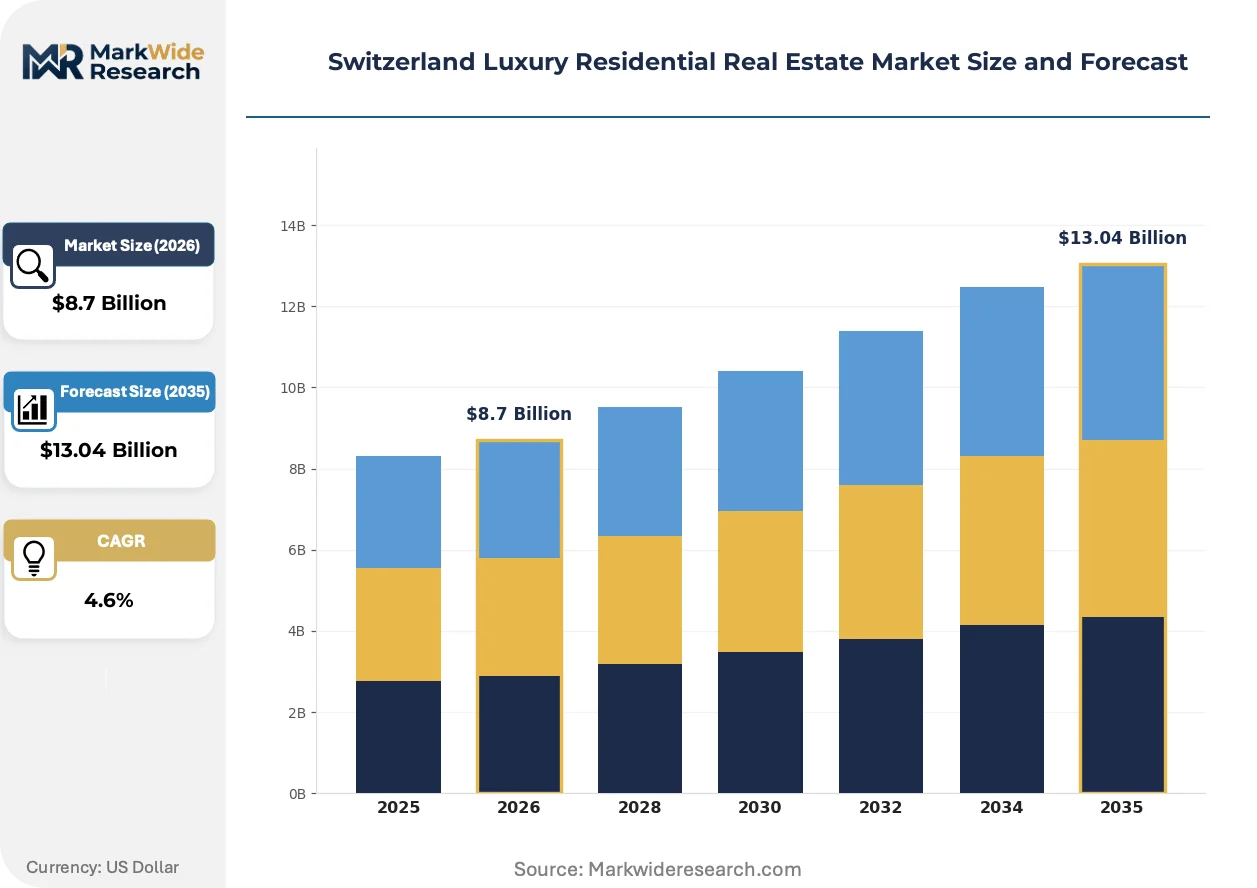
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Single-Family Homes, Condominiums, Villas, Penthouses End User: High-Net-Worth Individuals, Foreign Investors, Expats, Local Professionals Price Tier: Mid-Range, Premium, Ultra-Premium, Exclusive Investment Strategy: Buy-to-Let, Vacation Rentals, Long-Term Holding, Development |
| Companies Covered | Savills, UBS Global Wealth Management, BARNES International, JamesEdition, Luxury Portfolio, WSG AG, GuestReady, Houzy, Foxstone, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Switzerland Luxury Residential Real Estate Market Trends and Innovations
Digital twin modeling and generative design tools are compressing pre-construction phases for premium Alpine residences, while regulatory pressure on embodied carbon is accelerating material substitution away from conventional concrete.
Cross-laminated timber engineering is integrating seismic bracing and thermal mass properties into single-family villa designs across Graubünden and Valais. Zürich-based architects are specifying glulam frame systems for slopeside chalets above 1,500 meters elevation. This technology is integrating passive house certification requirements with faster weather-enclosure sequencing, compressing project finance carry costs.
The Federal Office for Spatial Development is tightening density caps around Lake Geneva peripheries under revised ARE guidelines effective through 2030. Developers in Vaud canton are responding with vertical densification strategies in approved urban cores rather than greenfield expansion. Geneva's Eaux-Vives and Zurich's Seefeld quarters face the most severe supply constraints, pushing transaction velocity toward existing inventory renovation.
Family office buyers are consolidating advisory relationships through single-source wealth management platforms rather than fragmented broker networks. BARNES International and Savills Geneva are capturing this consolidation by embedding property search into broader asset allocation mandates. This pattern concentrates commission pools among vertically integrated advisors serving Asian and Middle Eastern principals acquiring Alpine ski portfolios.
Switzerland Luxury Residential Real Estate Market Segmentation
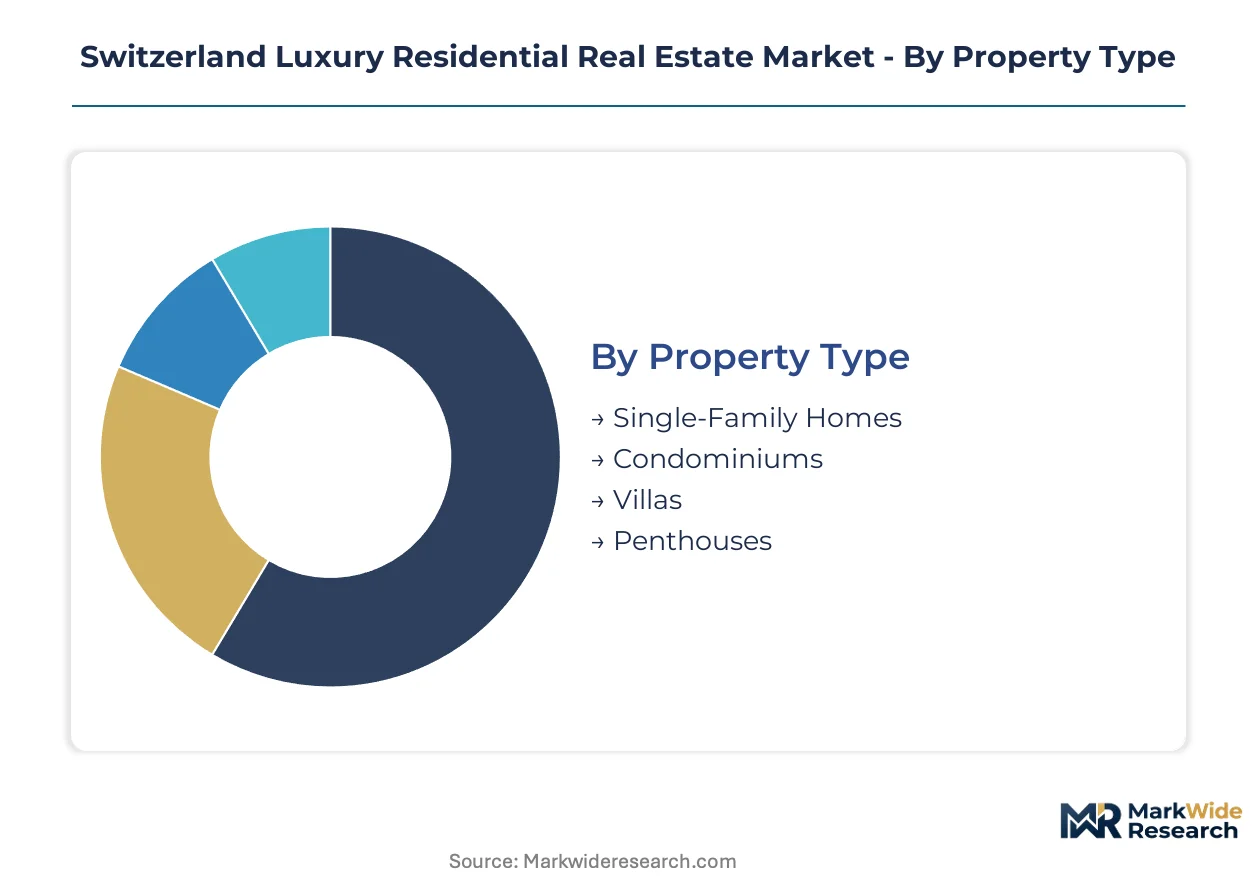
Segmentation in Switzerland's luxury residential market reveals how Lex Koller restrictions and cantonal zoning create divergent investment profiles across buyer types and property classes. Understanding these divisions exposes where regulatory friction concentrates demand and where construction innovation unlocks supply.
Property Type:
Minergie-P and SNBS certifications impose divergent compliance burdens across structural categories, with timber-frame single-family homes facing streamlined approval pathways compared to concrete high-rise condominiums.
- Single-Family Homes:Freehold detached dwellings typically exceeding 400 square meters on Alpine slopesides in Valais and Graubünden. Demand concentrates in Verbier and Gstaad where cross-laminated timber construction reduces build timelines by one-third against conventional framing, unlocking hillside parcels previously uneconomic for development.
- Condominiums:Multi-unit vertical housing stock dominating transaction velocity in Zurich and Geneva urban cores. Foreign professionals under Vaud and Ticino lump-sum taxation agreements sustain demand above CHF 5 million, though ARE density caps constrain new supply around Lake Geneva peripheries.
- Villas:Large-format estate properties with dedicated grounds in Vaud canton lakefront zones. Lex Koller permit scarcity forces foreign buyers into designated tourist municipalities, inflating clearing prices in Crans-Montana.
- Penthouses:Top-floor units with unimpeded views in Zurich Seefeld and Geneva Eaux-Vives quarters. ARE guidelines relaxing height restrictions near Cornavin station enable inventory expansion for expat banking professionals.
Condominiums sit at the top of the volume ranking, with penthouses climbing the fastest.
End User:
Buyer categories stratify sharply by capital source, with domestic purchasers accessing unrestricted financing while foreign principals navigate multi-jurisdictional compliance architectures.
- High-Net-Worth Individuals:Domestic Swiss residents with liquid assets above CHF 10 million deploying real estate for wealth preservation. UBS Global Wealth Management embeds property into integrated Lombard lending and trust structures, creating captive demand for trophy assets.
- Foreign Investors:Non-resident buyers from Singapore and Dubai family offices acquiring Alpine ski portfolios as currency hedges. Lex Koller quotas cap non-EU access at 1,500 annual permits, concentrating demand in St. Moritz and designated tourist zones with inflated price floors.
- Expats:Finance professionals relocating under preferential tax regimes to Geneva and Lugano cores. BARNES International and Savills Geneva capture this segment through vertically integrated advisory bundling property search with broader asset allocation mandates.
- Local Professionals:Domestic earners in Zurich and Basel purchasing primary residences in mid-range tiers. This category faces compressed access to ultra-premium inventory as foreign capital rotation absorbs scarce Alpine terrain.
High-net-worth individuals command the largest transaction value share, with foreign investors expanding most quickly.
Price Tier:
Price stratification correlates directly with regulatory exemption eligibility and concierge infrastructure intensity.
- Mid-Range:Properties trading between CHF 3 million and CHF 5 million with premium finishes but limited bespoke services. Local professionals dominate this tier in Zurich lakefront submarkets where concrete construction cost volatility erodes developer margins on fixed-price contracts.
- Premium:Assets between CHF 5 million and CHF 10 million featuring dedicated concierge infrastructure and proximity to transit corridors. High-net-worth individuals and expats concentrate demand here, particularly in Geneva Eaux-Vives where supply constraints push activity toward renovation of existing inventory.
- Ultra-Premium:Residences above CHF 10 million with integrated wellness facilities and private security. Foreign investors from Middle Eastern family offices target this tier in Gstaad and Verbier as wealth preservation instruments against regional currency volatility.
- Exclusive:Trophy assets exceeding CHF 25 million with singular architectural provenance and absolute privacy. Lex Koller permit scarcity and Alpine terrain constraints protect price floors, with broker fees scaling non-linearly across ancillary service contracts.
Ultra-Premium assets generate disproportionate margin pools, with Exclusive tier gaining share fastest.
Investment Strategy:
Strategy selection reflects holding period preferences and liquidity requirements across buyer tax domiciles.
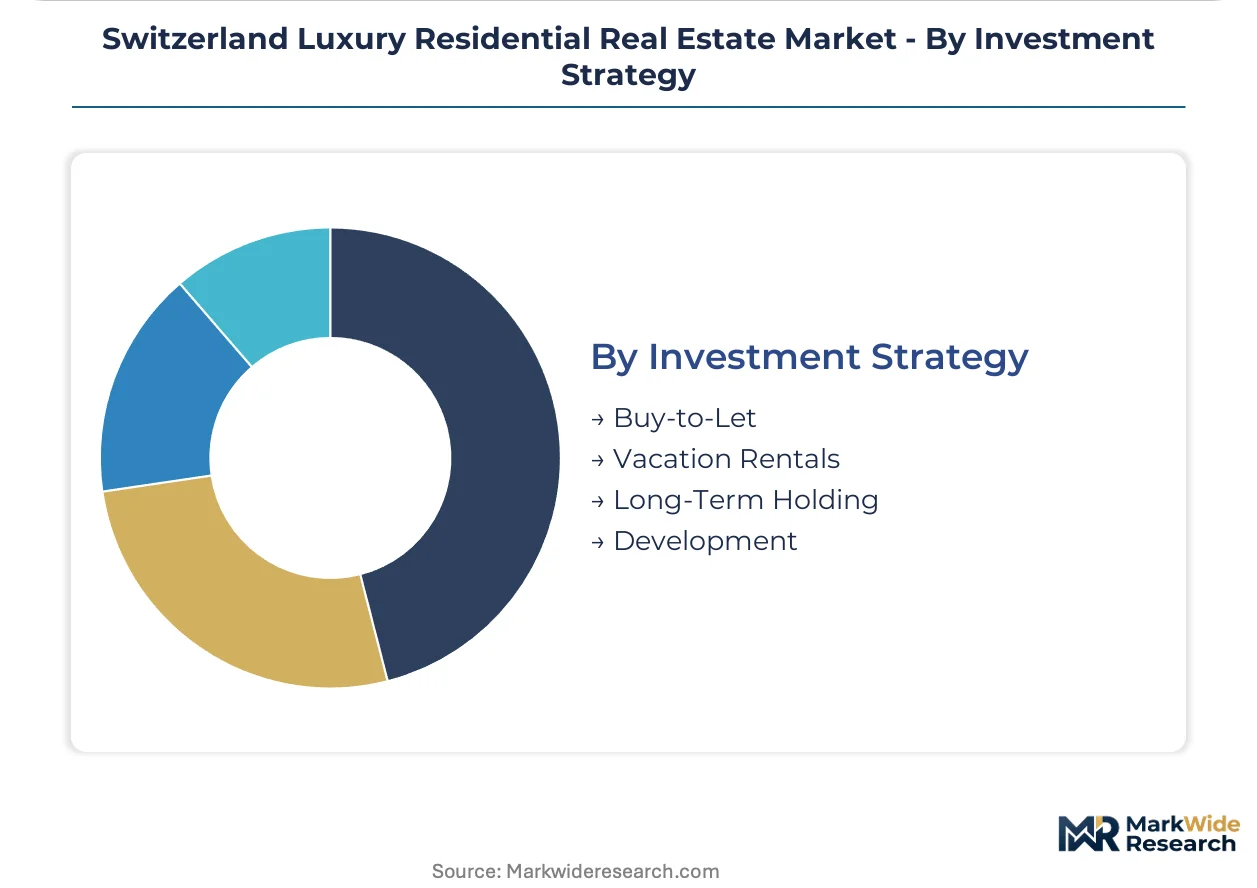
- Buy-to-Let:Income-generating acquisitions targeting expat tenant demand in Zurich and Geneva urban cores. Regulatory pressure on embodied carbon is accelerating material substitution toward cross-laminated timber in new rental stock.
- Vacation Rentals:Short-term hospitality-oriented properties in Crans-Montana and St. Moritz ski domains. Foreign investors leverage this strategy to satisfy Lex Koller commercial-use exemptions while capturing seasonal yield.
- Long-Term Holding:Generational wealth preservation vehicles for family offices with 15-20 year horizons. Digital twin modeling and generative design tools compress pre-construction phases for bespoke Alpine residences in this category.
- Development:Ground-up construction or heavy renovation plays in designated tourist zones. Specialized timber engineering expertise and certified mountain contractors command premium wages, constraining velocity in remote Valais locations.
Long-term holding dominates capital deployment, with development climbing fastest as timber methods unlock hillside parcels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Geneva's Eaux-Vives district anchors Swiss luxury residential demand, with Zurich's Seefeld quarter and Alpine clusters in Valais and Graubünden forming secondary gravity centers. Cantonal zoning authorities and Lex Koller restrictions fragment market access across sub-regional boundaries.
Lake Geneva Arc
Foreign professionals under Vaud canton lump-sum taxation agreements sustain condominium velocity above CHF 5 million in Geneva and Lausanne. The Federal Office for Spatial Development enforces density caps that protect rural landscapes but constrain new supply around lakefront peripheries. Developers respond with vertical densification strategies in approved urban cores rather than greenfield expansion.
Zurich Metropolitan Area
Expat finance professionals concentrate demand in Seefeld and lakeside quarters where ARE guidelines are relaxing height restrictions near Cornavin station. The cantonal zoning authority balances preservation mandates against penthouse inventory expansion for banking sector relocations. Construction cost volatility for concrete and steel inputs erodes developer margins on fixed-price lakefront contracts.
Valais Alpine Corridor
Cross-laminated timber adoption unlocks hillside parcels in Verbier and Crans-Montana previously uneconomic for concrete logistics. Lex Koller quotas cap non-EU purchases at 1,500 annual permits, forcing foreign demand concentration into designated tourist zones with inflated clearing prices. Specialized timber engineering expertise commands premium wages, constraining development velocity in remote locations.
Graubünden Ski Domain
Family offices from Singapore and Dubai direct allocations into Gstaad and St. Moritz properties as wealth preservation instruments against currency volatility. The cantonal authority administers federal restrictions while permitting commercial-use exemptions for vacation rental strategies. Buildable terrain faces absolute physical constraints, protecting price floors but preventing supply response to demand surges.
Ticino Southern Tier
Preferential tax regimes attract ultra-high-net-worth principals to Lugano urban core condominiums with cross-border Italian and Swiss market access. The regional planning office coordinates with federal spatial development guidelines to manage density around Lake Lugano. BARNES International and vertically integrated advisors capture consolidated family office advisory relationships in this corridor.
Switzerland Luxury Residential Real Estate Market Competitive Landscape
Global property consultancies compete with Swiss private banking networks across listing control and wealth integration dimensions. The vendor base stratifies into three tiers: international brokerage houses with Geneva and Zurich office networks, private bank real estate advisory units, and specialized Alpine ski-property boutiques. Market structure rewards vertical integration between property search and broader asset allocation mandates. Dominant competitive moves include embedding real estate into Lombard lending architectures and capturing exclusive listing flow through cantonal office density.
Within the integrated wealth management tier, UBS Global Wealth Management anchors private bank positioning by embedding property into trust and lending structures. Among international brokerage houses, Savills and BARNES International exemplify divergent specialization vectors—Savills controls prime Lake Geneva waterfront inventory flow, while BARNES concentrates ski-property advisory in Verbier and Gstaad. These three entities occupy positions that reflect broader industry segmentation between banking-integrated and pure-play advisory models.
| Leading Market Players |
|---|
| Savills |
| UBS Global Wealth Management |
| BARNES International |
| JamesEdition |
| Luxury Portfolio |
| WSG AG |
| GuestReady |
| Houzy |
| Foxstone |
| Others |
Pricing and Supply Chain Analysis
Family-owned Alpine construction specialists anchored in Valais and Graubünden enforce rigid pricing discipline through captive timber engineering capabilities and exclusive mountain contractor relationships, while their financing structures—tethered to Lombard lending architectures at UBS and Credit Suisse—insulate margin pools from conventional cost pass-through pressures.
Pricing Analysis
Cross-laminated timber input costs pass through directly to Alpine villa pricing, with glulam frame premiums compressing as Bavarian and Austrian suppliers expand engineered wood capacity. Pricing stratifies across Minergie-P certified, SNBS certified, and uncertified tiers, with certification premiums widening as Vaud canton tightens embodied carbon thresholds. Cost compression in mid-range condominiums intensifies because Zurich lakefront concrete projects face fixed-price contract exposure to steel volatility. Local professionals purchasing primary residences exhibit highest price sensitivity, while Middle Eastern family offices acquiring Gstaad trophy assets demonstrate near-zero elasticity.
Supply Chain Analysis
Dual-sourcing mandates from Geneva and Zurich developers require qualified timber engineers from both Austria and Bavaria, with secondary glulam suppliers in Slovenia increasingly pre-qualified for remote Valais sites. Alpine construction draws from cross-laminated timber panels, seismic bracing hardware, and specialized mountain foundation systems. Single-source vulnerability concentrates in certified mountain contractors commanding premium wages for slopeside access. Distribution runs through vertically integrated advisory networks at Savills Geneva and BARNES International rather than fragmented broker channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Switzerland's luxury residential market functions as a geographic-arbitrage mechanism, capturing capital flight from Singapore and Dubai into Alpine ski properties where Lex Koller permit scarcity creates artificial supply constraints absent in comparable Austrian or French resort markets.
For Market Incumbents: Cement listing control through exclusive mandates on Lake Geneva waterfront inventory before ARE density caps relax in Cornavin-adjacent zones. Cross-laminated timber engineering capabilities represent the priority defensive lever against concrete-dependent competitors facing input volatility. Backward integration into glulam frame manufacturing insulates margin pools from Austrian supplier pricing power. For New Entrants and Emerging Players: Private banking referral partnerships unlock captive demand from UBS Global Wealth Management clients seeking integrated property-wealth structures. The most penetrable white-space sits in Ticino's Lugano corridor, where lump-sum taxation agreements attract Italian cross-border principals underserved by Geneva-centric advisors. Position through sustainability-certified development advisory to capture potential Lex Koller carve-outs for Minergie-P projects. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized Alpine ski-property boutiques lacking vertical integration into wealth management platforms. Long-term viability across the analysis window hinges on regulatory permit scarcity persisting under Federal Act revisions. Acquisition targets should demonstrate captive timber engineering relationships and exclusive cantonal office density. The signal to watch is pending ARE guideline relaxation on height restrictions near transit corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Cross-Laminated Timber Certification | Minergie-P compliance unlocks potential Lex Koller exemptions for foreign buyers in Valais. |
| Cornavin Station Densification | ARE height restriction relaxation enables penthouse inventory expansion for expat banking professionals. |
| Lombard Lending Integration | UBS embedding property into trust architectures creates captive demand above CHF 10 million. |
| Dual-Sourcing Timber Engineering | Bavarian and Austrian supplier qualification mitigates remote Valais construction delays. |
| Family Office Advisory Consolidation | Single-source platforms displace fragmented brokers for Singapore and Dubai principals. |
Research Methodology
Coverage spans Lake Geneva Arc, Zurich Metropolitan Area, Valais Alpine Corridor, Graubünden Ski Domain, and Ticino Southern Tier, with primary inputs from each. The analysis combines structured interviews with Alpine construction directors, cantonal zoning officers, private bank real estate advisory heads, family office investment officers, and cross-laminated timber engineering specialists with secondary validation from Federal Office for Spatial Development guidelines, Lex Koller permit databases, Minergie certification registries, and cantonal trade statistics. Bottom-up transaction triangulation against top-down wealth flow estimates ensures methodological robustness.
Rate-of-change decomposition separates volume growth from price appreciation across the projection horizon. The analytical framework models property type, end user category, price tier, investment strategy, and cantonal regulatory cluster dimensions. CAGRs derive from fitted trend extrapolation adjusted for permit quota constraints and timber adoption S-curves. Industry-specific forecast inputs include cross-laminated timber cost curves and lump-sum taxation agreement renewal probabilities.
Revisions become necessary when Federal Act on Acquisition of Real Estate by Persons Abroad amendments materialize diverging from baseline permit scarcity assumptions. Deviation in ARE spatial planning guideline enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Residential Real Estate Market
Europe Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Ready-To-Move-In Luxury Homes Market
Luxury Residential Real Estate Market
Netherlands Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Australia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Vietnam Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
UAE Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
China Residential Real Estate Market
Luxury Residential Real Estate Market
Saudi Arabia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
China Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
GCC Luxury Market
Luxury Residential Real Estate Market
South Korea Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Italy Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Japan Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Saudi Arabia Luxury Market
Luxury Residential Real Estate Market
Belgium Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Denmark Luxury Residential Real Estate Market