
 Europe Industrial Automation Software Market | 2026-2036
Europe Industrial Automation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Industrial Automation Software Market Foresight
CE marking under the EU Machinery Directive is redrawing competitive boundaries for automation software vendors seeking access to European manufacturing sites. Siemens AG leverages deep vertical integration across PLC programming and MES layers to dominate German automotive lines. ABB Ltd anchors its position through R&D intensity in edge-computing control systems for Nordic energy providers. Schneider Electric SE competes via channel control over hybrid deployment architectures serving French chemical production complexes.
Europe industrial automation software comprises programmable platforms that orchestrate physical equipment through real-time data exchange, typically executing control loops with sub-millisecond latency via OPC UA or EtherCAT protocols. Its primary purpose is to synchronize discrete and process manufacturing operations while enabling predictive intervention before equipment failure. Cloud deployment architectures now capture the fastest expansion as chemical producers and energy providers migrate historian and analytics workloads off fragile on-premise servers. SCADA technology maintains the deepest installed base across Southern European food processing plants, though MES modules are displacing legacy paper-based batch records in pharmaceutical-adjacent manufacturing. Factory automation applications concentrate margin pools where automotive OEMs demand vendor-agnostic programming environments compliant with IEC 61131-3 standards.
The EU AI Act imposes conformity assessment obligations on automation software incorporating machine learning for safety-critical decisions, directly shaping product development roadmaps at European headquarters. ECHA's REACH restrictions on industrial chemical exposure are forcing automation vendors to embed emissions monitoring directly into DCS configurations for German and Dutch chemical clusters. The Machinery Directive's upcoming software-specific amendments will require updated validation documentation from any supplier integrating autonomous control logic. Stakeholders must monitor how CE marking scope expansion affects competitive access for non-European platform vendors serving European energy providers and manufacturing plants.
Market Dynamics
The EU AI Act's conformity assessment obligations for machine learning in safety-critical systems are forcing automation vendors to rearchitect validation pipelines before the Machinery Directive's software-specific amendments take effect.
Growth Catalysts
- CE marking expansion:The Machinery Directive's updated software validation requirements are compelling European manufacturers to replace legacy control systems with certified platforms, accelerating retrofit cycles in Germany's automotive corridors.
- Predictive maintenance platforms:German steel and chemical complexes in the Ruhr industrial belt are deploying edge-based analytics to preempt equipment failure, creating pull for real-time historian software.
- Cloud migration:Nordic energy providers are shifting SCADA and MES workloads from on-premise servers to hybrid architectures, reducing infrastructure fragility while enabling centralized fleet management.
Market Restraints
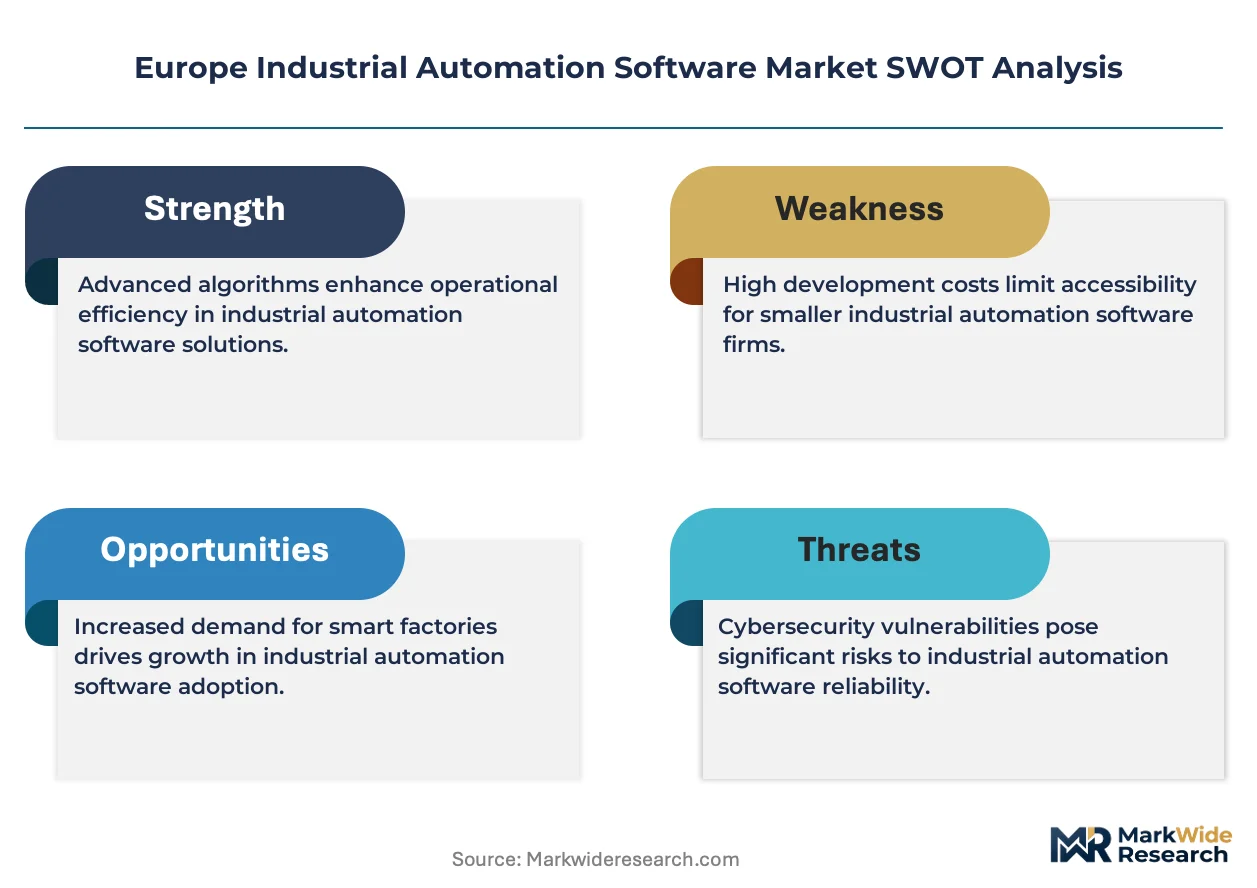
- Validation cost inflation:EU AI Act conformity assessments for autonomous control logic are extending software release timelines and inflating R&D overhead for safety-critical modules.
- Semiconductor supply concentration:Industrial edge-computing hardware depends on concentrated Asian foundry capacity, exposing European automation vendors to input volatility for control system components.
- Legacy protocol entrenchment:Southern European food processing plants remain locked into proprietary SCADA ecosystems, creating switching friction for IEC 61131-3 compliant alternatives.
Strategic Opportunities
- Pharmaceutical MES penetration:French and Swiss pharmaceutical-adjacent manufacturers are displacing paper-based batch records with electronic systems, opening greenfield deployment opportunities for validation-compliant software suites.
- REACH-integrated emissions monitoring:ECHA's chemical exposure restrictions are mandating embedded DCS configurations for emissions tracking, creating bundled software-hardware demand in Dutch chemical clusters.
- OPC UA over TSN convergence:The convergence of OPC UA semantic interoperability with Time-Sensitive Networking is enabling deterministic cloud-edge synchronization for French automotive suppliers.
Industry Challenges
- Functional safety engineer scarcity:IEC 61508 and ISO 13849 certification expertise is concentrated among aging specialists in Germany and Austria, constraining vendor scaling for safety-critical projects.
- Multi-protocol integration complexity:Retrofitting EtherCAT, PROFINET, and Modbus TCP stacks into unified control architectures is consuming 30-40% of deployment engineering hours at system integrators serving mixed-vendor environments.
- CSRD data lineage requirements:The Corporate Sustainability Reporting Directive's granular emissions disclosure mandates are forcing automation vendors to architect carbon-accounting modules into MES layers without standardized industrial data taxonomies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Industrial Automation Software Market |
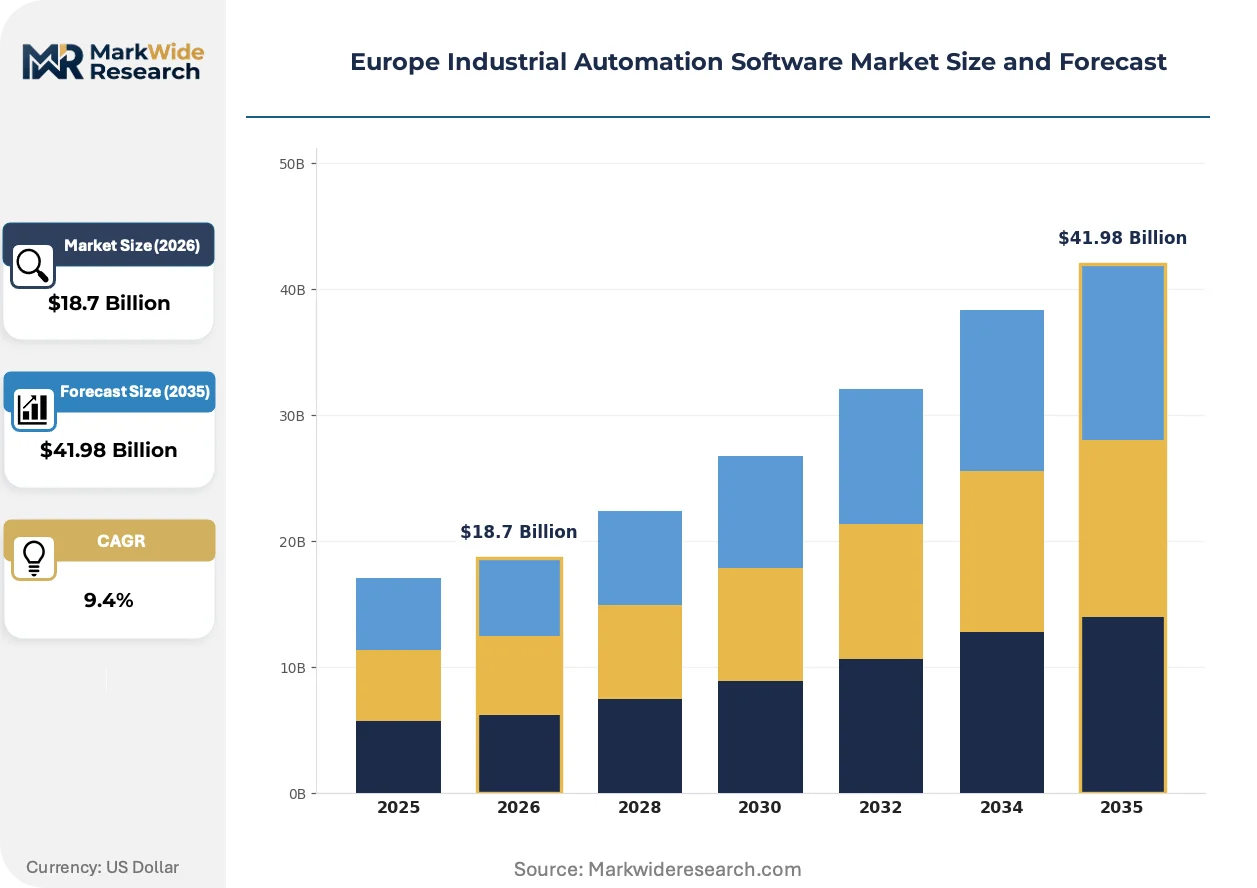
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud, Hybrid, Edge Computing Application: Process Automation, Factory Automation, Asset Management, Quality Control Technology: SCADA, MES, DCS, PLC Programming, HMI Development End User Industry: Manufacturing Plants, Energy Providers, Chemical Production, Food Processing |
| Companies Covered | Siemens AG, ABB Ltd, IBM Corporation, Emerson Electric Co., Rockwell Automation, Inc., Schneider Electric SE, Honeywell International Inc., OMRON Corporation, Yokogawa Electric Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Industrial Automation Software Market Shifts & Advancements
Edge-native control architectures are compressing the traditional hierarchy between field devices and cloud analytics, while regulatory pressure on AI-driven safety systems is reshaping how vendors validate autonomous decision logic.
Time-Sensitive Networking is miniaturizing deterministic communication from factory backbone infrastructure down to individual sensor-actuator loops. German automotive OEMs are adopting TSN-enabled I/O modules at the cell level to synchronize multi-axis robotics with sub-microsecond precision. This technology is miniaturizing the physical footprint of control cabinets while collapsing latency budgets that previously required dedicated motion controllers.
REACH enforcement through ECHA is mandating real-time chemical exposure monitoring embedded directly into distributed control system configurations. Dutch and German chemical clusters must now integrate emissions sensors with batch execution logic to trigger automatic containment protocols. Small-batch pharmaceutical producers in Switzerland face the steepest compliance burden, as their legacy DCS platforms lack the computational headroom for continuous environmental surveillance.
Subscription-based runtime licensing is displacing perpetual software ownership among mid-sized French and Italian manufacturers. System integrators are unbundling traditional SCADA packages into modular SaaS tiers, with predictive analytics and digital twin capabilities sold as metered add-ons. This shift is most visible in Southern European food processing, where capital-constrained plants prefer operational expenditure models for compliance-critical traceability modules.
Europe Industrial Automation Software Market Segmentation
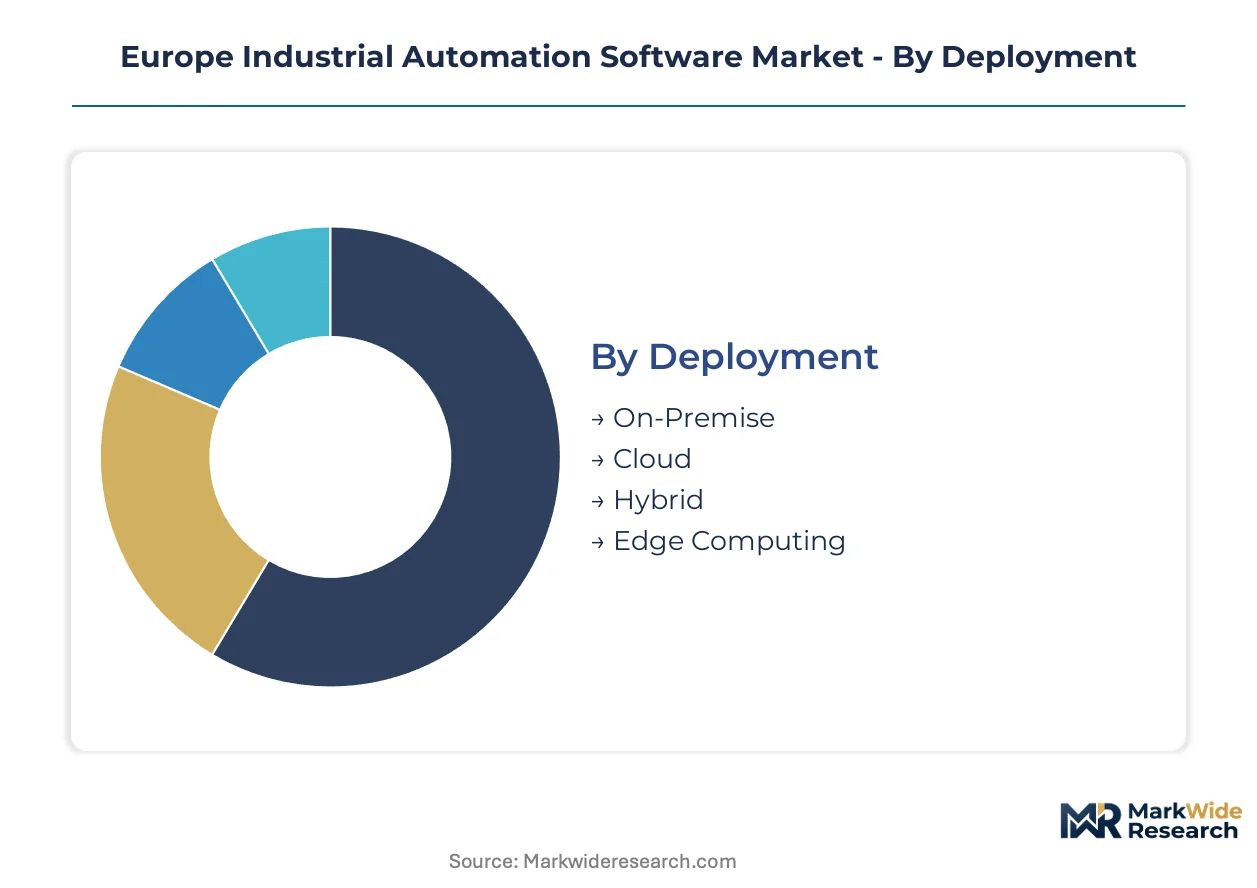
Deployment architecture determines compliance burden under the EU AI Act and Machinery Directive, with validation requirements varying sharply between centralized cloud platforms and distributed edge systems. Application focus shapes vendor specialization, as process automation demands continuous control loops while factory automation prioritizes discrete synchronization.
Deployment:
CE marking obligations under the Machinery Directive's software amendments create divergent validation costs across deployment modes, with cloud-hosted control logic facing stricter conformity assessment than on-premise alternatives.
- On-Premise:Legacy server installations running historian and SCADA workloads within facility data centers. German automotive corridors in Bavaria and Baden-Württemberg retain these configurations for sub-millisecond latency in robotics synchronization, though maintenance overhead is accelerating replacement cycles.
- Cloud:Centralized SaaS platforms hosting MES analytics and fleet management dashboards. Nordic energy providers in Denmark and Sweden are migrating SCADA workloads to hybrid cloud architectures to reduce infrastructure fragility while enabling centralized oversight of distributed generation assets.
- Hybrid:Split architectures keeping safety-critical control on-premise while pushing analytics to cloud tiers. Dutch chemical clusters near Rotterdam favor this model to satisfy ECHA REACH monitoring requirements without exposing batch execution logic to external connectivity.
- Edge Computing:Distributed compute nodes collocated with field devices for real-time preprocessing. French automotive suppliers around Paris are deploying TSN-enabled edge controllers to synchronize multi-axis robotics with deterministic microsecond precision.
On-Premise handles the majority of throughput; Edge Computing is the fastest mover on share.
Application:
Margin concentration follows application complexity, with asset management platforms commanding premium pricing for predictive intervention capabilities while quality control modules face commoditization in standardized deployments.
- Process Automation:Continuous control systems governing chemical reactions, refining operations, and energy generation. German Ruhr chemical complexes deploy these configurations for emissions-integrated batch execution under ECHA enforcement, with DCS platforms embedding real-time environmental surveillance.
- Factory Automation:Discrete manufacturing coordination for assembly lines, packaging systems, and material handling. Italian automotive component suppliers in Emilia-Romagna demand IEC 61131-3 compliant programming environments to enable multi-vendor interoperability without vendor lock-in.
- Asset Management:Predictive maintenance platforms correlating sensor telemetry with failure models. Steel producers in Spain's Basque Country are retrofitting legacy control infrastructure with edge-based analytics to preempt equipment downtime in blast furnace operations.
- Quality Control:Automated inspection and traceability systems enforcing batch consistency. Swiss pharmaceutical-adjacent manufacturers near Basel displace paper-based records with electronic systems to satisfy EMA validation requirements for audit trails.
Process Automation captures the deepest installed base; Asset Management is climbing the fastest on revenue contribution.
Technology:
Protocol entrenchment creates switching friction, with SCADA ecosystems dominating Southern European food processing while MES modules displace legacy documentation in pharmaceutical manufacturing.
- SCADA:Supervisory control platforms aggregating field-level data into centralized visualization layers. Spanish and Portuguese food processing plants maintain deep installed bases of proprietary SCADA systems, creating inertia for IEC 61131-3 migration despite interoperability benefits.
- MES:Manufacturing execution systems bridging ERP planning with shop-floor control. French pharmaceutical producers deploy validation-compliant MES suites to automate batch records and satisfy EMA audit requirements for electronic documentation.
- DCS:Distributed control architectures for continuous process industries. Dutch chemical clusters integrate emissions sensors directly into DCS configurations to trigger automatic containment protocols under ECHA REACH enforcement.
- PLC Programming:Logic development environments for programmable controllers. German automotive OEMs mandate vendor-agnostic IEC 61131-3 compliant tools to enable code portability across multi-vendor production lines.
- HMI Development:Human-machine interface design tools for operator visualization. Polish manufacturing plants adopt modern HMI platforms to replace aging panel interfaces with touch-enabled mobile access to control parameters.
SCADA retains the largest footprint; MES is gaining share fastest in regulated manufacturing.
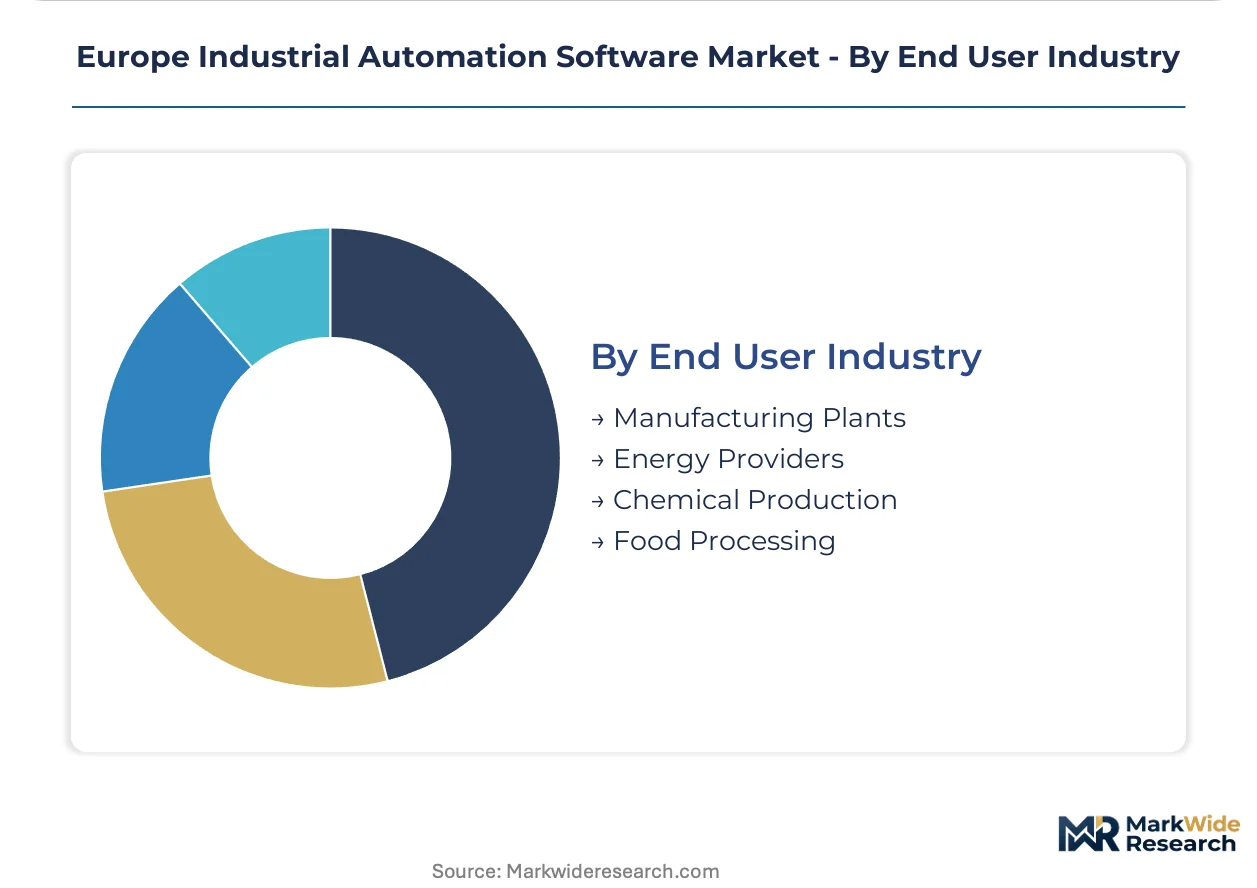
End User Industry:
Capital intensity and regulatory exposure determine software investment priority, with chemical production and energy providers leading upgrade cycles while food processing lags on legacy protocol entrenchment.
- Manufacturing Plants:Discrete assembly and fabrication facilities spanning automotive, electronics, and machinery sectors. German automotive OEMs in Stuttgart and Wolfsburg drive demand for vendor-agnostic programming environments compliant with Machinery Directive software validation requirements.
- Energy Providers:Electricity generation, transmission, and distribution operators. Nordic utilities in Norway and Finland migrate SCADA and MES workloads to hybrid architectures to enable centralized fleet management of hydroelectric and wind generation assets.
- Chemical Production:Petrochemical, specialty chemical, and pharmaceutical intermediate manufacturers. German and Dutch chemical clusters retrofit DCS platforms with embedded emissions monitoring to satisfy ECHA REACH restrictions on industrial chemical exposure.
- Food Processing:Dairy, meat, beverage, and packaged goods production facilities. Southern European plants in Italy and Spain remain locked into proprietary SCADA ecosystems, constraining migration to modern interoperability standards despite operational pressure.
Manufacturing Plants account for the dominant volume position; Chemical Production is expanding most quickly on compliance-driven retrofit demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial automation software procurement concentrates among German automotive OEMs, Dutch chemical clusters, and Nordic energy utilities seeking compliance-aligned retrofit solutions. Buyer archetypes prioritize CE marking readiness and ECHA REACH integration over pure functionality. Geographic demand splits between legacy manufacturing corridors upgrading control infrastructure and greenfield pharmaceutical facilities deploying validation-compliant MES suites.
Germany
Automotive OEMs in Stuttgart and Wolfsburg drive demand for IEC 61131-3 compliant programming environments enabling multi-vendor interoperability. The EU AI Act's conformity assessment obligations are compressing software validation timelines for safety-critical autonomous control modules. Ruhr industrial belt steel and chemical complexes are retrofitting legacy DCS platforms with edge-based predictive analytics to preempt equipment failure.
France
Pharmaceutical-adjacent manufacturers near Paris and Lyon are displacing paper-based batch records with EMA-validated electronic systems. ANSM oversight of manufacturing software validation is tightening documentation requirements for audit trail integrity. Île-de-France automotive suppliers deploy TSN-enabled edge controllers to synchronize multi-axis robotics with deterministic microsecond precision.
Netherlands
Rotterdam chemical clusters integrate emissions sensors directly into DCS configurations to trigger automatic containment protocols under ECHA REACH enforcement. Hybrid deployment architectures dominate as producers balance cloud analytics access with batch execution logic isolation. Brabant region specialty chemical manufacturers represent the steepest compliance burden for continuous environmental surveillance integration.
Sweden
Nordic energy providers migrate SCADA and MES workloads to hybrid cloud architectures enabling centralized fleet management of hydroelectric and wind generation assets. The EU Green Deal's decarbonization timelines are accelerating digital twin deployment for predictive maintenance of distributed generation infrastructure. Stockholm-based utilities lead edge-computing adoption for real-time grid balancing across variable renewable portfolios.
Italy
Emilia-Romagna automotive component suppliers demand vendor-agnostic control platforms to reduce switching costs across multi-vendor production lines. Southern food processing plants in Lombardy and Veneto remain locked into proprietary SCADA ecosystems despite operational pressure for modernization. CSRD disclosure mandates are forcing mid-sized manufacturers to architect carbon-accounting modules into legacy MES layers.
Europe Industrial Automation Software Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with captive hardware-software integration capabilities. Siemens AG, ABB Ltd, and Schneider Electric SE anchor the premium tier through vertical control across PLC programming, MES, and SCADA layers. Mid-scale specialists compete on sector-specific validation expertise for pharmaceutical and chemical compliance. Dominant competitive moves include strategic partnerships with system integrators and portfolio diversification into edge-native control architectures.
Within the diversified conglomerate tier, Siemens AG exemplifies deep vertical integration across automation software stacks, while ABB Ltd occupies a position emphasizing R&D intensity in edge-computing systems. Schneider Electric SE represents the channel-control archetype, anchoring competitive positioning through hybrid deployment architectures. These three companies collectively illustrate how European headquarters proximity shapes regulatory response speed under the EU AI Act and Machinery Directive amendments.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd |
| IBM Corporation |
| Emerson Electric Co. |
| Rockwell Automation, Inc. |
| Schneider Electric SE |
| Honeywell International Inc. |
| OMRON Corporation |
| Yokogawa Electric Corporation |
| Others |
Supply & Pricing Matrix
Forty-five-to-ninety-day lead times for industrial edge-computing hardware concentrate pricing power among Asian foundry suppliers, forcing European automation vendors to absorb input volatility or pass through semiconductor cost swings to German automotive OEMs and Dutch chemical producers.
Pricing Analysis
Cost-plus contracts with quarterly semiconductor indexation dominate procurement between European system integrators and Asian foundry suppliers. Three-tier pricing structure across premium, standard, and economy levels separates IEC 61508-certified safety modules from general-purpose SCADA licenses and entry-level HMI tools. Pricing pressure stems from EU AI Act conformity assessments inflating R&D overhead for autonomous control logic. Mid-sized French and Italian manufacturers exhibit highest price sensitivity, favoring subscription SaaS tiers over perpetual licenses, while German automotive OEMs absorb premium pricing for vendor-agnostic IEC 61131-3 compliant environments.
Supply Chain Analysis
Inventory buffers of sixty-to-ninety days for industrial processors and TSN-enabled I/O modules remain standard across European automation vendors, though just-in-time compression is accelerating. Semiconductor fabrication concentrates in Taiwan, South Korea, and China, with European vendors drawing from concentrated Asian foundry capacity for edge-computing control hardware. German and Dutch chemical clusters face single-source vulnerability for specialized emissions-monitoring sensors integrated into DCS configurations. Distribution runs through authorized system integrator channels serving automotive corridors in Stuttgart and chemical clusters near Rotterdam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe industrial automation software market sits at a high-growth inflection as the EU AI Act's conformity assessment obligations force safety-critical system rearchitecture, compressing validation timelines while expanding addressable retrofit demand across German automotive and Dutch chemical infrastructure.
For Market Incumbents: Shield installed base relationships by embedding REACH-compliant emissions monitoring directly into DCS configurations before ECHA enforcement hardens. Accelerate certification investment in IEC 61508 functional safety expertise to constrain scaling capacity of mid-scale specialists. Capture channel control over hybrid deployment architectures serving French pharmaceutical producers displacing paper-based batch records. For New Entrants and Emerging Players: Anchor in Southern European food processing plants locked into proprietary SCADA ecosystems but facing operational pressure for IEC 61131-3 migration. Target Spanish and Portuguese dairy and meat facilities with modular SaaS traceability modules priced on operational expenditure models. Pursue go-to-market partnerships with Italian system integrators serving Emilia-Romagna automotive component suppliers demanding vendor-agnostic control platforms. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compression play because CE marking scope expansion under Machinery Directive amendments creates structural barriers for non-European platform vendors. Acquisition targets should emphasize sector-specific validation expertise for pharmaceutical and chemical compliance rather than horizontal software scale. Watch for EMA audit enforcement intensity as the signal indicating acceleration in MES displacement of paper-based batch records.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Native Control Architecture Deployment | TSN-enabled I/O modules compress latency budgets for German automotive multi-axis robotics synchronization. |
| REACH-Integrated Emissions Monitoring | Embedded DCS sensor configurations satisfy ECHA enforcement for Dutch Rotterdam chemical cluster compliance. |
| Hybrid Cloud Migration | Split architectures enable Nordic energy providers to centralize fleet management without exposing batch logic. |
| Validation-Compliant MES Suite Launch | Electronic batch record automation captures French pharmaceutical-adjacent manufacturers under ANSM oversight. |
| System Integrator Channel Partnership | Authorized distribution control locks in Italian automotive component supplier demand for IEC 61131-3 tools. |
Research Methodology
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and system integrator technical leads anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through SEC filings of listed automation vendors, ECHA REACH enforcement documentation, EU AI Act implementation guidance, and IEC standard revision committees. Customs data on industrial control hardware imports and hyperscaler capex disclosures for edge-computing infrastructure supplemented demand-side triangulation. Bottom-up segment sizing across deployment modes and top-down macroeconomic cross-checks converged on volume and value estimates.
Sensitivity analysis tested forecast robustness across alternative regulatory implementation timelines and semiconductor supply disruption scenarios. The analytical framework modeled deployment architecture, application focus, technology protocol, and end-user industry verticals across the analysis window. CAGRs derived from segment-level growth trajectory blending and macroeconomic elasticity assumptions. Industry-specific inputs included EU AI Act conformity assessment cost curves and ECHA REACH monitoring mandate penetration rates by chemical cluster.
Decision-makers should treat outputs as directional under assumptions of steady EU regulatory enforcement and no catastrophic semiconductor supply disruption; material deviation would warrant model refresh. Forecasts embed assumptions about Machinery Directive amendment adoption speed and functional safety engineer availability constraints. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
North America Smart Factory Market
Industrial Automation
Global Feeder Automation Market
Industrial Automation
Europe Warehouse Automation Systems Market
Industrial Automation
Cold Storage AGV Market
Industrial Automation
Global Industrial Wireless Automation Market
Industrial Automation
Industrial Networking Solutions Market
Industrial Automation
Parcel Sortation Systems Market
Industrial Automation
Europe Industrial Embedded Systems Market
Industrial Automation
Latin America Automated Storage and Retrieval System Market
Industrial Automation
Conveyor Sorting Systems Market
Industrial Automation
Tilt Tray Sorter Market
Industrial Automation
Programmable Logic Controller [PLC] Market
Industrial Automation
Global Motion Controller Market
Industrial Automation
Asia Pacific Process Automation Market
Industrial Automation
Latin America Process Automation Market
Industrial Automation
Smart Sorting Machine Market