
 Spain Data Center Power Market | 2026-2036
Spain Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Data Center Power Market Insights
Project finance partnerships between utilities and infrastructure developers is reconfiguring capital requirements for new entrants in the Spain data center power sector. Schneider Electric SE leverages its integrated energy management portfolio to anchor large-scale facility deployments across Iberian markets. ABB Ltd sustains competitive positioning through high-voltage direct current systems optimized for hyperscale load profiles. Iberdrola dominates renewable-backed power purchase agreements that supply Madrid and Barcelona data center clusters.
Spain data center power encompasses electrical infrastructure, backup generation, and energy distribution systems engineered to sustain continuous operations within digital facilities, typically requiring redundancy levels from N+1 to 2N and voltage stability within plus or minus three percent. Uninterruptible power supply systems constitute the critical bridge between grid failure and generator activation, with lithium-ion battery configurations displacing traditional valve-regulated lead-acid architectures across new builds. Grid power remains the primary delivery mode, though renewable energy sourcing is accelerating fastest as operators respond to corporate sustainability commitments and regulatory pressure. Edge computing deployments represent an emerging structural segment where modular power architectures compete against centralized uninterruptible power supply designs.
Spain's Ministry for Ecological Transition enforces building efficiency codes that shape cooling and power density specifications for new data center construction. The country's national energy regulator monitors grid connection queues that directly determine project timelines in Madrid and Barcelona corridors. Stakeholders must weigh generator fuel choices against tightening emissions standards while securing renewable power offtake agreements that satisfy both operational cost targets and compliance frameworks.
Market Dynamics
Spain's National Integrated Energy and Climate Plan is forcing hyperscale operators to reconfigure power procurement around renewable integration timelines, compressing traditional diesel backup architectures while accelerating lithium-ion adoption and grid-interactive designs.
Growth Catalysts
- Hyperscale cloud expansion:Madrid and Barcelona corridors attract multi-hundred-megawatt deployments from international cloud services providers seeking EU data sovereignty compliance.
- EU Green Deal alignment:Spain's renewable energy mandates for digital infrastructure create preferential permitting pathways for facilities with verified carbon-free power sourcing.
- Lithium-ion battery maturation:Declining cell costs and improved thermal runaway management enable 10-15 minute bridge power at data halls previously restricted to valve-regulated lead-acid systems.
Market Restraints
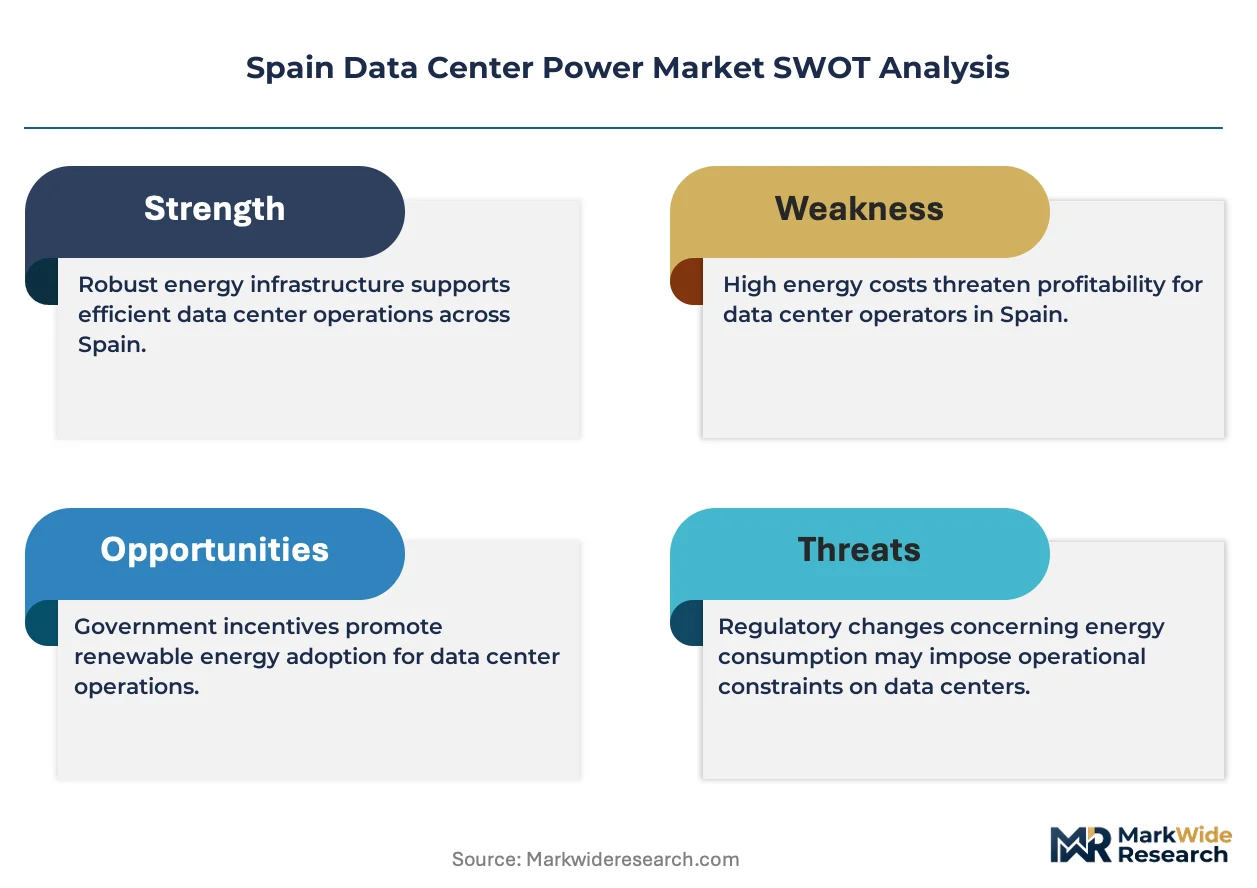
- Grid interconnection queuing:Spain's national energy regulator manages connection timelines extending 24-36 months for Madrid metropolitan zone projects, freezing development schedules.
- Copper and silicon carbide supply concentration:Power electronics fabrication depends on East Asian wafer supply chains vulnerable to export licensing friction and logistics bottlenecks.
- Diesel generator emissions compliance:Tightening EU F-Gas Regulation and local air quality standards threaten standard 2N backup configurations requiring fuel-switching or carbon offset purchases.
Strategic Opportunities
- Andalusian and Aragonese greenfield corridors:Lower land costs and abundant solar irradiance position southern and northeastern Spain for renewable-powered edge and hyperscale campuses outside saturated Madrid-Barcelona axis.
- Grid-interactive uninterruptible power supply architectures:Frequency regulation revenue streams and demand response participation create new value pools for operators with bi-directional power conversion capability.
- Spain's Recovery and Resilience Facility allocations:EU structural funds designate digital infrastructure as strategic priority, channeling concessional financing toward sustainable data center construction.
Industry Challenges
- Medium-voltage power engineering specialization:Spain's utility-scale electrical talent pool concentrates at Iberdrola and Endesa, leaving independent data center developers competing for scarce substation design and commissioning expertise.
- Legacy facility electrical retrofit complexity:Older Madrid colocation sites face 480V to 415V transition costs and physical constraints blocking lithium-ion battery room deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Data Center Power Market |
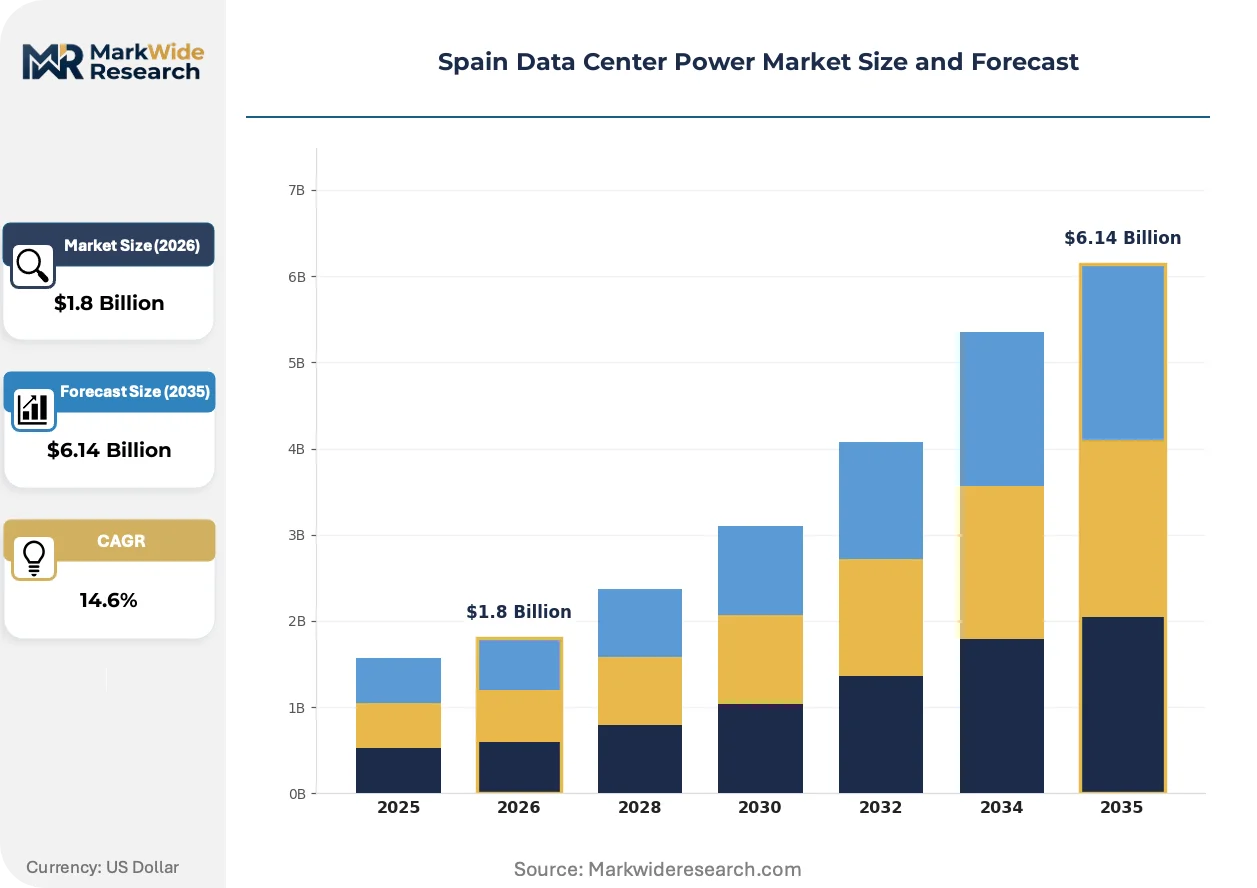
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Colocation, Managed Services, Cloud Services, Disaster Recovery Power Source: Grid Power, Renewable Energy, Generators, Uninterruptible Power Supply End User: IT Companies, Telecommunication Providers, Financial Institutions, E-commerce Deployment: On-Premise, Hybrid, Multi-tenant, Edge Computing |
| Companies Covered | Schneider Electric SE, ABB Ltd, Eaton Corporation, Vertiv Group Corp, Cummins Inc, Caterpillar Inc, Legrand Group, Rolls-Royce PLC, Iberdrola, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Data Center Power Market Trends and Innovations
Power architecture decisions in Spanish data centers now pivot on renewable energy matching requirements and grid stability services rather than traditional capital cost minimization, redefining vendor selection criteria and facility design standards.
Liquid cooling integration with power delivery is collapsing the historical separation between thermal and electrical infrastructure design. Hyperscale operators in Madrid's Alcobendas corridor are deploying direct-to-chip cooling loops that share power distribution units with rack-level busway systems. This convergence eliminates redundant containment and raises power usage effectiveness targets above 1.15.
Spain's Ministry for Ecological Transition enforces building efficiency codes that mandate real-time energy consumption disclosure for facilities exceeding 500kW installed capacity. Data center operators must install sub-metering architectures capable of granular power tracking by tenant and workload type. The Madrid metropolitan zone faces the steepest compliance timelines, with Q1 2026 reporting deadlines accelerating procurement of intelligent power distribution unit networks.
Corporate sustainability officers now dictate power sourcing specifications ahead of traditional facilities procurement teams. Spanish financial services and telecommunications verticals require documented renewable energy certificates matching 100 percent of annual consumption, displacing standard utility tariff negotiations. This shift elevates power purchase agreement structuring expertise within data center developer core competencies and compresses margins on conventional grid-sourced offerings.
Spain Data Center Power Market Segmentation
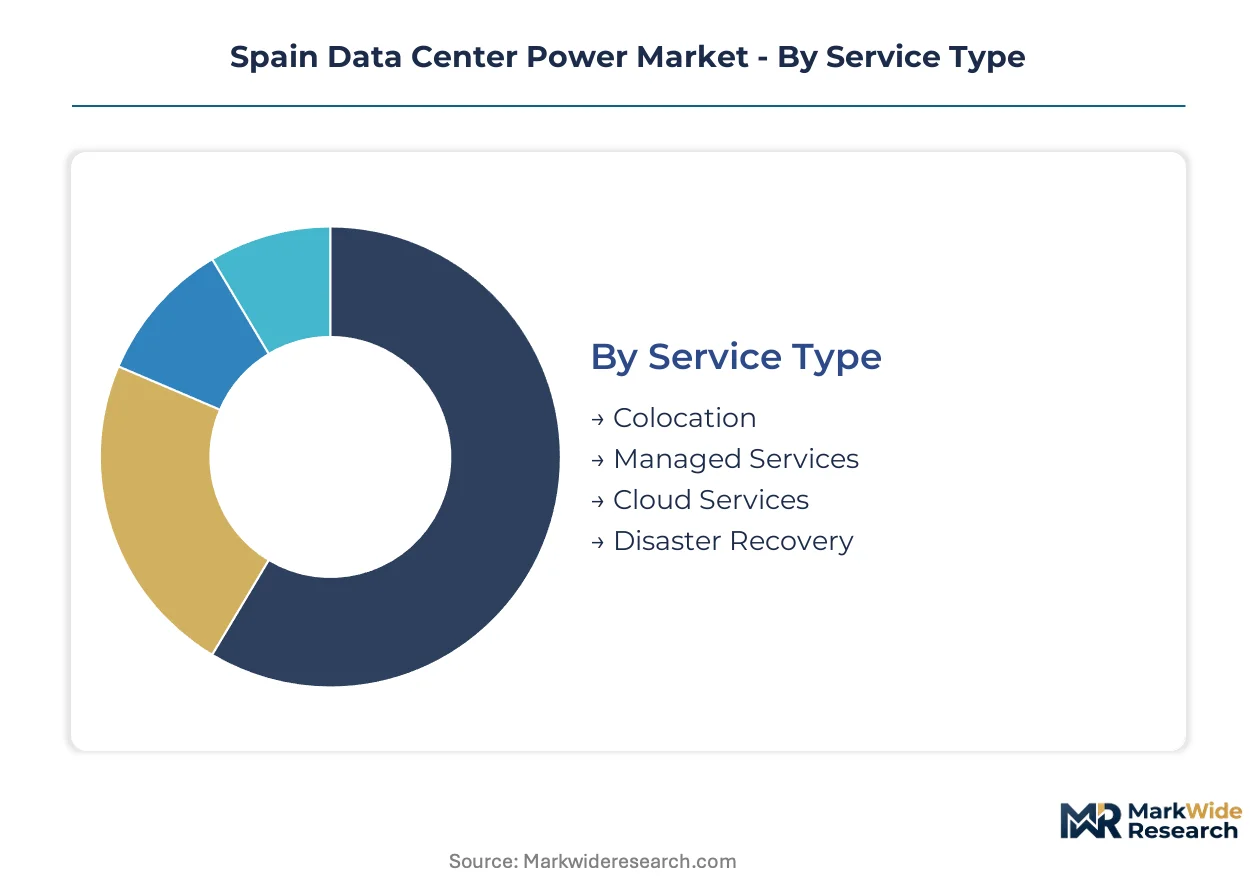
Segmentation in Spain's data center power market reveals divergent procurement cycles across infrastructure layers. Service models and power architectures refresh at markedly different velocities, shaping vendor engagement strategies and capital allocation priorities for Madrid and Barcelona corridor developments.
Service Type:
Colocation contracts turn over fastest at 3-5 year cycles, while disaster recovery engagements extend across decade-long frameworks, creating distinct sales motion requirements.
- Colocation:Wholesale and retail space leasing with dedicated power allocations measured in kilowatts per rack. Madrid's Alcobendas corridor concentrates hyperscale demand where Schneider Electric SE and ABB Ltd anchor electrical infrastructure deployments.
- Managed Services:Third-party operation of customer-owned IT equipment with bundled power management. Financial institutions in Barcelona's Sant Cugat cluster favor this model to bypass utility negotiation complexity.
- Cloud Services:Hyperscale provider-owned facilities with internal power architecture control. Amazon Web Services and Microsoft Azure expansion in Aragon's Calatorao corridor exemplifies this segment's capital intensity.
- Disaster Recovery:Geographically separated backup facilities with synchronous power redundancy requirements. Andalusian greenfield sites outside seismic zones attract these deployments for seismic isolation compliance.
Colocation anchors the volume base while cloud services gains share at the steepest rate.
Power Source:
Cost tier stratification separates commodity grid sourcing from premium renewable-backed procurement, with lithium-ion bridge systems commanding intermediate positioning.
- Grid Power:Standard utility tariff supply from Iberdrola and Endesa distribution networks. Madrid metropolitan zone projects face 24-36 month interconnection queues regulated by Spain's national energy regulator.
- Renewable Energy:Solar and wind power purchase agreements satisfying EU Green Deal alignment mandates. Iberdrola dominates PPAs supplying Barcelona data center clusters with verified carbon-free certificates.
- Generators:Diesel and natural gas backup systems facing tightening F-Gas Regulation compliance pressure. Valencia corridor operators test hydrogen fuel cells as diesel displacement alternatives.
- Uninterruptible Power Supply:Lithium-ion battery architectures displacing valve-regulated lead-acid across new builds. 10-15 minute bridge power duration now standard for Madrid hyperscale halls.
Grid power retains the dominant cost position though renewable energy climbs fastest as sustainability mandates harden.
End User:
Application-driven segmentation separates latency-sensitive workloads from batch processing, with divergent power density and redundancy specifications.
- IT Companies:Software and platform providers with variable compute loads and seasonal scaling requirements. Hybrid cloud operators in Barcelona prioritize modular power architectures for workload flexibility.
- Telecommunication Providers:5G core network functions and edge computing infrastructure demanding sub-10ms latency. Madrid's Telefónica and Vodafone deployments drive distributed power system procurement.
- Financial Institutions:Trading platforms and core banking systems requiring 2N redundancy with sub-millisecond failover. Banco Santander and BBVA specifications shape Madrid colocation provider electrical designs.
- E-commerce:Seasonal demand spikes with flash sale traffic patterns stressing power distribution scalability. Amazon and Mercado Libre fulfillment data centers in Zaragoza corridor exemplify this volatility.
Telecommunication providers drive edge computing power demand while financial institutions maintain the strictest redundancy specifications.
Deployment:
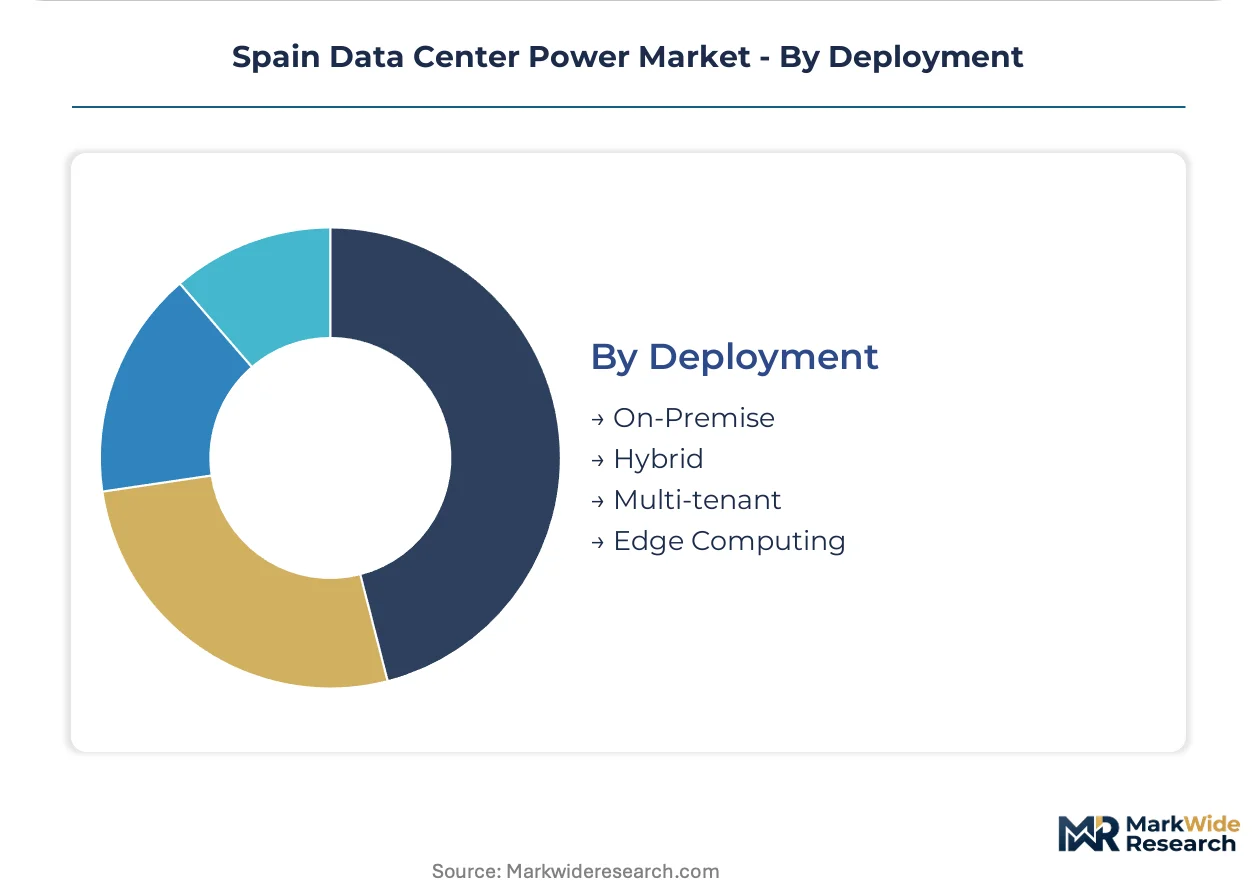
Maturity gradients separate legacy on-premise retrofit complexity from greenfield edge computing simplicity, with hybrid architectures occupying the transitional middle.
- On-Premise:Enterprise-owned facilities with captive electrical infrastructure and dedicated substations. Older Madrid financial services sites face 480V to 415V transition costs and lithium-ion battery room space constraints.
- Hybrid:Split workloads across owned and colocated infrastructure with unified power management visibility. Mid-market Spanish enterprises favor this model for regulatory data sovereignty compliance.
- Multi-tenant:Shared facility designs with segmented power distribution and individual tenant metering. Spain's Ministry for Ecological Transition mandates sub-metering architectures for facilities exceeding 500kW installed capacity.
- Edge Computing:Distributed micro-data centers with modular power architectures and reduced redundancy tiers. Andalusian solar-powered edge sites target content delivery and industrial IoT latency requirements.
On-premise deployment retains installed base dominance though edge computing expands most quickly as 5G rollout accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's National Integrated Energy and Climate Plan channels public investment toward renewable-powered digital infrastructure, accelerating data center power demand across autonomous communities with favorable solar and wind profiles.
Madrid
Hyperscale cloud providers cluster in the Alcobendas corridor seeking low-latency connectivity to European financial networks. Spain's Ministry for Ecological Transition mandates real-time energy disclosure for facilities exceeding 500kW installed capacity. Madrid metropolitan zone projects face 24-36 month grid interconnection queues regulated by Spain's national energy regulator.
Catalonia
Barcelona's Sant Cugat technology park attracts managed services demand from financial institutions bypassing utility negotiation complexity. EU Green Deal alignment creates preferential permitting pathways for facilities with verified carbon-free power sourcing. Iberdrola dominates renewable-backed power purchase agreements supplying Barcelona data center clusters.
Aragon
Amazon Web Services and Microsoft Azure expansion in Calatorao exemplifies capital-intensive cloud infrastructure deployment outside saturated coastal corridors. Spain's Recovery and Resilience Facility designates digital infrastructure as strategic priority, channeling concessional financing toward sustainable construction. Zaragoza corridor sites target e-commerce fulfillment workloads with seasonal power scalability requirements.
Andalusia
Lower land costs and abundant solar irradiance position southern Spain for renewable-powered edge and hyperscale campuses. Distributed micro-data centers with modular power architectures target content delivery and industrial IoT latency requirements. Seville and Málaga provinces attract disaster recovery deployments seeking seismic isolation compliance outside active fault zones.
Basque Country
Industrial IoT and advanced manufacturing workloads drive edge computing power demand across Bilbao and San Sebastián metropolitan areas. Regional energy agencies coordinate grid stability services for facilities with bi-directional power conversion capability. Basque technology parks emphasize grid-interactive uninterruptible power supply architectures capturing frequency regulation revenue streams.
Spain Data Center Power Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Spain's data center power market, creating a tiered structure where integrated energy management portfolios anchor large-scale deployments. Electrical infrastructure vendors concentrate around Madrid and Barcelona corridors, while independent developers compete for scarce substation design expertise. Two strategic archetypes dominate: multinational conglomerates with full-stack power portfolios, and regional specialists with deep utility relationships. Competitive moves center on strategic partnerships with renewable developers and portfolio diversification into grid-interactive architectures.
Within the integrated solutions tier, Schneider Electric SE anchors electrical infrastructure deployments across Iberian markets with energy management portfolios spanning uninterruptible power supply and distribution systems. ABB Ltd occupies a position among high-voltage direct current specialists optimized for hyperscale load profiles. Iberdrola sits within the utility-backed procurement archetype, dominating renewable power purchase agreements that supply Madrid and Barcelona clusters with verified carbon-free certificates.
| Leading Market Players |
|---|
| Schneider Electric SE |
| ABB Ltd |
| Eaton Corporation |
| Vertiv Group Corp |
| Cummins Inc |
| Caterpillar Inc |
| Legrand Group |
| Rolls-Royce PLC |
| Iberdrola |
| Others |
Pricing and Supply Chain Analysis
Madrid's Alcobendas corridor concentrates hyperscale power infrastructure deployment, creating localized capacity scarcity that shifts negotiating leverage toward electrical equipment vendors with certified renewable integration capabilities. Grid interconnection queues extending 24-36 months compress buyer alternatives and elevate premium positioning for suppliers with pre-certified lithium-ion architectures.
Pricing Analysis
Certification level creates the primary spread between commodity grid-sourced power and premium renewable-backed procurement with verified carbon-free certificates. Three-tier pricing structure separates hyperscale cloud operators with long-term power purchase agreements from financial institutions demanding 2N redundancy specifications and mid-market colocation tenants selecting standard N+1 configurations. Cost compression in standard grid-sourced offerings intensifies as Iberdrola and Endesa face competitive pressure from independent renewable developers. Financial institutions exhibit the lowest price sensitivity due to regulatory compliance mandates, while e-commerce operators prioritize seasonal scalability over redundancy tier premiums.
Supply Chain Analysis
Lithium carbonate and copper cathode feedstocks draw from Chilean mining operations and Chinese refining capacity before reaching Spanish power electronics fabrication. Silicon carbide wafers hinge on Taiwanese and South Korean semiconductor foundries with limited alternative sourcing. Power distribution unit assemblies and busway systems source from German and Italian industrial manufacturing clusters. Single-source vulnerability concentrates in East Asian battery cell production, where export licensing friction threatens lithium-ion bridge power deployment timelines. Distribution runs through Madrid-based electrical engineering specialists and Barcelona corridor EPC contractors with utility-scale substation commissioning expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from modular edge computing architectures that collapse traditional centralized uninterruptible power supply specifications into distributed micro-data center deployments.
For Market Incumbents: Insulate core hyperscale relationships by securing captive renewable generation capacity in Aragon and Andalusia corridors before independent developers capture grid-interactive frequency regulation revenue streams. Deepen backward integration into lithium-ion battery system integration to offset margin compression from commoditized power distribution hardware. Prioritize certification investment in EU Green Deal alignment documentation to maintain preferential permitting access against emerging competitors with unverified carbon sourcing claims. For New Entrants and Emerging Players: Pursue Andalusian solar-powered edge computing sites where land cost advantages and abundant irradiance enable modular power architecture deployment outside Madrid-Barcelona saturation. Target disaster recovery and industrial IoT latency-sensitive workloads in Seville and Málaga provinces where seismic isolation compliance creates structural demand. Establish go-to-market positioning through grid-interactive uninterruptible power supply revenue sharing models that capture frequency regulation payments unavailable to legacy diesel-dependent operators. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors electrical engineering specialists with utility-scale substation design capabilities and established relationships with Spain's national energy regulator. Long-term viability rests on renewable power purchase agreement structuring expertise and grid-interactive bi-directional power conversion portfolios. Acquisition targets should demonstrate documented carbon-free certificate matching and lithium-ion thermal runaway management certification. The signal to watch is acceleration in grid connection queue processing timelines, which would unlock stranded Madrid metropolitan zone project backlogs and revalue permitted development pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Power Purchase Agreement Structuring | Iberdrola's dominance in verified carbon-free certificates creates competitive moat for Madrid and Barcelona cluster supply. |
| Grid-Interactive UPS Architecture Deployment | Bi-directional power conversion capability unlocks frequency regulation revenue streams for Alcobendas corridor operators. |
| Lithium-Ion Battery System Integration | Thermal runaway management certification displaces valve-regulated lead-acid architectures across new Spanish builds. |
| Andalusian Greenfield Corridor Development | Lower land costs and solar irradiance position southern Spain outside saturated Madrid-Barcelona infrastructure axis. |
| Medium-Voltage Engineering Talent Acquisition | Scarce substation design expertise at Iberdrola and Endesa constrains independent developer project timelines. |
Research Methodology
The analysis maps uninterruptible power supply architectures, renewable energy sourcing models, and grid-interactive frequency regulation services, each validated through facility engineering directors, utility interconnection planners, and renewable project developers. Primary interviews with data center procurement officers, EPC contractor electrical specialists, and Spain's national energy regulator staff combined with secondary validation against EU Green Deal implementation documentation, Iberdrola power purchase agreement disclosures, and Ministry for Ecological Transition building efficiency code filings. Bottom-up project pipeline tracking triangulated against top-down renewable capacity allocation forecasts.
Fixed assumptions held Spain's National Integrated Energy and Climate Plan enforcement timelines and EU F-Gas Regulation compliance trajectories constant across the projection horizon, while varying lithium-ion cost curves and grid interconnection queue processing rates. Segmentation dimensions modeled encompass service type, power source, end user vertical, and deployment architecture across the analysis window. CAGRs derived from facility-level power density specifications and hyperscale cloud provider capacity expansion announcements. Forecast inputs incorporated Madrid metropolitan zone interconnection queue data and Andalusian solar irradiance measurements.
Sensitivities concentrate around grid connection timeline acceleration, lithium carbonate supply disruption, and EU Green Deal alignment verification standard revisions. Forecasts reflect documented assumptions regarding renewable integration mandates and battery technology substitution rates. Cross-checking against Spain's Recovery and Resilience Facility digital infrastructure allocation disbursements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Europe Data Center Colocation Market
Data Center Infrastructure
Singapore Data Center Rack Market
Data Center Infrastructure
Chile Data Center Processor Market
Data Center Infrastructure
Poland Data Center Rack Market
Data Center Infrastructure
Data Center Rack Solutions Market
Data Center Infrastructure
Vietnam Data Center Physical Security Market
Data Center Infrastructure
Europe Green Data Center Market
Data Center Infrastructure
Global Cloud Infrastructure Service Market
Data Center Infrastructure
Europe Data Center Rack Market
Data Center Infrastructure
UK Data Center Rack Market
Data Center Infrastructure
North America Data Center Construction Market
Data Center Infrastructure
India Data Center Server Market
Data Center Infrastructure
Middle East Data Center Rack Market
Data Center Infrastructure
France Data Center Market
Data Center Infrastructure
Canada Data Center Rack Market
Data Center Infrastructure
Switzerland Data Center Power Market