
 Chile Data Center Rack Market | 2026-2036
Chile Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Data Center Rack Market Insights
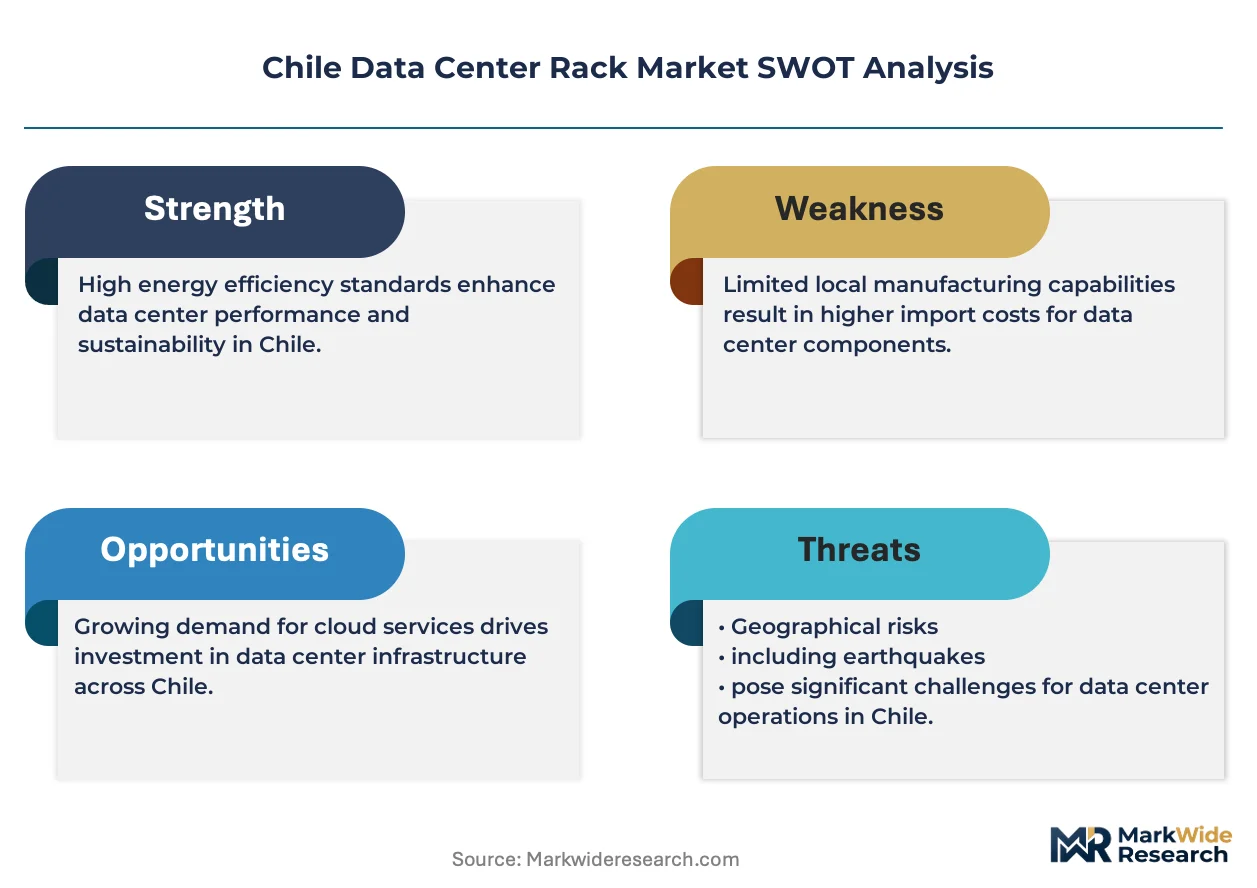
ISO/IEC 27001 certification compliance is collapsing the supplier field for enterprise-grade rack deployments in Chile. Schneider Electric SE leverages its global manufacturing footprint to sustain pre-certified supply lines into Santiago. Vertiv Group Corporation anchors thermal-integrated rack solutions for coastal humidity conditions. Delta Electronics, Inc. competes on power-distribution density within confined Chilean colocation footprints.
A data center rack is a standardized metal framework designed to house servers, networking equipment, and power distribution units, typically conforming to 19-inch EIA-310-D rail spacing for equipment mounting. These structures organize hardware vertically in rack unit increments, enable cable management, and support cooling airflow patterns essential for continuous operation in commercial computing environments. Enclosed rack configurations command premium positioning in Chile's enterprise segment due to dust filtration requirements in Santiago's arid climate, while open frame designs dominate hyperscale builds where aisle containment systems manage thermal loads. Wall-mount rack demand extends into edge computing nodes across Chile's mining corridors, where remote telemetry and autonomous equipment require localized processing. Custom rack fabrication serves submarine cable landing stations with seismic-bracing specifications unique to Chile's tectonic zone.
Chile's Subsecretaría de Telecomunicaciones (SUBTEL) enforces electromagnetic compatibility standards that filter non-compliant rack power distribution units from national infrastructure projects. The national data protection authority, under Law 19.628 and its modernizing amendments, mandates physical access logging systems that elevate demand for rack-level biometric and sensor-integrated enclosures. Stakeholders must weigh SUBTEL's evolving 5G infrastructure codes against seismic resilience requirements when specifying rack anchoring and cabinet isolation for deployments across Chile's central valley and northern mining regions.
Market Dynamics
Hyperscale cloud operators are compressing procurement cycles for rack infrastructure across Chile's central valley, forcing manufacturers to pre-certify seismic-braced enclosures before submarine cable capacity expansions activate in Santiago's Quilicura district.
Growth Catalysts
- Submarine Cable Landings:The Curie and Prat cable systems terminate in Quilicura, anchoring demand for high-density rack configurations at landing station facilities. Colocation providers pre-position cabinet inventory to capture cross-border latency-sensitive workloads.
- Law 19.628 Modernization:Chile's updated data protection framework mandates physical access logging for personal data processing infrastructure. Biometric rack enclosures capture premium positioning in enterprise and financial services deployments.
- Lithium Mining Telemetry:Autonomous extraction equipment across Chile's Atacama operations requires edge computing nodes. Wall-mount rack demand extends into remote mining corridors where localized processing reduces satellite backhaul dependency.
Market Restraints
- Copper Price Volatility:Busbar and grounding systems within rack power distribution units track London Metal Exchange copper futures. Input cost swings compress margin predictability for custom fabrication orders with 90-day delivery windows.
- Seismic Engineering Standards:Chile's tectonic zone requires zone-specific cabinet anchoring and isolation specifications. Non-specialized international suppliers face exclusion from national infrastructure tenders without local structural certification partnerships.
- Air-Cooled Thermal Limits:Santiago's summer temperature peaks constrain open-frame rack density in non-contained aisles. Hyperscale operators absorb liquid cooling capex premiums that mid-tier colocation providers cannot amortize across smaller footprint commitments.
Strategic Opportunities
- Antofagasta Edge Clusters:Northern mining regions remain underpenetrated by tier-3 data center infrastructure. Modular micro-rack deployments at extraction sites bypass fiber backhaul constraints to processing centers in Santiago.
- ISO/IEC 27001 Pre-Certification:Enterprise buyers filter supplier fields based on pre-existing certification documentation. Early certification investment creates preferred vendor status before mandatory compliance deadlines propagate through RFP processes.
- Converged Power-Thermal Systems:Integration of lithium-ion battery backup with precision cooling within single rack enclosures addresses coastal humidity and grid instability simultaneously. Vertically integrated subsystem suppliers capture specification authority from pure-play cabinet manufacturers.
Industry Challenges
- Seismic Structural Engineering Talent:Cabinet design teams require specialized expertise in Chile's NCh2361 seismic code adaptations. Engineering compensation premiums for this hybrid skill set inflate product development overhead.
- Legacy DCIM Integration:Existing data center infrastructure management platforms in Santiago's installed base operate on proprietary protocols. Rack-level sensor integration requires middleware development that extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Data Center Rack Market |
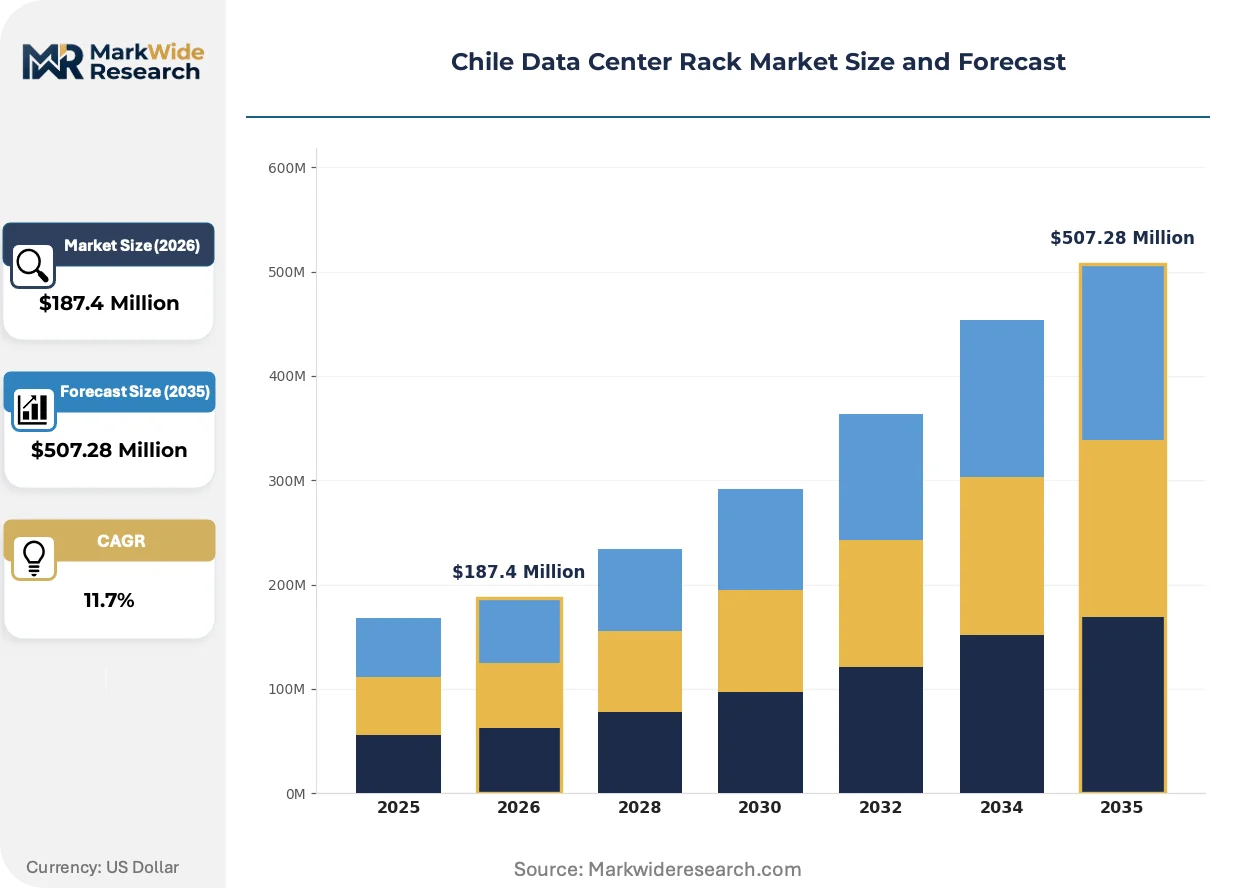
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Frame, Enclosed Rack, Wall-Mount Rack, Custom Rack End User: Telecommunications, IT Service Providers, Enterprises, Government Rack Size: 1U, 2U, 4U, 42U Material: Steel, Aluminum, Plastic, Composite |
| Companies Covered | Schneider Electric SE, Vertiv Group Corporation, Eaton Corporation plc, Legrand SA, Delta Electronics, Inc., Oracle Corporation, Scala Data Centers, Equinix, Inc., Ascenty, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Data Center Rack Market Trends and Innovations
Active reshaping in Chile's rack infrastructure centers on thermal density compression, regulatory-driven physical security integration, and procurement model fragmentation between hyperscale direct-buy and enterprise channel-mediated purchasing.
Immersion cooling-ready rack architectures are miniaturizing thermal management footprints within fixed floor space constraints. Hyperscale operators in Cerrillos deploy these configurations at 2-3x the pace of enterprise colocation tenants. The technology is miniaturizing the physical boundary between compute and heat rejection, enabling 50kW+ per rack without aisle containment infrastructure.
SUBTEL's electromagnetic compatibility enforcement for 5G infrastructure equipment filters non-compliant power distribution units from national projects. Rack manufacturers must redesign EMI shielding for PDU cable egress points to maintain certification eligibility. Enterprise deployments in Santiago's financial district absorb compliance-driven cost premiums most visibly, as banks face parallel pressure from the national data protection authority's physical security audits.
Direct procurement from manufacturers by hyperscale cloud operators fragments the traditional distributor-mediated channel structure. Systems integrators and value-added resellers lose specification authority in Quilicura and Cerrillos builds. This channel compression concentrates most acutely in deployments exceeding 500 rack units, where volume thresholds justify dedicated supplier relationship management.
Chile Data Center Rack Market Segmentation
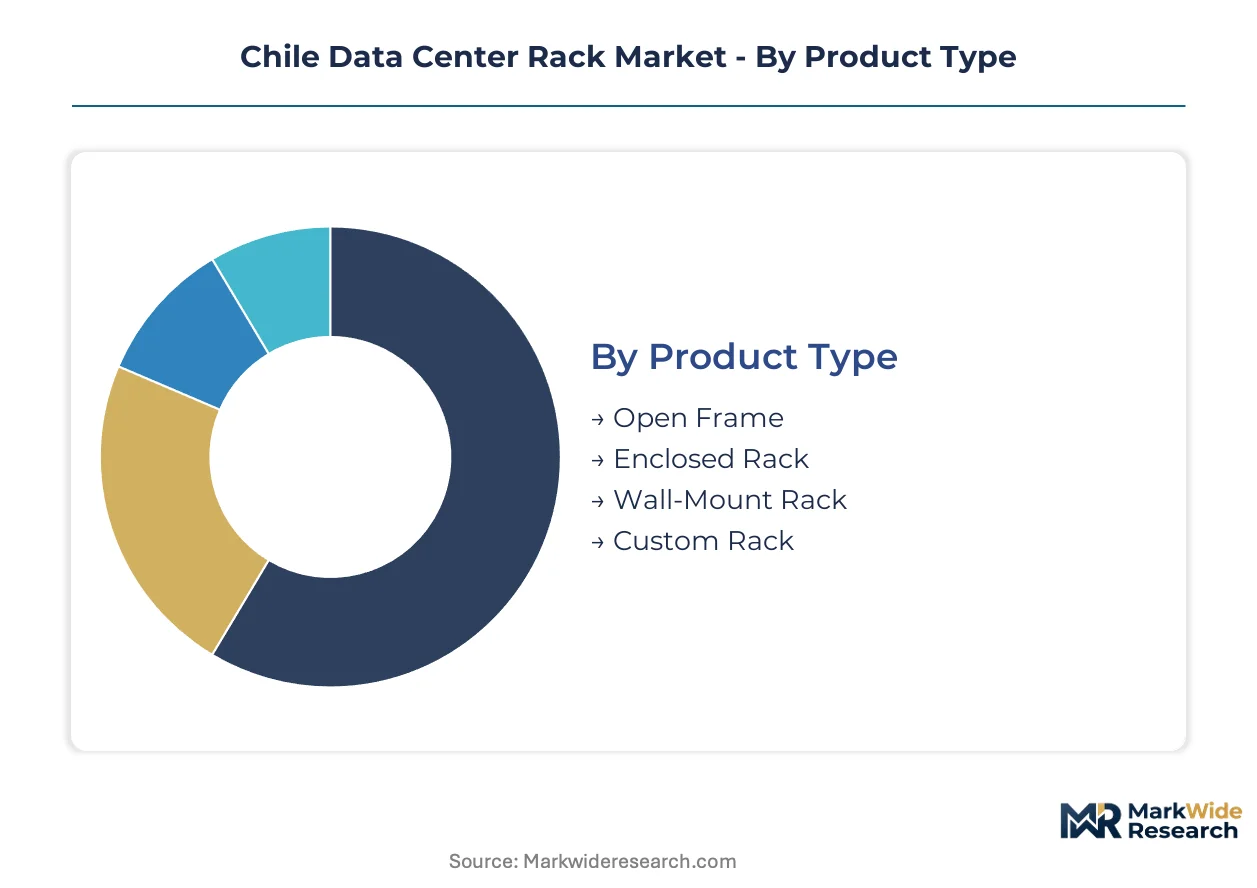
Segmentation in Chile's data center rack market reveals distinct procurement patterns across hyperscale direct-buy channels and enterprise-mediated distribution. Channel fragmentation intensifies as rack specifications diverge between Santiago's submarine cable landing zones and remote mining corridors.
Product Type:
Channel concentration varies sharply by product type: hyperscale operators in Quilicura and Cerrillos procure open-frame and custom racks through direct manufacturer relationships, while enterprise colocation tenants source enclosed and wall-mount configurations via systems integrators.
- Open Frame:Unenclosed structural frameworks with four mounting posts and open airflow pathways. Demand concentrates in hyperscale builds across Cerrillos where aisle containment systems manage thermal loads rather than cabinet-level isolation. SUBTEL's electromagnetic compatibility enforcement is compressing supplier fields for non-shielded configurations.
- Enclosed Rack:Sealed cabinet configurations with integrated doors, side panels, and cable management. Santiago's financial district enterprises absorb premium positioning here due to Law 19.628-mandated physical access logging and dust filtration requirements in the capital's arid climate.
- Wall-Mount Rack:Compact hinged or fixed enclosures for space-constrained deployments. Atacama mining corridors drive adoption for localized telemetry processing at extraction sites.
- Custom Rack:Seismic-braced fabrications with zone-specific anchoring specifications. Submarine cable landing stations in Quilicura require NCh2361-compliant structural engineering that filters non-specialized international suppliers.
By volume, Open Frame leads. By growth pace, Custom Rack is expanding most quickly.
End User:
Cost tier stratification separates hyperscale cloud operators with direct procurement authority from channel-dependent mid-market buyers.
- Telecommunications:Carriers deploying 5G infrastructure under SUBTEL codes. Procurement emphasizes EMI-shielded power distribution units for base station aggregation points.
- IT Service Providers:Colocation and managed hosting operators. Santiago's Quilicura district concentration drives high-density rack specifications with liquid cooling readiness.
- Enterprises:Financial services and mining sector buyers. Banks face parallel pressure from data protection authority audits and SUBTEL compliance, absorbing certification-driven cost premiums.
- Government:Public sector data center modernization. Procurement timelines extend due to seismic certification requirements and local content provisions.
Telecommunications captures the largest revenue share. IT Service Providers are climbing the fastest.
Rack Size:
Application density determines specification: hyperscale compute nodes demand 42U standardization while edge telemetry requires compact 1U-4U form factors.
- 1U:Single rack unit height for shallow-depth networking equipment. Edge computing nodes across northern mining regions deploy these for autonomous extraction telemetry.
- 2U:Dual-unit enclosures accommodating deeper server chassis. Enterprise colocation tenants in Santiago specify these for mixed compute-storage workloads.
- 4U:Quad-unit configurations for GPU-accelerated processing. Hyperscale operators in Cerrillos adopt these for AI training clusters ahead of density upgrades.
- 42U:Full-height standard cabinet. Quilicura hyperscale builds standardize on this form factor for maximum floor space utilization.
42U dominates deployment counts. 4U is gaining share fastest among size categories.
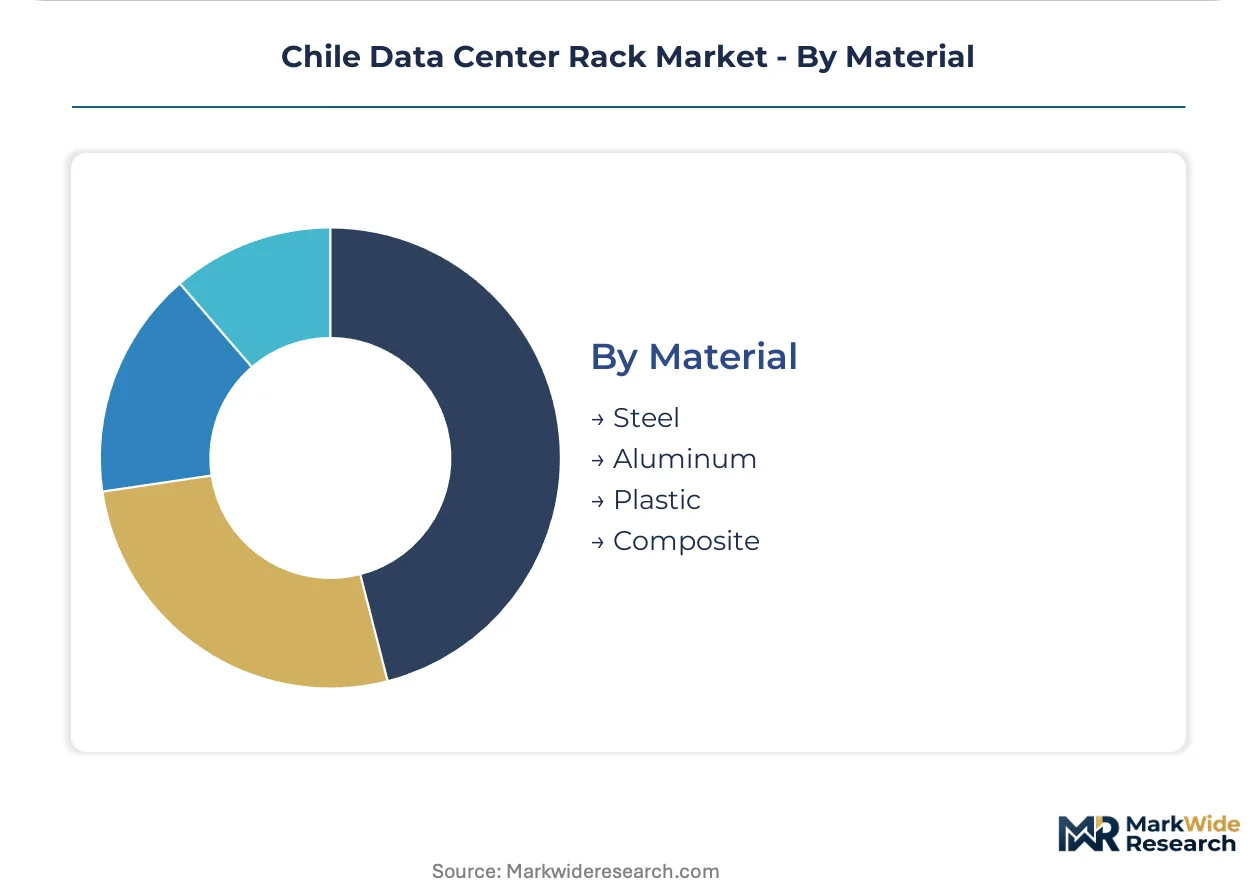
Material:
Margin structure separates commodity steel from premium aluminum and composite specifications.
- Steel:Cold-rolled carbon steel construction with powder-coated finishes. Standard for cost-sensitive enterprise deployments across Santiago's central valley.
- Aluminum:Lightweight alloy frames with corrosion resistance. Coastal humidity conditions in Valparaíso region drive specification for submarine cable landing facilities.
- Plastic:Reinforced polymer enclosures for low-load applications. Wall-mount edge nodes in mining corridors use these for weight-constrained installations.
- Composite:Hybrid material systems with thermal and electromagnetic properties. Premium positioning in financial district deployments requiring integrated shielding.
Steel leads by unit volume. Composite materials show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chile's data center rack market concentrates in metropolitan zones where submarine cable infrastructure and mining operations generate parallel demand streams. The national government's digital transformation agenda accelerates infrastructure deployment across distinct regional corridors.
Santiago Metropolitan Region
Quilicura and Cerrillos districts anchor national demand through Curie and Prat submarine cable terminations. SUBTEL's electromagnetic compatibility standards filter supplier fields for landing station deployments. Hyperscale operators pre-position seismic-braced cabinet inventory to capture cross-border latency-sensitive workloads.
Antofagasta Region
Atacama lithium extraction operations drive edge computing rack demand for autonomous telemetry processing. Mining sector procurement bypasses fiber backhaul constraints through localized wall-mount deployments. Calama and Antofagasta city clusters host modular micro-rack installations at extraction sites.
Valparaíso Region
Coastal humidity conditions elevate aluminum-frame specifications for corrosion resistance at submarine cable facilities. SUBTEL infrastructure codes enforce EMI shielding for 5G base station aggregation points. Valparaíso port city serves as secondary connectivity hub for Pacific cable systems.
Bío Bío Region
Concepción metropolitan area supports disaster recovery and business continuity deployments outside Santiago's seismic risk zone. Regional data center development attracts enterprise colocation tenants seeking geographic diversification. Government modernization programs extend procurement timelines through local content provisions.
Chile Data Center Rack Market Competitive Landscape
Listed leaders compete with private specialists across certification and seismic engineering capabilities. The supplier field compresses around ISO/IEC 27001 pre-certification status and NCh2361 structural code compliance. Three archetypes dominate: global electrical infrastructure conglomerates with captive manufacturing, precision thermal management specialists, and regional systems integrators with local certification partnerships. Competitive moves center on seismic engineering talent acquisition and direct hyperscale procurement relationship cultivation.
Among global electrical infrastructure providers, Schneider Electric SE and Eaton Corporation plc occupy positions anchored by manufacturing scale and pre-certified supply line maintenance. Vertiv Group Corporation exemplifies the thermal-integrated specialization archetype for coastal humidity conditions. These three entities represent the certification-heavy tier where enterprise and hyperscale procurement decisions concentrate.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Vertiv Group Corporation |
| Eaton Corporation plc |
| Legrand SA |
| Delta Electronics, Inc. |
| Oracle Corporation |
| Scala Data Centers |
| Equinix, Inc. |
| Ascenty |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts with seismic engineering specialists lock in both NCh2361-certified supply access and price visibility for hyperscale operators pre-positioning inventory ahead of Curie and Prat cable activations in Santiago. These arrangements insulate procurement teams from copper futures volatility while filtering non-compliant suppliers from national infrastructure tenders.
Pricing Analysis
Certification level creates the primary spread across Chile's rack market, with ISO/IEC 27001 pre-certified enclosures commanding substantial premiums over uncertified alternatives. Three-tier pricing structure separates seismic-braced custom fabrications from standard enclosed cabinets and commodity open-frame configurations. Pricing pressure stems from London Metal Exchange copper swings compressing margin predictability on 90-day delivery orders. Hyperscale cloud operators exhibit lowest price sensitivity due to volume-scale amortization, while mid-tier colocation providers face acute cost compression from liquid cooling capex premiums they cannot absorb.
Supply Chain Analysis
Strait of Magellan shipping lanes and Pacific port congestion at Valparaíso create chokepoints for aluminum alloy and precision cooling component deliveries to submarine cable landing facilities. Manufacturing concentration centers on China for steel frame stampings, South Korea for lithium-ion battery backup systems, and Germany for precision thermal management units. Copper busbar and EMI-shielded PDU assemblies draw from commodity markets with single-source vulnerability for zone-specific seismic anchoring hardware. Distribution runs through direct manufacturer relationships for hyperscale procurement and systems integrator channels for enterprise-mediated purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as hyperscale direct-buy patterns displace traditional distributor channels, creating white-space niches for specialized seismic engineering and edge computing rack suppliers serving underpenetrated mining corridors.
For Market Incumbents: Compound certification authority by acquiring NCh2361 structural engineering talent pools before mandatory compliance deadlines propagate through Santiago financial district RFPs. Defend specification authority against thermal-integrated subsystem suppliers through backward integration into precision cooling manufacturing. Prioritize direct relationship cultivation with Quilicura hyperscale operators deploying 500+ rack unit volumes where channel compression concentrates. For New Entrants and Emerging Players: Lead with modular micro-rack configurations targeting Antofagasta lithium extraction sites where fiber backhaul constraints bypass Santiago-centric incumbents. Capture wall-mount edge computing demand across Atacama mining corridors requiring localized telemetry processing. Position through regional systems integrator partnerships offering seismic certification documentation that filters established international competitors. For Investors and Strategic Acquirers: ISO/IEC 27001 pre-certified regional specialists with captive NCh2361 engineering capabilities represent the most defensible acquisition targets as enterprise compliance mandates harden. Long-term viability hinges on supplier field compression toward certification-heavy tiers with structural code compliance moats. Monitor SUBTEL electromagnetic compatibility enforcement intensity as inflection indicator for PDU redesign investment cycles and compliance-driven consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Seismic Engineering Talent Acquisition | NCh2361-certified design teams command compensation premiums that inflate product development overhead for specialized cabinet fabrications. |
| ISO/IEC 27001 Pre-Certification Investment | Early certification documentation creates preferred vendor status before Law 19.628 modernization mandates propagate through enterprise procurement. |
| Direct Hyperscale Relationship Cultivation | Volume thresholds above 500 rack units justify dedicated supplier management, bypassing distributor-mediated channel structures in Quilicura. |
| Converged Power-Thermal System Integration | Lithium-ion battery backup with precision cooling addresses coastal humidity and grid instability simultaneously for Valparaíso submarine cable facilities. |
| Antofagasta Edge Cluster Deployment | Modular micro-rack installations at lithium extraction sites bypass fiber backhaul constraints to Santiago processing centers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SUBTEL regulatory filings, copper futures exchange data, and seismic engineering certification records. Interviews with data center infrastructure managers, colocation procurement leads, SUBTEL compliance officers, and NCh2361 structural engineers inform demand-side validation. Secondary sources include customs import records for rack and PDU components, hyperscaler capex disclosures, and national data protection authority audit documentation. Bottom-up deployment tracking across Santiago, Antofagasta, and Valparaíso regions triangulates against top-down market sizing.
Segmentation dimensions modeled span product type, end user archetype, rack size specification, and material composition across the projection horizon. CAGRs derive from volume-weighted average growth trajectories by segment, with copper price sensitivity scenarios and submarine cable activation timelines as industry-specific forecast inputs. Analysis incorporates procurement cycle compression effects from hyperscale direct-buy patterns and regulatory compliance deadline impacts on supplier field filtering.
Forecasts assume regulatory continuity in SUBTEL electromagnetic compatibility enforcement and Law 19.628 data protection mandates; material policy shifts would require re-modeling. Copper price volatility, seismic event frequency, and hyperscale cloud operator expansion pace represent specific risk factors that could revise projections. Practitioners should keep alternative scenarios live as 5G infrastructure code evolution and liquid cooling technology cost curves shift.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Australia Data Center Physical Security Market
Data Center Infrastructure
Mini Data Center Market
Data Center Infrastructure
Hong Kong Data Center Power Market
Data Center Infrastructure
Norway Data Center Market
Data Center Infrastructure
Converged Data Center Infrastructure Market
Data Center Infrastructure
Brazil Data Center Server Market
Data Center Infrastructure
Brazil Data Center Rack Market
Data Center Infrastructure
Saudi Arabia Data Center Market
Data Center Infrastructure
Data Terminal Market
Data Center Infrastructure
Data Center Blade Server Market
Data Center Infrastructure
Smart Data Center Market
Data Center Infrastructure
North America Data Center Server Market
Data Center Infrastructure
Japan Data Center Rack Market
Data Center Infrastructure
China Data Center Market
Data Center Infrastructure
Global Micro Mobile Data Center Market
Data Center Infrastructure
Brazil Data Center Physical Security Market