
 North America Hosting Infrastructure Services Market | 2026-2036
North America Hosting Infrastructure Services Market Size, Share, and Industry Trends Forecast 2026-2036
North America Hosting Infrastructure Services Market Insights
Hyperscale data center construction across the United States and Canada is hardening as cloud providers race to match AI compute demand. Amazon Web Services leverages its proprietary chip designs and massive land positions in Ohio and Oregon to sustain cost leadership. Microsoft Corporation anchors enterprise trust through Azure's government cloud certifications, while Google Cloud Platform differentiates on Kubernetes-native infrastructure and carbon-free energy matching.
Hosting infrastructure services encompass the physical and virtual compute, storage, and networking resources delivered from third-party facilities to support enterprise IT workloads, typically measured in rack density per square foot and power usage effectiveness ratios below 1.3 for new builds. Cloud Hosting now captures the dominant share of new capacity commitments as enterprises exit owned data centers, while Hybrid Cloud deployments command premium pricing due to orchestration complexity and compliance requirements. Managed Hosting retains strong positions in regulated verticals where operational control outweighs cost optimization.
The Federal Risk and Authorization Management Program and Canada's Shared Services Canada cloud security standards shape vendor qualification and procurement pathways across public sector buyers. State-level renewable energy mandates in California, Texas, and Virginia directly influence site selection and power contracting strategies for new facilities. Stakeholders must weigh stranded asset risk in legacy colocation footprints against the capital intensity of liquid-cooled AI-ready designs.
Market Dynamics
Hyperscale cloud providers are consolidating control over the North America Hosting Infrastructure Services Market through proprietary chip architectures and vertically integrated facility designs, compressing margins for traditional colocation operators and forcing wholesale repositioning of competitive strategy.
Growth Catalysts
- FedRAMP Authorization Pathways:US federal procurement standards under the Federal Risk and Authorization Management Program create qualified vendor pipelines that accelerate public sector cloud migration and sustain multi-year contract visibility for compliant providers.
- Financial Services Workload Migration:Banking and capital markets firms are exiting owned data center assets in favor of managed hosting platforms that deliver operational resilience without balance sheet infrastructure ownership.
- Northern Virginia Data Center Corridor:Concentrated fiber density, tax incentive structures, and proximity to federal buyers in Ashburn and Loudoun County sustain the region's dominance in new capacity absorption.
Market Restraints
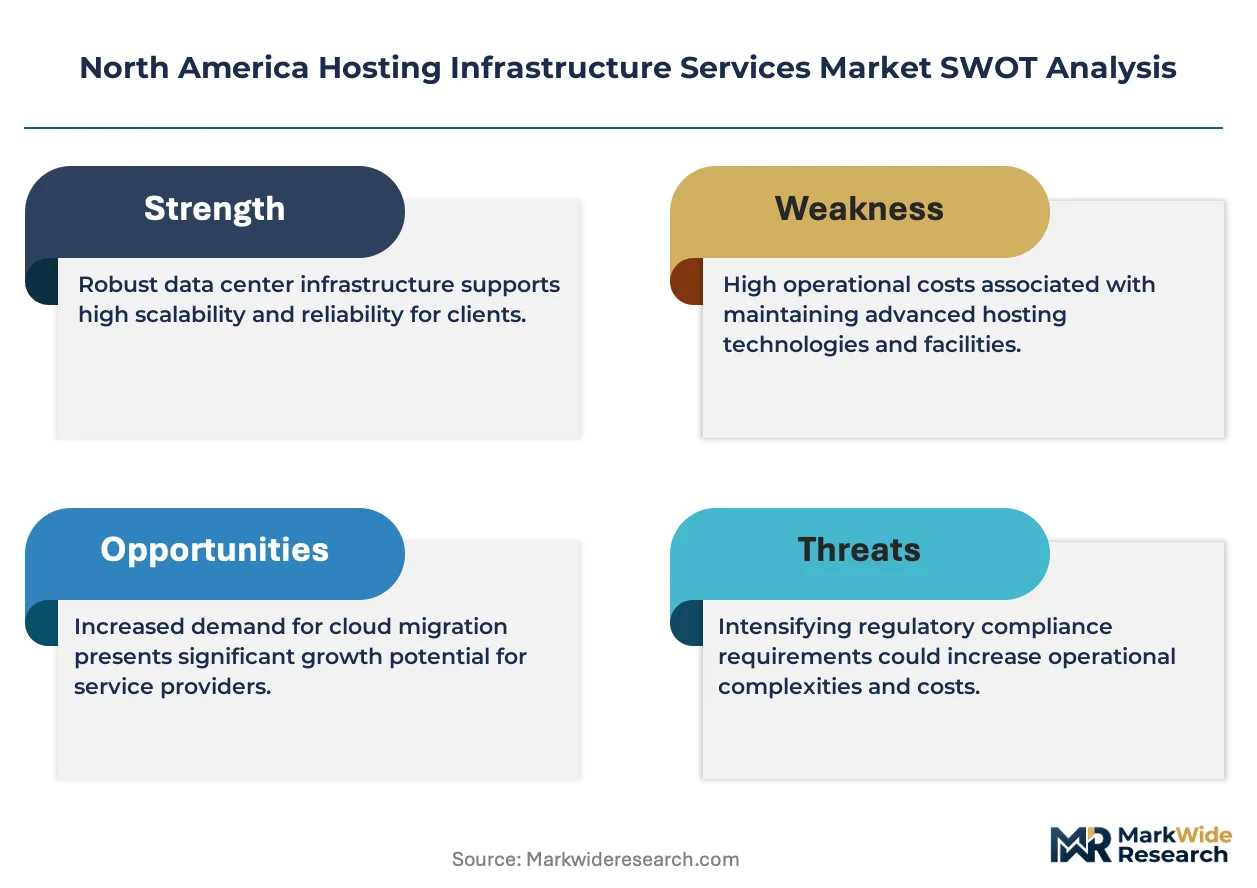
- Liquid-Cooled AI Facility Capex Burden:Next-generation GPU clusters require cooling infrastructure investments that triple traditional build costs, constraining expansion capital for mid-tier operators lacking hyperscale balance sheets.
- Stranded Legacy Colocation Assets:Aging facilities in secondary markets face accelerated obsolescence as enterprise demand concentrates in AI-ready designs, threatening impairment cycles for asset-heavy business models.
- Interconnection Pricing Compression:Dense fiber competition in primary markets erodes cross-connect revenue streams that historically subsidized facility operations, pressuring unit economics for retail colocation providers.
Strategic Opportunities
- Canada Shared Services Canada Cloud Standards:Federal security certification requirements create vendor qualification barriers that favor established operators with compliance infrastructure already deployed.
- Edge Computing Convergence with 5G:Low-latency application requirements are driving distributed micro-data center deployment partnerships between hosting providers and telecommunications infrastructure operators.
- California Renewable Energy Mandates:State-level clean power requirements accelerate demand for carbon-free energy matching capabilities, creating premium positioning for operators with contracted renewable portfolios.
Industry Challenges
- Liquid Cooling Engineering Talent Scarcity:Specialized thermal design expertise for direct-to-chip cooling systems remains concentrated among hyperscale engineering teams, constraining execution velocity for competitive builds.
- Hybrid Cloud Orchestration Complexity:Enterprise buyers demand seamless workload portability across on-premises, colocation, and public cloud environments, requiring integration capabilities that strain traditional managed hosting operational models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Hosting Infrastructure Services Market |
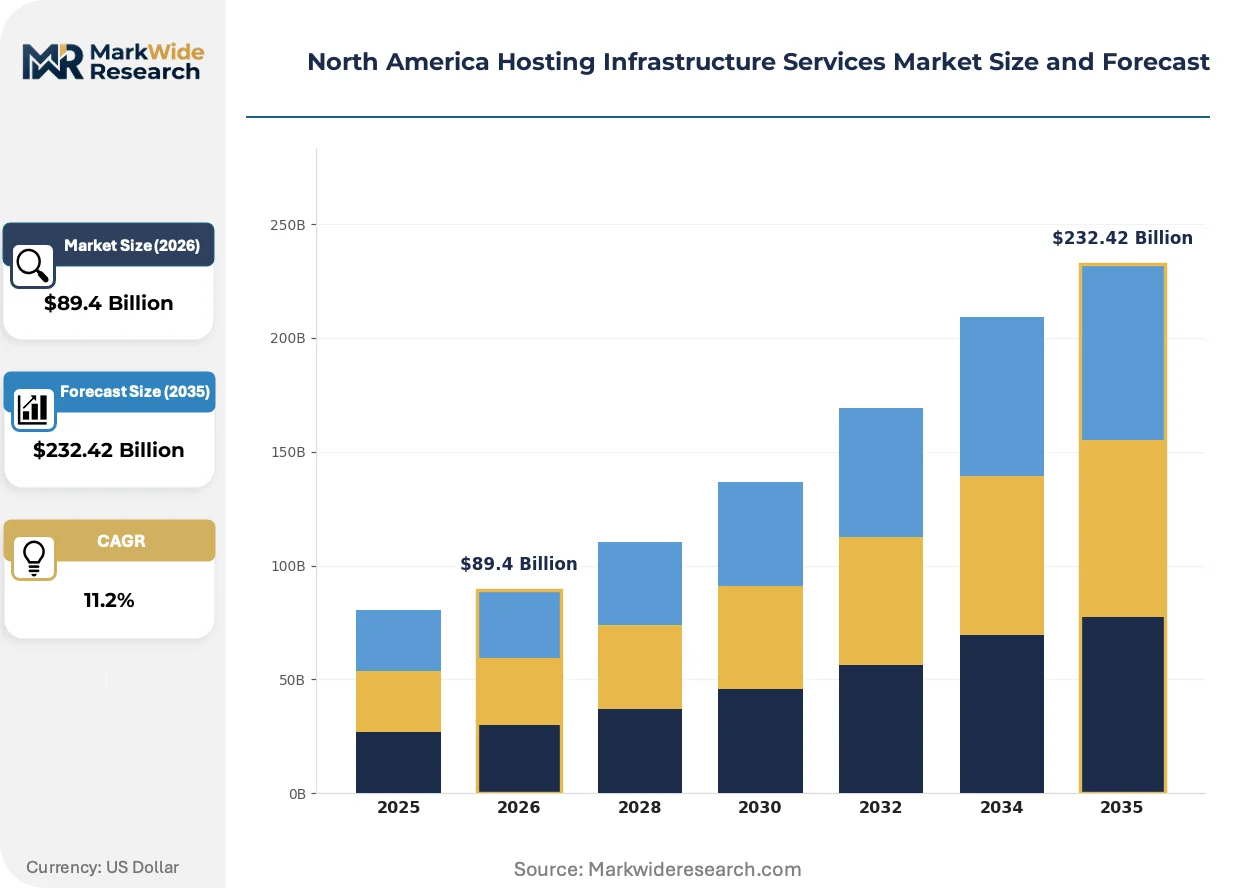
| Market Size in 2026 | $89.4 Billion |
| Market Size in 2035 | $232.42 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Dedicated Hosting, Cloud Hosting, Virtual Private Servers, Managed Hosting Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premise End User: Small Businesses, Enterprises, Startups, Government Agencies Technology: Linux, Windows, Containerization, Virtualization |
| Companies Covered | Amazon Web Services, Microsoft Corporation, Google Cloud Platform, IBM Corporation, Oracle Corporation, Equinix Inc., AT&T Inc., Rackspace Technology, Dell Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Hosting Infrastructure Services Market Trends and Innovations
Artificial intelligence compute demand is restructuring facility design priorities across North America, displacing conventional power density assumptions and accelerating investment in liquid-cooled infrastructure architectures.
Direct liquid cooling is consolidating as the dominant thermal management approach for AI training clusters exceeding 50 kilowatts per rack. Hyperscale operators and enterprise AI labs are mandating immersion and cold-plate designs for new deployments. This technology compression is rendering air-cooled legacy facilities economically uncompetitive for high-performance workloads.
Texas state-level renewable energy mandates and property tax abatement programs are reshaping site selection patterns for new hyperscale developments. ERCOT grid interconnection queues and wind power purchase agreements now factor prominently in facility economics. Data center operators are responding with concentrated land acquisition in the Dallas-Fort Worth corridor and West Texas renewable zones.
Enterprise procurement of hosting infrastructure is fragmenting across workload-specific sourcing strategies rather than consolidated vendor relationships. Financial services and healthcare buyers are unbundling storage, compute, and network services to optimize for regulatory jurisdiction and latency requirements. This pattern is most pronounced among multi-national corporations with Canadian data residency obligations under PIPEDA and provincial privacy statutes.
North America Hosting Infrastructure Services Market Segmentation
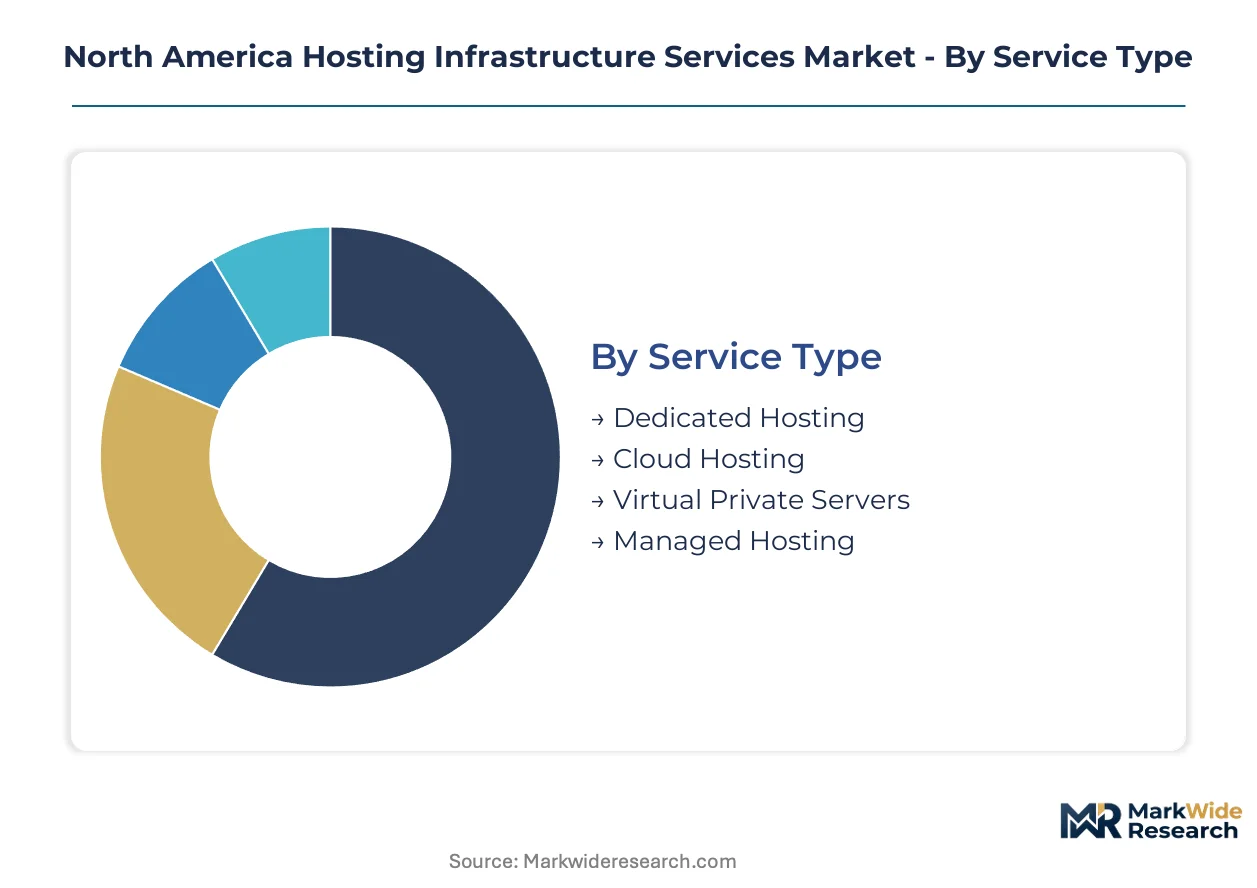
Hosting infrastructure procurement patterns diverge sharply by workload sensitivity, compliance posture, and capital availability. Buyers self-select into service tiers that trade operational control against scalability, creating distinct margin pools across the value chain.
Service Type:
Customization intensity spans from fully managed white-glove deployments to standardized self-service platforms, with pricing power concentrating at the managed end of the spectrum.
- Cloud Hosting:Elastic compute and storage resources delivered through hyperscale platforms with API-driven provisioning and consumption-based billing. Enterprise buyers in financial services and healthcare are consolidating workloads here to eliminate capital expenditure cycles and accelerate compliance certification through inherited platform attestations.
- Managed Hosting:Dedicated infrastructure with operational oversight provided by the vendor, including patching, monitoring, and security management. Northern Virginia and Dallas-Fort Worth corridors absorb the majority of new capacity as regulated industries prioritize operational resilience over cost minimization.
- Dedicated Hosting:Single-tenant physical servers with customer-managed software stacks.
- Virtual Private Servers:Partitioned compute instances on shared hardware with root access for technical users.
Most installed capacity flows through Cloud Hosting. Expansion is steepest in Managed Hosting.
Deployment:
Control boundaries determine procurement pathways, with hybrid architectures commanding premium positioning due to orchestration complexity.
- Hybrid Cloud:Integrated environments spanning on-premises, colocation, and public cloud resources with unified management planes. Banking and capital markets firms deploy this model to retain sensitive transaction processing on dedicated infrastructure while bursting analytics workloads to hyperscale clouds.
- Public Cloud:Shared multi-tenant infrastructure with no customer visibility into underlying physical resources. Startups and digital-native enterprises in Austin, Toronto, and Seattle metro areas drive absorption, prioritizing speed-to-market over data sovereignty controls.
- Private Cloud:Single-tenant virtualized environments with dedicated hardware isolation.
- On-Premise:Customer-owned facilities with no third-party operational involvement.
Hybrid Cloud captures the highest margin per rack, though Public Cloud dominates raw capacity absorption.
End User:
Procurement sophistication and contract scale separate buyer tiers, with government and enterprise segments driving qualified vendor pipeline development.
- Government Agencies:Federal, state, and municipal buyers with FedRAMP or StateRAMP authorization requirements. The US Department of Defense and civilian agencies anchor multi-year commitments in Northern Virginia, while Canadian federal buyers under Shared Services Canada standards concentrate demand in Toronto and Montreal corridors.
- Enterprises:Large corporations with dedicated procurement functions and custom security frameworks. Fortune 500 manufacturing and retail headquarters in Chicago, Detroit, and Atlanta metro areas are exiting owned facilities for managed platforms.
- Small Businesses:Organizations with limited technical staff and standardized workload requirements.
- Startups:Venture-backed and bootstrapped companies prioritizing variable cost structures.
Enterprises contribute the largest absolute contract value. Government Agencies are expanding most quickly due to cloud-first mandates.
Technology:
Platform selection locks in operational tooling and talent pools, with containerization emerging as the dominant abstraction layer for cloud-native workloads.
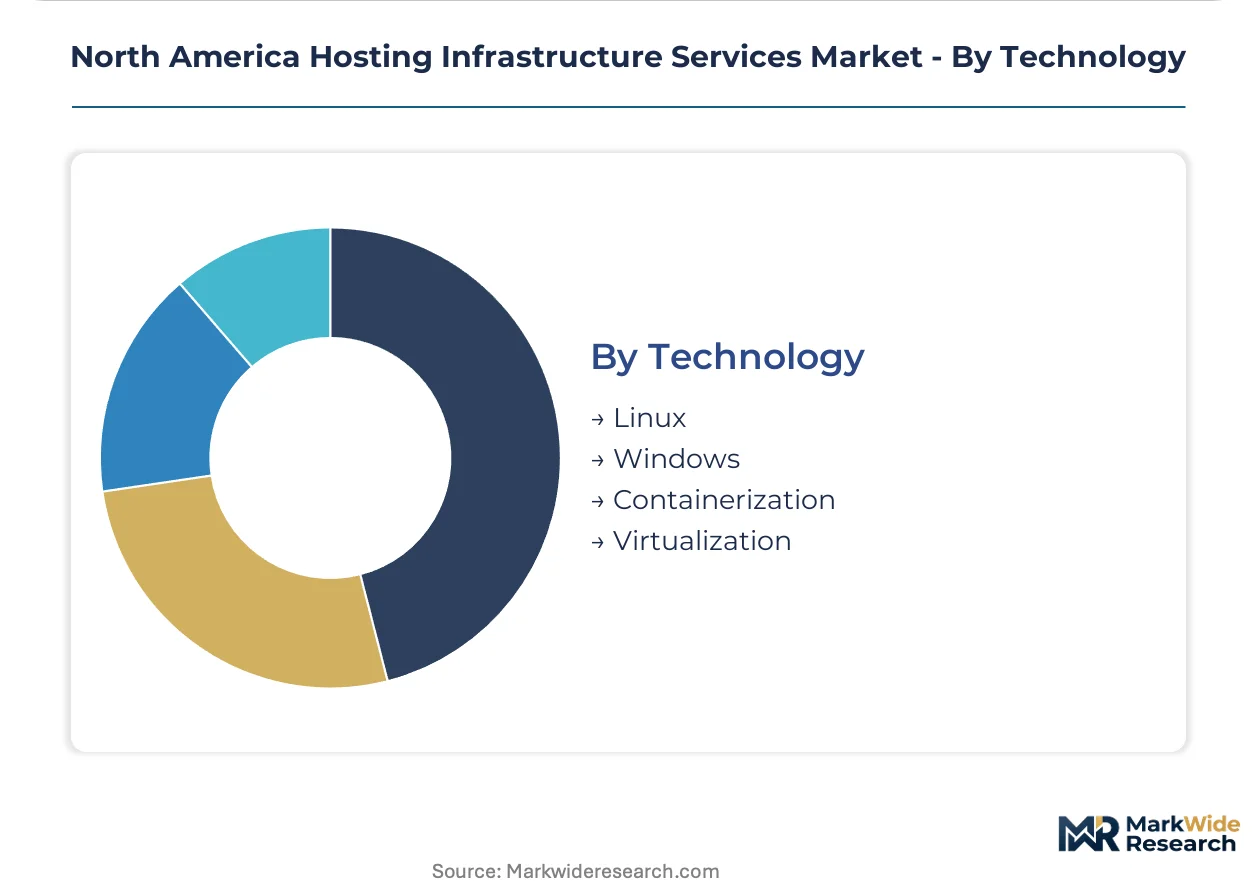
- Containerization:Operating-system-level virtualization through Docker and Kubernetes orchestration. Financial services DevOps teams in New York and San Francisco are mandating this stack for microservices deployments, driving demand for managed Kubernetes platforms.
- Linux:Open-source operating systems dominating web serving and high-performance computing workloads. Texas and California hyperscale developments standardize on custom Linux distributions optimized for energy efficiency.
- Virtualization:Hypervisor-based resource abstraction through VMware or KVM.
- Windows:Microsoft server operating systems with Active Directory integration for enterprise identity management.
Linux underpins the majority of installed web-facing infrastructure. Containerization is gaining share fastest among new deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States dominates North American hosting infrastructure capacity, while Canada builds sovereign cloud alternatives under distinct federal procurement frameworks. Mexico emerges as a latency-optimized edge corridor for cross-border workloads.
United States
Hyperscale cloud providers and financial services firms drive demand concentration in Northern Virginia's data center corridor. FedRAMP authorization pathways under the Federal Risk and Authorization Management Program create qualified vendor pipelines for federal buyers. Ashburn and Loudoun County absorb the majority of new capacity commitments as enterprises exit owned facilities for managed platforms.
Canada
Shared Services Canada cloud security standards shape federal procurement and sustain demand in Toronto and Montreal corridors. Provincial privacy statutes under PIPEDA drive data residency requirements for multinational enterprises. Quebec's hydroelectric power pricing attracts carbon-conscious operators building AI-ready facilities near Montreal.
Mexico
Querétaro and Mexico City metro areas attract edge computing deployments targeting sub-20 millisecond latency to US Southwest markets. The country's central bank and financial regulator supervise cloud outsourcing frameworks for domestic banks. Northern border states concentrate new fiber infrastructure investments supporting cross-border data flows.
North America Hosting Infrastructure Services Market Competitive Landscape
United States-based hyperscale operators anchor the premium tier; Canadian and regional specialists hold positions in sovereign cloud and managed hosting segments. Market structure concentrates around vertically integrated cloud platforms with proprietary silicon and facility designs, compressing margins for asset-heavy colocation operators. Three archetypes dominate: hyperscale cloud providers with captive infrastructure, wholesale data center developers with utility-scale power contracting, and managed hosting specialists with compliance certifications. Competitive moves center on liquid-cooled AI facility construction and strategic land banking in ERCOT-served Texas markets.
Within the hyperscale tier, Amazon Web Services and Microsoft Corporation exemplify vertically integrated operators controlling proprietary chip architectures and massive land positions. Google Cloud Platform occupies a position emphasizing Kubernetes-native infrastructure and carbon-free energy matching capabilities.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Corporation |
| Google Cloud Platform |
| IBM Corporation |
| Oracle Corporation |
| Equinix Inc. |
| AT&T Inc. |
| Rackspace Technology |
| Dell Technologies |
| Others |
Pricing and Supply Chain Analysis
Federal procurement officers under FedRAMP authorization pathways concentrate demand for compliant hosting tiers, anchoring contract-based long-term offtake structures that insulate premium pricing from spot-market volatility. This buyer archetype clustering reinforces three-tier pricing stratification across hyperscale cloud, managed hosting, and legacy colocation segments.
Pricing Analysis
Capacity additions in Northern Virginia and Dallas-Fort Worth corridors are reshaping price floors for standard compute tiers while liquid-cooled AI-ready facilities command certification-grade premiums. Pricing stratifies across FedRAMP-authorized premium tiers, standard enterprise managed hosting, and economy self-service cloud instances. Cost compression in retail colocation intensifies as hyperscale direct contracting bypasses intermediary layers. Startups and digital-native enterprises exhibit highest price sensitivity; government agencies demonstrate lowest sensitivity due to compliance-driven vendor qualification requirements.
Supply Chain Analysis
Freight logistics for specialized cooling equipment and proprietary chip architectures from Taiwan, South Korea, and the United States dominate capital deployment timelines. Facility construction draws from Chinese-manufactured electrical switchgear, domestically sourced concrete and steel, and Korean-built precision cooling systems. Single-source vulnerability in liquid cooling componentry threatens expansion velocity for mid-tier operators. Distribution runs through hyperscale direct sales forces, wholesale data center developers, and regional managed hosting specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FedRAMP authorization milestones and Canada's Shared Services Canada standards create qualified vendor pipelines that accelerate demand concentration among pre-certified operators.
For Market Incumbents: Anchor defensible positioning through backward integration into proprietary silicon designs and captive renewable energy contracting in ERCOT-served Texas markets. Liquid-cooled facility engineering talent scarcity threatens execution velocity for competitive builds; incumbents should consolidate specialized thermal design capabilities through targeted hiring from hyperscale engineering teams. Certification investment in dual FedRAMP-StateRAMP pathways creates switching costs that protect multi-year contract visibility against emerging cloud-native entrants. For New Entrants and Emerging Players: Launch via edge computing partnerships with telecommunications infrastructure operators targeting sub-20 millisecond latency corridors in Mexico's Querétaro and northern border states. The most penetrable white space sits in sovereign cloud alternatives for Canadian provincial data residency obligations under PIPEDA. Managed Kubernetes platforms for financial services DevOps teams in Toronto and Montreal offer a differentiated go-to-market angle against hyperscale commodity pricing. For Investors and Strategic Acquirers: Hyperscale cloud providers with captive infrastructure needs are the most active acquirers in this space, targeting wholesale data center developers with utility-scale power contracting in place. Long-term viability favors asset-light orchestration platforms over capital-intensive facility ownership given AI-driven power density transitions. Watch liquid-cooled facility deployment velocity as the inflection indicator for stranded legacy asset risk.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid-Cooled Facility Construction | Direct-to-chip thermal designs from AWS and Microsoft render air-cooled legacy assets economically obsolete. |
| Strategic Land Banking | Concentrated acreage acquisition in West Texas renewable zones secures ERCOT interconnection queue positioning. |
| FedRAMP Authorization Investment | Compliance infrastructure deployment opens multi-year federal procurement pipelines with sustained contract visibility. |
| Renewable Energy Contracting | Wind power purchase agreements in California and Texas satisfy state-level clean power mandates. |
| Edge Computing Partnership | Micro-data center deployment with Verizon and AT&T targets 5G low-latency application requirements. |
Research Methodology
Direct dialogue with data center operations executives, federal procurement officers, cloud platform engineers, and renewable energy developers grounded qualitative insights in operational reality. Secondary validation drew from hyperscaler capex disclosures, FERC interconnection filings, EIA power market data, and Shared Services Canada procurement records. Bottom-up facility-level capacity tracking and top-down enterprise IT spending analysis were triangulated to anchor segmentation outputs.
Bottom-up modeling aggregated individual facility announcements, power interconnection queues, and land acquisition records across the projection horizon. Segmentation dimensions included service type, deployment architecture, end-user vertical, and technology stack. CAGRs were derived from fitted growth curves against historical absorption patterns in Northern Virginia and Dallas-Fort Worth corridors. Forecast inputs incorporated AI compute demand trajectories and state-level renewable energy mandate compliance timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated AI demand scenarios or liquid cooling supply chain disruptions. Projections reflect assumptions around FedRAMP authorization velocity and ERCOT grid reliability. A model refresh is warranted upon material change in federal cloud-first procurement mandates or state-level data residency legislation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Chile Data Center Processor Market
Data Center Infrastructure
Data Center Substation Market
Data Center Infrastructure
White Box Server Market
Data Center Infrastructure
Sweden Data Center Market
Data Center Infrastructure
Italy Data Center Physical Security Market
Data Center Infrastructure
Philippines Data Center Market
Data Center Infrastructure
Global Hyper-Converged Infrastructure Market
Data Center Infrastructure
APAC Data Center Server Market
Data Center Infrastructure
France Data Center Rack Market
Data Center Infrastructure
Datacenter Infrastructure Services Market
Data Center Infrastructure
Paris Data Center Market
Data Center Infrastructure
China Internet Data Center Market
Data Center Infrastructure
Israel Data Center Rack Market
Data Center Infrastructure
Data Processing and Hosting Services Market
Data Center Infrastructure
Singapore Data Center Physical Security Market
Data Center Infrastructure
Data Center Monitoring Systems Market