
 Europe Articulated Robot Market | 2026-2036
Europe Articulated Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Articulated Robot Market Intelligence
The gap between premium precision systems and commodity handling units is repositioning how European manufacturers structure their automation budgets. ABB Ltd leverages its Nordic engineering heritage to dominate high-accuracy welding and assembly lines. KUKA AG anchors German automotive production with deep integration into OEM paint and body shops. Fanuc Corp sustains its position through relentless manufacturing scale and a dense service network across Continental Europe.
An articulated robot employs serial-linked rotary joints—typically four to seven axes—to manipulate payloads with sub-millimeter repeatability in three-dimensional workspace envelopes. These systems execute continuous-path operations including arc welding, material handling, and machine tending across factory floors. Industrial robots still command the largest installed base, though collaborative robots are capturing the fastest expansion as SMEs seek fenceless, human-parallel operations. Automotive Assembly applications retain the deepest margin pools due to cycle-time sensitivity and multi-decade supplier relationships, while Electronics Manufacturing is gaining share on the back of miniaturization demands and cleanroom compatibility requirements.
The EU Machinery Directive, CE marking protocols, and ISO 10218 safety standards collectively determine product compliance costs and market access timelines for any articulated robot sold in Europe. ECHA's REACH restrictions on lubricants and surface coatings further shape material selection and supply chain qualification burdens. Stakeholders must monitor how the EU AI Act intersects with autonomous motion planning algorithms, as this regulatory boundary will soon differentiate compliant platforms from stranded installations.
Market Dynamics
The EU Machinery Directive's tightened safety requirements are compressing vendor certification timelines while automotive OEMs demand faster cycle-time guarantees, creating a structural squeeze between compliance burden and operational urgency.
Growth Catalysts
- CE Marking Acceleration:The EU Machinery Directive's 2023 amendments mandate faster conformity assessment pathways, pushing integrators toward pre-certified modular platforms that slash deployment lead times for Bavarian automotive suppliers.
- Battery Gigafactory Buildouts:Hungary and Poland's expanding lithium-ion cell production lines require precision welding and handling systems, generating concentrated demand for six-axis articulated units in cleanroom-rated configurations.
- Labor Cost Compression:German metalworking and French aerospace sub-tier suppliers face wage pressures exceeding productivity gains, accelerating substitution of manual tending with servo-driven articulated cells.
Market Restraints
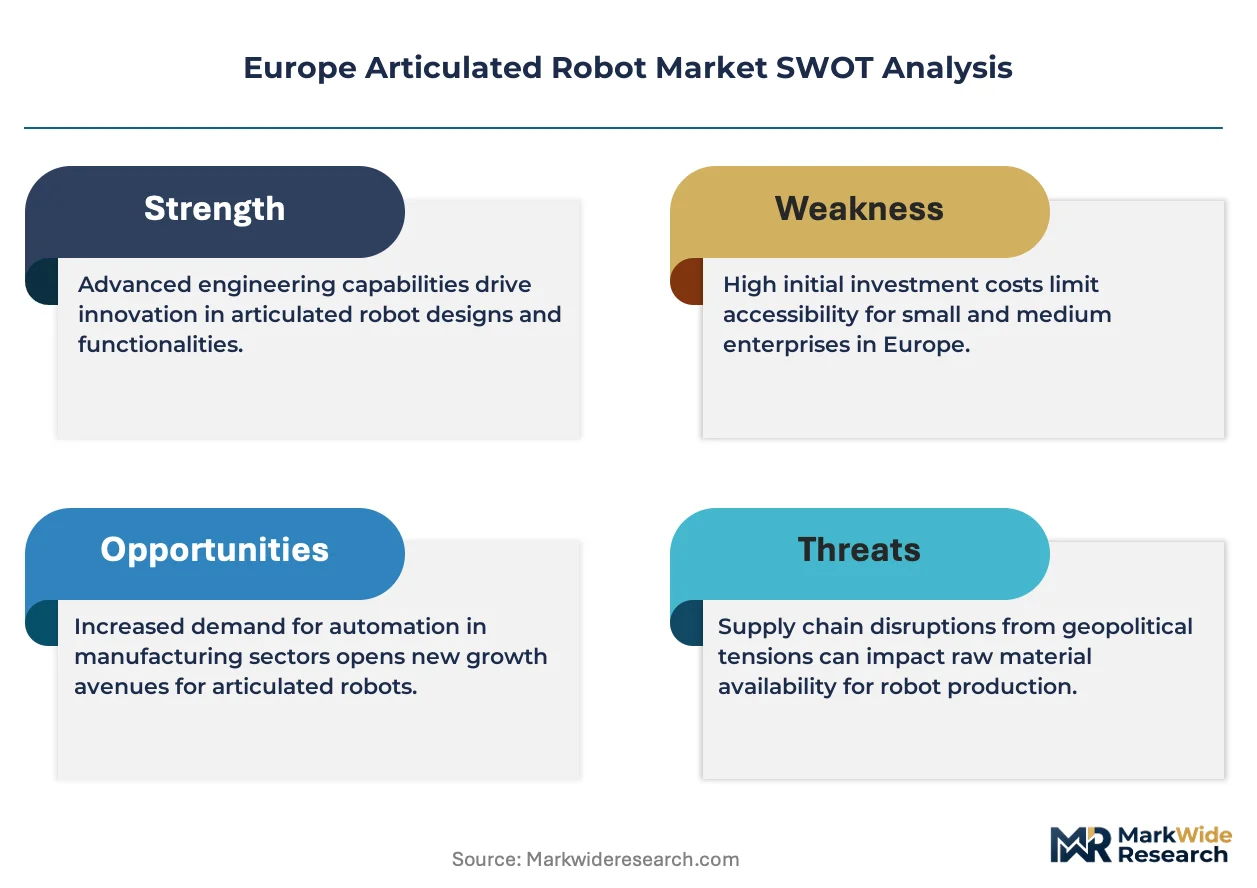
- Rare Earth Magnet Volatility:Neodymium and dysprosium price swings from Chinese processing concentration directly impact servo motor costs, squeezing margin predictability for mid-tier European robot manufacturers.
- REACH Compliance Burden:ECHA's expanding restricted substance lists for lubricants and cable sheathing force reformulation cycles that extend qualification timelines by 8-14 months for new product introductions.
- Cobotics Safety Certification:ISO/TS 15066's force-limiting requirements add €15,000-€40,000 per collaborative unit in sensor and control hardware, limiting price competitiveness against conventional guarded systems.
Strategic Opportunities
- Spanish Automotive Retooling:Seat-Volkswagen's Martorell complex and emerging EV suppliers in Zaragoza represent underpenetrated demand for paint shop automation and battery module assembly lines.
- AI Act Algorithmic Compliance:The EU AI Act's risk-based classification for autonomous motion planning creates first-mover advantage for vendors pre-certifying adaptive path-generation software ahead of 2025 enforcement windows.
- Remanufacturing Channel Expansion:Circular economy mandates under the EU Green Deal incentivize certified refurbishment programs, opening recurring revenue streams through controller upgrades and mechanical rebuilds for installed KUKA and ABB bases.
Industry Challenges
- Systems Integration Talent Scarcity:German integrators report 18-month backlogs for PLC programming and robotic commissioning specialists, constraining deployment velocity regardless of hardware availability.
- Legacy Equipment Interoperability:SINUMERIK and FANUC CNC controllers from the 1990s-2000s lack native OPC-UA connectivity, forcing expensive gateway hardware and custom middleware development for brownfield automation projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Articulated Robot Market |
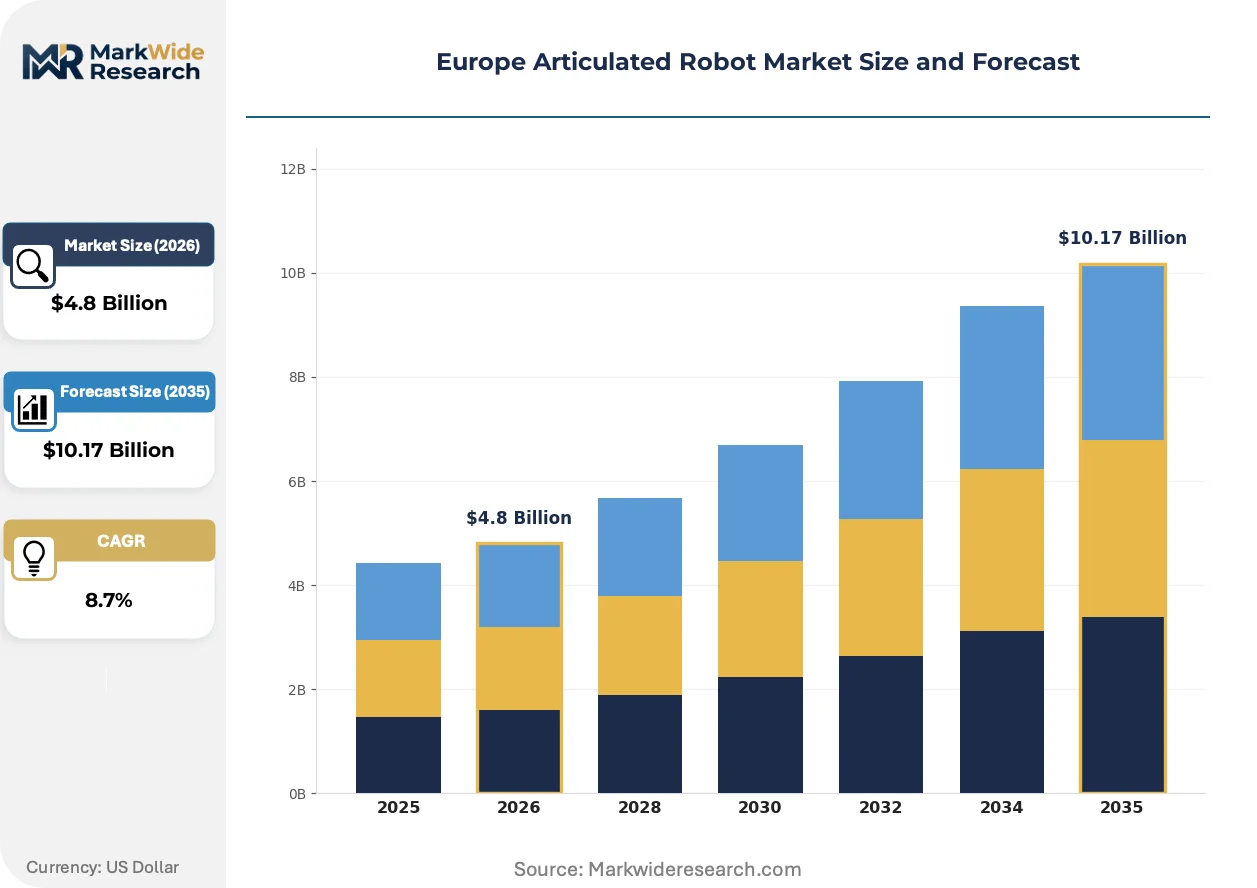
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Robots, Collaborative Robots, Service Robots, Mobile Robots Application: Automotive Assembly, Electronics Manufacturing, Metal Fabrication, Food Processing End User: Manufacturing, Healthcare, Logistics, Education Technology: Artificial Intelligence, Machine Learning, Automation Software, Motion Control |
| Companies Covered | ABB Ltd, KUKA AG, Fanuc Corp, Yaskawa Electric Corp, Mitsubishi Electric Corp, Kawasaki Heavy Industries Ltd, Comau, OMRON Corp, Stäubli, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Articulated Robot Market Strategic Shifts & Innovations
Digital twin architectures and edge-native control systems are collapsing the traditional boundary between simulation and physical deployment, enabling faster commissioning cycles and predictive maintenance models that reshape supplier-customer relationships.
Force-torque sensing arrays with haptic feedback loops are integrating into collaborative articulated platforms, enabling real-time surface-following for polishing and deburring operations. Tier-two automotive suppliers in Stuttgart's industrial belt are adopting these systems at pilot scale, with the technology compressing the traditional fence-guarded versus fenceless equipment distinction and opening smaller batch sizes to automation.
The EU AI Act's risk classification framework for autonomous decision-making systems is forcing vendors to re-architect motion planning algorithms around explainability and human override requirements. High-risk manufacturing applications including welding parameter adaptation now require documented conformity assessments, with German integrators front-loading compliance engineering to secure 2025 tender eligibility.
Small and mid-sized metalworking enterprises are consolidating vendor relationships around full-service automation partners who bundle hardware, programming, and remote monitoring subscriptions. This preference shift displaces the traditional equipment-only procurement model, with Baden-Württemberg's Mittelstand manufacturers leading the transition toward outcome-guaranteed performance contracts.
Europe Articulated Robot Market Segmentation
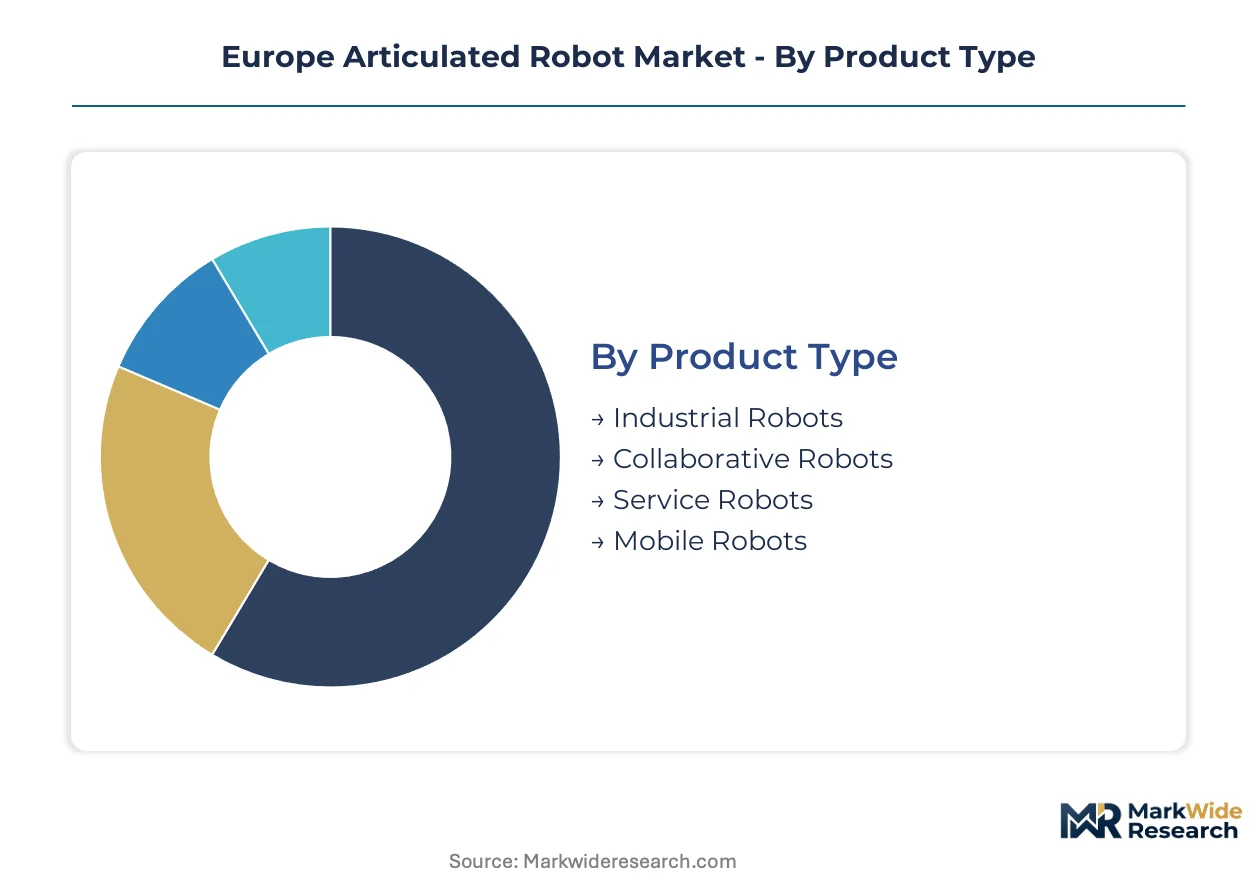
European manufacturers structure their articulated robot procurement around integration depth, with standalone heavy-payload systems dominating automotive body shops while embedded collaborative units penetrate fenceless SME environments. Segmentation choices directly determine compliance pathways under the EU Machinery Directive and CE marking requirements.
Product Type:
Integration depth separates standalone heavy-payload systems from embedded collaborative platforms, with each tier demanding distinct safety architectures and commissioning protocols.
- Industrial Robots:Six-axis serial-link architectures handle payloads exceeding 200 kg with sub-millimeter repeatability in guarded automotive paint and body shops. German OEMs in Bavaria and Baden-Württemberg anchor demand for these systems as labor costs outpace productivity gains in metal-intensive operations.
- Collaborative Robots:Force-limited articulated arms with ISO/TS 15066-compliant torque sensing enable fenceless human-parallel operation in batch-size-one production. French aerospace sub-tier suppliers around Toulouse are adopting these platforms to compress changeover times without dedicated safety infrastructure.
- Service Robots:Articulated manipulators for non-industrial tasks including inspection and maintenance in hazardous environments.
- Mobile Robots:Autonomous platforms with articulated manipulation for intralogistics and flexible material transport.
Volume placements concentrate in Industrial Robots; the faster expansion belongs to Collaborative Robots.
Application:
Cost tier stratification positions high-margin automotive applications against price-sensitive food processing, with electronics manufacturing capturing mid-tier investment cycles.
- Automotive Assembly:Continuous-path welding and sealing operations demand multi-decade supplier relationships and cycle-time guarantees. Seat-Volkswagen's Martorell complex and emerging EV suppliers in Zaragoza represent concentrated demand for paint shop automation and battery module handling.
- Electronics Manufacturing:Cleanroom-rated six-axis units execute precision component placement and miniaturized assembly. Hungarian and Polish lithium-ion cell production lines are generating demand for cleanroom-compatible welding and handling configurations.
- Metal Fabrication:Arc welding and machine tending applications serving German metalworking SMEs facing wage pressures.
- Food Processing:Hygienic-design articulated systems for packaging and palletizing in washdown environments.
Margin concentration sits with Automotive Assembly; Electronics Manufacturing is climbing the fastest.
End User:
Customer type diversity spans capital-intensive manufacturing against emerging healthcare and education deployments with distinct procurement rhythms.
- Manufacturing:Primary demand center spanning automotive, electronics, and metal fabrication with established automation budgets and integration expertise.
- Healthcare:Surgical assistance and rehabilitation applications requiring MDR compliance and specialized safety validation.
- Logistics:Intralogistics automation for e-commerce fulfillment and warehouse operations.
- Education:Training and research platforms for technical universities and vocational institutes.
Procurement scale favors Manufacturing; steepest expansion trajectory belongs to Healthcare.
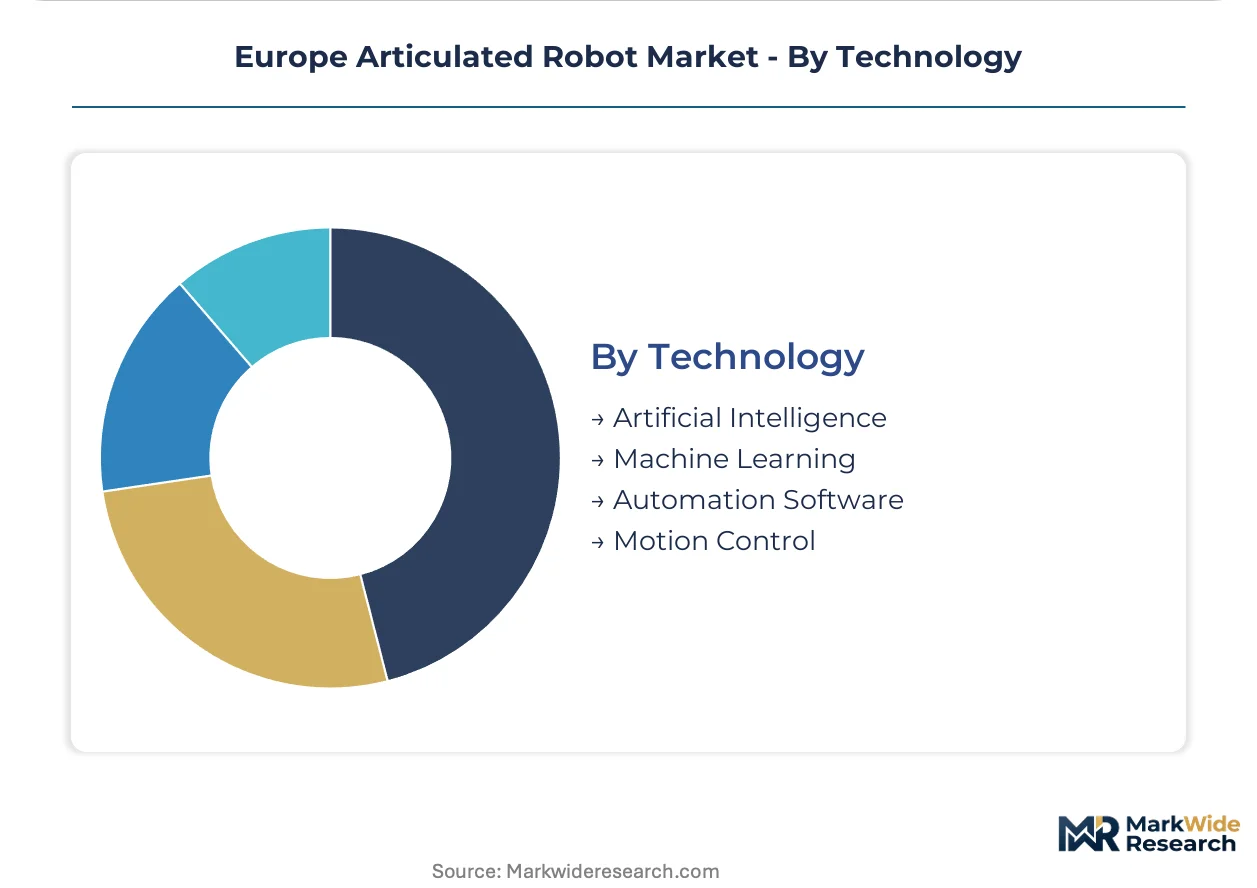
Technology:
Maturity gradients separate proven motion control architectures from emerging AI-driven adaptive systems facing EU AI Act compliance timelines.
- Artificial Intelligence:Autonomous motion planning and parameter adaptation now require documented conformity assessments under the EU AI Act's risk classification framework. German integrators are front-loading compliance engineering to secure tender eligibility ahead of enforcement windows.
- Machine Learning:Predictive maintenance models trained on operational data reshape supplier-customer relationships around uptime guarantees.
- Automation Software:Digital twin architectures and edge-native control systems collapsing simulation-to-deployment cycles.
- Motion Control:Established servo motor and drive technologies with proven CE marking pathways.
Deployment prevalence rests with Motion Control; AI is gaining share fastest as vendors pre-certify adaptive path-generation software.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European articulated robot deployment, with Baden-Württemberg's industrial belt hosting the densest concentration of automotive integrators and precision metalworking suppliers.
Germany
Bavarian automotive OEMs and Baden-Württemberg's Mittelstand metalworkers drive demand for six-axis welding and handling systems. The EU Machinery Directive's CE marking protocols compress vendor certification timelines for suppliers in these regions. Stuttgart, Augsburg, and Munich form a contiguous automation corridor where system integrators report 18-month backlogs for PLC programming specialists.
France
Aerospace sub-tier suppliers around Toulouse and Renault-Nissan production lines in Paris-Saclay accelerate collaborative robot adoption for batch-size-one flexibility. REACH restrictions from ECHA force reformulation cycles for lubricants and cable sheathing that extend qualification timelines. The Île-de-France and Occitanie regions concentrate demand for fenceless human-parallel operations in cleanroom-rated configurations.
Italy
Lombardy's machine tool builders and Emilia-Romagna's packaging machinery specialists integrate articulated arms for machine tending and palletizing. The EU Green Deal's circular economy mandates incentivize certified refurbishment programs for installed robot bases. Turin and Bologna host emerging integrator networks serving food processing and pharmaceutical packaging lines.
Spain
Seat-Volkswagen's Martorell complex and emerging EV suppliers in Zaragoza represent underpenetrated demand for paint shop automation and battery module assembly. Spanish automotive retooling lags German investment cycles by 24-36 months, creating catch-up potential. Catalonia and Aragón industrial zones are attracting German and Japanese system integrators seeking lower-cost deployment bases.
Hungary
Battery gigafactory buildouts near Debrecen and Győr generate concentrated demand for cleanroom-rated six-axis welding and handling systems. EU cohesion funds and national investment incentives accelerate foreign direct investment in lithium-ion cell production. The Hungarian government's industrial park development program targets automotive and electronics suppliers with streamlined permitting for automation-intensive facilities.
Europe Articulated Robot Market Key Industry Players
Premium-margin players sit above commodity-margin players across precision certification tiers, with high-accuracy welding specialists commanding 40-60% price premiums over standard handling units. The vendor base clusters around three strategic archetypes: Nordic-engineering heritage firms dominating automotive body shops, Japanese scale manufacturers sustaining dense Continental service networks, and German integrators anchoring OEM paint line relationships. Competitive moves concentrate on pre-certified modular platforms that slash deployment lead times and AI Act compliance engineering that secures 2025 tender eligibility.
Among Nordic-based precision specialists, ABB Ltd occupies a position exemplifying high-accuracy welding and assembly line dominance. KUKA AG represents the German automotive-anchored archetype with deep OEM integration heritage. Fanuc Corp sits within the scale-driven tier, sustaining market presence through manufacturing volume and service network density across Continental Europe. These three anchors illustrate how engineering origin, customer relationship depth, and production scale differentiate competitive positioning in European procurement cycles.
| Leading Market Players |
|---|
| ABB Ltd |
| KUKA AG |
| Fanuc Corp |
| Yaskawa Electric Corp |
| Mitsubishi Electric Corp |
| Kawasaki Heavy Industries Ltd |
| Comau |
| OMRON Corp |
| Stäubli |
| Others |
Cost & Logistics Intelligence
Stuttgart's concentration of PLC programming and robotic commissioning specialists widens pricing-tier spreads between Bavarian automotive OEMs and peripheral metalworking SMEs, with labor-cost differentials compressing margins for mid-tier integrators serving price-sensitive batch producers.
Pricing Analysis
Value-based pricing anchored to cycle-time guarantees and uptime performance dominates automotive procurement, separating premium CE-marked welding cells from standard handling units. Certification grade under the EU Machinery Directive and after-sales service bundling drive price differentiation across tiers. Cost compression in commodity handling configurations is intensifying because Chinese servo motor imports undercut European manufacturing. Batch-size-one metalworking SMEs exhibit highest price sensitivity; multi-decade automotive OEM relationships show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Seat-Volkswagen and BMW, while distributor networks serve fragmented Mittelstand metalworkers. Servo motor production draws from China, Japan, and Germany; precision gearboxes source from Switzerland and Japan; rare earth magnets concentrate in Chinese processing facilities. Neodymium and dysprosium price volatility from single-source Chinese refining creates margin unpredictability for European manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Articulated Robot Market sits in a technology-transition phase, with AI-driven adaptive path-generation displacing legacy fixed-sequence controllers under EU AI Act compliance timelines.
For Market Incumbents: Lock in multi-year service contracts with Baden-Württemberg automotive OEMs before 2025 tender eligibility windows close. Prioritize backward integration into servo drive manufacturing to offset rare earth magnet cost volatility from Chinese suppliers. CE marking pre-certification for collaborative platforms defends against emerging Asian entrants. For New Entrants and Emerging Players: Launch via certified refurbishment programs targeting Italy's circular economy mandates under the EU Green Deal. Spanish EV battery module assembly lines around Zaragoza represent the most penetrable geography, lagging German investment cycles. Target outcome-guaranteed performance contracts to displace equipment-only procurement models. For Investors and Strategic Acquirers: Re-rating potential sits with AI Act-compliant software vendors given enforcement window proximity. Five-to-ten year viability favors integrators with proprietary digital twin architectures collapsing commissioning cycles. Watch Hungarian battery gigafactory buildout velocity as inflection indicator for cleanroom-rated six-axis demand.| Strategic Initiative | Industry Significance |
|---|---|
| AI Act Compliance Pre-Certification | Secures tender eligibility ahead of enforcement windows for German integrators. |
| Backward Integration into Servo Manufacturing | Reduces exposure to Chinese rare earth magnet price volatility. |
| Certified Refurbishment Program Expansion | Captures EU Green Deal circular economy incentives in Italy. |
| Digital Twin Architecture Deployment | Collapses simulation-to-commissioning cycles for Stuttgart automotive suppliers. |
| Spanish EV Supplier Partnership | Exploits 24-36 month investment lag in Martorell and Zaragoza corridors. |
Research Approach
Multi-period observation of CE marking certification timelines, battery gigafactory investment flows, and integrator backlog durations anchored the trend analysis, supplemented by interviews with automotive OEM procurement directors, systems integration firm technical leads, robotic controller R&D heads, and aftermarket service managers. Secondary validation drew from EU Machinery Directive amendment texts, ECHA REACH substance restriction updates, SEC filings of listed automation vendors, and Hungarian industrial park development records. Bottom-up deployment estimates across Bavarian and Baden-Württemberg manufacturing clusters triangulated against top-down European automation capex aggregates.
Input-output matrices mapped articulated robot demand across product type, application, end user, and technology segments over the projection horizon. Modeled dimensions spanned industrial versus collaborative platform architectures, automotive versus electronics manufacturing end-uses, and motion control versus AI-driven control technologies. CAGRs were derived from regression analysis of historical installation data against labor cost indices and regulatory compliance cost trajectories. Forecast inputs incorporated EU cohesion fund disbursement schedules for Hungarian battery facilities and Spanish automotive retooling cycles.
Rare earth supply disruption, EU AI Act enforcement timing shifts, and German systems integration talent scarcity are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding CE marking pathway stability and Chinese magnet export policy continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Smart Curtain Robot Market
Robotics and Automation
Africa Agricultural Robots and Mechatronics Market
Robotics and Automation
AGV Intelligent Management Systems Market
Robotics and Automation
Robotics-Ready Fulfillment Center Design and Integration Services Market
Robotics and Automation
Global Enterprise Robotic Process Automation Market
Robotics and Automation
Smart Machines Market
Robotics and Automation
Mobile Robotics Software Market
Robotics and Automation
Robotic Process Automation in BFSI Market
Robotics and Automation
Robot for Public Service Market
Robotics and Automation
Europe Robotics and Automation Actuators Market
Robotics and Automation
Firefighting Robots Market
Robotics and Automation
Latin America Warehouse Robotics Market
Robotics and Automation
Latin America Automated Guided Vehicle (AGV) Market
Robotics and Automation
Robot As a Service Market
Robotics and Automation
Bot Services Market
Robotics and Automation
Smart Lawn Robot Market