
 Saudi Arabia French Fries Market | 2026-2036
Saudi Arabia French Fries Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia French Fries Market Intelligence
Quick-service restaurant chains are bifurcating from traditional foodservice distributors toward direct supplier relationships. McCain Foods leverages its regional production footprint to secure long-term contracts with major burger chains. Lamb Weston anchors its position through specialized cut varieties tailored to Middle Eastern menu preferences. Farm Frites competes on certified halal processing lines that align with local dietary requirements.
French fries are par-fried potato strips, typically blanched at 85–95°C and flash-frozen at minus 35°C to preserve starch structure and reheat performance. Frozen product type dominates volume throughput due to extended shelf stability and operational convenience for high-turnout kitchens. Steak cut thickness commands premium positioning in casual dining, while thin cuts saturate fast-food value menus. Bulk packaging type channels the majority of institutional procurement, though pouch formats gain traction in retail as home-prep habits expand.
SFDA mandates HACCP-aligned cold-chain documentation for all frozen potato imports, while SASO enforces labeling and nutritional disclosure standards on retail formats. The General Food Security Authority's import quota mechanisms influence seasonal supply availability and landed cost structures. Stakeholders must monitor evolving halal certification protocols and local content incentives under Vision 2030 industrial localization targets.
Market Dynamics
Quick-service restaurant chains in Saudi Arabia are consolidating procurement through direct supplier relationships, bypassing traditional foodservice distributors as cold-chain compliance costs reshape margin structures.
Growth Catalysts
- Vision 2030 localization incentives:Industrial policy targets domestic food manufacturing capacity expansion, creating procurement preference for locally produced frozen potato products.
- Quick-service restaurant expansion:Burger and fried chicken chains are extending their Saudi footprint, driving institutional volume demand for standardized fry cuts.
- Air fryer adoption:Home appliance penetration is expanding retail pouch format demand as consumers replicate restaurant-style preparation.
Market Restraints
- Import quota mechanisms:The General Food Security Authority's seasonal allocation limits create supply availability constraints and landed cost volatility.
- Potato input concentration:Raw material sourcing depends on contracted European and North American growers, exposing processors to currency and freight fluctuations.
- SFDA cold-chain documentation:HACCP-aligned compliance requirements impose capital-intensive infrastructure investments on distributors and importers.
Strategic Opportunities
- Halal-certified processing expansion:Dedicated production lines meeting Islamic dietary requirements unlock export potential to Gulf Cooperation Council markets.
- Eastern Province penetration:Dammam and Khobar restaurant density remains below Riyadh and Jeddah levels, presenting whitespace for distributor expansion.
- Retail channel innovation:Direct-to-consumer frozen potato subscription models are emerging through grocery delivery platforms.
Industry Challenges
- Temperature-controlled logistics talent:Specialized cold-chain operations management expertise remains scarce in the Saudi labor market.
- Halal certification timeline:Multi-stage approval processes with religious authorities extend product launch cycles for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia French Fries Market |
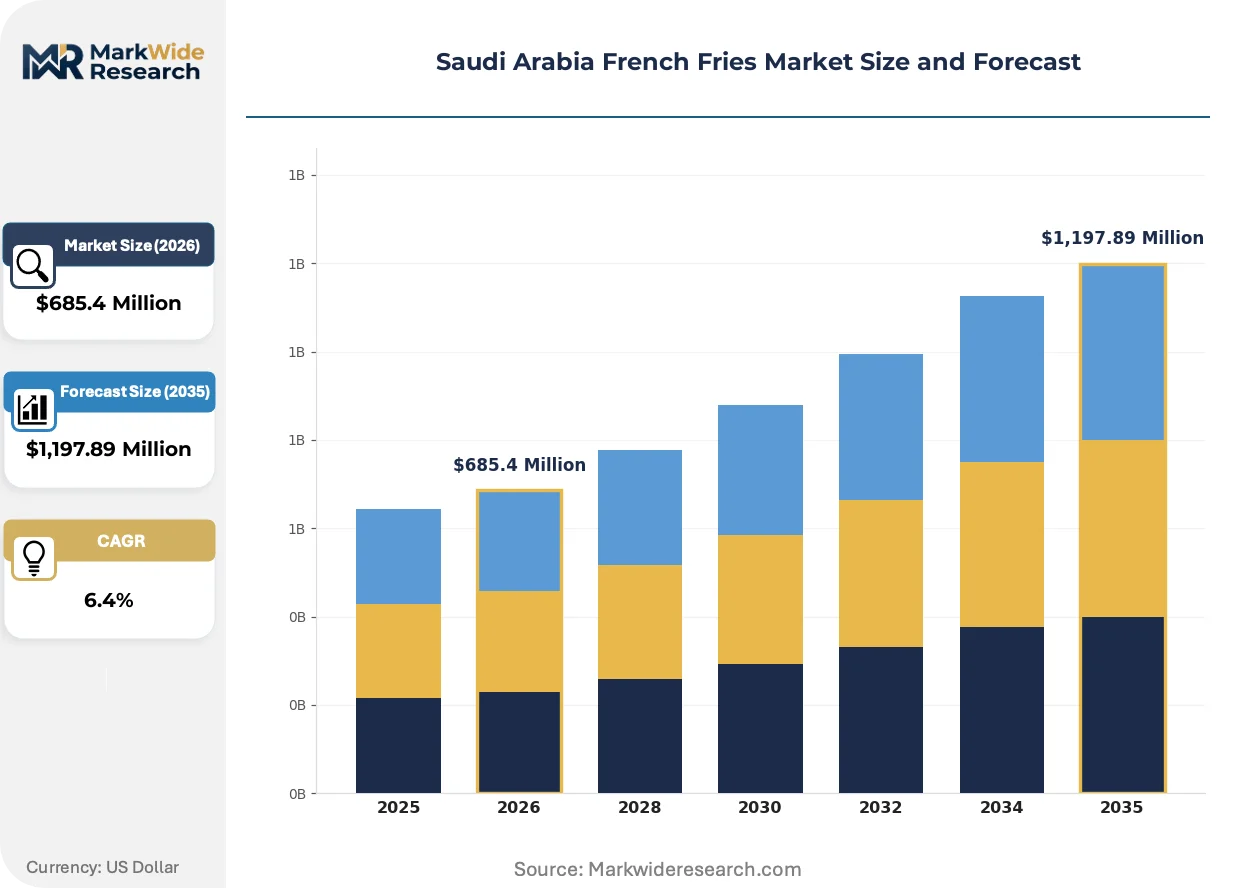
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,197.89 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen, Fresh, Dehydrated, Gourmet End User: Restaurants, Fast Food Chains, Retail, Food Services Thickness: Thin, Regular, Steak Cut, Crinkle Cut Packaging Type: Bulk, Sachets, Tray Packs, Pouches |
| Companies Covered | Al Jouf, McCain Foods, Americana Holding for Food, Lamb Weston, Simplot, Farm Frites, Kuwait Food Company, Aviko, Agricultural Growth and Processing Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia French Fries Market Strategic Shifts & Innovations
Processing technology and regulatory frameworks are converging to reshape how frozen potato products move from production to plate in Saudi Arabia.
Air fryer-compatible coating formulations are miniaturizing the performance gap between home-prepared and professionally fried products. Retail brands are reformulating surface starch structures to optimize crispness at lower oil volumes. This technology is compressing the quality differentiation between foodservice and retail segments.
SFDA's tightening HACCP documentation mandates are forcing distributors to deploy blockchain-traceable temperature logging systems. Compliance costs are accelerating consolidation among smaller cold-chain operators. Quick-service restaurant chains are responding by mandating direct supplier integration with their enterprise resource planning platforms.
Home-prep habits are fragmenting traditional retail channel concentration. Hypermarket frozen potato sections are losing share to quick-commerce platforms promising sub-hour delivery. This shift is most visible in Jeddah, where young household formation rates exceed national averages and digital grocery penetration leads the kingdom.
Saudi Arabia French Fries Market Segmentation
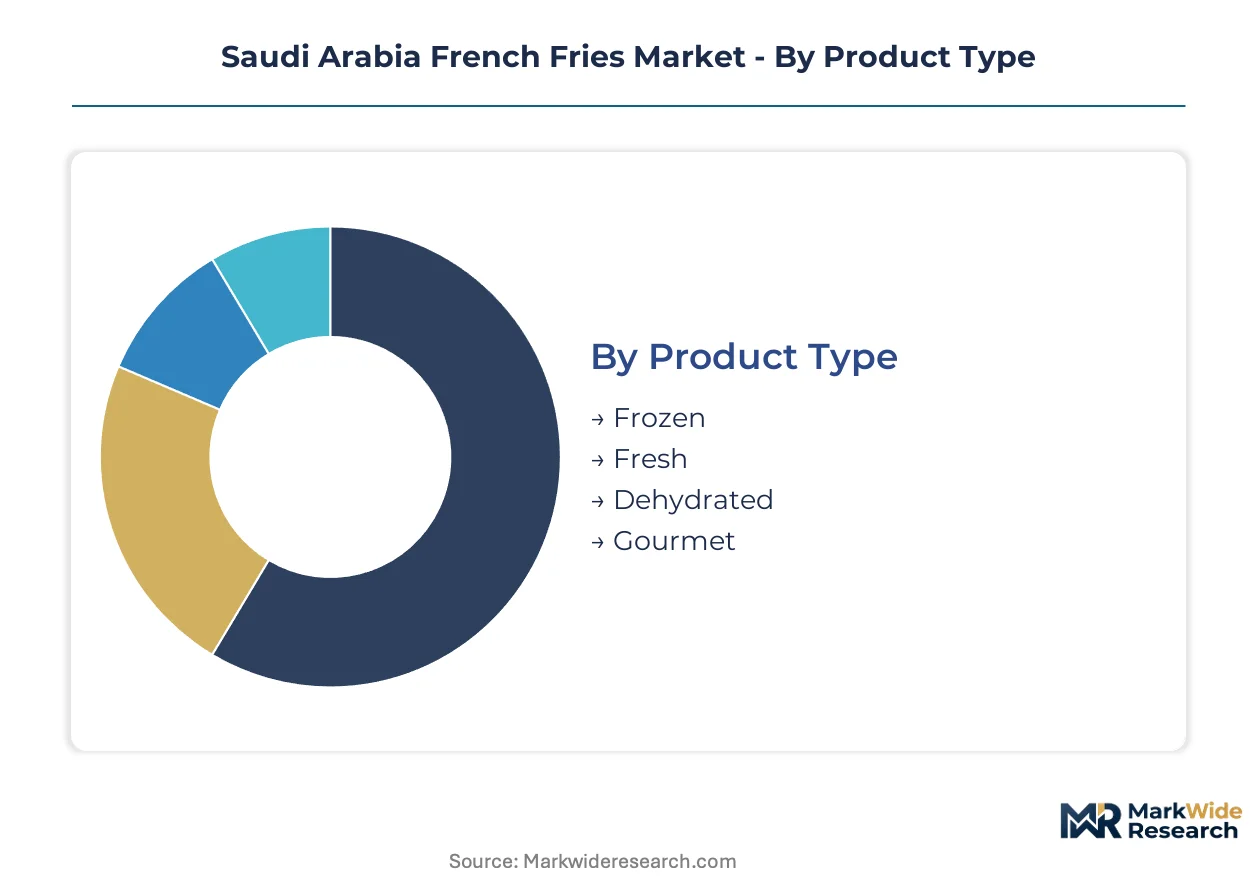
French fry segmentation in Saudi Arabia reflects the tension between foodservice standardization and retail channel evolution. SFDA cold-chain mandates and halal certification requirements create distinct compliance burdens across product formats that reshape procurement priorities.
Product Type:
SFDA's HACCP-aligned documentation requirements apply differentially across preservation states, with frozen formats facing the most intensive cold-chain verification while dehydrated products navigate alternative compliance pathways.
- Frozen:Par-fried strips flash-frozen at minus 35°C preserve starch crystalline structure for extended shelf stability. Quick-service restaurant chains in Riyadh and Jeddah concentrate procurement here, driven by operational convenience and batch consistency requirements.
- Fresh:Unprocessed potato strips demand same-day consumption windows and specialized handling protocols. Premium casual dining establishments in Khobar and Dammam source limited volumes, constrained by perishability and labor-intensive prep workflows.
- Dehydrated:Moisture-reduced products target military and institutional catering with extended ambient storage profiles.
- Gourmet:Hand-cut or specialty seasoned variants command niche positioning in upscale hotel foodservice.
Frozen handles the majority of throughput; Gourmet is climbing the fastest on share as hotel dining upgrades its potato offerings.
End User:
Customer procurement scale determines margin structure, with national fast-food chains extracting volume discounts that independent restaurants cannot match.
- Fast Food Chains:Burger and fried chicken networks standardize fry specifications across outlets, mandating direct supplier integration with enterprise resource planning platforms. Eastern Province expansion creates new demand nodes as Dammam and Khobar restaurant density grows.
- Restaurants:Independent casual dining operators balance customization desires against cold-chain infrastructure costs, often consolidating orders through foodservice distributors.
- Retail:Hypermarket and quick-commerce channels are fragmenting traditional distribution, with Jeddah leading digital grocery penetration for frozen potato pouches.
- Food Services:Institutional caterers, airlines, and contract feeding operations prioritize bulk formats with halal certification alignment.
Fast Food Chains dominate volume absorption; Retail is expanding most quickly as home air fryer adoption accelerates.
Thickness:
Cut geometry directly determines oil absorption rates, cooking time, and finished texture — variables that chain kitchens standardize rigorously.
- Thin:Rapid-fry strips optimize throughput in high-volume quick-service environments. Value-menu positioning across Saudi burger chains drives consistent demand, though precise dimensional tolerance requirements limit supplier pools.
- Steak Cut:Thicker cross-sections retain interior moisture through extended frying cycles. Casual dining establishments in Riyadh's entertainment districts specify these for premium side-dish positioning.
- Regular:Mid-range thickness balances speed and texture for mainstream foodservice applications.
- Crinkle Cut:Wavy profiles maximize surface area for seasoning adhesion in themed restaurant concepts.
Thin cuts manage the highest production volumes; Steak Cut is gaining share fastest as casual dining upgrades its menu architecture.
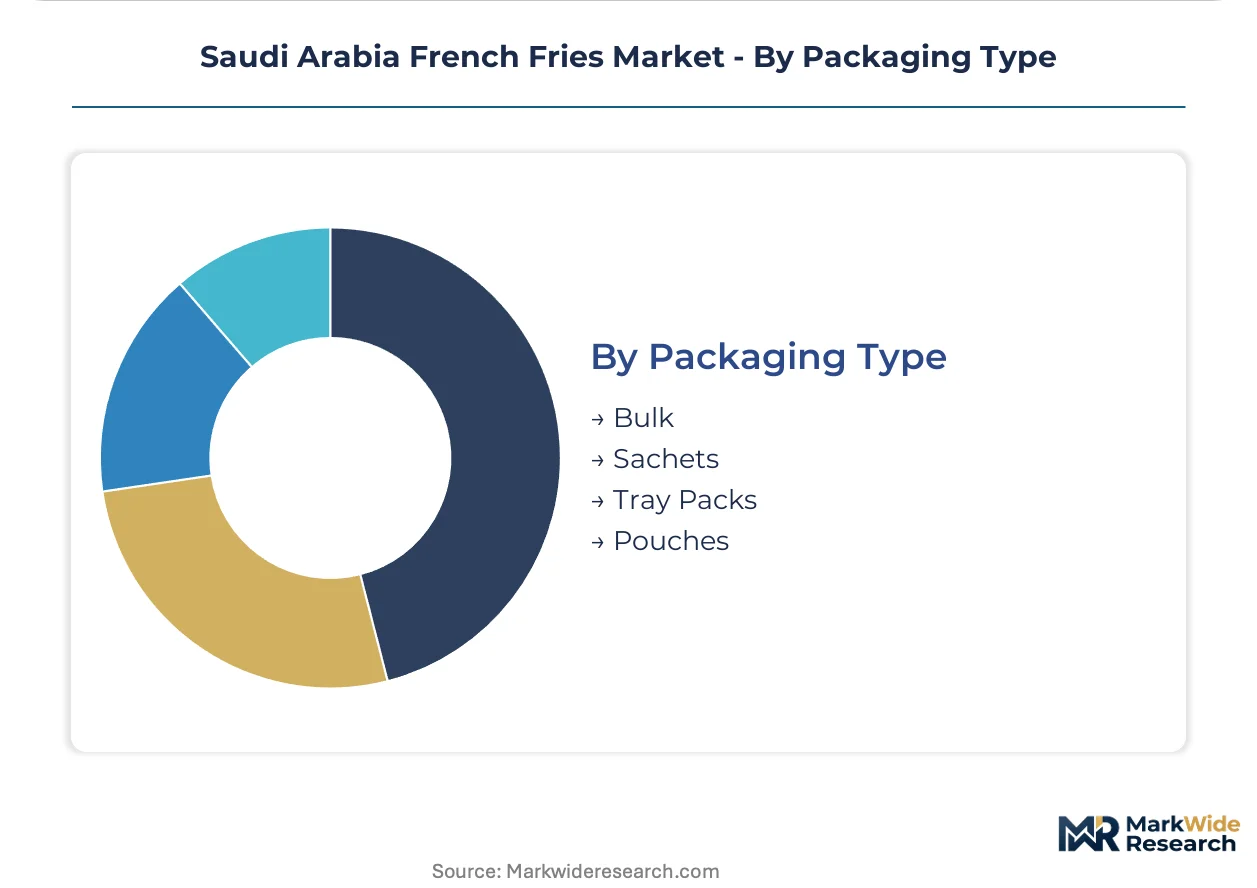
Packaging Type:
Format selection tracks channel destination, with institutional buyers prioritizing handling efficiency and retail channels emphasizing consumer convenience.
- Bulk:Large-format cases of 10–20 kilograms minimize per-unit handling costs for high-throughput kitchens. National fast-food chains and institutional caterers specify bulk for fryer-line efficiency, though SFDA mandates rigorous temperature logging throughout repackaging operations.
- Pouches:Consumer-facing bags with reseal features target home preparation via air fryer or conventional oven. Grocery delivery platforms in Jeddah and Riyadh are driving pouch format growth through sub-hour fulfillment promises.
- Sachets:Single-serve portions align with airline and healthcare catering portion control requirements.
- Tray Packs:Rigid containers with film sealing protect product integrity in retail display environments.
Bulk channels the greatest tonnage; Pouches are accelerating fastest as digital grocery platforms reshape household purchasing patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frozen potato processing capacity clusters in Riyadh and Jeddah, where cold-chain infrastructure density supports high-volume distribution to quick-service restaurant networks. Eastern Province demand lags these centers by roughly one-third, creating whitespace for logistics investment. SFDA compliance costs favor operators with established temperature-controlled warehousing.
Riyadh
National fast-food chain headquarters concentrate procurement decisions in Riyadh, driving institutional volume flows. Vision 2030 localization incentives direct state-backed investment toward domestic manufacturing facilities. The Riyadh Food Cluster anchors production expansion as international processors establish regional finishing lines.
Jeddah
Red Sea port access positions Jeddah as the primary import gateway for European and North American frozen potato shipments. Digital grocery penetration rates exceed national averages, accelerating pouch format retail growth. The King Abdullah Economic Zone hosts bonded cold-storage capacity serving western region distribution.
Eastern Province
Dammam and Khobar restaurant density remains below central and western benchmarks, constraining bulk format absorption. The General Food Security Authority's import quotas create seasonal supply volatility for distributors serving this corridor. Aramco workforce catering contracts represent a stable institutional demand node.
Western Region
Makkah and Madinah pilgrimage traffic generates concentrated seasonal demand spikes from hotel and hospitality foodservice. Halal certification requirements intensify for products entering religious tourism supply chains. Taif's agricultural periphery offers limited domestic raw material sourcing potential.
NEOM Northwest
The giga-project's construction phase imports frozen potato products through dedicated logistics corridors bypassing traditional distribution networks. Future hospitality infrastructure plans anticipate premium-positioned fry specifications. Regulatory sandbox provisions may relax certain SFDA documentation requirements for project-specific supply.
Saudi Arabia French Fries Market Key Industry Players
Concentration sits with multinational processors holding regional production footprints and long-term quick-service restaurant contracts. The vendor base separates into three tiers: integrated global processors with Middle East manufacturing, regional distributors with halal certification specialization, and local importers serving fragmented independent restaurant accounts. Strategic moves center on direct supplier integration with chain enterprise resource planning platforms and dedicated halal production line expansion.
Among globally integrated processors, McCain Foods, Lamb Weston, and Farm Frites occupy positions shaped by regional production presence and certification alignment. McCain Foods exemplifies the scale-driven archetype through its established Middle East manufacturing base. Lamb Weston represents product specialization tailored to Middle Eastern menu preferences. Farm Frites anchors the halal-certified processing tier, with certification protocols enabling Gulf Cooperation Council export reach. Americana Holding for Food and Kuwait Food Company sit within the regional distributor tier, leveraging local market knowledge and established cold-chain relationships.
| Leading Market Players |
|---|
| Al Jouf |
| McCain Foods |
| Americana Holding for Food |
| Lamb Weston |
| Simplot |
| Farm Frites |
| Kuwait Food Company |
| Aviko |
| Agricultural Growth and Processing Company |
| Others |
Cost & Logistics Intelligence
SFDA halal certification protocols gate both supplier qualification and price differentiation simultaneously, with certified processors commanding premium positioning over uncertified imports while compliance costs compress margins for distributors lacking scale.
Pricing Analysis
SFDA cold-chain mandates dictate the pricing tier structure across the Saudi frozen potato market. Three-tier pricing structure across premium, standard, and economy levels separates halal-certified steak cuts from conventional regular cuts and commodity thin strips. Price differentiation rests on certification grade and volume scale, with national fast-food chains extracting steep discounts through direct supplier integration. Cost compression in the economy tier is intensifying because import quota volatility disrupts landed cost predictability. Independent restaurants exhibit highest price sensitivity due to fragmented procurement volumes, while institutional caterers with Aramco contracts show lowest sensitivity.
Supply Chain Analysis
Belgium and the Netherlands anchor European frozen potato processing for Saudi import dependence. Raw material sourcing draws from contracted potato growers in Germany, France, and the United Kingdom, with par-frying and flash-freezing equipment concentrated among established processors. Single-source vulnerability runs through Red Sea shipping corridors where Jeddah port congestion creates seasonal bottlenecks. Distribution runs through bonded cold-storage facilities at King Abdullah Economic Zone serving western region quick-service restaurant networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Halal-certified processing services represent a faster-expanding revenue layer than commodity frozen potato production, with certification compliance and cold-chain monitoring emerging as recurring attach opportunities.
For Market Incumbents: Shield market position through dedicated halal production line expansion and backward integration into Saudi-based finishing facilities. The threat of Vision 2030 localization incentives favoring domestic manufacturing capacity demands preemptive capacity addition in Riyadh Food Cluster zones. Vertical integration into captive cold-chain warehousing locks in distributor relationships against compliance cost pressures.
For New Entrants and Emerging Players: Differentiate on blockchain-traceable temperature logging systems that satisfy SFDA HACCP documentation mandates. Eastern Province whitespace around Dammam and Khobar offers the most penetrable geography given restaurant density gaps versus Riyadh and Jeddah. Direct-to-consumer subscription models through quick-commerce platforms provide a defensible go-to-market angle in Jeddah's digitally mature grocery market.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cold-chain infrastructure sub-segments as SFDA compliance mandates accelerate distributor consolidation. The five-to-ten year viability window favors processors with regional manufacturing footprints over pure import-reliant traders. Acquisition targets should display established halal certification protocols and direct quick-service restaurant contracts. The signal to watch is General Food Security Authority import quota allocation tightening, which would structurally advantage domestic production capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Halal-Certified Processing Line Expansion | SFDA certification unlocks Gulf Cooperation Council export corridors beyond Saudi domestic absorption. |
| Direct Supplier ERP Integration | McDonald's and Al Baik mandate real-time inventory visibility, freezing out distributor-dependent competitors. |
| Eastern Province Distribution Buildout | Dammam and Khobar restaurant density gaps present first-mover warehousing advantages. |
| Air Fryer-Compatible Coating R&D | Retail pouch growth in Jeddah depends on crispness performance at reduced oil volumes. |
| Blockchain Cold-Chain Traceability | SFDA HACCP documentation compliance accelerates adoption of temperature-logging distributed ledger systems. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs import records, SFDA regulatory filings, and quick-service restaurant procurement databases. Interviews with frozen potato procurement directors, cold-chain logistics operators, halal certification auditors, and foodservice distributor executives informed demand-side validation. Top-down trade flow analysis triangulates against bottom-up outlet-level consumption modeling across Riyadh, Jeddah, and Eastern Province clusters.
Segmentation dimensions modeled include product preservation state, end-user channel, cut thickness geometry, and packaging format across the projection horizon. CAGRs derive from elasticity-adjusted volume projections incorporating air fryer adoption curves and quick-service restaurant expansion pipelines. Forecast inputs integrate Vision 2030 localization incentive trajectories and General Food Security Authority quota allocation patterns.
The analysis sits within stated boundaries; outcomes outside sustained quick-service restaurant expansion or relaxed import quota regimes would require recalibration. Forecasts reflect assumptions around cold-chain infrastructure investment continuity and halal certification timeline stability. Recalibration cycles align with material shifts in SFDA regulatory enforcement intensity and Vision 2030 domestic manufacturing incentive revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Indonesia Snack Bar Market
Snacks
Grass-Fed Jerkies Market
Snacks
Fruit Jerky Market
Snacks
Low Calorie Biscuits Market
Snacks
Europe Snack Bar Market
Snacks
Fat Free Meals and Snacks Market
Snacks
Europe Cereal Bar Market
Snacks
Middle East Snack Bar Market
Snacks
North America Baked Savory Snacks Market
Snacks
Low Fat Granola Market
Snacks
Nachos Market
Snacks
Cheese Snacks Market
Snacks
Tortilla Mix Market
Snacks
United States Snack Bar Market
Snacks
North America Snack Food Market
Snacks
Packaged Rice Snacks Market