
 Germany Power EPC Market | 2026-2036
Germany Power EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Power EPC Market Foresight
German offshore wind fabrication yards in Cuxhaven and Rostock are rebalancing turbine installation vessel schedules around North Sea lease round timelines. Siemens Energy anchors its North Sea project pipeline through dedicated converter platform manufacturing at its Nuremberg facility. HOCHTIEF AG leverages its civil engineering scale to dominate onshore substation and grid corridor construction across northern Länder. RWE sustains in-house EPC capability for lignite-to-renewables site repurposing in the Rhineland.
Power EPC encompasses the integrated engineering, procurement, and construction of electricity generation and delivery infrastructure, typically involving turbine-generator sets rated from 50 MW to 1,500 MW, high-voltage switchgear assemblies, and bespoke control systems programmed to grid code frequency response curves. The primary purpose is delivering utility-scale assets that synchronize with national transmission networks under defined voltage and reactive power schedules. Renewable Energy project types now command the dominant share of new order intake, while Thermal Power EPC has shifted toward combined-cycle gas turbine retrofits for grid balancing. Commissioning services within the Service Offering dimension carry disproportionate margin pools due to specialist technician scarcity and liability concentration during energization phases.
KBA emission standards for backup power systems and BNetzA grid connection certification under the EnWG shape equipment specification and contractor qualification requirements across German power EPC procurement. The EU Green Deal's REPowerEU targets and Germany's own EEG subsidy tiers direct capital allocation toward electrolyzer-coupled wind parks and hydrogen-ready gas turbine infrastructure. Stakeholders must monitor Bundestag negotiations on the EnWG amendment timeline, as accelerated permitting provisions would reshape project delivery schedules and contractor backlog visibility.
Market Dynamics
Offshore wind lease round acceleration under Germany's EnWG is compressing EPC contractor backlogs while redirecting fabrication capacity from Cuxhaven toward converter platform manufacturing. This regulatory-driven demand surge is colliding with specialized vessel scarcity and hydrogen-ready infrastructure mandates.
Growth Catalysts
- EEG renewable subsidies:Tiered feed-in tariffs for offshore wind parks are pulling EPC contractors toward electrolyzer-coupled generation clusters in the North Sea.
- Data center load expansion:Hyperscale facilities in Bavaria are straining transmission infrastructure and triggering substation upgrade contracts.
- Automotive electrification:Battery gigafactory construction in the Rhine-Ruhr region is expanding captive power EPC requirements for industrial manufacturing.
Market Restraints
- Specialized vessel concentration:Turbine installation jack-up availability is bottlenecked at Cuxhaven and Rostock fabrication yards.
- Copper and rare earth input volatility:High-voltage switchgear and permanent magnet generator supply chains face raw material price instability.
- BNetzA certification timelines:Grid connection approval delays under EnWG procedures are extending project commissioning windows.
Strategic Opportunities
- Lignite site repurposing:Rhineland brownfield conversions offer EPC contractors decommissioned grid infrastructure and existing land rights.
- Green hydrogen integration:Electrolyzer-coupled wind parks create bundled EPC contracts spanning generation, storage, and pipeline injection.
- REPowerEU alignment:EU Green Deal targets are unlocking blended finance structures for hydrogen-ready gas turbine retrofits.
Industry Challenges
- Commissioning technician scarcity:Specialist crews for converter platform energization are concentrated among a limited pool of certified contractors.
- Legacy lignite grid synchronization:Retiring thermal assets require complex frequency response recalibration for renewable-dominated networks.
- Cross-vendor control system integration:Bespoke turbine and switchgear programming creates interoperability friction during multi-supplier projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Power EPC Market |
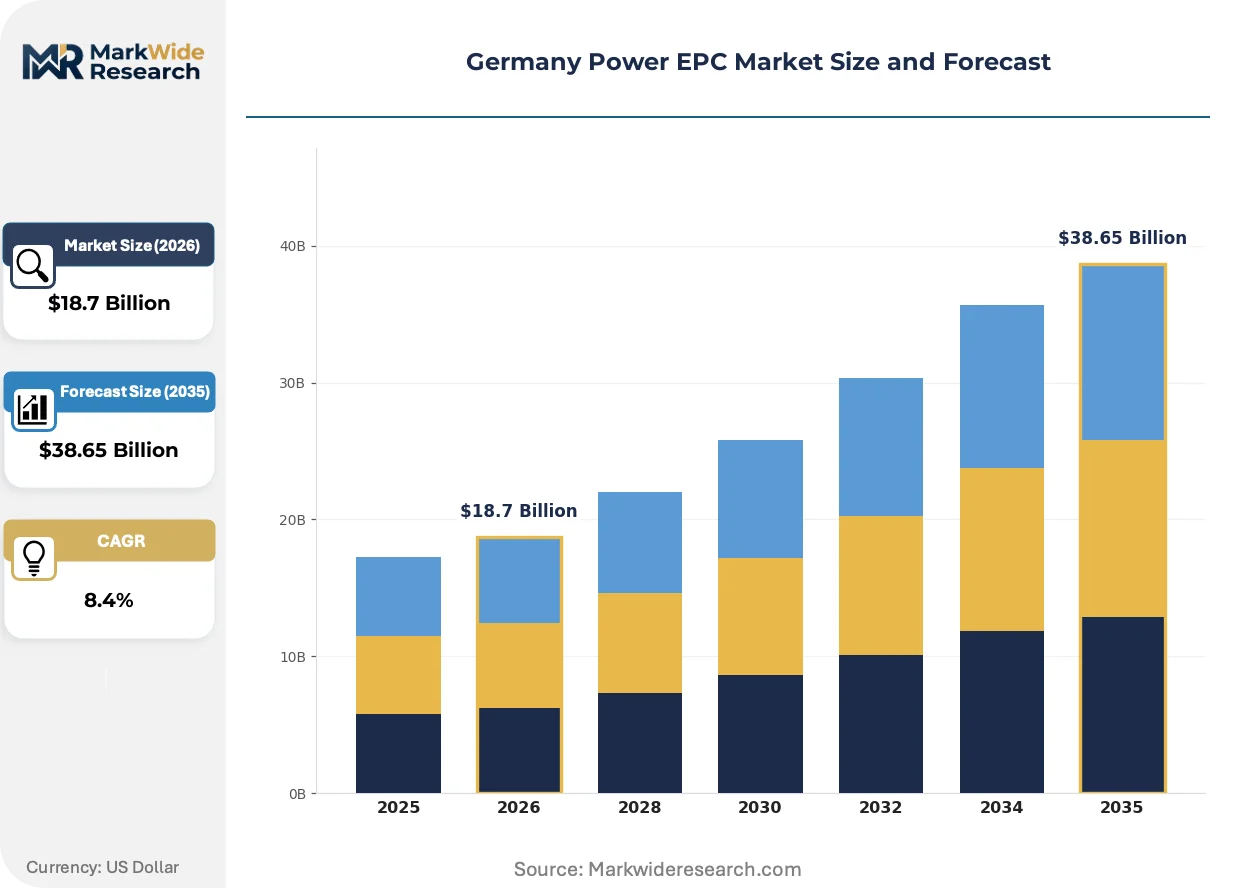
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Thermal Power, Hydro Power, Renewable Energy, Nuclear Energy, Cogeneration Service Offering: Engineering, Procurement, Construction, Commissioning, Operation & Maintenance Client Type: Independent Power Producers, Transmission Operators, Government Agencies, Utility Companies, Infrastructure Developers Contract Model: Turnkey, Design-Build, Lump Sum Turnkey, Cost Plus, Build Operate Transfer |
| Companies Covered | McDermott International Inc., Siemens Energy, Fluor Ltd, E.ON, RWE, General Electric Company, Wärtsilä Oyj Abp, HOCHTIEF AG, EPC Engineering & Technologies GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Power EPC Market Shifts & Advancements
Modular converter platform manufacturing is compressing offshore wind construction schedules while hydrogen-ready gas turbine specifications are rewriting thermal EPC scopes. These shifts are converging with digital twin commissioning tools that reduce on-site specialist deployment.
High-voltage direct current converter technology is consolidating offshore wind transmission efficiency. Transmission system operators are specifying modular multi-level converter platforms for North Sea grid connections. This standardization is consolidating EPC contractor procurement around Siemens Energy and Hitachi Energy platform designs, compressing vendor diversification in the German market.
EnWG amendment negotiations are accelerating permitting timelines for strategic energy infrastructure. Bundestag deliberations on streamlined approval procedures are compressing project development cycles from sixty to twenty-four months. Northern Länder planning authorities are responding with dedicated energy corridor zoning that affects onshore substation routing across Schleswig-Holstein and Lower Saxony.
Asset owners are unbundling commissioning services from turnkey EPC contracts. Renewable developers are separately procuring energization specialists to manage liability concentration during grid synchronization phases. This fragmentation is most visible in Bavaria, where data center and automotive loads are driving demand for independent commissioning verification beyond standard warranty provisions.
Germany Power EPC Market Segmentation
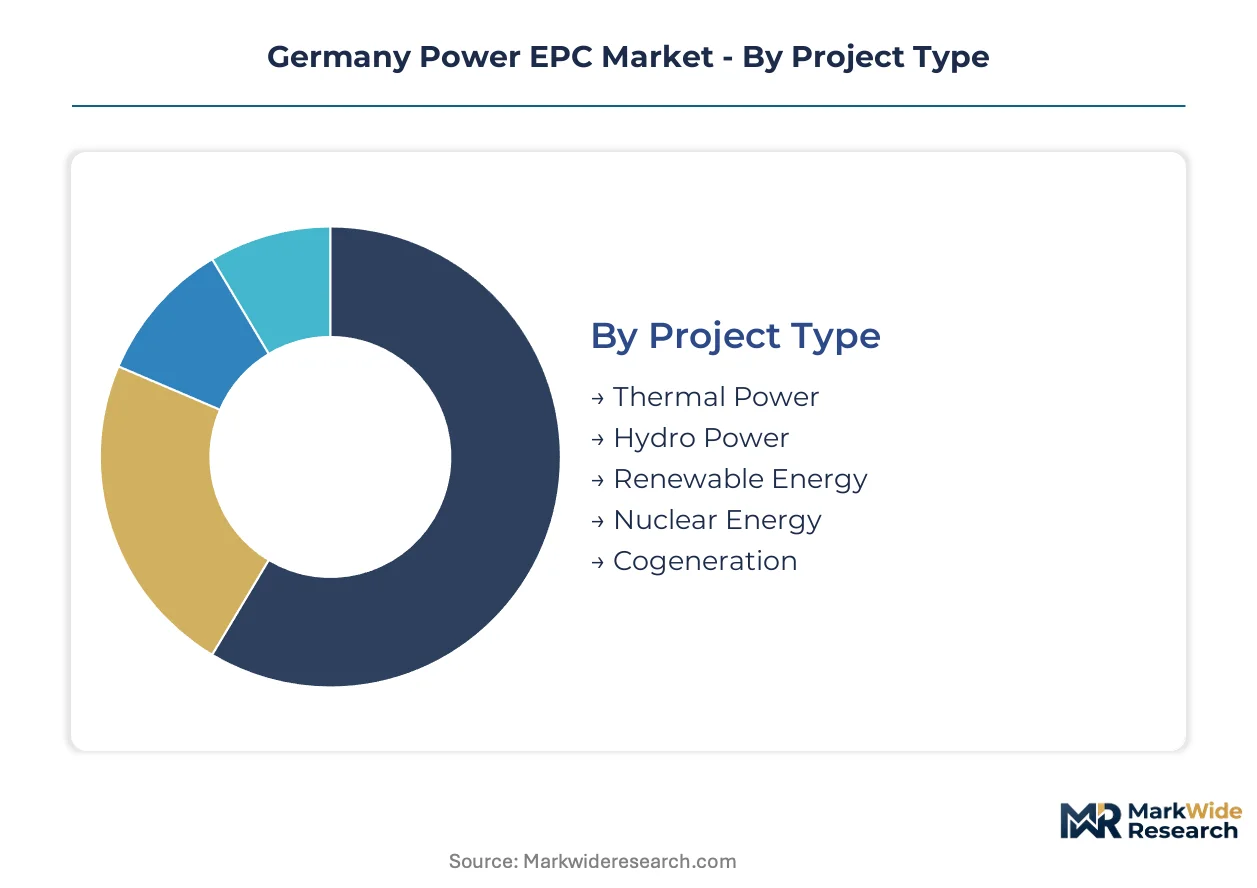
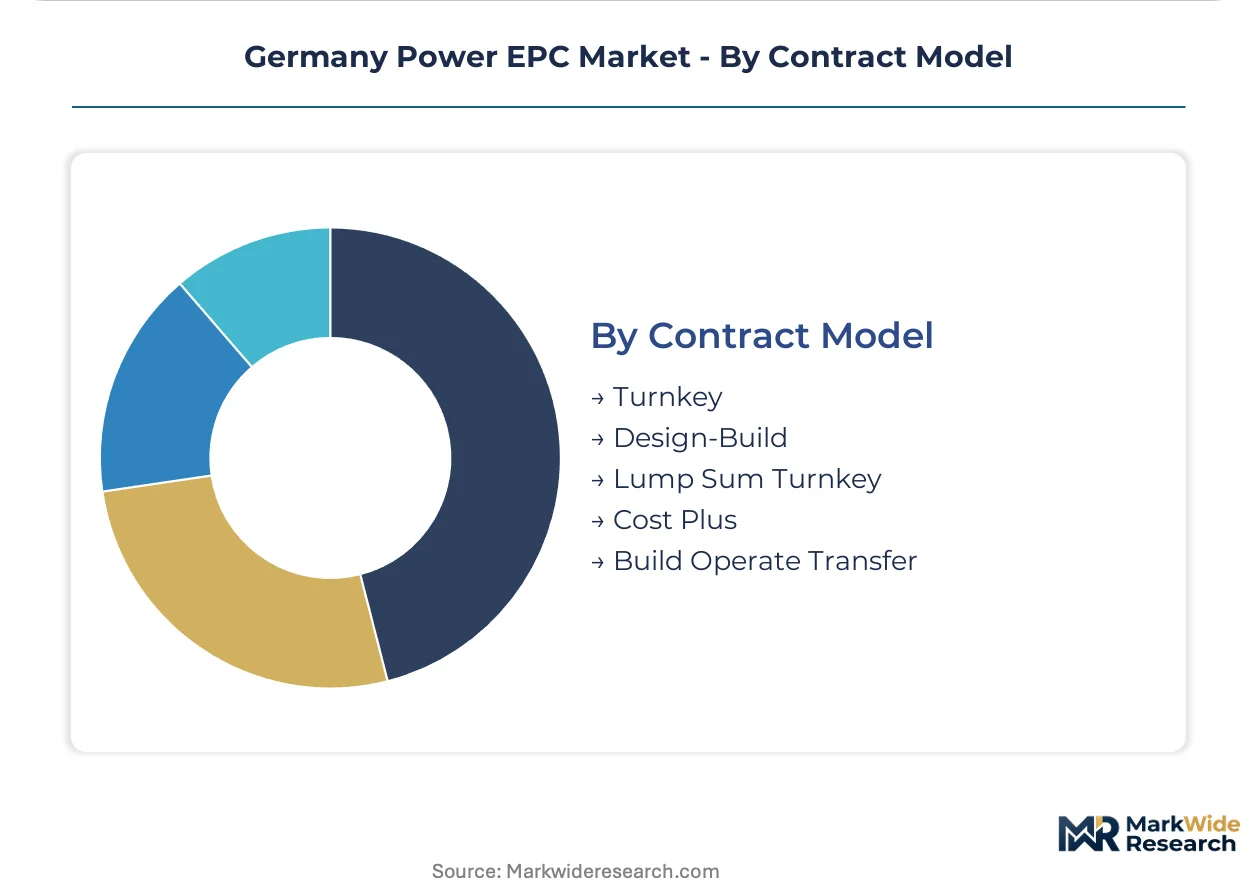
Power EPC procurement in Germany fragments across contract structures, client risk appetites, and technology maturity. Each segmentation dimension reveals distinct margin pools and backlog visibility patterns for contractors navigating EEG subsidy tiers and EnWG permitting timelines.
Project Type:
Technology selection hinges on grid connection queue position and EEG tariff eligibility windows.
- Renewable Energy:Offshore wind parks dominate new order intake, with turbine-generator sets scaling toward 15 MW per unit. North Sea lease round acceleration is compressing fabrication yard schedules at Cuxhaven and Rostock while pulling contractors toward electrolyzer-coupled generation clusters.
- Thermal Power:Combined-cycle gas turbine retrofits now concentrate on hydrogen-ready specifications for grid balancing. Rhineland lignite site repurposing under RWE's phase-out program offers brownfield grid infrastructure but demands complex frequency response recalibration.
- Hydro Power:Run-of-river upgrades in Bavarian Alpine regions target pumped-storage integration for data center load balancing.
- Nuclear Energy:Decommissioning scopes dominate as Isar 2, Neckarwestheim 2, and Emsland enter post-operational phases under BfE oversight.
- Cogeneration:Industrial clusters in Rhine-Ruhr deploy gas engine CHP for automotive battery gigafactory captive power.
Renewable Energy leads on scale; Thermal Power leads on momentum through hydrogen-ready retrofit specifications.
Service Offering:
Procurement bundling decisions track liability concentration and specialist crew availability.
- Commissioning:Converter platform energization commands premium pricing due to certified technician scarcity. Bavarian data center developers now unbundle this scope from turnkey contracts to secure independent grid synchronization verification.
- Construction:Civil works for onshore substations and grid corridors concentrate in northern Länder under dedicated energy corridor zoning. HOCHTIEF AG's scale position reflects bundling of foundation, structural, and electrical installation scopes.
- Engineering:Front-end design for modular converter platforms consolidates around Siemens Energy and Hitachi Energy specifications.
- Procurement:High-voltage switchgear and permanent magnet generator sourcing faces copper and rare earth price volatility.
- Operation & Maintenance:Long-term service agreements attach to offshore wind assets with remote monitoring obligations.
Construction leads on scale; Commissioning leads on momentum as liability fragmentation accelerates.
Client Type:
Counterparty credit quality and EnWG compliance burden shape contractor risk pricing.
- Transmission Operators:TenneT and 50Hertz drive HVDC converter platform demand with standardized multi-level specifications. Their BNetzA-regulated cost-plus frameworks offer backlog visibility but compress margin upside.
- Independent Power Producers:Renewable developers in North Sea zones pursue merchant exposure beyond EEG tariffs, demanding flexible EPC contract structures.
- Utility Companies:RWE and Uniper sustain in-house EPC capability for lignite-to-renewables transitions.
- Infrastructure Developers:Data center specialists in Bavaria procure captive substation upgrades under tight commissioning windows.
- Government Agencies:Federal network development plans under EnWG mandate strategic corridor construction with accelerated permitting.
Transmission Operators lead on scale; Infrastructure Developers lead on momentum through data center load expansion.
Contract Model:
Risk allocation mechanics determine contractor balance sheet exposure and surety requirements.
- Turnkey:Fixed-price delivery dominates offshore wind where weather windows and vessel availability create execution risk. Siemens Energy's converter platform contracts typically embed liquidated damages for grid connection delays.
- Lump Sum Turnkey:Brownfield lignite conversions favor this structure given existing site data and grid infrastructure.
- Design-Build:Emerging for hydrogen-ready gas turbine retrofits where performance specifications evolve during execution.
- Cost Plus:Applied to pioneering electrolyzer-coupled wind parks with unproven integration risk profiles.
- Build Operate Transfer:Limited deployment for strategic reserve capacity under federal capacity mechanism design.
Turnkey leads on scale; Lump Sum Turnkey leads on momentum through Rhineland repurposing activity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France and the Netherlands outpace Germany in offshore wind deployment velocity, yet German fabrication yards retain converter platform manufacturing dominance through specialized supply chains.
North Rhine-Westphalia
Industrial manufacturing clusters around Düsseldorf and Cologne are expanding captive power requirements for automotive battery gigafactories. The EnWG grid expansion mandates redirect contractor portfolios toward hydrogen-ready infrastructure. Rhine-Ruhr EPC procurement concentrates on combined-cycle gas turbine retrofits for grid balancing services.
Bavaria
Hyperscale data center loads near Munich are straining existing transmission infrastructure and triggering substation upgrade contracts. EEG renewable energy subsidies support Alpine run-of-river pumped-storage integration. Bavarian planning authorities are responding with dedicated energy corridor zoning for automotive electrification demand.
Lower Saxony
Offshore wind fabrication yards at Cuxhaven are rebalancing turbine installation vessel schedules around North Sea lease round timelines. BNetzA grid connection certification procedures shape equipment specification requirements. Northern coastal zones are consolidating EPC contractor backlogs around converter platform manufacturing.
Baden-Württemberg
Automotive electrification in Stuttgart manufacturing corridors is expanding industrial power demand beyond existing grid capacity. KBA emission standards for backup power systems shape contractor qualification requirements. Precision engineering clusters are driving demand for high-voltage switchgear assemblies with bespoke control systems.
Schleswig-Holstein
North Sea wind park development is compressing project delivery schedules through accelerated permitting provisions. EnWG amendment negotiations are reshaping contractor backlog visibility for strategic energy infrastructure. Coastal fabrication capacity is redirecting toward electrolyzer-coupled generation clusters.
Germany Power EPC Market Competitive Landscape
German producers anchor the engineering-intensive tier; international specialists hold project execution scale. The vendor base concentrates around three strategic archetypes: integrated energy conglomerates with captive EPC capability, pure-play construction groups leveraging civil engineering scale, and technology licensors controlling converter platform specifications. Competitive positioning is hardening through fabrication yard capacity commitments and specialist technician workforce capture.
Among Germany-based contractors, HOCHTIEF AG exemplifies the civil-engineering-scale archetype through its dominance in onshore substation and grid corridor construction, while Siemens Energy occupies a position anchoring converter platform manufacturing specifications. RWE represents the integrated-energy archetype sustaining in-house capability for brownfield site transitions. International players including McDermott International Inc. and Fluor Ltd sit within the global project execution tier, competing on lump-sum turnkey risk absorption for complex offshore installations.
| Leading Market Players |
|---|
| McDermott International Inc. |
| Siemens Energy |
| Fluor Ltd |
| E.ON |
| RWE |
| General Electric Company |
| Wärtsilä Oyj Abp |
| HOCHTIEF AG |
| EPC Engineering & Technologies GmbH |
| Others |
Supply & Pricing Matrix
EU Green Deal hydrogen-readiness specifications gate qualified EPC contractor status and premium-tier pricing access for converter platform manufacturing. Buyers without certified electrolyzer-coupled project experience face exclusion from TenneT and 50Hertz procurement frameworks, compressing viable supplier pools and sustaining margin premiums for qualified incumbents.
Pricing Analysis
Capacity additions in Lower Saxony and Schleswig-Holstein are reshaping price floors for offshore wind EPC as fabrication yard competition intensifies. Project-based contracting dominates, with price differentiation driven by BNetzA certification tier and vessel availability guarantees. Cost compression in standard turbine installation packages is intensifying due to jack-up vessel oversubscription at Cuxhaven. Utility-scale developers show least price sensitivity, while industrial captive power buyers in Rhine-Ruhr negotiate hardest on balance-of-plant scopes.
Supply Chain Analysis
High-voltage switchgear supply rests on German and Swiss precision engineering clusters, with permanent magnet generators drawing from Chinese rare earth processing and Japanese magnet fabrication. Copper busbar and semiconductor-grade silicon dependencies expose contractors to commodity price volatility. Single-source vulnerability concentrates in specialized turbine installation vessel chartering. Distribution runs through TenneT-regulated grid connection queues and BNetzA-certified equipment vendor lists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German Power EPC margins are expanding through commissioning service unbundling and electrolyzer-coupled project premiums. Standardized converter platform specifications are compressing engineering costs while specialist technician scarcity sustains energization pricing power.
For Market Incumbents: Acquire certified commissioning crews and converter platform fabrication slots to defend against emerging pure-play energization specialists. Secure long-term vessel charter agreements at Cuxhaven and Rostock before lease round acceleration tightens availability. Prioritize BNetzA pre-certification for hydrogen-ready gas turbine retrofit portfolios to capture Rhineland repurposing demand. For New Entrants and Emerging Players: Modular digital twin commissioning tools offer a technology-first wedge into Bavarian data center substation upgrades where independent verification demand is fragmenting turnkey contracts. Target captive power EPC for automotive battery gigafactories in North Rhine-Westphalia. Lead with EnWG permitting acceleration expertise to differentiate against established civil engineering incumbents. For Investors and Strategic Acquirers: Roll-up economics work for regional commissioning specialists because liability fragmentation is unbundling energization from construction scopes and concentrating margin pools. Five-to-ten year viability hinges on technician workforce capture and BNetzA certification asset ownership. Watch Bundestag EnWG amendment passage as inflection trigger for project development cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyzer-Coupled Wind Park Development | Bundled EPC contracts spanning generation, storage, and pipeline injection capture REPowerEU-aligned blended finance structures. |
| Converter Platform Manufacturing Scale-Up | Siemens Energy and Hitachi Energy specifications consolidate procurement around modular multi-level HVDC designs. |
| Commissioning Capability Acquisition | Specialist crew capture addresses scarcity premiums for converter platform energization and grid synchronization phases. |
| Lignite Site Repurposing Execution | Rhineland brownfield conversions leverage decommissioned grid infrastructure under RWE's phase-out program. |
| EnWG Permitting Acceleration Investment | Streamlined approval expertise compresses project development cycles from sixty to twenty-four months. |
Research Methodology
Bottom-up project pipeline modeling reconciled against top-down contractor backlog tracking forms the analytical core of this study. Primary interviews with EPC project directors, TenneT grid planning officers, BNetzA certification auditors, and offshore wind fabrication yard managers combined with secondary validation from EnWG amendment documentation, EEG subsidy tier schedules, and North Sea lease round filings. Triangulation against customs data for high-voltage switchgear imports and vessel charter market reports verified capacity utilization assumptions.
Historical trendline analysis of EPC contract award values and completion timelines established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include project type, service offering, client archetype, and contract structure, with CAGRs derived from regression-adjusted backlog-to-award ratios. Forecast inputs incorporated EnWG permitting velocity scenarios and electrolyzer cost curve assumptions for hydrogen-ready infrastructure.
The model holds under stable EEG subsidy tiers and EnWG amendment passage; deviation in Bundestag negotiation timelines or rare earth export restrictions would shift contractor backlog visibility. Forecasts reflect documented assumptions regarding vessel availability and BNetzA certification throughput. A small set of named triggers—specialized jack-up vessel delivery delays, copper price spikes, and grid connection queue reforms—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Romania Power EPC Market
Power Equipment
Power Magnetics for MV AC Drive Market
Power Equipment
Egypt Power EPC Market
Power Equipment
Wind Turbine Components Market
Power Equipment
Process Plants Gas Turbine Market
Power Equipment
Process Air Heater Market
Power Equipment
United Arab Emirates Power EPC Market
Power Equipment
Heavy Duty Gas Turbine Market
Power Equipment
Power Grid Primary and Secondary Fusion Equipment Market
Power Equipment
Turbine Governor Market
Power Equipment
G-3 PLC Solutions Market
Power Equipment
Automatic Power Factor Controller Market
Power Equipment
Power Recovery Winches Market
Power Equipment
Chad Power EPC Market
Power Equipment
Variable Frequency Drive (VFD) Market
Power Equipment
Industrial Power Transmission Drive Belts Market