
 Romania Power EPC Market | 2026-2036
Romania Power EPC Market Size, Share, and Industry Trends Forecast 2026-2036
Romania Power EPC Market Analytics
Buyer concentration among Romanian utilities is hardening as Transelectrica SA and Societatea Nationala Nuclearelectrica SA consolidate procurement under larger framework agreements. Enel SpA leverages its integrated development platform to capture utility-scale renewable mandates. Mytilineos SA anchors its position through captive engineering capacity and regional fuel supply chains.
Romania Power EPC encompasses engineering, procurement, and construction contracting for power generation and delivery infrastructure, typically involving turnkey delivery of substations, generation blocks, and interconnection assets rated from 110 kV to 400 kV. The primary purpose is transferring project risk from asset owners to contractors while guaranteeing output performance and grid code compliance. Renewable Energy projects now command the dominant share of contractor pipelines, while Thermal Power segments retain margin concentration in combined-cycle upgrades and flexibility retrofits. Engineering Services within the Service Type dimension sit at the high-margin core, as owners outsource front-end design and permitting before competitive bidding construction phases.
Romania's National Regulatory Authority for Energy (ANRE) sets grid connection tariffs and technical codes that determine project viability timelines for developers. The National Recovery and Resilience Plan (PNRR) imposes spending deadlines and local-content conditions that reshape contractor qualification requirements. BIS certification and EU taxonomy alignment pressures are filtering into procurement specifications for transmission equipment. Stakeholders must monitor whether PNRR disbursement pacing and ANRE permitting queue reforms sustain contractor backlog visibility or create intermittent demand gaps.
Market Dynamics
PNRR disbursement deadlines are compressing contractor qualification timelines while ANRE permitting queue reforms create intermittent demand visibility gaps across the Wallachia solar cluster. This structural tension between financing availability and execution capacity defines current market mechanics.
Growth Catalysts
- PNRR Auction Mechanisms:Romania's National Recovery and Resilience Plan channels public financing toward grid modernization and renewable capacity auctions, creating predictable procurement pipelines for turnkey contractors.
- Turnkey Solution Demand:Utilities are expanding procurement of integrated turnkey solutions, transferring project risk from asset owners to contractors while guaranteeing output performance.
- Wallachia Infrastructure Clustering:Solar and gas-fired projects concentrate near existing transmission infrastructure in the Wallachia plain, reducing interconnection costs and accelerating development timelines.
Market Restraints
- Copper and Steel Input Volatility:Raw material price swings for transformer windings and structural steel compress fixed-price contract margins, particularly for 400 kV substation builds.
- BIS Certification Bottlenecks:EU taxonomy alignment pressures and BIS certification requirements for transmission equipment extend procurement cycles and filter out smaller contractors.
- Local-Content Thresholds:PNRR spending conditions impose domestic sourcing mandates that strain supply chains for specialized high-voltage components.
Strategic Opportunities
- Black Sea Offshore Wind:Romania's maritime zone offers untapped capacity for floating wind platforms, requiring new interconnection corridors and specialized marine EPC capabilities.
- Battery Storage Co-Location:Pairing solar farms with grid-scale battery systems creates hybrid project demand, converging renewable generation with flexibility services.
- Regional Export Positioning:Romanian contractors can leverage EU membership and lower labor costs to bid on Bulgarian and Hungarian transmission upgrades.
Industry Challenges
- Grid Code Compliance Expertise:ANRE technical codes evolve rapidly, creating skill gaps in power systems engineering and protection relay configuration.
- Permitting Timeline Uncertainty:Environmental impact assessments and grid connection queue positions extend project gestation, straining working capital for mid-tier EPC firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Romania Power EPC Market |
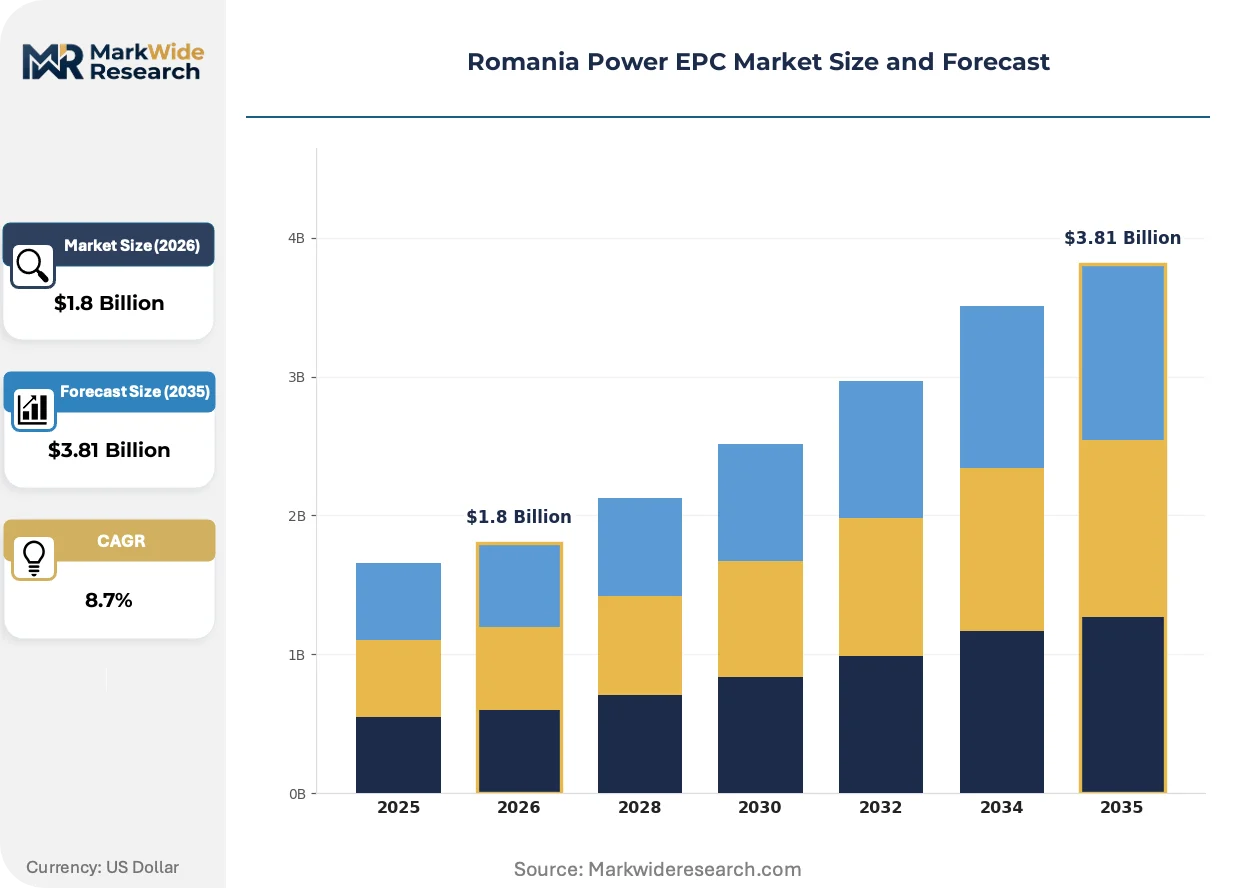
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Renewable Energy, Thermal Power, Hydro Power, Nuclear Power Service Type: Engineering Services, Procurement Services, Construction Services, Project Management End User: Utilities, Independent Power Producers, Government Entities, Industrial Clients Technology: Solar Technology, Wind Technology, Biomass Technology, Hydropower Technology |
| Companies Covered | Enel SpA, Mytilineos SA, Transelectrica SA, Electroalfa, E.ON SE, Romelectro SA, Siemens AG, Societatea Nationala Nuclearelectrica SA, JinkoSolar Holding Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Romania Power EPC Market Evolving Landscape
Digital design tools and prefabrication methods are compressing construction schedules while regulatory pressure on embodied carbon reshapes equipment sourcing. These forces converge on contractor capability requirements.
Containerized substation solutions are modularizing 110 kV to 220 kV distribution infrastructure, enabling factory-assembly and rapid site deployment. Romanian utilities facing PNRR spending deadlines favor these packages for rural electrification and renewable interconnection projects. The technology is modularizing contractor field labor requirements while shifting margin capture toward manufacturing partners.
EU taxonomy alignment requirements are filtering into Romanian transmission procurement specifications, mandating lifecycle carbon disclosure for switchgear and transformers. Contractors must now document embodied emissions across steel, copper, and SF6 insulation supply chains. Grid modernization tenders in Wallachia and Transylvania increasingly specify taxonomy-compliant equipment, favoring vendors with verified environmental product declarations.
Integrated development platforms are displacing fragmented design-bid-build sequences as Enel and other utilities consolidate engineering, procurement, and construction under single accountability structures. This model compresses interface risk and accelerates commissioning timelines. Romanian solar developers in the Muntenia region increasingly mandate turnkey delivery, forcing pure-play engineering firms to partner with construction specialists or exit the market.
Romania Power EPC Market Segmentation
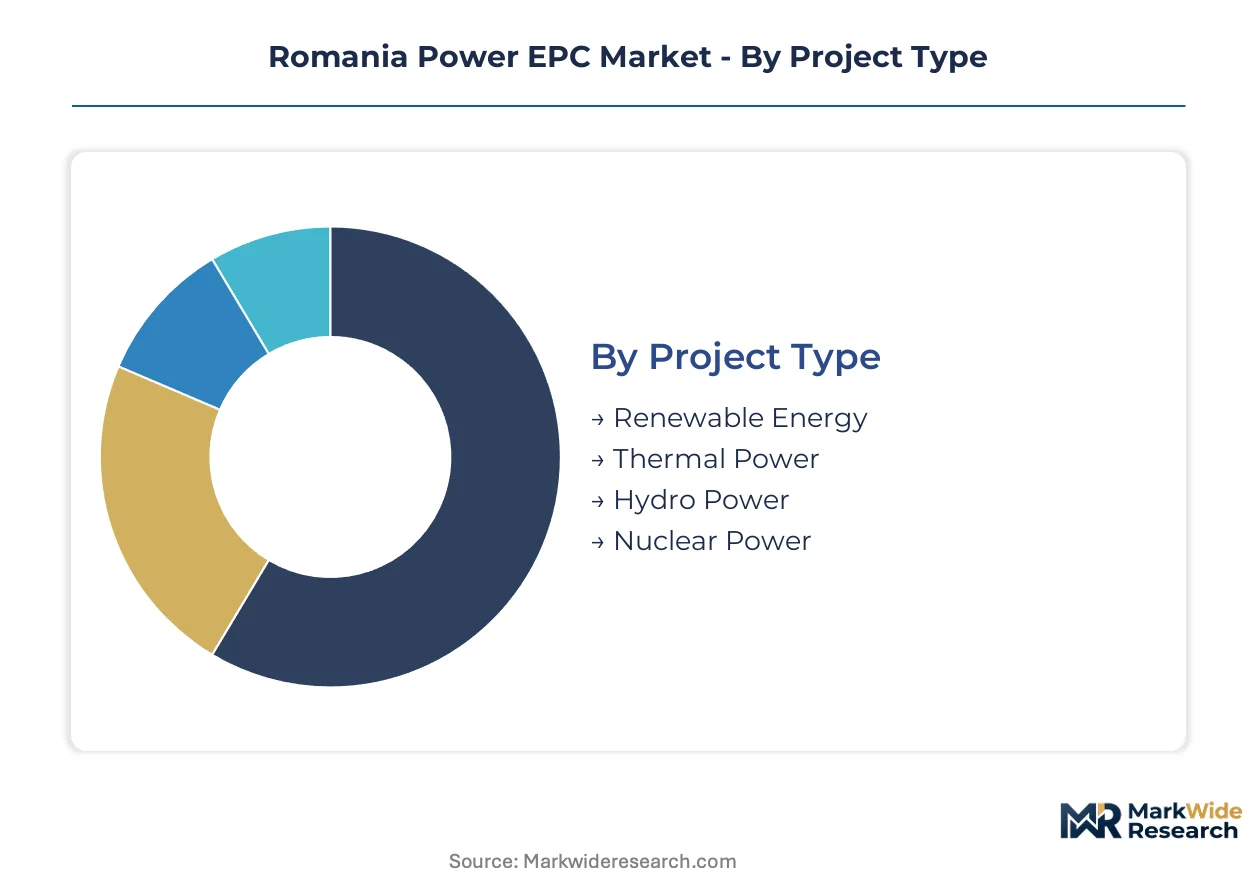
Romania Power EPC contractors configure delivery models around project risk allocation and technology complexity. Segment boundaries determine whether contractors pursue integrated turnkey mandates or specialized design-only roles.
Project Type:
Standardization dominates utility-scale thermal retrofits while renewable mandates demand customized engineering for site-specific solar and wind resources.
- Renewable Energy:Photovoltaic and wind farm construction commands contractor pipelines through PNRR auction mechanisms. Wallachia plain developments cluster near existing 400 kV transmission corridors, compressing interconnection timelines for solar developers.
- Thermal Power:Combined-cycle gas turbine upgrades and flexibility retrofits retain margin concentration despite declining new-build activity. Black Sea coastal facilities prioritize efficiency improvements over greenfield construction.
- Hydro Power:Run-of-river rehabilitation projects concentrate in Carpathian foothills.
- Nuclear Power:Cernavodă unit refurbishment drives specialized civil and mechanical contracting.
Leading the category by volume: Renewable Energy. Growing fastest: Thermal Power flexibility retrofits.
Service Type:
Front-end engineering concentrates margin with specialized consultants while construction phases commoditize through competitive bidding.
- Engineering Services:Front-end design and grid code compliance sit at the high-margin core. ANRE technical specifications evolve rapidly, forcing owners to outsource protection relay configuration and power systems modeling before construction tendering.
- Construction Services:Field execution scales through labor deployment and equipment logistics. Romanian contractors leverage lower wage structures against regional competitors for Bulgarian and Hungarian transmission upgrades.
- Procurement Services:Equipment sourcing and supplier qualification for high-voltage components.
- Project Management:Schedule coordination and interface risk absorption across multi-contractor sites.
Highest margin capture: Engineering Services. Steepest expansion trajectory: Project Management as utilities consolidate accountability structures.
End User:
Procurement sophistication varies sharply between state-mandated utilities and private developers navigating permitting complexity.
- Utilities:Transelectrica SA and distribution operators consolidate procurement under framework agreements favoring integrated turnkey delivery. PNRR disbursement deadlines compress contractor qualification timelines for grid modernization tenders.
- Independent Power Producers:Solar developers in Muntenia mandate single-accountability structures, displacing fragmented design-bid-build sequences. IPPs transfer interface risk to contractors while retaining development margin.
- Government Entities:Public infrastructure projects through national recovery programs.
- Industrial Clients:Cogeneration and captive power for manufacturing facilities.
Dominant procurement volume: Utilities. Fastest contract growth: Independent Power Producers.
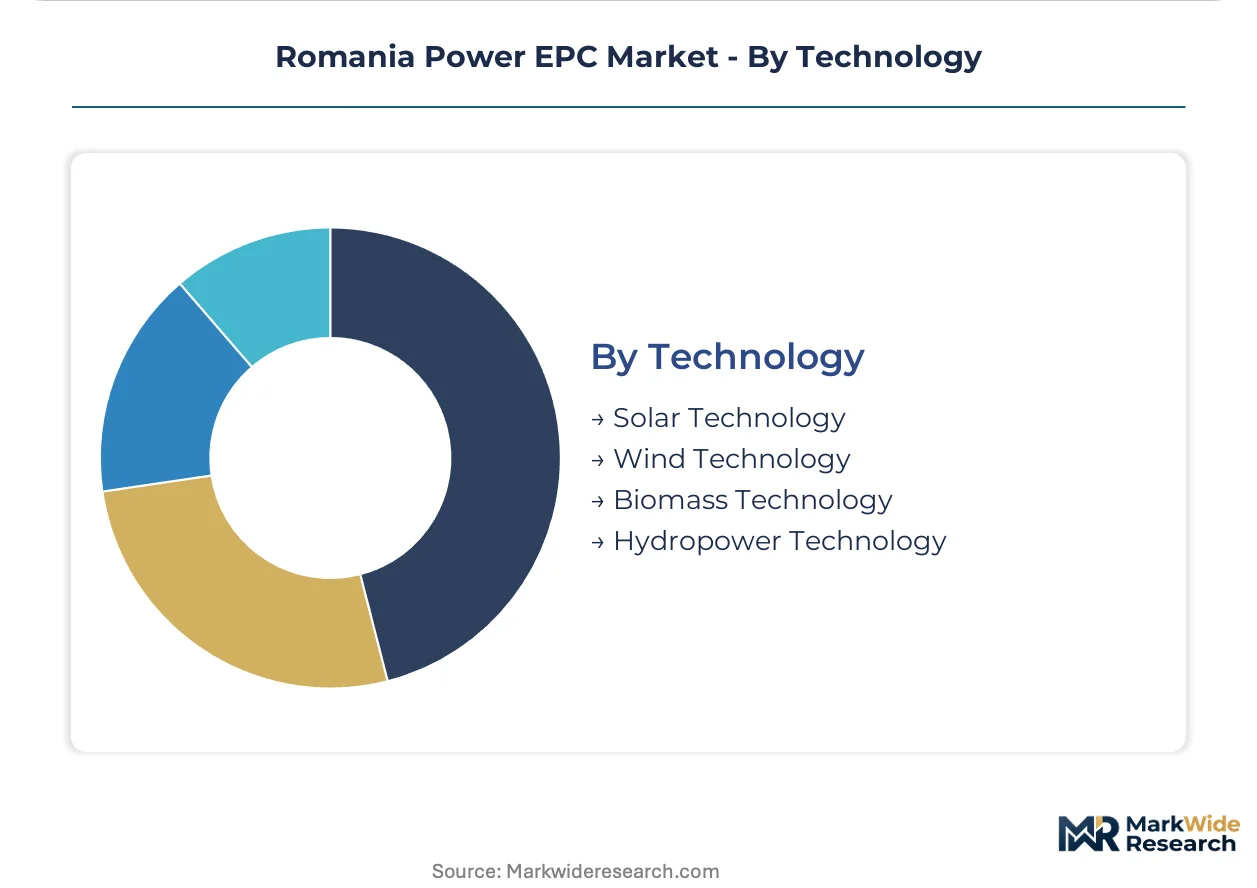
Technology:
Technology selection determines supply chain configuration and local-content compliance thresholds under PNRR conditions.
- Solar Technology:Fixed-tilt and tracking systems dominate Wallachia procurement. Containerized substation solutions modularize 110 kV interconnection, enabling rapid deployment for rural electrification mandates.
- Wind Technology:Onshore turbine installation concentrates in Dobrogea region near Black Sea coast. Offshore floating platforms represent untapped capacity requiring marine EPC capabilities and new corridor development.
- Biomass Technology:Agricultural residue-to-energy projects in rural Moldova.
- Hydropower Technology:Small-scale run-of-river rehabilitation in mountain regions.
Technology commanding current investment: Solar Technology. Emerging fastest: Wind Technology offshore variants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper deposits in the Apuseni Mountains anchor Romania's electrical equipment supply chain, feeding transformer winding production and cable manufacturing clusters that support power infrastructure deployment across Southeastern Europe.
Wallachia
Solar farm development concentrates along the Wallachia plain where existing 400 kV transmission corridors reduce interconnection costs for photovoltaic developers. ANRE grid connection tariffs determine project viability timelines across Muntenia's renewable auction pipeline. Bucharest and Ploiești host engineering consultancies that specialize in turnkey EPC contracting for utility-scale solar mandates.
Transylvania
Grid modernization tenders drive substation refurbishment demand across central Romania's distribution network. BIS certification requirements for high-voltage equipment extend procurement cycles for transformer upgrades. Cluj-Napoca anchors a cluster of power systems engineering firms that configure protection relay systems for regional transmission operators.
Dobrogea
Onshore wind installation concentrates near the Black Sea coast where consistent wind resources support turbine deployment. The maritime zone offers untapped capacity for floating offshore platforms requiring specialized marine EPC capabilities. Constanța serves as the logistics hub for heavy component transport and coastal construction staging.
Moldova
Agricultural residue-to-energy projects create distributed biomass generation demand across rural northeastern counties. PNRR spending conditions impose local-content thresholds that strain supply chains for specialized combustion equipment. Iași hosts regional contractors that configure small-scale run-of-river hydropower rehabilitation in the Carpathian foothills.
Banat
Industrial cogeneration facilities drive captive power demand among manufacturing plants near the Hungarian and Serbian borders. EU taxonomy alignment pressures filter into equipment procurement specifications for switchgear and transformer replacements. Timișoara supports a base of electrical contractors that bid on cross-border transmission upgrades leveraging Romania's lower labor cost structure.
Romania Power EPC Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue hybrid project integration and digital delivery platforms. Romanian Power EPC market structure consolidates around integrated utilities with captive engineering capacity, mid-tier regional contractors, and international equipment vendors with local partnerships. Strategic archetypes include turnkey solution providers, specialized high-voltage engineering consultancies, and modular substation packagers. Dominant competitive moves span framework agreement consolidation by state utilities and cross-border expansion into Bulgarian and Hungarian transmission markets.
Among Italy-based integrated energy groups, Enel SpA exemplifies the development-platform archetype that compresses design-bid-build sequences into single-accountability structures. Greek industrial conglomerate Mytilineos SA anchors the regional fuel-supply-chain position through captive engineering capacity. Romanian state utility Transelectrica SA sits within the procurement-concentration tier, consolidating grid modernization mandates under compressed PNRR disbursement timelines.
| Leading Market Players |
|---|
| Enel SpA |
| Mytilineos SA |
| Transelectrica SA |
| Electroalfa |
| E.ON SE |
| Romelectro SA |
| Siemens AG |
| Societatea Nationala Nuclearelectrica SA |
| JinkoSolar Holding Co Ltd |
| Others |
Value Network & Pricing Analysis
Captive engineering capacity among integrated utilities anchors both supply security and pricing power in Romania's Power EPC market. Enel SpA and Mytilineos SA leverage in-house design teams to compress procurement cycles while insulating margins from spot-market volatility in copper and steel inputs. This backward integration into front-end engineering creates a two-tier market where turnkey providers command premium pricing against commoditized construction-only bidders.
Pricing Analysis
Extended warranty and performance guarantee bundling separates premium EPC contractors from price-competitive construction specialists. Turnkey providers embed 10-year equipment warranties and output performance bonds into lump-sum contracts, while design-only firms price engineering services separately with limited liability exposure. Price differentiation hinges on BIS certification status and ANRE grid code compliance track records. Pricing pressure stems from raw material volatility in transformer windings and structural steel, compressing fixed-price contract margins for 400 kV substation builds. State utilities like Transelectrica SA exhibit lowest price sensitivity due to PNRR-backed financing, while independent solar developers in Muntenia negotiate aggressively on construction phases.
Supply Chain Analysis
Direct-to-utility channels handle framework agreement volumes for Transelectrica SA and distribution operators, while project-specific procurement serves independent power producers. Geographic supply concentration centers on Germany, Italy, and China for high-voltage switchgear, power transformers, and photovoltaic module supply. Raw material dependencies span copper from Apuseni Mountain deposits, electrical steel from European mills, and SF6 insulation gas from specialized chemical producers. Supply chain risk concentrates in single-source vulnerability for 400 kV circuit breakers and protection relay systems. Distribution runs through authorized equipment distributors in Bucharest and Cluj-Napoca, with direct manufacturer relationships for utility-scale mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Romania's Power EPC market is consolidating around integrated turnkey capabilities as PNRR disbursement deadlines and BIS certification requirements force fragmented engineering firms toward exit or acquisition. Compressed qualification timelines favor contractors with captive supply chains and established ANRE relationships.
For Market Incumbents: Deepen backward integration into high-voltage equipment manufacturing to capture margin currently flowing to German and Italian switchgear suppliers. Expand containerized substation assembly capacity near Ploiești to serve Wallachia solar cluster demand under compressed PNRR timelines. Threat substitution from modular packagers like Electroalfa demands faster factory-assembly turnaround than traditional field-built alternatives.
For New Entrants and Emerging Players: Enter via Black Sea offshore wind engineering partnerships, where marine EPC capabilities remain scarce and Constanța logistics infrastructure creates natural moats. Target Dobrogea onshore wind repowering projects as the most penetrable segment, with existing grid corridors reducing interconnection risk. Go-to-market angle: joint venture with Greek or Italian marine contractors to transfer floating platform expertise.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to European integrated energy groups seeking Romanian platform assets. Long-term viability hinges on PNRR disbursement pacing sustaining contractor backlog visibility through the projection horizon. Acquisition target archetype: mid-tier engineering consultancies with ANRE permitting relationships and Cluj-Napoca power systems talent pools. Signal to watch: ANRE queue reform implementation pace as inflection indicator for demand continuity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Switchgear Manufacturing | Captures margin from German suppliers while meeting BIS certification thresholds for Transelectrica tenders. |
| Containerized Substation Assembly Expansion | Compresses rural electrification timelines for Muntenia solar developers facing PNRR spending deadlines. |
| Black Sea Offshore Wind Partnership | Accesses untapped maritime capacity requiring specialized marine EPC capabilities and new corridor development. |
| ANRE Grid Code Compliance Certification | Qualifies contractors for protection relay configuration work that utilities outsource before construction tendering. |
| Cross-Border Bulgarian Transmission Bidding | Leverages Romanian labor cost advantages against regional competitors for EU-funded grid modernization. |
Research Methodology
Independent corroboration across utility procurement officers, EPC project directors, and ANRE regulatory staff underwrites the qualitative findings in this analysis. Primary fieldwork engaged IPP development leads, transmission equipment procurement managers, and power systems engineering consultants across Bucharest, Cluj-Napoca, and Constanța. Secondary validation drew from ANRE grid connection tariff publications, PNRR disbursement tracking databases, and EU taxonomy technical screening criteria. Bottom-up project pipeline assessments triangulated against top-down market sizing from equipment import records and construction permit filings.
Historical reference periods spanning pre-PNRR baseline activity through current auction pipeline development anchored the forecast window construction. The analytical framework modeled segmentation dimensions across project type, service type, end user category, and technology selection throughout the projection horizon. CAGRs derived from weighted average of equipment deployment trajectories and construction labor cost indices. Industry-specific forecast inputs included ANRE permitting queue velocity assumptions and copper price volatility bands.
Forecast precision tightens around the base case; tail outcomes carry wider variance under PNRR disbursement delays or ANRE technical code revision cycles. Forecasts reflect documented assumptions regarding auction mechanism continuity and local-content threshold enforcement. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
AC Power Sources Market
Power Equipment
Thailand Power Market
Power Equipment
Qatar Power EPC Market
Power Equipment
Asia-Pacific Steam Turbine Market
Power Equipment
United Kingdom Power EPC Market
Power Equipment
United States Power Rental Market
Power Equipment
Wind Tunnel Fans Market
Power Equipment
Power Conditioning Services Market
Power Equipment
Global Exhaust Heat Recovery System Market
Power Equipment
North America SCR Power Controller Market
Power Equipment
Gas Insulated Power Equipment Market
Power Equipment
Power Analyzers Market
Power Equipment
India Power EPC Market
Power Equipment
Clean Steam Separator Market
Power Equipment
Global Power Rental Systems Market
Power Equipment
Turbine Control Systems Market