
 United Arab Emirates Power Market | 2026-2036
United Arab Emirates Power Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Power Market Outlook
The UAE Net Zero by 2050 Strategic Initiative is rebalancing procurement priorities across the Emirates, pushing utilities toward low-carbon baseload and dispatchable renewable contracts. DEWA leverages its Mohammed bin Rashid Al Maktoum Solar Park to sustain one of the world's largest single-site solar installations. TAQA anchors generation diversification through its integrated water-power assets and growing clean energy pipeline. ACWA Power competes aggressively on independent power producer tenders, securing long-term offtake agreements that reshape capacity planning.
United Arab Emirates power encompasses electricity generation, transmission, and distribution infrastructure operating across a desert climate with ambient temperatures exceeding 50°C, requiring gas turbine inlet cooling and advanced transformer thermal management. The primary purpose is to supply reliable baseload and peak power to energy-intensive industries, desalination plants, and rapidly expanding urban centers. Renewable installations lead capacity additions, with solar PV dominating new build economics. Grid-connected infrastructure occupies the largest share of installed capacity, though microgrid deployments at remote industrial sites and island communities represent an emerging margin pool for specialized engineering firms.
MOHAP and the UAE Ministry of Energy and Infrastructure shape demand through federal building efficiency codes and federal energy performance standards that mandate retrofit timelines for existing stock. The Emirates Authority for Standardization and Metrology (ESMA) enforces equipment efficiency labels and testing protocols that restrict market access for non-compliant generation and cooling technologies. Stakeholders must monitor how federal clean energy procurement mandates interact with emirate-level utility restructuring, particularly as EWEC and Etihad Water & Electricity consolidate buyer functions and reshape developer engagement models.
Market Dynamics
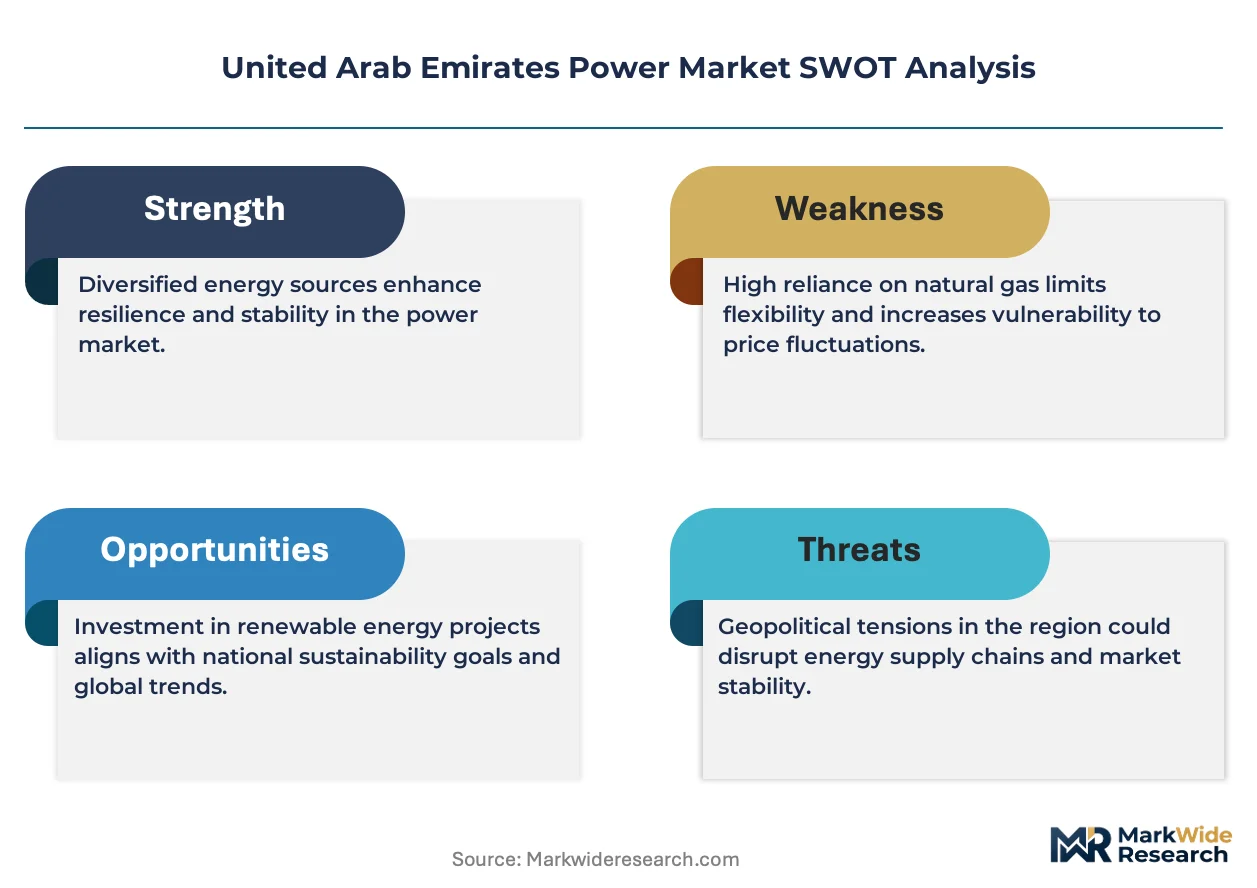
The UAE Net Zero by 2050 Strategic Initiative is restructuring power procurement economics, compelling utilities to renegotiate long-term offtake terms and accelerate capital rotation from gas-fired baseload toward dispatchable solar and nuclear capacity. This federal mandate intersects with emirate-level utility consolidation, creating divergent buyer profiles between Abu Dhabi's EWEC-led centralized procurement and Dubai's DEWA-anchored integrated model.
Growth Catalysts
- Industrial Clean Power Procurement Mandates:Aluminum smelters and petrochemical complexes under the UAE Net Zero by 2050 Strategic Initiative are contracting dedicated renewable capacity, creating anchor demand for solar PV and nuclear output at Barakah.
- Federal Building Efficiency Codes:MOHAP and the Ministry of Energy and Infrastructure mandate retrofit timelines for existing federal building stock, stimulating distributed generation and smart metering deployments across government facilities.
- Desalination-Energy Integration:Reverse osmosis plants co-located with solar PV at Al Taweelah and Mirfa are capturing economies of scale in water-power asset development, concentrating developer attention on coastal industrial zones.
Market Restraints
- Gas Price Volatility:Natural gas remains the marginal fuel for peaking capacity, and import dependency through Dolphin Energy links exposes generators to regional supply disruptions and fuel cost pass-through limitations under regulated tariffs.
- Transformer Thermal Management Constraints:Ambient temperatures exceeding 50°C in summer months degrade conventional transformer insulation life, forcing derating or expensive liquid-immersed cooling systems that inflate substation capital intensity.
- Land Availability for Utility-Scale Solar:Suitable desert parcels with transmission access are concentrating in Abu Dhabi emirate, creating site scarcity and interconnection queue delays for developers targeting Dubai or Northern Emirates.
Strategic Opportunities
- Remote Industrial Microgrids:Islanded mining and oilfield operations in Ras Al Khaimah and Fujairah present unserved demand for hybrid solar-diesel-battery systems, bypassing grid extension economics entirely.
- Green Hydrogen Export Infrastructure:The UAE National Hydrogen Strategy positions Al Reyadah and ADNOC's Ruwais complex as production hubs, requiring dedicated renewable offtake and electrolyzer-ready grid connections that reshape generation planning.
- Behind-the-Meter C&I Solar:ESMA equipment efficiency labels are accelerating rooftop PV adoption in Dubai's free zones, where commercial tenants seek to reduce exposure to DEWA's demand-based tariff structures.
Industry Challenges
- Grid-Scale Battery Integration Complexity:Four-hour lithium-ion storage systems are struggling to meet grid code requirements for frequency response in high-renewable scenarios, forcing extended procurement timelines and technical qualification delays.
- Nuclear Workforce Pipeline Constraints:Barakah's four-reactor expansion has depleted the regional pool of qualified operations and maintenance personnel, driving compensation inflation and training program bottlenecks for subsequent clean energy projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Power Market |
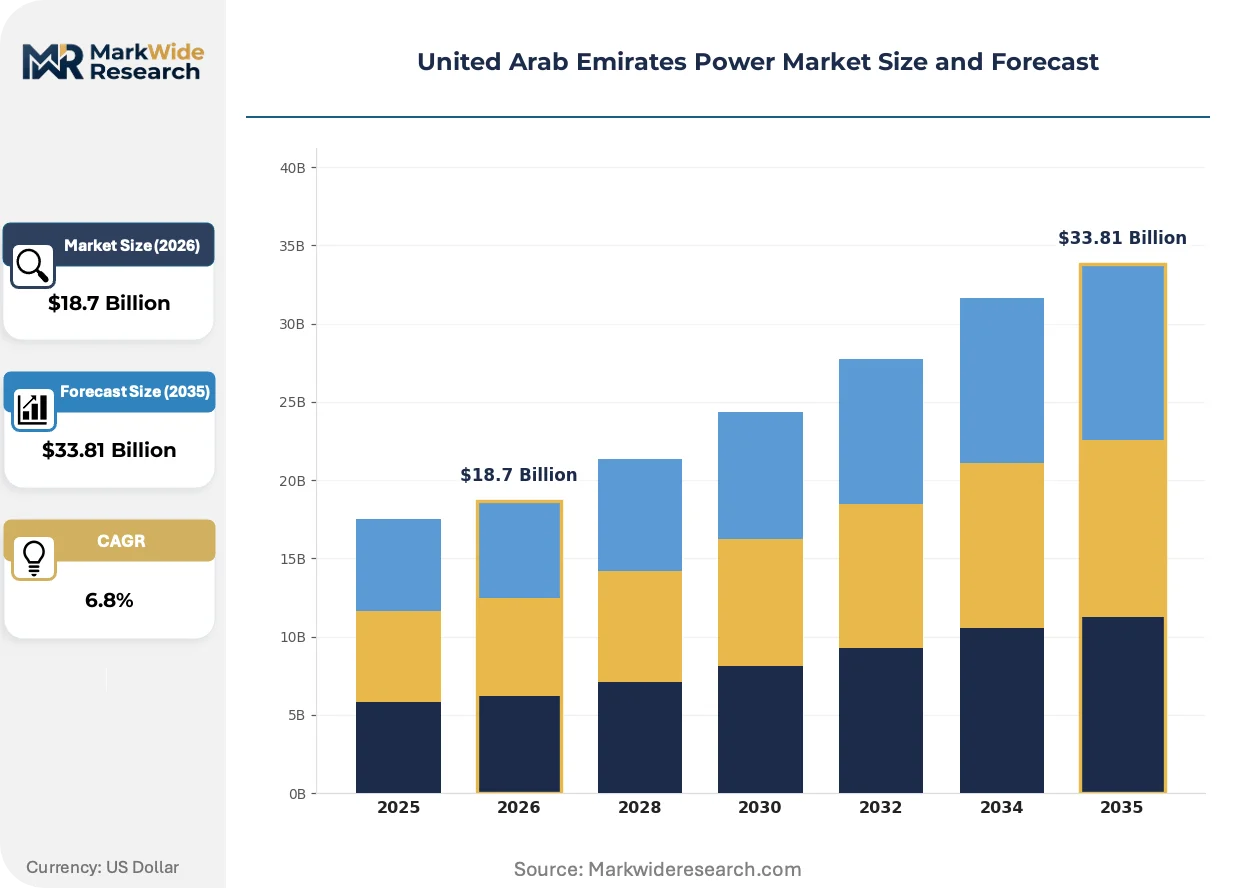
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Renewable, Conventional, Nuclear, Hydropower End User: Residential, Industrial, Commercial, Government Installation: Grid-Connected, Off-Grid, Microgrid, Centralized Technology: Solar PV, Wind Turbine, Gas Turbine, Biomass |
| Companies Covered | Masdar (Abu Dhabi Future Energy Company), Etihad Water & Electricity, Dubai Electricity and Water Authority (DEWA), GE Vernova, Emirates Water and Electricity Company (EWEC), Abu Dhabi National Energy Company PJSC (TAQA), ACWA Power Company, National Central Cooling PJSC, Emirates Nuclear Energy Corporation (ENEC), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Power Market Strategic Shifts
Digitalization of asset management and hybridization of generation portfolios are compressing planning cycles and redefining competitive differentiation among UAE power developers. These shifts are accelerating procurement of predictive analytics platforms and integrated water-energy technologies.
Hybrid solar-plus-storage configurations are unifying generation and firming functions in single asset classes, reducing offtaker exposure to separate capacity market products. EWEC's recent tenders mandate co-located battery storage for new PV projects, compressing developer margins but streamlining grid integration timelines. This unifying architecture is displacing standalone peaker plant economics in Abu Dhabi's capacity expansion planning.
MOHAP's federal building efficiency codes are tightening minimum performance standards for cooling equipment and envelope insulation across government facilities. The regulations are accelerating replacement cycles for aging HVAC and lighting systems, stimulating demand for building-integrated photovoltaics and smart energy management platforms. Dubai's retrofit program under the Demand Side Management Strategy is experiencing the most concentrated compliance activity.
Large industrial offtakers are consolidating procurement functions under centralized energy management offices, bypassing traditional utility intermediaries for direct renewable power purchase agreements. Aluminum producers and cement manufacturers are negotiating bilateral contracts with IPPs, fragmenting the historical utility monopoly over generation sourcing. This behavioral shift is most visible in Abu Dhabi's KIZAD and Dubai's Jebel Ali industrial corridors.
United Arab Emirates Power Market Segmentation
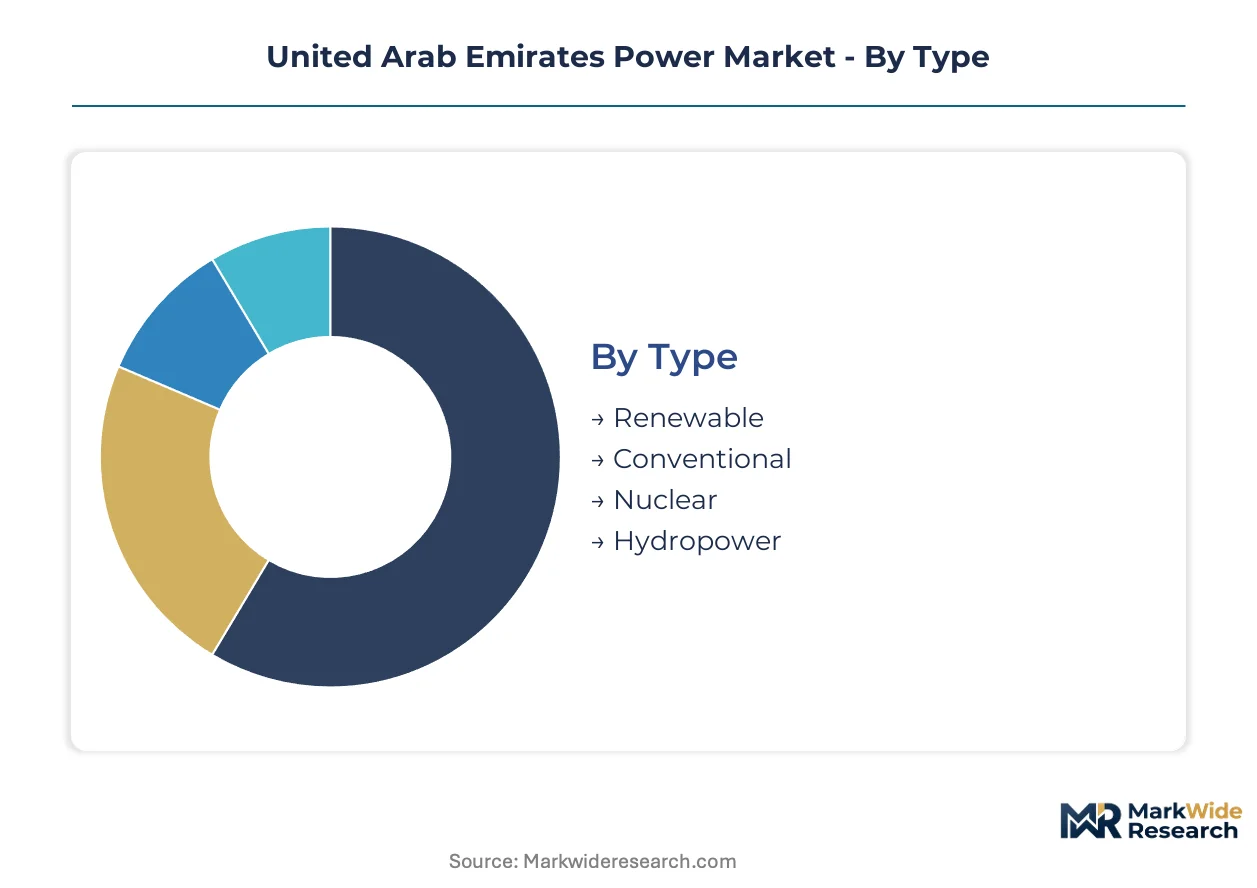
The UAE power market segments across generation technology, end-use demand, grid architecture, and equipment type. Each dimension reveals distinct procurement patterns shaped by emirate-level utility structures and federal decarbonization mandates under the UAE Net Zero by 2050 Strategic Initiative.
Type:
Generation type segments split between standalone baseload assets and embedded dispatchable capacity integrated with industrial or water production facilities.
- Renewable:Solar PV dominates new capacity additions with single-site installations exceeding 2 GW at Mohammed bin Rashid Al Maktoum Solar Park. EWEC's tender mandates now require co-located battery storage, compressing developer margins while streamlining grid code compliance for variable output.
- Conventional:Natural gas-fired combined cycle plants remain the marginal fuel for peak demand, though Barakah nuclear output is displacing CCGT baseload hours. Dolphin Energy import dependency exposes generators to regional supply disruptions under regulated tariff structures that limit cost pass-through.
- Nuclear:Barakah's four-reactor expansion supplies firm low-carbon baseload to Abu Dhabi emirate, with output contracted to aluminum smelters and desalination plants at Al Taweelah.
- Hydropower:Pumped storage at Hatta represents the sole utility-scale hydro asset, providing frequency regulation and black-start capability for Dubai's grid.
Conventional capacity leads installed volumes today; renewable additions are gaining share fastest across the Emirates.
End User:
Demand segmentation reflects divergent tariff structures and procurement autonomy across customer classes, from regulated residential rates to bilateral industrial power purchase agreements.
- Residential:DEWA and EWEC maintain monopoly supply relationships with demand-based tariff tiers that incentivize consumption reduction during summer peak hours. Smart meter penetration exceeds 90% in Dubai, enabling time-of-use pricing and distributed solar net metering.
- Industrial:Aluminum smelters and petrochemical complexes at KIZAD and Ruwais negotiate direct renewable PPAs with IPPs, bypassing utility intermediaries. Federal clean power procurement mandates under the UAE Net Zero by 2050 Strategic Initiative are accelerating this behavioral shift.
- Commercial:Dubai's free zone tenants deploy behind-the-meter rooftop PV to reduce exposure to DEWA demand charges, with ESMA efficiency labels restricting equipment market access.
- Government:MOHAP federal building efficiency codes mandate retrofit timelines across federal facilities, stimulating distributed generation and smart energy management platform procurement.
Industrial offtake commands the largest share of contracted renewable capacity; commercial segment expansion is climbing the fastest as free zone developers accelerate rooftop deployments.
Installation:
Grid architecture segments range from centralized transmission-connected assets to islanded systems serving remote industrial and island communities.
- Grid-Connected:Transmission-linked utility-scale solar and nuclear at Barakah, Al Dhafra, and Mohammed bin Rashid Al Maktoum Solar Park constitute the dominant capacity share. Interconnection queue delays concentrate suitable desert parcels in Abu Dhabi emirate.
- Off-Grid:Islanded diesel-solar hybrid systems serve mining operations in Ras Al Khaimah and Fujairah oilfields where grid extension economics fail. These deployments bypass utility procurement entirely.
- Microgrid:Remote industrial sites and island communities deploy hybrid solar-diesel-battery configurations with advanced energy management systems. Specialized engineering firms target this emerging margin pool.
- Centralized:Large-scale combined cycle and nuclear plants anchor generation portfolios with dedicated transmission corridors to load centers in Abu Dhabi and Dubai.
Grid-connected infrastructure dominates capacity today; microgrid deployments are expanding most quickly in Northern Emirates industrial zones.
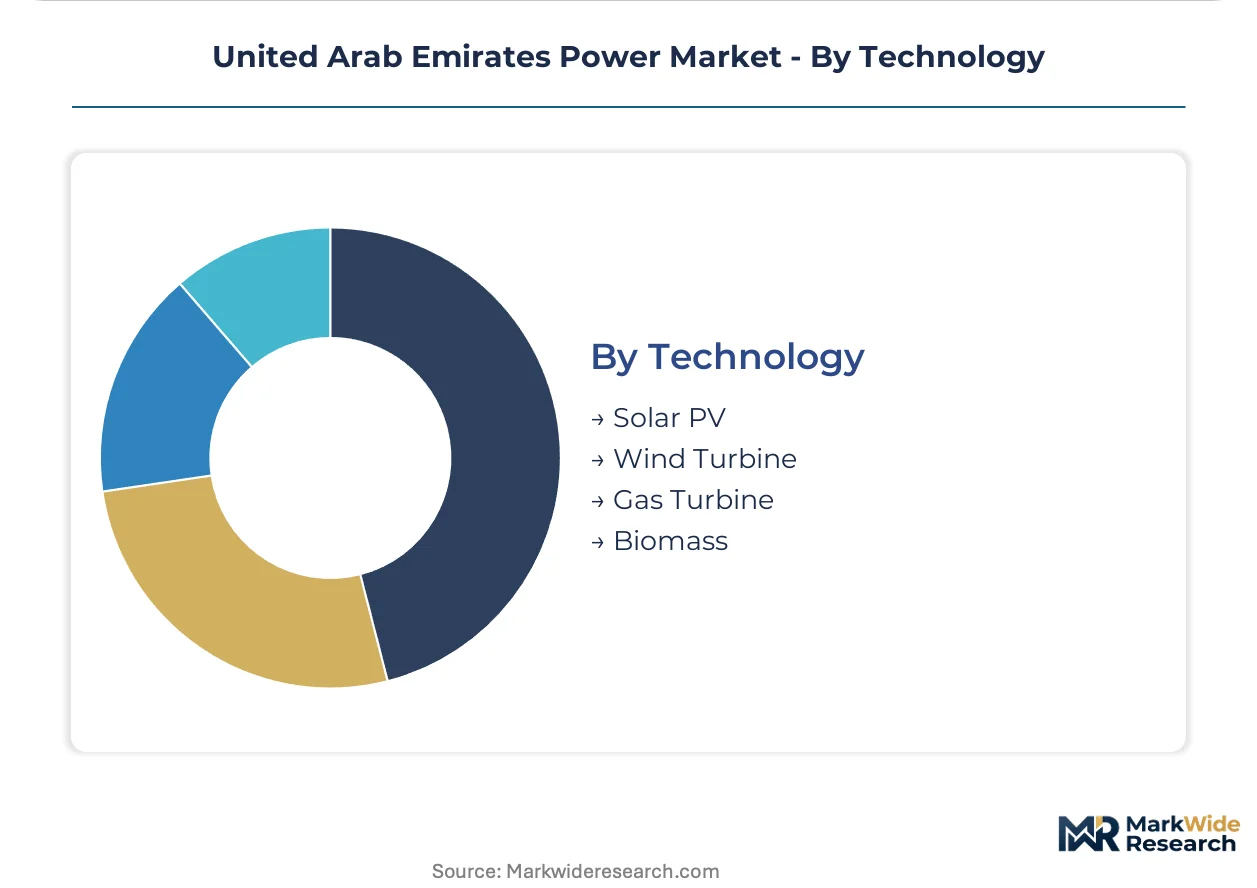
Technology:
Equipment technology segments span renewable capture, thermal conversion, and biomass combustion systems with varying capital intensity and fuel requirements.
- Solar PV:Crystalline silicon modules with single-axis tracking dominate utility-scale economics at Al Dhafra and Noor Abu Dhabi, achieving record-low levelized costs. Ambient temperatures exceeding 50°C degrade inverter efficiency, requiring derating or advanced thermal management.
- Gas Turbine:Advanced F-class and H-class units provide peaking and mid-merit capacity with inlet cooling systems to maintain output during summer heat. Fuel cost volatility under regulated tariffs compresses generator margins.
- Wind Turbine:Limited onshore resource quality restricts deployment to coastal and mountainous zones in Fujairah with capacity factors below solar alternatives.
- Biomass:Municipal waste-to-energy at Al Warsan represents the primary operational asset, with feedstock constraints limiting scale-up potential.
Solar PV technology leads new capacity additions; gas turbine installations face the steepest contraction as nuclear and renewable output displaces thermal baseload hours.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UAE power sector traces its modern expansion to the 1970s oil boom, when federal investment established integrated utilities in Abu Dhabi and Dubai to serve emerging industrial zones and desalination complexes.
Dubai
Dubai's Mohammed bin Rashid Al Maktoum Solar Park anchors the emirate's renewable pivot, with DEWA commissioning the world's largest single-site solar installation. MOHAP federal building efficiency codes mandate retrofit timelines across government facilities, accelerating distributed generation procurement. Jebel Ali industrial corridor hosts aluminum smelters and free zone tenants deploying behind-the-meter rooftop PV to reduce exposure to demand-based tariff structures.
Abu Dhabi
Abu Dhabi concentrates the nation's nuclear and utility-scale solar capacity through Barakah's four-reactor expansion and Al Dhafra's crystalline silicon installations. EWEC consolidates centralized procurement functions, reshaping developer engagement with co-located battery storage mandates. KIZAD and Ruwais industrial zones host petrochemical complexes negotiating direct renewable PPAs that bypass traditional utility intermediaries.
Sharjah
Sharjah's smaller industrial base drives demand for commercial and residential efficiency retrofits under federal energy performance standards. The emirate's waste-to-energy facility at Al Saja'a represents the primary operational biomass asset, with feedstock constraints limiting scale-up potential. Sharjah Research Technology and Innovation Park clusters clean energy startups targeting microgrid deployments for remote industrial applications.
Northern Emirates
Ras Al Khaimah and Fujairah present unserved demand for hybrid solar-diesel-battery systems at islanded mining and oilfield operations where grid extension economics fail. Mountainous coastal zones in Fujairah host limited wind turbine deployments with capacity factors below solar alternatives. Specialized engineering firms target this emerging margin pool for remote industrial microgrids.
United Arab Emirates Power Market Competitive Environment
Premium-margin players sit above commodity-margin players across technology integration depth and offtake contract duration. The UAE power market exhibits tiered consolidation, with state-backed utilities controlling generation procurement and transmission infrastructure while independent power producers compete for long-term renewable tenders. Three archetypes dominate: integrated water-power asset owners, specialized renewable developers, and nuclear operations specialists. Competitive intensity centers on strategic partnerships for hybrid project development and portfolio diversification into green hydrogen offtake agreements.
Within the state-backed utility tier, Dubai Electricity and Water Authority and Emirates Water and Electricity Company anchor procurement functions across their respective emirates. Among independent power producers, ACWA Power Company occupies a position exemplifying competitive tender participation for solar-plus-storage configurations. Masdar represents the clean energy investment archetype, with project development spanning domestic and international markets. Abu Dhabi National Energy Company PJSC sits within the integrated asset owner category, leveraging water-power synergies across its operational portfolio.
| Leading Market Players |
|---|
| Masdar (Abu Dhabi Future Energy Company) |
| Etihad Water & Electricity |
| Dubai Electricity and Water Authority (DEWA) |
| GE Vernova |
| Emirates Water and Electricity Company (EWEC) |
| Abu Dhabi National Energy Company PJSC (TAQA) |
| ACWA Power Company |
| National Central Cooling PJSC |
| Emirates Nuclear Energy Corporation (ENEC) |
| Others |
Value Chain & Pricing Dynamics
Captive renewable offtake integration by Emirates Water and Electricity Company and Dubai Electricity and Water Authority anchors supply security and pricing power across the UAE power sector. This utility-controlled procurement architecture concentrates buyer leverage while insulating developers from spot market volatility through regulated tariff structures.
Pricing Analysis
Long-term power purchase agreements with inflation-linked escalation clauses dominate capacity procurement, separating baseload nuclear and solar contracts from peaking gas tariffs. Price differentiation rests on contract duration and technology risk allocation, with Barakah nuclear commanding premium firming value and solar-plus-storage facing margin compression from mandated battery co-location. Cost compression in utility-scale solar stems from crystalline silicon module oversupply and developer competition for EWEC tenders. Industrial offtakers at KIZAD and Ruwais exhibit lowest price sensitivity due to carbon compliance mandates, while commercial free zone tenants in Dubai face highest sensitivity to DEWA demand charges.
Supply Chain Analysis
Workforce scarcity for nuclear operations and maintenance personnel across the Gulf Cooperation Council constrains Barakah expansion timelines and drives compensation inflation for subsequent clean energy projects. Equipment manufacturing concentrates in China for crystalline silicon modules, South Korea for advanced gas turbines, and France for nuclear reactor components. Raw material dependencies span polysilicon ingots, high-grade steel forgings, and transformer core laminations. Single-source vulnerability for large power transformer manufacturing creates procurement bottlenecks for substation upgrades. Distribution runs through Emirates Global Aluminium and ADNOC-led industrial consortia for direct bilateral contracting, bypassing traditional utility intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE power market functions as a stable compounder underpinned by federal Net Zero procurement mandates that guarantee renewable capacity absorption through regulated offtake structures.
For Market Incumbents: Deploy hybrid solar-plus-storage engineering capabilities to capture EWEC tender mandates requiring co-located battery systems. Incumbents should secure long-term service contracts for Barakah nuclear operations to lock in specialized workforce pipelines before regional competition intensifies. DEWA and TAQA face emerging threat from industrial direct PPA fragmentation that bypasses utility intermediaries entirely. For New Entrants and Emerging Players: Specialized engineering firms serving remote industrial microgrids in Ras Al Khaimah and Fujairah represent the most penetrable white-space target, where grid extension economics fail and hybrid solar-diesel-battery systems command premium margins. New entrants should pursue joint development partnerships with mining operators and oilfield service companies rather than competing for utility-scale tenders dominated by established IPPs. For Investors and Strategic Acquirers: Roll-up economics work for distributed generation asset operators because federal building efficiency codes mandate retrofit timelines across government facilities that fragment procurement into numerous small-scale projects. Long-term viability centers on platform consolidation of behind-the-meter C&I solar installers in Dubai's free zones. Watch for inflection when EWEC extends battery storage mandates beyond four-hour duration requirements, signaling technology maturation and margin reset.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Solar-Plus-Storage Capacity Buildout | EWEC tender mandates compress developer margins while streamlining grid integration timelines for variable output. |
| Direct Industrial Power Purchase Agreement | Aluminum smelters and petrochemical complexes at KIZAD bypass utility intermediaries for renewable offtake. |
| Nuclear Workforce Pipeline Investment | Barakah expansion depletes regional qualified operations personnel, driving training program bottlenecks. |
| Remote Industrial Microgrid Deployment | Islanded mining operations in Ras Al Khaimah present unserved demand for hybrid solar-diesel-battery systems. |
| Green Hydrogen Electrolyzer-Ready Grid Connection | ADNOC's Ruwais complex requires dedicated renewable offtake that reshapes generation planning priorities. |
Study Parameters
Direct dialogue with utility planning officers, independent power producer project developers, EPC contractors, and grid operators grounded qualitative assessment in operational realities across the Emirates. Secondary validation drew from IEA country reports, EWEC tender documentation, DEWA regulatory filings, and federal energy performance standards issued by MOHAP. Bottom-up project pipeline analysis triangulated with top-down macroeconomic modeling to reconcile capacity addition timelines with demand growth projections.
Segment-level capacity and investment outputs across the analysis window reflect discrete modeling of generation technology, end-use demand class, grid architecture type, and equipment technology tier. CAGRs derived from regression analysis against historical deployment rates, policy mandate trajectories, and industrial load growth patterns. Key forecast inputs incorporated Barakah nuclear commissioning schedules, EWEC tender award timelines, and federal building retrofit compliance deadlines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to gas price volatility through Dolphin Energy import links and transformer thermal management constraints during extreme summer temperatures. Material deviation in federal clean energy procurement mandate enforcement or emirate-level utility restructuring warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Digital Power Conversion Market
Power Equipment
Industrial Gas Turbine Ignition System Market
Power Equipment
Power Infrastructure Market
Power Equipment
Romania Power EPC Market
Power Equipment
Global Power Rental Systems Market
Power Equipment
Asia-Pacific Gas Turbine Service Market
Power Equipment
Wind Turbine Maintenance Market
Power Equipment
Clean Steam Separator Market
Power Equipment
ASEAN Power EPC Market
Power Equipment
China Power EPC Market
Power Equipment
Brazil Power EPC Market
Power Equipment
Advanced Gas Generators Sales Market
Power Equipment
North America SCR Power Controller Market
Power Equipment
Asia-Pacific Gas Turbine Market
Power Equipment
Variable Frequency Drive (VFD) Market
Power Equipment
Power Cables Market