
 North America Nuclear Imaging Market | 2026-2036
North America Nuclear Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Nuclear Imaging Market Analytics
Digital PET detector technology is tilting the technology stack toward silicon photomultiplier architectures that replace conventional photomultiplier tubes. GE Healthcare leverages its vertically integrated supply chain for lutetium-based crystal arrays to sustain manufacturing scale across its PET-CT portfolio. Siemens Healthineers anchors its North American position through proprietary digital photon counting platforms that differentiate image resolution performance. Cardinal Health Inc. competes in the radiopharmaceutical distribution layer, controlling cold-chain logistics for short-lived isotopes across hospital networks.
North America nuclear imaging encompasses diagnostic systems and radiopharmaceuticals that detect gamma ray emissions from administered radioactive tracers to visualize organ function and metabolic activity, with PET scanners achieving spatial resolution below 4 millimeters using lutetium yttrium orthosilicate crystals. The technology serves primarily to stage cancer, evaluate myocardial perfusion, and detect neurodegenerative disease before structural changes appear on conventional imaging. PET scanners command the premium tier of product type segmentation due to cyclotron dependency and isotope half-life constraints that limit manufacturing flexibility. Hybrid imaging technology, combining PET with CT or MRI, leads application growth by correlating metabolic activity with anatomical detail in a single acquisition session.
The FDA oversees device clearance through 510(k) and PMA pathways while the Nuclear Regulatory Commission governs radiopharmaceutical handling licenses, creating a dual-compliance environment that shapes capital procurement timelines. Health Canada and the Canadian Nuclear Safety Commission impose parallel requirements that manufacturers must navigate for cross-border market access. Stakeholders must monitor reimbursement decisions by the Centers for Medicare & Medicaid Services, as coding changes for theranostic procedures will determine whether capital investments in PET-MRI platforms generate adequate clinical throughput.
Market Dynamics
Silicon photomultiplier architectures are collapsing the cost-performance tradeoff that has governed PET detector design for decades, forcing incumbent manufacturers to reconfigure supply chains around lutetium-based crystal sourcing.
Growth Catalysts
- Oncology Precision Staging:Hospital networks in the United States are expanding PET-CT utilization for tumor characterization and treatment response monitoring, driving replacement cycles for aging gamma camera installations.
- FDA Streamlined 510(k) Pathway:Iterative reconstruction software now clears faster through abbreviated review channels, compressing algorithm deployment timelines from 18 months to under 9 months.
- Academic Medical Center Clustering:Major research hospitals concentrated in the Northeast and Midwest maintain continuous capital refresh programs that sustain premium scanner demand.
Market Restraints
- Cyclotron Dependency:PET radiopharmaceutical manufacturing requires proximity to particle accelerator facilities, constraining distribution radius to 100-150 miles for fluorine-18 compounds.
- Isotope Half-Life Constraints:Molybdenum-99 decays to technetium-99m within 66 hours, forcing just-in-time production logistics that amplify cold-chain failure risks.
- Nuclear Regulatory Commission Licensing:Dual compliance with FDA device clearance and NRC radiopharmaceutical handling permits extends procurement timelines by 8-14 months.
Strategic Opportunities
- Theranostic Procedure Expansion:Centers for Medicare & Medicaid Services reimbursement coding for combined diagnostic-therapeutic protocols creates throughput justification for PET-MRI platform investments.
- Silicon Photomultiplier-Digital PET Convergence:Solid-state detector integration with photon-counting electronics enables sub-3-millimeter resolution without proportional scintillator volume increases.
- Canadian Market Access:Health Canada and Canadian Nuclear Safety Commission parallel requirements, once navigated, open procurement channels to major Toronto and Vancouver hospital systems.
Industry Challenges
- Cyclotron Engineer Scarcity:Qualified personnel for isotope production facility operation remain concentrated at legacy atomic energy research sites, constraining new site development.
- Hybrid Imaging Integration Complexity:PET-CT and PET-MRI systems require synchronized calibration protocols between nuclear medicine and radiology departments, fragmenting maintenance responsibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Nuclear Imaging Market |
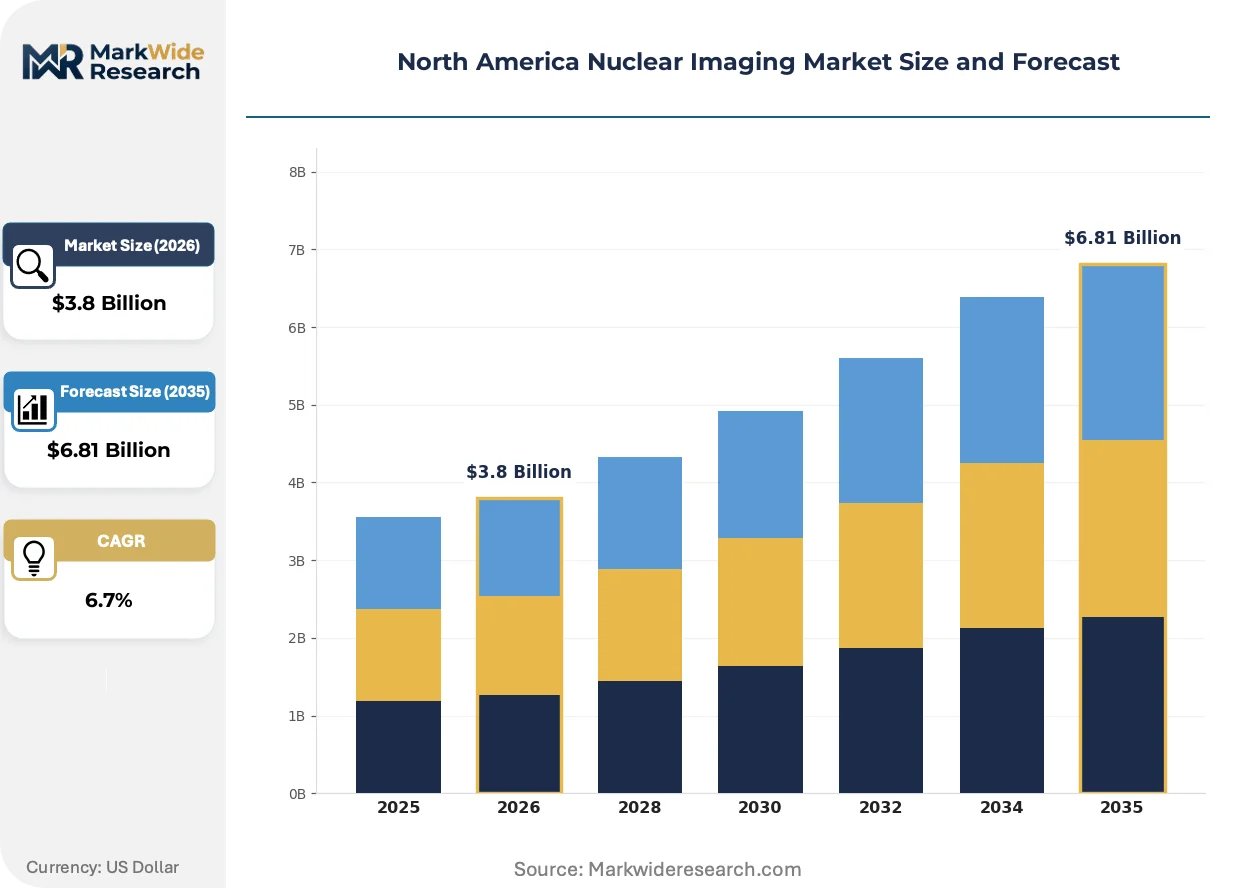
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gamma Cameras, SPECT Scanners, PET Scanners, Accessories End User: Hospitals, Diagnostic Centers, Laboratories, Research Institutions Application: Oncology, Cardiology, Neurology, Thyroid Function Technology: Digital Imaging, Hybrid Imaging, 3D Imaging, Quantitative Imaging |
| Companies Covered | GE Healthcare, Siemens Healthineers, Cardinal Health Inc., Koninklijke Philips NV, Bracco Imaging SpA, Lantheus Medical Imaging Inc., Canon Medical Systems, Curium, Nordion (Canada) Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Nuclear Imaging Market Evolving Landscape
Detector material science and computational reconstruction are converging to redefine performance benchmarks, while reimbursement policy evolution determines which technical capabilities translate to commercial viability.
Lutetium yttrium orthosilicate crystal arrays paired with silicon photomultiplier readout circuits are collapsing the spatial resolution gap between research-grade and clinical PET systems. Academic medical centers in Boston and Chicago are deploying these configurations for neurodegenerative disease protocols. The technology is collapsing price premiums previously commanded by specialized brain-dedicated scanners.
The FDA's streamlined 510(k) pathway for artificial intelligence-enabled iterative reconstruction software compresses algorithm validation requirements for vendors with predicate device histories. Siemens Healthineers and GE Healthcare leverage existing digital PET platform clearances to accelerate deep learning noise reduction deployment. Cardiac perfusion imaging suites represent the segment most affected, with software updates now outpacing hardware replacement cycles.
Hospital procurement committees are unbundling service contracts from capital equipment purchases, forcing original equipment manufacturers to compete with independent service organizations for preventive maintenance revenue. Major health systems in Texas and California now source parts and labor separately through group purchasing organizations. This disintermediation is most visible in cyclotron maintenance, where third-party nuclear pharmacy operators capture service margins previously retained by scanner manufacturers.
North America Nuclear Imaging Market Segmentation
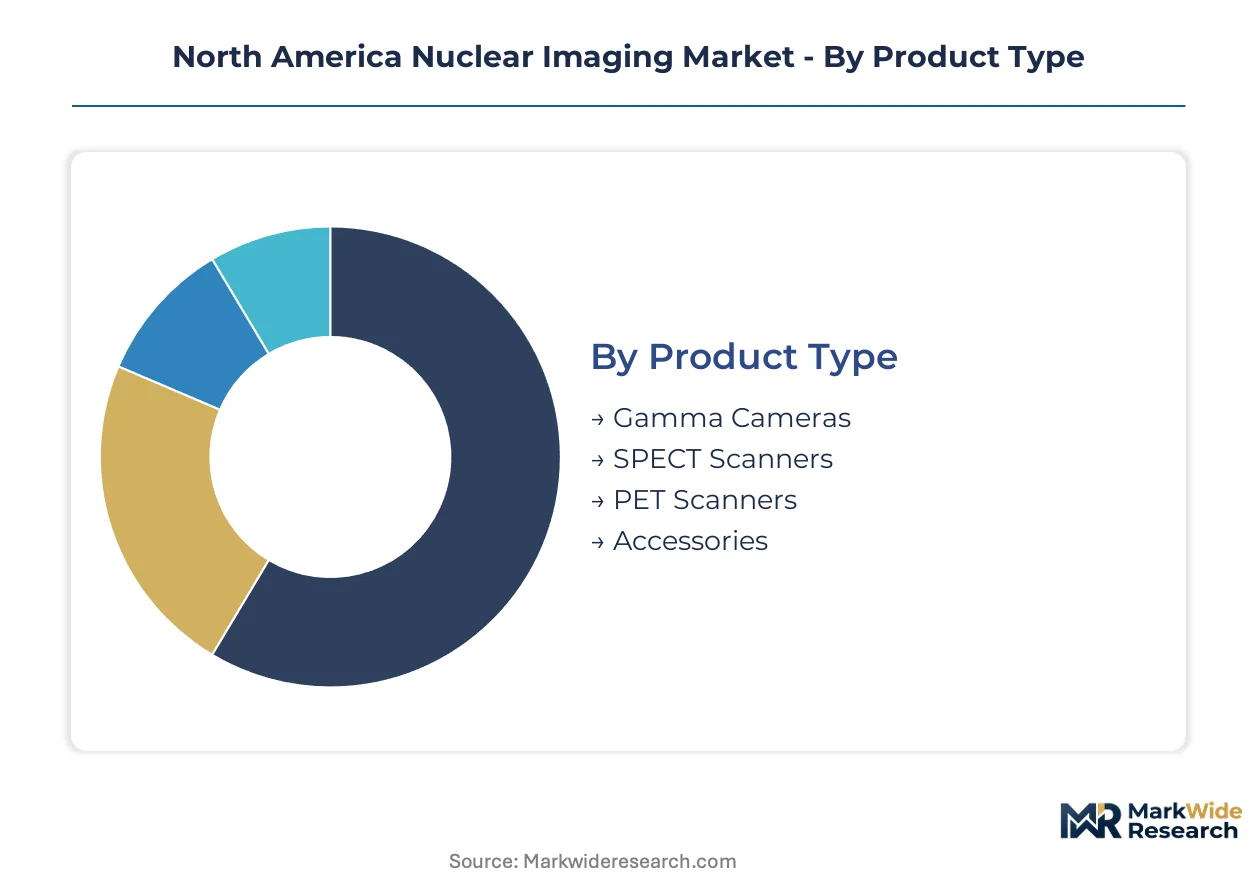
Segmentation in nuclear imaging reveals how technology maturity and reimbursement patterns concentrate capital deployment across distinct customer and application profiles. Understanding these divisions exposes where procurement committees allocate budget and where manufacturers must align product specifications with clinical workflow requirements.
Product Type:
Mature gamma camera installations coexist with emerging digital PET platforms that command replacement cycles and premium pricing.
- PET Scanners:Lutetium yttrium orthosilicate crystal arrays paired with silicon photomultiplier readout circuits achieve sub-4-millimeter spatial resolution. Academic medical centers in Boston and Chicago deploy these configurations for neurodegenerative disease protocols, with cyclotron proximity requirements constraining site selection to major metropolitan clusters.
- Gamma Cameras:Conventional Anger camera technology using sodium iodide crystals and photomultiplier tubes dominates myocardial perfusion imaging throughput. Community hospitals in the Midwest sustain replacement demand as reimbursement codes favor established SPECT procedures over capital-intensive PET alternatives.
- SPECT Scanners:Single-photon systems with cadmium-zinc-telluride semiconductor detectors are displacing conventional Anger architecture in cardiac suites.
- Accessories:Collimators, phantom calibration tools, and patient positioning systems complete installation packages.
PET scanners retain volume leadership; digital detector accessories hold the steepest expansion curve.
End User:
Customer type determines procurement authority and service contract structure across the capital equipment lifecycle.
- Hospitals:Integrated delivery networks in Texas and California unbundle service contracts from capital purchases, sourcing parts and labor separately through group purchasing organizations. These systems generate the majority of PET-CT throughput for oncology staging protocols.
- Diagnostic Centers:Independent imaging facilities concentrate in Florida and Arizona where Medicare reimbursement density supports standalone operations. These centers prioritize workflow efficiency and rapid patient turnover over research capabilities.
- Laboratories:Reference labs perform radioimmunoassay and tracer quality control functions.
- Research Institutions:National laboratories and university medical centers operate cyclotron facilities for isotope production.
Hospitals dominate installed base; diagnostic centers are climbing the fastest as outpatient migration accelerates.
Application:
Clinical indication shapes detector specification requirements and determines reimbursement code availability.
- Oncology:Tumor characterization and treatment response monitoring drive hybrid imaging adoption. PET-CT utilization for precision staging expands across hospital networks as iterative reconstruction software improves lesion detectability in obese patients.
- Cardiology:Myocardial perfusion imaging sustains gamma camera demand through established SPECT protocols. FDA streamlined 510(k) clearance for AI-enabled reconstruction software compresses algorithm deployment timelines in cardiac suites.
- Neurology:Amyloid plaque imaging for Alzheimer's disease requires high-resolution digital PET platforms.
- Thyroid Function:Iodine-131 uptake studies utilize basic gamma camera configurations with specialized collimators.
Oncology commands capital allocation priority; neurology applications are gaining share fastest as dementia protocols expand.
Technology:
Imaging modality integration determines resolution performance and capital intensity thresholds.
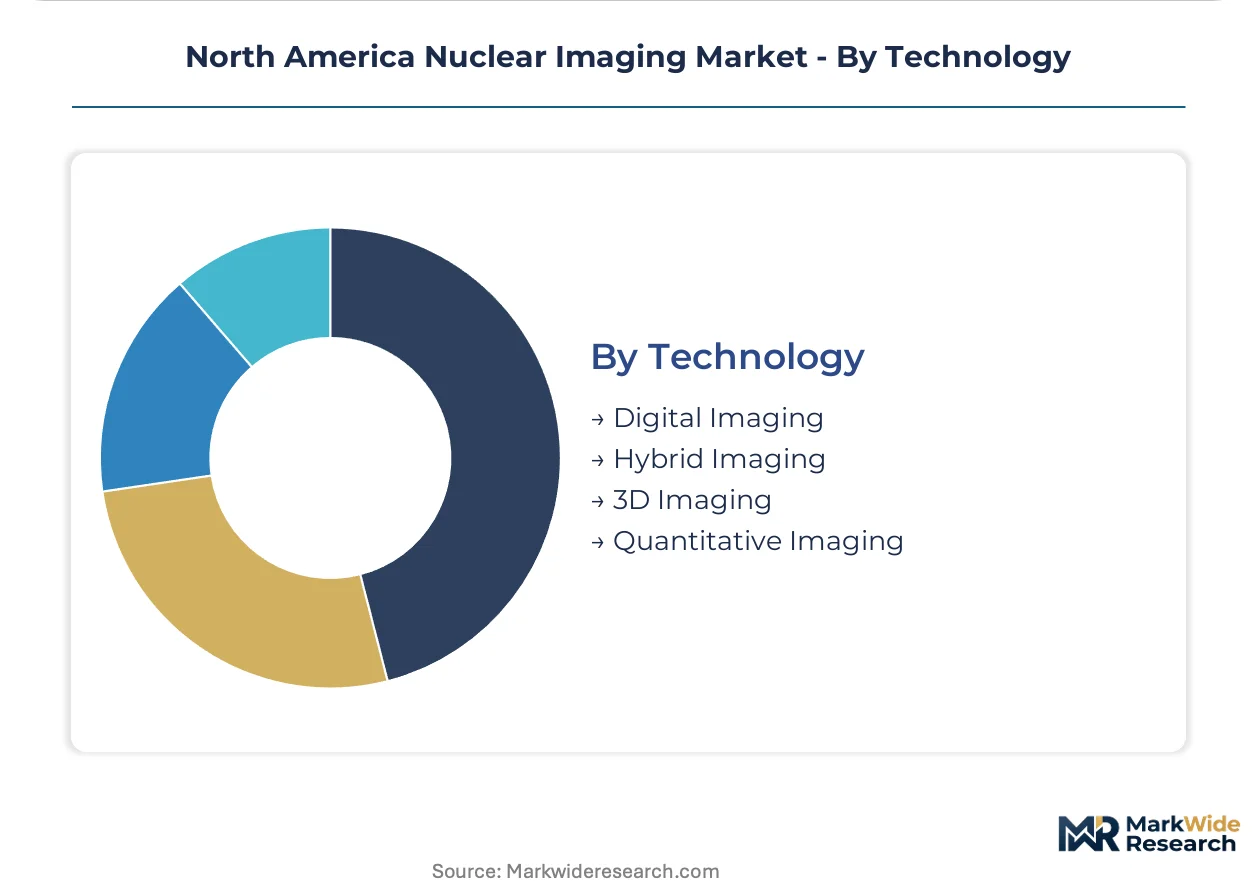
- Hybrid Imaging:PET-CT and PET-MRI systems correlate metabolic activity with anatomical detail in single acquisition sessions. Major health systems evaluate PET-MRI platforms where CMS reimbursement coding for theranostic procedures justifies throughput investment.
- Digital Imaging:Silicon photomultiplier architectures replace photomultiplier tubes, collapsing the cost-performance tradeoff that governed detector design. Solid-state readout circuits enable sub-3-millimeter resolution without proportional scintillator volume increases.
- 3D Imaging:Tomographic reconstruction algorithms improve contrast-to-noise ratios in SPECT applications.
- Quantitative Imaging:Standardized uptake value metrics enable treatment response tracking across serial examinations.
Hybrid imaging anchors premium tier positioning; digital detector platforms are expanding most quickly as manufacturers reconfigure supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian radiopharmaceutical suppliers ship short-lived isotopes across the Great Lakes corridor to Midwestern hospital networks, while Mexican manufacturing facilities assemble detector components for US-based system integrators.
United States
Oncology precision staging protocols and cardiac perfusion imaging sustain PET-CT and SPECT demand across integrated delivery networks. FDA streamlined 510(k) pathways compress algorithm deployment timelines for iterative reconstruction software. Academic medical centers in Boston and Chicago anchor cyclotron-dependent isotope production, with major health systems in Texas and California unbundling service contracts through group purchasing organizations.
Canada
Toronto and Vancouver hospital systems drive hybrid imaging procurement as provincial health authorities expand PET-MRI platform evaluations. Health Canada and the Canadian Nuclear Safety Commission impose parallel device and radiopharmaceutical compliance requirements that manufacturers navigate for cross-border market access. Nordion (Canada) Inc. operates legacy atomic energy research sites that constrain qualified cyclotron engineer availability for new facility development.
Mexico
Northern border states concentrate maquiladora assembly operations for detector component manufacturing serving US system integrators. COFEPRIS regulatory alignment with FDA standards facilitates component export certification. Mexico City Metro area hospitals upgrade gamma camera installations as public health insurance expansion broadens diagnostic access.
North America Nuclear Imaging Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a consolidated tier dominated by vertically integrated imaging conglomerates and fragmented radiopharmaceutical logistics layers. Three strategic archetypes occupy distinct positions: full-stack system manufacturers with captive crystal sourcing, independent radiopharmaceutical distributors with cold-chain infrastructure, and semiconductor detector specialists supplying subcomponent architectures. Competitive moves concentrate on M&A for cyclotron network expansion and strategic partnerships for silicon photomultiplier technology licensing.
Among diversified health technology conglomerates, GE Healthcare and Siemens Healthineers exemplify the vertically integrated system manufacturer archetype with North American digital PET platform deployments. Cardinal Health Inc. occupies the independent distributor position, anchoring radiopharmaceutical logistics across hospital network cold chains. These three entities represent the dominant competitive vectors shaping procurement committee vendor selection criteria.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Cardinal Health Inc. |
| Koninklijke Philips NV |
| Bracco Imaging SpA |
| Lantheus Medical Imaging Inc. |
| Canon Medical Systems |
| Curium |
| Nordion (Canada) Inc. |
| Others |
Value Network & Pricing Analysis
Cyclotron proximity constraints for fluorine-18 isotope production compress both pricing tier spreads and supply chain geography, forcing premium PET scanner pricing to absorb cold-chain logistics premiums while standard-tier gamma cameras compete on stripped hardware margins.
Pricing Analysis
The technology-generation pricing gap between silicon photomultiplier-based digital PET platforms, conventional photomultiplier-tube systems, and legacy Anger camera configurations structures procurement committee negotiations. Pricing stratifies across premium, standard, and economy tiers where sub-3-millimeter resolution capabilities command research-institution premiums, while cardiac SPECT suites face cost compression from AI-enabled reconstruction software extending hardware lifecycles. Price differentiation rests on lutetium-based crystal sourcing security and FDA 510(k) clearance pedigree. Margins are tightening in the standard tier as third-party nuclear pharmacy operators disintermediate OEM service contracts. Community hospitals in the Midwest exhibit highest price sensitivity; academic medical centers in Boston and Chicago demonstrate lowest.
Supply Chain Analysis
Tariff exposure between the United States and China for silicon photomultiplier readout circuits dominates supply chain risk planning across detector manufacturers. Lutetium yttrium orthosilicate crystal sourcing concentrates in China, Japan, and the United States; silicon photomultiplier fabrication rests on Taiwan and South Korean semiconductor foundries. Single-source vulnerability for lutetium ore refining amplifies cost volatility in premium detector arrays. Distribution runs through Cardinal Health's radiopharmaceutical cold-chain network and independent group purchasing organizations serving Texas and California health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America nuclear imaging market functions as a service-attach opportunity where cyclotron maintenance contracts and AI reconstruction software subscriptions expand recurring revenue faster than scanner hardware replacement cycles.
For Market Incumbents: Build captive cyclotron network moats through strategic site acquisitions near major metropolitan hospital clusters. Siemens Healthineers and GE Healthcare should accelerate silicon photomultiplier supply agreements with Taiwanese foundries to preempt semiconductor allocation constraints. Cardinal Health must defend its cold-chain logistics position against emerging third-party nuclear pharmacy operators capturing preventive maintenance margins previously retained by OEMs. Vertical integration into lutetium crystal sourcing reduces exposure to Chinese export licensing volatility. For New Entrants and Emerging Players: Build out independent service organization capabilities targeting unbundled maintenance contracts at community hospitals in the Midwest and diagnostic centers in Florida. The diagnostic center segment offers lowest competitive density and fastest outpatient migration. Penetrable white space sits in AI-enabled iterative reconstruction software clearing through FDA's streamlined 510(k) pathway with predicate device histories. A software-first go-to-market angle bypasses capital-intensive cyclotron infrastructure requirements while capturing recurring revenue from cardiac perfusion imaging suites. For Investors and Strategic Acquirers: CMS reimbursement coding for theranostic procedures reshapes the acquisition landscape by determining PET-MRI platform throughput viability across hospital networks. Long-term viability favors targets with established cyclotron infrastructure and Health Canada cross-border clearance capabilities. Acquisition archetypes include regional radiopharmaceutical distributors with 100-150 mile isotope distribution radiuses and semiconductor detector specialists supplying silicon photomultiplier subcomponents. The signal to monitor is NRC licensing timeline compression or expansion affecting new facility development economics.| Strategic Initiative | Industry Significance |
|---|---|
| Cyclotron Network Expansion | Proximity to fluorine-18 production facilities constrains radiopharmaceutical distribution radius and site selection. |
| Silicon Photomultiplier Technology Licensing | Photon-counting electronics differentiation separates digital PET resolution performance from conventional architectures. |
| FDA Streamlined 510(k) Submission | Abbreviated review channels compress AI reconstruction software deployment timelines from 18 months to under 9 months. |
| Hospital System Partnership | Integrated delivery network procurement committees unbundle service contracts and source through group purchasing organizations. |
| Reimbursement Strategy Development | CMS coding for theranostic procedures determines capital investment returns on PET-MRI platform acquisitions. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with cyclotron facility engineers, hospital nuclear medicine department heads, biomedical equipment procurement managers, and GPO contracts specialists; and secondary validation against FDA 510(k) clearances, NRC licensing databases, CMS reimbursement coding updates, and hospital capital expenditure disclosures. Bottom-up triangulation across scanner installation records and top-down reconciliation against radiopharmaceutical production volumes anchored market sizing.
Forecast inputs considered product type segmentation across PET scanners, gamma cameras, and SPECT systems; end-user patterns distinguishing academic medical centers from community hospitals and diagnostic centers; application prioritization in oncology staging, cardiac perfusion, and neurology protocols; and technology evolution from hybrid imaging to digital detector platforms. CAGRs were derived through logarithmic interpolation across the projection horizon. Industry-specific inputs included cyclotron facility capacity utilization rates and silicon photomultiplier adoption curves in replacement cycles.
Stress conditions across isotope half-life logistics failure, semiconductor supply allocation constraints, and CMS reimbursement code revisions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about cyclotron engineer availability and Health Canada regulatory alignment trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Dental Imaging Market
Medical Imaging
Global Orthopedic Imaging Equipment Market
Medical Imaging
Global Contrast-Enhanced Ultrasound Market
Medical Imaging
North America Fluoroscopy Market
Medical Imaging
AI-Enabled Diagnostic Imaging Market
Medical Imaging
Germany Digital Radiology Market
Medical Imaging
Imaging Agents Market
Medical Imaging
Europe Digital Radiology Market
Medical Imaging
Radiography-Fluoroscopy Combo System Market
Medical Imaging
Global Medical Imaging Reagents Market
Medical Imaging
Asia Pacific Open System MRI Market
Medical Imaging
Portable Ultrasound Market
Medical Imaging
Radiology As a Service Market
Medical Imaging
Cone Beam Computed Tomography (CBCT) System Market
Medical Imaging
Nuclear Magnetic Resonance Spectroscopy Market
Medical Imaging
Teleultrasound System Market