
 Asia-Pacific Circuit Breakers Market | 2026-2036
Asia-Pacific Circuit Breakers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Circuit Breakers Market Analytics
Data center power distribution is shifting toward higher-capacity, intelligent protection schemes across the Asia-Pacific circuit breakers market. Schneider Electric leverages its digital energy management portfolio to anchor positions in hyperscale facilities. Siemens AG competes through localized manufacturing scale and IEC-compliant product platforms. Mitsubishi Electric Corporation specializes in vacuum interrupter technology for utility-grade installations.
Asia-Pacific circuit breakers are electromechanical or solid-state protective devices designed to interrupt fault currents exceeding rated thresholds, typically operating within milliseconds to prevent thermal damage to conductors and connected equipment. Molded case circuit breakers dominate volume shipments across commercial and light industrial applications, while air circuit breakers command premium positioning in heavy infrastructure and utility switchgear. Intelligent and smart technology segments are expanding fastest as grid operators mandate remote monitoring, predictive maintenance protocols, and arc flash mitigation across transmission and distribution networks.
China's MIIT enforces GB standards for low-voltage switchgear efficiency, while India's CEA mandates centralized grid protection coordination under national power system guidelines. Japan's METI drives METI-ordained JIS certification for earthquake-resistant breaker designs. Stakeholders must weigh standardization divergence against platform economics when allocating R&D across national certification pipelines.
Market Dynamics
Grid digitization mandates across Asia-Pacific are forcing circuit breaker manufacturers to embed IoT sensors and edge computing capabilities into legacy electromechanical platforms, compressing product development cycles and fragmenting certification requirements.
Growth Catalysts
- China's dual carbon goals:MIIT's GB efficiency standards for low-voltage switchgear mandate higher-breaking-capacity designs, pulling demand for intelligent air circuit breakers in utility substations.
- Hyperscale data center buildouts:Cloud infrastructure operators in Singapore, Australia, and Japan require arc-resistant, remotely monitored protection schemes with sub-50ms fault clearance.
- India's renewable integration:CEA grid protection coordination guidelines for solar and wind farms drive vacuum interrupter adoption in 33kV and 66kV collector substations.
Market Restraints
- Copper and silver price volatility:Contact and conductor materials constitute 35-45% of raw material costs, exposing margins to LME commodity swings without pass-through mechanisms in fixed-price utility contracts.
- Japanese supplier concentration:Vacuum interrupter manufacturing clusters in Nagoya and Osaka create single-source dependency for critical arc-quenching components.
- IEC 61850 retrofit friction:Legacy electromechanical breakers in Southeast Asian distribution networks lack digital communication ports, forcing complete switchgear replacement rather than modular upgrades.
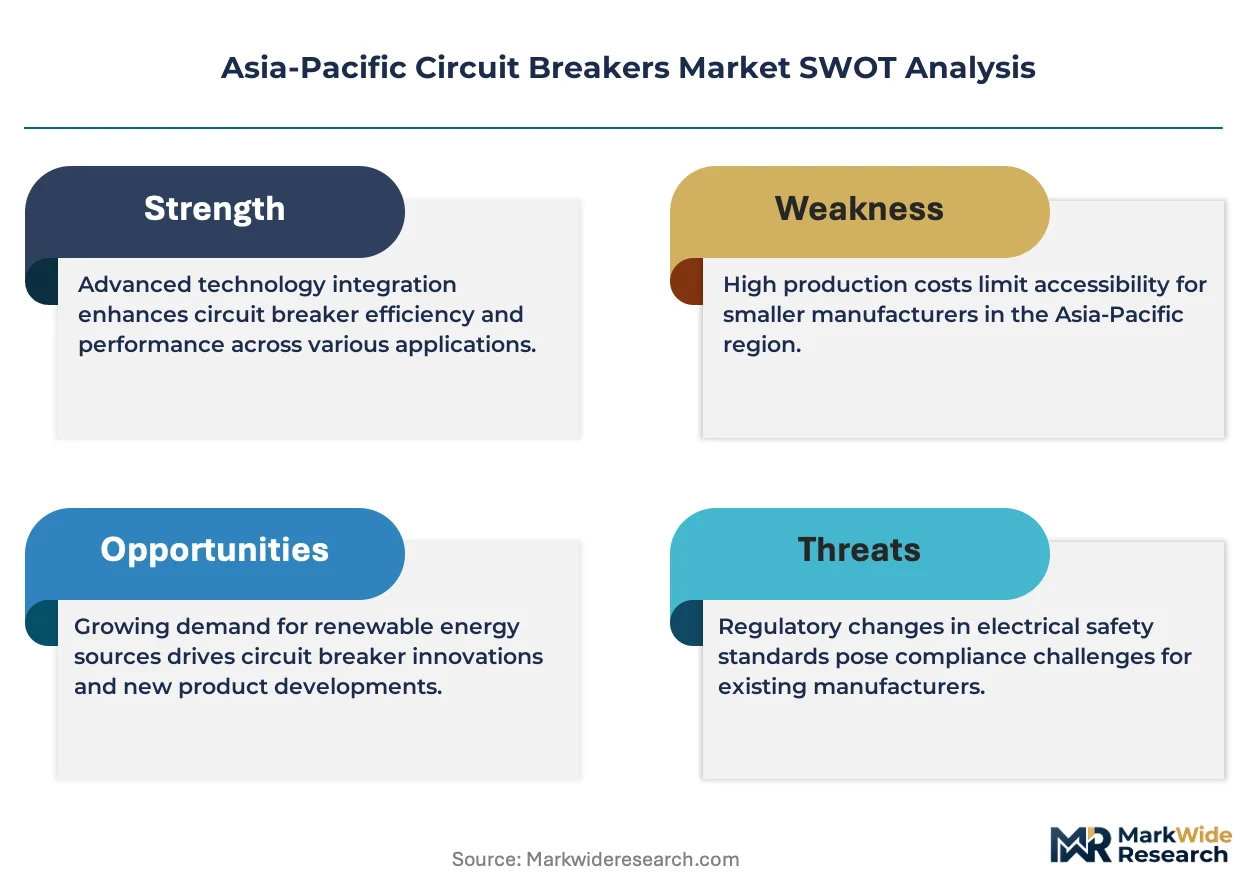
Strategic Opportunities
- Vietnam's industrial corridor expansion:Northern manufacturing zones around Hai Phong and Bac Ninh lack mature electrical infrastructure, creating first-mover advantage for integrated protection-and-monitoring packages.
- Digital twin convergence:Pairing breaker-mounted sensors with predictive analytics platforms enables condition-based maintenance contracts that extend customer lifetime value.
- Japan's earthquake-resilience mandates:METI-ordained JIS certification for seismic-rated designs creates premium positioning for mechanically reinforced product lines in nuclear and critical infrastructure.
Industry Challenges
- Embedded software certification:Functional safety compliance for IEC 61508-2 in intelligent breakers requires specialized firmware validation capabilities scarce among traditional electromechanical engineering teams.
- Multi-standard testing timelines:Simultaneous GB, JIS, BIS, and IEC certification for pan-Asia-Pacific product launches extends time-to-revenue by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Circuit Breakers Market |
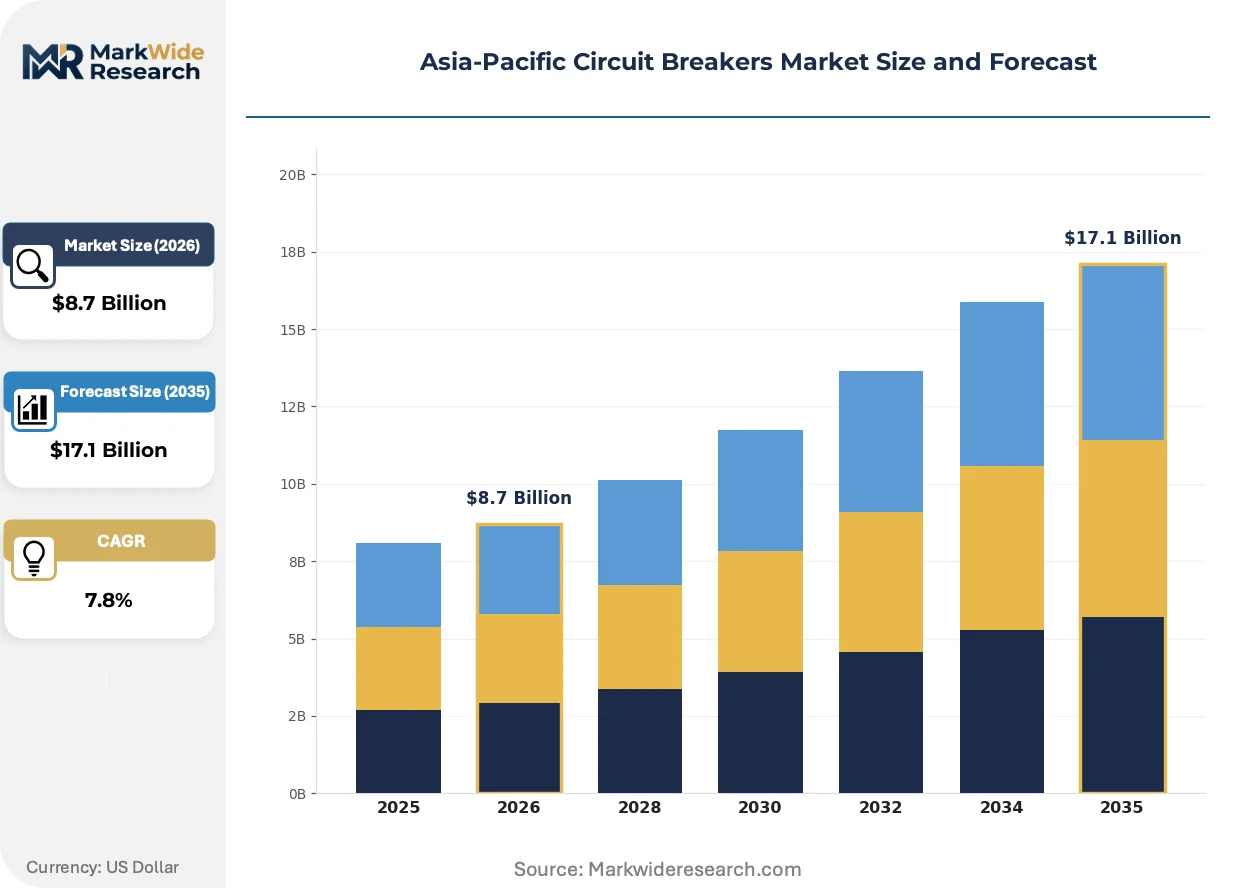
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Miniature Circuit Breakers, Molded Case Circuit Breakers, Air Circuit Breakers, Hydraulic Magnetic Circuit Breakers End User: Residential, Commercial, Industrial, Utilities Installation Type: Indoor, Outdoor, Wall-Mounted, Panel-Mounted Technology: Electromechanical, Digital, Intelligent, Smart |
| Companies Covered | Schneider Electric, Eaton Corporation, Siemens AG, ABB Ltd, Mitsubishi Electric Corporation, Hitachi Ltd, Toshiba Corporation, Fuji Electric, LS Electric, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Circuit Breakers Market Evolving Landscape
Electrification of heavy industry and data center buildouts are compressing protection device lifecycles while elevating performance thresholds. Three interconnected developments are reshaping competitive positioning.
Smart circuit breakers with integrated microprocessor-based trip units are automating fault detection, load profiling, and selective coordination in real-time. Hyperscale data center operators in Singapore and Sydney deploy these systems to eliminate manual breaker resetting during transient faults. The technology is automating the transition from scheduled maintenance to predictive intervention, reducing unplanned downtime in 24/7 facilities.
China's MIIT enforcement of GB/T 7251.12-2013 efficiency tiers for low-voltage switchgear mandates minimum breaking capacity thresholds and energy loss limits. Manufacturers must redesign thermal-magnetic trip mechanisms to meet stricter heat dissipation standards. Domestic producers in Jiangsu and Zhejiang provinces are accelerating vacuum interrupter substitution for air-break technologies to comply.
Asset-light procurement models are displacing traditional capital expenditure approaches among Southeast Asian industrial buyers. Leasing arrangements with bundled maintenance and remote monitoring services now dominate transactions for facilities above 10MVA capacity. This shift is most visible in Thailand's Eastern Economic Corridor, where Japanese automotive transplants favor operational expenditure structures over owned electrical infrastructure.
Asia-Pacific Circuit Breakers Market Segmentation
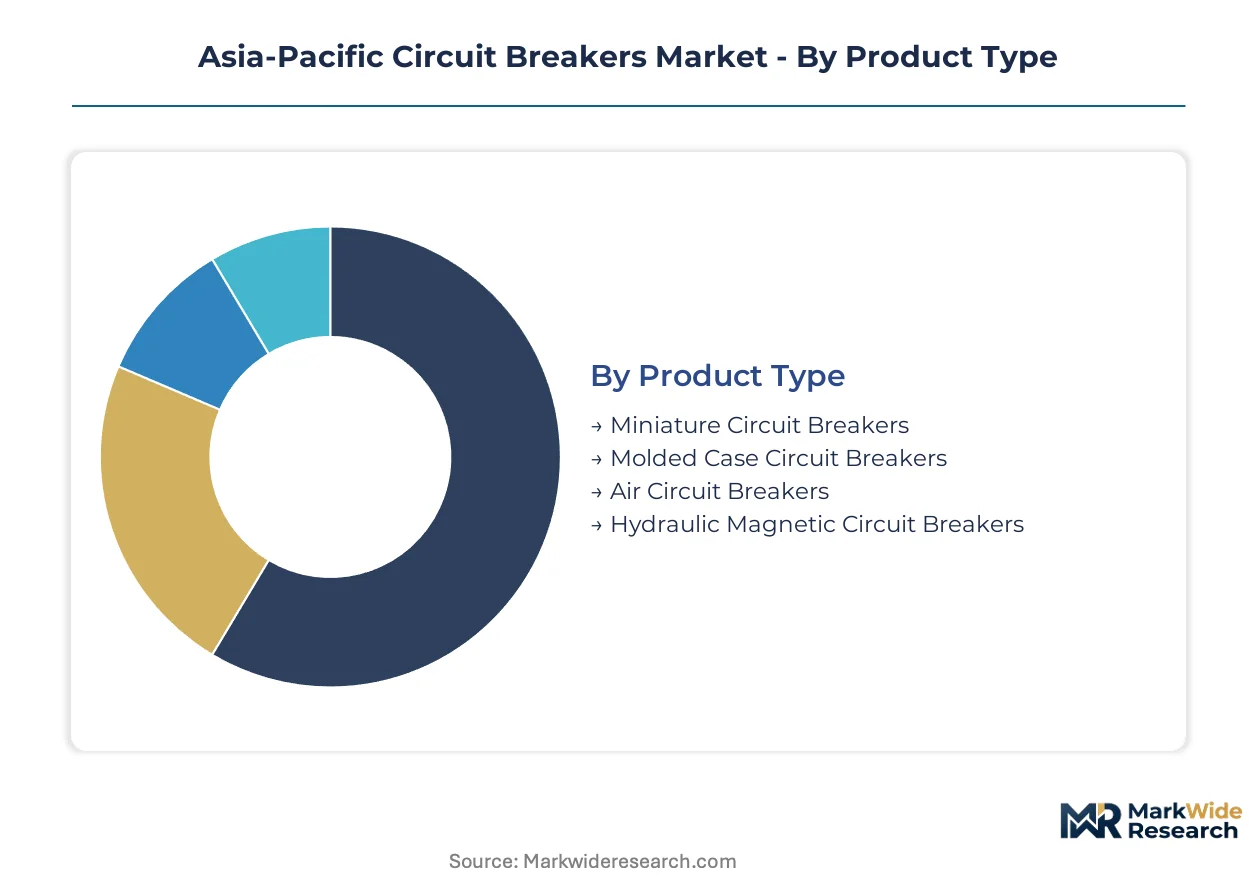
Circuit breaker procurement in Asia-Pacific fragments across protection capacity, deployment environment, and intelligence tier. Certification requirements from MIIT, METI, and BIS create divergent product specifications that reshape segment economics.
Product Type:
MIIT's GB standards enforce breaking-capacity minimums on low-voltage categories, while METI's JIS certification adds seismic-resistance layers for utility-grade equipment.
- Miniature Circuit Breakers:Single-pole and multi-pole units rated below 125A dominate residential distribution boards across India's urban corridor expansion. BIS certification timelines for these compact units run shorter than industrial grades, accelerating supplier rotation in price-sensitive segments.
- Molded Case Circuit Breakers:Thermoset plastic enclosures house thermal-magnetic trip mechanisms rated 15A to 1600A. Commercial buildouts in Vietnam's Hai Phong manufacturing zone and Thailand's Eastern Economic Corridor concentrate demand for IEC 60947-2 compliant MCCB platforms with adjustable trip settings.
- Air Circuit Breakers:Open-architecture designs with draw-out mechanisms serve 800A to 6300A applications in Chinese utility substations modernizing under dual carbon mandates.
- Hydraulic Magnetic Circuit Breakers:Temperature-stable solenoid designs meet MIL-spec and marine applications in Singapore's port infrastructure and Australian offshore installations.
Molded case units sit at the top of the volume ranking, with air circuit breakers climbing the fastest on grid modernization pull.
End User:
Customer procurement scale determines service bundling potential, with utilities and hyperscale data centers commanding predictive maintenance contracts unavailable to residential channels.
- Residential:Single-phase miniature breakers in 6kA to 10kA breaking capacities serve apartment distribution panels across China's tier-2 city expansion and India's PMAY housing schemes.
- Commercial:Office towers and retail complexes in Sydney, Singapore, and Tokyo specify selective coordination between MCCB tiers to minimize outage propagation during transient faults.
- Industrial:Heavy manufacturing in Jiangsu province and automotive transplants in Thailand's Eastern Economic Corridor demand arc-flash-rated air circuit breakers with zone-selective interlocking.
- Utilities:State Grid Corporation of China and Power Grid Corporation of India mandate intelligent air circuit breakers with IEC 61850 communication for remote substation operation.
Industrial offtake leads absolute volume, with utilities expanding most quickly on renewable integration mandates.
Installation Type:
Environmental exposure ratings and enclosure IP codes segment manufacturing cost structures, with outdoor specifications requiring corrosion-resistant alloys that elevate material bills.
- Indoor:Flush-mounted distribution panels in climate-controlled data centers and commercial buildings specify standard IP40 enclosures without weatherproofing premiums.
- Outdoor:Pad-mounted and pole-top installations across Australia's mining corridors and Indonesia's island grids require IP65-rated sealing against humidity and particulate ingress.
- Wall-Mounted:Surface distribution boards dominate residential retrofits in Japan's dense urban housing and India's informal construction sector.
- Panel-Mounted:Draw-out chassis designs in Chinese and Indian utility switchgear enable hot-swappable maintenance without busbar de-energization.
Indoor configurations anchor volume shipments, with outdoor specifications gaining share fastest on rural electrification programs.
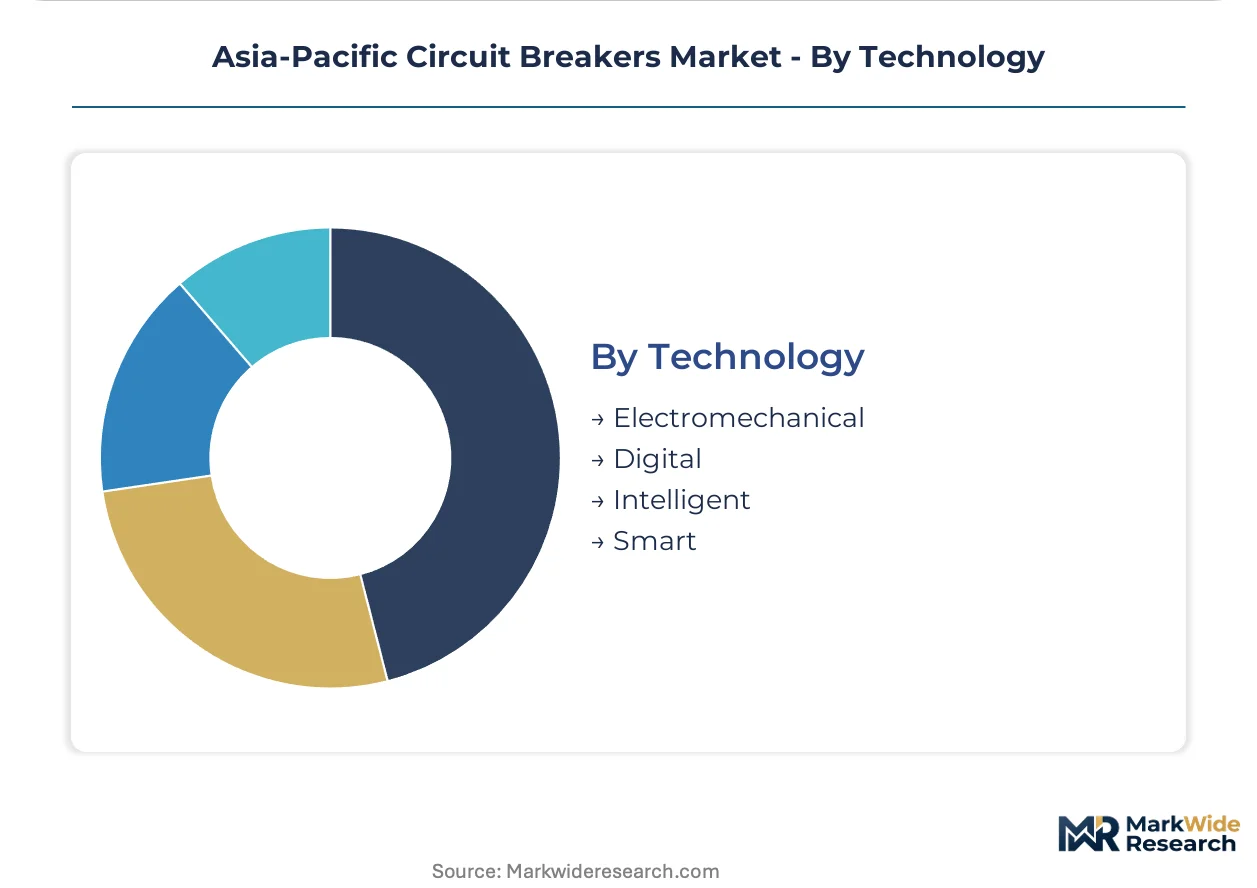
Technology:
Embedded software validation burdens concentrate in intelligent and smart tiers, where IEC 61508-2 functional safety compliance extends firmware development cycles.
- Electromechanical:Bimetallic thermal elements and magnetic solenoids constitute the legacy installed base across Southeast Asian distribution networks lacking capital for digital retrofit.
- Digital:Microprocessor-based trip units with LCD displays enable field-adjustable protection curves in commercial and light industrial applications.
- Intelligent:Breakers with embedded sensors and Modbus communication automate fault logging and selective coordination in hyperscale data centers across Singapore and Sydney.
- Smart:Edge-computing platforms with predictive analytics integration enable condition-based maintenance contracts for utilities and critical infrastructure operators.
Electromechanical units retain volume leadership, with smart technology ascending fastest on asset-light procurement model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu province's electrical equipment manufacturing belt anchors regional circuit breaker demand through State Grid Corporation substation modernization and data center power distribution buildouts.
China
Dual carbon mandates from MIIT accelerate vacuum interrupter substitution in 800A to 6300A utility switchgear across Jiangsu and Zhejiang manufacturing zones. GB/T 7251.12-2013 efficiency tiers force thermal-magnetic redesigns. Shanghai and Beijing hyperscale data centers specify intelligent air circuit breakers with sub-50ms fault clearance.
India
CEA grid protection coordination guidelines drive vacuum interrupter adoption in 33kV and 66kV solar collector substations. BIS certification timelines compress for miniature breakers serving PMAY housing schemes. Gujarat and Maharashtra industrial corridors demand arc-flash-rated molded case platforms with zone-selective interlocking.
Japan
METI-ordained JIS certification for seismic-resistant breaker designs creates premium positioning in nuclear and critical infrastructure. Kanto and Kansai data center operators deploy smart breakers with predictive analytics integration. Nagoya and Osaka vacuum interrupter clusters concentrate arc-quenching component supply.
Australia
Mining corridor electrification and Sydney hyperscale facility buildouts pull intelligent protection schemes with IEC 61850 communication. Queensland and Western Australia outdoor installations require IP65-rated sealing against humidity and particulate ingress. TGA-equivalent electrical safety standards govern commercial and industrial procurement.
Vietnam
Northern manufacturing zones around Hai Phong and Bac Ninh lack mature electrical infrastructure, creating first-mover advantage for integrated protection-and-monitoring packages. Ministry of Industry and Trade grid expansion programs target 99% electrification coverage. Thai Nguyen and Vinh Phuc provinces concentrate Japanese and Korean automotive transplant demand.
Asia-Pacific Circuit Breakers Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers localize production to circumvent multi-standard certification bottlenecks. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with digital energy portfolios, specialized vacuum interrupter manufacturers with utility-grade expertise, and regional electrical equipment specialists serving price-sensitive construction markets. Geographic expansion and technology licensing represent the dominant competitive moves, with players establishing captive certification pipelines in China, India, and Southeast Asia to compress 14-18 month approval timelines.
Among French-based industrial conglomerates, Schneider Electric exemplifies the diversified archetype with digital energy management positioning. Siemens AG represents German engineering fabricators competing through localized manufacturing scale. Mitsubishi Electric Corporation anchors the specialized tier with vacuum interrupter technology concentration for utility installations.
| Leading Market Players |
|---|
| Schneider Electric |
| Eaton Corporation |
| Siemens AG |
| ABB Ltd |
| Mitsubishi Electric Corporation |
| Hitachi Ltd |
| Toshiba Corporation |
| Fuji Electric |
| LS Electric |
| Others |
Value Network & Pricing Analysis
State Grid Corporation and Power Grid Corporation of India procurement contracts anchor pricing discipline through long-term offtake structures, while Japanese vacuum interrupter specialists command premium positioning via METI-certified seismic resilience. Copper and silver contact material costs transmit directly into utility contract renegotiation cycles, compressing margins for manufacturers lacking backward integration into conductor supply.
Pricing Analysis
Distributor margins in Southeast Asian construction channels absorb 18-25 point spreads before project-based pricing reaches end-users, while direct-to-OEM arrangements for data center operators compress intermediary layers. Three-tier pricing structure across intelligent, digital, and electromechanical tiers separates premium IEC 61850-compliant platforms from standard thermal-magnetic units. Cost compression in residential miniature breakers intensifies because BIS certification acceleration in India pulls price-sensitive suppliers into rotating low-bid competitions. Data center operators exhibit lowest price sensitivity, prioritizing sub-50ms fault clearance and predictive maintenance bundling over unit economics.
Supply Chain Analysis
Container freight volatility from Nagoya and Osaka vacuum interrupter clusters to Southeast Asian assembly plants elevates landed costs for arc-quenching components. Manufacturing gravity centers on China for molded case platforms, Japan for vacuum interrupter technology, and South Korea for digital trip unit semiconductors. Raw material dependencies span Chilean copper cathode, Australian silver concentrate, and Chinese rare earth magnets for sensor arrays. Single-source vulnerability concentrates in Japanese vacuum interrupter supply for utility-grade installations. Distribution runs through electrical equipment distributors in Hai Phong and Bac Ninh for Vietnam's industrial corridor expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MIIT's GB efficiency enforcement in Jiangsu province operates on faster timelines than India's CEA coordination mandates, creating 8-12 month certification arbitrage windows for manufacturers with dual-approval capabilities.
For Market Incumbents: To counter IEC 61850 retrofit friction in Southeast Asian legacy networks, Schneider Electric and Mitsubishi Electric should accelerate captive certification pipelines in India and Vietnam to compress 14-18 month approval timelines. Backward integration into copper contact manufacturing insulates margins against LME commodity swings in fixed-price State Grid contracts. R&D allocation toward embedded software validation capabilities addresses IEC 61508-2 functional safety scarcity among traditional electromechanical engineering teams. For New Entrants and Emerging Players: The 40-60% price-point gap between premium intelligent breakers and economy electromechanical units opens white-space targeting in Vietnam's Hai Phong manufacturing zone and Thailand's Eastern Economic Corridor. Asset-light procurement model adoption among Japanese automotive transplants creates service-bundling entry angles unavailable in capital-expenditure-dominant segments. Leasing arrangements with predictive maintenance contracts represent the most penetrable go-to-market structure for facilities above 10MVA capacity. For Investors and Strategic Acquirers: Valuations sit cheapest among regional electrical equipment specialists serving price-sensitive Indian construction markets, relative to diversified conglomerates with digital energy portfolios. Five-to-ten year viability hinges on vacuum interrupter technology concentration and multi-standard certification infrastructure. Acquisition targets should demonstrate captive pipelines in China, India, and Southeast Asia. The signal to watch is MIIT enforcement acceleration for GB/T 7251.12-2013 efficiency tiers, which would force thermal-magnetic redesign investments and consolidate supplier tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Standard Certification Pipeline | Captive GB, JIS, BIS, and IEC testing compresses 14-18 month approval timelines for pan-Asia-Pacific launches. |
| Backward Integration into Contact Materials | In-house copper and silver conductor production insulates margins against LME commodity volatility in fixed-price utility contracts. |
| Embedded Software Validation Capability | IEC 61508-2 functional safety compliance addresses firmware expertise scarcity among electromechanical engineering teams. |
| Asset-Light Service Bundling | Leasing with predictive maintenance contracts captures operational expenditure shift in Thailand's Eastern Economic Corridor. |
| Seismic-Resistant Product Line Investment | METI-ordained JIS certification creates premium positioning in Japan's nuclear and critical infrastructure procurement. |
Research Methodology
Bottom-up utility and data center demand modeling reconciled against top-down vacuum interrupter and contact material supply tracking forms the analytical core of this study. Primary interviews with substation planning officers at State Grid Corporation, procurement leads at hyperscale data center operators in Singapore and Sydney, plant managers at Jiangsu electrical equipment manufacturers, and aftermarket service heads at Japanese vacuum interrupter specialists combined with secondary validation. Secondary sources span MIIT GB standard filings, CEA grid protection coordination guidelines, METI JIS certification databases, customs trade data for copper and silver imports, and SEC 10-K disclosures from listed electrical equipment conglomerates. Triangulation between installation volume estimates and component shipment data grounds market sizing.
Input-output matrices map breaker capacity tiers against end-use segments across the projection horizon. Segmentation dimensions span product type, installation environment, intelligence tier, and national regulatory cluster. CAGRs derive from regression analysis of historical procurement patterns against policy mandate timelines. Industry-specific forecast inputs include State Grid Corporation substation modernization capex disclosures and hyperscale data center power distribution buildout announcements from cloud infrastructure operators.
Caveats apply where copper and silver price volatility, Japanese vacuum interrupter supply disruption, or multi-standard certification timeline extensions could materially shift the outlook. Forecasts reflect assumptions about MIIT enforcement consistency, CEA coordination guideline adoption rates, and asset-light procurement model penetration. A model refresh is warranted upon material change in China's dual carbon policy trajectory or India's renewable integration mandate acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
High Voltage Insulator Market
Electrical Equipment
Soft Starter Market
Electrical Equipment
High Voltage Commercial Switchgear Market
Electrical Equipment
Wire Splicing Kits Market
Electrical Equipment
Consumer Electronics High Voltage Electric Capacitor Market
Electrical Equipment
Electrical Label Market
Electrical Equipment
Portable Misting Fans Market
Electrical Equipment
PDU Power Cords Market
Electrical Equipment
Electrical Steel Coatings Market
Electrical Equipment
Ground Fault Circuit Interrupter Market
Electrical Equipment
Global EMC Filtration Market
Electrical Equipment
Global Busbar Market
Electrical Equipment
Electrical Bushings Market
Electrical Equipment
DC Contactor Market
Electrical Equipment
Electrical Isolator Market
Electrical Equipment
Electric Motors for Conveyor System Market