
 Modular Contactor Market | 2026-2036
Modular Contactor Market Size, Share, and Industry Trends Forecast 2026-2036
Modular Contactor Market Foresight
China is fragmenting as domestic manufacturers expand electromechanical contactor capacity to serve Asia-Pacific industrial automation demand. Schneider Electric leverages its TeSys product architecture and extensive distributor network to sustain premium positioning across European infrastructure projects. ABB anchors its competitive stance through integrated control-distribution portfolios that combine modular contactors with variable speed drives. Siemens differentiates via digital twin compatibility and IoT-enabled predictive maintenance interfaces embedded in its 3RT series.
A modular contactor is an electromechanical switching device designed for DIN-rail mounting, typically rated between 9 A and 100 A, that controls motor loads, heating circuits, and lighting systems through remote electrical actuation of its main contacts. The device employs silver-nickel or silver-cadmium oxide contact materials to withstand repeated make-break cycles under inductive loads, with mechanical lifespans exceeding ten million operations in premium specifications. Electromechanical technology still commands the largest installed base due to proven durability and lower unit costs, though solid-state variants are gaining share in applications demanding millions of cycle operations without mechanical wear. Motor starters represent the most margin-rich product category because they integrate overload protection and short-circuit coordination, reducing panel complexity for OEM customers.
IEC 60947-4-1 governs contactor performance and coordination requirements across European markets, while UL 508 shapes North American product certification and panel builder acceptance. China's GB 14048.4 standard mandates specific breaking capacity tests that foreign suppliers must complete through SAMR-recognized laboratories. The EU Ecodesign Directive and F-Gas Regulation indirectly steer demand toward contactors paired with energy-efficient motor systems. Stakeholders must monitor how IEC standard revision timelines and regional energy efficiency mandates alter replacement specifications before committing to next-generation platform investments.
Market Dynamics
Data center power distribution retrofits are compressing replacement cycles as hyperscale operators prioritize energy density and remote monitoring compatibility over mechanical longevity.
Growth Catalysts
- Hyperscale facility construction:Cloud providers in Germany and the Netherlands are specifying IEC 60947-4-1 certified modular contactors for redundant busbar configurations in 100+ MW campuses.
- EU F-Gas Regulation:Phase-down schedules for fluorinated greenhouse gases are accelerating motor system upgrades that bundle contactors with variable speed drives to reduce refrigerant leakage risks.
- Silver-cadmium oxide contact materials:Premium electromechanical specifications now achieve mechanical lifespans exceeding ten million operations, sustaining demand in heavy-cycling heating and ventilation applications.
Market Restraints
- Raw material volatility:Silver price fluctuations directly compress margins for contact manufacturers dependent on silver-nickel and silver-cadmium oxide formulations.
- Domestic capacity expansion in China:Local electromechanical contactor producers are capturing Asia-Pacific industrial automation demand through GB 14048.4 certification, fragmenting export opportunities for established suppliers.
- Solid-state substitution:Silicon-controlled rectifier and IGBT-based switching modules are displacing electromechanical units in applications demanding millions of operations without contact wear.
Strategic Opportunities
- India industrial corridors:PLI scheme incentives for domestic manufacturing are creating localized assembly demand for DIN-rail mounted motor control devices in Gujarat and Tamil Nadu.
- Digital twin integration:Convergence of modular contactor hardware with IoT-enabled predictive maintenance interfaces is opening premium pricing tiers for infrastructure OEMs.
- Energy-efficient motor mandates:EU Ecodesign Directive tiered efficiency requirements are forcing replacement of legacy magnetic starters with integrated contactor-overload combinations.
Industry Challenges
- SAMR laboratory accreditation:Foreign suppliers face extended certification timelines for China's GB 14048.4 breaking capacity tests, delaying market entry by 12-18 months.
- Legacy panel compatibility:Retrofit projects require mechanical and electrical coordination with existing thermal overload relays, complicating specification engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modular Contactor Market |
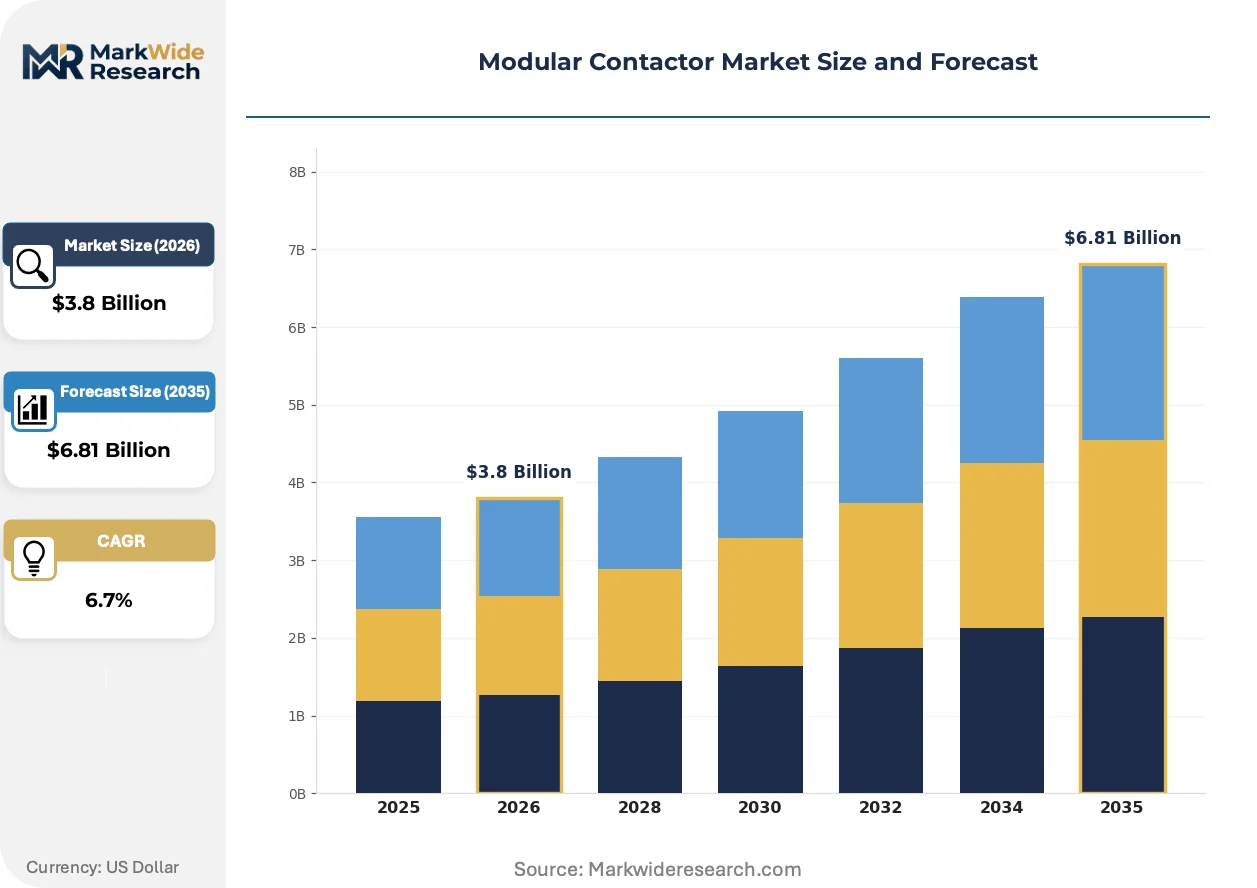
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Miniature Contactors, Motor Starters, Relay Modules, Universal Contactors Technology: Electromechanical, Solid State, Programmable, Dual Function End User: Manufacturing, Building Automation, Renewable Energy, Transportation Solution: Control Solutions, Safety Systems, Automation Systems, Distribution Solutions |
| Companies Covered | Schneider Electric, ABB, Siemens, Eaton, Legrand, Mitsubishi Electric, LS Electric, Fuji Electric, Lovato Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modular Contactor Market Shifts & Advancements
Virtualization of switching functions and predictive maintenance architectures are redefining how panel builders specify motor control components, compressing the boundary between hardware and software-defined power distribution.
Digital twin software is virtualizing contactor performance modeling before physical deployment. System integrators in Germany are adopting Siemens 3RT series compatibility layers to simulate arc quenching behavior and predict maintenance windows. This capability is virtualizing traditional specification workflows that previously relied on empirical safety margins.
REACH substance restrictions are forcing contact material transitions across European supply chains. ECHA scrutiny of cadmium compounds is accelerating silver-tin oxide and silver-graphite formulations in new product platforms. Motor starter manufacturers serving German automotive OEMs are reformulating contact stacks to maintain CE marking compliance under evolving substance thresholds.
Certification-driven procurement is consolidating supplier relationships among North American panel builders. UL 508 Type E self-protected combination ratings are becoming mandatory for food processing and pharmaceutical facilities governed by FDA sanitary equipment standards. Distributors report that contractors in Wisconsin and Pennsylvania are narrowing approved vendor lists to three brands with pre-validated short-circuit coordination tables.
Modular Contactor Market Segmentation
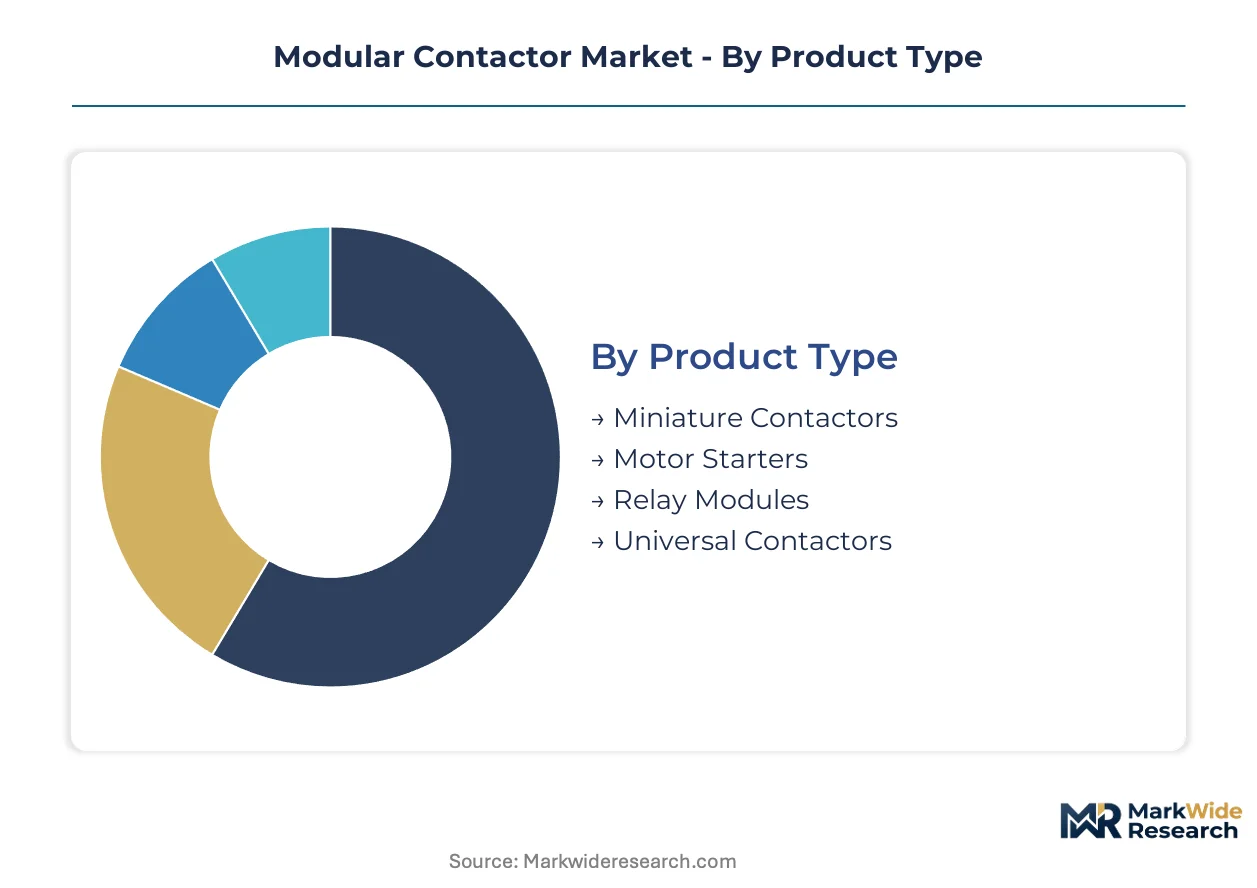
Segmentation in the modular contactor market reveals how service intensity, technical complexity, and regulatory exposure vary across product architectures. Understanding these fault lines helps suppliers calibrate inventory depth, field engineering resources, and certification investments to where margin concentration actually occurs.
Product Type:
After-sales service intensity diverges sharply across product types, with integrated motor starters demanding ongoing calibration support while miniature contactors operate largely maintenance-free.
- Motor Starters:These units combine overload protection, short-circuit coordination, and contactor switching in a single DIN-rail enclosure. Demand concentrates in German automotive OEM panel shops where IEC 60947-4-1 coordination tables reduce engineering liability for system integrators.
- Miniature Contactors:Rated 9-25 A, these devices serve lighting and HVAC control circuits through compact 17.5mm or 22.5mm widths. Building automation retrofits in the Netherlands specify these for space-constrained distribution boards where every millimeter of rail space carries cost implications.
- Relay Modules:Interface-level switching devices for PLC output isolation and signal conditioning.
- Universal Contactors:Modular platforms accepting auxiliary contact blocks and mechanical interlocks across multiple frame sizes.
By volume, Miniature Contactors leads. By growth pace, Motor Starters is ahead.
Technology:
Cost tier stratification separates electromechanical workhorses from solid-state premium offerings, with programmable variants capturing mid-market specification flexibility.
- Electromechanical:Silver-nickel or silver-cadmium oxide contacts deliver mechanical lifespans exceeding ten million operations. Manufacturing plants in Bavaria specify these for motor control reliability where downtime costs dwarf incremental efficiency gains from solid-state alternatives.
- Solid State:Silicon-controlled rectifier and IGBT-based switching eliminates contact wear for heating applications demanding millions of cycles. Data center operators in Frankfurt specify these for redundant busbar configurations where silent operation and zero arc energy reduce fire suppression system complexity.
- Programmable:Microprocessor-based units with configurable timing, latching logic, and communication interfaces.
- Dual Function:Hybrid architectures combining electromechanical main contacts with solid-state pre-charge or arc suppression circuits.
By installed base, Electromechanical dominates. By specification momentum, Solid State is climbing the fastest.
End User:
Application maturity determines whether procurement prioritizes proven durability or digital integration capabilities.
- Manufacturing:Automotive stamping lines and packaging machinery drive demand for IEC 60947-4-1 certified motor control with predictable maintenance windows.
- Building Automation:HVAC and lighting control systems specify DIN-rail contactors for centralized energy management.
- Renewable Energy:Solar inverter manufacturers and wind turbine nacelle builders require DC-rated contactors with extended temperature ranges.
- Transportation:Railway rolling stock and electric vehicle charging infrastructure specify shock-resistant contactor modules.
By revenue concentration, Manufacturing leads. By expansion trajectory, Renewable Energy is gaining share fastest.
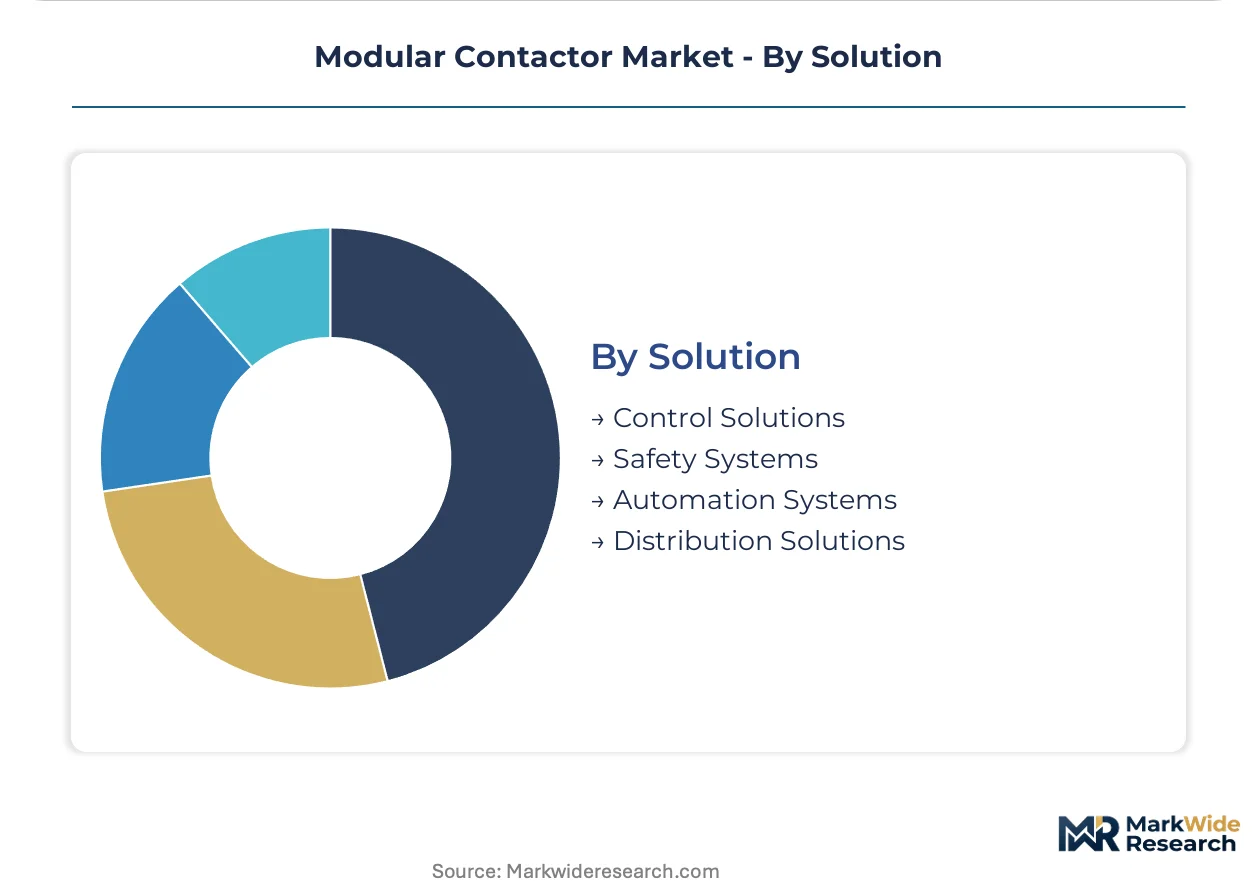
Solution:
Customer type segmentation separates specification influencers from purchasing decision-makers across the value chain.
- Control Solutions:Motor starting, reversing, and speed control architectures for machinery OEMs.
- Safety Systems:Contactors with positively-driven auxiliary contacts for emergency stop and guard door interlock circuits.
- Automation Systems:Fieldbus-integrated contactors with embedded IO-Link or Profinet interfaces for predictive maintenance architectures.
- Distribution Solutions:Panel builder-focused offerings with pre-engineered busbar adapters and coordinated short-circuit protection.
By project volume, Distribution Solutions leads. By margin expansion, Automation Systems is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Germany's centrality in European industrial automation supply chains, while the Pearl River Delta container port cluster anchors China's electromechanical component export capacity.
Germany
Automotive OEM panel shops in Stuttgart and Munich drive demand for IEC 60947-4-1 certified motor starters with coordinated short-circuit protection. The EU F-Gas Regulation accelerates retrofits of refrigeration compressors bundled with energy-efficient contactor-overload combinations. Bavarian manufacturing plants specify electromechanical units with ten-million-cycle lifespans for stamping line reliability.
China
Domestic electromechanical contactor manufacturers expand capacity to serve Asia-Pacific industrial automation through GB 14048.4 certification pathways. SAMR laboratory accreditation requirements extend foreign supplier market entry timelines by 12-18 months. Yangtze River Delta factory automation clusters absorb locally-produced DIN-rail motor control devices for textile and packaging machinery.
United States
Data center power distribution retrofits in Northern Virginia and Dallas-Fort Worth specify solid-state contactors for redundant busbar configurations in hyperscale campuses. UL 508 Type E self-protected combination ratings become mandatory for FDA-governed food processing facilities in Wisconsin and Pennsylvania. Midwest panel builders consolidate approved vendor lists to three pre-validated brands with coordinated short-circuit tables.
India
PLI scheme incentives for domestic manufacturing create localized assembly demand for motor control devices in Gujarat and Tamil Nadu industrial corridors. Bureau of Indian Standards certification requirements shape procurement specifications for DIN-rail mounted contactors in building automation retrofits. Maharashtra automotive component suppliers specify IEC-compliant motor starters for robotic welding line upgrades.
Netherlands
Cloud providers specify IEC 60947-4-1 certified modular contactors for 100+ MW hyperscale facility construction in Amsterdam and Eindhoven regions. REACH substance restrictions accelerate silver-tin oxide contact material transitions in European supply chains. Randstad building automation integrators deploy miniature contactors in space-constrained HVAC distribution boards.
Modular Contactor Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower portfolios but deeper specification engineering relationships. The vendor base stratifies across three tiers: diversified electrical conglomerates with integrated control-distribution portfolios, mid-cap contactor-focused manufacturers with regional certification depth, and emerging domestic producers in Asia-Pacific leveraging cost-positioned electromechanical platforms. Dominant competitive moves include backward integration into silver-alloy contact material production and technology licensing partnerships for solid-state switching architectures.
Within the diversified conglomerate tier, Schneider Electric, ABB, and Siemens occupy positions defined by platform breadth rather than component specialization. Schneider Electric exemplifies the distributor-network-dependent archetype through its TeSys product architecture. ABB anchors the integrated portfolio approach combining modular contactors with variable speed drives. Siemens represents the digitalization-forward positioning through IoT-enabled predictive maintenance interfaces embedded in its 3RT series.
| Leading Market Players |
|---|
| Schneider Electric |
| ABB |
| Siemens |
| Eaton |
| Legrand |
| Mitsubishi Electric |
| LS Electric |
| Fuji Electric |
| Lovato Electric |
| Others |
Supply & Pricing Matrix
Silver-alloy contact material production concentrates in Chinese and German metallurgical facilities, anchoring margin pools in electromechanical contactor tiers where raw material costs comprise the dominant cost stack. Panel builders in Wisconsin and Bavaria face asymmetric pricing power against these upstream concentrations, compressing procurement leverage for standard-grade DIN-rail devices.
Pricing Analysis
IEC 60947-4-1 certification tiering dictates the pricing tier structure across European procurement channels. Three-tier pricing structure across premium, standard, and economy levels separates IoT-enabled predictive maintenance units from basic electromechanical specifications. Price differentiation rests on silver-cadmium oxide contact grade and UL 508 Type E self-protected combination ratings. Cost compression in economy-tier miniature contactors is intensifying because Chinese domestic manufacturers expand GB 14048.4 certified capacity. Food processing OEMs in FDA-governed facilities show least price sensitivity; building automation retrofit contractors exhibit highest.
Supply Chain Analysis
Contract manufacturing capacity for electromechanical contactor assembly concentrates with Foxconn Industrial Internet, Jabil, and regional European EMS providers in Czech Republic and Romania. Silver-nickel and silver-cadmium oxide contact materials draw from Chinese and German metallurgical suppliers; copper busbar components source from Chilean and Zambian mining operations. Single-source vulnerability in SAMR-recognized laboratory accreditation for GB 14048.4 testing extends foreign supplier lead times. Distribution runs through authorized electrical distributor networks with pre-validated short-circuit coordination tables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward hyperscale data center operators consolidating vendor relationships across 100+ MW campuses, fragmenting specification influence among traditional panel builders.
For Market Incumbents: Pre-empt solid-state substitution in heating and ventilation applications by accelerating dual-function hybrid architectures that combine electromechanical reliability with silicon-controlled rectifier cycle endurance. Deepen backward integration into silver-tin oxide contact material production to offset REACH substance restriction compliance costs. Lock in UL 508 Type E pre-validation partnerships with Wisconsin and Pennsylvania distributors before certification-driven procurement narrows approved vendor lists further. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, where GB 14048.4 certification barriers are lower and DIN-rail space constraints favor compact 17.5mm miniature contactor formats. Target India's Gujarat and Tamil Nadu industrial corridors under PLI scheme incentives, where localized assembly partnerships circumvent BIS certification delays. Lead with fieldbus-integrated automation systems featuring IO-Link compatibility to bypass incumbent distributor channel control. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European mid-cap contactor specialists holding deep IEC 60947-4-1 certification libraries but limited digital twin integration capabilities. Five-to-ten year viability hinges on successful platform transitions from electromechanical to solid-state architectures. Monitor SAMR laboratory accreditation queue lengths as inflection indicator for Chinese market entry feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contact Materials | Captive silver-alloy production insulates margins from ECHA REACH cadmium restrictions. |
| Digital Twin Platform Integration | Siemens 3RT compatibility layers virtualize arc quenching for German automotive OEMs. |
| GB 14048.4 Certification Investment | SAMR-recognized laboratory access unlocks Yangtze River Delta factory automation clusters. |
| IoT-Enabled Predictive Maintenance Interface | Embedded Profinet connectivity commands premium pricing from infrastructure OEMs. |
| Regional Assembly Partnership | PLI scheme leveraging in Gujarat reduces BIS compliance timelines for motor starter production. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant engineers, OEM procurement teams, electrical distributor category managers, and aftermarket service heads; and secondary validation through IEC 60947-4-1 certification databases, UL 508 listing directories, SAMR accreditation records, SEC 10-K filings from listed electrical conglomerates, and customs trade data for silver-alloy contact material flows. Bottom-up unit economics triangulated against top-down market sizing across electromechanical, solid-state, and programmable technology tiers.
Forecast inputs span product type segmentation by motor starter, miniature contactor, relay module, and universal contactor architectures; technology tier stratification; end-use intensity across manufacturing, building automation, renewable energy, and transportation; and solution complexity from distribution-focused to automation-integrated offerings. CAGRs were derived from installed base replacement cycle analysis and specification momentum tracking. Hyperscale data center capex disclosures and EU F-Gas Regulation phase-down schedules informed demand elasticity assumptions.
Macroeconomic conditions sit as an overlay; deviation in silver price volatility, industrial automation capital expenditure cycles, or cloud infrastructure investment trajectories would shift the trajectory. Quarterly review of SAMR laboratory queue lengths, REACH substance restriction amendment timelines, and hyperscale facility construction permit filings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Global Panelboards Market
Electrical Equipment
Electric Control Panel Market
Electrical Equipment
Insulator Market
Electrical Equipment
GCC Ceiling Fan Market
Electrical Equipment
High Voltage Circuit Breaker Market
Electrical Equipment
High-Speed Busbar Transfer Devices Market
Electrical Equipment
US Electric Enclosure Market
Electrical Equipment
Surface Mounting Distribution Panel Market
Electrical Equipment
High Voltage Electric Heater Market
Electrical Equipment
United Kingdom Thermal Protector Market
Electrical Equipment
Global Dehydrating Breather Market
Electrical Equipment
Earth Leakage Circuit Breakers Market
Electrical Equipment
Vacuum Interrupter Market
Electrical Equipment
Electrical Sub Panels Market
Electrical Equipment
Ceiling Fans Market
Electrical Equipment
Wire Splicing Kits Market