
 Asia-Pacific High Voltage Switchgear Market | 2026-2036
Asia-Pacific High Voltage Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific High Voltage Switchgear Market Insights
Digital substation architecture is reconfiguring how protection and control systems integrate with primary switchgear across Asia-Pacific grids. Hitachi Energy Ltd leverages its software-defined protection platforms to anchor premium positioning in digital switchgear deployments. Siemens AG sustains manufacturing scale across German-engineered and locally assembled product lines. Mitsubishi Electric Corporation dominates gas-insulated switchgear supply to Japanese utilities and export markets.
Asia-Pacific high voltage switchgear encompasses electrical apparatus rated above 36 kV designed to interrupt, isolate, and protect power circuits using sulfur hexafluoride, vacuum, or air as dielectric media, with primary purpose of ensuring grid stability and personnel safety in transmission networks. Gas-insulated switchgear commands the dominant share due to compact footprint requirements in dense urban substations across Tokyo, Seoul, and Shanghai. Smart switchgear represents the fastest-expanding technology segment as utilities embed sensors and edge computing for predictive maintenance and real-time load balancing. Air-insulated variants retain cost competitiveness in rural and mining applications where space constraints are minimal.
China's MEE enforces SF6 emission monitoring and phased reduction protocols that are redirecting R&D investment toward vacuum interrupter alternatives and sealed-pressure GIS designs. India's CEA mandates centralized testing and certification through NABL-accredited laboratories, creating compliance barriers for imported equipment. Japan's METI promotes IEC 61850 interoperability standards that shape procurement specifications across ASEAN utility tenders. Stakeholders must monitor how divergent national efficiency benchmarks and localization requirements reshape supplier qualification criteria and project economics across the region.
Market Dynamics
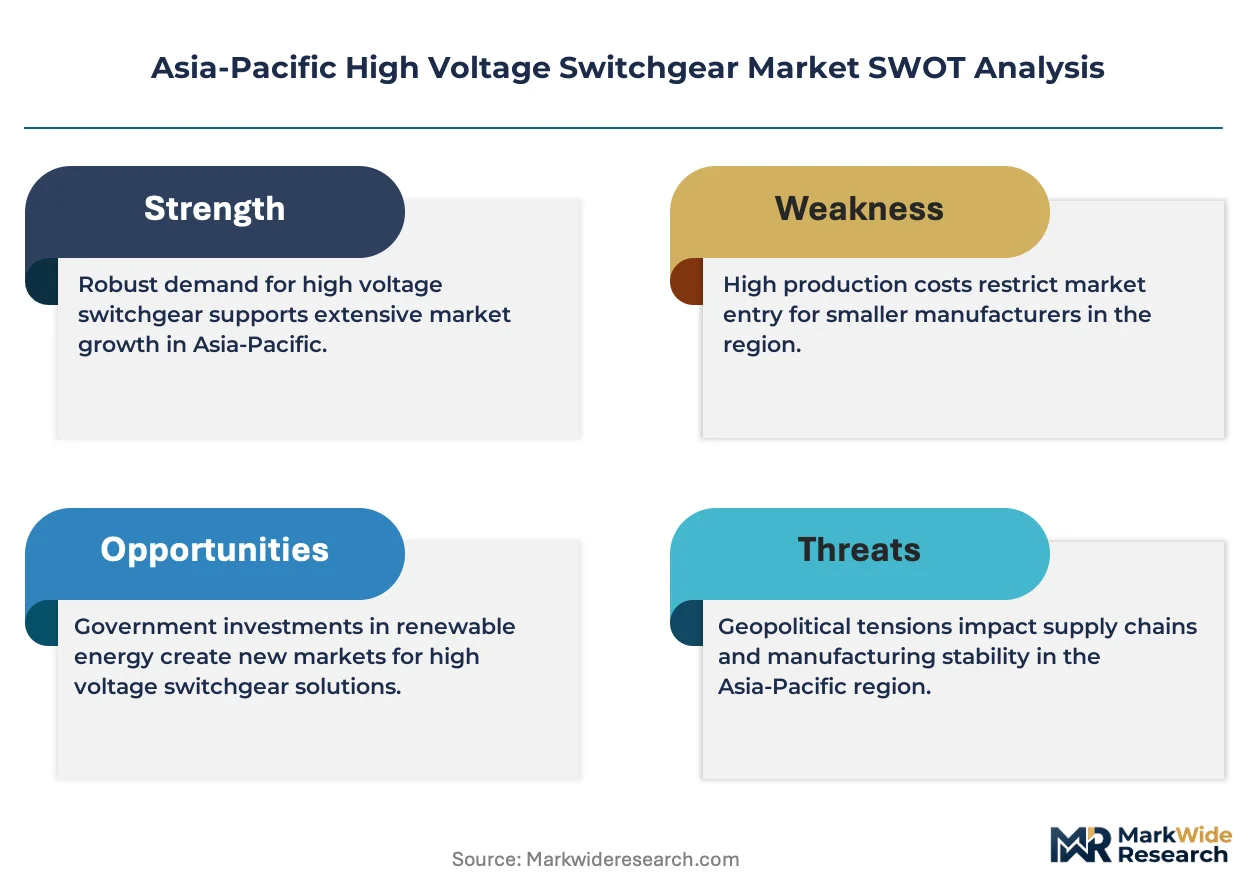
SF6 phase-down mandates across Asia-Pacific are forcing a fundamental retooling of switchgear dielectric systems, redirecting capital from gas-insulated toward vacuum interrupter architectures and pressurized air alternatives.
Growth Catalysts
- China's dual carbon goals:Beijing's emission reduction framework is accelerating retirement of legacy oil-circuit breakers in provincial grids, creating replacement demand for digital switchgear with integrated monitoring.
- India's PLI scheme for power equipment:Production-linked incentives are attracting foreign joint ventures to establish localized GIS manufacturing in Gujarat and Tamil Nadu, compressing import dependency.
- Urban densification:Substation footprint constraints in Tokyo, Seoul, and Shanghai are mandating compact gas-insulated designs that reduce land acquisition costs by over half versus air-insulated equivalents.
Market Restraints
- Copper and aluminum price volatility:Raw material input swings of twenty to thirty percent within single quarters are compressing OEM margins and destabilizing project bidding.
- SF6 supply concentration:Three Chinese chemical producers control over seventy percent of global sulfur hexafluoride refining capacity, creating single-source vulnerability for GIS manufacturers.
- Vacuum interrupter current ceiling:Technical limitations above 145 kV ratings restrict vacuum technology deployment in ultra-high voltage transmission corridors.
Strategic Opportunities
- Vietnam and Indonesia grid expansion:State utility procurement cycles in these markets remain underpenetrated by digital switchgear, offering first-mover positioning for IEC 61850-compliant suppliers.
- Offshore wind integration:Floating substation projects in Japanese and South Korean waters require marine-grade GIS with corrosion-resistant enclosures.
- Retrofit sensorization:Edge computing modules that graft onto installed air-insulated switchgear are creating aftermarket revenue streams without full asset replacement.
Industry Challenges
- IEC 61850 systems integration:Legacy protection relays in Indian and Southeast Asian substations lack standardized communication protocols, forcing costly middleware development.
- SF6 handling certification gaps:Field technician shortages for sealed-system maintenance are extending commissioning timelines and elevating service backlogs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific High Voltage Switchgear Market |
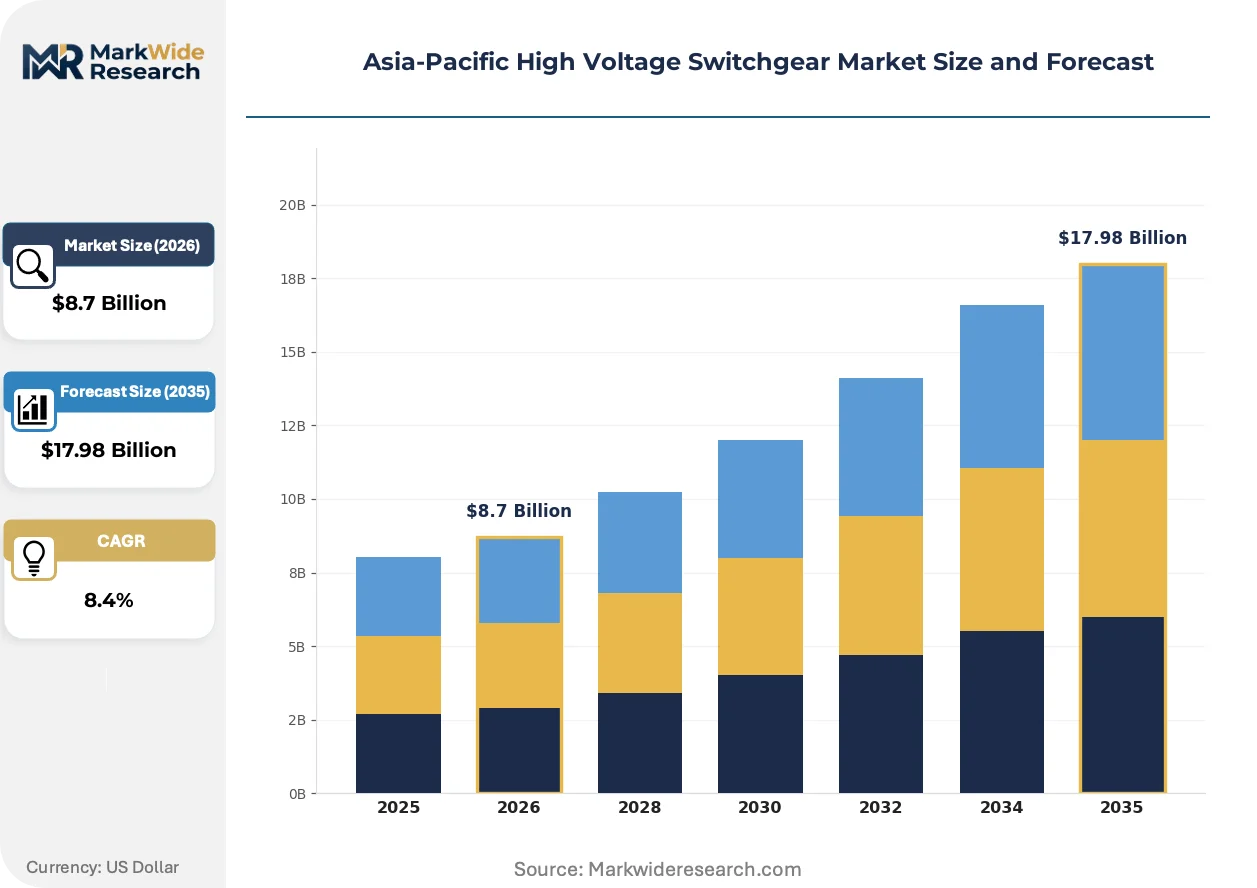
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-insulated Switchgear, Gas-insulated Switchgear, Hybrid Switchgear, Oil-insulated Switchgear End User: Utilities, Industrial, Commercial, Mining Installation Type: Indoor, Outdoor, Modular, Compact Technology: Smart Switchgear, Conventional Switchgear, Digital Switchgear, Others |
| Companies Covered | Toshiba International Corporation, Hitachi Energy Ltd, ABB Ltd, Larsen & Toubro Limited, Bharat Heavy Electricals Limited, General Electric Company, Mitsubishi Electric Corporation, Hyosung Heavy Industries Corp., Siemens AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific High Voltage Switchgear Market Trends and Innovations
Digital twin integration is reconfiguring how utilities manage switchgear asset lifecycles, compressing maintenance intervals and enabling condition-based rather than calendar-based interventions.
Vacuum interrupter technology is digitizing protection coordination in medium-voltage feeder networks across Chinese smart city pilots. State Grid Corporation is deploying these systems in Shenzhen and Suzhou substations at accelerated procurement cycles. The architecture is digitizing fault isolation response times from seconds to milliseconds, reducing outage propagation across urban distribution rings.
Japan's METI is enforcing IEC 61850 Edition 2.1 interoperability mandates that reshape procurement specifications for ASEAN utility tenders. Industrial consequence includes disqualification of proprietary communication protocols in favor of standardized data models. Japanese manufacturers are responding by open-sourcing middleware layers previously held as competitive moats.
Utility procurement departments are consolidating vendor panels from twenty-plus suppliers to preferred partnerships with three to five OEMs capable of full-lifecycle service. This concentration is displacing spot-buying of commodity components through electrical distributors. The shift is most visible in Australia's NEM grid operators, where long-term service agreements now accompany hardware procurement.
Asia-Pacific High Voltage Switchgear Market Segmentation
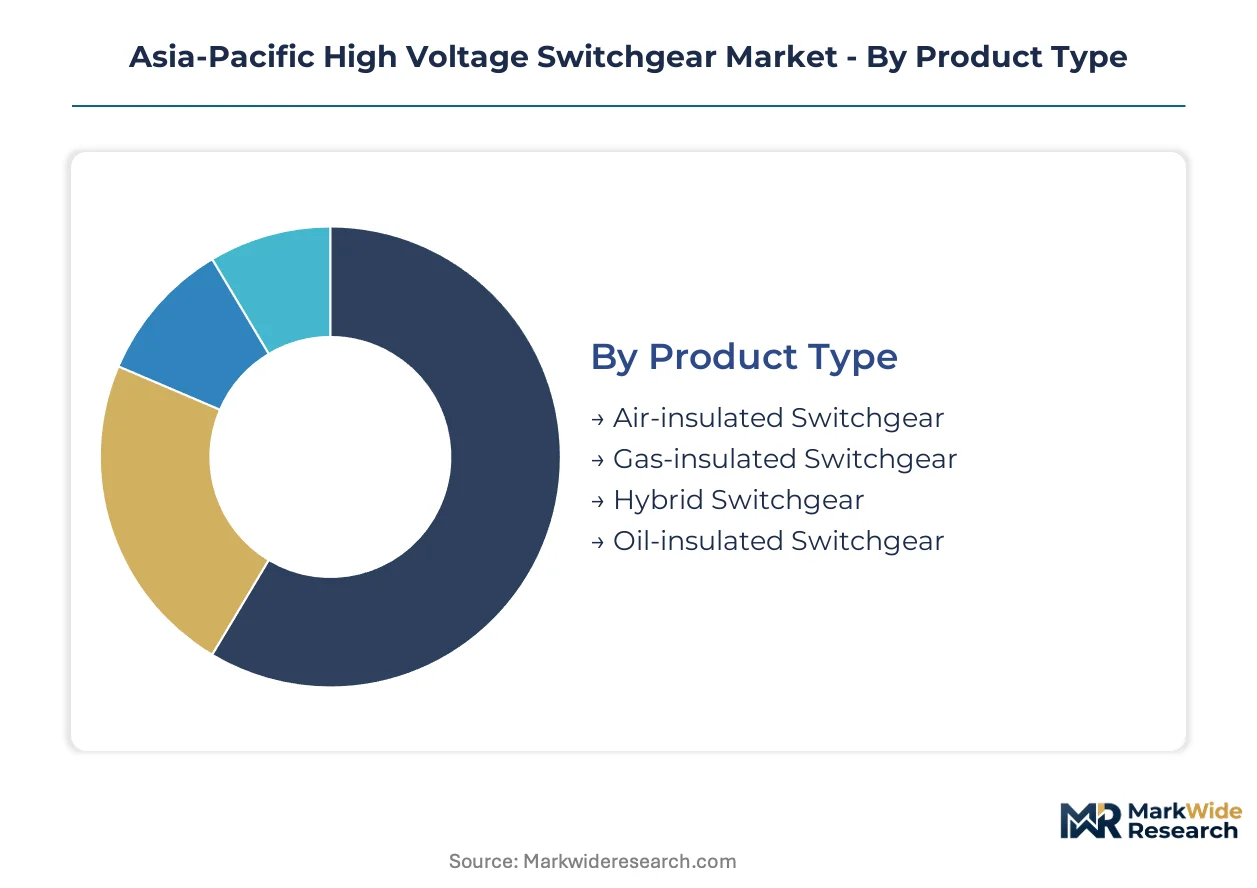
High voltage switchgear procurement cycles vary dramatically by dielectric technology and installation environment, with replacement intervals stretching from fifteen years for air-insulated outdoor installations to thirty-five years for sealed gas-insulated systems. Understanding these turnover rhythms helps suppliers align R&D pipelines with predictable replacement waves across Asia-Pacific utility networks.
Product Type:
Gas-insulated switchgear commands the longest replacement cycles due to sealed-system longevity, while oil-insulated units face accelerated retirement under environmental regulations.
- Gas-insulated Switchgear:Sulfur hexafluoride-filled enclosures achieve dielectric strength three times higher than air, enabling footprint reductions critical for Tokyo and Shanghai substations where land costs exceed equipment capital outlays. State Grid Corporation and Korea Electric Power Corporation are standardizing on 145 kV and 300 kV GIS for urban ring-main units.
- Air-insulated Switchgear:Open-air conductor spacing requires substantially larger substation footprints but delivers capital cost advantages and simplified maintenance access. Rural electrification programs in Indonesia and Vietnam specify AIS for 72.5 kV distribution substations where space constraints are minimal.
- Hybrid Switchgear:Combines gas-insulated busbars with air-insulated circuit breakers to balance footprint efficiency with maintenance accessibility. Indian transmission utilities are piloting hybrid designs at 245 kV ratings to reduce SF6 inventory while preserving compact layouts.
- Oil-insulated Switchgear:Legacy mineral-oil dielectric systems face accelerated phase-out under China's MEE emission protocols and Japan's PCB contamination remediation mandates. Remaining installations concentrate in older Indian state utility networks awaiting capital refresh cycles.
Gas-insulated switchgear anchors the volume base while hybrid configurations gain share at the steepest rate as utilities seek middle-ground solutions.
End User:
Procurement authority and technical specification complexity diverge sharply between centralized utility buyers and fragmented industrial purchasers.
- Utilities:Vertically integrated state and private transmission operators specify IEC 61850-compliant architectures with twenty-five-year service agreements. China's State Grid and Southern Power Grid account for the dominant procurement volume across 110 kV through 800 kV ratings.
- Industrial:Steel, cement, and petrochemical complexes purchase switchgear as captive substation assets with specialized arc-flash and harmonic withstand requirements. Japanese automotive manufacturing clusters specify 66 kV GIS with integrated power quality monitoring.
- Commercial:Data center and metro rail developers procure medium-voltage switchgear through EPC contractors with compressed delivery timelines. Singapore and Sydney financial district substations prioritize compact digital switchgear for basement installation.
- Mining:Open-pit and underground operations demand explosion-proof and corrosion-resistant enclosures for 33 kV through 132 kV feeder protection. Australian iron ore and Indonesian nickel operations specify outdoor AIS with elevated ingress protection ratings.
Utility procurement dominates absolute volume while industrial end-use climbs fastest as captive power investment accelerates across Southeast Asian manufacturing zones.
Installation Type:
Spatial constraints and environmental exposure dictate enclosure architectures that cascade through civil engineering costs and permitting timelines.
- Indoor:Climate-controlled switchgear halls protect against tropical humidity and particulate contamination in coastal Chinese and Indian substations. 145 kV GIS dominates indoor specifications where real estate premiums justify capital-intensive sealed systems.
- Outdoor:Open-yard installations prevail in Australian mining corridors and Indian rural transmission networks with abundant land availability and lower environmental protection requirements.
- Modular:Factory-assembled skid-mounted substations compress field commissioning from months to weeks. Bangladesh and Myanmar utilities are adopting 132 kV modular GIS for rapid electrification of islanded grid segments.
- Compact:Ultra-dense arrangements for underground metro substations and offshore wind platforms integrate switchgear, transformers, and control systems within single enclosures. South Korean floating offshore wind projects specify marine-grade compact GIS with nitrogen-sealed interrupters.
Outdoor installations retain the largest installed base while compact configurations expand most quickly alongside urban densification and renewable integration projects.
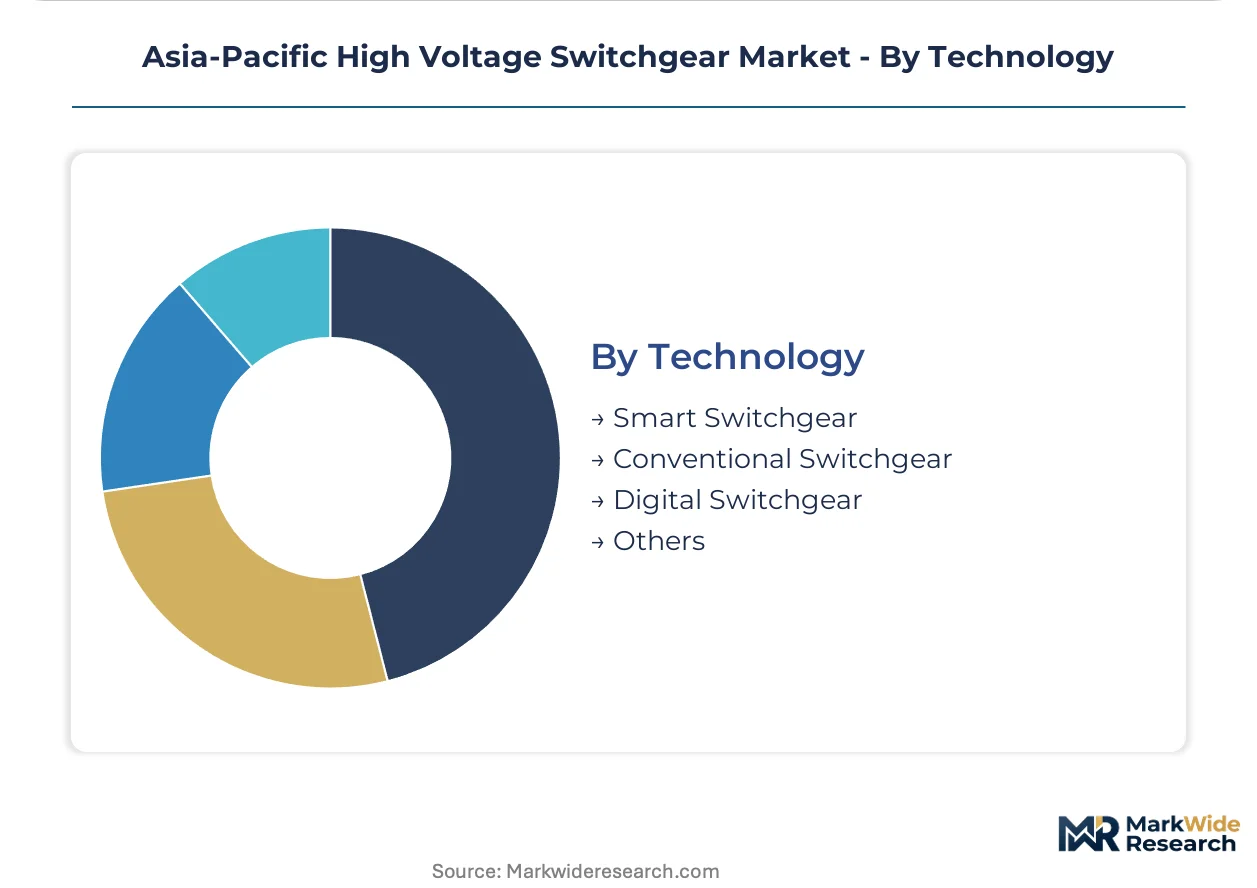
Technology:
Intelligence integration levels separate commodity hardware from premium-positioned systems with embedded sensing and edge analytics capabilities.
- Smart Switchgear:Distributed sensor networks monitor contact wear, gas density, and thermal profiles to enable predictive maintenance algorithms. State Grid's Suzhou and Shenzhen pilots deploy smart 220 kV GIS with millisecond fault localization.
- Digital Switchgear:Software-defined protection relays and process bus architectures replace hardwired copper control circuits with fiber-optic communication. Japan's METI IEC 61850 Edition 2.1 mandates are accelerating digital adoption across ASEAN tender specifications.
- Conventional Switchgear:Electromechanical protection and discrete wiring persist in cost-sensitive Indian state utilities and Indonesian regional power authorities with limited automation expertise.
- Others:Emerging solid-state interrupter prototypes and superconducting fault current limiters remain pre-commercial but attract R&D investment from Korean and Chinese national laboratories.
Conventional technology holds the majority of installed capacity while digital switchgear demonstrates the steepest expansion trajectory as interoperability standards mature across Asia-Pacific procurement frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility procurement departments across Asia-Pacific concentrate purchasing authority within state-owned transmission operators and large private grid developers, creating buyer-archetype concentration that favors suppliers with full-lifecycle service capabilities and long-term maintenance contracts.
China
State Grid Corporation and Southern Power Grid drive procurement volume for 110 kV through 800 kV switchgear as eastern coastal provinces integrate offshore wind and retire legacy oil-circuit breakers. The MEE enforces SF6 emission monitoring and phased reduction protocols that redirect R&D investment toward vacuum interrupter alternatives. Jiangsu and Zhejiang provinces concentrate demand for compact GIS in Shanghai-adjacent substations where land acquisition costs dominate project economics.
India
Central and state transmission utilities are expanding 765 kV corridors under green energy corridor schemes while industrial zones in Gujarat and Maharashtra build captive substations. The CEA mandates centralized testing and certification through NABL-accredited laboratories, creating compliance barriers for imported equipment. Tamil Nadu and Karnataka host emerging GIS manufacturing joint ventures attracted by PLI scheme incentives, compressing import dependency for western industrial corridor projects.
Japan
Tokyo Electric Power and regional utilities standardize on 145 kV and 300 kV GIS for dense urban substations as METI enforces IEC 61850 Edition 2.1 interoperability mandates. METI protocols reshape procurement specifications across ASEAN utility tenders by disqualifying proprietary communication protocols. Kanto and Kansai regions concentrate demand for marine-grade switchgear supporting floating offshore wind platforms in Japanese waters.
South Korea
Korea Electric Power Corporation accelerates smart grid deployment with digital protection platforms as renewable integration targets drive substation automation investment. National standards align with IEC 61850 frameworks to ensure interoperability with ASEAN procurement specifications. Busan-Ulsan industrial clusters and Seoul Capital Area substations prioritize compact GIS designs that reduce footprint in land-constrained urban environments.
Australia
National Electricity Market grid operators consolidate vendor panels to preferred partnerships with three to five OEMs capable of full-lifecycle service, displacing spot-buying through electrical distributors. Network operators in New South Wales and Victoria prioritize long-term service agreements accompanying hardware procurement. Queensland and Western Australia mining corridors specify outdoor AIS with elevated ingress protection ratings for iron ore and nickel operations.
Asia-Pacific High Voltage Switchgear Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement frameworks that reward either manufacturing scale or technical customization depth. The vendor base organizes around three strategic archetypes: integrated electrical conglomerates with software-defined protection platforms, heavy industrial manufacturers with localized assembly capabilities, and regional specialists focused on cost-optimized AIS for rural applications. Dominant competitive moves include capacity expansion into PLI-incentivized Indian manufacturing zones and strategic partnerships to embed edge computing modules into installed base retrofit programs.
Within the integrated conglomerate tier, Hitachi Energy Ltd and Siemens AG occupy positions defined by software-defined protection platforms and German-engineered product lines respectively. Mitsubishi Electric Corporation exemplifies the heavy industrial archetype with concentrated supply relationships to Japanese utilities and export markets. Among India-based fabricators, Larsen & Toubro Limited and Bharat Heavy Electricals Limited represent localized manufacturing strategies aligned with CEA certification requirements and PLI scheme incentives. Toshiba International Corporation and Hyosung Heavy Industries Corp. anchor regional specialist positions across Pacific Rim procurement cycles.
| Leading Market Players |
|---|
| Toshiba International Corporation |
| Hitachi Energy Ltd |
| ABB Ltd |
| Larsen & Toubro Limited |
| Bharat Heavy Electricals Limited |
| General Electric Company |
| Mitsubishi Electric Corporation |
| Hyosung Heavy Industries Corp. |
| Siemens AG |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Singapore maritime corridor anchors cost dynamics across Asia-Pacific switchgear procurement, where freight volatility amplifies pricing power for Chinese chemical producers controlling sulfur hexafluoride refining while compressing margins for OEMs serving price-sensitive Indian state utilities.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange copper and aluminum pricing dominate utility procurement frameworks across State Grid and Korea Electric Power Corporation tenders. Price differentiation rests on IEC 61850 certification tier and localized manufacturing presence under India's PLI scheme. Cost compression in air-insulated switchgear intensifies as Indonesian and Vietnamese utilities prioritize capital efficiency over smart functionality. Mining and industrial end-users in Australia and Japan exhibit lowest price sensitivity due to arc-flash compliance mandates and captive power reliability requirements.
Supply Chain Analysis
Tariff exposure between China and India dominates supply chain risk calculations for GIS manufacturers dependent on Chinese SF6 and vacuum interrupter components. Manufacturing concentrates in China, Germany, and India, with Chinese Jiangsu and Zhejiang provinces hosting dielectric gas refining and interrupter assembly. Raw material dependencies span copper busbars, aluminum enclosures, and epoxy resin insulation systems. Distribution runs through EPC contractors for utility projects and direct OEM relationships for industrial captive substations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific high voltage switchgear represents a service-attach opportunity where predictive maintenance contracts and digital retrofit modules expand faster than hardware replacement cycles across aging installed bases.
For Market Incumbents: Harden lifecycle service capabilities through backward integration into vacuum interrupter manufacturing in Tamil Nadu and Gujarat PLI zones. Deepen software-defined protection platform stickiness by embedding edge analytics that reduce customer switching costs. Vacuum interrupter supply concentration threatens margin stability for gas-insulated product lines. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, with Bangkok and Jakarta data center developers specifying compact digital switchgear through EPC contractors lacking incumbent relationships. Target 66 kV hybrid configurations for Indian industrial zones seeking SF6 reduction without full digital premium. Partner with regional electrical distributors for aftermarket sensorization retrofit programs. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with undermonetized switchgear divisions lacking digital platform integration. Long-term viability favors suppliers with captive vacuum interrupter technology and IEC 61850 Edition 2.1 certification pipelines. Monitor METI enforcement patterns across ASEAN tender specifications as interoperability mandate diffusion signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum Interrupter Manufacturing | PLI scheme incentives in Tamil Nadu reduce import dependency for GIS producers serving Indian utilities. |
| Digital Retrofit Module Development | Edge computing grafts onto installed air-insulated switchgear create recurring revenue without asset replacement. |
| IEC 61850 Edition 2.1 Certification Investment | METI mandates across ASEAN tenders disqualify proprietary protocols, reshaping competitive qualification criteria. |
| Marine-Grade GIS Capacity Buildout | South Korean floating offshore wind projects require corrosion-resistant enclosures with nitrogen-sealed interrupters. |
| Long-Term Service Agreement Structuring | Australia's NEM grid operators consolidate vendor panels to preferred partnerships with full-lifecycle capabilities. |
Research Methodology
The analysis maps gas-insulated, air-insulated, hybrid, and oil-insulated switchgear sub-sectors, each validated through utility procurement officers, EPC contractor project managers, OEM aftermarket service heads, and industrial plant engineers. Primary interviews with State Grid planning departments, Korea Electric Power Corporation automation teams, and Indian CEA certification officials combined with secondary validation from customs trade databases, SEC filings of listed electrical equipment manufacturers, IEC standard revision documentation, and national grid investment announcements. Bottom-up unit deployment estimates and top-down utility capital expenditure triangulation anchored volume and value outputs.
Assumption-sets held grid modernization timelines and carbon neutrality policy intensity as fixed boundary conditions while varying copper price volatility bands and SF6 phase-down acceleration scenarios across the projection horizon. Segmentation dimensions modeled include dielectric technology, installation environment, end-user archetype, and intelligence integration level. CAGRs derived from replacement cycle analysis correlated with utility capital refresh schedules and renewable integration targets. Forecast inputs incorporated offshore wind substation procurement pipelines and smart city pilot expansion rates.
Macroeconomic conditions sit as an overlay; deviation in Chinese infrastructure stimulus intensity, Indian PLI scheme renewal patterns, or yen-dollar exchange rate movements would shift the trajectory. Forecasts reflect documented assumptions regarding interoperability standard adoption velocity and vacuum interrupter technical ceiling progression. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Surface Mount Switch Market
Switches
Japan Reed Sensors Switches Market
Switches
Electronic Shift-By-Wire Selector Modules Market
Switches
Reed Switch Market
Switches
United States Circuit Breaker Market
Switches
North America Push Buttons & Signaling Devices Market
Switches
Australia and New Zealand Medium Voltage Switchgear Market
Switches
Europe Push Buttons and Signaling Devices Market
Switches
Cross Point Switch Market
Switches
Contactor-based Transfer Switch Market
Switches
Australia Switchgear Market
Switches
Rocker Switch Market
Switches
Fixed Switch Cabinet Market
Switches
Navigation Switches Market
Switches
Asia Pacific Transfer Switches Market
Switches
Global Safety Switches Market