
 Global Magnetic Circuit Breaker Market | 2026-2036
Global Magnetic Circuit Breaker Market Size, Share, and Industry Trends Forecast 2026-2036
Global Magnetic Circuit Breaker Market Outlook
Utility procurement in the Global Magnetic Circuit Breaker Market is consolidating around fewer but larger grid operators and EPC contractors with multi-year framework agreements. ABB leverages its installed base in substation automation to sustain recurring breaker replacement cycles across European utilities. Schneider Electric anchors its position through integrated energy management platforms that bundle magnetic circuit breakers with digital monitoring. Eaton competes on hazardous-location certifications, differentiating its offerings for oil, gas, and mining end users in North America and the Middle East.
A magnetic circuit breaker employs an electromagnet whose coil energizes proportionally to current flow; when the magnetic field strength exceeds a calibrated threshold, a solenoid plunger mechanically trips the contact assembly to interrupt fault currents. These devices typically handle rated currents from milliamperes to several thousand amperes, with trip characteristics defined by B, C, D, or K curves depending on inrush tolerance and load type. Molded case circuit breakers dominate volume in industrial and commercial panels due to their compact form factor and modular trip units, while air circuit breakers command the premium segment in low-voltage switchgear for utilities and large manufacturing facilities. DIN rail mount installation leads in European and Asian distribution boards, though panel mount configurations retain share in North American OEM equipment.
The US National Electrical Code, IEC 60947-2 for low-voltage switchgear, and UL 489 standards collectively govern magnetic circuit breaker design, testing, and market access across major economies. China's GB 14048 standards and India's BIS certification requirements add compliance layers for manufacturers targeting Asia-Pacific infrastructure buildouts. Stakeholders must monitor evolving arc-fault detection mandates and digital retrofit compatibility as electrification accelerates and grid operators prioritize predictive maintenance over scheduled replacement.
Market Dynamics
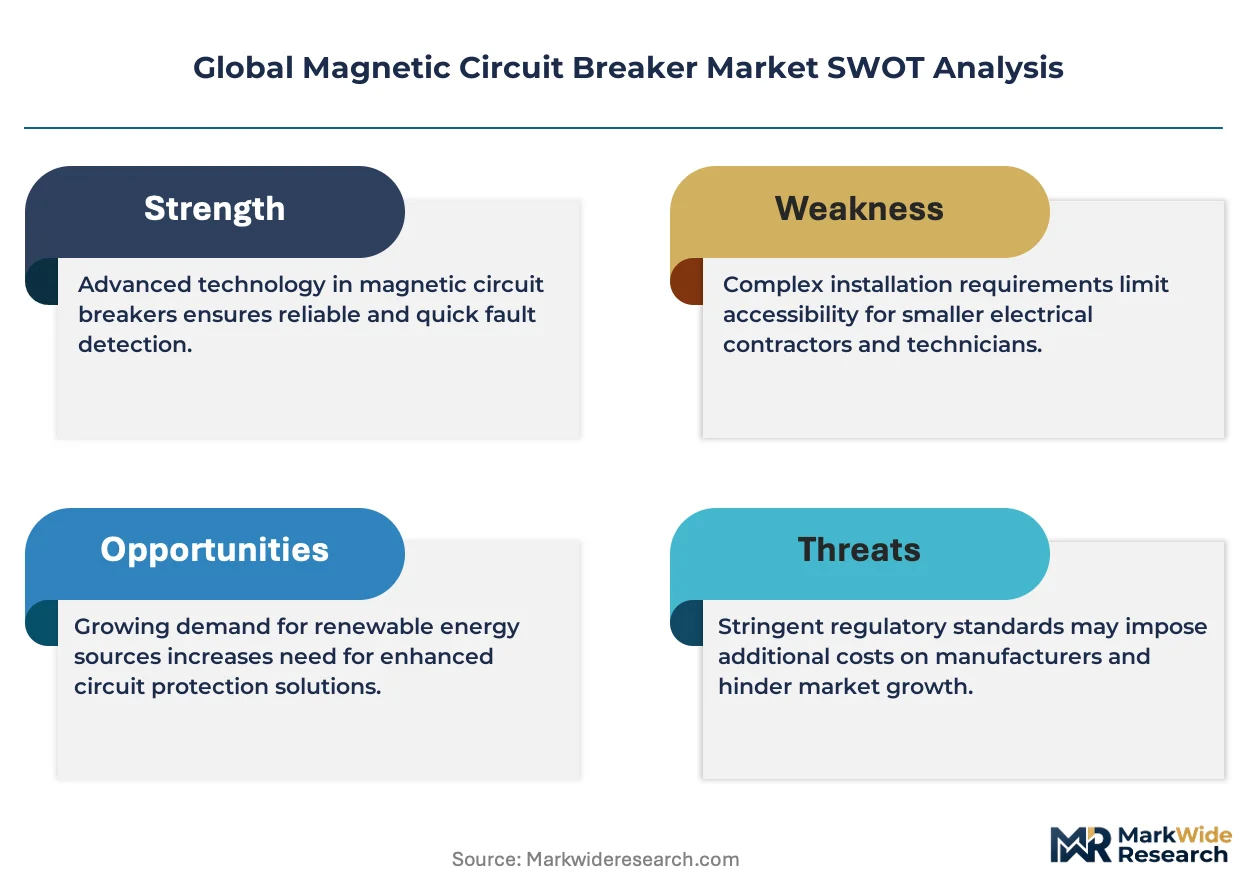
Utility-scale grid modernization programs across emerging markets are consolidating procurement authority into fewer transmission operators with multi-year framework agreements, compressing vendor selection cycles and favoring manufacturers with integrated digital monitoring capabilities.
Growth Catalysts
- IEC 60947-2 harmonization:Unified low-voltage switchgear standards across European and Asian markets are reducing certification duplication costs for manufacturers targeting cross-border utility contracts.
- Industrial electrification clusters:Heavy manufacturing facilities in Germany and India are retrofitting legacy motor control centers with magnetic trip units rated for higher fault interruption capacity.
- Copper-aluminum hybrid busbars:Advanced conductor materials are enabling compact molded case designs that reduce panel footprint by 30% in commercial building distribution boards.
Market Restraints
- Silver contact volatility:Spot price fluctuations for silver-cadmium oxide alloys used in high-ampacity contacts are squeezing gross margins on air circuit breaker production lines.
- Foundry concentration in China:Gray iron casting for breaker housings relies on a narrow supplier base in Zhejiang and Jiangsu provinces, creating single-source vulnerability.
- Thermomagnetic hybrid displacement:Residential and light commercial segments in North America are migrating to combination AFCI-GFCI devices that reduce pure magnetic breaker specification rates.
Strategic Opportunities
- India's renewable evacuation infrastructure:State transmission utilities are tendering for 33kV and 66kV substation upgrades requiring low-voltage switchgear with digital trip unit retrofit compatibility.
- CE marking plus BIS dual certification:Manufacturers achieving concurrent compliance can access both European distribution board OEMs and Indian infrastructure EPCs without separate product lines.
- IIoT-enabled predictive maintenance:Integration of contact wear sensors with SCADA systems is automating replacement scheduling for utility customers seeking to shift from time-based to condition-based maintenance.
Industry Challenges
- Arc flash calculation expertise:System integrators face shortages of engineers certified to perform IEEE 1584 incident energy analyses required for breaker coordination studies in industrial facilities.
- Legacy electromechanical retrofit complexity:Utilities with 1980s-era air circuit breaker installations encounter mechanical incompatibility when attempting to upgrade to electronic trip units without full frame replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Magnetic Circuit Breaker Market |
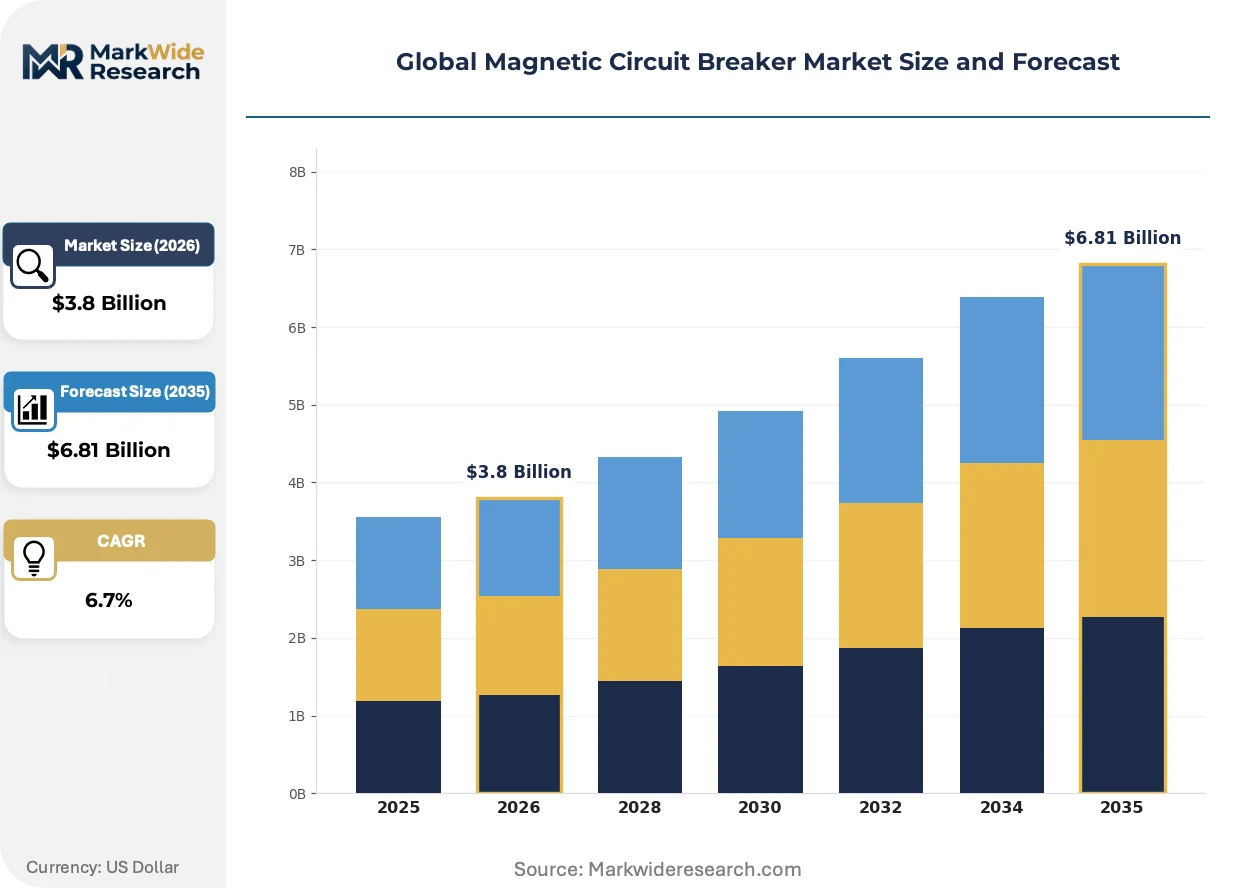
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Miniature Circuit Breaker, Earth Leakage Circuit Breaker, Molded Case Circuit Breaker, Air Circuit Breaker Installation Type: Panel Mount, Wall Mount, DIN Rail Mount, In-Line Mount Application: Residential, Commercial, Industrial, Aerospace End User: Utilities, Construction, Manufacturing, Automotive |
| Companies Covered | ABB, Schneider Electric, Eaton, TE Connectivity, R. STAHL, Techna International, Carling Technologies, Rockwell Automation, E-T-A Elektrotechnische Apparate, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Magnetic Circuit Breaker Market Strategic Shifts
Digitalization of protection coordination and embedded sensing is transforming magnetic circuit breakers from passive safety devices into data nodes within grid automation architectures, compressing replacement cycles and reshaping aftermarket service economics.
Embedded Rogowski coil sensors within molded case breaker frames are automating real-time load monitoring and fault waveform capture for industrial energy management systems. Food processing and pharmaceutical manufacturers in Germany and the Netherlands are specifying these units to satisfy ISO 50001 energy audit requirements without separate meter installation. The technology is automating the displacement of external current transformers in panel assemblies below 800A rated capacity.
China's GB 14048.2-2020 amendments mandating electromagnetic compatibility testing for electronic trip units are forcing redesigns of microprocessor-based protection modules. Domestic manufacturers in Shanghai and Shenzhen are absorbing six-to-nine month recertification timelines to maintain access to state grid tenders. The regulation most acutely affects export-oriented suppliers previously certified only to IEC baselines without Chinese national deviations.
Specifying engineers at EPC contractors are unbundling breaker procurement from switchgear assembly, sourcing trip units directly from ABB or Schneider Electric while outsourcing mechanical frames to regional metal fabricators. This pattern compresses margins for integrated manufacturers but opens aftermarket revenue streams for firmware upgrades and calibration services. The behavior is most visible in India's transmission and distribution expansion programs where cost engineering pressures dominate vendor selection.
Global Magnetic Circuit Breaker Market Segmentation
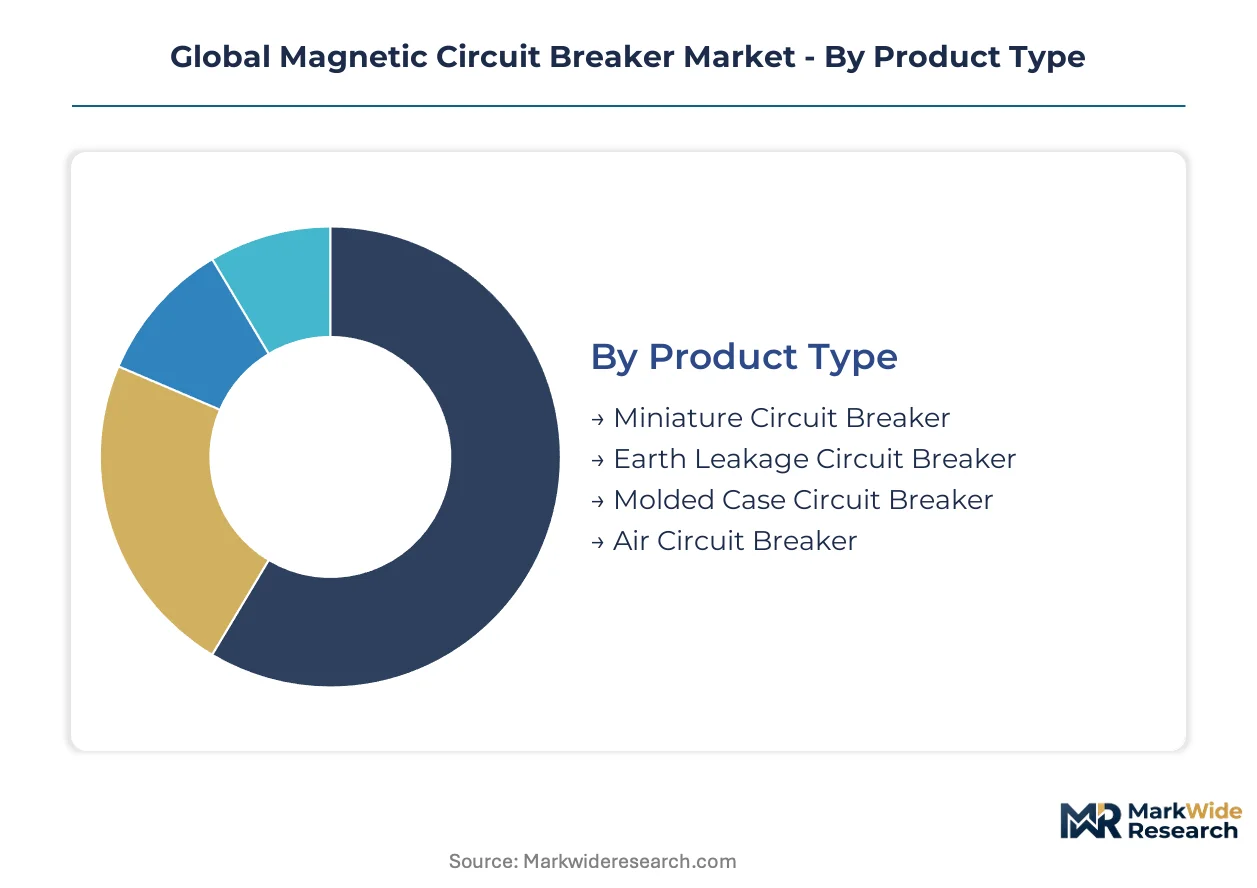
Magnetic circuit breaker procurement varies sharply across installation contexts and load requirements, with certification burdens and fault-interruption specifications dictating vendor selection. Understanding segment boundaries clarifies why utilities, industrial facilities, and residential developers source from distinct supplier tiers despite overlapping underlying technology.
Product Type:
UL 489 and IEC 60947-2 certifications dominate commercial and industrial procurement, while residential segments prioritize cost-optimized designs meeting national deviations of baseline standards. CE marking unlocks European distribution board OEM contracts; BIS certification is mandatory for Indian infrastructure tenders.
- Miniature Circuit Breaker:Compact thermal-magnetic units rated up to 125A dominate residential distribution boards and commercial lighting panels. German and Dutch electrical contractors specify these for retrofit projects requiring DIN rail compatibility without panel redesign. IEC 60898 compliance is baseline for European residential access.
- Air Circuit Breaker:High-ampacity units with adjustable electronic trip units serve main incoming protection in utility substations and large manufacturing facilities. Indian state transmission utilities tender these for 33kV substation upgrades requiring selective coordination with downstream molded case units. UL 1066 certification governs North American utility procurement.
- Earth Leakage Circuit Breaker:Combines overcurrent and residual current protection for wet-location installations in commercial kitchens and healthcare facilities.
- Molded Case Circuit Breaker:Modular trip units enable field-adjustable protection settings across industrial motor control centers and commercial building risers.
Leading the category by volume: Miniature Circuit Breaker. Growing fastest: Air Circuit Breaker.
Installation Type:
Mounting configuration determines panel footprint, wiring labor, and retrofit feasibility across OEM equipment and field-installed distribution boards. Cost tier separation is pronounced: DIN rail dominates mass-market commercial construction, while panel mount commands premium pricing in specialized industrial equipment.
- DIN Rail Mount:Standardized 35mm rail attachment enables rapid installation and modular expansion in European and Asian commercial buildings. German electrical wholesalers stock these exclusively for construction projects targeting ISO 50001 energy management certification. The format is displacing screw-terminal alternatives in Indian metro rail electrification.
- Panel Mount:Direct chassis attachment with through-hole or stud mounting serves OEM switchgear and heavy industrial control enclosures. North American mining equipment manufacturers specify these for vibration resistance in haul truck electrical compartments. NEMA enclosure compatibility adds certification cost.
- Wall Mount:Surface-mounted enclosures for standalone residential and light commercial feeder protection.
- In-Line Mount:Direct conductor integration for appliance cord sets and mobile equipment power feeds.
DIN Rail Mount captures the highest shipment volumes. Panel Mount generates the steepest expansion trajectory in industrial electrification clusters.
Application:
Application scope correlates with fault-current magnitude and coordination complexity, driving specification divergence between commodity residential units and engineered industrial systems. Customer type concentration shapes margin structure: aerospace programs sustain multi-year development contracts, while residential competes on distributor pricing.
- Industrial:Motor protection, feeder circuits, and machine tool isolation demand high interrupting capacity and adjustable magnetic trip thresholds. German automotive stamping plants specify these for press line protection requiring coordination with upstream air circuit breakers. Arc flash energy calculations per IEEE 1584 govern breaker selection.
- Aerospace:Mil-spec environmental qualification and weight minimization drive specialized designs for aircraft electrical distribution. French and German Tier 1 suppliers integrate these into next-generation electric aircraft power architectures. RTCA DO-160G testing adds substantial certification duration.
- Residential:Standard branch circuit protection in single-family and multi-family dwelling units.
- Commercial:Tenant panel distribution and HVAC feeder protection in office and retail buildings.
Industrial application leads by revenue concentration. Aerospace application climbs fastest on electrification investment.
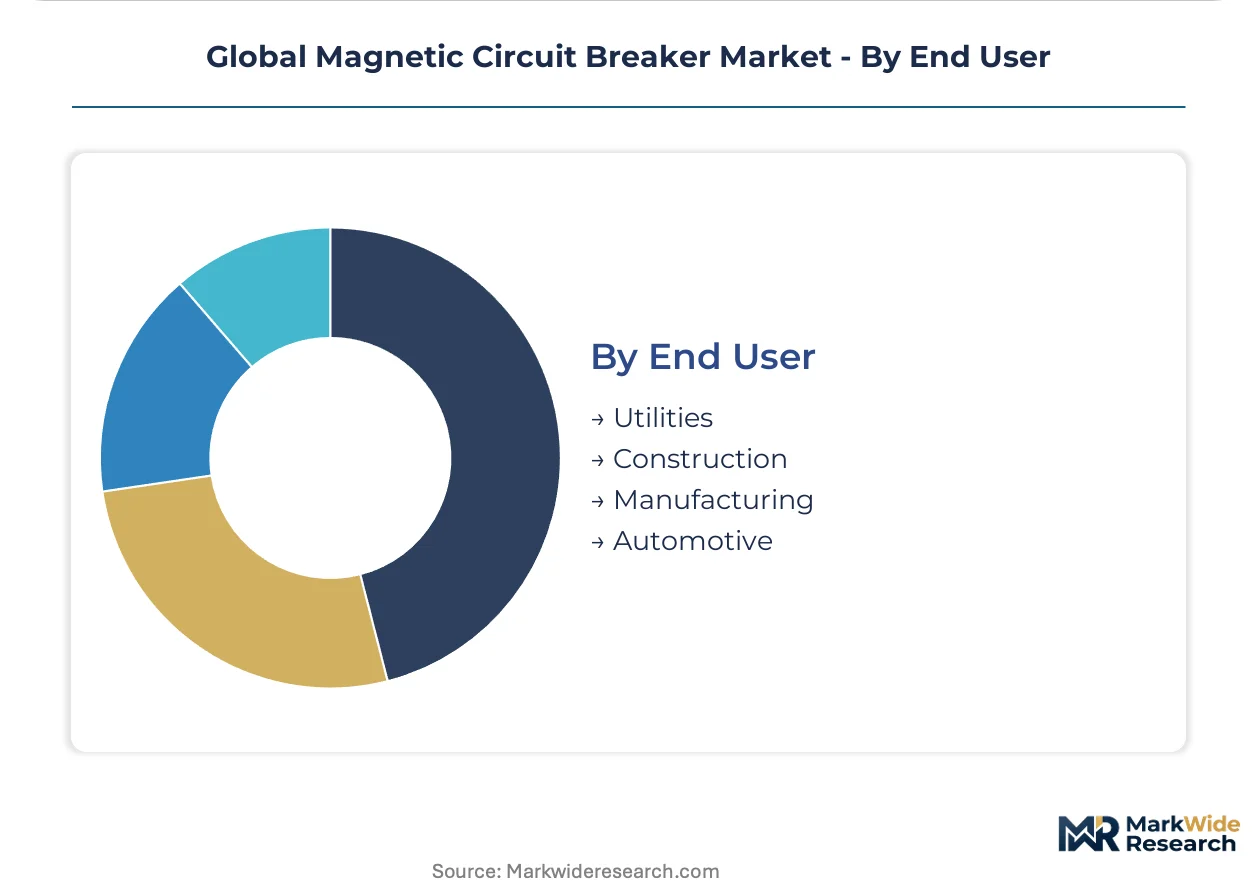
End User:
End user category determines procurement authority structure and replacement cycle predictability. Utilities operate multi-year framework agreements with centralized technical specifications; construction procurement fragments across project-specific bidding.
- Utilities:Transmission and distribution operators standardize on electronic trip units with SCADA integration for remote monitoring. Chinese state grid tenders mandate GB 14048.2-2020 electromagnetic compatibility certification for all substation switchgear. Recurring replacement cycles sustain aftermarket service revenue.
- Manufacturing:Discrete and process industries specify coordinated protection for motor control centers and power distribution units. Indian steel and cement producers retrofit legacy installations with digital trip units compatible with existing breaker frames. Plant uptime requirements prioritize selective coordination over first cost.
- Construction:Electrical contractors source through distribution channels for project-specific panel assembly.
- Automotive:EV charging infrastructure and battery manufacturing line protection drives specification of DC-rated variants.
Utilities dominate procurement value. Manufacturing end use is gaining share fastest on industrial electrification momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gray iron foundries in Zhejiang province anchor breaker housing production, concentrating supply-side leverage in eastern China before distribution to assembly plants worldwide.
China
State Grid tenders for 33kV substation upgrades drive procurement of low-voltage switchgear with digital trip compatibility. GB 14048.2-2020 electromagnetic compatibility mandates force six-to-nine month recertification timelines for microprocessor-based protection modules. Shanghai and Shenzhen manufacturers absorb these delays to maintain access to renewable evacuation infrastructure contracts.
Germany
Automotive stamping plants and steel producers retrofit motor control centers with higher fault-interruption capacity units. IEC 60947-2 harmonization reduces certification duplication costs for manufacturers targeting cross-border utility contracts. The Ruhr industrial cluster and Bavarian manufacturing belt concentrate demand for coordinated protection systems with arc flash energy calculations per IEEE 1584.
India
State transmission utilities tender for 66kV substation upgrades requiring selective coordination capabilities. BIS certification requirements add compliance layers for manufacturers targeting infrastructure buildouts. The Delhi-Mumbai Industrial Corridor and Gujarat Special Investment Regions concentrate cement and steel producer retrofits of legacy installations with frame-compatible digital trip units.
United States
EV charging infrastructure and battery manufacturing lines drive specification of DC-rated variants. The National Electrical Code and UL 489 standards govern design and market access, with arc-fault detection mandates reshaping residential product mix. Texas and California industrial clusters prioritize predictive maintenance integration with SCADA systems for utility-scale solar and storage interconnection.
United Arab Emirates
Oil, gas, and mining operators in the Middle East specify hazardous-location certifications for upstream electrical protection. Regional EPC contractors unbundle breaker procurement from switchgear assembly, sourcing trip units directly while outsourcing mechanical frames. Dubai and Abu Dhabi infrastructure expansion concentrates demand for panel mount configurations with NEMA enclosure compatibility in desert environments.
Global Magnetic Circuit Breaker Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue digital monitoring integration and IIoT-enabled predictive maintenance services. The vendor base concentrates around integrated energy management platforms and specialized hazardous-location certifications. Three archetypes dominate: full-platform providers bundling breakers with automation software, component specialists focusing on trip unit electronics, and regional metal fabricators supplying mechanical frames to EPC contractors. Competitive moves center on firmware upgrade services and dual-certification strategies spanning CE marking and BIS compliance.
Among European-headquartered full-platform providers, ABB leverages its installed base in substation automation while Schneider Electric anchors its position through integrated energy management platforms. Eaton occupies a position within the hazardous-location specialization tier. These three exemplify the strategic divergence between recurring replacement cycle capture and digital monitoring bundling.
| Leading Market Players |
|---|
| ABB |
| Schneider Electric |
| Eaton |
| TE Connectivity |
| R. STAHL |
| Techna International |
| Carling Technologies |
| Rockwell Automation |
| E-T-A Elektrotechnische Apparate |
| Others |
Value Chain & Pricing Dynamics
Silver spot price volatility cascades through magnetic circuit breaker manufacturing, compressing margins on high-ampacity air circuit breaker production while forcing tiered pricing stratification across premium IEC-certified, standard UL-listed, and economy-grade residential units.
Pricing Analysis
Warranty and firmware upgrade bundling separates full-platform providers from component specialists, with ABB and Schneider Electric commanding premium positioning through integrated SCADA-compatible trip units while regional fabricators compete on unbundled mechanical frames. Price differentiation hinges on dual CE-BIS certification status and embedded Rogowski coil sensing capability. Pricing pressure stems from foundry cost escalation in Zhejiang province, squeezing mid-tier producers without captive gray iron casting. Residential contractors in North America exhibit highest price sensitivity, while Indian state transmission utilities prioritize selective coordination over first cost.
Supply Chain Analysis
Single-source vulnerability sits with gray iron foundries concentrated in Zhejiang and Jiangsu provinces, where breaker housing production anchors global assembly networks. Raw material dependencies encompass silver-cadmium oxide alloys for contacts, copper-aluminum hybrid busbars, and epoxy resin compounds for molded case insulation. Supply chain risk centers on electromagnetic compatibility recertification delays under China's GB 14048.2-2020 amendments, which freeze microprocessor-based module shipments for six-to-nine month windows. Distribution runs through electrical wholesalers in Germany, EPC contractor frameworks in India, and utility procurement departments in China and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as IEC 60947-2 harmonization and digital trip unit recertification burdens force smaller manufacturers without dual-certification capabilities toward exit or acquisition.
For Market Incumbents: Deepen backward integration into gray iron casting to insulate margin structures from Zhejiang foundry price volatility, while accelerating firmware-as-a-service revenue streams to offset mechanical frame commoditization. Threatened by EPC contractor unbundling behaviors in India and the Middle East, incumbents must tighten channel control through multi-year framework agreements with transmission operators. For New Entrants and Emerging Players: Begin with IIoT-enabled predictive maintenance modules as attachable retrofits for legacy molded case installations, targeting India's 66kV substation upgrade tenders where frame-compatible digital trip units face supply shortages. The most penetrable white space sits with contact wear sensors integrated into SCADA systems for German automotive stamping plants seeking ISO 50001 compliance without full panel replacement. For Investors and Strategic Acquirers: Distressed-cycle entries favor component specialists with captive electromagnetic compatibility testing capabilities in Shanghai or Shenzhen, positioned to absorb GB 14048.2-2020 recertification timelines that strain export-oriented competitors. Long-term viability hinges on recurring aftermarket service revenue rather than transactional breaker sales. Watch for Indian state transmission utility tender awards as inflection indicators, particularly 33kV and 66kV substation frameworks specifying digital trip compatibility.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | CE marking plus BIS compliance unlocks concurrent European OEM and Indian EPC access without parallel product lines. |
| Backward Integration into Foundry Operations | Captive gray iron casting in Zhejiang or alternative geographies insulates margin structures from supplier concentration risk. |
| Firmware-as-a-Service Development | Remote trip unit calibration and protection curve updates transform one-time sales into recurring utility revenue streams. |
| Rogowski Coil Sensor Integration | Embedded load monitoring automates ISO 50001 energy audit compliance for German food processing and pharmaceutical manufacturers. |
| SCADA Integration Partnership | Direct interoperability with ABB Ability or Schneider Electric EcoStruxure platforms secures placement in utility automation architectures. |
Study Parameters
Independent corroboration across primary interviews with substation automation engineers, EPC contractor procurement leads, gray iron foundry operations managers, and utility protection coordination specialists underwrites the qualitative findings, validated against IEC 60947-2 certification databases, GB 14048 amendment filings, Indian state transmission utility tender documents, and SEC 10-K disclosures from listed electrical equipment manufacturers. Bottom-up shipment estimates from molded case and air circuit breaker production facilities triangulate against top-down utility capital expenditure tracking across China, Germany, India, and the United States.
Comparable-period anchoring to historical renewable interconnection and industrial electrification investment cycles shapes the projection horizon, with segmentation modeling across product type, installation configuration, application scope, and end user category. CAGRs derive from regression analysis of procurement volume against grid modernization program announcements and motor control center retrofit pipelines. Forecast inputs incorporate copper and silver price trajectory assumptions alongside electromagnetic compatibility regulatory phase-in schedules.
Underlying measurement precision varies by segment; utility-scale air circuit breaker procurement carries tighter precision than fragmented residential distribution board sales. Forecasts reflect documented assumptions regarding IEC-GB harmonization timelines and Indian infrastructure tender execution rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
HV Bushing Market
Electrical Power Equipment
Europe Gas Insulated Switchgear Market
Electrical Power Equipment
Marine Switchboard Market
Electrical Power Equipment
Solid Vacuum Reclosers Market
Electrical Power Equipment
Switching Residential Voltage Regulator Market
Electrical Power Equipment
Gas Circuit Breaker Market
Electrical Power Equipment
Motor Generator Set Market
Electrical Power Equipment
Composite Line Post Insulators Market
Electrical Power Equipment
Residential Air Insulated Power Distribution Component Market
Electrical Power Equipment
Magnet Bearings Market
Electrical Power Equipment
Copper Ground Rod Market
Electrical Power Equipment
MV Protection Relay Market
Electrical Power Equipment
Digital Fault Recorder (DFR) Market
Electrical Power Equipment
Gas Insulated Switchgear Sales Market
Electrical Power Equipment
Europe Electric Radiators Market
Electrical Power Equipment
Power Over Ethernet Lighting Market