
 France Adjuvants Market | 2026-2036
France Adjuvants Market Size, Share, and Industry Trends Forecast 2026-2036
France Adjuvants Market Foresight
Pharmaceutical-grade adjuvant specifications is reorganizing competitive dynamics among French formulators. BASF SE leverages its integrated surfactant technology platform to serve agricultural manufacturers with consistent batch quality. Evonik Industries anchors its position through silicone-based super-spreader chemistry for precision crop applications. Croda International PLC differentiates via bio-based emulsifier portfolios aligned with EU Green Deal sourcing requirements.
Adjuvants are functional additives that modify the physical properties of active formulations, typically comprising surfactants, solvents, or emulsifiers that reduce surface tension below 30 mN/m to enhance spreading, penetration, or stability of the primary agent. Their industrial purpose centers on maximizing biological or chemical performance of carrier formulations across agricultural, pharmaceutical, and coatings applications. Surfactant-based adjuvants command the largest volume share due to universal compatibility with aqueous pesticide systems, while emulsifier segments exhibit the fastest structural expansion driven by oil-in-water formulation trends in fungicide and herbicide blends. Corrosion inhibitor adjuvants maintain stable margin pools through specialized demand from industrial lubricant and coatings producers facing extended equipment lifecycle requirements.
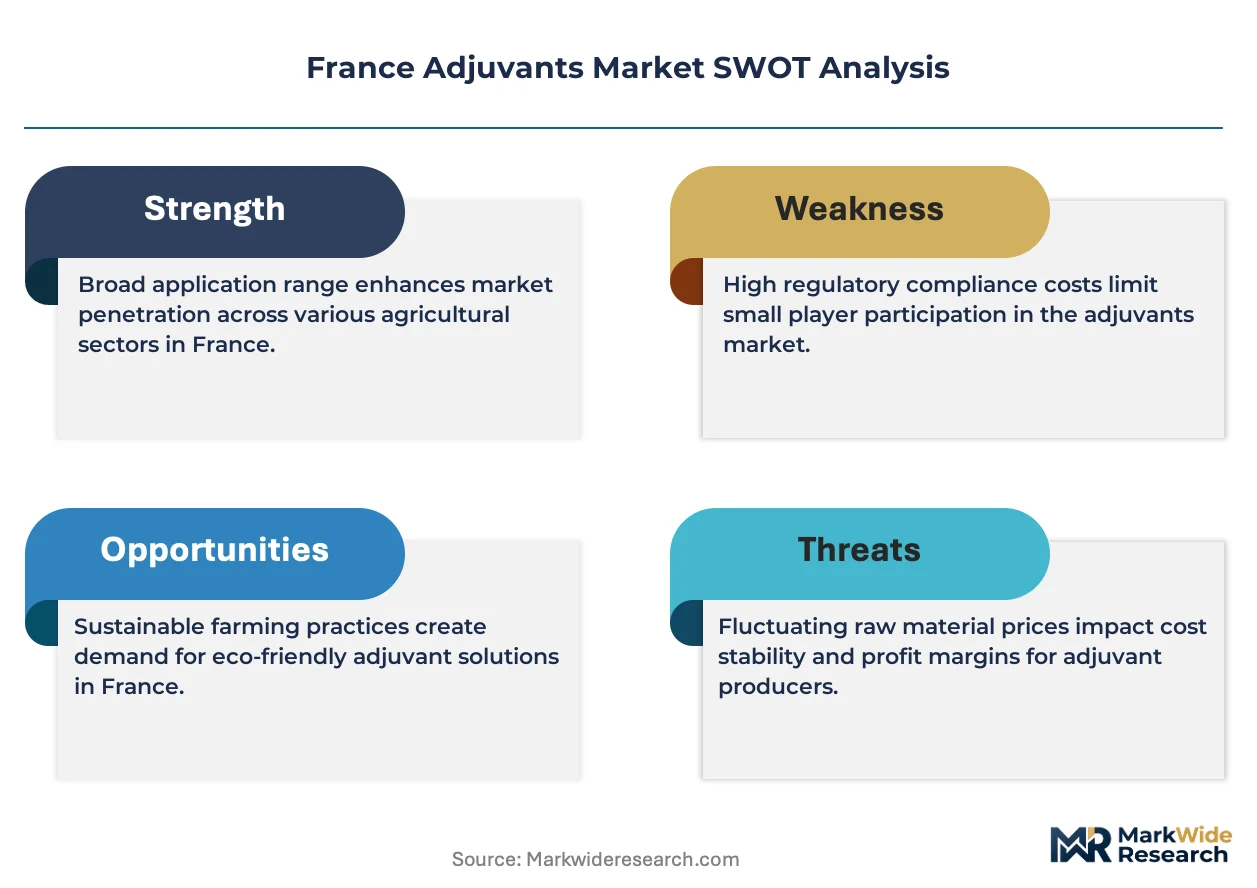
ANSM oversight of pharmaceutical adjuvant safety profiles and REACH registration mandates for surfactant chemistries jointly elevate compliance costs for non-specialized suppliers. The EU Green Deal's carbon border adjustments and France's national low-carbon strategy increasingly filter procurement decisions toward bio-based and regionally manufactured adjuvant inputs. Stakeholders must monitor evolving ECHA substance evaluation timelines and agricultural input subsidy restructuring to anticipate formulation reformulation cycles and distribution channel realignments.
Market Dynamics
REACH registration mandates for surfactant chemistries are restructuring supplier economics across France's adjuvant sector, forcing formulators to consolidate batch volumes or exit non-core product lines entirely.
Growth Catalysts
- EU Green Deal carbon border adjustments:Procurement officers in Grand Est cereal operations now prioritize bio-based emulsifiers to preempt compliance cost escalation on imported petrochemical inputs.
- Precision agriculture penetration:Drone-assisted pesticide application in Île-de-France specialty vineyards demands silicone-based super-spreader chemistries that reduce water volumes per hectare.
- ANSM pharmaceutical-grade specifications:Vaccine adjuvant safety documentation requirements are pulling technical surfactant expertise from agricultural into human health applications.
Market Restraints
- Ethoxylated alcohol feedstock volatility:Palm kernel and coconut oil price swings transmit directly into surfactant production costs, compressing margin predictability for mid-tier formulators.
- German-Belgian supply corridor concentration:Over half of France's silicone adjuvant precursors originate from two integrated chemical parks near Antwerp and Ludwigshafen, creating single-source vulnerability.
- Technical incompatibility with hard water:Calcium and magnesium levels above 300 ppm in Aquitaine irrigation sources degrade anionic surfactant performance, limiting product efficacy without chelation additives.
Strategic Opportunities
- Occitanie wine cooperative consolidation:Merging vineyard management entities create centralized procurement volumes that favor dedicated adjuvant supply contracts over distributor purchasing.
- Biostimulant-pesticide co-formulation:Regulatory convergence between ANSM and ANSES frameworks permits novel adjuvant positioning as dual-function carriers for microbial inoculants.
- Direct-to-farm digital platforms:Agritech marketplaces bypass traditional cooperative distribution, enabling formulators to capture margin previously allocated to regional depots.
Industry Challenges
- REACH substance evaluation timeline uncertainty:ECHA's rolling prioritization of ethoxylates forces continuous reformulation investment without predictable endpoint.
- Cross-functional regulatory expertise scarcity:Formulation chemists fluent in both agricultural efficacy testing and pharmaceutical safety documentation command premium compensation that smaller suppliers cannot match.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Adjuvants Market |
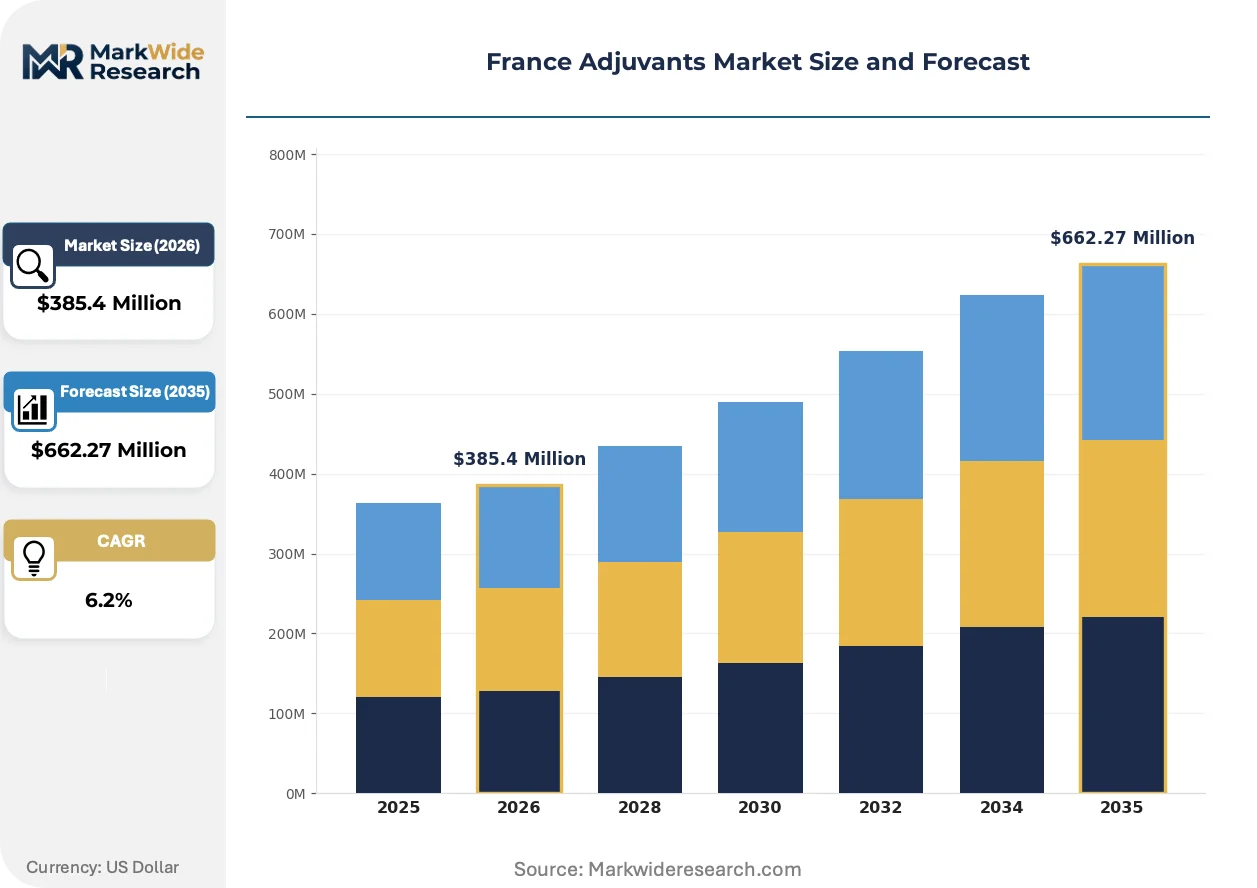
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surfactants, Solvents, Emulsifiers, Thickeners, Corrosion Inhibitors Application: Pesticide Formulation, Detergents, Paints & Coatings, Adhesives, Lubricants End User Industry: Agricultural Manufacturers, Chemical Processors, Coating Producers, Pharmaceutical Formulators, Personal Care Brands Distribution Channel: Direct Sales, Distributors, Online Platforms, Retailers, Industrial Suppliers |
| Companies Covered | BASF SE, Nouryon, Evonik Industries, Croda International PLC, Clariant AG, Nufarm, Rovensa Group, Nutrient Ltd, Vivagro, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Adjuvants Market Shifts & Advancements
Formulation chemistry is pivoting toward bio-based feedstocks as carbon accounting penetrates procurement decisions, while digital traceability tools reshape how adjuvant performance is verified in field conditions.
Alkyl polyglucoside surfactants synthesized from wheat-derived glucose and palm-free fatty alcohols are displacing conventional ethoxylated nonylphenol chemistries in fungicide applications. Bordeaux-region wine producers have adopted these bio-based alternatives across three growing seasons. The shift is compressing demand for petroleum-derived surfactants in high-value crop segments where sustainability certification commands price premiums.
France's national low-carbon strategy implementation is accelerating disclosure requirements for Scope 3 emissions across agricultural input supply chains. Formulators must now document cradle-to-gate carbon intensity for every adjuvant batch sold to cooperative buyers. Specialty crop producers in Champagne-Ardenne are responding by specifying bio-based content minimums in tender documents, effectively filtering supplier eligibility before technical evaluation begins.
Cooperative procurement officers are consolidating annual adjuvant volumes into framework agreements with performance guarantees rather than spot purchasing through distributor networks. This behavioral shift concentrates buying power among three national agricultural cooperatives controlling two-thirds of pesticide expenditure in northern cereal regions. The restructuring is most visible in Hauts-de-France, where direct manufacturer relationships now bypass traditional regional chemical distributors entirely.
France Adjuvants Market Segmentation
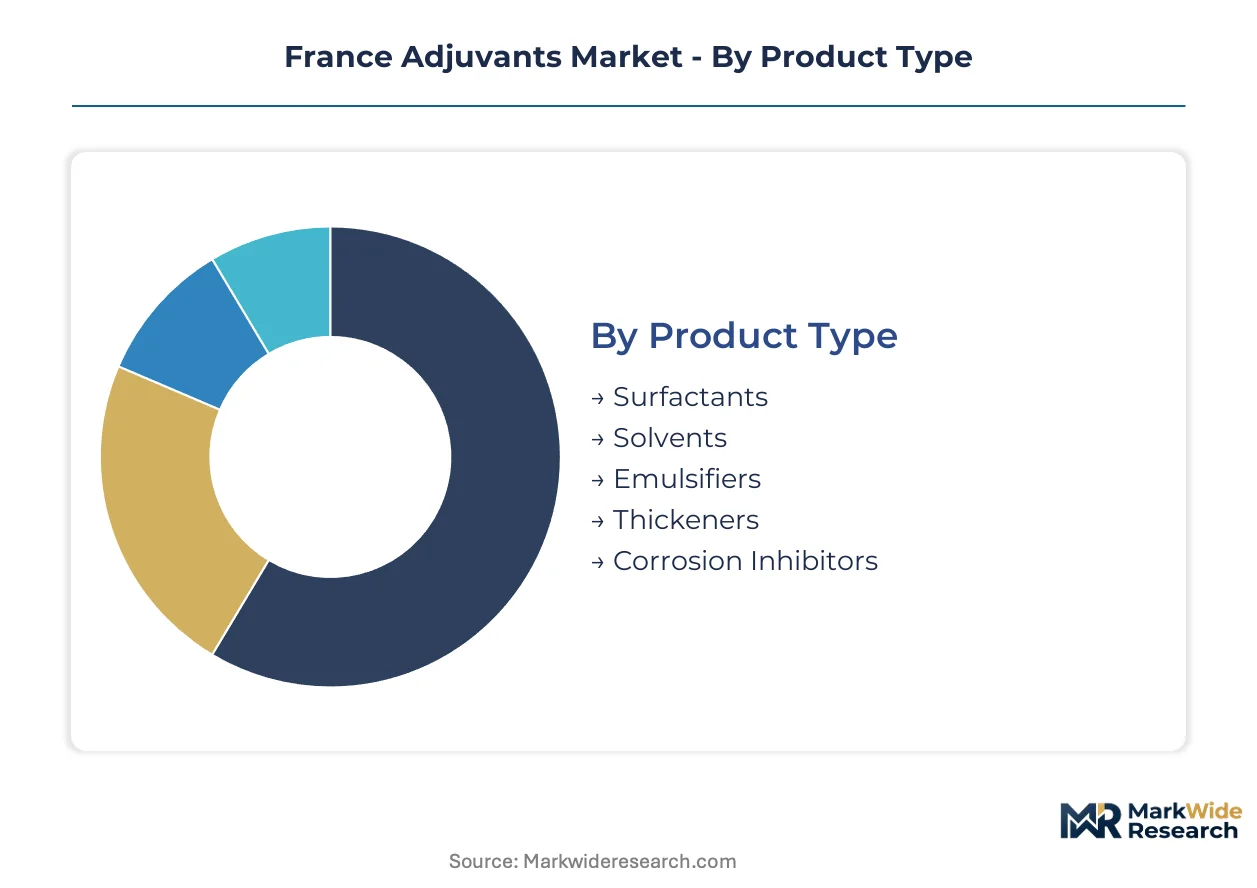
Channel economics in France's adjuvant sector vary sharply by segment. Agricultural manufacturers favor direct relationships for volume surfactant contracts, while coating producers and personal care brands rely on distributor networks for formulation flexibility.
Product Type:
Channel mix splits sharply: surfactants and emulsifiers flow predominantly through direct sales to agricultural cooperatives, while solvents and corrosion inhibitors reach coating producers via industrial suppliers.
- Surfactants:These anionic and non-ionic surface-active agents reduce interfacial tension below 30 mN/m in aqueous pesticide systems. Demand concentrates among cereal belt cooperatives in Grand Est seeking compatibility with hard water conditions without chelation additives. ANSM pharmaceutical-grade specifications are pulling technical surfactant expertise toward vaccine adjuvant applications.
- Emulsifiers:Oil-in-water stabilizers enable fungicide and herbicide blend formulations with extended shelf stability. Île-de-France specialty vineyards specify bio-based emulsifiers to meet EU Green Deal carbon border adjustment requirements. REACH registration mandates for ethoxylated chemistries are forcing continuous reformulation investment.
- Solvents:Hydrocarbon and oxygenated carriers dissolve lipophilic active ingredients for coatings and adhesives segments.
- Thickeners:Rheology modifiers adjust viscosity in personal care and pharmaceutical suspension formulations.
- Corrosion Inhibitors:Specialized additives protect metal surfaces in industrial lubricant systems facing extended equipment lifecycle requirements.
Surfactants dominate installed base. Emulsifiers are where expansion concentrates.
Application:
Margin structure varies by application maturity: pesticide formulation commands premium pricing for performance guarantees, while detergents and lubricants compete on volume throughput.
- Pesticide Formulation:Adjuvants enhance active ingredient efficacy in fungicide, herbicide, and insecticide delivery systems. Drone-assisted application in Champagne-Ardenne vineyards demands silicone-based super-spreader chemistries that reduce water volumes per hectare. Precision agriculture penetration is restructuring procurement toward framework agreements with performance guarantees.
- Detergents:Surfactant blends optimize foaming and grease-cutting in household and industrial cleaning products.
- Paints & Coatings:Rheology modifiers and wetting agents control film formation and substrate adhesion.
- Adhesives:Tackifiers and plasticizers modify bond strength and open time in industrial assembly applications.
- Lubricants:Friction modifiers and anti-wear additives extend equipment service intervals under high-load conditions.
Pesticide formulation anchors revenue concentration. Precision agriculture applications are climbing the fastest.
End User Industry:
Customer sophistication tiers separate agricultural manufacturers seeking batch consistency from pharmaceutical formulators demanding documentation depth.
- Agricultural Manufacturers:Pesticide producers in France's cereal belt specify surfactant-based adjuvants for high-volume cereal applications. Cooperative consolidation in Occitanie wine regions creates centralized procurement volumes favoring dedicated supply contracts.
- Chemical Processors:Intermediary formulators blend adjuvant packages for downstream industrial applications.
- Coating Producers:Industrial paint manufacturers leverage wetting agents and dispersants for substrate coverage optimization.
- Pharmaceutical Formulators:Vaccine adjuvant safety documentation requirements under ANSM oversight demand cross-functional regulatory expertise scarce among smaller suppliers.
- Personal Care Brands:Cosmetic formulators specify bio-based emulsifiers aligned with EU Green Deal sourcing requirements.
Agricultural manufacturers represent the largest volume base. Pharmaceutical formulators are gaining share fastest.
Distribution Channel:
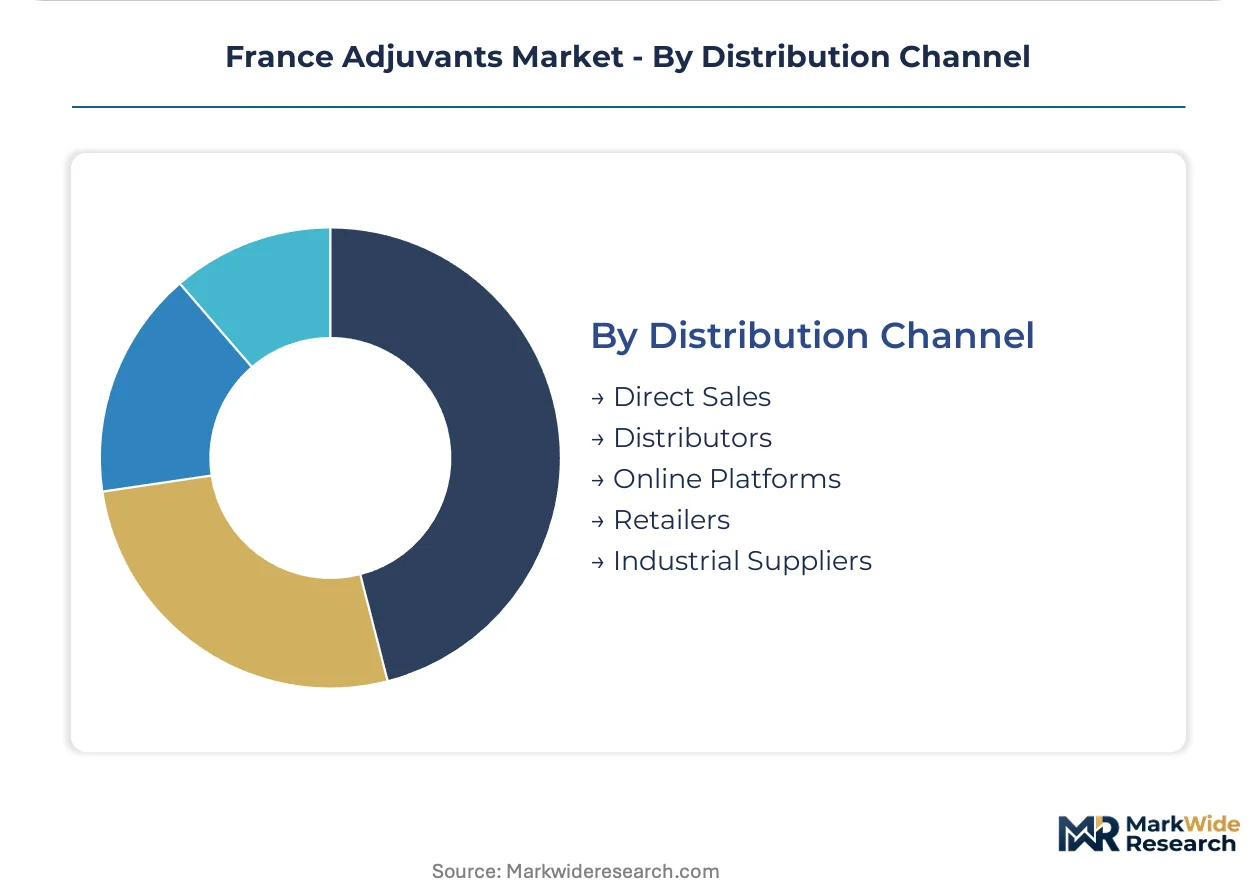
Digital platforms are bypassing traditional cooperative distribution in northern cereal regions, enabling formulators to capture margin previously allocated to regional depots.
- Direct Sales:Manufacturer relationships with national agricultural cooperatives control two-thirds of pesticide expenditure in Hauts-de-France. Framework agreements with performance guarantees are displacing spot purchasing through distributor networks.
- Distributors:Regional chemical distributors serve mid-tier coating producers and personal care brands requiring formulation flexibility.
- Online Platforms:Agritech marketplaces enable direct-to-farm procurement bypassing traditional cooperative distribution channels.
- Retailers:Specialty agriculture supply stores serve smallholder vineyard operations with packaged adjuvant products.
- Industrial Suppliers:Bulk chemical distributors serve lubricant and coatings manufacturers with volume solvent and corrosion inhibitor deliveries.
Direct sales dominate transaction value. Online platforms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical parks near Ludwigshafen and Antwerp-Belgian supply corridors export silicone precursors and surfactant intermediates to French formulators, creating concentrated import dependency for high-performance agricultural adjuvants.
Île-de-France
Precision viticulture in Champagne-Ardenne vineyards drives silicone-based super-spreader demand for drone-assisted pesticide application. ANSM pharmaceutical-grade specifications pull technical surfactant expertise toward vaccine adjuvant documentation. Paris-region headquarters of major cooperatives centralize procurement decisions for northern cereal operations.
Grand Est
Cereal belt cooperatives specify surfactant-based adjuvants compatible with hard water conditions above 300 ppm calcium. EU Green Deal carbon border adjustments filter procurement toward bio-based emulsifiers with documented Scope 3 emissions. Strasbourg-based formulators serve cross-border agricultural operations into German Saarland.
Occitanie
Wine cooperative consolidation creates centralized procurement volumes favoring dedicated supply contracts over distributor purchasing. REACH registration mandates for ethoxylated chemistries force continuous reformulation investment among regional blenders. Toulouse-area biostimulant developers explore dual-function adjuvant positioning for microbial inoculants.
Nouvelle-Aquitaine
Bordeaux-region wine producers have adopted alkyl polyglucoside surfactants across three growing seasons, displacing petroleum-derived alternatives. Hard water degradation of anionic surfactants limits product efficacy without chelation additives in Aquitaine irrigation sources. Regional formulators document cradle-to-gate carbon intensity for cooperative buyers under France's national low-carbon strategy.
Hauts-de-France
Direct manufacturer relationships now bypass traditional regional chemical distributors entirely. Framework agreements with performance guarantees displace spot purchasing through cooperative networks. Lille-based agricultural supply chains concentrate two-thirds of pesticide expenditure in northern cereal regions through three national cooperatives.
France Adjuvants Market Competitive Landscape
Listed leaders compete with private specialists across formulation chemistry depth, with publicly traded chemical conglomerates facing agile private formulators who pivot faster on bio-based feedstock transitions. The vendor base splits between integrated surfactant technology platforms and focused silicone chemistry specialists. Three archetypes dominate: diversified chemical majors with agricultural divisions, pure-play adjuvant formulators, and biostimulant-pesticide hybrid developers. Competitive moves center on backward integration into bio-based feedstock supply and strategic partnerships with precision agriculture equipment manufacturers.
Within the integrated chemical tier, BASF SE anchors German-origin supply relationships across French agricultural cooperatives. Evonik Industries exemplifies silicone-based super-spreader specialization for precision crop applications. Croda International PLC represents UK-based bio-based emulsifier positioning aligned with EU Green Deal sourcing requirements.
| Leading Market Players |
|---|
| BASF SE |
| Nouryon |
| Evonik Industries |
| Croda International PLC |
| Clariant AG |
| Nufarm |
| Rovensa Group |
| Nutrient Ltd |
| Vivagro |
| Others |
Supply & Pricing Matrix
REACH registration mandates for surfactant chemistries gate both supplier qualification and price differentiation simultaneously, compressing mid-tier formulators while rewarding integrated majors with compliant batch documentation. Bio-based certification premiums now separate qualified suppliers from commodity traders in cooperative procurement.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure with volume-tiered discounts. Price differentiation hinges on REACH registration status and bio-based content certification under EU Green Deal frameworks. Pricing pressure stems from ethoxylated alcohol feedstock volatility in palm kernel and coconut oil markets. Mid-tier agricultural cooperatives exhibit highest price sensitivity, while pharmaceutical formulators accept premium positioning for ANSM-compliant documentation depth.
Supply Chain Analysis
Container availability constraints on Antwerp-Rotterdam-Hamburg trade lanes elevate inbound logistics costs for silicone precursor imports. Supply concentrates in Germany and Belgium for surfactant intermediates, with China and India feeding specialty emulsifier chemistries. Raw material dependencies include ethoxylated alcohols, silicone oils, and wheat-derived glucose for alkyl polyglucoside alternatives. Single-source vulnerability from Ludwigshafen-Antwerp chemical parks creates structural risk. Distribution runs through direct manufacturer relationships with national cooperatives, bypassing traditional regional depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's adjuvant sector presents a service-attach opportunity as technical support contracts and formulation customization services expand faster than commodity surfactant sales. Performance guarantees and field efficacy verification now command recurring revenue premiums.
For Market Incumbents: Secure backward integration into bio-based feedstock supply chains to preempt EU carbon border adjustment cost escalation. Lock in exclusive framework agreements with consolidating Occitanie wine cooperatives before distributor relationships solidify. Defend against agile private formulators by accelerating REACH-compliant batch documentation capabilities that smaller rivals cannot replicate.
For New Entrants and Emerging Players: Differentiate on bio-based emulsifier positioning aligned with Champagne-Ardenne sustainability certification requirements. Target underpenetrated precision agriculture equipment partnerships for silicone super-spreader co-development. Pursue direct-to-farm digital platform routes that bypass cooperative distribution gatekeepers entirely.
For Investors and Strategic Acquirers: ANSM pharmaceutical-grade specification expansion reshapes the acquisition landscape toward formulators with cross-functional regulatory expertise. Long-term viability favors specialists bridging agricultural efficacy testing and vaccine adjuvant documentation. Watch ECHA substance evaluation timeline acceleration as the inflection signal triggering consolidation waves among non-compliant mid-tier suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstocks | Captures margin from wheat-derived glucose supply chains under France's national low-carbon strategy. |
| REACH Registration Completion | Preserves market access as ECHA prioritizes ethoxylated alcohol evaluations. |
| Direct-to-Farm Digital Platform Launch | Bypasses cooperative distribution concentration in Hauts-de-France cereal regions. |
| Silicone Super-Spreader Co-development | Aligns with drone-assisted pesticide penetration in Champagne-Ardenne vineyards. |
| Pharmaceutical-Grade Certification Investment | Opens vaccine adjuvant revenue streams under ANSM oversight requirements. |
Research Methodology
Operator-level perspectives from agricultural cooperative procurement officers, formulator R&D directors, and ANSM regulatory affairs specialists anchored the qualitative base. Secondary validation drew from ECHA substance evaluation databases, REACH registration filings, and French customs trade statistics for surfactant imports. Bottom-up volume estimates from regional cooperative purchasing data triangulated against top-down sector expenditure benchmarks.
Sensitivity analysis tested forecast robustness across bio-based feedstock cost scenarios and regulatory timeline variations. The projection framework modeled product type, application, end-use industry, and distribution channel dimensions alongside regional production hub clustering. CAGRs derived from historical volume trajectories adjusted for cooperative consolidation patterns and precision agriculture penetration curves.
Decision-makers should treat outputs as directional under assumptions of stable REACH evaluation timelines and continued EU Green Deal carbon border adjustment implementation; material deviation would warrant model refresh. Forecasts reflect base-case assumptions for ethoxylated alcohol price volatility and cooperative procurement centralization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Fermented Chymosin Market
Food Additives and Ingredients
United Kingdom Food Additives Market
Food Additives and Ingredients
North America Food Preservatives Market
Food Additives and Ingredients
Granulated Tapioca Market
Food Additives and Ingredients
Spain Food Additives Market
Food Additives and Ingredients
Europe Food Micronized Salt Market
Food Additives and Ingredients
Instant Fat Powder Market
Food Additives and Ingredients
Europe Leavening Agents Market
Food Additives and Ingredients
Film Forming Starches Market
Food Additives and Ingredients
Global Cereal Ingredients Market
Food Additives and Ingredients
Food Processing Ingredients Market
Food Additives and Ingredients
Clean Labelled Food Additives Market
Food Additives and Ingredients
Food Grade Ammonium Bicarbonate Market
Food Additives and Ingredients
Italy Sodium Reduction Ingredients Market
Food Additives and Ingredients
Fat-Replacing Starch Market
Food Additives and Ingredients
Ammonia Caramel Market